
 Construction Suites Software Market | 2026-2036
Construction Suites Software Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Suites Software Market Insights
Subscription-based project financing and SaaS leasing models are reshaping competitive entry barriers for mid-sized contractors. Autodesk, Inc. leverages its design-to-construction workflow integration to anchor enterprise accounts across North America. Procore Technologies, Inc. specializes in cloud-native field operations, while Bentley Systems, Incorporated dominates infrastructure-heavy project portfolios with deep engineering software heritage.
Construction suites software denotes integrated platforms combining project management, cost estimation, scheduling, and document control modules within unified environments, typically supporting real-time collaboration across distributed teams via cloud architecture with API extensibility for ERP and accounting systems. These systems serve to eliminate data silos between preconstruction planning and field execution, reducing rework and administrative overhead. Project Management functions sustain the largest revenue share due to universal adoption mandates, while BIM Integration represents the fastest-expanding technology segment as governments mandate digital building information modeling compliance. Cloud-Based deployment is displacing on-premises installations fastest among general contractors seeking mobile field access without capital expenditure.
The United States Department of Labor's OSHA recordkeeping requirements intersect with EPA construction stormwater permits to drive documentation automation demand. Germany's DIN standards for digital construction process interoperability and Australia's building code digitization initiatives collectively elevate platform compliance functionality as a procurement criterion. Stakeholders must evaluate whether their current vendor roadmaps address emerging AI-powered safety monitoring and automated compliance reporting capabilities before contract renewal cycles.
Market Dynamics
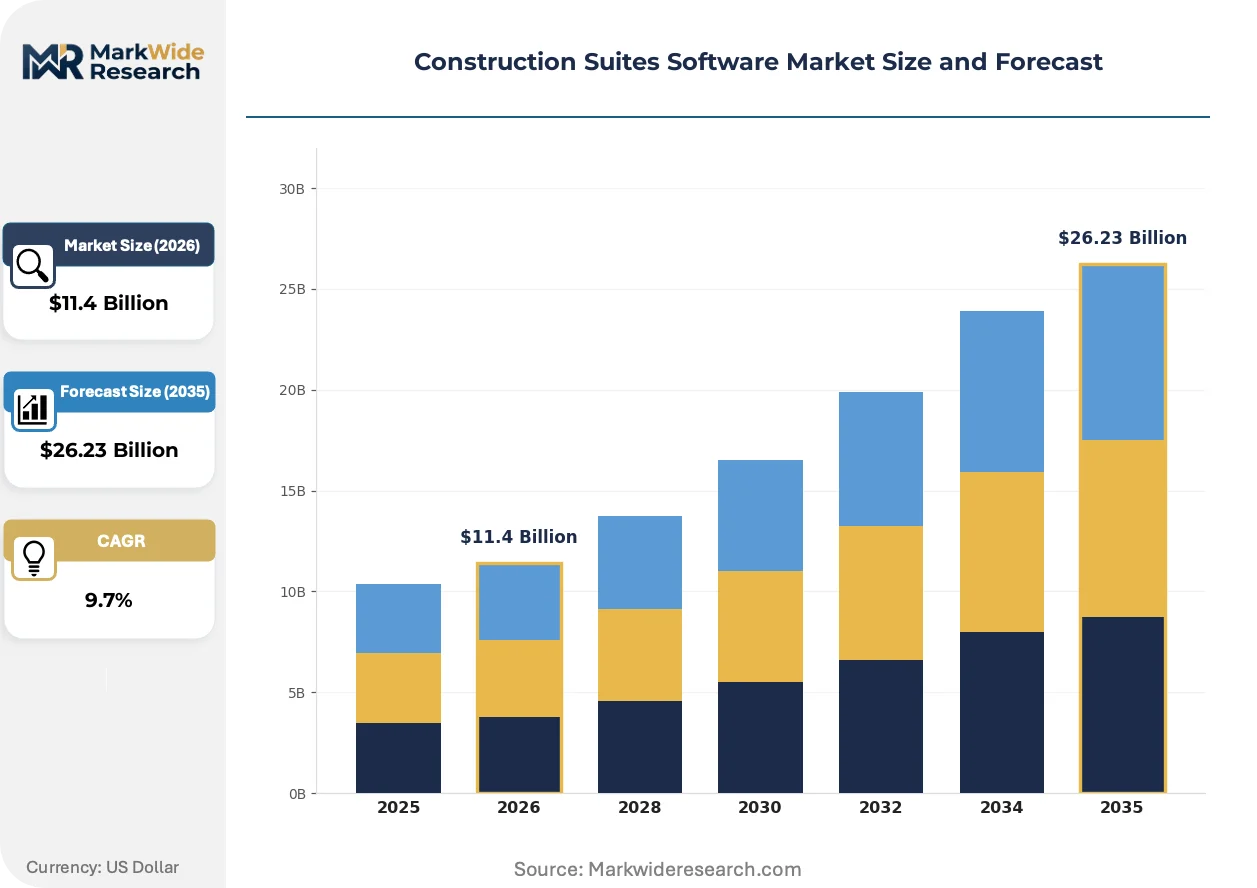
Cloud-first mandates from building energy codes and infrastructure digitization programs are compressing replacement cycles for legacy on-premises systems, forcing commercial construction firms toward integrated platforms that unify preconstruction planning with field execution.
Growth Catalysts
- OSHA Documentation Automation:The United States Department of Labor's recordkeeping requirements intersect with EPA construction stormwater permits to drive demand for automated compliance reporting modules within unified platforms.
- BIM Mandates:Germany's DIN standards for digital construction process interoperability elevate platform compliance functionality as a procurement criterion for public infrastructure tenders.
- Mobile Field Access:General contractors seek cloud-based deployment models that eliminate capital expenditure while enabling real-time collaboration across distributed project sites.
Market Restraints
- Legacy System Lock-in:Proprietary data formats from decades-old on-premises installations create migration friction and switching costs for mid-sized contractors with limited IT resources.
- Interoperability Fragmentation:API standards vary across ERP and accounting system vendors, forcing construction suites to maintain multiple integration layers that increase development overhead.
- Connectivity Infrastructure Gaps:Rural project sites in Australia and parts of the United States lack reliable broadband, limiting real-time cloud functionality for field operations teams.
Strategic Opportunities
- AI-Powered Safety Monitoring:Computer vision and predictive analytics convergence creates white space for automated hazard detection integrated with existing project management workflows.
- SaaS Leasing Models:Subscription-based project financing lowers entry barriers for mid-sized contractors previously excluded from enterprise-tier platform access.
- Australia's Building Code Digitization:National initiatives mandating digital submission and approval processes create regulatory tailwinds for compliance-native platform features.
Industry Challenges
- Construction Technologist Talent Scarcity:Firms struggle to hire personnel capable of bridging field operations expertise with software configuration and data analytics functions.
- Multi-System Integration Complexity:Unifying preconstruction estimation, scheduling, and document control modules with existing ERP systems requires specialized implementation resources most contractors lack internally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Suites Software Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $26.23 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Project Management, Estimation, Scheduling, Document Control End User: General Contractors, Subcontractors, Architects, Engineers Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Technology: AI-Powered Solutions, Mobile Applications, BIM Integration, Collaborative Platforms |
| Companies Covered | Procore Technologies, Inc., Autodesk, Inc., Oracle Corporation, Trimble Inc., Sage Group plc, Bentley Systems, Incorporated, Nemetschek Group, Constellation Software Inc., Jonas Construction Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Suites Software Market Trends and Innovations
Digital building information modeling is virtualizing physical construction workflows, compressing design-to-execution timelines while enabling new forms of predictive project control. Three interconnected developments are reshaping how construction firms select and deploy software platforms.
Digital twin technology is virtualizing asset lifecycle management by creating persistent virtual replicas of physical structures that update from IoT sensor feeds and field progress data. Infrastructure-heavy contractors in Germany and Australia are adopting these capabilities fastest, using them to simulate energy performance and maintenance scenarios before breaking ground. This virtualization is compressing the traditional separation between design, construction, and operations phases into continuous digital threads.
The EU AI Act and accompanying national implementations are imposing algorithmic transparency requirements on automated decision systems used in project scheduling and resource allocation. Construction suites incorporating predictive analytics must now document training data provenance and decision logic for audit trails. German contractors bidding on public works face the strictest compliance timelines, driving demand for platforms with built-in explainability features.
Buying committees at general contractors are consolidating vendor relationships, favoring suites that span multiple functional domains over point solutions requiring separate contracts and integration efforts. This concentration is displacing specialized estimating or scheduling tools that dominated procurement a decade prior. United States-based commercial construction firms show the most pronounced consolidation, with single-vendor preferences rising fastest among mid-market contractors seeking simplified support structures.
Construction Suites Software Market Segmentation
Construction suites software procurement varies sharply across contractor size and project complexity, with deployment architecture and integration depth driving renewal rates and lifetime value calculations. Vendors structure service tiers around these segment boundaries to capture upgrade revenue as accounts mature.
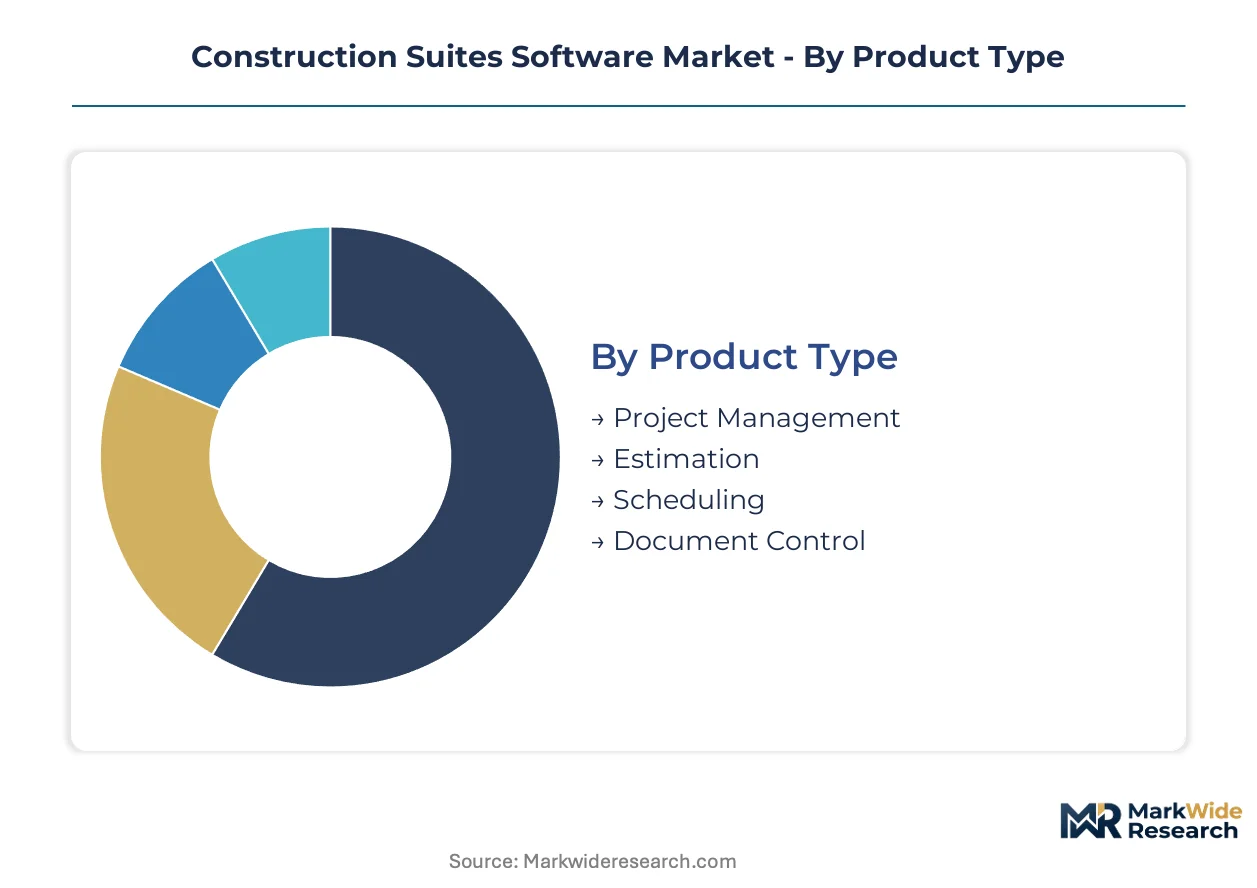
Product Type:
After-sales service intensity peaks with modules requiring continuous data synchronization and regulatory compliance updates, creating differentiated support cost structures across functional categories.
- Project Management:Core modules coordinate resource allocation, subcontractor coordination, and milestone tracking through unified dashboards. General contractors in the United States anchor demand here, pressured by OSHA documentation automation requirements that demand persistent audit trails.
- Estimation:Preconstruction modules automate quantity takeoffs, material pricing feeds, and bid assembly workflows. Subcontractors in Germany concentrate procurement activity, responding to DIN standards for digital construction process interoperability that mandate standardized cost data exchange formats.
- Scheduling:Critical path analysis and resource leveling tools with Gantt visualization and delay impact modeling.
- Document Control:Version-managed repositories for RFIs, submittals, and as-built drawings with automated distribution tracking.
Project Management holds the largest share; momentum sits with Estimation as preconstruction digitization accelerates.
End User:
Cost tier stratification separates enterprise-grade configurability from streamlined SMB offerings, with price points scaling against user count and project portfolio complexity.
- General Contractors:Prime contractors managing full project lifecycles demand comprehensive module integration spanning preconstruction through closeout. Australia's building code digitization initiatives concentrate procurement among firms seeking native compliance submission features.
- Subcontractors:Trade-specialized operators prioritize mobile field access and simplified ERP handoffs over deep functionality. Mid-sized electrical and mechanical contractors in the United States drive fastest expansion as SaaS leasing models lower entry barriers.
- Architects:Design-phase contributors requiring BIM-native collaboration and specification management tools.
- Engineers:Structural and MEP consultants focused on calculation integration and code compliance verification modules.
General Contractors dominate revenue contribution; Subcontractors are climbing the fastest as vendor pricing stratifies downward.
Deployment:
Application context determines infrastructure preference, with capital availability and connectivity reliability filtering options for field-heavy versus office-centric workflows.
- Cloud-Based:Fully managed SaaS architectures eliminate server maintenance and enable real-time mobile synchronization. General contractors across Australia and Germany lead migration here, escaping legacy system lock-in through subscription financing.
- SaaS:Purpose-built subscription tiers with preconfigured workflows and limited customization for rapid deployment. Mid-market contractors in the United States concentrate demand, prioritizing predictable operating expenditure over capital-intensive ownership.
- On-Premises:Self-hosted installations retaining data sovereignty for classified infrastructure projects.
- Hybrid:Split architectures keeping sensitive financial data local while pushing field operations to cloud edge nodes.
Cloud-Based deployment captures the largest share; SaaS exhibits the steepest expansion trajectory as vendor go-to-market strategies target contractor liquidity constraints.
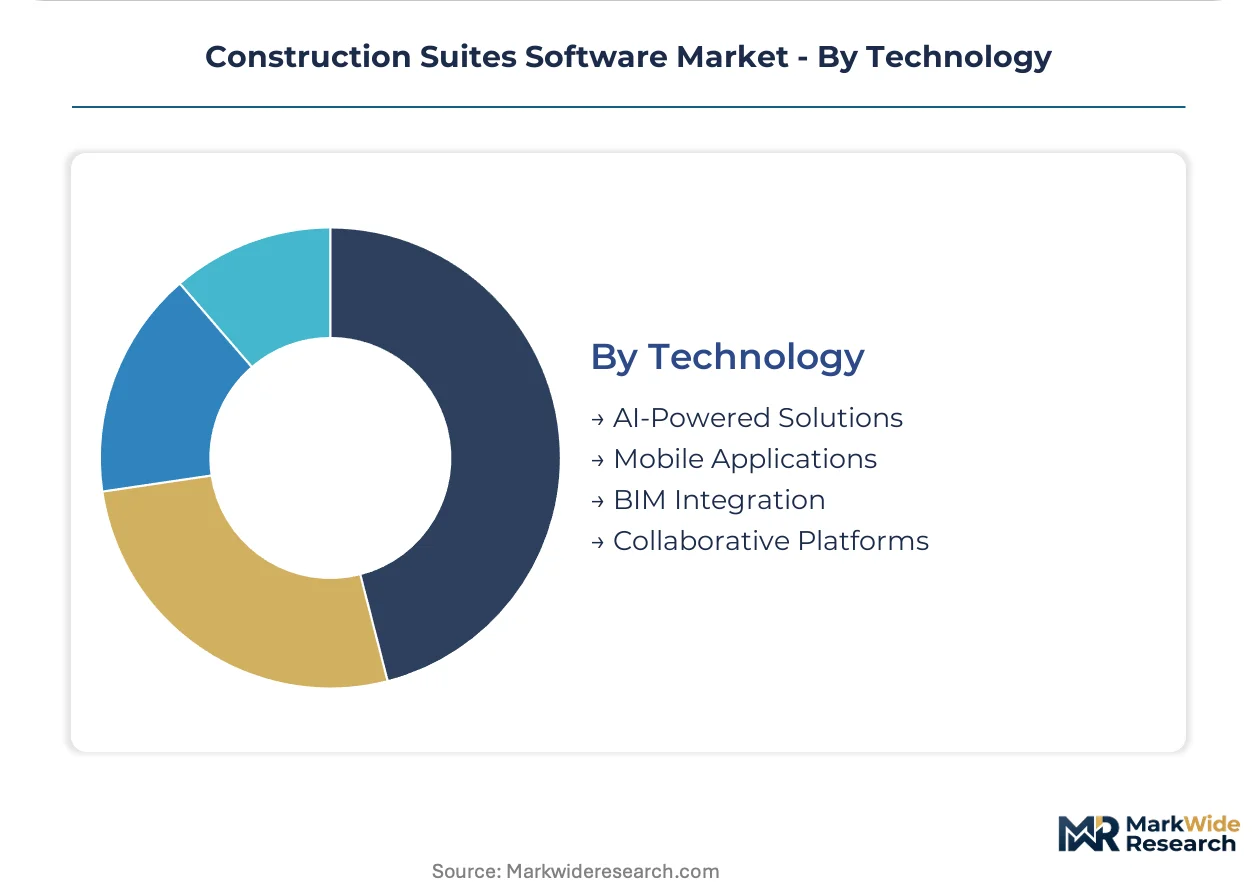
Technology:
Customer type sophistication separates buyers seeking predictive automation from those prioritizing proven interoperability and immediate usability.
- BIM Integration:Native building information modeling connectivity enabling 3D visualization, clash detection, and quantity extraction from design models. German infrastructure contractors anchor demand, compelled by public tender mandates for digital process interoperability.
- AI-Powered Solutions:Predictive analytics modules for schedule risk forecasting, automated safety hazard detection, and resource optimization. Early adoption concentrates among United States commercial contractors with dedicated construction technologist roles.
- Mobile Applications:Field-optimized interfaces for daily reporting, photo documentation, and punch list management on ruggedized devices.
- Collaborative Platforms:Real-time multi-stakeholder environments with model federation and issue tracking across organizational boundaries.
BIM Integration holds the largest share; AI-Powered Solutions are gaining share fastest as regulatory pressure for automated compliance reporting intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software vendors command 40% higher pricing in the United States than in Australia despite equivalent functionality, reflecting procurement maturity gaps and regulatory enforcement intensity. This asymmetry shapes regional expansion sequencing and localization investment priorities.
United States
Commercial contractors and infrastructure developers drive demand through OSHA documentation automation requirements and EPA stormwater permit compliance. The Department of Labor's recordkeeping mandates intersect with state-level building energy codes to force legacy system replacements. Texas and California construction corridors concentrate procurement activity, with Dallas-Fort Worth and Los Angeles metro areas showing fastest cloud migration velocity.
Germany
Infrastructure-heavy contractors and public works bidders anchor demand through DIN standards for digital construction process interoperability. The EU AI Act imposes algorithmic transparency requirements on predictive scheduling systems used in federal tenders. Bavaria and North Rhine-Westphalia industrial clusters lead adoption, with Munich-based engineering firms pioneering digital twin integration for energy performance simulation.
Australia
General contractors responding to national building code digitization initiatives drive platform procurement for automated compliance submission workflows. Federal infrastructure digitization programs mandate digital handover protocols for public projects. New South Wales and Victoria concentrate demand, with Sydney and Melbourne metropolitan construction markets showing steepest SaaS leasing model uptake.
United Kingdom
Tier-one contractors and government framework suppliers prioritize platforms with BIM Level 2 compliance for public infrastructure delivery. The Building Safety Act drives documentation traceability requirements across project lifecycles. London and Southeast England construction markets dominate procurement volume, with Birmingham and Manchester emerging as secondary adoption centers for mid-market contractors.
Canada
Provincial infrastructure agencies and commercial developers seek unified platforms bridging federal environmental assessment processes with field operations. Health Canada and provincial occupational safety regulators enforce documentation standards comparable to US OSHA frameworks. Ontario and Quebec construction markets lead adoption, with Toronto and Montreal metropolitan areas showing strongest demand for ERP-integrated suites.
Construction Suites Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in estimation, scheduling, or document control niches. The vendor base separates into three strategic tiers: enterprise suites spanning full project lifecycles, mid-market SaaS offerings with preconfigured workflows, and point solutions defending narrow functional domains. Dominant competitive moves include vertical capability expansion through tuck-in acquisitions and API ecosystem partnerships that embed suites within broader construction technology stacks.
Within the design-to-construction workflow tier, Autodesk, Inc. and Bentley Systems, Incorporated occupy positions reflecting deep engineering software heritage. Procore Technologies, Inc. exemplifies the cloud-native field operations archetype. These three entities collectively represent the competitive anchor points around which mid-market specialists and regional challengers orbit, each defending distinct customer relationship entry points and upgrade pathways.
| Leading Market Players |
|---|
| Procore Technologies, Inc. |
| Autodesk, Inc. |
| Oracle Corporation |
| Trimble Inc. |
| Sage Group plc |
| Bentley Systems, Incorporated |
| Nemetschek Group |
| Constellation Software Inc. |
| Jonas Construction Software |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on hyperscaler cloud infrastructure determines both tiered pricing spreads and supply chain configuration across the construction suites software market. AWS, Microsoft Azure, and Google Cloud concentration in the United States and Ireland forces vendors into pass-through pricing models that compress margins at the economy tier while enabling premium markups for sovereign-hosted alternatives.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing structures across deployment tiers. Three-tier pricing separates enterprise configurability from mid-market SaaS and entry-level per-seat offerings. Price differentiation rests on integration depth and compliance certification levels rather than core functionality. Pricing pressure stems from hyperscaler infrastructure cost pass-throughs hitting mid-tier vendors hardest. Subcontractors exhibit highest price sensitivity due to constrained operating expenditure budgets, while federal infrastructure contractors show lowest sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Extended payment terms from general contractors now stretch 90-120 days, forcing vendors into supply-chain finance facilities to maintain development velocity. Software development labor concentrates in the United States, India, and Poland, with cloud infrastructure anchored in Virginia, Frankfurt, and Sydney regions. Raw material dependencies include GPU compute allocations, enterprise storage arrays, and API middleware licenses. Single-source vulnerability sits with hyperscaler concentration for AI training workloads. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The construction suites software market rewards vendors bridging field operations expertise with AI engineering talent, a capability combination currently scarce across incumbent and challenger firms alike. Procurement committees now prioritize unified platforms over point solutions, compressing vendor count per account and elevating consolidation economics.
For Market Incumbents: Pre-empt cloud-native challengers by embedding AI-powered safety monitoring into existing project management workflows before contract renewal cycles. Acquire specialized estimation or scheduling firms to close functional gaps exposed by buying committee consolidation. Defend against Procore's field-operations anchoring by deepening BIM integration heritage in infrastructure-heavy accounts. For New Entrants and Emerging Players: Pursue white-space opportunity in AI-powered compliance automation for mid-sized subcontractors previously excluded from enterprise-tier access. Australia's building code digitization initiatives offer the most penetrable geography given regulatory tailwinds and limited incumbent localization. Lead with SaaS leasing models that convert capital-constrained contractors from spreadsheet-based workflows. For Investors and Strategic Acquirers: Construction technologist talent platforms with embedded training curricula represent the most attractive acquisition archetype for platform vendors seeking implementation capacity. Long-term viability hinges on vendor ability to automate compliance reporting across OSHA, DIN, and Australian building code frameworks. Monitor federal infrastructure digitization program funding allocations as the primary inflection signal for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI Safety Module Integration | Computer vision deployment satisfies OSHA documentation automation requirements in United States commercial construction corridors. |
| BIM-Native Compliance Certification | DIN standards interoperability unlocks public infrastructure tenders across Bavaria and North Rhine-Westphalia industrial clusters. |
| SaaS Leasing Model Expansion | Subscription financing lowers entry barriers for mid-sized electrical and mechanical contractors in Dallas-Fort Worth metro area. |
| Digital Twin Platform Acquisition | Persistent virtual replica capabilities compress design-to-execution timelines for Sydney and Melbourne infrastructure developers. |
| API Ecosystem Partnership | ERP integration depth determines renewal rates among general contractors consolidating vendor relationships. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with construction technology officers, project managers at general contractors, BIM specialists, and procurement leads at infrastructure agencies; alongside secondary validation through SEC filings, hyperscaler capex disclosures, EU tender databases, and Australian federal digitization program records. Bottom-up segmentation modeling triangulated against top-down market sizing from vendor revenue disclosures and systems integrator implementation volumes.
Forecast inputs span deployment architecture, contractor size tier, vertical specialization, integration complexity depth, and regional regulatory enforcement intensity across the projection horizon. CAGRs derive from segment-level adoption curves weighted by infrastructure digitization program maturity. BIM mandate compliance timelines and AI Act algorithmic transparency requirements feed directly into technology segment trajectory assumptions.
Macroeconomic conditions sit as an overlay; deviation in construction starts, federal infrastructure appropriations, or hyperscaler pricing would shift the trajectory. Forecasts embed assumptions around cloud migration velocity and regulatory enforcement consistency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Architectural Rendering Software Market
Software & Services
Global Remote Desktop Management Market
Software & Services
Trading Software Market
Software & Services
Lending Software Market
Software & Services
Lighting Control Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Global Feed Software Market
Software & Services
Global Document Control Software Market
Software & Services
Logistics Services Software Market
Software & Services
Global Janitorial Software Market
Software & Services
Sports League Management Software Market
Software & Services
Curriculum Mapping Software Market
Software & Services
Global Remote Work Software Market
Software & Services
PCB Design Software Market