
 Media Asset Management (MAM) Solutions Market | 2026-2036
Media Asset Management (MAM) Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Media Asset Management (MAM) Solutions Market Foresight
Cloud-native architecture is reconfiguring how media enterprises ingest, store, and distribute content at scale. Bynder leverages SaaS delivery models to serve distributed marketing teams across multinational brands. Cloudinary anchors its position through AI-powered image and video optimization APIs that integrate with developer workflows. MediaValet specializes in Azure-native infrastructure, competing on security certifications for government and healthcare media clients.
Media Asset Management Solutions encompass software platforms that catalog, preserve, retrieve, and distribute digital media files through centralized repositories with metadata indexing, transcoding engines, and access control layers. These systems process uncompressed video at 1.5 Gbps or higher, support MXF and IMF interchange formats, and enable frame-accurate search across petabyte-scale archives for broadcast, advertising, and film production workflows. Cloud-Based deployment leads in new installations as broadcasters abandon tape-based vaults, while AI-Powered technology segments attract the fastest upgrade cycles through automated speech-to-text and facial recognition indexing. Workflow Automation segments retain mature margin pools in newsroom and live sports environments where real-time proxy generation remains non-negotiable.
FCC regulations governing closed-caption accuracy and emergency alert distribution shape product requirements for US broadcasting customers, while GDPR and the EU AI Act impose data residency and algorithmic transparency obligations on European deployments. ISO 27001 and SOC 2 Type II certifications function as baseline market-access credentials for vendors serving financial services and public-sector media buyers. Stakeholders must weigh sovereign cloud mandates against multi-cloud interoperability as governments tighten data-localization rules for audiovisual archives.
Market Dynamics
Cloud-native infrastructure is compressing deployment timelines from months to weeks while forcing incumbents to abandon perpetual-license revenue models for consumption-based pricing architectures.
Growth Catalysts
- AI-powered metadata extraction:Automated speech-to-text and facial recognition indexing slashes manual cataloging labor for broadcast archives. Sports leagues deploy these tools to monetize decades of footage.
- FCC closed-caption mandates:US broadcasters must maintain frame-accurate caption synchronization, driving replacement of legacy tape-based vaults with searchable digital repositories.
- India:Streaming platform investment in regional-language content libraries creates demand for scalable MAM systems handling 22+ official languages.
Market Restraints
- Storage cost volatility:Cloud egress fees and tiered retrieval pricing compress margins for archive-heavy operations managing petabyte-scale uncompressed video.
- Azure-Google-AWS concentration:Three hyperscalers control infrastructure backing most cloud-native MAM deployments, creating single-point-of-failure exposure.
- Interoperability gaps:Proprietary API architectures prevent seamless migration between vendor platforms, locking buyers into incumbent relationships.
Strategic Opportunities
- Brazil:Underpenetrated broadcast infrastructure and rising streaming investment create whitespace for cloud-native MAM vendors.
- EU AI Act transparency requirements:Automated content indexing systems must document algorithmic decision trails, opening compliance-tooling revenue streams.
- Edge-compute convergence:5G-enabled remote production workflows demand distributed MAM nodes at stadiums and live event venues.
Industry Challenges
- Archive engineer scarcity:Expertise in MXF/IMF interchange formats and LTO tape migration commands premium compensation, constraining implementation velocity.
- SOC 2 Type II certification timelines:Six-to-twelve month audit cycles delay market entry for vendors targeting financial services and public-sector buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Media Asset Management (MAM) Solutions Market |
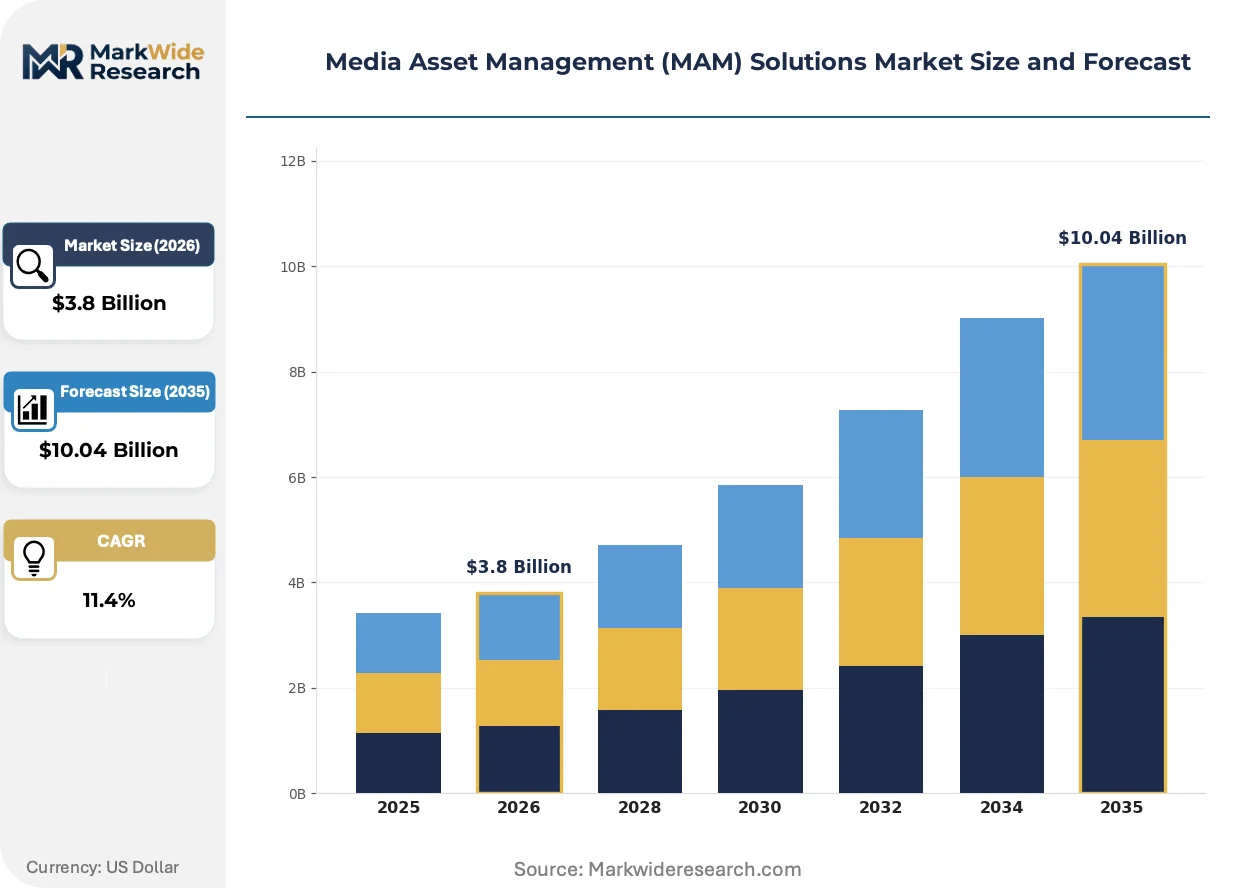
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, SaaS End User: Broadcasting, Advertising, Film Production, Media Agencies Technology: AI-Powered, Workflow Automation, Metadata Management, Digital Rights Management Deployment: Public Cloud, Private Cloud, Multi-Cloud, Edge Computing |
| Companies Covered | Canto, Aprimo, MediaValet, Frontify, Acquia DAM, Bynder, Air, Cloudinary, Brandfolder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Media Asset Management (MAM) Solutions Market Shifts & Advancements
Artificial intelligence is redefining content discoverability while regulatory pressure on algorithmic transparency forces architectural redesigns across vendor roadmaps.
Neural-network-based video analysis is migrating from experimental feature to core infrastructure. Broadcasters now expect automated scene detection, object recognition, and sentiment tagging as standard capabilities. This compression of indexing timelines from weeks to hours enables same-day archive monetization for live sports rights holders.
The EU AI Act imposes documentation and human-oversight requirements on automated content classification systems. Vendors serving European broadcasters must retrofit explainability layers into black-box recognition engines. Newsroom and documentary production segments face the steepest compliance costs due to high volumes of sensitive archival footage requiring ethical review.
Subscription-based procurement is displacing perpetual-license purchases across mid-market buyers. Channel partners and systems integrators now bundle MAM access with transcoding and delivery services in consolidated monthly fees. This shift concentrates most visibly in Germany, where Mittelstand broadcasters prioritize operational expenditure predictability over capital ownership.
Media Asset Management (MAM) Solutions Market Segmentation
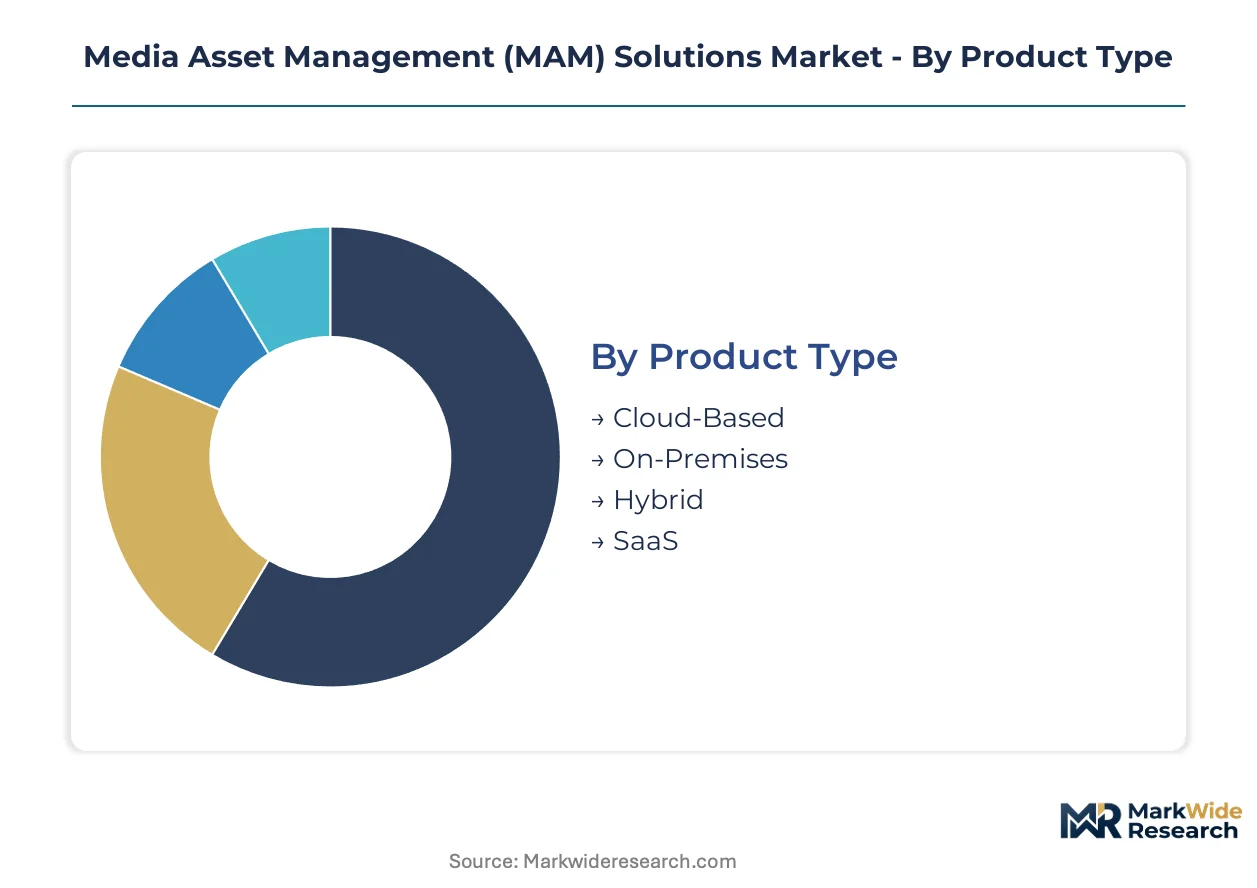
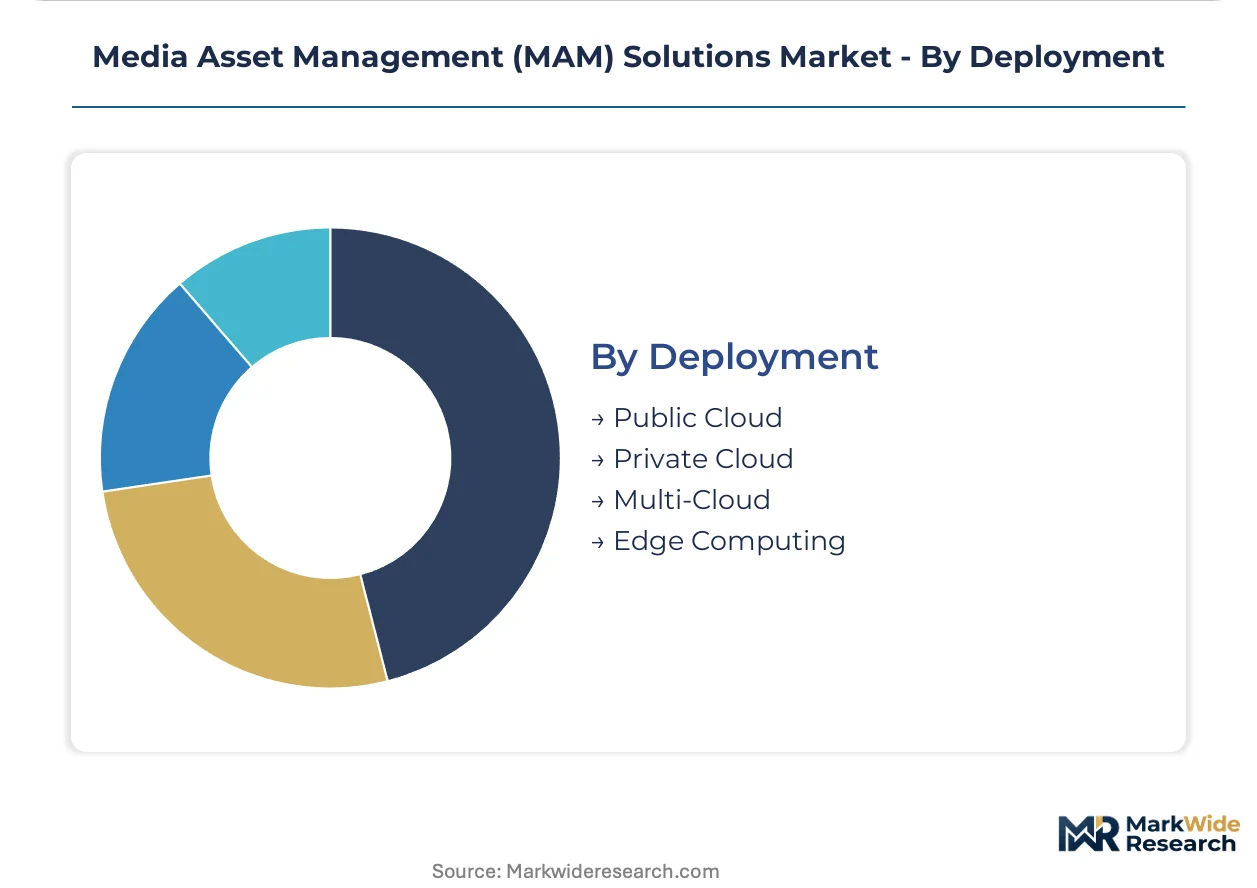
Media Asset Management Solutions segment across four critical dimensions that determine procurement priorities and technical architecture. Deployment models dictate infrastructure investment profiles, while technology tiers separate automation maturity levels across buyer organizations.
Product Type:
Maturity spreads from established perpetual-license platforms to consumption-based cloud services rewriting vendor economics.
- Cloud-Based:Architectures leverage hyperscaler infrastructure to eliminate capital expenditure on storage hardware. Major US broadcasters and European public-service media organizations prioritize these deployments for disaster recovery and distributed team access.
- On-Premises:Installations maintain local hardware control for latency-sensitive live production workflows and classified content handling. Defense contractors and sovereign wealth fund media holdings in the UAE and Saudi Arabia mandate these configurations for data residency compliance.
- Hybrid:Configurations blend local performance tiers with cloud archive tiers, enabling hot-cold storage economics for mid-market film distributors.
- SaaS:Delivery models compress procurement cycles to weeks, attracting marketing departments at multinational consumer brands seeking rapid campaign asset deployment.
Cloud-Based retains volume leadership; SaaS holds the steepest expansion curve.
End User:
Application intensity varies from real-time production environments to rights-management-heavy archive operations.
- Broadcasting:Organizations process uncompressed 4K/8K feeds requiring frame-accurate metadata synchronization for FCC closed-caption compliance. National networks in the United States and public broadcasters in Germany drive enterprise-scale deployments.
- Advertising:Agencies manage high-velocity creative versioning across localized campaign adaptations. WPP and Publicis network agencies in London and New York anchor demand for rapid proxy generation and client review workflows.
- Film Production:Studios coordinate dailies distribution and VFX handoffs across dispersed production sites.
- Media Agencies:Boutiques and independent producers seek cost-optimized tiered storage without enterprise feature overhead.
Broadcasting commands the highest per-seat licensing values; Advertising generates the most rapid user-base expansion.
Technology:
Capability layering separates experimental AI deployments from proven workflow automation installations.
- AI-Powered:Systems deploy neural networks for automated speech-to-text transcription, facial recognition indexing, and sentiment analysis. Sports leagues including the NFL and Premier League rights holders monetize decades of footage through these tools.
- Workflow Automation:Engines orchestrate transcoding, QC validation, and distribution handoffs without manual intervention. Newsroom operations at BBC and CNN depend on these systems for deadline-critical publishing pipelines.
- Metadata Management:Taxonomies and controlled vocabularies enable cross-departmental asset discovery for corporate communications teams.
- Digital Rights Management:Modules track licensing windows, territorial restrictions, and royalty obligations for studio archive monetization.
Workflow Automation retains installed-base dominance; AI-Powered claims the most aggressive upgrade investment.
Deployment:
Infrastructure topology choices reflect risk tolerance for vendor lock-in and data sovereignty requirements.
- Public Cloud:Configurations ride AWS, Azure, or Google Cloud infrastructure with shared-tenant economics. Indian streaming platforms investing in regional-language content libraries favor these for elastic capacity during production surges.
- Private Cloud:Instances isolate compute and storage resources for healthcare media and financial services compliance. Swiss private banks and German automotive manufacturers mandate these for internal video communications.
- Multi-Cloud:Architectures distribute workloads across hyperscalers to mitigate single-point-of-failure exposure and negotiate pricing leverage.
- Edge Computing:Nodes position processing capacity at stadiums, concert venues, and remote production sites for 5G-enabled live event workflows.
Public Cloud retains transaction volume leadership; Edge Computing posts the most rapid deployment growth among live sports rights holders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net export positions in media technology services concentrate in the United States and Germany, while import-dependent broadcast infrastructure expansion accelerates across India and Brazil. Cloud infrastructure investments flow disproportionately toward North American and Western European hyperscaler regions.
United States
Major studios in Los Angeles and sports leagues in New York drive enterprise-grade MAM deployments requiring FCC closed-caption compliance. The FCC mandates frame-accurate caption synchronization for broadcasters, forcing digital vault replacements. Seattle-based hyperscaler infrastructure anchors cloud-native migrations for national networks.
Germany
Public-service broadcasters in Berlin and Mittelstand media operations prioritize operational expenditure predictability through SaaS procurement. The EU AI Act imposes algorithmic transparency obligations on automated content classification systems. Munich's media technology cluster hosts compliance-tooling development for European deployments.
India
Streaming platforms investing in regional-language content libraries create demand for scalable systems handling 22-plus official languages. TRAI regulations govern content distribution infrastructure without direct MAM mandates. Mumbai's production hub generates petabyte-scale archive growth for multilingual broadcasters.
Brazil
Underpenetrated broadcast infrastructure and rising streaming investment create whitespace for cloud-native vendors. ANVISA regulates healthcare media content without direct MAM jurisdiction. São Paulo's advertising agencies anchor demand for rapid creative versioning workflows.
United Kingdom
WPP and Publicis network agencies in London drive rapid proxy generation requirements for localized campaign adaptations. GDPR data residency rules constrain cloud architecture choices for broadcast archives. Manchester's post-production cluster specializes in sports rights holder archive monetization.
Media Asset Management (MAM) Solutions Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers differentiated by deployment architecture and customer scale. Cloud-native specialists compete with legacy platform vendors migrating to subscription models. Strategic archetypes include hyperscaler-aligned SaaS providers, Azure-native security specialists, and creative workflow integrators. Dominant competitive moves encompass API ecosystem expansion and consumption-based pricing architecture adoption.
Within the cloud-native tier, Bynder and Cloudinary represent SaaS delivery models serving distributed marketing teams and developer-integrated optimization workflows respectively. MediaValet occupies a position among Azure-native infrastructure specialists competing on security certifications. These three exemplify the strategic divergence between horizontal marketing platforms and vertically integrated broadcast solutions.
| Leading Market Players |
|---|
| Canto |
| Aprimo |
| MediaValet |
| Frontify |
| Acquia DAM |
| Bynder |
| Air |
| Cloudinary |
| Brandfolder |
| Others |
Supply & Pricing Matrix
Hyperscaler concentration risk determines both pricing tier spreads and supply chain shape in Media Asset Management Solutions. AWS, Azure, and Google Cloud infrastructure dependencies create single-source vulnerability that compresses margins for archive-heavy operations while forcing vendors into consumption-based pricing architectures that pass through cloud egress volatility.
Pricing Analysis
Current-generation AI-powered indexing commands premium subscription tiers against prior-generation workflow automation platforms and emerging next-generation edge-compute nodes. Pricing stratifies across enterprise broadcast, mid-market advertising, and entry-level media agency tiers based on ISO 27001 certification status and petabyte-scale storage commitments. Cost compression in cloud archive tiers is intensifying because hyperscalers negotiate volume discounts against multi-cloud switching threats. Mid-market film distributors exhibit highest price sensitivity; defense contractors and sovereign wealth fund media holdings show lowest sensitivity due to data residency mandates.
Supply Chain Analysis
Extended payment terms from hyperscalers to MAM vendors now stretch 60-90 days, compressing working capital for platform developers. Supply concentrates in the United States for hyperscaler infrastructure, Germany for compliance-tooling development, and India for regional-language content processing engineering. Raw material dependencies include LTO tape media for migration services, GPU clusters for neural network training, and API middleware for integration layers. Single-source vulnerability runs through Azure-native specialists serving government clients. Distribution runs through channel partners and systems integrators bundling transcoding and delivery services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Media Asset Management Solutions sits at a high-growth disruption inflection where AI-powered metadata extraction rewrites competitive economics. The EU AI Act's algorithmic transparency mandates accelerate vendor consolidation around explainable AI capabilities.
For Market Incumbents: Pre-empt SaaS-native challengers by accelerating consumption-based pricing migration before subscription displacement erodes perpetual-license revenue pools. Acquire edge-compute specialists to capture 5G-enabled remote production workflows at stadiums and live venues. Defend against hyperscaler direct-entry threats by deepening API ecosystem lock-in with broadcast archive engineers. For New Entrants and Emerging Players: Pursue whitespace in Brazil's underpenetrated broadcast infrastructure where rising streaming investment outpaces legacy vendor coverage. Target India's 22-plus official language content processing gap with scalable cloud-native architectures. Enter through compliance-tooling partnerships with Munich-based media technology clusters serving EU AI Act mandates. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors Azure-native security specialists with government certifications and AI-powered indexing startups with explainable algorithmic layers. Long-term viability hinges on multi-cloud interoperability rather than hyperscaler alignment. Watch hyperscaler pricing leverage negotiations as the inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API ecosystem expansion locks in broadcast archive engineers against switching threats. |
| Geographic Expansion | Brazilian broadcast infrastructure whitespace captures streaming platform investment flows. |
| Acquisition of Specialist Firm | Edge-compute node developers enable 5G-enabled remote production workflow capture. |
| Strategic Partnership | Munich compliance-tooling alliances navigate EU AI Act algorithmic transparency mandates. |
| Product Launch | Explainable AI indexing layers differentiate offerings for European public-service broadcasters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and broadcast technology trade publications. Primary interviews engaged CTOs at national networks, IT procurement officers at sports leagues, platform engineers at streaming services, and integration specialists at systems integrators. Bottom-up triangulation across deployment model, organization size, vertical, and regional adoption pattern dimensions validates top-down market sizing.
Forecast inputs include AI adoption velocity across broadcast archives, cloud migration timelines for tape-based vault replacements, and regulatory compliance cost burdens from FCC closed-caption mandates and EU AI Act transparency requirements. CAGRs derive from segment-level growth rate reconciliation across the projection horizon. Modeling incorporates uncompressed video storage economics, neural network training cost curves, and sovereign cloud mandate proliferation.
Sensitivities concentrate around hyperscaler pricing leverage, archive engineer scarcity compensation inflation, and algorithmic explainability retrofit timelines. Forecasts reflect assumptions about cloud egress fee stabilization and multi-cloud interoperability standardization. Macroeconomic downturn compressing advertising agency MAM budgets, regulatory acceleration of data localization rules, or breakthroughs in on-device AI indexing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
China EDA Electronic Design Automation Market
Digital Solutions
Content Moderation Services Market
Digital Solutions
Load Balancer Market
Digital Solutions
Mexico Online Gambling Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Middle East Smart Card Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Digital Signage Market
Digital Solutions
Digital Commerce Platform Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Customer-To-Customer (C2C) Community Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Consent Management Market
Digital Solutions
Global Data Virtualization Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market