
 United Kingdom Digital Twin Market | 2026-2036
United Kingdom Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Digital Twin Market Insights
Subscription-based software-defined feature layers is decoupling perpetual licensing from value capture in the United Kingdom digital twin landscape. Siemens leverages deep industrial automation heritage to anchor high-loyalty manufacturing accounts. Dassault Systèmes sustains dominance through integrated product lifecycle management suites that span design-to-operations workflows. Aveva Group specializes in energy and infrastructure verticals where complex asset hierarchies demand specialized visualization.
A digital twin constitutes a dynamic virtual replica of a physical asset, system, or process that ingests real-time sensor data and applies physics-based simulation algorithms to mirror operational behavior, predict degradation, and optimize performance across industrial and built environments. Simulation platforms command the largest solution-type revenue pool due to their centrality in predictive maintenance and process optimization workflows. Smart manufacturing applications within the manufacturing firms end-user category are expanding fastest as British factories pursue OEE improvements and carbon accountability under tightening environmental disclosure rules.
The UK National Digital Twin Programme and BS ISO 23247 standards framework shape interoperability requirements and data governance protocols for vendors seeking public-sector contracts. The Health and Safety Executive's process safety expectations for hazardous facilities further embed twin-based monitoring into regulated industries. Stakeholders must weigh cloud-versus-hybrid deployment commitments against evolving UK data residency expectations and sector-specific cybersecurity certifications.
Market Dynamics
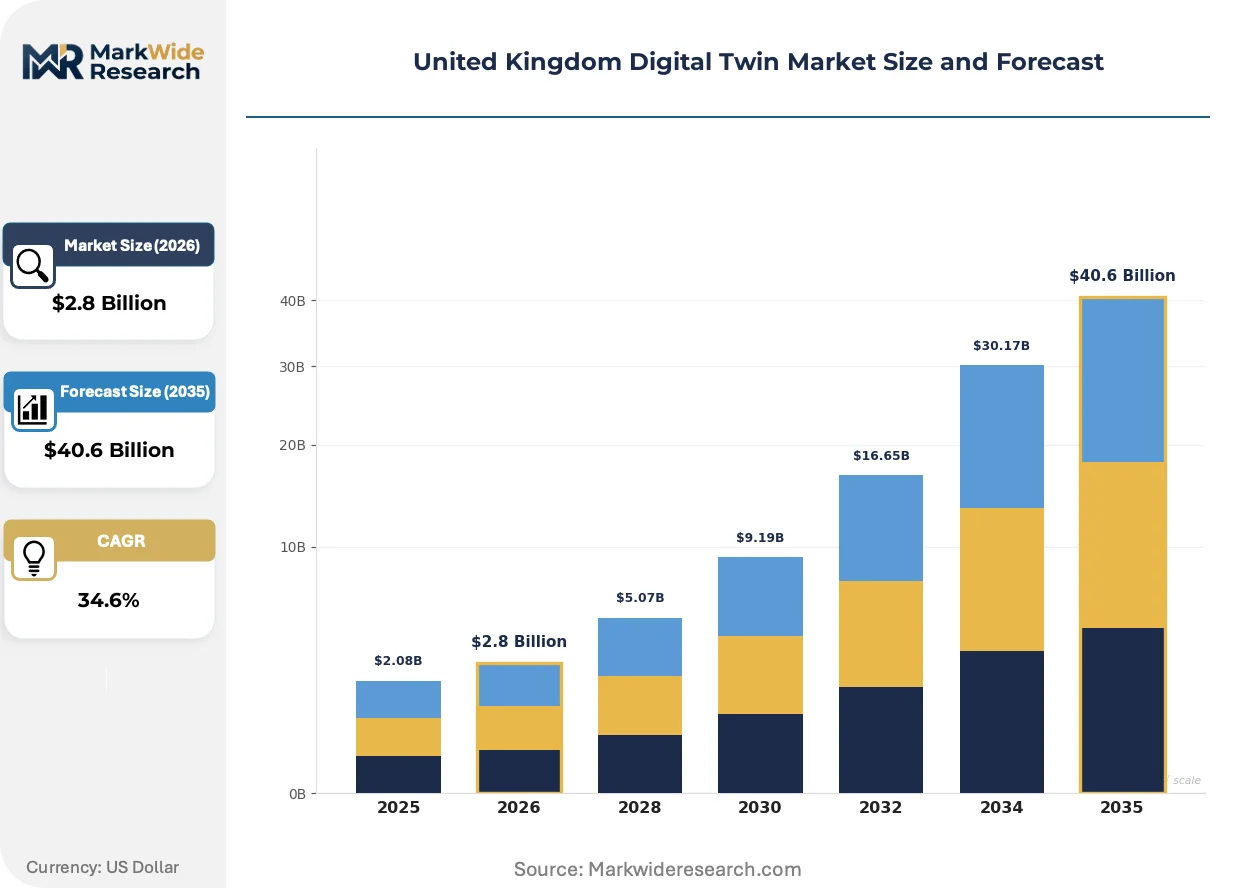
The United Kingdom Digital Twin Market is experiencing structural pressure from the National Digital Twin Programme's procurement mandates, which now require BIM Level 2 compliance for all publicly funded infrastructure projects and are accelerating vendor consolidation around interoperable data standards.
Growth Catalysts
- BS ISO 23247 framework adoption:The British Standards Institution's digital twin reference architecture creates unified data governance protocols that reduce integration friction across asset-heavy industries.
- Health and Safety Executive process safety mandates:Hazardous facility operators in chemicals and oil refining must deploy continuous monitoring systems, embedding twin-based predictive analytics into regulatory compliance workflows.
- Greater Manchester smart manufacturing cluster:Concentrated industrial automation investment across advanced materials and aerospace supply chains generates dense demand for asset optimization platforms.
Market Restraints
- Cloud-to-edge latency constraints:Real-time physics simulation for high-frequency rotating machinery requires sub-10 millisecond response times that public cloud architectures struggle to guarantee consistently.
- Specialized systems engineering talent scarcity:The intersection of industrial domain expertise, data science, and 3D visualization skills commands salary premiums that mid-market manufacturing firms cannot absorb.
- Cybersecurity certification fragmentation:Sector-specific requirements from the National Cyber Security Centre for critical national infrastructure create overlapping compliance burdens without mutual recognition.
Strategic Opportunities
- NHS estate modernization:Hospital infrastructure digitalization programmes spanning thermal comfort optimization and medical equipment lifecycle management represent an underpenetrated vertical with standardized procurement pathways.
- AI-physics hybrid simulation convergence:Neural network acceleration of finite element analysis is compressing computation time for complex fluid dynamics scenarios by orders of magnitude.
- Net-zero disclosure obligations:Streamlined Energy and Carbon Reporting mandates force asset-intensive firms to model embodied carbon and operational emissions through integrated twin environments.
Industry Challenges
- Legacy SCADA protocol incompatibility:Decades-old industrial control systems use proprietary data formats that require expensive middleware development for twin ingestion pipelines.
- Data ownership ambiguity in multi-stakeholder projects:Construction consortiums involving developers, operators, and maintenance contractors generate disputes over who controls the digital twin asset post-handover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Digital Twin Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $40.6 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Simulation Platforms, Visualization Tools, Analytics Engines, Integration Modules, Data Management Systems Application: Smart Manufacturing, Urban Planning, Energy Management, Infrastructure Monitoring, Asset Optimization End User Industry: Manufacturing Firms, Construction Companies, Energy Providers, Logistics Operators, Facility Managers Deployment Mode: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Siemens, Dassault Systèmes, ANSYS, Aveva Group, Schneider Electric, GE Vernova, PTC, Honeywell International, Accenture, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Digital Twin Market Trends and Innovations
Generative AI capabilities are being woven into simulation workflows, enabling natural language interfaces for scenario modeling and automated generation of physics-based digital replicas from unstructured engineering documents.
Physics-informed machine learning is rewriting how British manufacturers approach predictive maintenance. These hybrid models embed domain constraints directly into neural architectures, reducing training data requirements by incorporating first-principles knowledge. Aerospace and power generation operators are deploying these systems for turbine blade degradation forecasting. The technology is compressing time-to-insight from weeks to hours, forcing traditional simulation vendors to rearchitect their computational engines.
The UK government's National Digital Twin Programme mandates are reshaping public procurement specifications. Infrastructure operators must now demonstrate federated data interoperability across asset lifecycles to qualify for central government funding. Transport for London and Network Rail are requiring open data formats that prevent vendor lock-in. This regulatory pressure is fragmenting the supplier landscape between compliance-ready incumbents and modular specialists.
Subscription-based feature unbundling is altering how manufacturing buyers acquire twin capabilities. Large industrial groups are rejecting monolithic perpetual licenses in favor of metered access to specific simulation modules. Automotive and pharmaceutical producers in the Midlands and Southeast England are piloting usage-based pricing for supply chain visibility tools. This behavioral shift is most visible among FTSE 250 manufacturers seeking operational expenditure treatment for digital infrastructure investments.
United Kingdom Digital Twin Market Segmentation
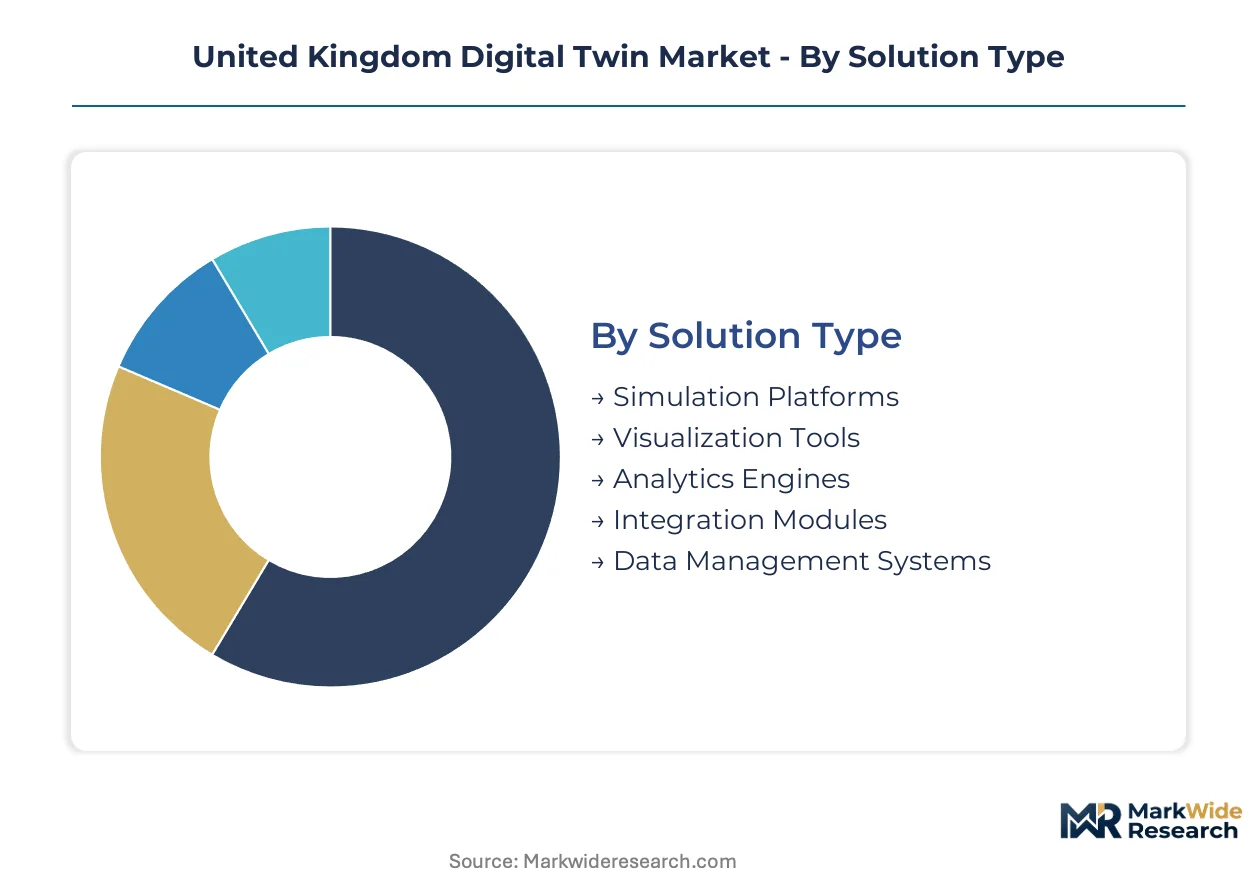
United Kingdom digital twin deployments vary sharply by operational maturity and legacy system replacement cycles. Procurement patterns diverge between asset-heavy incumbents modernizing brownfield sites and greenfield projects embedding twin architectures from commissioning.
Solution Type:
Replacement timelines for legacy engineering software are compressing as BS ISO 23247 mandates force interoperability upgrades across public infrastructure portfolios.
- Simulation Platforms:Physics-based computational engines execute finite element analysis and computational fluid dynamics for predictive maintenance scenarios. British aerospace and power generation operators in the Midlands deploy these for turbine degradation forecasting under Health and Safety Executive continuous monitoring requirements.
- Analytics Engines:Machine learning pipelines process sensor streams to detect anomaly patterns and prescribe maintenance interventions. Greater Manchester smart manufacturing clusters favor these for overall equipment effectiveness optimization as carbon disclosure rules tighten.
- Visualization Tools:3D rendering interfaces translate complex asset hierarchies into operational dashboards for control room operators.
- Integration Modules:Middleware layers bridge proprietary SCADA protocols with modern twin ingestion pipelines.
- Data Management Systems:Federated data lakes govern multi-stakeholder asset information across construction handover workflows.
Volume placements concentrate in Simulation Platforms; the faster expansion belongs to Analytics Engines.
Application:
Cost-tier differentiation separates enterprise-grade deployments from mid-market pilot programs across British industrial zones.
- Smart Manufacturing:Real-time production line twins synchronize physical and virtual states for quality control and throughput optimization. Automotive and pharmaceutical producers in the Southeast pilot usage-based pricing models for supply chain visibility under Streamlined Energy and Carbon Reporting obligations.
- Infrastructure Monitoring:Bridge, tunnel, and railway asset twins ingest structural health sensor data for predictive degradation assessment. Transport for London mandates open data formats that prevent vendor lock-in across these deployments.
- Asset Optimization:Lifecycle value maximization for heavy industrial equipment through condition-based maintenance scheduling.
- Energy Management:Grid and facility-level twins model consumption patterns against renewable generation profiles.
- Urban Planning:City-scale digital twins integrate transportation, utilities, and building performance for development scenario testing.
Revenue weight sits with Infrastructure Monitoring; Smart Manufacturing is climbing the fastest as factory automation budgets expand.
End User Industry:
Customer-type segmentation reflects divergent procurement authority and technical staffing capabilities across British sectors.
- Manufacturing Firms:Discrete and process manufacturers deploy twins for OEE improvement and regulatory compliance documentation. FTSE 250 industrial groups favor operational expenditure treatment through subscription-based feature access rather than perpetual licensing.
- Energy Providers:Generation, transmission, and distribution operators model asset performance under Net Zero disclosure mandates.
- Construction Companies:Project consortia generate disputes over digital twin ownership post-handover, complicating data governance.
- Facility Managers:Estate operators optimize thermal comfort and equipment lifecycles in commercial and healthcare properties.
- Logistics Operators:Warehouse and distribution network twins synchronize inventory flows with transportation assets.
Procurement volume clusters around Manufacturing Firms; NHS estate modernization is gaining share fastest among Facility Managers.
Deployment Mode:
Supply concentration in cloud infrastructure is displacing traditional on-premises installations as data residency frameworks mature.
- Cloud-Based:Scalable compute resources host simulation workloads without capital-intensive hardware procurement. National Cyber Security Centre certification requirements for critical national infrastructure create compliance friction that slows adoption in regulated sectors.
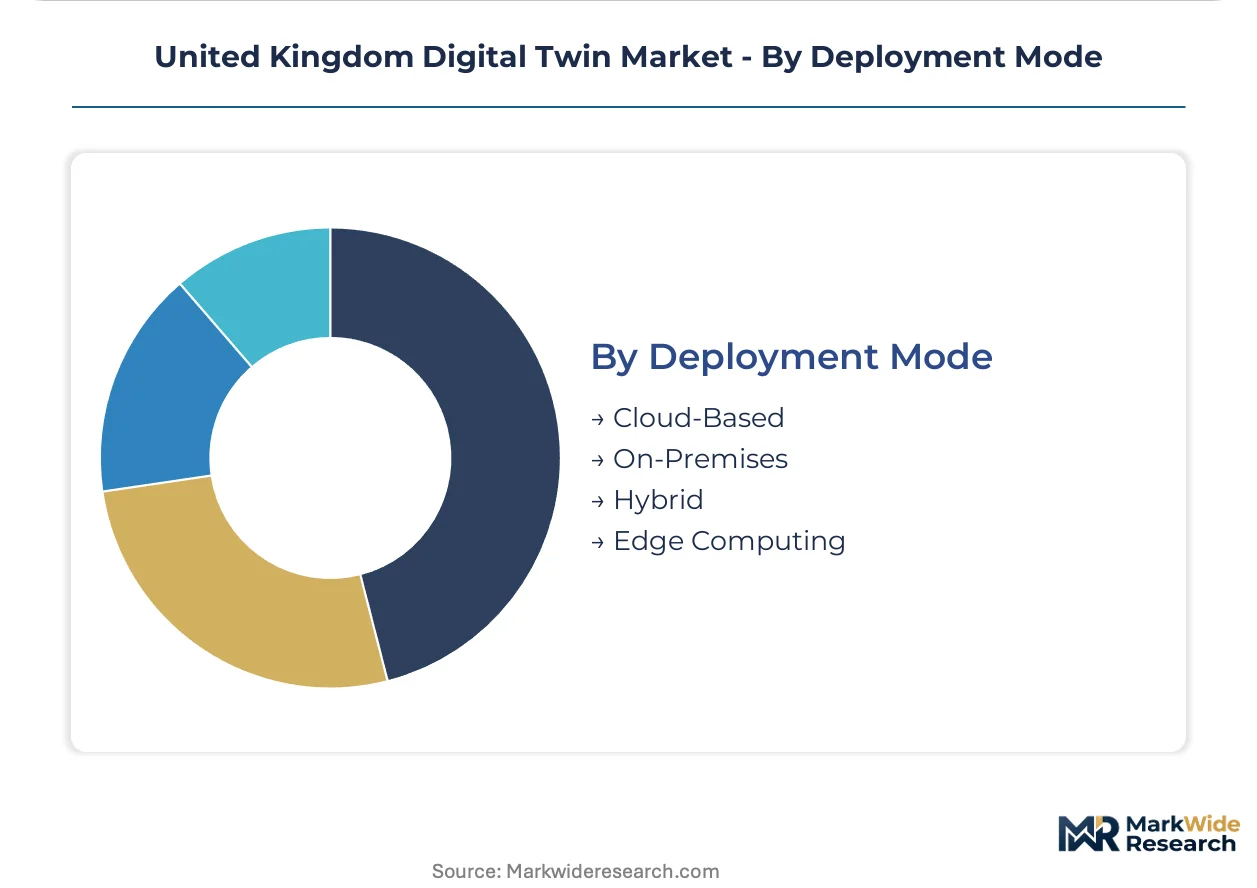
- Hybrid:Sensitive operational data remains on-premises while analytics workloads burst to cloud resources. This architecture dominates among energy providers balancing latency requirements against centralized processing economies.
- Edge Computing:Sub-10 millisecond response times for high-frequency rotating machinery monitoring push computation toward plant-floor nodes.
- On-Premises:Air-gapped installations persist in defense and classified industrial facilities with strict data sovereignty requirements.
Deployment volume favors Hybrid architectures; Edge Computing shows steepest expansion trajectory as factory automation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United Kingdom digital twin production concentrates in software engineering hubs, while consumption spreads across industrial zones demanding asset optimization. London and Southeast England generate platform development, whereas Midlands and North England manufacturing clusters absorb deployment capacity.
London and Southeast England
Financial services and infrastructure operators drive demand for building performance twins and real-time monitoring dashboards. Transport for London mandates open data formats that prevent vendor lock-in across its estate. The capital's technology corridor hosts engineering software development for predictive maintenance platforms serving national clients.
Midlands
Automotive and pharmaceutical producers pilot subscription-based twin modules for supply chain visibility and carbon reporting compliance. Streamlined Energy and Carbon Reporting obligations force asset-intensive firms to model operational emissions through integrated environments. Birmingham and Coventry manufacturing zones deploy production line synchronization for quality control improvements.
North England
Greater Manchester's smart manufacturing cluster generates dense demand for overall equipment effectiveness optimization and industrial automation integration. The Health and Safety Executive's process safety expectations embed twin-based monitoring into chemicals and materials processing facilities. Liverpool and Sheffield industrial zones pursue brownfield modernization with hybrid cloud-edge architectures.
Scotland
North Sea energy operators deploy asset lifecycle twins for offshore platform maintenance and decommissioning planning under Net Zero disclosure mandates. Aberdeen's oil and gas engineering base transitions toward renewable energy asset modeling. Edinburgh's data science sector contributes physics-informed machine learning capabilities for predictive degradation forecasting.
Wales
Advanced manufacturing and compound semiconductor facilities adopt digital twin architectures for cleanroom environmental control and equipment calibration. The Welsh Government's innovation funding prioritizes digital manufacturing adoption among small and medium enterprises. Cardiff and Newport industrial parks concentrate pilot programs for supply chain resilience modeling.
United Kingdom Digital Twin Market Competitive Landscape
Top-tier vendors anchor the premium software tier, while specialized integrators occupy the mid-market implementation layer. Siemens leverages deep industrial automation heritage to anchor high-loyalty manufacturing accounts. Dassault Systèmes sustains dominance through integrated product lifecycle management suites. Strategic moves concentrate on subscription-based feature unbundling and AI-physics hybrid simulation convergence.
Within the integrated platform tier, Siemens and Dassault Systèmes exemplify divergent approaches to manufacturing verticals. Aveva Group occupies a position among infrastructure and energy specialists where complex asset hierarchies demand specialized visualization. These three entities represent the spectrum from broad industrial automation to sector-specific engineering software, illustrating how procurement mandates from the National Digital Twin Programme favor vendors with proven interoperability credentials.
| Leading Market Players |
|---|
| Siemens |
| Dassault Systèmes |
| ANSYS |
| Aveva Group |
| Schneider Electric |
| GE Vernova |
| PTC |
| Honeywell International |
| Accenture |
| Others |
Pricing and Supply Chain Analysis
Industrial software licensing benchmarks cascade through the United Kingdom digital twin supply chain, compressing margins for systems integrators while amplifying pricing power for platform vendors holding BS ISO 23247 certification credentials.
Pricing Analysis
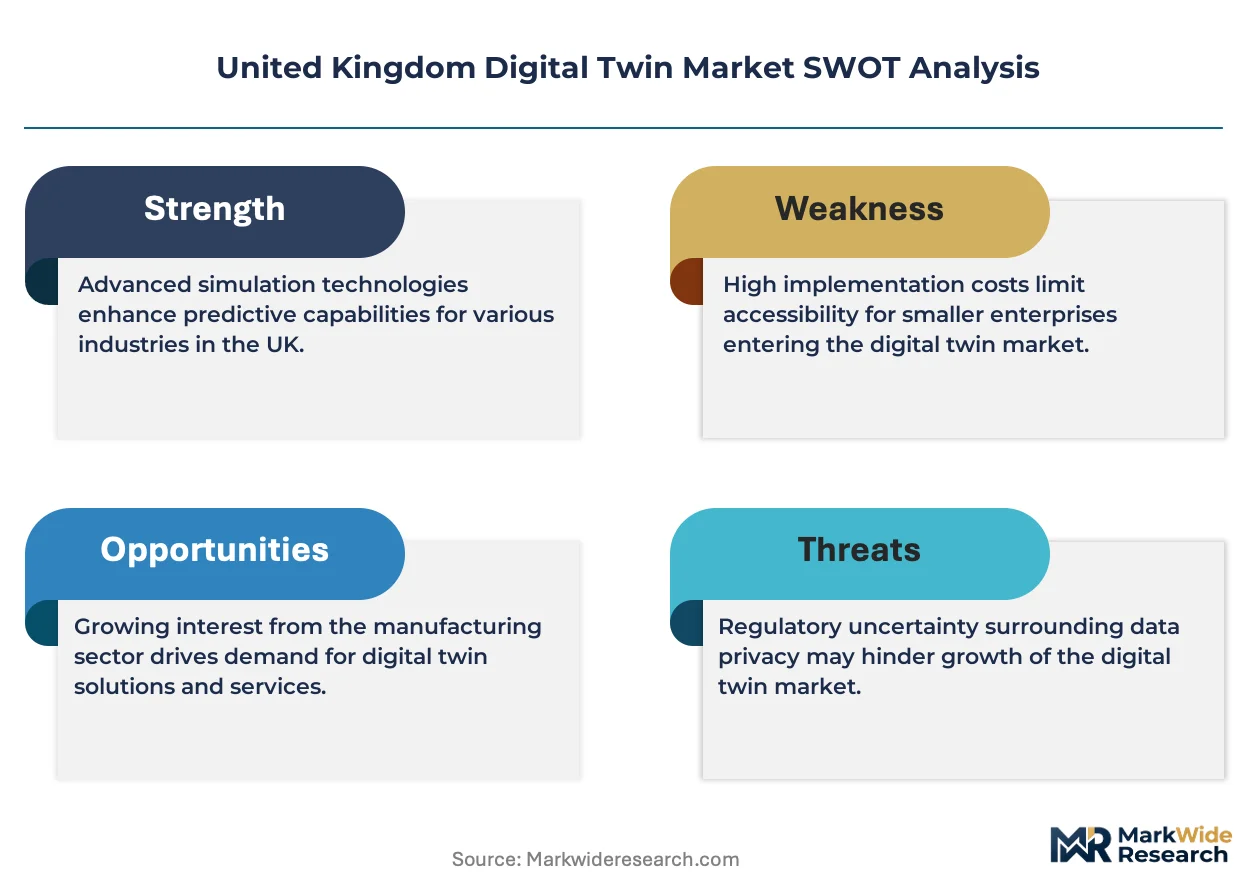
Margin tightening in mid-market manufacturing deployments reflects subscription unbundling pressure from FTSE 250 buyers seeking operational expenditure treatment. Three-tier pricing structure across premium, standard, and economy levels separates certified interoperability platforms from modular point solutions. Cost-down pressure on visualization modules accelerates because Greater Manchester smart manufacturing clusters negotiate usage-based contracts. Price differentiation hinges on Health and Safety Executive compliance documentation and AI-physics hybrid simulation capabilities.
Supply Chain Analysis
Specialized systems engineering talent scarcity in British university towns and Greater London technology corridors constrains implementation capacity for complex asset hierarchy deployments. Platform development draws from Germany, France, and the United States for core simulation engines, while integration services source from domestic industrial automation specialists. Single-source vulnerability concentrates in neural network acceleration hardware for finite element analysis. Distribution runs through certified systems integrators serving Midlands automotive and North England chemicals corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom digital twin market sits at a physics-informed machine learning transition, with neural network acceleration displacing traditional computational fluid dynamics solvers in predictive maintenance workflows.
For Market Incumbents: To counter modular specialist encroachment into infrastructure monitoring verticals, anchor manufacturing accounts through backward integration into edge computing hardware and deepen subscription platform stickiness with AI-physics hybrid modules that compress turbine degradation forecasting from weeks to hours. For New Entrants and Emerging Players: Begin with NHS estate modernization white space, where hospital infrastructure thermal comfort optimization lacks standardized procurement pathways and Facility Managers demonstrate acute price sensitivity. Target usage-based pricing pilots in Southeast England pharmaceutical cleanroom environmental control applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-ready mid-cap specialists with proven BS ISO 23247 interoperability credentials in North England chemicals corridors. Watch Transport for London open data format mandates as inflection signal for vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Federated data interoperability across Transport for London and Network Rail estates prevents vendor lock-in per National Digital Twin Programme mandates. |
| Acquisition of Specialist Firm | Physics-informed machine learning capabilities from Edinburgh data science sector compress time-to-insight for North Sea offshore platform maintenance. |
| Product Launch | Natural language scenario modeling interfaces capitalize on generative AI convergence in Midlands automotive supply chain visibility tools. |
| Strategic Partnership | Greater Manchester smart manufacturing cluster alliances accelerate overall equipment effectiveness optimization pilot deployments. |
| Geographic Expansion | Wales compound semiconductor cleanroom environmental control penetration leverages Welsh Government innovation funding for SME adoption. |
Research Methodology
Document review covered National Digital Twin Programme procurement specifications, Health and Safety Executive process safety guidance, and BS ISO 23247 standards documentation, complemented by interviews with industrial automation engineers, facility management directors at NHS trusts, smart manufacturing cluster coordinators, and platform vendor solution architects. Secondary validation drew from UK government infrastructure spending disclosures, British Standards Institution publications, and hyperscaler cloud certification registries. Bottom-up deployment sizing triangulated against top-down industrial automation investment flows.
Segment-level projections across solution type, application, end user industry, and deployment mode were generated through adoption curve modeling calibrated against BIM mandate compliance timelines and carbon disclosure regulation enforcement patterns. CAGRs were derived from replacement cycle compression analysis and interoperability upgrade obligation schedules. Physics simulation workload migration patterns and neural network training cost trajectories informed platform revenue allocation assumptions.
Underlying measurement precision varies by segment; Infrastructure Monitoring and Smart Manufacturing carry tighter precision than emerging Urban Planning applications. Forecasts reflect documented assumptions regarding National Cyber Security Centre certification timelines and Streamlined Energy and Carbon Reporting enforcement consistency. Material deviation in Health and Safety Executive mandate expansion or BS ISO 23247 revision schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
India Loyalty Program Market
Digital Solutions
India PLM Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Workflow Management System Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Ediscovery Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Application Performance Management Market
Digital Solutions
Personality Assessment Solutions Market
Digital Solutions
Crop Management Software Market
Digital Solutions
Digital Rights Management (DRM) Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
North America IT Asset Disposition Market