
 Europe ICT Market | 2026-2036
Europe ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Europe ICT Market Analysis
Multi-source procurement for semiconductor lithography systems is broadening across European foundries. ASML anchors advanced node equipment supply from its Veldhoven base. Infineon sustains power semiconductor fabrication through its Dresden manufacturing complex. Nokia competes in Open RAN infrastructure across Nordic and German carrier networks.
Information and communications technology encompasses electronic systems, software architectures, and network infrastructure enabling data processing, transmission, and storage at speeds exceeding 400 Gbps in backbone fiber deployments. Its primary commercial purpose is reducing transaction latency and automating decision workflows across distributed enterprises. Software and cloud solutions capture expanding margin pools as enterprises migrate from capital-intensive on-premises stacks to subscription-based consumption. Cybersecurity technology leads growth within the technology dimension as NIS2 Directive deadlines harden resilience requirements for critical infrastructure operators. Hybrid cloud deployment dominates large-finance adoption where data sovereignty concerns fragment workload placement between private controlled environments and hyperscale public regions.
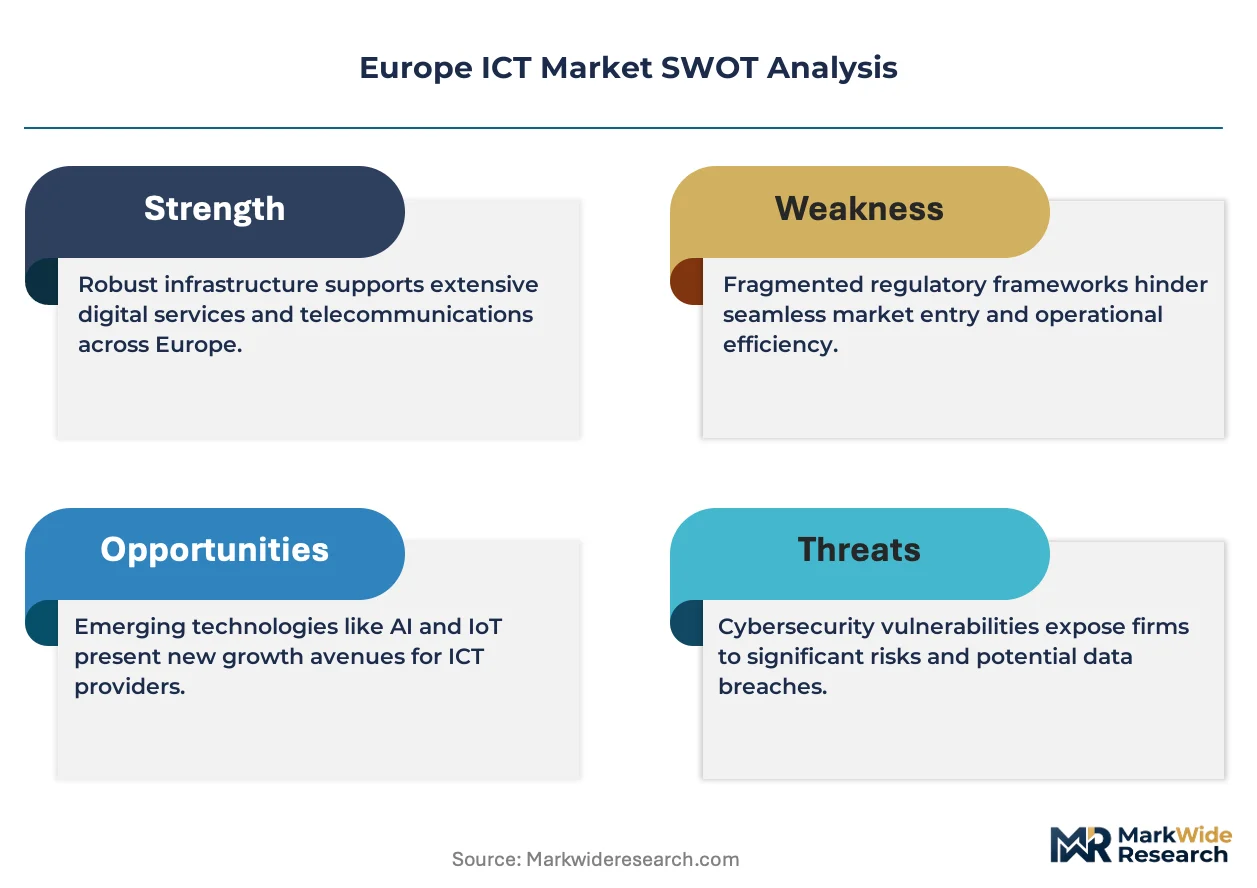
GDPR enforcement by national data protection authorities shapes cross-border data flow architectures and vendor selection criteria. The EU AI Act's risk-classification framework forces conformity assessments for high-risk applications in healthcare diagnostics and credit scoring. ETSI standards for network interoperability govern 5G equipment certification across member states. Stakeholders must monitor how the CSRD's digital reporting mandates reshape enterprise software procurement priorities.
Market Dynamics
The EU AI Act's risk-classification framework is restructuring conformity assessment requirements for algorithmic systems across healthcare diagnostics and financial services, forcing vendors to redesign product architectures before enforcement deadlines crystallize.
Growth Catalysts
- CSRD Digital Reporting Mandates:The Corporate Sustainability Reporting Directive compels enterprise software procurement cycles as large-cap industrials replace legacy ERP stacks with integrated ESG data platforms.
- German Automotive Cloud Migration:Stuttgart and Munich-based OEMs are consolidating supplier data exchanges onto hyperscale infrastructure to support software-defined vehicle architectures.
- NIS2 Cybersecurity Deadlines:The directive hardens resilience requirements for energy and transport operators, expanding addressable market for managed security service providers.
Market Restraints
- Advanced Node Equipment Concentration:EUV lithography supply from Veldhoven creates single-point vulnerability for sub-7nm fabrication capacity expansion.
- GDPR Cross-Border Friction:Schrems II enforcement complicates transatlantic data flows, fragmenting cloud workload placement decisions for multinational enterprises.
- Legacy System Interoperability:Decades-old mainframe architectures in French banking resist API-based integration with modern cloud-native stacks.
Strategic Opportunities
- Paris-Saclay Enterprise Corridor:The cluster's density of AI research labs and SaaS scale-ups creates concentrated demand for specialized data infrastructure.
- 5G Open RAN Deployment:Nordic carrier networks are disaggregating hardware from software layers, opening procurement to non-incumbent radio vendors.
- AI Act Conformity Services:High-risk application assessments for healthcare diagnostics create recurring revenue pools for accredited testing bodies.
Industry Challenges
- Semiconductor Process Engineering Talent:Dresden and Leuven fabs compete for finite pools of EUV technicians and compound semiconductor specialists.
- Multi-Cloud Integration Complexity:Hybrid deployments spanning private controlled environments and hyperscale regions strain DevOps orchestration capabilities.
- ETSI Certification Timelines:5G equipment approval cycles delay network modernization programs for tier-two mobile operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe ICT Market |
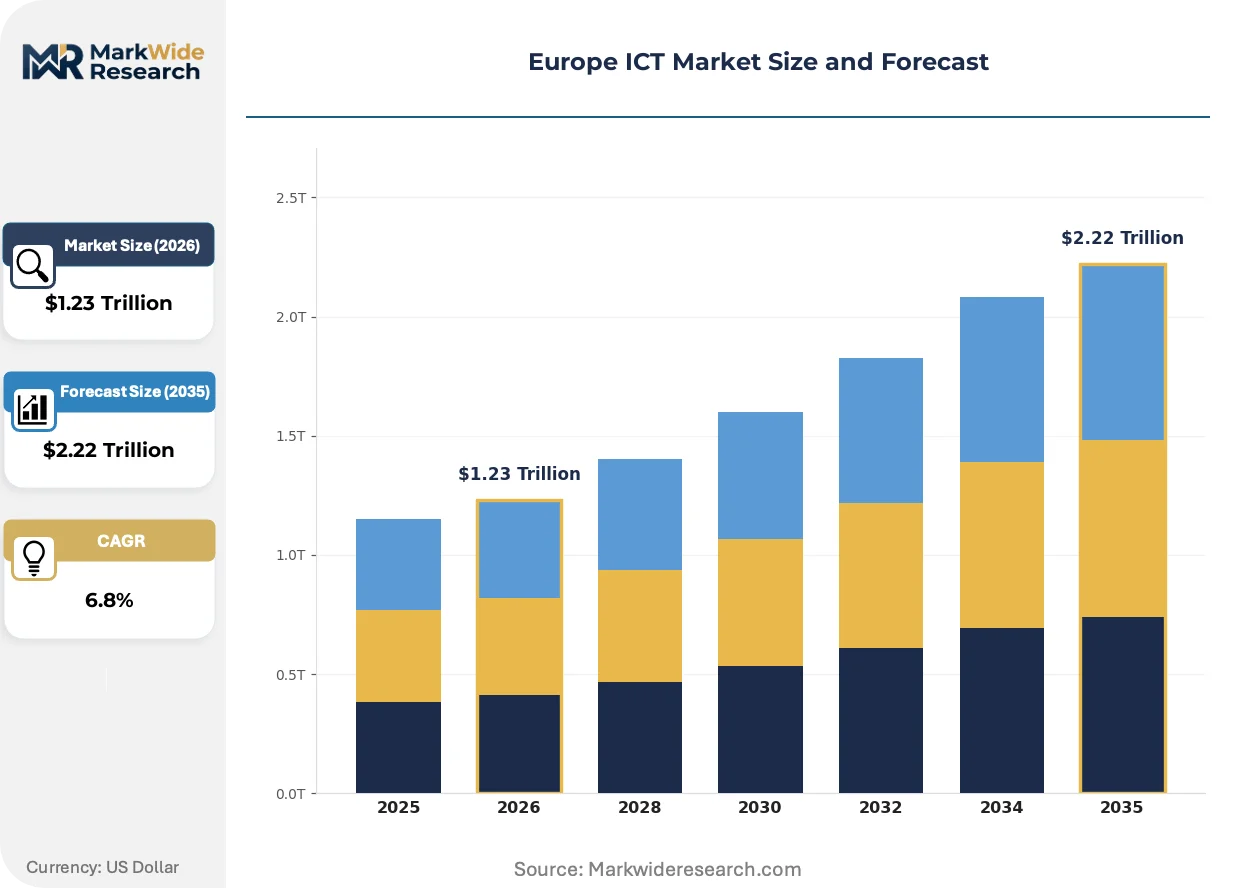
| Market Size in 2026 | $1.23 Trillion |
| Market Size in 2035 | $2.22 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Cloud Solutions End User: Finance, Education, Healthcare, Telecommunications Technology: AI, IoT, Blockchain, Cybersecurity Deployment: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud |
| Companies Covered | Spotify, Adyen, ASML, Dassault Systèmes, Nokia, SAP, Infineon, Capgemini, Prosus, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe ICT Market Emerging Trajectories
Generative AI inference workloads are redistributing compute demand from centralized training clusters toward edge-optimized architectures, while regulatory fragmentation accelerates specialized compliance tooling.
ARM-based server processors are overtaking x86 dominance in hyperscale data centers. Cloud operators in Frankfurt and Dublin are deploying Graviton and Ampere Altra instances for web serving and containerized microservices. The shift is overtaking traditional socket-based pricing models and compressing energy consumption metrics for sustainability reporting.
The EU AI Act's conformity assessment framework is mandating technical documentation and risk management systems for high-risk applications. Medical device manufacturers must integrate algorithmic transparency requirements into quality management systems. French and German notified bodies are building specialized AI audit capacities to handle certification volume.
Subscription consumption models are displacing perpetual license structures in enterprise software procurement. CIOs in the Netherlands and Belgium are unbundling maintenance from core platform fees and negotiating usage-based pricing for analytics workloads. This reconfiguration is most visible in financial services verticals where variable cost structures align with regulatory capital constraints.
Europe ICT Market Segmentation
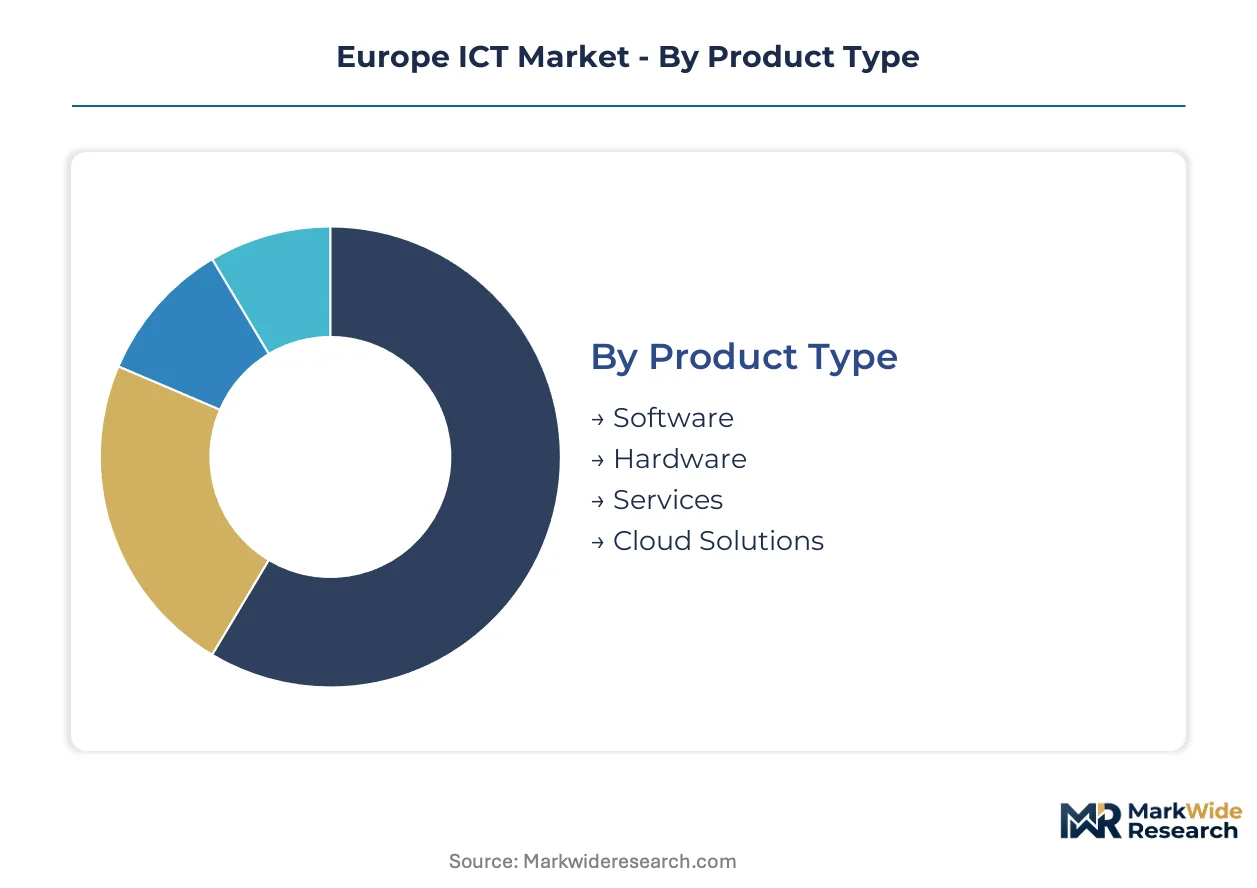
ICT procurement in Europe fragments across four interlocking dimensions that shape vendor selection and contract structures. Buyers prioritize data sovereignty compliance, legacy system interoperability, and subscription economics when allocating budgets across these categories.
Product Type:
Enterprise buyers weigh total cost of ownership against migration complexity when selecting product categories, with cloud-native architectures displacing capital-intensive hardware commitments.
- Software:Subscription-based enterprise applications dominate procurement cycles as French and German industrials replace perpetual-license ERP stacks. Demand concentrates in integrated ESG reporting platforms driven by CSRD disclosure deadlines.
- Cloud Solutions:Hyperscale infrastructure services capture expanding margin pools as Stuttgart automotive OEMs consolidate supplier data exchanges for software-defined vehicle programs. German and French banking regulators' data localization requirements fragment workload placement decisions.
- Services:Managed security and AI conformity assessment offerings expand as NIS2 implementation hardens resilience mandates for energy operators.
- Hardware:Server and storage procurement compresses as enterprises shift compute consumption to subscription models, though edge inference devices gain traction for low-latency AI workloads.
Cloud Solutions leads on scale; AI conformity services within Services leads on momentum.
End User:
Vertical-specific compliance architectures reshape how vendors configure product roadmaps and pricing tiers.
- Healthcare:Medical device manufacturers integrate algorithmic transparency requirements into quality management systems under EU AI Act high-risk classification rules. French notified bodies are building specialized audit capacities to handle diagnostic imaging certification volume.
- Finance:Hybrid cloud deployment dominates as data sovereignty concerns fragment workload placement between private controlled environments and hyperscale regions. Dutch and Belgian CIOs negotiate usage-based pricing for analytics workloads to align with regulatory capital constraints.
- Telecommunications:Open RAN disaggregation opens procurement to non-incumbent radio vendors across Nordic carrier networks, though ETSI certification timelines delay modernization programs.
- Education:Public sector procurement cycles favor standardized framework agreements with emphasis on GDPR-compliant data processing and long-term support commitments.
Finance leads on scale; Healthcare leads on momentum.
Technology:
Regulatory risk classification determines which technology layers command premium pricing and specialized implementation services.
- Cybersecurity:Resilience technology leads growth as NIS2 Directive deadlines expand addressable market for managed security service providers serving energy and transport operators.
- AI:Generative inference workloads redistribute compute demand from centralized training clusters toward edge-optimized architectures in Paris-Saclay research corridors.
- IoT:Industrial sensor networks in German manufacturing clusters require harmonized data formats for supplier exchange platforms.
- Blockchain:Distributed ledger applications concentrate in supply chain traceability and digital identity verification for cross-border trade documentation.
Cybersecurity leads on scale; AI leads on momentum.
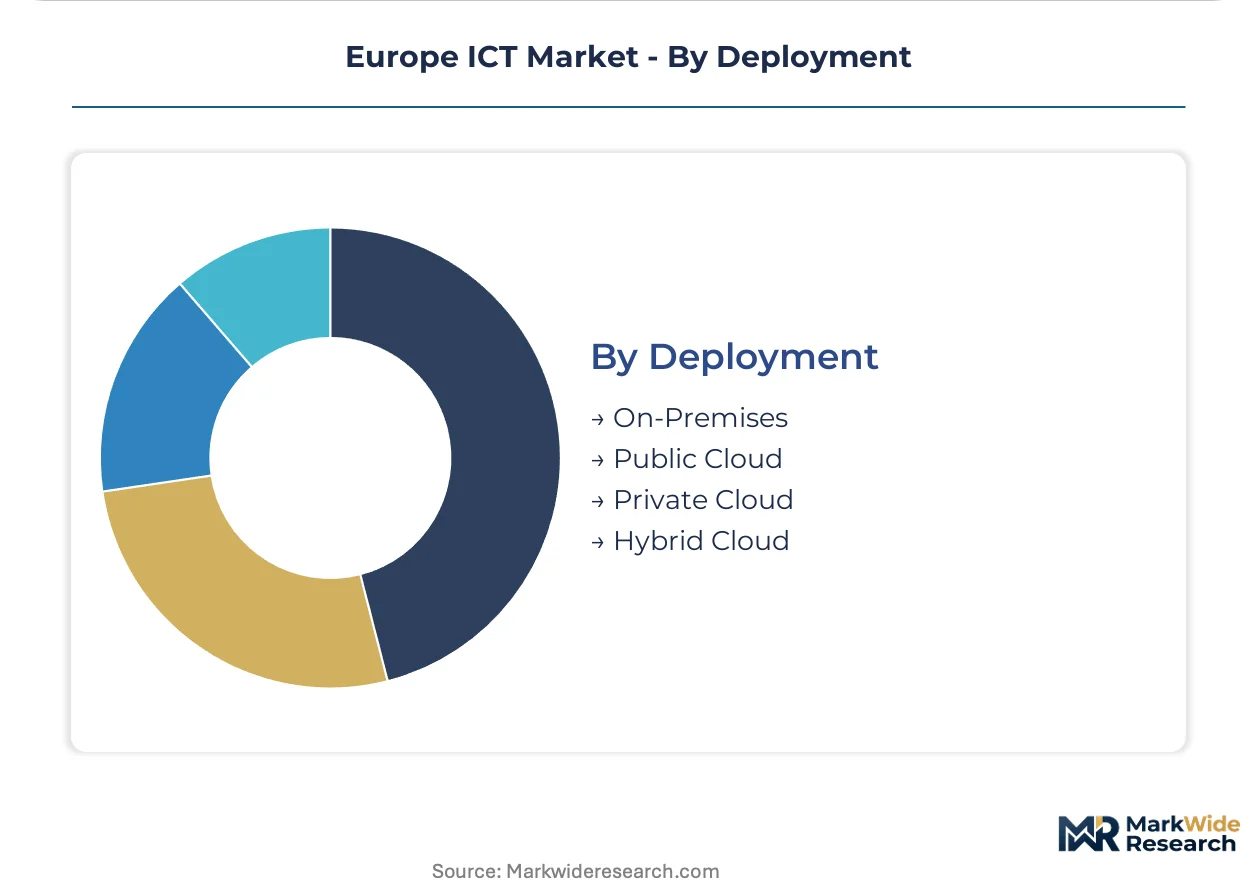
Deployment:
Data residency requirements and latency sensitivity determine workload placement across infrastructure layers.
- Hybrid Cloud:Large-finance adoption dominates where data sovereignty concerns fragment placement between private controlled environments and hyperscale public regions in Frankfurt and Dublin.
- Private Cloud:German automotive manufacturers consolidate supplier exchanges onto dedicated infrastructure to maintain architectural control over software-defined vehicle programs.
- Public Cloud:ARM-based Graviton and Ampere Altra instances displace x86 dominance for web serving and containerized microservices, compressing energy consumption metrics for sustainability reporting.
- On-Premises:French banking mainframe architectures resist API-based integration with modern cloud-native stacks, preserving legacy maintenance revenue pools.
Hybrid Cloud leads on scale; Private Cloud leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing ICT investment across European member states as compliance cost differentials widen between jurisdictions with mature digital frameworks and those building enforcement capacity.
Germany
Stuttgart and Munich automotive OEMs are consolidating supplier data exchanges onto hyperscale infrastructure for software-defined vehicle architectures. The national data protection authority enforces GDPR with sector-specific guidance for connected vehicle telemetry. Dresden anchors EUV-dependent power semiconductor fabrication through Infineon's manufacturing complex.
France
Paris-Saclay's density of AI research labs and SaaS scale-ups concentrates demand for specialized data infrastructure serving healthcare diagnostics and financial modeling. The national pharmaceutical regulator ANSM coordinates with notified bodies on EU AI Act high-risk application assessments. Île-de-France banking clusters resist mainframe-to-cloud migration despite API standardization pressure.
Netherlands
Veldhoven-based lithography equipment supply creates single-point dependency for advanced node fabrication capacity across European foundries. The Dutch Authority for Digital Infrastructure enforces NIS2 resilience mandates for energy and transport operators. Amsterdam and Rotterdam data center clusters attract hyperscale investment through submarine cable landing diversity.
Sweden
Nordic carrier networks are disaggregating hardware from software layers through Open RAN procurement, opening radio vendor selection beyond incumbent suppliers. The national post and telecom authority accelerates 5G spectrum allocation for industrial automation corridors. Stockholm's enterprise software procurement favors framework agreements with GDPR-compliant processing commitments.
United Kingdom
London financial services maintain hybrid cloud fragmentation between private controlled environments and hyperscale regions due to data sovereignty interpretations post-Brexit. The Financial Conduct Authority shapes algorithmic trading system transparency requirements alongside EU AI Act convergence pressure. Cambridge and Oxford research corridors attract edge inference hardware development for low-latency AI workloads.
Europe ICT Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent specialization in AI conformity assessment and edge-optimized inference hardware. The vendor base stratifies across three maturity tiers: legacy enterprise software incumbents with deep ERP integration, hyperscale cloud operators with sovereign region deployments, and specialized semiconductor equipment fabricators with captive EUV technology. Dominant competitive moves include strategic partnerships between automotive OEMs and infrastructure operators, plus portfolio diversification into managed security services as NIS2 deadlines crystallize.
Among Netherlands-based equipment specialists, ASML occupies a position exemplifying extreme technology concentration in lithography systems. German enterprise software and services providers SAP and Capgemini sit within the integration-heavy tier, representing archetypes of ERP consolidation and IT consulting scale respectively. Nordic infrastructure vendor Nokia anchors the telecommunications equipment segment through Open RAN disaggregation positioning.
| Leading Market Players |
|---|
| Spotify |
| Adyen |
| ASML |
| Dassault Systèmes |
| Nokia |
| SAP |
| Infineon |
| Capgemini |
| Prosus |
| Others |
Supply Flow & Price Mechanics
DRAM spot price indices cascading from Seoul and Hsinchu foundries compress margin structures across European server and storage procurement tiers, with hyperscale buyers in Frankfurt and Dublin extracting volume concessions that reshape contract structures for mid-tier enterprise customers.
Pricing Analysis
Input-cost pass-through from EUV lithography equipment and advanced node wafers concentrates pricing power with Veldhoven-based equipment specialists and Dresden foundry operators. Subscription-based SaaS pricing stratifies across premium compliance-integrated tiers, standard API-accessible bundles, and economy self-service tiers differentiated by GDPR certification depth and NIS2 audit documentation. Cost compression in public cloud compute is intensifying because ARM-based instance proliferation disrupts x86 socket-based pricing models. Mid-market French industrials exhibit highest price sensitivity due to legacy ERP migration friction, while German automotive OEMs prioritize architectural control over unit cost.
Supply Chain Analysis
EU data localization mandates and NIS2 resilience requirements are reshaping sourcing patterns toward sovereign cloud regions and EU-based managed security service providers. Geographic supply concentration centers on the Netherlands for lithography systems, Germany for power semiconductors and enterprise software, and Taiwan for advanced node fabrication capacity. Raw material dependencies encompass neon gas for laser systems, high-purity silicon wafers, and cobalt-based interconnect materials. Single-source vulnerability runs through EUV equipment exclusivity. Distribution feeds from direct hyperscale contracting for large enterprises and channel partner networks for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's enforcement crystallization compounds procurement cycles across high-risk application categories, with conformity assessment deadlines forcing budget reallocation toward compliance-integrated technology stacks.
For Market Incumbents: Deploy sovereign cloud region expansion as the primary defensive lever. Add capacity in Frankfurt and Paris hyperscale clusters to preempt data residency requirements hardening under GDPR enforcement patterns. Invest in NIS2-certified managed security service capabilities before directive deadlines crystallize competitive differentiation. Counter emerging AI conformity assessment specialists by acquiring accredited testing body capacity in French and German regulatory corridors. For New Entrants and Emerging Players: Begin with AI Act conformity services for healthcare diagnostics manufacturers as the most penetrable white-space target. French notified body capacity constraints create immediate demand for algorithmic transparency documentation and risk management system implementation. Target Paris-Saclay AI research corridor density for initial customer concentration. Pursue partnership-based go-to-market positioning with established medical device quality management consultants to bypass direct enterprise sales cycle friction. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized AI audit and edge inference hardware developers serving regulated European verticals. Five-to-ten year viability favors firms with EU AI Act accreditation pathways and ARM-based server processor design capabilities. Monitor CSRD disclosure deadline acceleration as the critical inflection signal for ESG-integrated enterprise software demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Region Expansion | Frankfurt and Paris hyperscale investments preempt GDPR data localization enforcement tightening. |
| AI Conformity Assessment Accreditation | French and German notified body partnerships capture EU AI Act high-risk application certification volume. |
| ARM-Based Server Processor Deployment | Graviton and Ampere Altra instances compress energy metrics for CSRD sustainability reporting compliance. |
| Open RAN Infrastructure Partnership | Nordic carrier network disaggregation opens procurement to non-incumbent radio vendors beyond Ericsson. |
| NIS2-Certified Managed Security Services | Energy and transport operator resilience mandates expand recurring revenue pools for specialized providers. |
Methodological Framework
Direct dialogue with CTOs at Stuttgart automotive OEMs, IT procurement officers at Paris-Saclay SaaS scale-ups, platform engineers at Frankfurt hyperscale operators, and channel partners serving Dutch mid-market enterprises grounded qualitative findings. Secondary validation drew from SEC filings of listed European technology vendors, hyperscaler capex disclosure reports, ETSI 5G equipment certification databases, and national data protection authority enforcement bulletins. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the European ICT value chain.
Segmented outputs across deployment model, organization size, vertical application, integration complexity, and regional regulatory cluster populated the analytical framework throughout the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology substitution patterns. Model inputs incorporated EU AI Act implementation timelines, CSRD disclosure phase-in schedules, and NIS2 directive enforcement capacity building across member states.
Caveats apply where EU AI Act enforcement consistency, GDPR cross-border data flow rulings, or advanced node fabrication capacity expansion delays could materially shift the outlook. Forecasts embed assumptions about regulatory timeline adherence and hyperscale investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Australia Cloud OSS BSS Market
Digital Solutions
Digital Clothing Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
API Management Market
Digital Solutions
Global Interactive Whiteboard (IWB) Market
Digital Solutions
Virtual Office Market
Digital Solutions
Transport Management System Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Global Online Dating Services Market
Digital Solutions
Germany Digital Twin Market
Digital Solutions
AI Infrastructure Market
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market