
 North America Canned Meat Market | 2026-2036
North America Canned Meat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Canned Meat Market Analytics
Private-label contract manufacturing revenue is reconfiguring margin pools across the North America canned meat landscape as branded processors outsource production to specialized canneries. Hormel Foods Corporation leverages its Austin, Minnesota processing complex to sustain vertical integration across pork slaughtering, canning, and distribution. Tyson Foods anchors its position through backward integration into poultry supply, controlling feed-to-can operations across multiple southern states. Conagra Brands competes via diversified protein sourcing, spanning beef, chicken, and turkey across its canned portfolio.
North America canned meat comprises thermally processed animal proteins preserved in hermetically sealed containers, typically achieving commercial sterility through retort processing at temperatures exceeding 121 degrees Celsius to eliminate Clostridium botulinum spores and enable ambient shelf stability from 24 to 60 months. Its primary commercial purpose centers on delivering protein security for institutional buyers, emergency feeding programs, and consumers in geographies with limited cold-chain infrastructure. Beef and pork categories occupy mature, high-volume positions with established military and institutional contracts, while chicken is gaining fastest among health-conscious household segments seeking leaner protein alternatives. Metal can packaging dominates manufacturing economics and recycling infrastructure, though pouch formats are capturing premium positioning in camping and outdoor recreation channels.
The USDA Food Safety and Inspection Service governs labeling, inspection, and pathogen standards for all canned meat products crossing state lines, while FDA regulations under 21 CFR Part 108 enforce emergency permit controls for low-acid canned foods. State-level cottage food laws and provincial health codes in Canada create additional compliance layers for smaller processors seeking retail distribution. Stakeholders must monitor evolving sodium reduction mandates and front-of-package labeling requirements that threaten reformulation costs across legacy recipes.
Market Dynamics
Private-label contract manufacturing is fragmenting production control across the North America canned meat landscape, as branded processors outsource retort operations to specialized canneries while retaining distribution and marketing functions. This structural shift is redistributing margin pools and reshaping competitive positioning between integrated processors and toll-manufacturing specialists.
Growth Catalysts
- USDA School Nutrition Standards:Updated federal guidelines are expanding institutional eligibility for shelf-stable proteins in K-12 feeding programs across the United States.
- Hurricane-Season Stockpiling:Southeastern United States households sustain above-average penetration through seasonal emergency preparedness purchasing concentrated in coastal counties.
- Pouch Format Innovation:Flexible retort packaging technology is capturing premium positioning in camping and outdoor recreation distribution channels.
Market Restraints
- Feed Cost Volatility:Corn and soybean price swings directly compress margins for integrated poultry and pork processors operating captive feed-to-can supply chains.
- Sodium Reduction Mandates:Front-of-package labeling requirements under FDA 21 CFR Part 101 threaten reformulation costs across legacy cured meat recipes.
- Metal Can Supply Concentration:Three domestic suppliers control the majority of food-grade tinplate and aluminum can manufacturing capacity, creating input bottlenecks.
Strategic Opportunities
- Canadian Provincial Expansion:Underpenetrated rural grocery markets in Manitoba and Saskatchewan present whitespace for shelf-stable protein distribution.
- Emergency Management Procurement:Federal and state-level disaster relief stockpiling programs are expanding multi-year contracts for retort-processed meat formats.
- Lean Chicken Positioning:Health-conscious household segments are displacing red meat purchases with poultry-based canned alternatives in suburban markets.
Industry Challenges
- Retort Operator Shortage:Specialized thermal processing technicians with commercial sterility certification are scarce across Midwestern canning facilities.
- Legacy Equipment Modernization:Continuous rotary retort systems require substantial capital replacement to meet updated USDA Food Safety and Inspection Service pathogen standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Canned Meat Market |
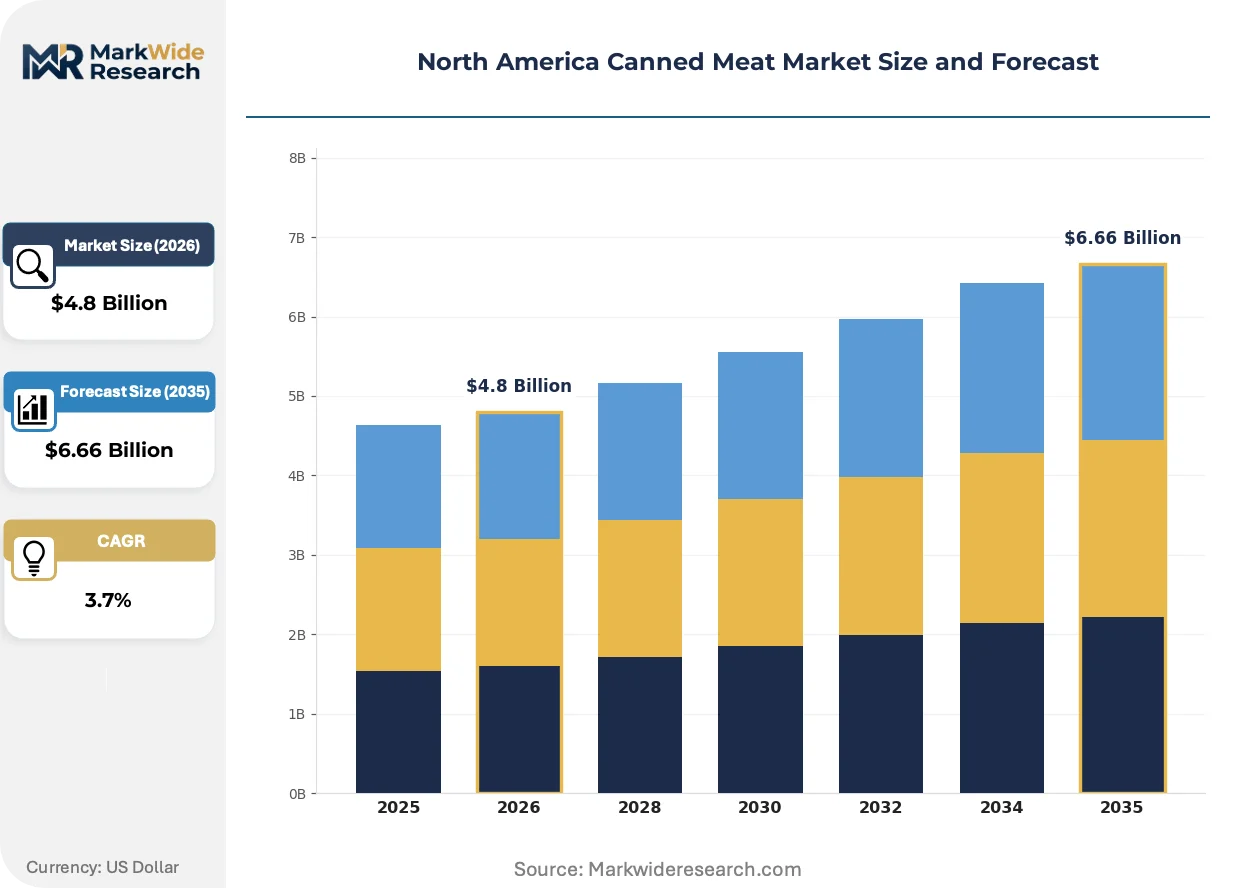
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Chicken, Pork, Turkey Packaging Type: Metal Can, Tetra Pak, Glass Jar, Pouch End User: Households, Food Service, Retail Outlets, Institutions Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers |
| Companies Covered | Hormel Foods Corporation, Tyson Foods, Conagra Brands, JBS Foods, Smithfield Foods, Kraft Heinz Company, Campbell Soup Company, Danish Crown, Maple Leaf Foods, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Canned Meat Market Evolving Landscape
Retort packaging technology and regulatory compliance frameworks are actively reshaping competitive differentiation in North American shelf-stable proteins. Processors are navigating between metal can economics and flexible format premiums while adapting to evolving federal labeling mandates.
Retort pouch laminates combining aluminum oxide barrier layers with polyester films are hybridizing traditional canning economics with lightweight logistics. Backpacking and overlanding retailers are adopting these formats at accelerating rates for backcountry protein resupply. The technology is hybridizing manufacturing asset utilization as canneries retool lines for dual-format output.
FDA enforcement of 21 CFR Part 108 emergency permit controls for low-acid canned foods is intensifying inspection frequency and documentation requirements. Smaller processors face compliance cost barriers that favor scaled operators with dedicated quality systems. Canadian provincial health codes create additional layering, with Health Canada and PMRA coordination requirements slowing cross-border product introductions.
Direct-to-consumer subscription models for emergency preparedness kits are displacing traditional retail stock-up behavior among hurricane-zone households. Specialty outdoor retailers and preparedness e-commerce platforms are capturing share from conventional grocery channels in Florida and Gulf Coast markets. This channel rotation is most visible in Texas and Louisiana, where FEMA coordination with state emergency management agencies drives institutional procurement parallel to household demand.
North America Canned Meat Market Segmentation
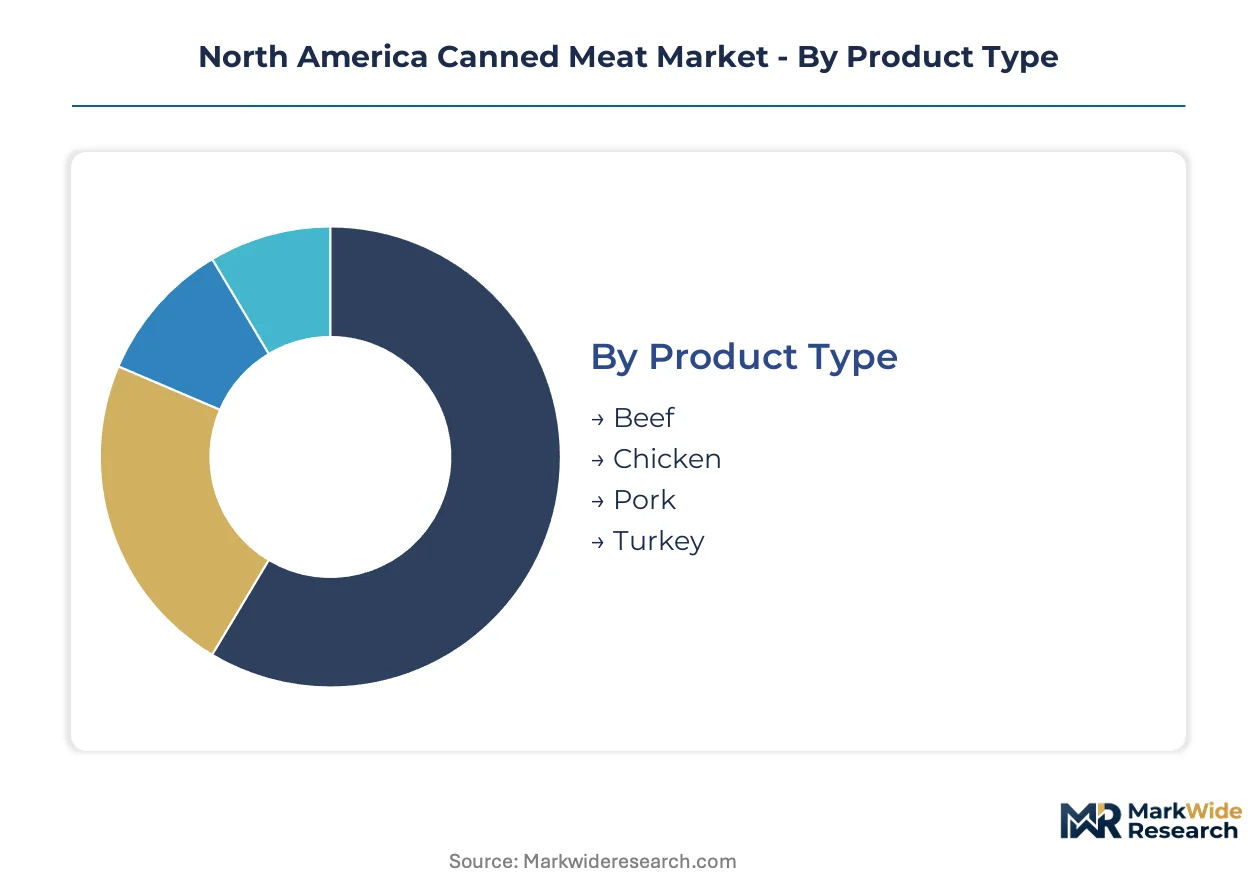
Segmentation in the North America canned meat market reveals how protein sourcing, packaging economics, and channel access shape procurement patterns across military, institutional, and household buyers. Understanding these divides clarifies where retort capacity investments align with demand concentration.
Product Type:
After-sales service intensity varies sharply by protein category, with beef and pork demanding specialized technical support for institutional contract fulfillment while chicken and turkey require leaner handling protocols for health-conscious retail segments.
- Beef:Thermally processed bovine muscle tissue preserved in hermetically sealed containers, typically achieving commercial sterility through retort processing at temperatures exceeding 121 degrees Celsius. Demand concentrates in military procurement channels and Texas-Louisiana hurricane preparedness zones, driven by institutional preference for high-calorie protein density in emergency feeding programs.
- Pork:Shelf-stable swine protein formats ranging from cured hams to ground preparations, occupying mature volume positions with established USDA Food Safety and Inspection Service inspection protocols. Southeastern United States households sustain above-average penetration through seasonal stockpiling behavior concentrated in Florida and Gulf Coast coastal counties.
- Chicken:Lean poultry alternatives capturing suburban health-conscious segments seeking reduced saturated fat content compared to red meat options.
- Turkey:Seasonal protein format concentrated in holiday-oriented procurement cycles and institutional menu rotation programs.
Beef holds the largest share; momentum sits with chicken.
Packaging Type:
Cost tier stratification separates metal can economics from premium flexible formats, with manufacturing asset utilization driving cannery investment decisions across legacy rotary retort systems and newer pouch-capable lines.
- Metal Can:Dominant food-grade tinplate and aluminum formats controlling manufacturing economics and recycling infrastructure across North American processing facilities. Demand anchors in institutional procurement and rural grocery distribution where shelf visibility and damage resistance outweigh logistics weight considerations.
- Pouch:Flexible retort laminates combining aluminum oxide barrier layers with polyester films, hybridizing traditional canning economics with lightweight logistics. Backpacking and overlanding retailers in Colorado and Pacific Northwest markets adopt these formats at accelerating rates for backcountry protein resupply.
- Tetra Pak:Aseptic carton formats limited to specific prepared meat applications with shorter ambient stability requirements.
- Glass Jar:Premium positioning format constrained by weight logistics and breakage risk in emergency preparedness channels.
Metal can holds the largest share; pouch formats are expanding most quickly.
End User:
Application-driven segmentation separates household emergency stockpiling from institutional procurement scale, with USDA school nutrition standards reshaping eligibility criteria for K-12 feeding programs.
- Households:Individual and family-level purchasers concentrated in hurricane-season preparedness cycles and rural cold-chain-limited geographies. Florida and Texas coastal counties drive above-average penetration through FEMA-coordinated emergency management awareness campaigns.
- Institutions:Federal and state-level disaster relief stockpiling programs, military commissaries, and K-12 school feeding programs governed by updated USDA nutrition standards expanding shelf-stable protein eligibility.
- Food Service:Commercial kitchen operators seeking backup protein security for supply chain disruption scenarios.
- Retail Outlets:Grocery and convenience store operators managing inventory depth for seasonal demand spikes.
Institutions hold the largest share; households are gaining share fastest.
Distribution Channel:
Channel concentration reflects geographic access patterns, with supermarket dominance in suburban markets contrasting wholesaler control of institutional procurement and online retail capture of preparedness-kit subscription models.
- Supermarkets:Primary retail channel for household stockpiling behavior, with southeastern United States chains maintaining expanded seasonal inventory depth for hurricane preparedness windows. Kroger and Publix regional networks anchor volume distribution across Florida, Georgia, and Carolinas coastal markets.
- Wholesalers:Institutional procurement channel controlling military and emergency management multi-year contracts, with Sysco and US Foods distribution networks managing retort-processed meat logistics to federal and state stockpile facilities.
- Online Retail:Direct-to-consumer subscription models for emergency preparedness kits displacing traditional retail stock-up behavior among hurricane-zone households.
- Convenience Stores:Limited rural access points for individual can purchases in cold-chain-constrained geographies.
Supermarkets hold the largest share; online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household buyers in hurricane-exposed coastal counties show the lowest price elasticity, accepting premiums for emergency stockpiling reliability, while institutional procurement programs operate under rigid cost-per-serving constraints that compress margins for contract manufacturers.
United States
Southeastern coastal households from Florida through Texas drive seasonal demand spikes through FEMA-coordinated preparedness campaigns. USDA school nutrition standards under 7 CFR Part 210 expand shelf-stable protein eligibility for K-12 feeding programs nationwide. Austin, Minnesota anchors pork processing concentration where Hormel Foods Corporation operates integrated slaughter-to-can facilities.
Canada
Underpenetrated rural grocery markets in Manitoba and Saskatchewan present whitespace for shelf-stable protein distribution beyond current cold-chain limitations. Health Canada and PMRA coordinate cross-border product registration requirements that slow new format introductions from US processors. Toronto and Montreal metropolitan areas concentrate retail channel headquarters controlling Atlantic Canada distribution networks.
Mexico
Northern border states experience spillover demand from Texas preparedness stockpiling behaviors. Mexico's national health regulator enforces NOM-130-SSA1-1995 standards for thermally processed meat products that create compliance barriers for US-format imports. Mexico City metropolitan area anchors institutional procurement for federal disaster relief programs.
North America Canned Meat Market Competitive Landscape
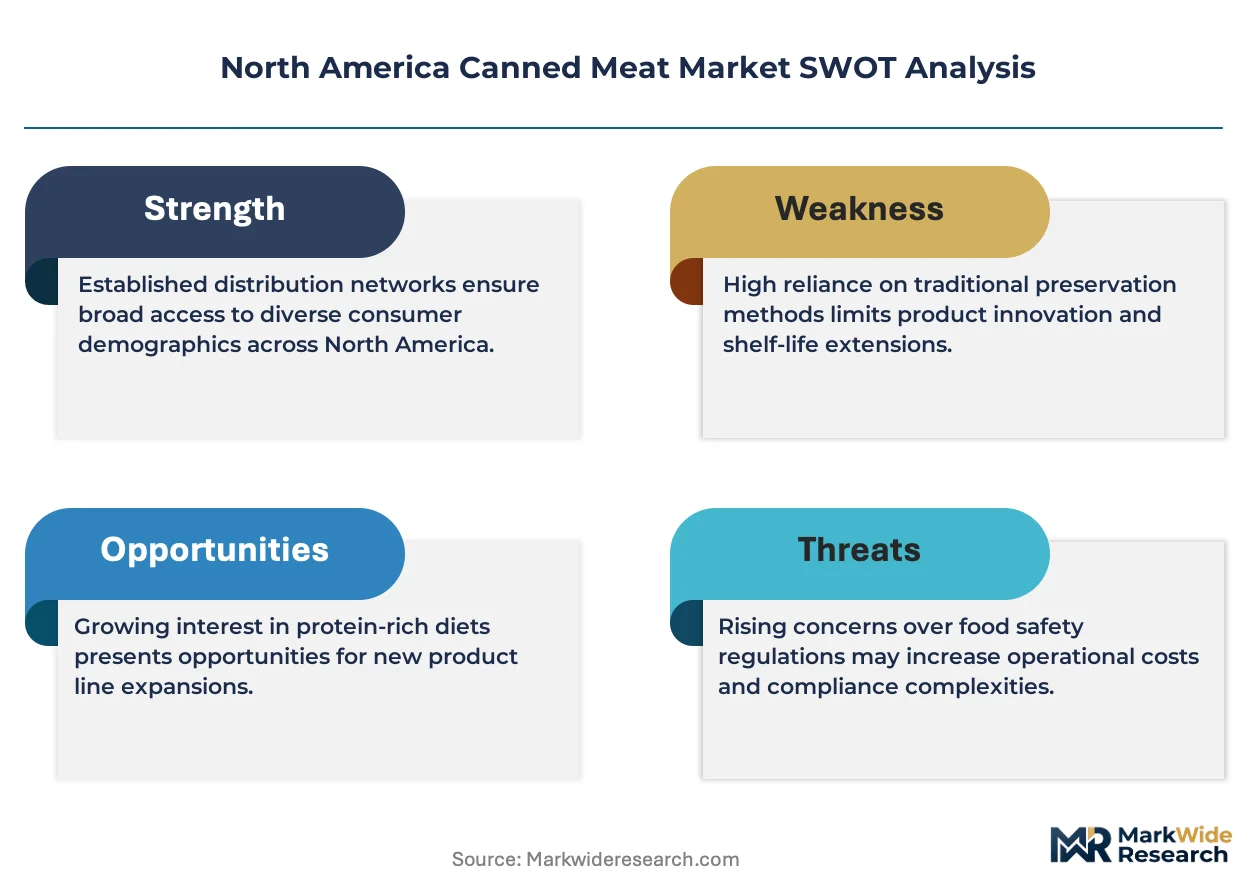
Capability concentration sits with vertically integrated pork and poultry processors commanding captive feed-to-can supply chains; scale advantage sits with diversified protein aggregators sourcing across species to buffer commodity volatility. The market structures around three tiers: integrated slaughter-and-can operators, toll-manufacturing specialists, and branded portfolio managers outsourcing retort production. Dominant competitive moves include backward integration into feed operations and multi-year institutional contract capture.
Among US-based integrated processors, Hormel Foods Corporation and Tyson Foods exemplify the capability-concentrated tier through in-house production of slaughtering and thermal processing operations. Conagra Brands occupies a position within the diversified-aggregator archetype, sourcing beef, chicken, and turkey across its portfolio without captive supply chain ownership.
| Leading Market Players |
|---|
| Hormel Foods Corporation |
| Tyson Foods |
| Conagra Brands |
| JBS Foods |
| Smithfield Foods |
| Kraft Heinz Company |
| Campbell Soup Company |
| Danish Crown |
| Maple Leaf Foods |
| Others |
Value Network & Pricing Analysis
Three domestic metal can suppliers controlling food-grade tinplate and aluminum manufacturing capacity anchor upstream concentration, pushing margin pools toward retort-processing specialists with multi-format line capabilities. This supply bottleneck amplifies pricing power for toll-manufacturing operators while squeezing branded processors locked into legacy can-only production assets.
Pricing Analysis
After-sales contract revenue from institutional emergency stockpile maintenance and military commissary service agreements drives lifetime value for integrated processors. Three-tier pricing structure across premium retort-pouch formats, standard institutional metal-can contracts, and economy private-label retail tiers separates margin capture by buyer archetype. Cost compression in economy retail tiers is intensifying because feed cost volatility in corn and soybean markets transmits directly to processor margins. Institutional buyers operate under rigid cost-per-serving constraints and show highest price sensitivity, while hurricane-zone households in Florida and Texas coastal counties demonstrate lowest elasticity due to emergency reliability premiums.
Supply Chain Analysis
Upstream feedstock operations draw from Iowa and Illinois corn belt dominance for swine and poultry feed, Minnesota pork processing concentration, and southern states poultry integration across Arkansas and Mississippi. Raw material dependencies center on food-grade tinplate from domestic steel mills, aluminum can sheet, and retort pouch laminates combining aluminum oxide barriers with polyester films. Single-source vulnerability in metal can manufacturing creates structural risk for processors without dual-format line capabilities. Distribution runs through Sysco and US Foods wholesaler networks for institutional channels, with Kroger and Publix regional supermarket systems anchoring retail volume in southeastern coastal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated institutional procurement programs as federal and state emergency management agencies consolidate multi-year retort-meat contracts under fewer vendors. This consolidation compresses margin capture for fragmented toll-manufacturing operators while rewarding scaled processors with dedicated quality systems and dual-format production assets.
For Market Incumbents: Entrench position through backward integration into feed operations and captive slaughter-to-can capacity in Minnesota and southern states poultry corridors. Defend against pouch-format entrants by retrofitting Austin, Minnesota and Arkansas processing complexes for dual-format retort lines. Prioritize USDA Food Safety and Inspection Service certification investments to meet intensified 21 CFR Part 108 documentation requirements that smaller competitors cannot absorb.
For New Entrants and Emerging Players: Build out toll-manufacturing specialization in underpenetrated Manitoba and Saskatchewan rural grocery markets where cold-chain limitations create natural demand for shelf-stable proteins. Target Canadian provincial health code compliance as a regulatory moat against US-format competitors facing Health Canada and PMRA coordination delays. Deploy direct-to-consumer subscription models for emergency preparedness kits through specialty outdoor retailers and preparedness e-commerce platforms displacing traditional grocery channels in Gulf Coast markets.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap processors with in-house retort capacity and established military or K-12 institutional contract books. Long-term viability over the next decade hinges on format flexibility and regulatory compliance scale rather than single-species protein concentration. Watch for inflection signals in sodium reduction mandate enforcement under FDA 21 CFR Part 101, which would trigger reformulation cost barriers favoring scaled operators with R&D resources.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Format Retort Line Retrofit | Captures pouch format premiums in Colorado and Pacific Northwest outdoor recreation channels. |
| Backward Integration into Feed Operations | Buffers margin compression from Iowa and Illinois corn price volatility for poultry processors. |
| USDA FSIS Certification Investment | Meets intensified 21 CFR Part 108 documentation requirements blocking smaller competitors. |
| Canadian Provincial Market Entry | Exploits whitespace in Manitoba and Saskatchewan cold-chain-limited rural grocery distribution. |
| Direct-to-Consumer Subscription Launch | Displaces traditional retail stock-up behavior among FEMA-coordinated hurricane-zone households. |
Research Methodology
The analysis maps beef, pork, chicken, and turkey protein categories alongside metal can and retort pouch packaging formats, each validated through primary interviews with USDA Food Safety and Inspection Service compliance officers, military procurement directors, K-12 school nutrition program administrators, and toll-manufacturing plant managers. Secondary validation drew from FDA 21 CFR Part 108 enforcement records, USDA 7 CFR Part 210 school nutrition standard filings, Health Canada and PMRA cross-border registration databases, and customs trade data for tinplate and aluminum can sheet imports. Bottom-up production capacity estimates from Minnesota, Arkansas, and Mississippi processing facilities were triangulated against top-down demand aggregation from institutional contract disclosures and hurricane-zone household penetration surveys.
Assumptions held fixed across the modeling period include current USDA school nutrition standard eligibility criteria for shelf-stable proteins, existing FDA low-acid canned food permit controls, and prevailing Health Canada and PMRA coordination timelines for cross-border product introductions. Variables stress-tested included corn and soybean feed cost volatility bands, metal can supply concentration scenarios, and sodium reduction mandate enforcement intensity. Segmentation dimensions modeled encompassed protein type, packaging format, end-user category, and distribution channel, with CAGRs derived from production capacity expansion schedules and institutional contract award patterns.
Stress conditions across feed commodity price swings, retort operator labor availability, and front-of-package labeling requirement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that regulatory acceleration in sodium reduction mandates or metal can supply disruption could materially revise trajectory. Cross-checking against FEMA emergency stockpile procurement disclosures and state emergency management agency contract awards is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Pork Meat Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Global Canned Meat Market
Meat Products
Raw Chicken Feet Market
Meat Products
Low Fat Beef Market
Meat Products
Organic Eggs Market
Meat Products
Organic Pork Market
Meat Products
Grass-Fed Meat Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Brisket Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Bacon Slicers Market
Meat Products
Organic Halal Meat Market
Meat Products
Meat Emulsions Market
Meat Products
Animal Protein Market
Meat Products
Pork Belly Meat Market