
 Global Rapid Application Development Market | 2026-2036
Global Rapid Application Development Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rapid Application Development Market Foresight
Enterprise buyer concentration is pivoting from fragmented departmental pilots to consolidated enterprise-wide procurement mandates. Microsoft leverages its Azure ecosystem to anchor large-account deployments across hybrid cloud environments. OutSystems competes through specialized high-performance application generation for regulated industries. Mendix sustains technology leadership in model-driven development with deep SAP integration capabilities.
Rapid Application Development encompasses visual, model-driven, and low-code methodologies that enable accelerated software delivery through declarative programming interfaces and pre-built component libraries. These platforms abstract traditional hand-coding into graphical workflows, reducing time-to-deployment from months to weeks for enterprise-grade applications. Cloud-based deployment leads solution type demand as organizations prioritize elastic scalability and reduced infrastructure overhead, while low-code platforms capture expanding margin pools through citizen developer enablement. Process automation within the use case dimension shows the steepest adoption curve as enterprises digitize operational workflows.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that shape platform architecture decisions across European deployments. FDA 21 CFR Part 11 and HIPAA in the United States enforce audit trail and electronic record standards that rapid application development vendors must embed natively. ISO 27001 and SOC 2 certifications have become baseline gating factors for vendor selection in BFSI and public sector procurement. Stakeholders must monitor how emerging sovereign cloud mandates fragment deployment architectures and compliance obligations.
Market Dynamics
Enterprise procurement of rapid application development platforms is consolidating around hybrid cloud architectures as Fortune 500 firms mandate enterprise-wide standardization over fragmented departmental pilots. This structural shift compresses vendor selection cycles while elevating compliance and governance requirements into primary evaluation criteria.
Growth Catalysts
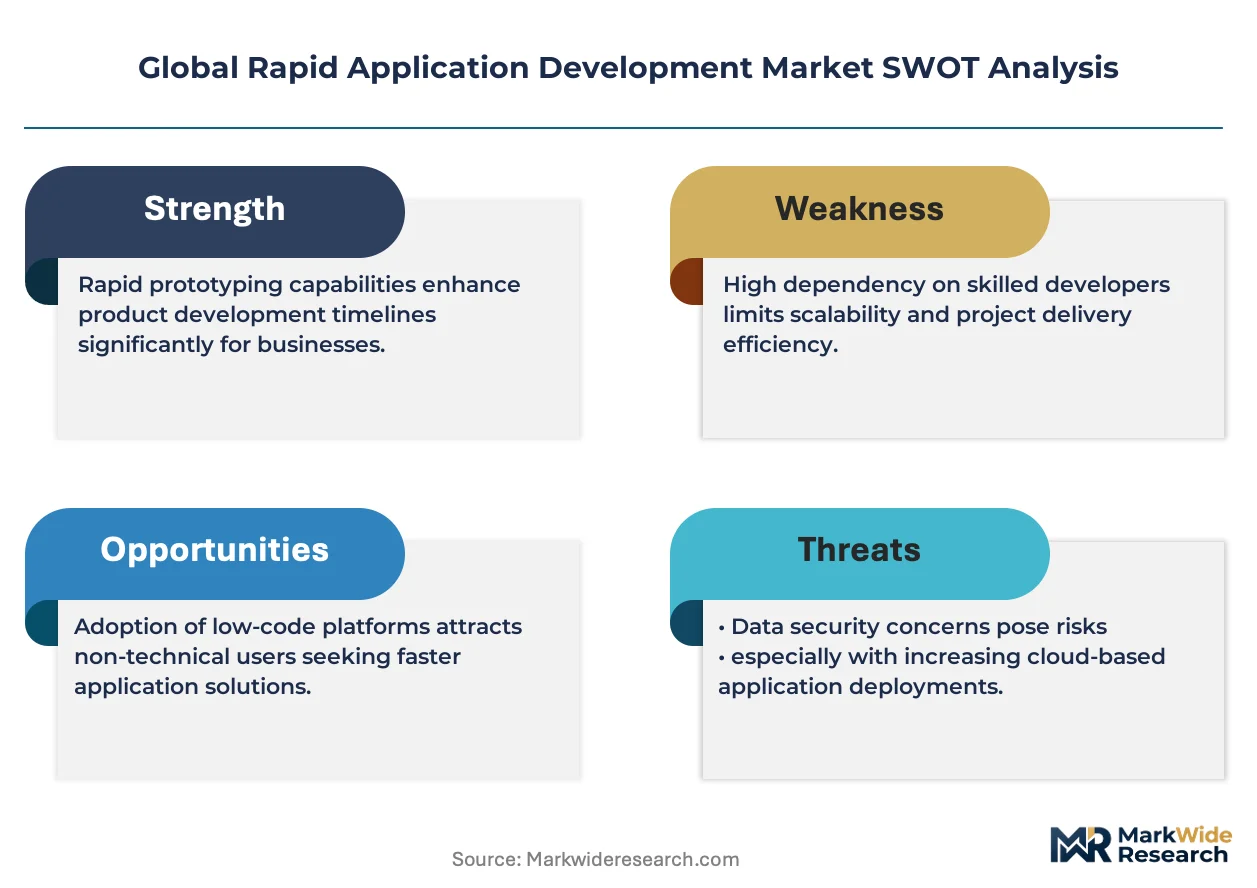
- EU AI Act compliance mandates:European enterprises require auditable development frameworks with built-in algorithmic transparency, accelerating platform replacement cycles for legacy code-based systems.
- Financial services modernization:Banks and insurers deploy low-code solutions to refactor core banking systems without disrupting transaction processing, reducing dependency on scarce COBOL expertise.
- Citizen developer governance models:United States enterprises establish centralized IT governance over business-unit application creation, expanding seat licenses through controlled democratization.
Market Restraints
- Specialized integration talent scarcity:Shortage of architects skilled in SAP S/4HANA and Salesforce API orchestration limits deployment velocity for complex enterprise stacks.
- Sovereign cloud fragmentation:Germany's Gaia-X requirements and France's cloud certification frameworks force vendors to maintain parallel infrastructure instances, elevating operational overhead.
- Proprietary runtime lock-in:Applications built on vendor-specific execution engines resist migration, creating switching costs that deter multi-platform experimentation.
Strategic Opportunities
- India's PLI scheme for software products:Domestic rapid application development vendors gain tax incentives and preferential procurement access in government digitization tenders.
- Process mining convergence:Integration of Celonis-style process intelligence with low-code builders enables automatic workflow generation from ERP transaction logs.
- FDA 21 CFR Part 11 digitization wave:Pharmaceutical manufacturers require validated electronic record systems, opening regulated industry deployments with premium pricing tolerance.
Industry Challenges
- Multi-cloud Kubernetes orchestration complexity:Enterprises struggle to maintain consistent security policies and performance monitoring across Azure, AWS, and Google Cloud deployments.
- ISO 27001 certification timeline compression:Accelerated vendor onboarding demands compress security audit cycles, straining quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rapid Application Development Market |
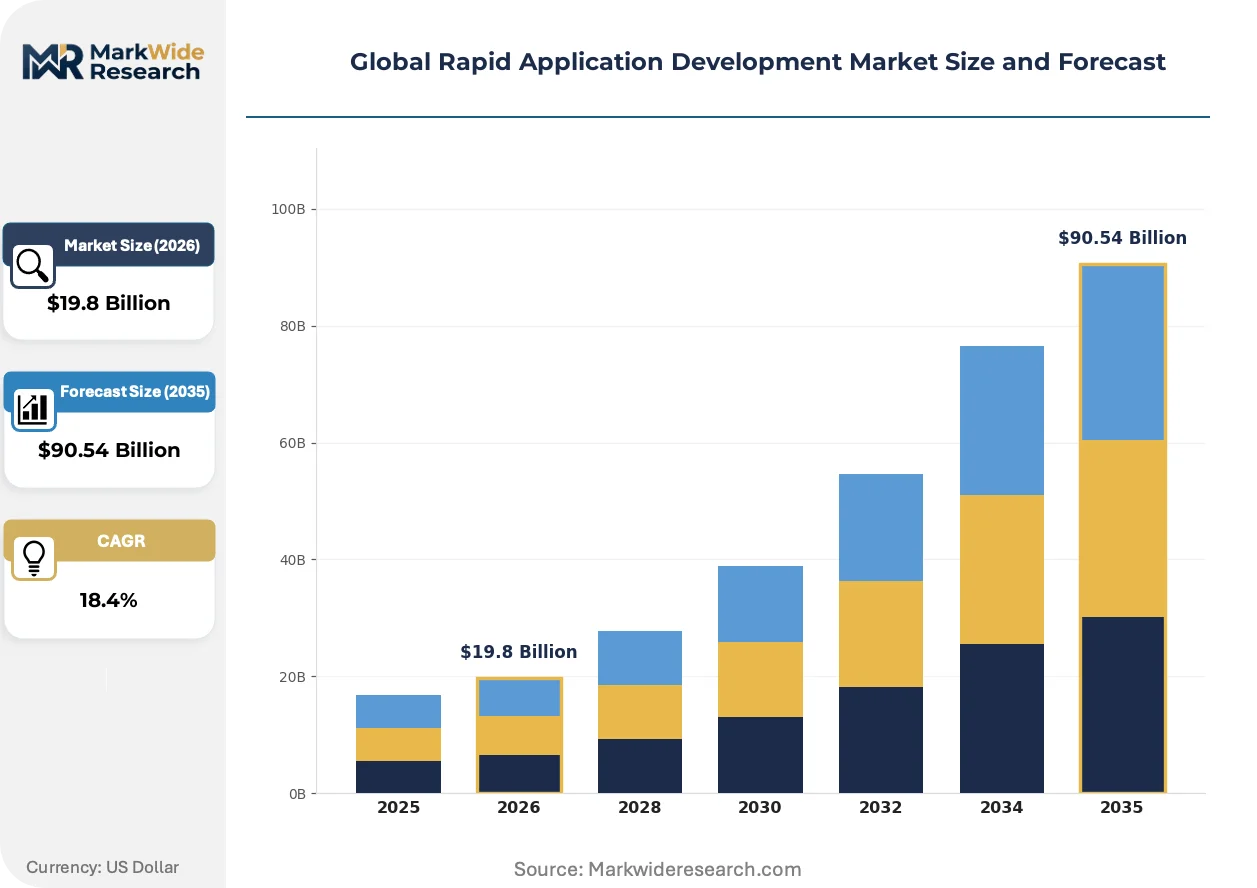
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $90.54 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge, Multi-Cloud Solution Type: Low-Code Platforms, Visual Development, Model-Driven Development, Agile Frameworks, DevOps Integration Use Case: Enterprise Application, Customer Engagement, Process Automation, Data Integration, Workflow Management End User Industry: BFSI, Manufacturing, Telecommunications, Public Sector, Education |
| Companies Covered | Microsoft, Zoho Creator, OutSystems, GeneXus, QuickBase, Mendix, ServiceNow, Betty Blocks, Appian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rapid Application Development Market Shifts & Advancements
Generative AI capabilities are embedding directly into visual development interfaces, transforming how business users specify application logic through natural language rather than drag-and-drop configuration. This convergence is compressing the boundary between professional developers and citizen builders.
Retrieval-augmented generation paired with low-code form builders is rewriting how enterprises construct customer-facing applications. Insurance claims processors and healthcare patient intake teams now generate production-ready interfaces from policy document ingestion, collapsing specification-to-deployment cycles from weeks to days. The structural consequence is displacement of traditional business analyst roles in requirements gathering.
REACH chemical substance restrictions and the EU Green Deal sustainability disclosure requirements are mandating carbon footprint tracking within software procurement decisions. European enterprises now embed emissions reporting into vendor evaluation scorecards, favoring platforms with renewable energy-powered data centers and efficient runtime architectures. German automotive suppliers and French luxury goods houses lead this compliance-driven selection behavior.
Subscription-to-outcome contracting is reshaping how enterprises procure development capacity. Rather than per-seat licensing, United States healthcare systems and United Kingdom public sector bodies negotiate fixed-price deliverables tied to operational KPI improvements. This transfers delivery risk to platform vendors while compressing sales cycle complexity for buyers with constrained capital budgets.
Global Rapid Application Development Market Segmentation
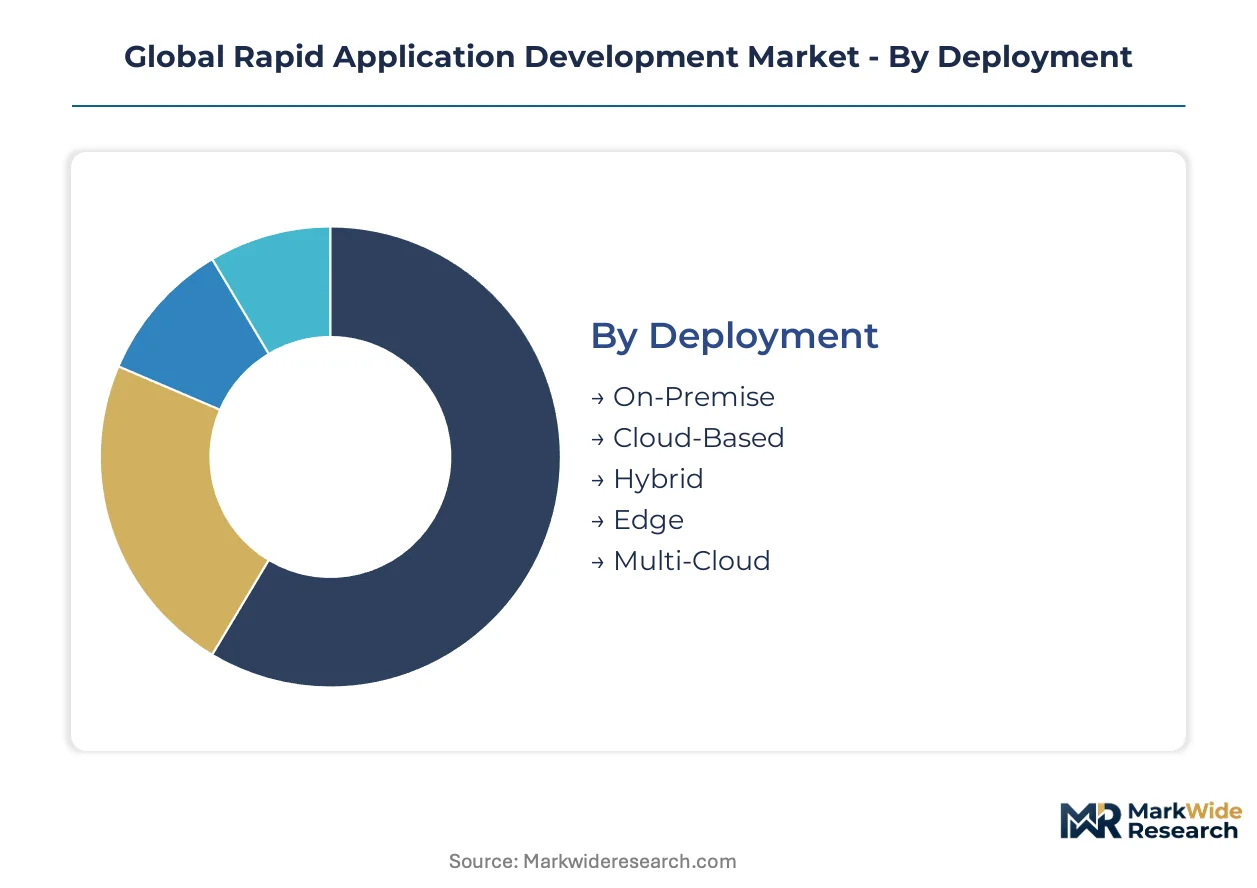
Segmentation in rapid application development reveals how procurement priorities diverge across infrastructure maturity, technical governance models, and industry-specific compliance burdens. Understanding these divides enables vendors to align platform architecture with buyer readiness and regulatory exposure.
Deployment:
Buyer risk tolerance around data sovereignty and latency requirements dictates deployment architecture selection.
- Cloud-Based:Elastic scalability through hyperscaler infrastructure dominates procurement among mid-market enterprises prioritizing reduced capital expenditure. United States healthcare systems and United Kingdom public sector bodies favor consumption-based pricing with automatic scaling during enrollment periods.
- Hybrid:Split workload architectures allow sensitive transaction processing on-premises while customer-facing layers deploy to public cloud. German automotive suppliers and French banking consortia mandate this configuration to satisfy GDPR data residency while maintaining digital channel agility.
- On-Premise:Air-gapped installations persist in defense contractors and classified government facilities requiring physical network isolation.
- Edge:Distributed runtime nodes process manufacturing sensor data and retail point-of-sale logic with sub-50 millisecond response requirements.
- Multi-Cloud:Abstraction layers spanning Azure, AWS, and Google Cloud mitigate vendor concentration risk for Fortune 500 procurement mandates.
Volume sits with Cloud-Based; growth tilts toward Hybrid.
Solution Type:
Technical sophistication of the buying organization's existing developer workforce shapes platform category preference.
- Low-Code Platforms:Visual drag-and-drop interfaces with pre-built connectors abstract database and API complexity. BFSI compliance teams in the United States deploy these for audit-ready workflow automation without traditional software engineering headcount.
- Model-Driven Development:Executable UML and domain-specific language generation enable complex enterprise architecture alignment. SAP-centric industrial conglomerates in Germany leverage Mendix-style visual modeling to synchronize application logic with core ERP data structures.
- Visual Development:Canvas-based interface builders accelerate mobile and web frontend delivery for marketing and customer service departments.
- Agile Frameworks:Scrum and Kanban tooling integration supports iterative delivery methodologies in technology-native organizations.
- DevOps Integration:CI/CD pipeline orchestration and automated testing hooks appeal to mature engineering organizations seeking deployment velocity.
Seat concentration favors Low-Code Platforms; capability premiums concentrate in Model-Driven Development.
Use Case:
Operational pain intensity and quantifiable ROI visibility determine use case prioritization in enterprise procurement cycles.
- Process Automation:Digitization of paper-based workflows and legacy system integration delivers measurable headcount reduction. Insurance claims processors in the United States and pharmaceutical quality assurance teams in Switzerland deploy these solutions to eliminate manual data re-entry.
- Customer Engagement:Self-service portals and conversational interfaces reduce call center dependency. Retail banking divisions across Spain and Italy prioritize mobile-first account servicing applications.
- Enterprise Application:Core system modernization and legacy replacement projects absorb the largest absolute budgets.
- Data Integration:ETL pipeline construction and master data harmonization connect fragmented ERP instances.
- Workflow Management:Approval routing and exception handling standardization improve operational visibility.
Procurement volume clusters in Enterprise Application; Process Automation exhibits the steepest expansion trajectory.
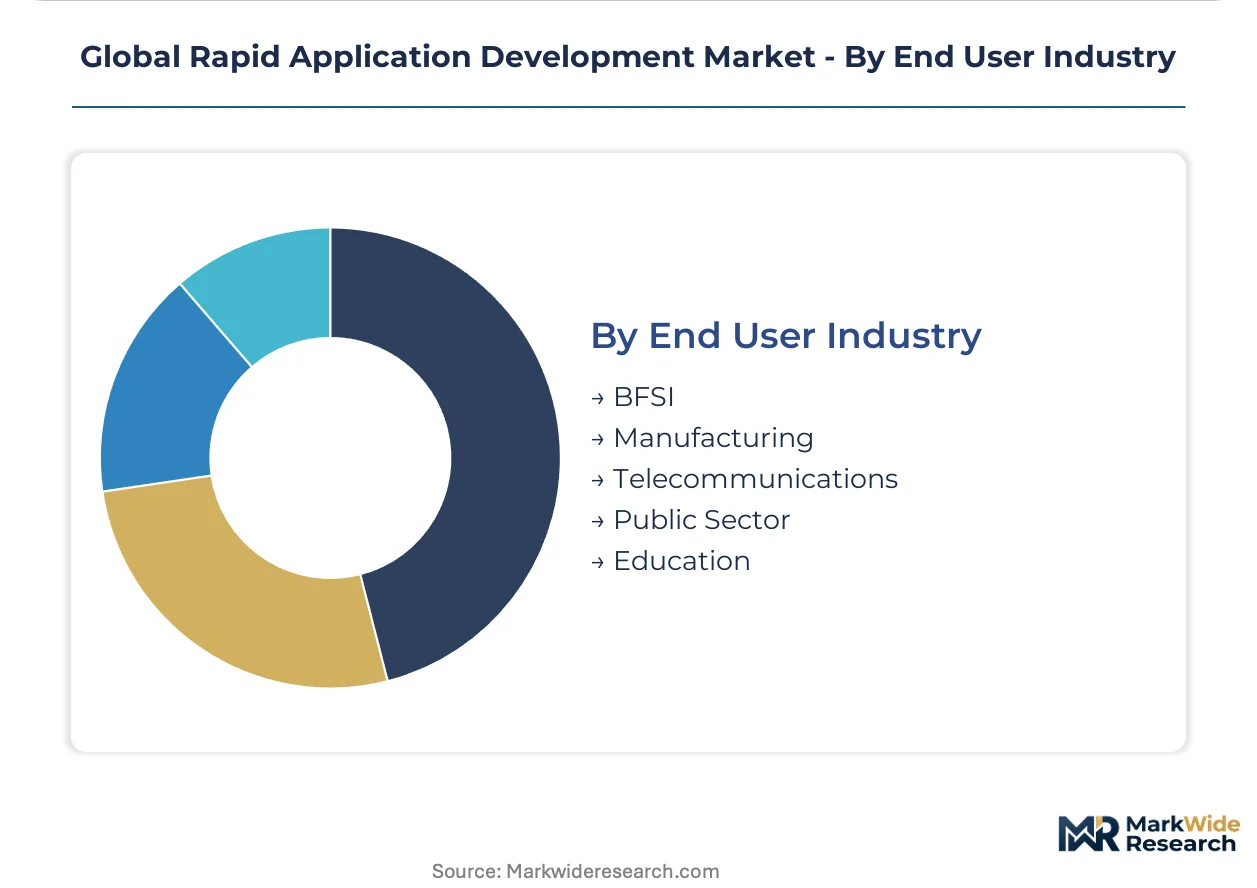
End User Industry:
Regulatory burden intensity and legacy technical debt levels create divergent platform requirements across verticals.
- BFSI:Audit trail mandates from SEC, FINRA, and ECB operational risk frameworks demand immutable logging and granular access controls. Core banking modernization projects in the United States and post-Brexit regulatory reporting adjustments in the United Kingdom drive sustained investment.
- Public Sector:Procurement transparency requirements and citizen service digitization targets accelerate platform adoption. India's PLI scheme for software products creates preferential access for domestic vendors in government tenders.
- Manufacturing:Shop-floor system integration and supply chain visibility projects connect MES, WMS, and ERP layers.
- Telecommunications:Network operations automation and customer provisioning systems reduce manual intervention.
- Education:Student information systems and learning management platform customization serve institutional digitization.
Revenue concentration remains in BFSI; Public Sector procurement velocity is accelerating fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscaler concentration anchors North American platform development, while European regulatory complexity and Asia-Pacific government digitization programs shape divergent deployment patterns across major economies.
United States
Fortune 500 enterprises in New York and Chicago drive enterprise-wide procurement mandates for citizen developer governance models. SEC and HIPAA audit trail requirements elevate compliance into primary vendor selection criteria. Microsoft's Azure ecosystem anchors large-account deployments across hybrid cloud environments in Seattle and Redmond.
Germany
Automotive suppliers in Stuttgart and Munich mandate hybrid architectures to satisfy GDPR data residency while maintaining digital channel agility. Gaia-X requirements force vendors to maintain parallel infrastructure instances, elevating operational overhead. Mendix-style visual modeling dominates SAP-centric industrial conglomerates in the Rhine-Ruhr region.
United Kingdom
Post-Brexit regulatory reporting adjustments in London's financial district drive sustained investment in audit-ready workflow automation. Subscription-to-outcome contracting reshapes procurement in National Health Service digitization tenders. Edinburgh and Manchester emerge as secondary hubs for public sector platform adoption.
India
Bengaluru and Hyderabad host domestic vendors gaining tax incentives under the PLI scheme for software products. Government digitization tenders create preferential procurement access for local rapid application development platforms. Mumbai's BFSI sector deploys low-code solutions for core banking modernization without disrupting transaction processing.
Japan
Tokyo-based manufacturing conglomerates prioritize model-driven development for complex enterprise architecture alignment. METI industrial digitization programs accelerate shop-floor system integration projects in Osaka and Nagoya. Domestic vendors compete through deep integration with legacy ERP data structures.
Global Rapid Application Development Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized high-performance niches and regulated industry verticals. Microsoft leverages its Azure ecosystem to anchor large-account deployments across hybrid cloud environments. OutSystems competes through specialized high-performance application generation. Mendix sustains technology leadership in model-driven development with deep SAP integration capabilities. Strategic consolidation centers on M&A activity targeting complementary workflow automation assets and geographic expansion into sovereign cloud jurisdictions.
Among hyperscaler-anchored platforms, Microsoft and ServiceNow exemplify ecosystem-driven competitive positioning through cloud infrastructure integration. OutSystems and Mendix occupy the specialized tier, representing European-origin vendors with regulated industry penetration. Zoho Creator anchors the mid-market accessibility vector from its Indian operational base. These three archetypes—ecosystem-anchored, specialized-regulated, and mid-market accessible—capture divergent procurement priorities across enterprise maturity tiers.
| Leading Market Players |
|---|
| Microsoft |
| Zoho Creator |
| OutSystems |
| GeneXus |
| QuickBase |
| Mendix |
| ServiceNow |
| Betty Blocks |
| Appian |
| Others |
Supply & Pricing Matrix
Fortune 500 enterprise procurement mandates concentrate buying power among hybrid cloud architects, compressing vendor selection cycles and elevating outcome-based contracting as the dominant pricing model across North American deployments.
Pricing Analysis
Volume concentrates in consumption-based SaaS tiers while margin pools accrue to specialized high-performance application generation for regulated industries. Three-tier pricing structure across premium, standard, and economy levels segments by compliance certification intensity, with ISO 27001 and SOC 2 tiers commanding substantial premiums. Pricing pressure stems from hyperscaler ecosystem bundling as Microsoft and ServiceNow absorb standalone platform margins into infrastructure contracts. Mid-market enterprises exhibit highest price sensitivity, while pharmaceutical manufacturers under FDA 21 CFR Part 11 mandates demonstrate lowest elasticity.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand while channel partners serve mid-market accessibility requirements. Platform development concentrates in the United States, Germany, and India, with Bengaluru and Hyderabad hosting domestic vendors gaining preferential procurement access under India's PLI scheme. Runtime architecture draws from hyperscaler infrastructure in Azure, AWS, and Google Cloud, while specialized integration talent for SAP S/4HANA and Salesforce API orchestration remains constrained. Single-source vulnerability in proprietary execution engines creates switching costs that deter multi-platform experimentation. Distribution runs through cloud marketplaces and direct enterprise sales organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race as players pursue captive control over citizen developer governance tooling to lock in seat expansion and reduce churn.
For Market Incumbents: Hedge against hyperscaler bundling by deepening SAP and Salesforce native integration capabilities that resist displacement. Acquire specialized process mining assets to enable automatic workflow generation from ERP transaction logs. Fortify ISO 27001 and SOC 2 certification moats as baseline gating factors for BFSI procurement. For New Entrants and Emerging Players: EU AI Act compliance mandates in Europe open a window for auditable development frameworks with built-in algorithmic transparency. Target German automotive suppliers and French banking consortia requiring hybrid architectures for GDPR data residency. Pursue Gaia-X certification as a differentiated entry credential against US-origin hyperscaler platforms. For Investors and Strategic Acquirers: The window for entry favors specialized-regulated vendors with deep vertical integration in pharmaceutical and financial services workflows. Monitor FDA 21 CFR Part 11 digitization waves as inflection indicators for premium pricing tolerance in validated electronic record systems.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep SAP S/4HANA native connectors capture Rhine-Ruhr industrial conglomerate procurement. |
| Regulatory Certification Investment | Gaia-X and EU AI Act compliance opens German and French sovereign cloud tenders. |
| Acquisition of Specialist Firm | Process mining assets enable automatic workflow generation from Celonis-style intelligence. |
| Geographic Expansion | India PLI scheme access secures preferential government digitization procurement positioning. |
| Strategic Partnership | Hyperscaler marketplace listings compress customer acquisition costs for mid-market segments. |
Research Methodology
Independent corroboration across platform engineering directors, IT procurement officers at Fortune 500 enterprises, channel partners, and integration specialists underwrites the qualitative findings. Secondary validation draws from SEC filings of publicly traded vendors, hyperscaler capex disclosures, and EU regulatory submission databases. Bottom-up deployment estimates triangulate against top-down market sizing from cloud infrastructure consumption metrics.
Rate-of-change decomposition separates baseline subscription growth from expansion revenue and new logo acquisition across the analysis window. Segmentation dimensions modeled include deployment architecture, solution type technical sophistication, use case operational pain intensity, and end-user industry regulatory burden. CAGRs derive from elasticity-adjusted seat expansion curves and outcome-based contract value realization patterns. Generative AI capability embedding timelines and citizen developer governance model maturity serve as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for retrieval-augmented generation paired with low-code form builders would alter the outlook. Forecasts reflect assumptions about hybrid cloud procurement mandate persistence and sovereign cloud fragmentation trajectory. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
School Timetable Software Market
Software & Services
Global Embedded Database Management Systems Market
Software & Services
Relational Database Management System Market
Software & Services
Attendance Tracking Software Market
Software & Services
Asia-Pacific ERP Software Market
Software & Services
US Software Consulting Market
Software & Services
Family Office Software Solutions Market
Software & Services
Global Address Verification Software Market
Software & Services
Content Distribution Software Market
Software & Services
HCS Software and Services Market
Software & Services
Mobile Application Development Market
Software & Services
Taxi Booking Software Market
Software & Services
Software Testing Tools Market
Software & Services
SMS Marketing Software Market
Software & Services
Life Sciences Software Market