
 Taxi Booking Software Market | 2026-2036
Taxi Booking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Taxi Booking Software Market Outlook
GDPR data-localization enforcement is shifting compliance burdens onto smaller platform vendors entering European markets. iCabbi leverages its dispatch-specialization heritage to sustain operator loyalty across Ireland and the United Kingdom. Yelowsoft anchors its position through white-label SDK architectures that compete with Autocab's vertically integrated driver-terminal ecosystem.
Taxi booking software comprises real-time dispatch algorithms, GPS-enabled driver-rider matching engines, digital payment gateways, and cloud-native fleet management dashboards designed to automate ground-transportation allocation. On-demand apps dominate transaction volume by embedding surge-pricing logic directly into consumer interfaces, while backend systems capture margin pools through subscription-based SaaS models sold to multi-city fleet operators. Cloud-based deployment leads new installations for taxi operators seeking elastic compute during peak-hour demand spikes.
FCC guidelines on emergency-location accuracy shape US mobile-app certification requirements, while EMA data-governance protocols indirectly pressure European platforms to harden passenger-health record handling. India's TRAI net-neutrality rulings and BIS cloud-security standards together constrain how payment processing modules route through domestic data centers. Stakeholders must weigh regulatory fragmentation against the cost of maintaining jurisdiction-specific compliance stacks.
Market Dynamics
Municipal open-data mandates are forcing API interoperability upgrades across fleet management platforms, accelerating the displacement of legacy radio dispatch networks by cloud-native systems in dense urban corridors.
Growth Catalysts
- FCC Emergency Location Accuracy:US mobile-app certification requirements are compelling platform vendors to embed GPS-enhanced driver-rider matching engines, expanding real-time dispatch capabilities.
- India TRAI Net-Neutrality Rulings:Domestic data-center routing requirements for payment processing modules are strengthening local cloud-security compliance under BIS standards, accelerating indigenous platform development.
- Cloud Elasticity:Taxi operators are adopting cloud-based deployment to handle peak-hour demand spikes without maintaining idle on-premise infrastructure.
Market Restraints
- GDPR Data-Localization:European enforcement is shifting compliance burdens onto smaller platform vendors, raising entry costs for Ireland and United Kingdom market penetration.
- Legacy Radio Network Sunk Costs:Fleet operators in North American secondary cities face high replacement costs for depreciated dispatch hardware.
- Payment Gateway Fragmentation:Jurisdiction-specific routing requirements are fragmenting backend margin pools across domestic data-center mandates.
Strategic Opportunities
- White-Label SDK Architectures:Modular platform licensing is enabling mid-size fleet operators to deploy branded consumer interfaces without captive development teams.
- EMA Data-Governance Protocols:Hardened passenger-health record handling requirements are creating differentiation openings for compliance-specialized vendors.
- Subscription SaaS Models:Multi-city fleet operators are shifting from perpetual licenses to recurring revenue structures, expanding addressable spend per customer.
Industry Challenges
- API Interoperability Talent Scarcity:Municipal mandate compliance requires specialized integration engineers familiar with legacy dispatch protocols.
- Certification Timeline Compression:FCC mobile-app certification cycles are compressing product release schedules for cross-platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taxi Booking Software Market |
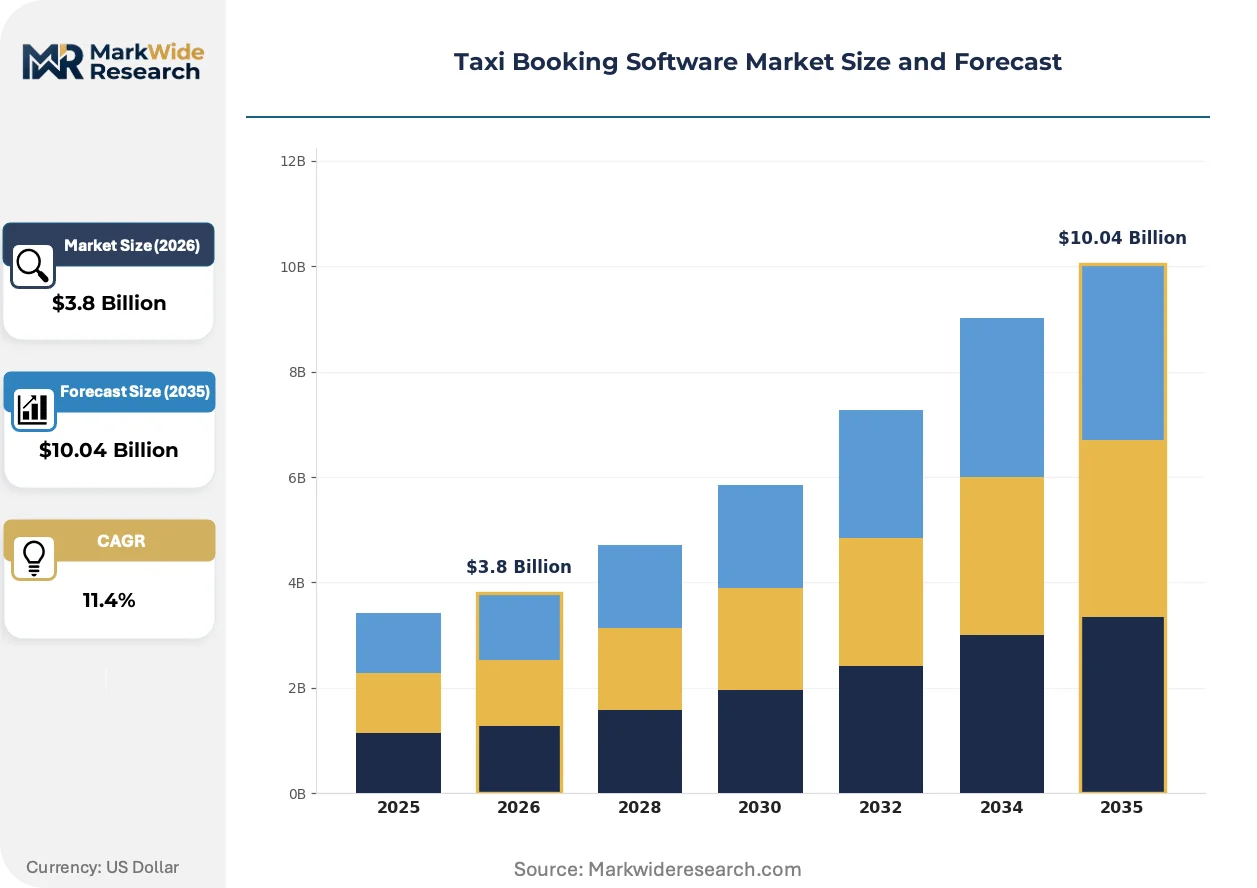
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Demand Apps, Web-Based Solutions, Mobile Apps, Backend Systems Service Type: Dispatch Services, Payment Processing, Customer Support, Analytics Services End User: Taxi Operators, Independent Drivers, Fleet Managers, Ride-Sharing Companies Deployment Model: Cloud-Based, On-Premise, Hybrid, Open Source |
| Companies Covered | Yelowsoft, iCabbi, Autocab, TaxiCaller, Cabsoluit, AllRide, Cab Treasure, Onde, Zoyride, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taxi Booking Software Market Strategic Shifts
Dispatch automation is converging with embedded finance and regulatory compliance tooling, reshaping how fleet operators select platform vendors and structure technology procurement.
AI-powered surge-pricing algorithms are automating real-time fare adjustment based on demand-density mapping and historical trip-pattern analysis. Fleet operators in Chicago and Los Angeles are deploying these engines to capture margin during event-driven demand spikes. The technology is automating price-discovery processes that previously required manual dispatcher intervention.
EMA data-governance protocols are mandating hardened passenger-data handling across European taxi platforms. Vendors serving Ireland and the United Kingdom must now implement encryption-at-rest and access-audit trails for health-related trip records. Backend system providers are responding by embedding compliance-as-a-service modules into standard SaaS offerings.
Fleet procurement teams are consolidating vendor relationships around vertically integrated platform stacks that combine dispatch, payment, and driver-management functions. Single-vendor contracts are displacing best-of-breed procurement models in urban corridors with 500-plus vehicle fleets. This consolidation is most visible in New York City and London, where procurement cycles have compressed from 18 months to 9 months.
Taxi Booking Software Market Segmentation
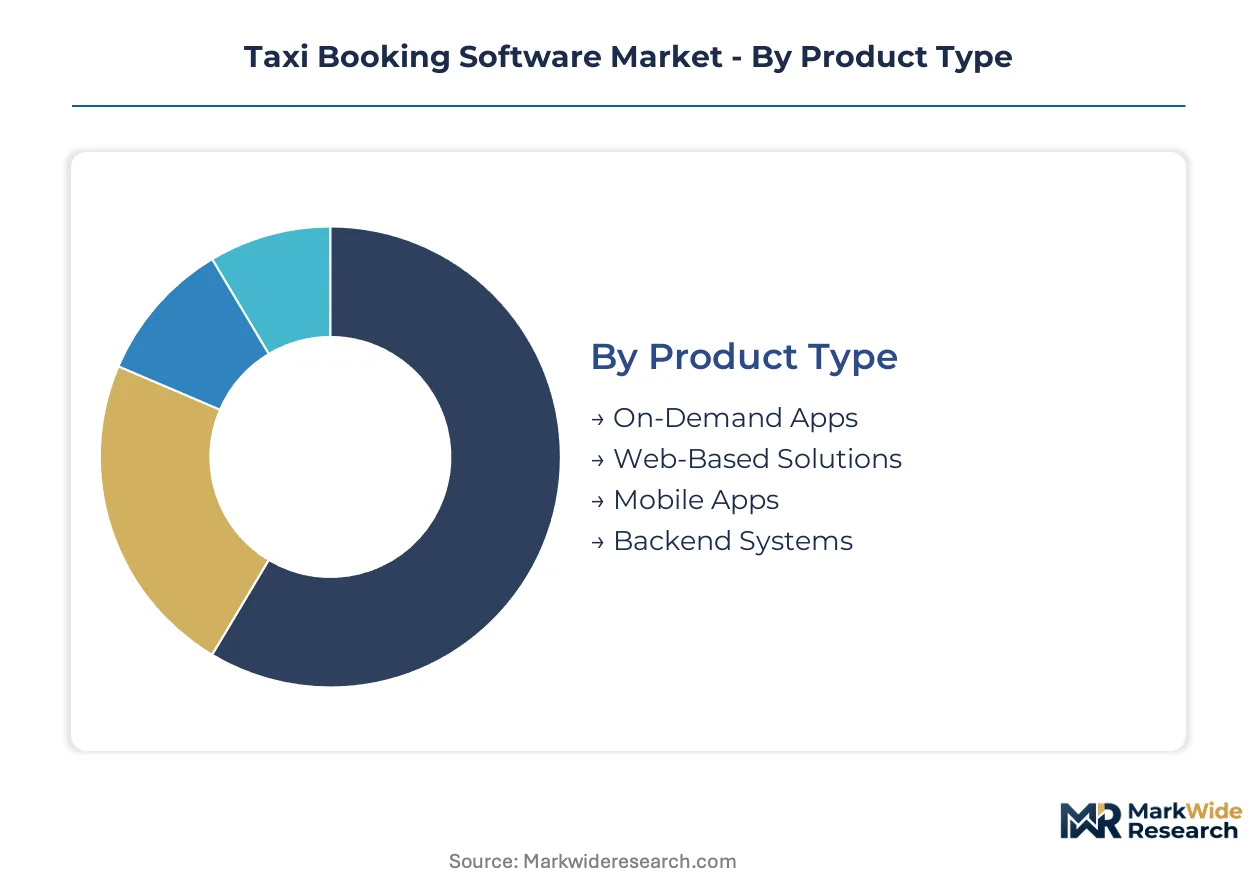
Fleet procurement teams segment taxi booking software by certification burden and integration complexity. Municipal mandates in Chicago, London, and Mumbai force operators to match deployment models against jurisdiction-specific compliance stacks.
Product Type:
FCC mobile-app certification requirements in the United States and EMA data-governance protocols in Europe impose divergent testing burdens across product architectures.
- On-Demand Apps:Consumer-facing interfaces embed surge-pricing logic and GPS-enhanced matching engines. Chicago and Los Angeles operators deploy these for event-driven demand spikes, though FCC emergency-location accuracy rules extend certification timelines.
- Backend Systems:Cloud-native dispatch algorithms and fleet management dashboards automate ground-transportation allocation. Fleet managers in London favor these for elastic compute during peak hours, with GDPR localization adding compliance modules.
- Web-Based Solutions:Browser-accessible booking portals serving secondary markets with lighter infrastructure requirements.
- Mobile Apps:Native iOS and Android applications requiring platform-specific store approvals and location-permission handling.
Backend Systems sit at the top of the volume ranking, with On-Demand Apps climbing the fastest.
Service Type:
Margin capture varies sharply by service layer, with payment processing facing the most fragmented regulatory routing requirements.
- Payment Processing:Digital gateways route transactions through jurisdiction-mandated data centers. India's TRAI net-neutrality rulings and BIS cloud-security standards force domestic routing, constraining cross-border platform architectures.
- Dispatch Services:Real-time driver-rider matching engines replace legacy radio networks. Fleet operators in New York City and London consolidate around these as municipal open-data mandates force API interoperability upgrades.
- Customer Support:Multi-channel assistance layers including in-app chat and voice support for dispute resolution.
- Analytics Services:Trip-pattern analysis and demand-density mapping for fleet optimization.
Dispatch Services dominate current procurement cycles, while Payment Processing expands most quickly as operators retrofit compliance-as-a-service modules.
End User:
Procurement authority concentrates differently across user types, with fleet scale determining SaaS subscription tiers versus perpetual license preferences.
- Fleet Managers:Multi-city operators with 500-plus vehicle fleets drive consolidation toward vertically integrated platform stacks. Procurement cycles in New York City and London compressed from 18 months to 9 months as single-vendor contracts displace best-of-breed models.
- Taxi Operators:Urban corridor incumbents replace depreciated radio hardware with cloud-native dispatch. Sunk costs in North American secondary cities slow replacement timelines despite municipal mandate pressure.
- Independent Drivers:Solo operators accessing platform marketplaces through revenue-share arrangements.
- Ride-Sharing Companies:Technology-first entrants embedding booking software within broader mobility ecosystems.
Fleet Managers command the largest addressable spend per customer, with Taxi Operators gaining share fastest as municipal mandates accelerate replacement cycles.
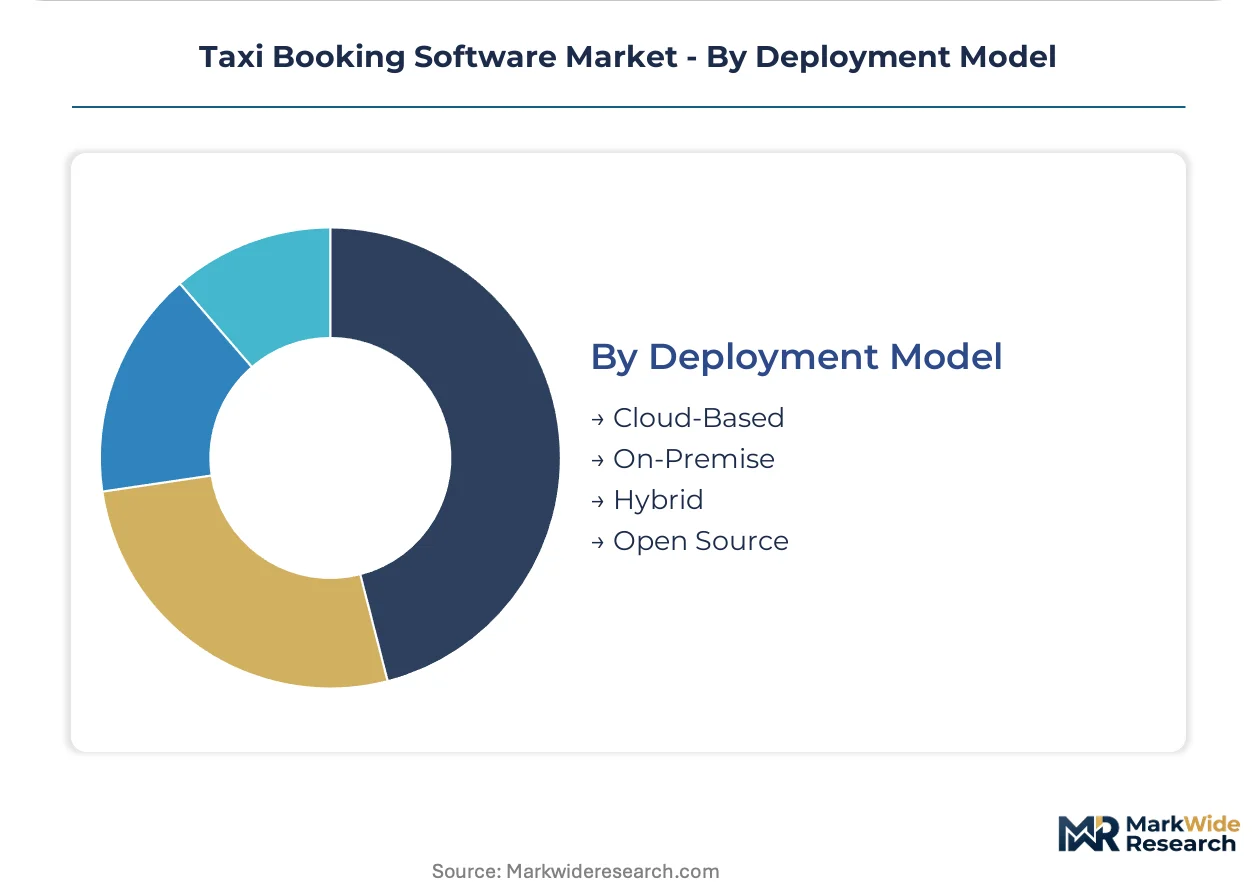
Deployment Model:
Elasticity requirements and data-sovereignty rules create divergent total-cost-of-ownership profiles across deployment architectures.
- Cloud-Based:Elastic compute deployment handles peak-hour demand spikes without idle on-premise infrastructure. European operators face GDPR localization requirements that shift compliance burdens onto vendor selection.
- Hybrid:Split architectures keeping sensitive dispatch data on-premise while consumer interfaces run cloud-native. Indian operators favor these under BIS standards constraining payment module routing.
- On-Premise:Captive infrastructure maintained by operators with legacy IT investments and strict data-control requirements.
- Open Source:Community-developed platforms modified by operators with captive development teams.
Cloud-Based deployment leads new installations, with Hybrid architectures steepest expansion trajectory as data-sovereignty rules harden across India and Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The taxi booking software industry traces its commercial roots to the United States, where early computer-aided dispatch systems emerged in the 1980s to replace radio-based fleet coordination in New York City and Chicago.
United States
FCC emergency-location accuracy mandates are compelling platform vendors to embed GPS-enhanced matching engines into mobile interfaces. Fleet operators in Chicago and Los Angeles deploy AI-powered surge-pricing algorithms to capture margin during event-driven demand spikes. Municipal open-data requirements in these cities are accelerating API interoperability upgrades that displace legacy radio networks.
United Kingdom
GDPR data-localization enforcement is shifting compliance burdens onto smaller platform vendors seeking market entry. EMA data-governance protocols mandate hardened passenger-health record handling with encryption-at-rest requirements. London's procurement cycles have compressed from 18 months to 9 months as 500-plus vehicle fleets consolidate around vertically integrated platform stacks.
Germany
CE marking requirements for connected vehicle systems shape mobile-app certification pathways for dispatch platforms. Fleet managers in Berlin and Munich favor cloud-native backend systems that offer elastic compute during peak-hour demand without idle on-premise infrastructure. The country's federal data protection authority enforces strict passenger-data handling standards that favor established compliance-specialized vendors.
India
TRAI net-neutrality rulings and BIS cloud-security standards constrain payment processing modules to route through domestic data centers. Fleet operators in Mumbai and Bangalore are adopting hybrid deployment architectures that keep sensitive dispatch data on-premise while consumer interfaces run cloud-native. Indigenous platform development is accelerating as regulatory mandates strengthen local compliance requirements.
Japan
METI guidelines on mobility-as-a-service integration are shaping how taxi platforms interconnect with broader transportation ecosystems. Fleet operators in Tokyo and Osaka prioritize real-time dispatch algorithms that coordinate with public transit APIs during high-congestion periods. JIS standards for information security management systems govern how passenger data flows through cloud-based booking infrastructures.
Taxi Booking Software Market Competitive Environment
The competitive structure tilts toward dispatch-specialization heritage rather than horizontal platform breadth. Vendor concentration remains moderate, with regional specialists commanding operator loyalty through deep protocol familiarity. Two strategic archetypes dominate: vertically integrated stack providers and modular white-label SDK architects. Competitive moves center on single-vendor contract consolidation and compliance-as-a-service module embedding.
Within the dispatch-specialist tier, iCabbi and Autocab exemplify contrasting architectural philosophies. iCabbi occupies a position anchored in Ireland and United Kingdom operator relationships sustained through legacy protocol expertise. Autocab represents the vertically integrated driver-terminal ecosystem approach that fleet managers in dense urban corridors increasingly favor. Yelowsoft sits within the modular camp, its white-label SDK architecture enabling mid-size operators to deploy branded consumer interfaces without captive development teams.
| Leading Market Players |
|---|
| Yelowsoft |
| iCabbi |
| Autocab |
| TaxiCaller |
| Cabsoluit |
| AllRide |
| Cab Treasure |
| Onde |
| Zoyride |
| Others |
Value Chain & Pricing Dynamics
Multi-city fleet operators with 500-plus vehicle fleets command concentrated procurement leverage, anchoring subscription-based SaaS pricing as the dominant commercial model across taxi booking platforms. Their consolidated vendor selection compresses procurement cycles while amplifying volume-discount negotiating power against modular SDK providers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by integration complexity and compliance module depth. Premium tiers bundle FCC-certified GPS-enhanced matching engines with GDPR-localized data handling, while economy tiers offer stripped dispatch automation for secondary cities. Cost compression in the mid-tier is intensifying because municipal open-data mandates force API interoperability investments without corresponding price elasticity. Small taxi operators in North American secondary cities exhibit highest price sensitivity due to legacy radio network sunk costs, whereas London and New York City fleet managers prioritize compliance bundling over unit economics.
Supply Chain Analysis
Certification gating through FCC mobile-app approval and EMA data-governance protocols fragments vendor qualification pathways across jurisdictions. Software development concentrates in Ireland, the United Kingdom, and India, with Indian vendors drawing from domestic engineering talent pools under BIS cloud-security standards. Critical dependencies include GPS chipset modules, encryption libraries, and payment gateway APIs. Single-source vulnerability runs through cloud infrastructure providers serving elastic compute workloads. Distribution runs through direct enterprise sales teams targeting fleet procurement committees, supplemented by channel partners serving independent driver marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
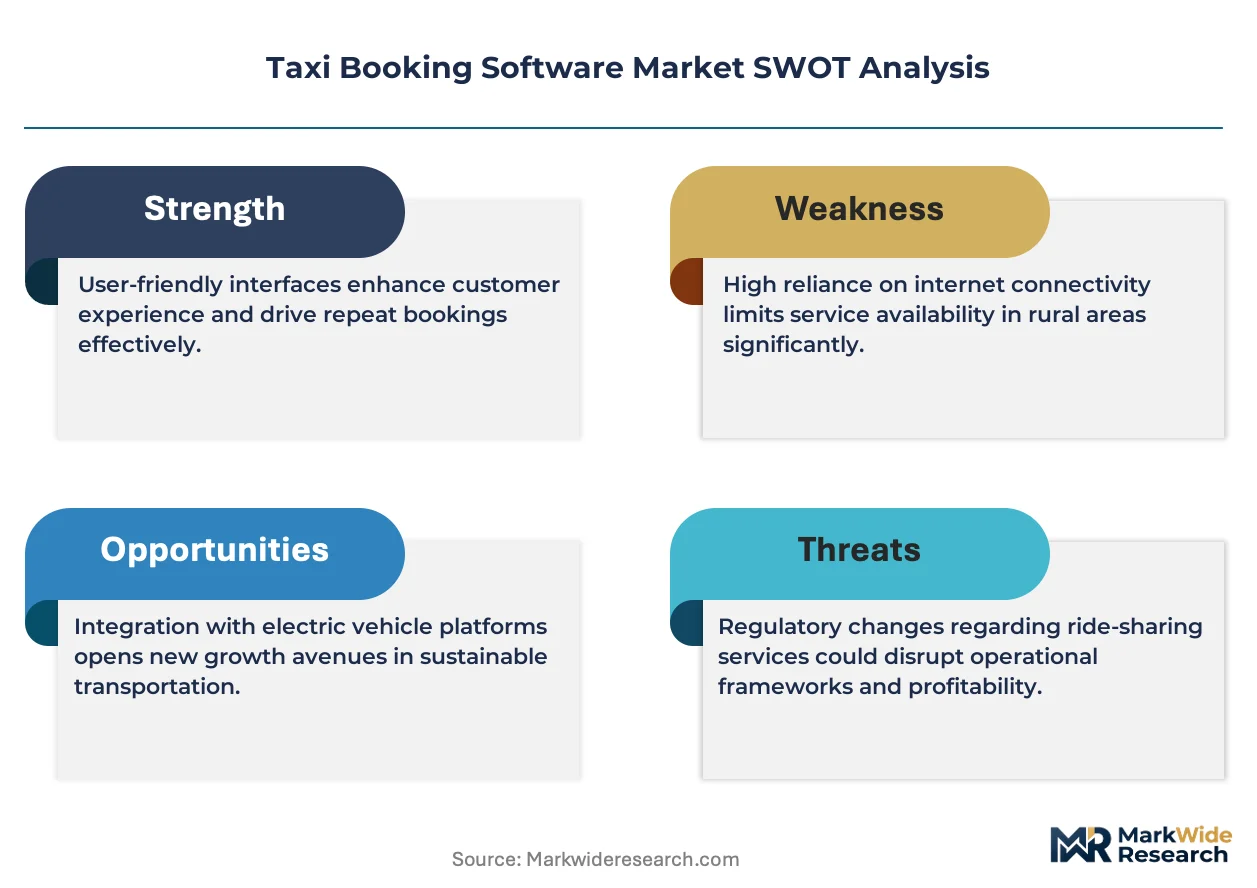
GDPR localization costs in Europe run 40-60% above comparable US deployments, creating arbitrage opportunities for vendors with modular compliance architectures that port across regulatory regimes without full stack rebuilds.
For Market Incumbents: Deepen vertical integration into driver-terminal hardware to defend against white-label SDK disintermediation. Autocab's ecosystem approach demonstrates how captive hardware-software bundles lock in fleet procurement committees. Prioritize EMA compliance-as-a-service module embedding to capture margin from smaller vendors buckling under GDPR enforcement costs. For New Entrants and Emerging Players: The premium-to-economy price gap in backend systems offers entry space for hybrid-deployment specialists serving India's TRAI-constrained market. Target Mumbai and Bangalore taxi operators seeking domestic data-center routing without full on-premise infrastructure. Lead with BIS-certified payment processing modules as the wedge capability, then expand into dispatch automation. For Investors and Strategic Acquirers: Fleet management software consolidators are the most active acquirer in this space, seeking dispatch-specialist targets with deep municipal protocol expertise. Long-term viability hinges on regulatory fragmentation persisting across FCC, EMA, and TRAI jurisdictions. Watch for API interoperability talent scarcity as the inflection signal—acute shortages in legacy dispatch protocol engineers will accelerate acquisition premiums for qualified teams.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance-as-a-Service Module Embedding | EMA data-governance protocols harden passenger-data handling requirements across European deployments. |
| Hybrid Deployment Architecture Launch | Indian operators favor split architectures under BIS standards constraining payment routing. |
| API Interoperability Specialist Acquisition | Municipal mandates force upgrades requiring engineers familiar with legacy radio protocols. |
| White-Label SDK Platform Expansion | Mid-size fleet operators deploy branded interfaces without captive development teams. |
| Vertically Integrated Driver-Terminal Ecosystem | Single-vendor contracts displace best-of-breed procurement in 500-plus vehicle fleets. |
Study Parameters
Multiple input streams — fleet operator procurement interviews, platform vendor technical disclosures, and municipal regulatory filings — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged CTOs at multi-city fleet operators, integration specialists at white-label SDK providers, and regulatory affairs leads navigating FCC and EMA certification pathways. Secondary validation drew from SEC filings of mobility-technology consolidators, TRAI net-neutrality rulings, and BIS cloud-security standard documentation. Bottom-up deployment counts and top-down SaaS revenue pools were triangulated to anchor market sizing.
Data-stream reconciliation across product type, service layer, and deployment model dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves calibrated against municipal mandate implementation timelines. Modeled inputs included cloud infrastructure capacity expansion, API interoperability upgrade cycles, and payment gateway regulatory routing constraints.
The model assumes a particular technology adoption path; alternative pathways for AI-powered surge-pricing algorithms would alter the outlook if regulatory caps on dynamic pricing emerge. Forecasts reflect documented assumptions about municipal open-data mandate enforcement intensity and cloud-security standard harmonization. A model refresh is warranted upon material change in FCC emergency-location accuracy certification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Vehicle Embedded Software Market
Software & Services
Global Mobile Application Testing Solution Market
Software & Services
Global Church Management Software Market
Software & Services
Small Business Marketing Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
Hydraulic Modeling Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Global Proposal Management Software Market
Software & Services
India Software Services Export Market
Software & Services
Software-Defined Anything Market
Software & Services
United Kingdom IT Services Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Customer Revenue Optimization Software Market
Software & Services
IT Services Market
Software & Services
Global Programming Software Market