
 Executive Search (Headhunting) Software Market | 2026-2036
Executive Search (Headhunting) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Executive Search (Headhunting) Software Market Foresight
Platform licensing revenue is reshaping competitive economics in executive search technology, shifting value capture from perpetual deployments toward recurring SaaS architectures. Vincere leverages cloud-native infrastructure to anchor its position among mid-market recruitment agencies across Europe. QLU sustains differentiation through AI-driven candidate matching algorithms that reduce time-to-placement for retained search mandates. Cluen competes by dominating the relationship intelligence layer, where decades of interaction data creates switching costs for boutique executive search firms.
Executive search software comprises specialized applications that automate candidate sourcing, engagement tracking, and placement workflow management for retained and contingency search operations, typically integrating with professional networking databases and calendar systems to map organizational hierarchies and predict candidate availability. Recruitment CRM solutions lead the solution type category because search firms prioritize relationship capital over transaction volume, while talent intelligence platforms represent the fastest-growing segment as predictive analytics displace manual research methods. Cloud-based deployment anchors the infrastructure mix, though hybrid architectures persist among established firms managing sensitive candidate data under strict confidentiality protocols.
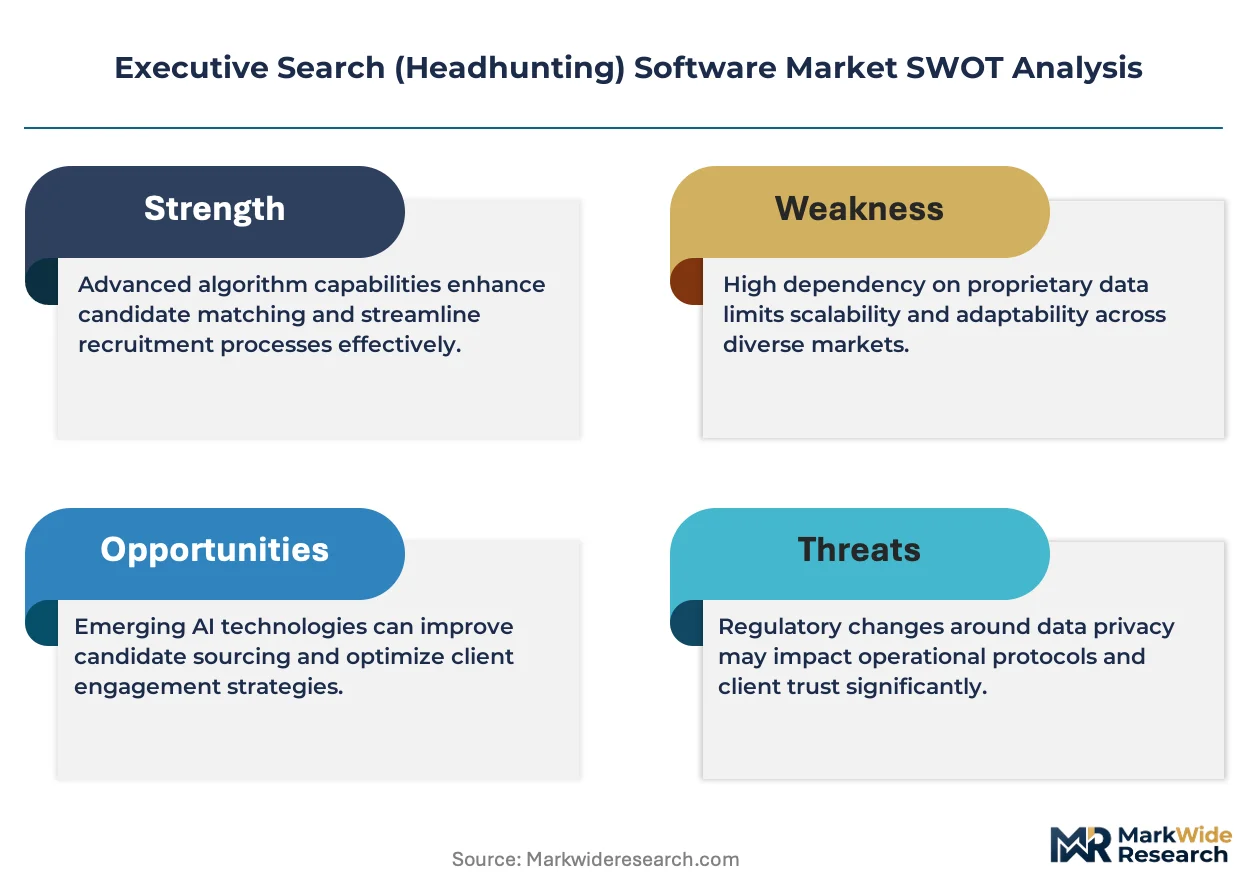
The EU AI Act and GDPR impose algorithmic transparency requirements on automated candidate ranking systems, compelling vendors to document decision logic and enable human override functions. The US Equal Employment Opportunity Commission scrutinizes AI hiring tools for disparate impact, creating compliance complexity for platforms deployed across multinational search engagements. Stakeholders must monitor evolving regulatory definitions of automated decision-making to determine whether their scoring engines trigger mandatory audit obligations or disclosure requirements.
Market Dynamics
The transition from perpetual license models to recurring SaaS revenue streams is compressing vendor margins while expanding addressable markets through lower entry costs for boutique search firms.
Growth Catalysts
- EU AI Act compliance mandates:Regulatory pressure across European jurisdictions is forcing retained search firms to upgrade from spreadsheet-based tracking to auditable platforms with documented decision trails.
- Predictive analytics in talent mapping:Machine learning models that forecast executive mobility patterns are shortening research cycles for C-suite mandates in financial services and private equity.
- Contingency search digitization:Mid-market agencies in Germany and France are abandoning fragmented email-and-CRM workflows for unified candidate engagement systems.
Market Restraints
- GDPR data portability requirements:The technical burden of enabling candidate data extraction without compromising relationship intelligence creates engineering overhead that slows vendor roadmaps.
- Cloud infrastructure concentration:Reliance on hyperscale providers in Ireland and Frankfurt for EU data residency limits vendor negotiating leverage and compresses gross margins.
- Legacy system entrenchment:Decades of proprietary contact databases stored in on-premise Cluen and FileMaker installations create switching friction that delays platform consolidation.
Strategic Opportunities
- Underpenetrated Benelux mid-market:Brussels and Amsterdam-based boutique firms managing EU institutional mandates still operate on decade-old infrastructure without relationship analytics.
- API-first ecosystem integration:Native connectivity with LinkedIn Recruiter, Calendly, and Zoom is displacing manual data entry and creating platform stickiness through workflow embedding.
- CSRD sustainability reporting:Executive search firms serving ESG-focused boards require diversity tracking and carbon footprint measurement tools that current platforms lack.
Industry Challenges
- AI transparency engineering:Building explainable candidate scoring systems that satisfy French CNIL and German BfDI scrutiny demands specialized compliance talent scarce among SaaS vendors.
- Multi-jurisdiction deployment complexity:Simultaneous compliance with US EEOC disparate impact rules and EU algorithmic accountability frameworks fragments product architecture and slows release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Executive Search (Headhunting) Software Market |
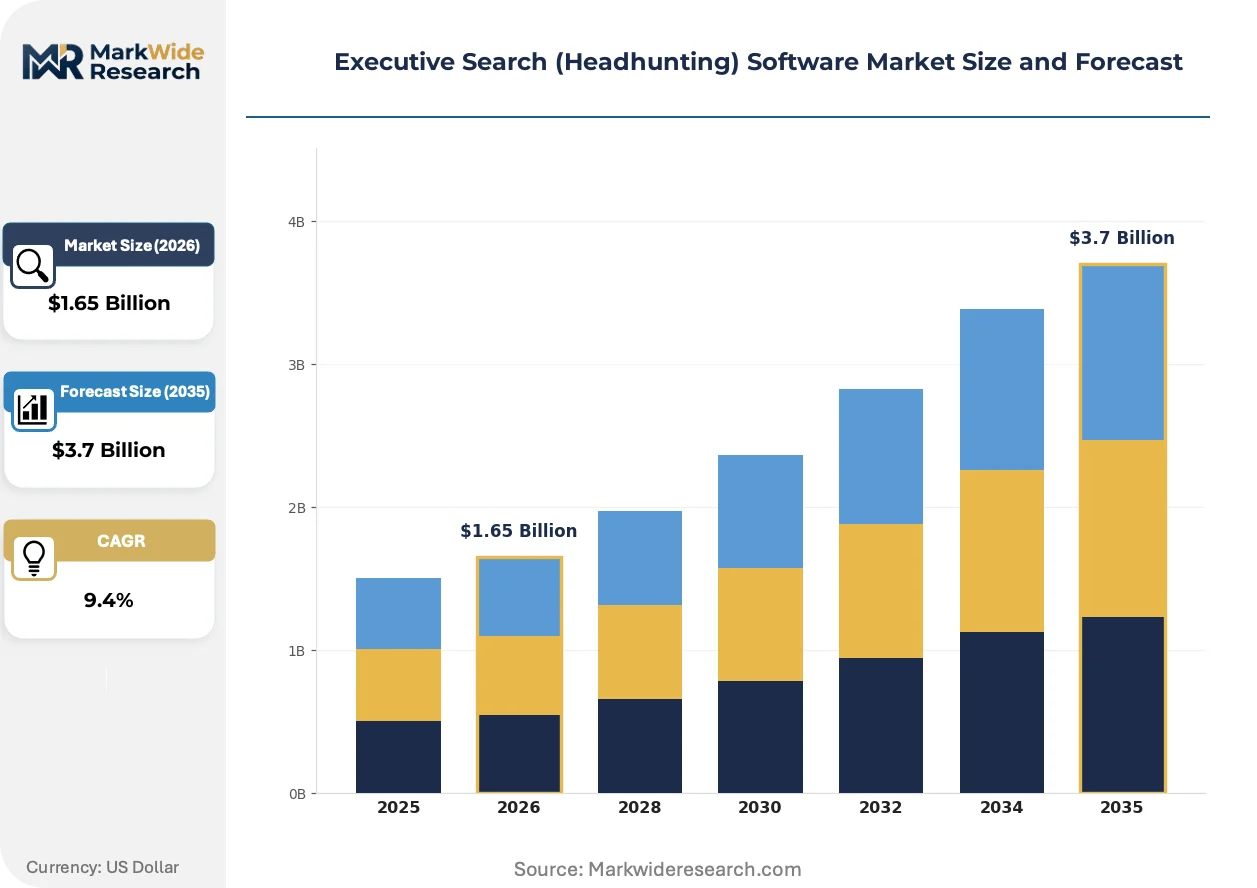
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.7 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Applicant Tracking System, Recruitment CRM, Video Interviewing Solutions, Talent Intelligence Platforms Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS End User: Corporations, Recruitment Agencies, Executive Search Firms, HR Departments Pricing Model: Subscription, Pay-Per-User, One-Time License, Freemium |
| Companies Covered | QLU, Invenias, Cluen, Clockwork, Talentis, Vincere, iSmartRecruit, Recruiterflow, Metaview, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Executive Search (Headhunting) Software Market Shifts & Advancements
Automation of candidate sourcing and relationship mapping is compressing the traditional research-to-outreach timeline from weeks to days, forcing vendors to compete on predictive accuracy rather than database scale.
Generative AI for personalized executive outreach is rendering obsolete the template-based email sequences that dominated retained search business development for two decades. Boutique firms in London and New York are deploying large language models to craft role-specific narratives at scale. The technology is compressing the cost structure of candidate engagement while raising client expectations for speed.
The EU AI Act's risk-based classification system is forcing vendors to redesign automated ranking features as assistive rather than determinative tools. Platforms must now implement human-in-the-loop checkpoints for high-stakes executive placements. German search firms serving automotive and industrial clients are pioneering compliance frameworks that other EU jurisdictions are adopting.
Subscription pricing for talent intelligence is displacing the traditional per-placement fee structure that tied vendor revenue to search firm success. Mid-market agencies in Spain and Italy are demanding platform access without contingent costs. This shift is visible most acutely among contingency search operations where placement volumes fluctuate seasonally.
Executive Search (Headhunting) Software Market Segmentation
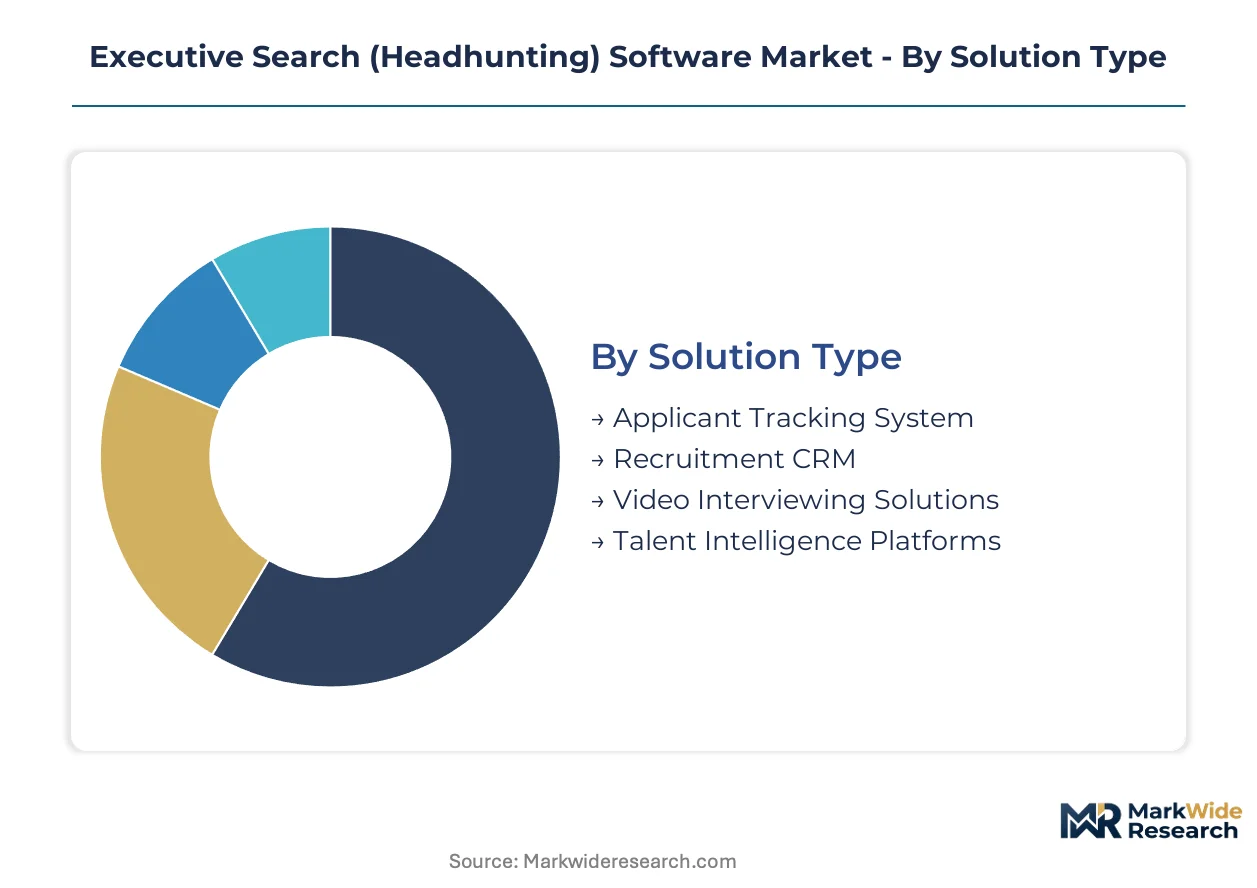
Executive search software vendors architect product portfolios around distinct operational workflows, with solution configuration directly tied to client sophistication and data sovereignty requirements. Segmentation reveals where platform economics concentrate and which deployment architectures capture margin.
Solution Type:
After-sales service intensity varies sharply across solution categories, with talent intelligence platforms demanding continuous model retraining and compliance documentation while applicant tracking systems require lighter ongoing support.
- Applicant Tracking System:Workflow automation engines that manage requisition posting, resume parsing, and pipeline progression through standardized stages. Corporations in the United States prioritize ATS modules with native EEOC reporting to satisfy federal contractor obligations. By volume, applicant tracking systems lead. By growth pace, talent intelligence platforms are climbing the fastest.
- Recruitment CRM:Relationship-centric databases capturing interaction history, meeting notes, and organizational mapping for retained search operations. Executive search firms in London and New York anchor demand here, valuing decades-long contact histories over transactional efficiency. Recruitment CRM solutions command premium pricing through data migration services that preserve proprietary relationship networks.
- Video Interviewing Solutions:Asynchronous and live video platforms with structured evaluation frameworks for early-stage candidate screening.
- Talent Intelligence Platforms:Predictive analytics systems forecasting executive mobility, compensation benchmarks, and succession vulnerability through machine learning models.
By revenue concentration, recruitment CRM dominates retained search. By expansion trajectory, talent intelligence platforms are gaining share fastest.
Deployment Model:
Cost tier stratification separates enterprise clients willing to absorb infrastructure overhead from mid-market buyers seeking operational expenditure predictability.
- Cloud-Based:Fully managed multi-tenant architectures with automatic updates and elastic scaling. Mid-market agencies in Germany and France favor cloud deployment for GDPR-compliant EU data residency without capital expenditure. Cloud-based delivery eliminates version fragmentation that plagued on-premise upgrade cycles.
- On-Premises:Single-tenant installations within client data centers, preserving complete control over security configurations and network isolation. Boutique executive search firms in Switzerland and Luxembourg maintain on-premise systems to satisfy banking client confidentiality protocols. These deployments carry higher lifetime service costs due to manual patch management.
- Hybrid:Split architectures placing sensitive candidate data on-premise while leveraging cloud analytics for non-confidential processing.
- SaaS:Subscription-native delivery with usage-based scaling and embedded compliance updates for evolving regulatory frameworks.
By installed base, cloud-based deployments lead. By new contract velocity, SaaS offerings are expanding most quickly.
End User:
Customer type determines feature prioritization, with executive search firms demanding relationship depth and corporations requiring process standardization across distributed hiring managers.
- Corporations:Enterprise buyers integrating search software with broader HRIS ecosystems and procurement systems. Multinational technology firms in Ireland and the Netherlands drive demand for unified platforms replacing fragmented point solutions. Corporations prioritize audit trails and diversity analytics for board reporting.
- Recruitment Agencies:Contingency-focused operators valuing speed-to-candidate and placement volume metrics over relationship longevity. Agencies in Spain and Italy favor modular pricing that scales with seasonal hiring cycles. This segment exhibits highest price sensitivity and churn risk.
- Executive Search Firms:Retained search specialists managing C-suite mandates with multi-year engagement horizons.
- HR Departments:Internal talent acquisition teams balancing executive search with high-volume recruitment.
By aggregate spending, executive search firms lead. By user growth, HR departments are climbing the fastest.
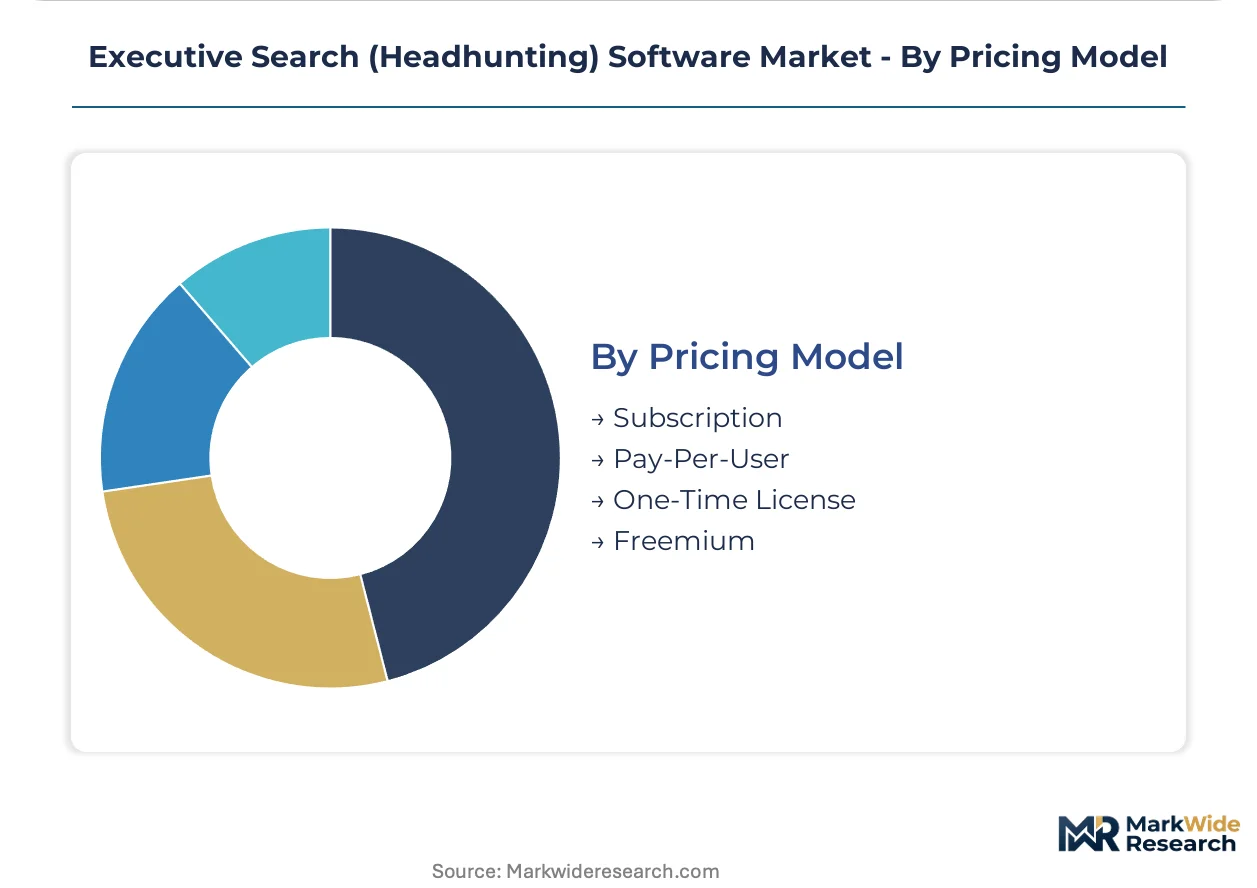
Pricing Model:
Margin structure diverges between recurring revenue architectures and perpetual license models, with vendor strategy increasingly favoring predictable subscription streams.
- Subscription:Recurring monthly or annual fees bundling platform access, support, and continuous feature delivery. Vendors targeting the United States market default to subscription pricing to align with SaaS procurement standards. This model compresses upfront revenue but extends customer lifetime value.
- Pay-Per-User:Seat-based licensing scaling with headcount and active recruiter count. Mid-market firms in Belgium and the Netherlands prefer pay-per-user structures for workforce flexibility. Pricing granularity enables precise cost allocation across practice groups.
- One-Time License:Perpetual purchase with optional maintenance contracts, now concentrated among legacy on-premise installations.
- Freemium:Limited-feature entry tiers converting to paid subscriptions through usage thresholds or advanced functionality.
By contract volume, subscription pricing leads. By adoption momentum, freemium models are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor infrastructure clusters in Ireland and Germany to satisfy EU data residency mandates, while United States hyperscale providers dominate cloud delivery. Demand dispersion follows financial services and technology sector concentration.
United States
Enterprise technology firms and private equity houses drive predictive analytics procurement for C-suite succession planning. The EEOC scrutinizes AI hiring tools for disparate impact, compelling vendors to document decision logic. New York and Boston anchor retained search firm density, with boutique agencies investing heavily in relationship-mapping platforms.
Germany
Automotive and industrial clients demand algorithmic transparency for executive placements under BfDI guidance. The EU AI Act mandates human-in-the-loop checkpoints for automated candidate ranking systems. Frankfurt and Munich host the densest concentration of search firms serving DAX-listed conglomerates.
United Kingdom
London-based boutiques lead adoption of generative AI for personalized executive outreach at scale. The Information Commissioner's Office enforces GDPR data portability requirements that complicate legacy system migrations. The City and Canary Wharf financial clusters sustain premium pricing for talent intelligence subscriptions.
France
CNIL audit obligations for automated decision-making slow deployment of candidate scoring engines among Parisian search firms. The EU AI Act risk-based classification system forces platform redesigns toward assistive rather than determinative tools. La Défense and central Paris house retained search specialists serving luxury and aerospace sectors.
Netherlands
Amsterdam-based agencies managing EU institutional mandates still operate on decade-old infrastructure without relationship analytics. GDPR compliance complexity creates vendor switching friction for firms serving banking clients in Luxembourg and Brussels. The Randstad metro anchors contingency search digitization among mid-market operators.
Executive Search (Headhunting) Software Market Competitive Landscape
Cloud-native specialists and legacy relationship intelligence providers split the market between speed-to-deployment and data moat defensibility. The vendor landscape exhibits moderate concentration, with mid-market SaaS entrants challenging established on-premise incumbents through API-first architectures. Two strategic archetypes dominate: subscription-native platforms optimizing for recurring revenue capture, and database-centric systems maximizing switching costs through proprietary contact histories. Competitive moves center on M&A for compliance technology capabilities and strategic partnerships with professional networking data providers.
Within the cloud-native tier, Vincere and QLU exemplify divergent positioning strategies. Vincere occupies a position among mid-market recruitment agencies across Europe, leveraging infrastructure efficiency to compress entry costs. QLU anchors the AI-driven matching segment, representing the predictive analytics specialization that shortens retained search timelines. Cluen sits within the relationship intelligence layer, where decades of accumulated interaction data create structural barriers to displacement for boutique executive search firms.
| Leading Market Players |
|---|
| QLU |
| Invenias |
| Cluen |
| Clockwork |
| Talentis |
| Vincere |
| iSmartRecruit |
| Recruiterflow |
| Metaview |
| Others |
Supply & Pricing Matrix
Hyperscale cloud infrastructure in Ireland and Frankfurt concentrates upstream compute costs for executive search software vendors, compressing gross margins while anchoring subscription pricing power downstream among SaaS-native providers. This geographic concentration of EU data residency compliance creates tiered margin pools where cloud-native platforms capture recurring value against on-premise legacy installations.
Pricing Analysis
Implementation services and continuous compliance documentation drive lifetime value more than initial subscription fees, with vendors bundling GDPR audit support and EU AI Act documentation into enterprise tiers. Three-tier pricing structure across premium, standard, and economy levels separates full relationship intelligence suites from stripped-down ATS modules and freemium entry points. Cost compression in mid-market segments is intensifying because contingency search agencies in Southern Europe demand platform access without placement-linked fees. Recruitment agencies exhibit highest price sensitivity, while retained executive search firms prioritize data migration fidelity over subscription cost.
Supply Chain Analysis
Export-control scrutiny on machine learning training infrastructure limits flows of advanced GPU clusters into certain jurisdictions, forcing vendors to architect compliance-first deployment patterns. Software development concentrates in the United States, Germany, and the United Kingdom, with EU data residency requirements tethering cloud hosting to Ireland and Frankfurt. Raw material dependencies include proprietary professional networking data licenses, hyperscale compute contracts, and specialized compliance engineering talent. Single-source vulnerability runs through LinkedIn's API access terms, which can shift without notice. Distribution runs through direct enterprise sales teams for large accounts and self-service digital channels for mid-market adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in executive search technology hinge on API-first interoperability, with vendors embedding into LinkedIn Recruiter, Calendly, and Zoom workflows to create switching costs that transcend raw feature comparisons.
For Market Incumbents: Pre-empt displacement by cloud-native entrants through accelerated data migration tooling that preserves decades of proprietary contact histories for boutique search firms. Invest in in-house compliance engineering capabilities to satisfy French CNIL and German BfDI audit requirements without external dependency. The threat of AI-native matching algorithms from QLU and similar specialists demands defensive capability acquisition in predictive analytics. For New Entrants and Emerging Players: Build out white-space presence in Brussels and Amsterdam-based boutique firms managing EU institutional mandates, where decade-old infrastructure lacks relationship analytics entirely. Target Benelux mid-market agencies with modular pricing that scales with seasonal hiring cycles. A compliance-first go-to-market angle—pre-built EU AI Act documentation and GDPR data portability tooling—differentiates against legacy vendors burdened by technical debt. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed recruitment technology platforms seeking exit liquidity through consolidation with adjacent talent intelligence capabilities. Long-term viability favors vendors with demonstrated compliance architecture across multiple European jurisdictions rather than single-market point solutions. The signal to watch is regulatory enforcement velocity—material fines under the EU AI Act would accelerate replacement demand for non-compliant legacy systems.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native API connectivity with LinkedIn Recruiter eliminates manual data entry friction for retained search workflows. |
| Acquisition of Specialist Firm | Purchasing compliance technology vendors addresses EU AI Act documentation gaps without internal R&D delay. |
| Geographic Expansion | Establishing Frankfurt infrastructure satisfies BfDI data residency mandates for automotive and industrial search clients. |
| Strategic Partnership | Alliances with professional networking data providers secure proprietary relationship intelligence moats against cloud-native entrants. |
| Product Launch | CSRD-aligned diversity tracking and carbon footprint modules capture ESG-focused board search demand lacking current tools. |
Research Methodology
Initial hypotheses were tested against primary input from executive search firm managing partners, chief technology officers at recruitment agencies, GDPR compliance officers, and vendor product managers, then refined through secondary validation against SEC filings, EU regulatory guidance documents, hyperscaler capex disclosures, and trade association reports. Bottom-up modeling of vendor contract values triangulated with top-down market sizing across deployment models and end-user segments.
Demand-supply balance framing anchored the analytical framework, with segmentation across solution type, deployment architecture, organization size, integration complexity, and regional adoption pattern modeled throughout the forecast period. CAGRs were derived from growth rate convergence analysis applied to subscription revenue trajectories and replacement cycle timing for legacy on-premise installations. Forecast inputs included EU AI Act implementation timelines and EEOC enforcement patterns on AI hiring tools.
Stress conditions across regulatory enforcement velocity, cloud infrastructure pricing, and professional networking API access terms were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about compliance cost trajectories and replacement demand timing. Material shifts in EU AI Act risk classification thresholds or hyperscaler market concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
3D CAD Software Market
Software & Services
Chemical Manufacturing Software Market
Software & Services
Website Translation Software Market
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Middle East and Africa Automotive Software Market
Software & Services
Global Ad Server Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Global Chromatography Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Pure Play Software Testing Market
Software & Services
Global Construction Punch List Software Market
Software & Services
Server Software Market
Software & Services
Computer Assisted Translation Software Market
Software & Services
Global Architect Software Market
Software & Services
Non-Profit Software Market