
 SMS Marketing Software Market | 2026-2036
SMS Marketing Software Market Size, Share, and Industry Trends Forecast 2026-2036
SMS Marketing Software Market Analysis
API-first architecture is pivoting SMS marketing software economics away from monolithic legacy stacks toward modular, programmable messaging infrastructure. Twilio leverages its developer-centric platform to anchor cloud-native messaging workflows for enterprise clients. Attentive specializes in AI-powered personalization layers that differentiate its offering for retail and hospitality verticals. Postscript controls the Shopify-integrated SMS commerce niche with deep e-commerce automation capabilities.
SMS marketing software comprises programmable messaging platforms that transmit text-based communications through carrier-grade SMPP or REST API protocols, typically supporting throughput rates exceeding 10,000 messages per second for high-volume campaigns. These systems orchestrate opt-in subscriber management, automated drip sequences, and two-way conversational flows to drive direct-response revenue for commercial entities. Cloud-based deployment dominates structural investment as enterprises abandon on-premise infrastructure maintenance, while the automation feature set captures disproportionate R&D allocation due to its margin expansion potential across SaaS pricing tiers. The analytics feature dimension is maturing rapidly as attribution modeling becomes table stakes, though personalization modules still command premium pricing from retailers and e-commerce operators seeking cart-recovery yield improvement.
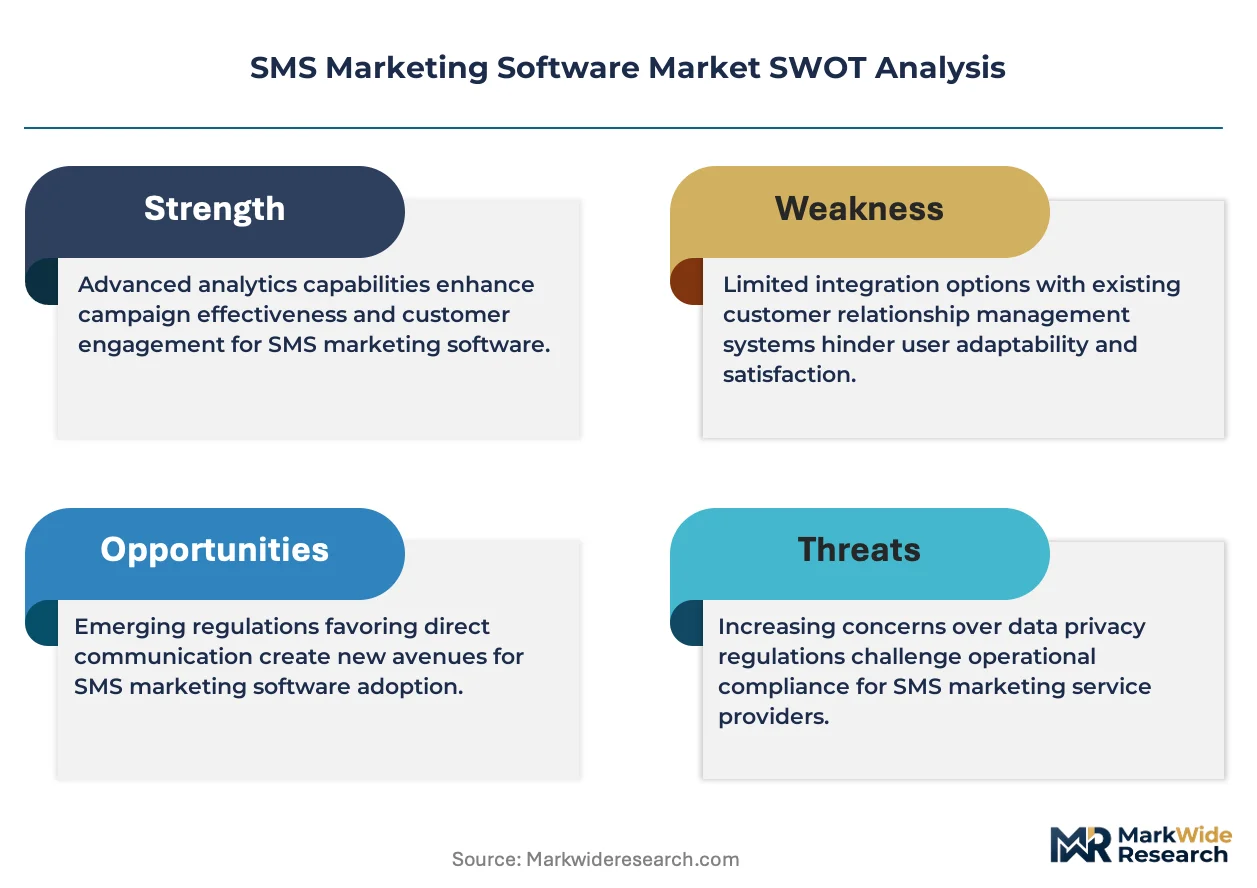
The Federal Communications Commission enforces TCPA consent requirements that elevate compliance infrastructure costs and filter out subscale vendors lacking legal-technology integration. The EU AI Act and GDPR jointly constrain automated message personalization across European deployments, creating divergent product roadmaps for cross-border platform providers. Stakeholders must monitor evolving carrier surcharge regimes and A2P 10DLC registration mandates as these fee structures directly compress unit economics for high-volume senders.
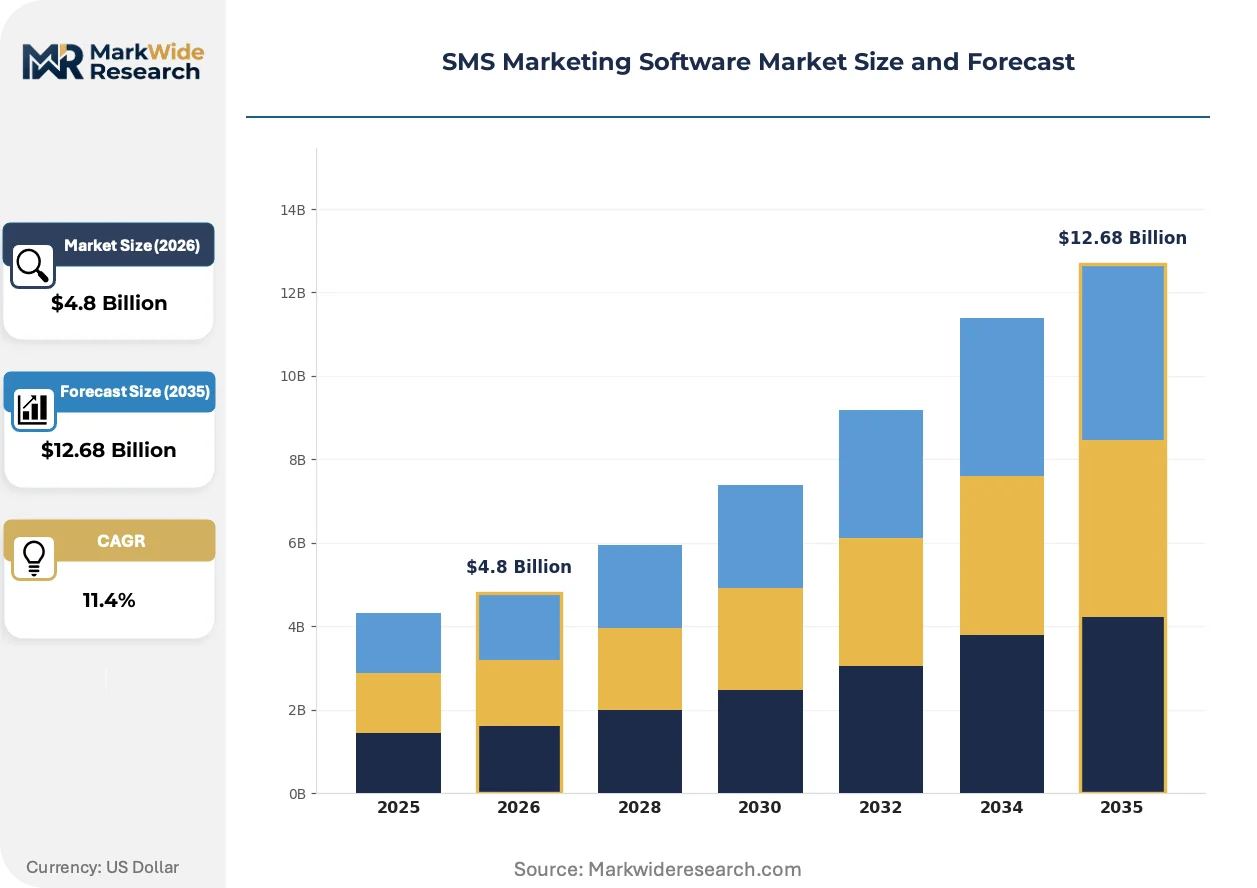
Market Dynamics
Carrier-grade SMPP infrastructure is consolidating around cloud-native API stacks as legacy on-premise deployments face unsustainable maintenance burdens and talent scarcity. This architectural migration concentrates purchasing power among enterprise buyers demanding programmable throughput exceeding 10,000 messages per second.
Growth Catalysts
- A2P 10DLC registration mandates:The FCC-enforced framework filters subscale vendors and elevates compliance infrastructure spending, creating captive demand for integrated legal-technology platforms among high-volume senders.
- Cart-recovery automation:Retail and hospitality operators deploy AI-powered drip sequences to recapture abandoned transactions, driving platform stickiness through measurable revenue attribution.
- Cloud deployment preference:North American enterprise buyers abandon data center ownership for elastic infrastructure, compressing vendor sales cycles and expanding addressable seat counts per contract.
Market Restraints
- Carrier surcharge volatility:Per-message fees from tier-one mobile network operators compress unit economics for high-volume campaigns, forcing platform providers to absorb margin erosion or pass costs to price-sensitive mid-market segments.
- Cross-border regulatory fragmentation:The EU AI Act and GDPR jointly constrain automated personalization architectures, requiring divergent product roadmaps that inflate R&D overhead for multi-territory deployments.
- Consent management complexity:TCPA litigation exposure elevates legal-technology integration costs beyond the reach of subscale vendors, consolidating supply among well-capitalized platforms with dedicated compliance modules.
Strategic Opportunities
- Two-way conversational commerce:Natural language processing integration enables interactive purchase flows within messaging threads, opening premium pricing tiers for platforms that reduce friction in high-consideration transactions.
- Underpenetrated LATAM markets:Brazil and Mexico exhibit low SMS marketing saturation relative to mobile commerce penetration, presenting first-mover advantages for localized compliance infrastructure and Portuguese-Spanish language automation.
- Attribution modeling convergence:Unified identity resolution across SMS, email, and paid media channels creates cross-sell opportunities for platforms with native customer data platform capabilities.
Industry Challenges
- Legacy system integration friction:Enterprise ERP and CRM environments require custom middleware development, extending implementation timelines and inflating professional services costs relative to SaaS subscription revenue.
- Deliverability engineering scarcity:Deep expertise in carrier relationship management and spam-filter evasion concentrates among senior practitioners, constraining platform scaling velocity and inflating compensation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SMS Marketing Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Tenant Target Audience: Retailers, E-Commerce, Hospitality, Nonprofits Feature: Automation, Analytics, Personalization, Integration Service Type: SaaS, Managed Services, Consulting, Support |
| Companies Covered | SimpleTexting, Postscript, Twilio, TextUs, Salesmsg, ActiveCampaign, Attentive, Falkon SMS, Klaviyo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SMS Marketing Software Market Emerging Trajectories
Programmable messaging infrastructure is displacing campaign-centric tools as buyers prioritize workflow automation over broadcast capabilities. This shift rewards vendors with native developer ecosystems and modular API architectures.
Generative AI is automating message composition and personalization at scale, enabling retail marketers to produce variant copy for segmented audiences without creative team bottlenecks. Mid-market e-commerce operators adopt these tools fastest, compressing campaign deployment from days to hours. The technology is automating the traditional agency intermediary role and capturing margin that previously flowed to creative services providers.
The EU AI Act imposes transparency requirements on automated messaging systems that deploy predictive personalization, forcing platform providers to implement explainability layers and human-in-the-loop safeguards. European deployments now require distinct product architectures from North American counterparts, fragmenting engineering roadmaps and elevating compliance tooling costs. Retail and hospitality verticals operating across both jurisdictions face the steepest adaptation burdens as they reconcile divergent consent and audit standards.
Subscription-based pricing is displacing usage-based models as enterprise procurement teams seek predictable operational expenditure structures. Annual platform fees with bundled message allotments replace per-SMS metering, transferring volume risk to vendors and compressing margins on high-throughput accounts. This shift is most visible among North American retailers consolidating vendor relationships under master service agreements with committed spend minimums.
SMS Marketing Software Market Segmentation
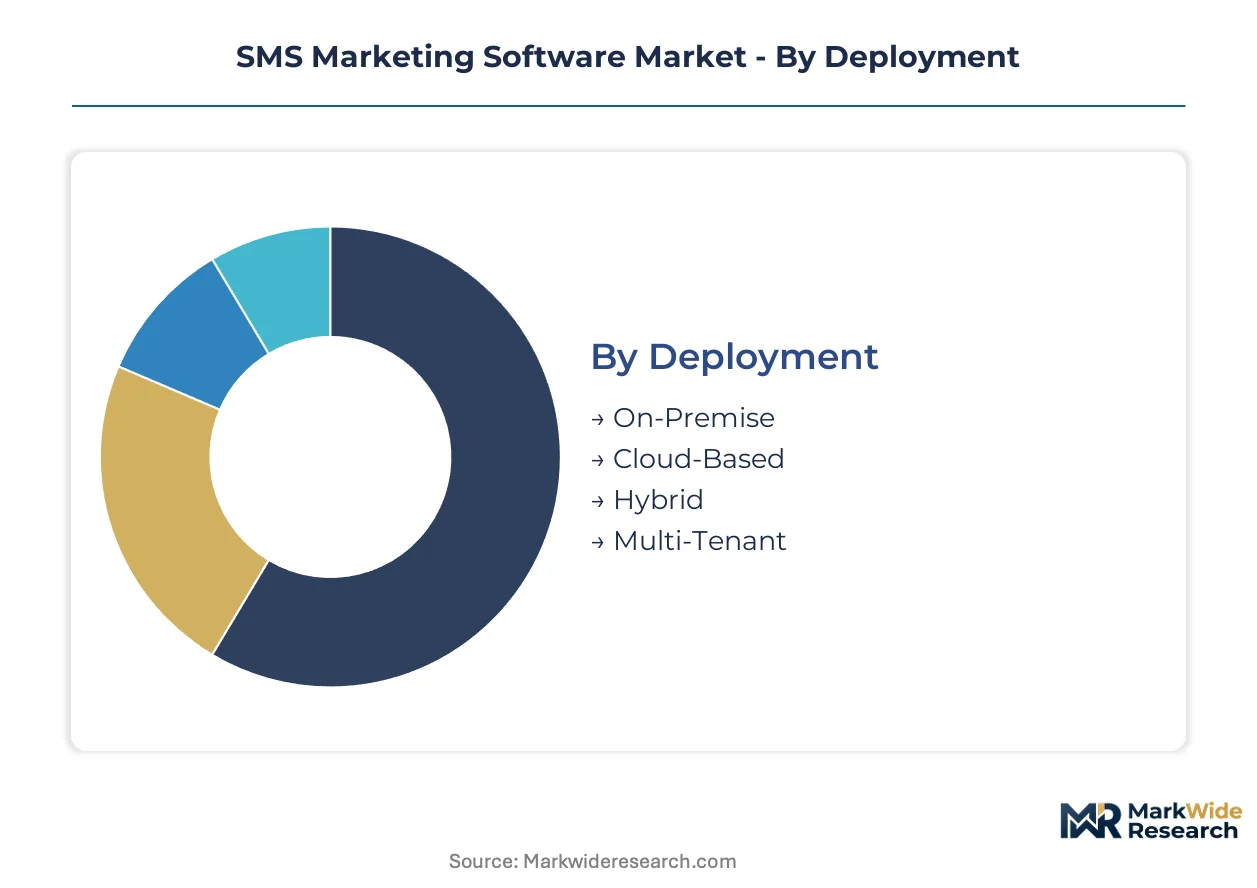
SMS marketing software vendors architect product portfolios around deployment flexibility and buyer sophistication tiers. Segmentation discipline separates high-velocity cloud adopters from compliance-constrained legacy operators, while feature packaging captures differential willingness to pay across retail and hospitality verticals.
Deployment:
Cloud-based infrastructure commands volume leadership while hybrid deployments capture premium pricing from regulated enterprises.
- Cloud-Based:Elastic compute resources enable throughput scaling beyond 10,000 messages per second without capital expenditure. North American retailers consolidate procurement under multi-year agreements with committed spend minimums, transferring volume risk to platform providers.
- On-Premise:Dedicated hardware installations serve financial services and healthcare entities with data residency mandates. Germany and Switzerland maintain disproportionate demand due to national banking secrecy frameworks and Bundesdatenschutzgesetz compliance requirements.
- Hybrid:Split architectures route sensitive subscriber data through private infrastructure while leveraging public cloud for broadcast campaigns. Mid-market e-commerce operators in France adopt this model to reconcile GDPR consent management with cost efficiency.
- Multi-Tenant:Shared infrastructure partitions resources across client organizations with tenant-isolated data stores. This configuration attracts agency holding companies managing brand portfolios across CPG and quick-service restaurant accounts.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Target Audience:
Retail concentration versus hospitality fragmentation shapes go-to-market economics and customer acquisition costs.
- Retailers:Brick-and-mortar chains deploy location-triggered messaging to bridge physical and digital commerce. Cart-recovery automation generates measurable revenue attribution that sustains platform stickiness through renewal negotiations.
- E-Commerce:Direct-to-consumer brands prioritize Shopify-integrated workflows with abandoned checkout sequences. This segment expands most quickly as merchant adoption of conversational commerce accelerates in Brazil and Mexico.
- Hospitality:Hotel and restaurant operators leverage two-way booking confirmations and real-time service recovery. Seasonal demand volatility complicates subscription pricing models and elevates churn risk during low-occupancy periods.
- Nonprofits:Donor stewardship campaigns emphasize compliance-light peer-to-peer fundraising tools. Limited technology budgets constrain feature adoption to core broadcast capabilities with minimal automation layering.
Revenue concentrates with E-Commerce. Margin expansion sits with Hospitality.
Feature:
Automation modules capture disproportionate R&D investment due to recurring revenue expansion potential across pricing tiers.
- Automation:Drip sequences and behavioral triggers orchestrate subscriber lifecycle management without manual campaign execution. AI-powered personalization layers from Attentive demonstrate premium pricing power in retail verticals.
- Analytics:Attribution modeling converges SMS performance with email and paid media channels. Unified identity resolution capabilities differentiate platforms with native customer data platform architecture.
- Personalization:Dynamic content insertion adapts message copy to individual purchase history and browsing behavior. EU AI Act transparency requirements fragment product roadmaps for European versus North American deployments.
- Integration:API connectivity bridges SMS workflows with ERP, CRM, and e-commerce environments. Custom middleware development extends implementation timelines and inflates professional services costs relative to SaaS subscription revenue.
Automation anchors current bookings. Analytics drives renewal expansion.
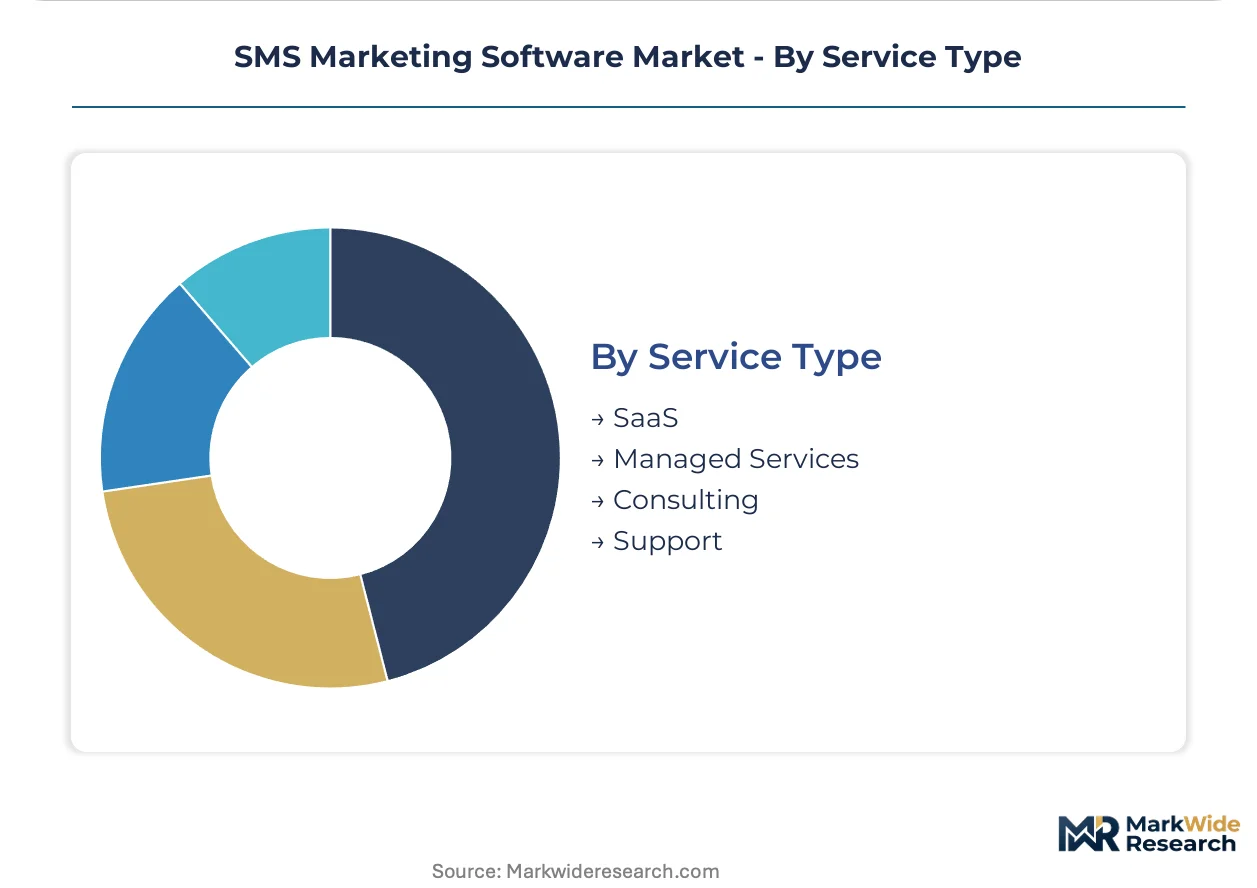
Service Type:
Pure-play SaaS margins attract capital while managed services capture complex implementation revenue.
- SaaS:Subscription pricing with bundled message allotments replaces per-SMS metering. Annual platform fees transfer volume risk to vendors and compress margins on high-throughput enterprise accounts.
- Managed Services:Outsourced campaign execution and deliverability engineering address talent scarcity in carrier relationship management. This tier commands premium pricing from mid-market operators lacking internal technical resources.
- Consulting:Strategic advisory on TCPA compliance and consent architecture elevates legal-technology integration. FCC enforcement actions filter subscale vendors from competitive consideration in United States procurement cycles.
- Support:Tiered response commitments and dedicated customer success managers reduce churn among high-value accounts. Professional services attach rates correlate with implementation complexity in legacy system environments.
SaaS dominates valuation multiples. Managed Services captures implementation friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's developer-centric SaaS ecosystem anchors global SMS marketing software innovation, with enterprise procurement patterns diverging sharply across regulatory jurisdictions and carrier infrastructure maturity.
United States
E-commerce retailers and hospitality chains drive cloud-native platform adoption as TCPA compliance costs reshape vendor selection criteria. The FCC enforces A2P 10DLC registration mandates that filter subscale providers lacking integrated legal-technology infrastructure. New York and Los Angeles metro areas concentrate demand from direct-to-consumer brands deploying cart-recovery automation.
Germany
Financial services and healthcare entities sustain on-premise deployment demand due to Bundesdatenschutzgesetz data residency requirements. The EU AI Act imposes transparency obligations on automated personalization systems, fragmenting product architectures from North American counterparts. Frankfurt's banking cluster maintains disproportionate hybrid infrastructure adoption.
United Kingdom
Retail and agency holding companies favor multi-tenant configurations for managing brand portfolios across CPG and quick-service restaurant accounts. GDPR consent management frameworks elevate compliance tooling costs for cross-border campaign orchestration. London's fintech corridor drives API-first messaging integration with payment workflows.
Brazil
Mobile commerce penetration outpaces SMS marketing saturation, creating first-mover opportunities for localized Portuguese-language automation. ANVISA and consumer protection regulations constrain pharmaceutical and healthcare messaging without explicit opt-in architecture. São Paulo's e-commerce ecosystem concentrates merchant adoption of Shopify-integrated conversational commerce.
India
TRAI regulations on commercial messaging and DND scrubbing elevate deliverability engineering requirements for high-volume campaigns. Mid-market retailers adopt cloud-based automation as digital payment adoption accelerates conversational purchase flows. Bangalore and Mumbai tech corridors host platform development centers serving Asia-Pacific expansion.
SMS Marketing Software Market Vendor Landscape
Global majors compete with regional champions across API infrastructure depth and vertical specialization depth, producing a tiered structure where scale-driven platforms absorb volume risk while niche specialists capture premium pricing. The vendor base separates into three strategic archetypes: developer-centric programmable messaging providers, retail-focused personalization engines, and e-commerce-integrated automation specialists. M&A activity concentrates on compliance technology tuck-ins and conversational AI capabilities, while geographic expansion targets underpenetrated LATAM markets.
Within the API-first infrastructure tier, Twilio and TextUs exemplify programmable messaging architectures that anchor enterprise workflow integration. Attentive occupies a position among AI-powered personalization specialists targeting retail and hospitality verticals with premium-tier feature differentiation. Postscript represents the e-commerce automation archetype through deep platform integration with merchant ecosystems. These three anchors demonstrate how vendor positioning stratifies across technical sophistication, vertical focus, and go-to-market channel density.
| Leading Market Players |
|---|
| SimpleTexting |
| Postscript |
| Twilio |
| TextUs |
| Salesmsg |
| ActiveCampaign |
| Attentive |
| Falkon SMS |
| Klaviyo |
| Others |
Supply Flow & Price Mechanics
Carrier surcharge volatility cascades from tier-one mobile network operators through platform pricing tiers, compressing margins for high-volume senders while forcing SaaS vendors to absorb cost shocks or transfer risk to mid-market subscribers.
Pricing Analysis
Input-cost pass-through from carrier networks shapes platform economics as per-message fees from Verizon, T-Mobile, and AT&T inflate operational expenditure. Three-tier pricing structure across premium, standard, and economy levels separates enterprise API throughput from mid-market automation bundles and entry-level broadcast tools. Pricing pressure stems from A2P 10DLC registration mandates elevating compliance infrastructure costs. Mid-market e-commerce operators exhibit highest price sensitivity due to thin margins on direct-to-consumer transactions, while enterprise retailers accept premium tiers for dedicated deliverability engineering.
Supply Chain Analysis
Dual-sourcing requirements from enterprise buyers mandate qualification across Twilio, MessageBird, and Sinch for carrier-grade SMPP connectivity, reducing single-platform dependency. Cloud infrastructure concentrates in the United States, Ireland, and Singapore for latency optimization and data residency compliance. Raw material dependencies center on compute instances, bandwidth provisioning, and AI training data for personalization engines. Single-source vulnerability concentrates in carrier relationship management expertise. Distribution runs through direct enterprise sales, agency holding company partnerships, and self-serve developer portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SMS marketing software market compounds steadily as conversational commerce penetration deepens retail and hospitality workflows, sustaining recurring revenue expansion across SaaS pricing tiers.
For Market Incumbents: Extend platform stickiness through native customer data platform architecture that unifies SMS, email, and paid media attribution. Deepen carrier relationship management capabilities to defend against emerging API-first challengers. Vertical integration into compliance technology modules addresses TCPA litigation exposure and filters subscale competitors from procurement consideration. For New Entrants and Emerging Players: Boutique hospitality operators in secondary US metro areas represent underserved buyer archetypes lacking dedicated conversational commerce infrastructure. White-space concentration sits with LATAM mid-market retailers in São Paulo and Mexico City seeking Portuguese-Spanish language automation. Partner with Shopify Plus agencies for embedded distribution rather than building direct sales capacity. For Investors and Strategic Acquirers: Consolidation pressure builds where TCPA compliance costs exceed subscale vendor capitalization, creating captive acquisition opportunities in legal-technology integration. Long-term viability favors platforms with multi-tenant architecture serving agency holding companies across brand portfolios. Watch carrier surcharge regime adjustments as inflection indicators for margin compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| Conversational AI Integration | Natural language processing enables interactive purchase flows within messaging threads, opening premium pricing tiers. |
| Compliance Technology Acquisition | TCPA litigation exposure elevates legal-technology integration as a competitive moat for enterprise procurement. |
| Geographic Expansion | Brazil and Mexico exhibit low SMS marketing saturation relative to mobile commerce penetration, creating first-mover positioning. |
| Platform Integration Partnership | Shopify-embedded workflows capture abandoned checkout sequences and compress merchant acquisition costs. |
| Attribution Modeling Convergence | Unified identity resolution across channels creates cross-sell opportunities for native customer data platform capabilities. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and integration specialists with secondary validation against SEC filings, hyperscaler capex disclosures, carrier surcharge regime documentation, and FCC enforcement action records. Bottom-up sizing of vendor-reported seat counts and message volumes triangulated against top-down addressable market estimates derived from e-commerce GMV and retail foot traffic proxies.
Segment-weighting approaches distributed growth assumptions across deployment model, organization size, vertical concentration, and regional adoption pattern throughout the forecast period. CAGRs emerged from cohort-based progression modeling of subscriber acquisition costs and lifetime value ratios. Industry-specific inputs included A2P 10DLC registration velocity, carrier fee schedule adjustments, and conversational commerce penetration curves by merchant tier.
Underlying measurement precision varies by segment; cloud-based deployment and e-commerce verticals carry tighter precision than hybrid configurations and nonprofit applications due to disclosed vendor metrics and transaction transparency. Forecasts reflect documented assumptions about regulatory enforcement intensity and carrier pricing behavior. Deviation in FCC TCPA litigation patterns or tier-one operator surcharge regimes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Content Moderation Software Market
Software & Services
Global Affiliate Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Semiconductor Fabrication Software Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Embedded Hypervisor Market
Software & Services
Legal Software Market
Software & Services
Human Identification Analysis Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
Global Product Information Management (PIM) Software Market
Software & Services
Computer Backup Software Market
Software & Services
Saas Based HRM Market
Software & Services
POS Software Market
Software & Services
APAC Workforce Management Software Market
Software & Services
Global Video Streaming Software Market
Software & Services
Bank Reconciliation Software Market