
 Life Sciences Software Market | 2026-2036
Life Sciences Software Market Size, Share, and Industry Trends Forecast 2026-2036
Life Sciences Software Market Analysis
Cloud infrastructure is consolidating around subscription models that displace perpetual-license on-premises deployments. Veeva Systems dominates cloud-native customer relationship management for life sciences with vertical-specific compliance layers. SAP Life Sciences anchors enterprise resource planning across large pharmaceutical manufacturers with validated manufacturing execution modules. Thermo Fisher Scientific extends instrument-to-software connectivity through laboratory information management systems that capture instrument data natively.
Life sciences software comprises regulated digital platforms designed for data capture, workflow orchestration, and compliance documentation in pharmaceutical, biotechnology, and clinical research environments. These systems enforce 21 CFR Part 11 audit trails, electronic signatures, and ALCOA+ data integrity principles while integrating with laboratory instruments and clinical site networks. Laboratory Information Management Systems and Clinical Trial Management Systems lead deployment value, reflecting mature validation requirements and site-network complexity that lock in replacement cycles. Cloud-Based and SaaS deployment models represent the fastest-expanding configuration, as multi-tenant architectures reduce qualification overhead for mid-tier biotechnology firms and contract research organizations.
FDA 21 CFR Part 11, EMA GCP inspections, and EU GDPR create overlapping compliance burdens that elevate software procurement standards and disqualify non-validated vendors. The FDA's draft guidance on computer software assurance shifts regulatory emphasis toward critical-thinking-based testing, altering vendor documentation obligations. Stakeholders must monitor evolving FDA digital health software precertification pilots and EMA DARWIN EU real-world evidence frameworks to anticipate data-integration requirements that reshape platform architecture decisions.
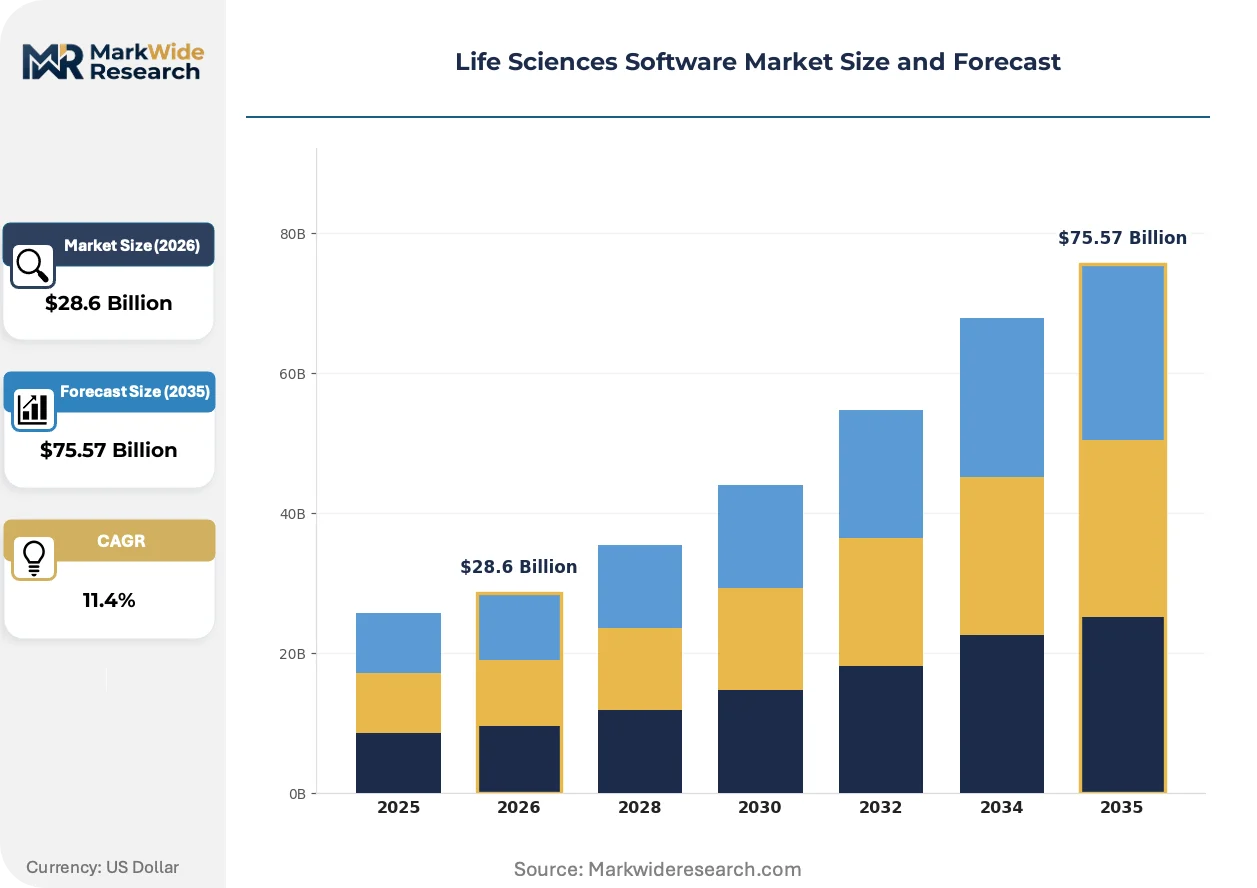
Market Dynamics
Cloud-native architectures are compressing validation cycles for clinical trial platforms while FDA computer software assurance guidance reduces documentation burdens for non-critical functions.
Growth Catalysts
- EMA Clinical Trials Regulation:Harmonized submission portals across EU member states accelerate multi-site study activation and expand addressable contract research organization demand.
- Real-world evidence frameworks:EMA DARWIN EU and FDA Sentinel initiatives integrate electronic health record streams, creating new data-capture software categories.
- Boston-San Francisco biotech corridor:Concentrated NIH funding flows and venture deployment sustain early-stage software procurement velocity.
Market Restraints
- Validation cost structure:IQ/OQ/PQ documentation for 21 CFR Part 11 compliance adds 40-60% implementation overhead versus non-regulated software.
- Specialized talent scarcity:Qualified validation engineers and CSV consultants concentrate in Cambridge, Basel, and Research Triangle Park, creating regional supply bottlenecks.
- Legacy system entrenchment:Perpetual-license on-premises deployments at top-20 pharmaceutical manufacturers lock out cloud migration through multi-year depreciation cycles.
Strategic Opportunities
- Decentralized clinical trials:Direct-to-patient data capture and telemedicine endpoints expand site-less study models, requiring new mobile-first platform architectures.
- AI-enabled protocol design:Machine learning for patient recruitment optimization and adaptive trial simulation creates premium software tiers.
- India contract research expansion:CDSCO streamlined approval pathways and cost arbitrage position Indian CROs for mid-tier software adoption acceleration.
Industry Challenges
- CSV talent pipeline:Computer system validation expertise gaps delay implementation timelines for mid-tier biotechnology firms without dedicated quality infrastructure.
- Multi-tenant qualification:Shared cloud infrastructure complicates vendor audit rights and data segregation proofs under FDA investigator scrutiny.
- Interoperability fragmentation:HL7 FHIR adoption variance across health systems impedes seamless electronic data capture integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Life Sciences Software Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Information Management Systems, Electronic Lab Notebooks, Bioinformatics Software, Clinical Trial Management Systems Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutions, Contract Research Organizations Application: Research & Development, Clinical Trials, Regulatory Compliance, Data Management |
| Companies Covered | SAP Life Sciences, Thermo Fisher Scientific, Veeva Systems, Microsoft Dynamics 365, Dassault Systèmes, IQVIA, Medidata Solutions, Salesforce Life Sciences Cloud, Oracle Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Life Sciences Software Market Emerging Trajectories
Artificial intelligence and federated data networks are restructuring how life sciences software captures, validates, and exchanges regulated information across distributed research environments.
Generative AI for clinical document authoring is rewriting regulatory submission preparation workflows. Contract medical writers and biotechnology sponsors deploy large language models for protocol deviation narratives and clinical study report generation. This capability compresses documentation timelines from weeks to days, though FDA skepticism toward AI-generated safety narratives constrains deployment velocity.
EU AI Act risk classification rules impose new conformity obligations on machine learning components embedded in diagnostic and trial management software. High-risk AI systems must demonstrate accuracy, robustness, and cybersecurity through notified body assessment. German and French health technology assessment bodies now require algorithmic transparency documentation alongside traditional clinical evidence packages.
Site payment unbundling from full-service contracts is altering CRO software procurement patterns. Sponsors increasingly license clinical trial management systems directly while outsourcing only monitoring and logistics functions. This bifurcation concentrates in North American mid-phase studies where sponsor IT maturity supports direct platform ownership.
Life Sciences Software Market Segmentation
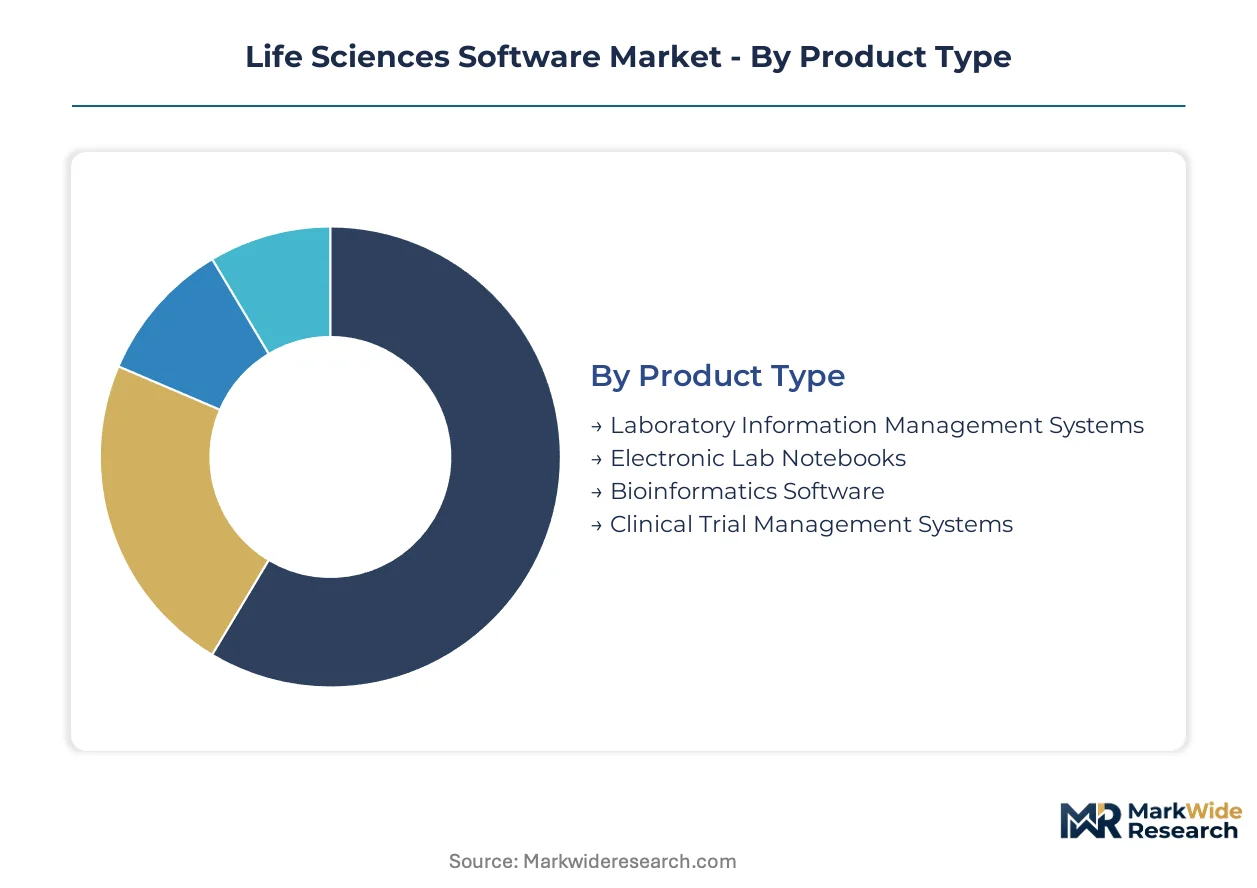
Life sciences software procurement diverges sharply by organizational scale and regulatory burden, with enterprise pharmaceutical manufacturers prioritizing validated systems while emerging biotechnology firms favor agile deployment models. Understanding these fault lines clarifies where platform consolidation versus fragmentation will concentrate across the forecast horizon.
Product Type:
Supply concentration in this category clusters around platforms with the deepest validation moats and longest replacement cycles, creating asymmetric competitive dynamics between incumbent and challenger vendors.
- Clinical Trial Management Systems:These platforms orchestrate site activation, patient recruitment, and regulatory submission workflows across multi-country study networks. Demand concentrates at top-20 pharmaceutical manufacturers in Basel and New Jersey, driven by EMA Clinical Trials Regulation harmonization requirements and FDA inspection readiness protocols that lock in multi-year contracts.
- Laboratory Information Management Systems:Instrument-native data capture systems enforce ALCOA+ integrity standards while integrating chromatography, mass spectrometry, and sequencing hardware. Contract research organizations in India and Singapore represent the fastest-expanding customer base, reflecting CDSCO streamlined approval pathways and cost arbitrage in analytical services outsourcing.
- Electronic Lab Notebooks:Cloud-native documentation platforms displace paper batch records in quality control laboratories.
- Bioinformatics Software:Genomic analysis pipelines and variant interpretation tools support precision medicine target identification.
Today's leader: Clinical Trial Management Systems. Tomorrow's challenger: Laboratory Information Management Systems.
Deployment:
Cost tier stratification in this category separates enterprise buyers absorbing qualification overhead from mid-market adopters prioritizing speed-to-validation over architectural control.
- SaaS:Multi-tenant subscription platforms reduce IQ/OQ/PQ documentation burden through vendor-managed infrastructure qualification. Biotechnology clusters in Boston and San Francisco drive procurement velocity, with NIH funding flows sustaining early-stage firm software budgets despite capital market volatility.
- Cloud-Based:Dedicated tenant architectures balance customization flexibility with reduced data center capital expenditure. European mid-tier pharmaceutical manufacturers favor this model under EU GDPR data residency requirements and EMA inspection expectations for physical infrastructure audit rights.
- On-Premises:Perpetual-license deployments persist at manufacturers with validated manufacturing execution system integrations.
- Hybrid:Split architectures segregate critical GxP functions on-premises while pushing analytics to cloud environments.
SaaS deployments are climbing the fastest among emerging biotechnology firms, though Cloud-Based configurations retain preference where data sovereignty constraints apply.
End User:
Customer type segmentation in this category maps directly to procurement sophistication, with dedicated quality infrastructure separating enterprise buyers from organizations dependent on vendor-managed validation services.
- Pharmaceutical Companies:Integrated quality management systems spanning manufacturing, clinical, and pharmacovigilance functions. Top-tier manufacturers in Germany, Switzerland, and the United States anchor demand, with FDA 21 CFR Part 11 and EU GMP Annex 11 driving replacement cycles that favor incumbent vendors with established inspection track records.
- Contract Research Organizations:Multi-sponsor platform deployments requiring rapid study startup and cross-client data segregation. Indian CROs in Hyderabad and Mumbai represent the steepest expansion trajectory, supported by CDSCO regulatory harmonization and Western sponsor cost reduction mandates.
- Biotechnology Firms:Agile platforms prioritizing speed over enterprise feature depth, concentrated in Cambridge and South San Francisco.
- Academic Research Institutions:Grant-funded procurement with limited validation requirements, concentrated at NIH-funded centers.
Pharmaceutical Companies dominate current procurement value. Contract Research Organizations are gaining share fastest as sponsor direct-licensing models bifurcate traditional full-service contracts.
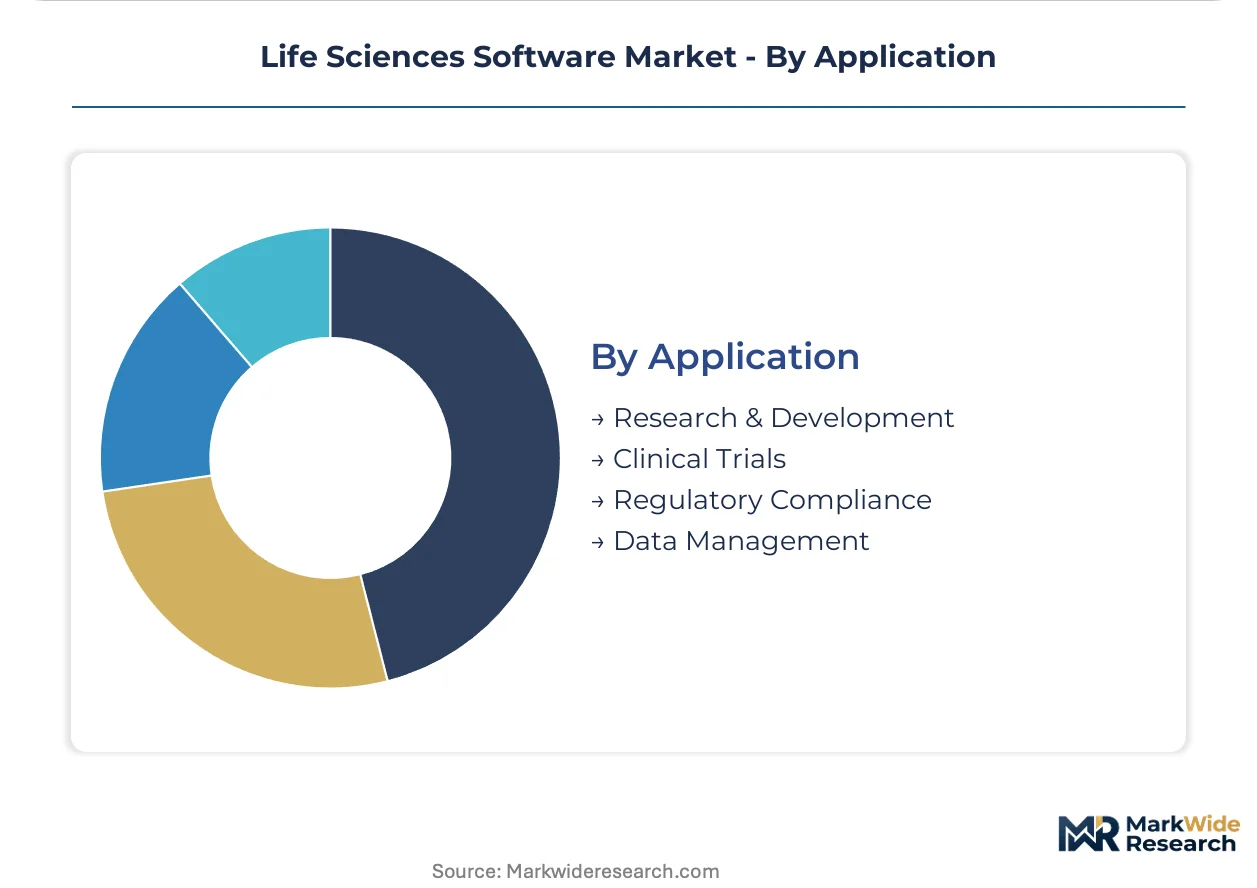
Application:
Maturity gradients in this category separate functionally saturated segments from emerging categories where regulatory frameworks remain in flux and vendor positioning is unresolved.
- Clinical Trials:Patient-facing data capture, site monitoring, and regulatory submission management across decentralized and traditional study models. Demand concentrates in the United States and Western Europe, with FDA computer software assurance guidance and EMA DARWIN EU real-world evidence frameworks reshaping platform architecture requirements.
- Regulatory Compliance:Submission authoring, health authority correspondence, and post-approval change management systems. Japanese pharmaceutical manufacturers expanding into European markets drive specialized procurement, with PMDA-EMA mutual recognition agreement implementation creating dual-validation requirements.
- Research & Development:Discovery-stage informatics and preclinical data management with lighter validation burdens.
- Data Management:Centralized statistical programming and clinical data repository functions.
Clinical Trials applications command the deepest vendor entrenchment. Regulatory Compliance represents the most open competitive terrain as AI-enabled submission tools disrupt incumbent document management workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and San Francisco anchor global procurement velocity for life sciences software, with NIH funding flows and biotech venture deployment sustaining platform adoption despite capital market volatility. Regulatory harmonization across FDA, EMA, and CDSCO jurisdictions reshapes vendor qualification requirements. Cloud infrastructure investments concentrate where validation expertise clusters.
United States
FDA 21 CFR Part 11 enforcement and computer software assurance guidance drive enterprise pharmaceutical procurement in New Jersey and North Carolina. The NIH's $47 billion annual budget sustains early-stage biotechnology software spending in Cambridge and South San Francisco. Veeva Systems and IQVIA anchor cloud-native deployments across top-20 manufacturers.
Germany
EMA Clinical Trials Regulation harmonization and EU GDPR data residency requirements favor dedicated cloud tenant architectures. Baden-Württemberg and Bavaria host SAP Life Sciences validated manufacturing execution modules across chemical-pharma conglomerates. German HTA bodies now require algorithmic transparency documentation for AI-enabled diagnostic software.
Switzerland
Swissmedic inspection protocols and dual EMA-FDA submission pathways elevate validation standards for Basel-headquartered pharmaceutical manufacturers. Roche and Novartis procurement patterns lock in multi-year contracts with incumbent vendors possessing established inspection track records. The Lake Geneva corridor concentrates quality infrastructure investment.
India
CDSCO streamlined approval pathways and Western sponsor cost reduction mandates accelerate contract research organization software adoption in Hyderabad and Mumbai. Indian CROs represent the fastest-expanding customer base for laboratory information management systems, reflecting analytical services outsourcing migration. PLI scheme incentives support domestic biotechnology manufacturing digitization.
United Kingdom
MHRA post-Brexit regulatory autonomy and alignment with FDA mutual recognition agreements create dual-validation complexity for London and Cambridge biotech clusters. NHS electronic health record integration requirements reshape clinical data capture platform specifications. UK-based AI-enabled protocol design vendors target North American sponsor procurement.
Life Sciences Software Market Vendor Landscape
Strategic partnerships dominate the current landscape as incumbent vendors defend position against cloud-native challengers. The vendor base concentrates around three tiers: enterprise resource planning anchors with validated manufacturing modules, vertical-specific cloud platforms with compliance layers, and instrument-native data capture systems. Two archetypes prevail—horizontal software giants extending life sciences verticals and purpose-built specialists with regulatory moats. Competitive moves center on M&A for data network expansion and technology licensing for AI-enabled functionality.
Within the enterprise software tier, SAP Life Sciences and Oracle Life Sciences exemplify horizontal platform extension into validated pharmaceutical workflows. Veeva Systems occupies a distinct position as a cloud-native vertical specialist with FDA inspection-ready compliance architectures. Thermo Fisher Scientific anchors the instrument-to-software connectivity segment, representing the laboratory hardware vendor archetype that bundles data capture platforms with analytical equipment procurement. IQVIA and Medidata Solutions sit within the clinical research services-to-software hybrid model, leveraging CRO relationships to drive platform adoption.
| Leading Market Players |
|---|
| SAP Life Sciences |
| Thermo Fisher Scientific |
| Veeva Systems |
| Microsoft Dynamics 365 |
| Dassault Systèmes |
| IQVIA |
| Medidata Solutions |
| Salesforce Life Sciences Cloud |
| Oracle Life Sciences |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure cost indices cascade through life sciences software procurement tiers, compressing margins for multi-tenant SaaS providers while elevating premiums for validated single-tenant deployments. Tier-one pharmaceutical manufacturers absorb qualification overhead through enterprise licensing, whereas mid-tier biotechnology firms gravitate toward subscription models that externalize infrastructure capital expenditure.
Pricing Analysis
Input-cost pass-through from hyperscaler compute and storage rates reshapes vendor margin structures across deployment tiers. Three-tier pricing structure across premium, standard, and economy levels segments by validation depth and audit trail granularity, with FDA 21 CFR Part 11 certification commanding substantial premiums. Pricing pressure stems from Indian CRO procurement velocity and Western sponsor cost reduction mandates. Contract research organizations exhibit highest price sensitivity, while Basel and New Jersey pharmaceutical manufacturers prioritize inspection readiness over unit economics.
Supply Chain Analysis
Direct-to-sponsor licensing channels handle enterprise pharmaceutical demand, while value-added reseller networks serve mid-market biotechnology clusters. Development and validation labor concentrates in the United States, Switzerland, and India, with Cambridge, Basel, and Hyderabad anchoring talent pools. Platform architecture draws from open-source frameworks, proprietary compliance engines, and instrument-native data protocols. Single-source vulnerability permeates the validation engineer tier, where qualified CSV consultants cluster regionally. Distribution runs through vendor-direct sales for top-20 manufacturers and partner-enabled channels for emerging firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Life sciences software functions as a regulatory compounder, where FDA 21 CFR Part 11 enforcement and EMA Clinical Trials Regulation harmonization create sustained demand for validated platforms.
For Market Incumbents: Anticipate cloud-native challengers exploiting multi-tenant qualification shortcuts to undercut enterprise pricing. Defensive consolidation through acquisition of specialized validation service providers in Cambridge and Basel reinforces inspection-ready moats. Investment in AI-enabled compliance documentation addresses FDA computer software assurance guidance shifts. For New Entrants and Emerging Players: The mid-tier pricing gap between Veeva Systems premiums and open-source alternatives creates white-space for modular, validation-as-a-service platforms. Indian CRO procurement represents the most penetrable segment, supported by CDSCO regulatory harmonization and Western sponsor cost arbitrage. A channel partnership strategy with regional system integrators accelerates site activation velocity without direct sales infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native vertical specialists possessing FDA inspection track records and EU GDPR data residency architectures. Five-to-ten year viability hinges on regulatory moat durability rather than feature velocity. Acquisition target archetype: validated manufacturing execution module providers with SAP or Oracle integration depth. The signal to watch is EMA DARWIN EU real-world evidence framework adoption rates as platform architecture inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Validated LIMS-CTMS interoperability reduces sponsor audit burden under FDA 21 CFR Part 11. |
| Acquisition of Specialist Firm | CSV consultancy targets in Cambridge and Basel compress implementation timelines for enterprise buyers. |
| Product Launch | AI-enabled protocol design tools address EMA DARWIN EU real-world evidence data capture requirements. |
| Strategic Partnership | Instrument vendor alliances with Thermo Fisher Scientific secure laboratory hardware connectivity moats. |
| Geographic Expansion | Hyderabad and Mumbai CRO penetration captures CDSCO streamlined approval pathway demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads, clinical operations executives, CSV consultants, and IT procurement officers at pharmaceutical and biotechnology firms. Secondary validation drew from FDA 510(k) filings, EMA submission databases, ClinicalTrials.gov protocol records, and SEC 10-K software revenue disclosures. Bottom-up deployment model sizing and top-down enterprise IT spending estimates were triangulated against vendor-reported subscription metrics.
Segment-weighting approaches distributed value across SaaS, cloud-based, on-premises, and hybrid deployment configurations, further stratified by organization size, vertical application, and regional regulatory cluster. CAGR derivation reflected validated system replacement cycles, NIH funding flow trajectories, and CRO outsourcing penetration curves. Forecast inputs incorporated FDA computer software assurance guidance implementation pace and EMA Clinical Trials Regulation portal adoption rates.
Caveats apply where FDA digital health precertification pilots or EU AI Act risk reclassifications could materially shift the outlook. Forecasts reflect assumptions regarding regulatory harmonization continuity and cloud infrastructure cost stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Harbor and Marina Management Software Market
Software & Services
Global Mobile Application Testing Solution Market
Software & Services
Pharmacy Billing Software Market
Software & Services
Staffing Software Market
Software & Services
Bank Reconciliation Software Market
Software & Services
Europe Database Management Software Market
Software & Services
Family Office Software Solutions Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Software Construction Components Market
Software & Services
Global Invoice Automation Software Market
Software & Services
Global Data Discovery Software Market
Software & Services
Global Nosql Software Market
Software & Services
Construction Simulation Software Market
Software & Services
Home Fitness App Market
Software & Services
Enterprise Software Market
Software & Services
Advanced Process Control Software Market