
 Analytical Ultracentrifuge Systems Market | 2026-2036
Analytical Ultracentrifuge Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Analytical Ultracentrifuge Systems Market Outlook
German precision engineering clusters is consolidating as a dominant supply base for high-performance rotor assemblies and optical detection modules. Thermo Fisher Scientific leverages its installed base of laboratory instrumentation to cross-sell analytical ultracentrifuge platforms into pharmaceutical quality control workflows. Danaher anchors its position through diagnostic-centric R&D intensity across its operating companies. Eppendorf AG specializes in compact benchtop configurations that occupy space-constrained academic laboratories.
An analytical ultracentrifuge system measures molecular weight, size, and shape distributions by monitoring sedimentation behavior under centrifugal forces exceeding 150,000 × g, employing interference optics or absorbance detection to record concentration boundaries in real time. The instrument serves biopharmaceutical development, enabling formulation stability assessment and aggregation profiling of monoclonal antibodies. Sedimentation velocity technology leads in routine adoption due to its throughput advantage for protein heterogeneity screening, while multiwavelength detection represents the fastest-expanding segment as users demand simultaneous multi-analyte resolution. Academic institutions constitute the most mature end-user pool, whereas biotechnology companies concentrate margin capture through high-service contracts and application-specific method development.
The FDA enforces current Good Manufacturing Practice requirements that drive pharmaceutical firms toward qualified analytical ultracentrifuge platforms with validated software and traceable calibration protocols. ISO 17025 accreditation standards shape procurement criteria for contract research laboratories seeking defensible sedimentation data. The European Medicines Agency's quality guidelines on biosimilar analytical comparability reinforce demand for sedimentation equilibrium capabilities. Stakeholders must monitor evolving pharmacopeial monographs that could mandate specific optical detection modalities for biologics release testing.
Market Dynamics
Biopharmaceutical pipeline expansion is compressing analytical timelines and forcing contract research organizations to triple their sedimentation capacity within eighteen-month windows.
Growth Catalysts
- Biosimilar comparability mandates:The FDA's evolving guidance on analytical characterization for biosimilar approval creates mandatory demand for qualified sedimentation equilibrium protocols in quality control laboratories.
- Monoclonal antibody aggregation screening:Formulation stability requirements for biologics now incorporate sedimentation velocity as a standard release test, embedding these instruments into GMP workflows.
- German precision manufacturing clusters:Concentrated rotor assembly and optical module production near Stuttgart enables rapid equipment customization for specialized academic and industrial applications.
Market Restraints
- High-purity sapphire window supply:Optical detection modules depend on synthetic sapphire manufactured at only three qualified facilities worldwide, creating input concentration risk.
- Qualified technician scarcity:Sedimentation data interpretation requires specialized training in hydrodynamic modeling that university curricula rarely cover.
- Benchtop centrifuge substitution:Preparative ultracentrifuge systems from Eppendorf and Beckman Coulter capture routine pelleting workflows that analytical systems once addressed.
Strategic Opportunities
- India biologics manufacturing expansion:CDSCO's accelerated approval pathways for biosimilars is attracting multinational investment in analytical infrastructure at Hyderabad and Bengaluru facilities.
- Multiwavelength detection convergence:Integration of UV-Vis with interference optics enables simultaneous quantification of co-sedimenting species without fractionation.
- Service contract unbundling:Equipment vendors can disaggregate hardware sales from method development and validation services, capturing recurring revenue from mid-tier biotechnology firms.
Industry Challenges
- ISO 17025 accreditation timelines:Contract laboratories face eighteen-month validation cycles for sedimentation methods, delaying revenue recognition on new analytical service lines.
- Legacy LIMS integration:Pharmaceutical quality systems built around chromatography data structures require expensive middleware development to ingest sedimentation boundary files.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analytical Ultracentrifuge Systems Market |
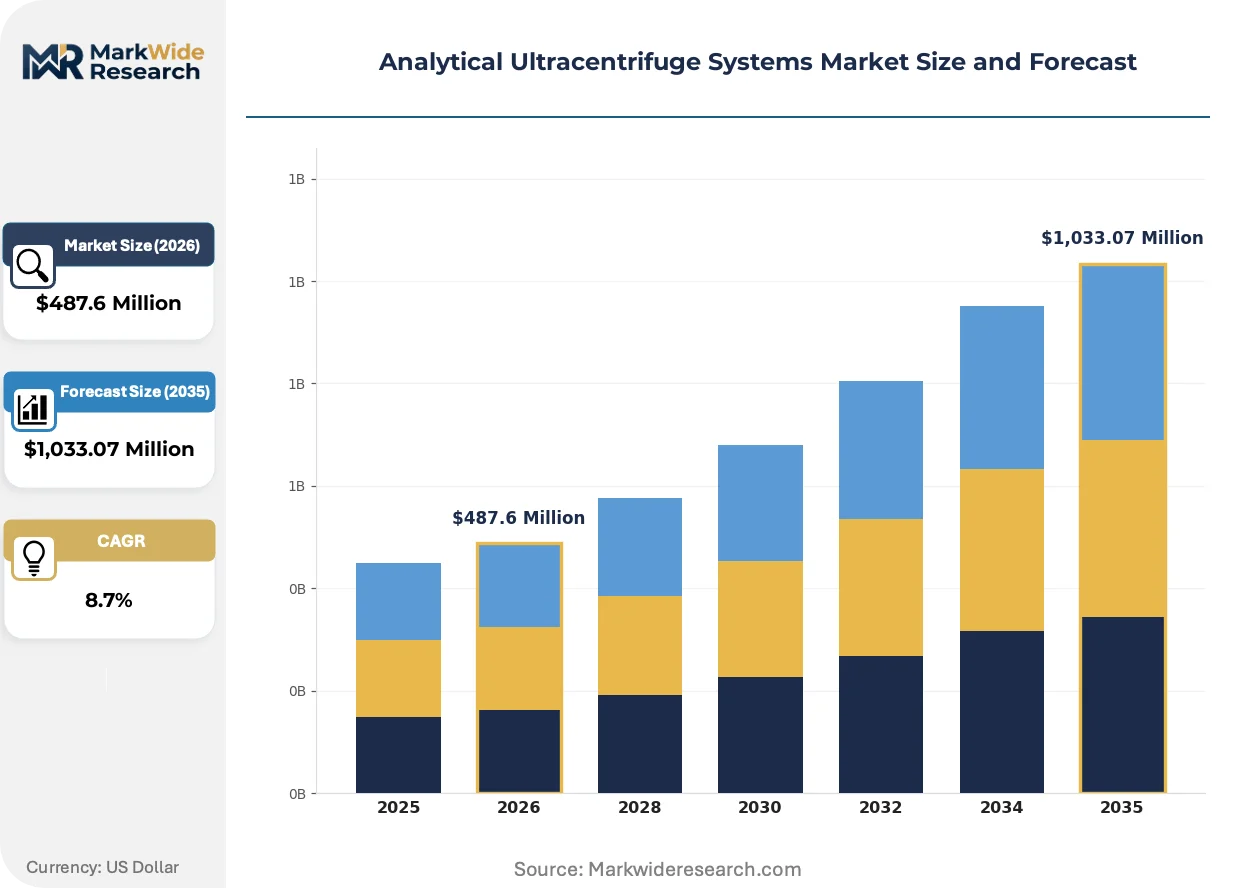
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Ultracentrifuges, Analytical Ultracentrifuges, High-Performance Ultracentrifuges, Ultracentrifuge Accessories End User: Academic Institutions, Biotechnology Companies, Pharmaceutical Firms, Research Laboratories Application: Protein Analysis, Nucleic Acid Purification, Nanoparticle Characterization, Cell Biology Studies Technology: Optical Detection, Sedimentation Velocity, Sedimentation Equilibrium, Multiwavelength Detection |
| Companies Covered | Spin Analytical, Hettich Instruments, Thermo Fisher Scientific, HighRes Biosolutions, Helmer Scientific, Danaher, NuAire, Hanil, Eppendorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analytical Ultracentrifuge Systems Market Strategic Shifts
Real-time sedimentation monitoring is displacing endpoint analysis, compressing experimental duration from days to hours while expanding the addressable application set.
Multiwavelength absorbance detection is decentralizing protein characterization workflows by enabling simultaneous quantification of nucleic acid contaminants, unlabeled aggregates, and formulation excipients without secondary assays. Academic core facilities at MIT, ETH Zurich, and Tsinghua University are deploying these systems for shared-user screening programs. The technology is compressing demand for separate analytical ultracentrifuge and UV-Vis spectrophotometer capital allocations.
The EMA's revised biosimilar quality guidelines now explicitly reference sedimentation equilibrium for higher-order structure confirmation, forcing European manufacturers to qualify these methods for regulatory submissions. This policy shift is accelerating equipment procurement at Milan, Copenhagen, and Basel manufacturing sites. Analytical service providers are responding by building dedicated sedimentation capacity rather than outsourcing to academic collaborators.
Biotechnology procurement teams are consolidating vendor relationships through multi-year platform leases that bundle hardware, software, and application support. This model displaces traditional capital purchase cycles and transfers calibration and maintenance risk to OEM service organizations. The shift is most pronounced among Series C-funded biologics developers in Boston and San Diego seeking predictable operating expenditure structures.
Analytical Ultracentrifuge Systems Market Segmentation
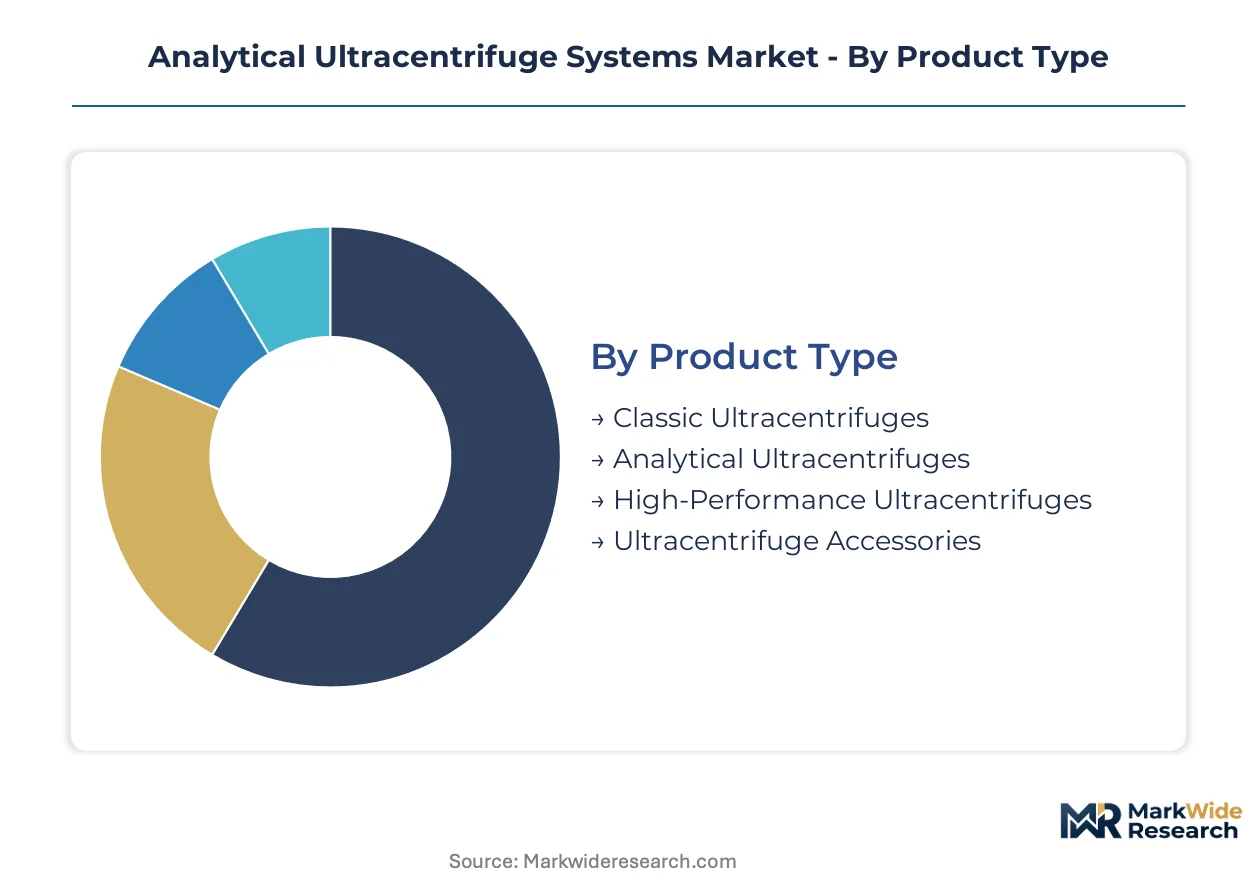
Analytical ultracentrifuge systems segment across four dimensions that reflect divergent technical requirements and procurement economics. Product architecture determines capital intensity and service attachment rates. End-user concentration shapes pricing power and contract structures across the value chain.
Product Type:
Volume-driven configurations dominate unit shipments, while premium platforms capture margin through optical sophistication and regulatory qualification support.
- Classic Ultracentrifuges:These systems employ standard interference optics and fixed-wavelength absorbance detection for routine molecular weight determination. Pharmaceutical quality control laboratories in Germany specify these platforms for biosimilar comparability protocols, driven by EMA guidelines on higher-order structure confirmation. Today's leader: Classic Ultracentrifuges. Tomorrow's challenger: High-Performance Ultracentrifuges.
- Analytical Ultracentrifuges:Purpose-built instruments integrate real-time boundary detection with validated software packages for GMP environments. Biotechnology companies in Boston and San Diego lease these systems through multi-year platform contracts to convert capital expenditure into predictable operating costs.
- High-Performance Ultracentrifuges:Configurations exceeding 150,000 × g with multiwavelength detection capabilities serve advanced aggregation profiling and formulation stability assessment. Academic core facilities at MIT and ETH Zurich deploy these for shared-user screening programs.
- Ultracentrifuge Accessories:Rotor assemblies, sapphire windows, and calibration standards generate recurring revenue streams. German precision manufacturing clusters near Stuttgart concentrate production of these components.
Hardware sales concentrate in classic platforms. Service and consumable attachment rates climb fastest on high-performance configurations.
End User:
Customer type stratifies the market between price-sensitive academic procurement and value-driven pharmaceutical qualification requirements.
- Academic Institutions:Universities and research institutes constitute the most mature installed base, prioritizing compact benchtop configurations for space-constrained laboratories. Funding cycles and shared-user models compress capital budgets and extend replacement timelines.
- Biotechnology Companies:Series C-funded biologics developers concentrate margin capture through high-service contracts and application-specific method development. These firms demand sedimentation velocity protocols for monoclonal antibody aggregation screening.
- Pharmaceutical Firms:GMP-compliant workflows drive procurement of qualified platforms with traceable calibration protocols and validated software. FDA current Good Manufacturing Practice requirements embed these instruments into release testing infrastructure.
- Research Laboratories:Contract research organizations scale sedimentation capacity to address compressed analytical timelines from biopharmaceutical pipeline expansion.
Biotechnology companies are expanding most quickly. Academic institutions retain the largest installed base.
Application:
Protein-focused workflows generate the majority of current demand, while nanoparticle applications represent the steepest expansion trajectory.
- Protein Analysis:Sedimentation velocity technology enables heterogeneity screening and aggregation profiling for biologics formulation development. Monoclonal antibody manufacturers incorporate these methods as standard release tests.
- Nucleic Acid Purification:Preparative workflows for plasmid DNA and viral vector characterization employ ultracentrifuge density gradients. Gene therapy developers specify these protocols for process analytical technology implementation.
- Nanoparticle Characterization:Lipid nanoparticle and exosome analysis requires sedimentation equilibrium for size distribution determination. Vaccine and drug delivery applications are accelerating equipment procurement.
- Cell Biology Studies:Subcellular fractionation and organelle isolation workflows utilize preparative ultracentrifuge systems. Academic cell biology departments maintain steady replacement demand.
Protein analysis commands current revenue share. Nanoparticle characterization is gaining share fastest.
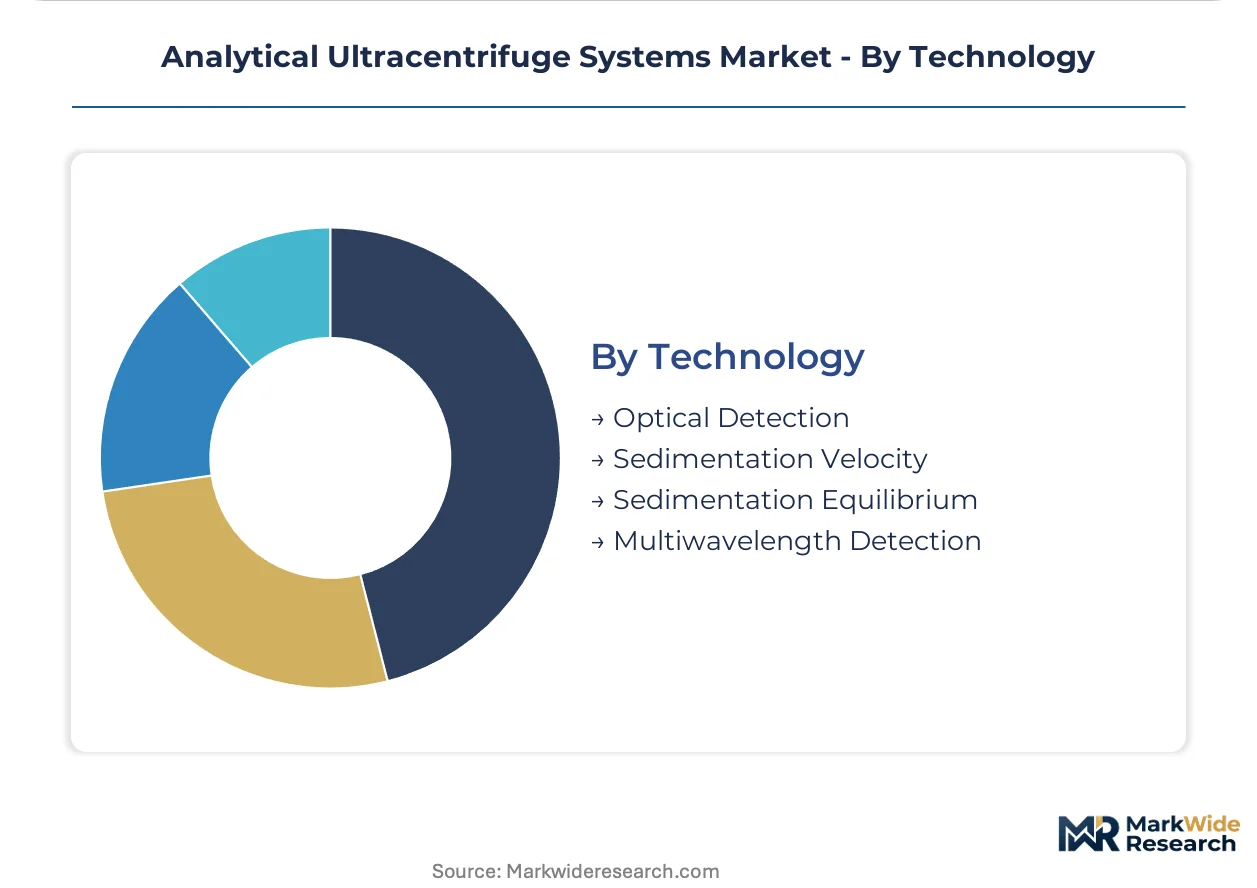
Technology:
Detection modality determines throughput, analyte resolution, and regulatory defensibility in quality control environments.
- Optical Detection:Interference optics and absorbance systems form the foundational measurement approach for concentration boundary monitoring. These modules depend on synthetic sapphire windows manufactured at concentrated supply facilities.
- Sedimentation Velocity:This technology leads in routine adoption due to throughput advantages for protein heterogeneity screening. Contract research organizations triple capacity in eighteen-month windows to meet biopharmaceutical demand.
- Sedimentation Equilibrium:Thermodynamic equilibrium methods provide absolute molecular weight determination for biosimilar comparability testing. EMA quality guidelines explicitly reference this capability for higher-order structure confirmation.
- Multiwavelength Detection:Integration of UV-Vis with interference optics enables simultaneous quantification of co-sedimenting species without fractionation. These systems decentralize protein characterization workflows by eliminating secondary assays.
Sedimentation velocity anchors current volume. Multiwavelength detection is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing analytical ultracentrifuge procurement toward jurisdictions with streamlined biosimilar approval pathways and concentrated precision manufacturing ecosystems. Cost-of-compliance gaps between established and emerging biopharmaceutical hubs are accelerating equipment migration patterns.
United States
FDA current Good Manufacturing Practice requirements drive pharmaceutical quality control laboratories toward qualified platforms with validated software and traceable calibration protocols. The agency's evolving guidance on biosimilar comparability testing embeds sedimentation equilibrium methods into release testing infrastructure. Boston and San Diego biotechnology clusters concentrate Series C-funded biologics developers leasing multi-year platform contracts to convert capital expenditure into predictable operating costs.
Germany
EMA quality guidelines on biosimilar analytical comparability reinforce mandatory demand for sedimentation equilibrium capabilities at Milan, Copenhagen, and Basel manufacturing sites. German precision engineering clusters near Stuttgart concentrate production of high-performance rotor assemblies and optical detection modules, enabling rapid equipment customization. Contract research organizations across Baden-Württemberg and Bavaria triple sedimentation capacity within eighteen-month windows to address compressed analytical timelines.
India
CDSCO accelerated approval pathways for biosimilars attract multinational investment in analytical infrastructure at Hyderabad and Bengaluru facilities. The country's national pharmaceutical regulator harmonizes quality standards with international benchmarks, reducing validation overhead for imported equipment. Contract development and manufacturing organizations in Telangana and Karnataka expand sedimentation service capacity to serve export-oriented biologics manufacturing.
China
NMPA biologics registration reforms compress analytical method qualification timelines for domestic and multinational manufacturers. National Medical Products Administration guidelines on monoclonal antibody quality control explicitly reference aggregation screening protocols. Yangtze River Delta biopharmaceutical manufacturing zones in Shanghai and Suzhou deploy analytical ultracentrifuge systems for formulation stability assessment of domestic biosimilar pipelines.
Switzerland
Swissmedic biosimilar approval frameworks emphasize higher-order structure confirmation through orthogonal analytical methods including sedimentation equilibrium. The regulatory agency's quality guidelines align with EMA standards, facilitating equipment qualification protocols for export-oriented manufacturers. Basel pharmaceutical manufacturing sites and Zurich academic core facilities maintain concentrated demand for multiwavelength detection capabilities.
Analytical Ultracentrifuge Systems Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue compact benchtop configurations for space-constrained academic laboratories. The vendor base stratifies across three tiers: diversified laboratory instrumentation conglomerates, specialized centrifuge manufacturers, and precision component suppliers. Strategic archetypes include cross-selling platform integrators, diagnostic-centric R&D intensity players, and compact-system specialists. Dominant competitive moves center on multi-year platform lease bundling and service contract unbundling to capture recurring revenue streams.
Among diversified laboratory instrumentation providers, Thermo Fisher Scientific and Danaher represent cross-selling platform integrators leveraging installed bases to embed analytical ultracentrifuge systems into pharmaceutical quality control workflows. Eppendorf AG exemplifies the compact-system specialist archetype, occupying a position focused on space-constrained academic and biotechnology laboratory environments. Spin Analytical anchors the specialized precision manufacturer tier, sitting within a competitive position emphasizing rotor assembly and optical detection module customization.
| Leading Market Players |
|---|
| Spin Analytical |
| Hettich Instruments |
| Thermo Fisher Scientific |
| HighRes Biosolutions |
| Helmer Scientific |
| Danaher |
| NuAire |
| Hanil |
| Eppendorf AG |
| Others |
Value Chain & Pricing Dynamics
EMA-mandated sedimentation equilibrium protocols for biosimilar comparability are forcing pharmaceutical quality control laboratories toward GMP-qualified platforms with validated software and traceable calibration, compressing procurement flexibility and elevating supplier pricing power for regulatory-compliant configurations.
Pricing Analysis
Distributor margins on analytical ultracentrifuge systems compress at the high-performance tier where direct-to-OEM channels dominate. Three-tier pricing structure across premium, standard, and economy levels separates multiwavelength detection platforms from classic interference optics and entry-level academic configurations. Pricing pressure stems from biotechnology procurement teams consolidating vendor relationships through multi-year platform leases. Academic institutions exhibit highest price sensitivity; pharmaceutical quality control laboratories demonstrate lowest sensitivity due to regulatory qualification requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Boston and San Diego biotechnology clusters, while authorized distributors serve mid-tier academic and contract research markets. Manufacturing concentrates in Germany for rotor assemblies and optical detection modules, with final system integration distributed across United States and Swiss facilities. Synthetic sapphire windows for optical modules draw from concentrated supply facilities creating single-source vulnerability. Distribution runs through region-specific service organizations that bundle calibration and maintenance protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
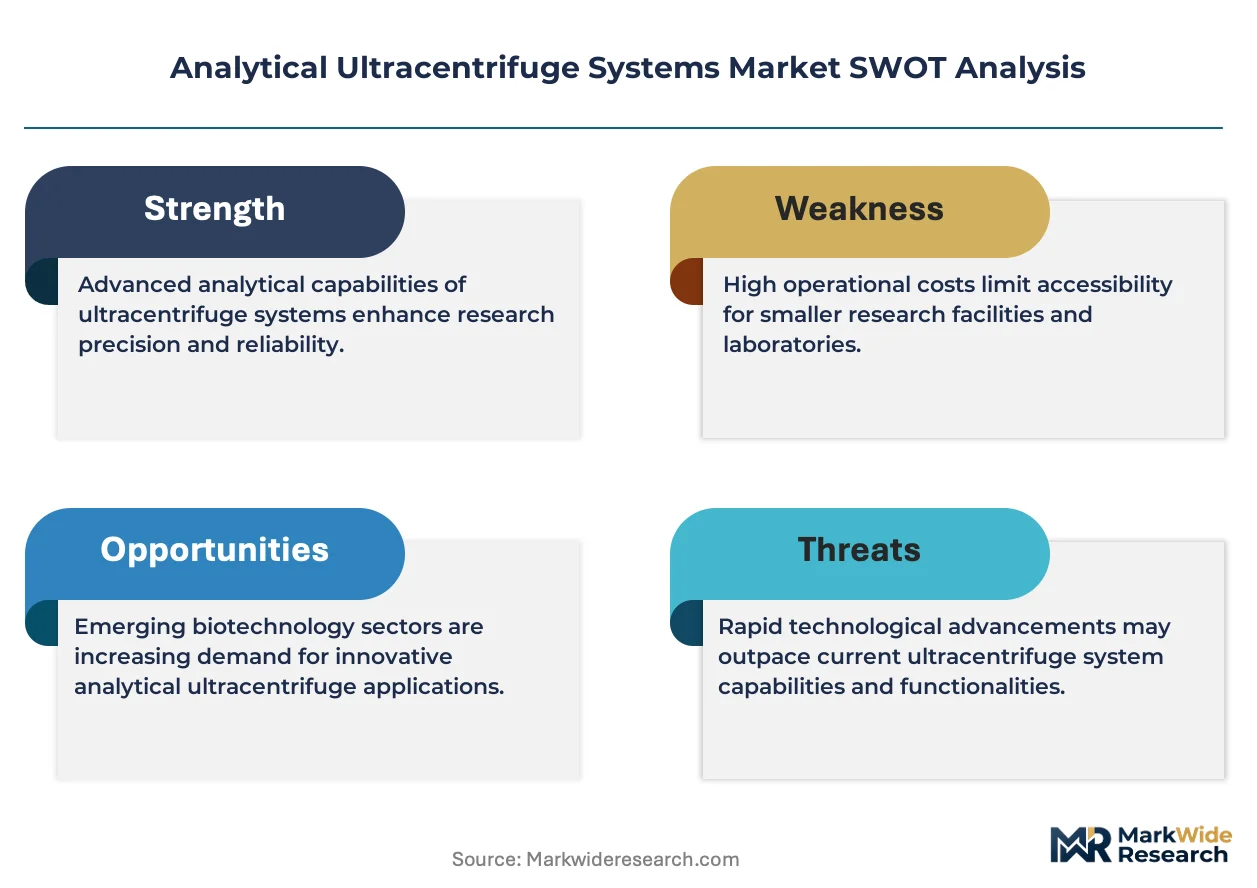
This market reads as a late-cycle quality story where EMA and FDA biosimilar guidelines are elevating demand toward GMP-qualified platforms with validated sedimentation equilibrium capabilities.
For Market Incumbents: Lock in pharmaceutical quality control relationships through multi-year platform leases that bundle hardware, software, and regulatory qualification support. Deepen captive supply of synthetic sapphire windows to neutralize single-source input risk. Defend against benchtop centrifuge substitution by embedding analytical ultracentrifuge protocols into FDA-mandated release testing workflows. For New Entrants and Emerging Players: Launch via compact benchtop configurations targeting space-constrained academic core facilities at MIT, ETH Zurich, and Tsinghua University. Target India biologics manufacturing expansion at Hyderabad and Bengaluru facilities where CDSCO accelerated approval pathways are attracting multinational analytical infrastructure investment. Penetrate through application-specific method development services unbundled from hardware sales. For Investors and Strategic Acquirers: Asymmetric upside sits with precision component suppliers controlling synthetic sapphire window and high-performance rotor assembly production. Five-to-ten year viability favors vendors with installed base leverage for cross-selling analytical ultracentrifuge platforms into existing pharmaceutical quality control workflows. Monitor ISO 17025 accreditation timeline compression as inflection signal for contract research organization sedimentation capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Multiwavelength Detection Integration | Enables simultaneous quantification of co-sedimenting species without fractionation at MIT and ETH Zurich core facilities. |
| Service Contract Unbundling | Captures recurring revenue from mid-tier biotechnology firms through disaggregated method development and validation offerings. |
| German Precision Manufacturing Expansion | Concentrates rotor assembly production near Stuttgart for rapid equipment customization serving EMA-mandated protocols. |
| India Analytical Infrastructure Buildout | Addresses CDSCO accelerated biosimilar approval pathways at Hyderabad and Bengaluru manufacturing zones. |
| Real-Time Sedimentation Monitoring Deployment | Compresses experimental duration from days to hours while expanding addressable applications beyond protein analysis. |
Study Parameters
Direct dialogue with pharmaceutical quality control directors, biotechnology procurement leads, academic core facility managers, and contract research organization laboratory directors grounded the qualitative foundation. Secondary validation drew from FDA guidance documents on biosimilar comparability, EMA quality guidelines, ISO 17025 accreditation standards, and pharmacopeial monographs. Bottom-up equipment procurement modeling and top-down biopharmaceutical pipeline analysis were triangulated to cross-verify segment sizing.
Segment-level outputs across product architecture, end-user concentration, application focus, and detection technology dimensions were generated through the analytical framework. CAGRs were derived from equipment shipment trajectories and service contract attachment rate projections. Key inputs included biopharmaceutical pipeline expansion timelines, regulatory qualification protocol evolution, and precision manufacturing cluster capacity utilization.
Forecast precision tightens around the base case; tail outcomes carry wider variance under single-source sapphire window supply disruption or abrupt FDA guidance revision on sedimentation equilibrium requirements. Forecasts reflect assumptions about EMA guideline stability and biotechnology funding cycle continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Surface Plasmon Resonance Market
Analytical Instruments
Global Gel Documentation Systems Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Microfluidic Modulation Spectroscopy Market
Analytical Instruments
Dissolved Gas Analyzer Market
Analytical Instruments
Kinetic Chromogenic Spectrophotometer Market
Analytical Instruments
Infrared Spectroscopy Devices Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Discrete Analyzers Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
Global Ultrapycnometer Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
ICP-MS System Market
Analytical Instruments
Global Mercury Analyzer Market
Analytical Instruments
Atomic Magnetometers Market