
 Flame Ionization Detectors Market | 2026-2036
Flame Ionization Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Flame Ionization Detectors Market Foresight
European sensor foundries is realigning flame ionization detector supply chains toward tighter hydrogen safety protocols and modular assembly formats. Agilent Technologies leverages its chromatography platform dominance to anchor premium laboratory detector demand in North American and Asian research corridors. Thermo Fisher Scientific sustains competitive pressure through integrated analytical workflows that bundle FID modules with mass spectrometry systems. PerkinElmer specializes in compact, field-hardened designs that target environmental monitoring agencies requiring rapid deployment capabilities.
A flame ionization detector measures organic compound concentration by ionizing carbon-containing samples in a hydrogen-air flame and collecting the resulting charged particles across a polarized electrode assembly, typically achieving detection thresholds below one part per million. The device serves as the reference standard for hydrocarbon quantification in gas chromatography systems, process stream analyzers, and stack emissions monitors across regulated industries. Laboratory detectors retain the dominant value share due to recurring consumables demand and qualification protocols in pharmaceutical quality assurance, while portable detector adoption is accelerating fastest among environmental agencies conducting fugitive emission surveys at petrochemical perimeter zones. Online detector configurations command premium positioning where continuous process control integration eliminates manual sampling delays in refinery operations.
The US EPA enforces Method 25A and New Source Performance Standards that mandate calibrated hydrocarbon monitoring, directly shaping FID procurement cycles and recertification timelines for energy producers and chemical manufacturers. In Europe, the EU Green Deal and Industrial Emissions Directive tighten methane and volatile organic compound thresholds, compelling facility operators to replace legacy thermal conductivity detectors with flame ionization systems that deliver superior selectivity. China's MEE administers parallel ambient air quality standards that require stationary source monitoring networks to employ flame-based detection for total hydrocarbon reporting. Stakeholders must weigh hydrogen infrastructure constraints against detector performance gains as fuel cell supply chains compete for the same compressed gas logistics.
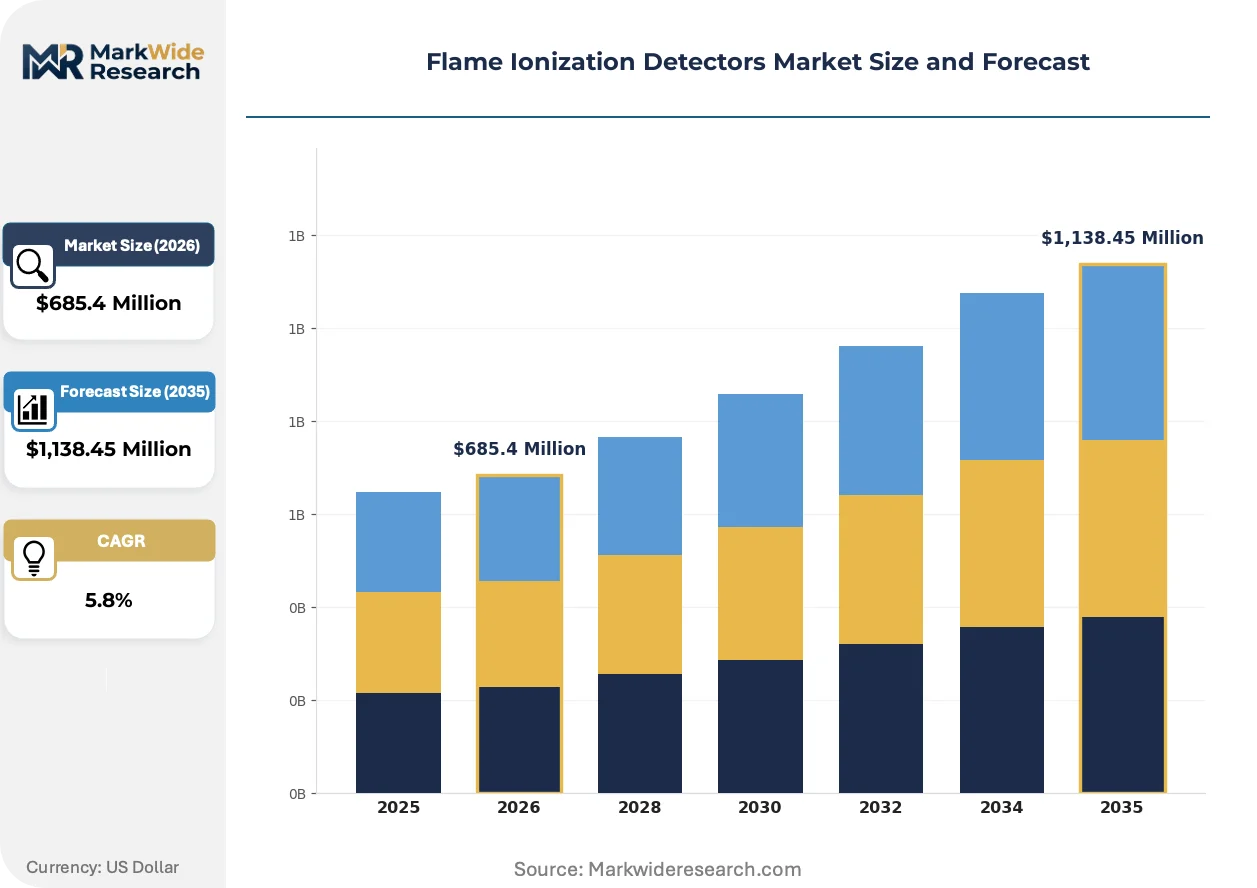
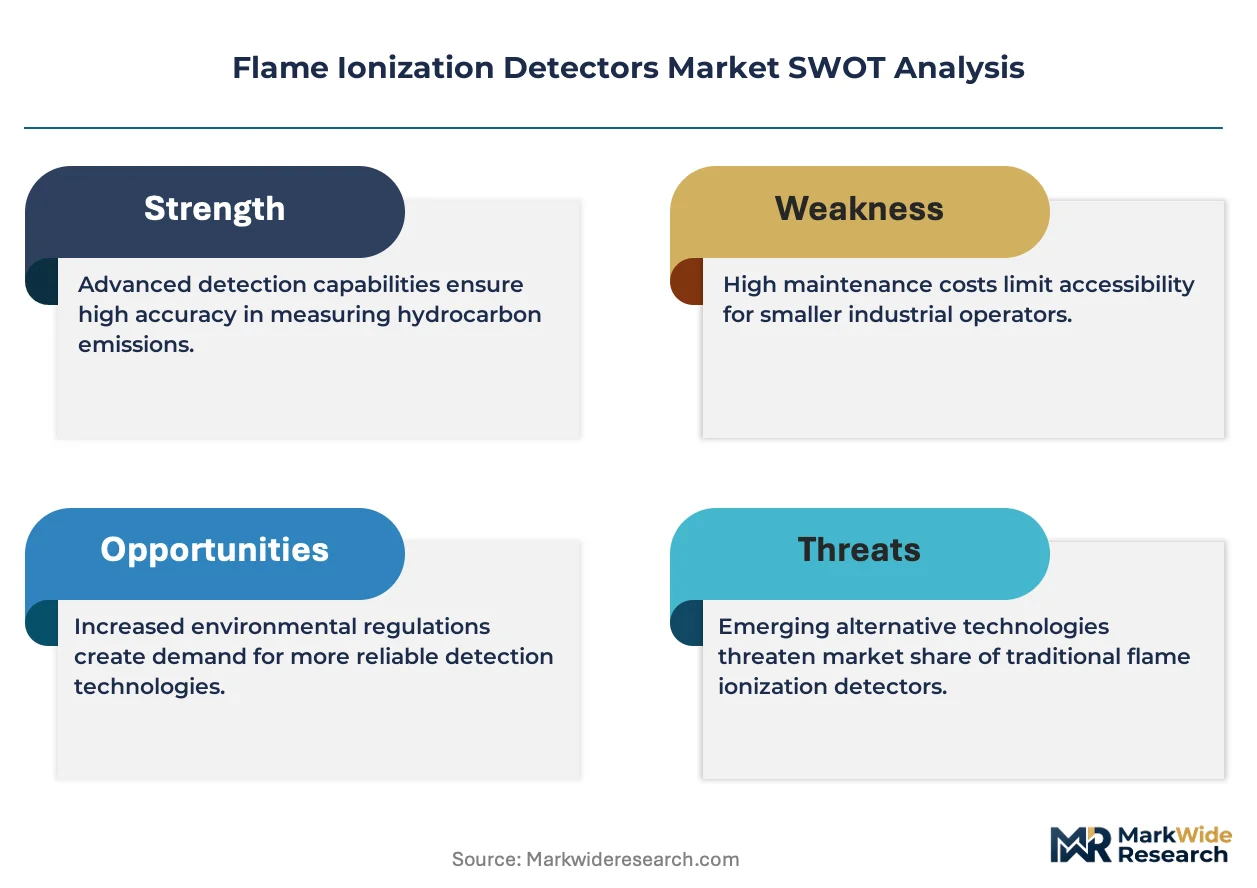
Market Dynamics
The US EPA's methane monitoring mandates are compressing replacement cycles for legacy thermal conductivity detectors while hydrogen fuel logistics compete for compressed gas supply chains essential to flame ionization operation.
Growth Catalysts
- Method 25A Enforcement:The US EPA mandates calibrated hydrocarbon monitoring at petrochemical facilities, forcing systematic detector upgrades and recertification investments across energy producers.
- EU Green Deal Thresholds:Tightened methane and volatile organic compound limits under the Industrial Emissions Directive compel European operators to retire legacy detection systems.
- Portable Field Demand:Environmental agencies in China and India are accelerating procurement of compact units for fugitive emission surveys at refinery perimeter zones.
Market Restraints
- Hydrogen Supply Competition:Fuel cell infrastructure expansion constrains compressed hydrogen logistics that FID systems require for flame maintenance and continuous operation.
- Sensor Foundry Concentration:European manufacturing clusters dominate precision electrode assembly, creating geographic vulnerability in critical component sourcing.
- Platinum Electrode Costs:Precious metal price volatility in polarized electrode materials elevates consumables expenditure for high-frequency laboratory deployments.
Strategic Opportunities
- Modular Assembly Formats:Standardized hydrogen safety protocols enable field-swappable detector heads that reduce downtime in remote environmental monitoring stations.
- Process Analyzer Integration:Bundled FID modules with mass spectrometry workflows capture premium positioning in pharmaceutical quality assurance laboratories.
- China Ambient Networks:The MEE's stationary source monitoring requirements for total hydrocarbon reporting expand addressable infrastructure in provincial industrial corridors.
Industry Challenges
- Electronics-Hydrogen Safety Certification:ATEX and IECEx compliance timelines for flame-based instruments in explosive atmospheres extend product launch schedules by 8-14 months.
- Chromatography Specialist Shortage:Qualified technicians capable of polarized electrode calibration and flame optimization remain scarce in environmental field service organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flame Ionization Detectors Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detector, Laboratory Detector, Online Detector, Fixed Detector Technology: Gas Chromatography, Process Monitoring, Environmental Analysis, Petrochemical Analysis, Food Quality Control Application: Air Quality Testing, Chemical Composition Analysis, Fuel Leak Detection, Industrial Emissions Monitoring, Research and Development End User: Research Institutes, Environmental Agencies, Chemical Manufacturers, Energy Producers, Quality Assurance Laboratories |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, PerkinElmer, Shimadzu Corporation, INFICON, Buck Scientific, GOW-MAC Instrument, Control Instruments Corporation, SRI Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flame Ionization Detectors Market Shifts & Advancements
Detector architectures are converging around miniaturized hydrogen safety systems and digital signal processing that compresses form factors while preserving sub-ppm sensitivity thresholds for field deployment.
Micro-electromechanical systems are unifying flame stabilization chambers with solid-state hydrogen sensors in compact detector heads. Environmental contractors in the Permian Basin and North Sea extraction zones are piloting these integrated units for continuous perimeter monitoring. The technology is unifying previously separate safety and detection functions into single-module designs that slash field maintenance intervals.
REACH authorization requirements for flame-based analytical instruments are tightening substance restrictions on electrode coatings and housing materials. German chemical manufacturers must now document full material flows for platinum-group metal sourcing in process analyzers. Laboratory instrument vendors are accelerating RoHS-compliant redesigns to maintain EU market access ahead of sunset dates.
Service unbundling is fragmenting traditional bundled maintenance contracts for laboratory FID systems. Pharmaceutical quality teams in Massachusetts and Basel now procure electrode replacement and calibration as discrete subscription tiers separate from hardware acquisition. This consumption-pattern shift pressures incumbent vendors to restructure recurring revenue models around certified consumables rather than capital equipment margins.
Flame Ionization Detectors Market Segmentation
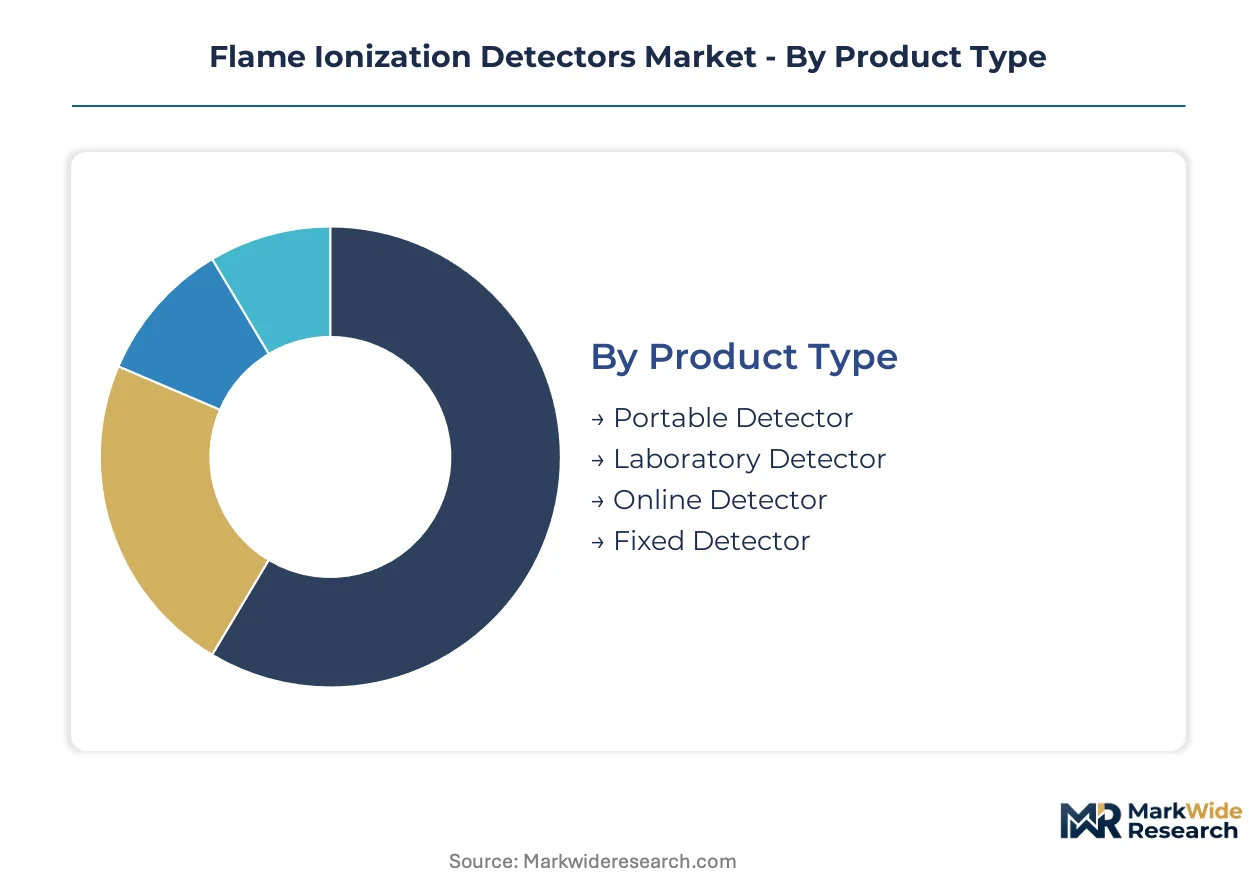
Flame ionization detector procurement splits sharply between capital-intensive laboratory installations with recurring consumables revenue and field-deployable units serving regulatory compliance mandates. Understanding where volume concentration diverges from premium pricing power clarifies vendor positioning across research, industrial, and environmental enforcement channels.
Product Type:
Laboratory detectors command premium positioning through qualification protocols and recurring electrode replacement cycles, while portable units expand fastest among environmental contractors conducting fugitive emission surveys.
- Laboratory Detector:These systems integrate with gas chromatography platforms in pharmaceutical quality assurance workflows, achieving detection thresholds below one part per million through precision polarized electrode assemblies. Demand concentrates in Massachusetts and Basel research corridors where Agilent Technologies and Thermo Fisher Scientific anchor bundled analytical workflows, driven by FDA and EMA validation requirements that enforce systematic recertification investments.
- Portable Detector:Compact hydrogen-powered units serve environmental agencies conducting perimeter monitoring at petrochemical facilities, with China and India accelerating procurement for field emission surveys. The MEE's stationary source monitoring requirements and India's Central Pollution Control Board enforcement protocols are compressing replacement cycles for legacy thermal conductivity detectors in these markets.
- Online Detector:Continuous process stream analyzers eliminate manual sampling delays in refinery operations.
- Fixed Detector:Permanent stack monitoring installations serve EPA Method 25A compliance at energy production facilities.
Mature deployment sits with laboratory detectors. Newer deployment is concentrated in portable units.
Technology:
Application specificity determines whether FID modules integrate with chromatography separation systems or operate as standalone analyzers in process control environments.
- Gas Chromatography:The reference standard configuration couples FID detection with capillary column separation for hydrocarbon speciation in research and pharmaceutical quality laboratories. Demand clusters in North American and European analytical corridors where regulatory agencies mandate calibrated hydrocarbon monitoring for drug substance purity verification.
- Process Monitoring:Direct insertion analyzers bypass chromatographic separation for total hydrocarbon quantification in refinery streams. Deployment accelerates in US Gulf Coast and Rotterdam-Antwerp petrochemical clusters where continuous emissions tracking requirements under EPA and EU Industrial Emissions Directive compel systematic detector upgrades.
- Environmental Analysis:Field-hardened units serve ambient air quality networks and fugitive emission surveys.
- Petrochemical Analysis:Process-optimized configurations target olefin and aromatic stream monitoring.
- Food Quality Control:Specialized detectors quantify residual solvents and packaging volatiles.
Chromatography-integrated systems retain the dominant value share. Process-optimized configurations are expanding most quickly.
Application:
Regulatory enforcement intensity varies dramatically between continuous industrial emissions monitoring and discrete research applications, reshaping procurement cycle predictability.
- Industrial Emissions Monitoring:Stack and perimeter analyzers enforce EPA Method 25A, EU Industrial Emissions Directive, and China MEE stationary source standards through calibrated hydrocarbon reporting. US energy producers and European chemical manufacturers face compressed replacement cycles as methane threshold tightening forces detector upgrades.
- Air Quality Testing:Ambient network analyzers quantify total hydrocarbons in urban monitoring stations and industrial zone perimeter arrays. China's provincial environmental bureaus and India's state pollution control boards are deploying expanded stationary source networks that require flame-based detection for regulatory compliance.
- Chemical Composition Analysis:Laboratory-based hydrocarbon speciation serves research and quality assurance workflows.
- Fuel Leak Detection:Portable survey units identify fugitive emissions at storage terminals and distribution infrastructure.
- Research and Development:Academic and corporate laboratories employ FID systems for method development and analytical validation.
Compliance-driven applications dominate procurement volume. Research-oriented applications sustain premium pricing.
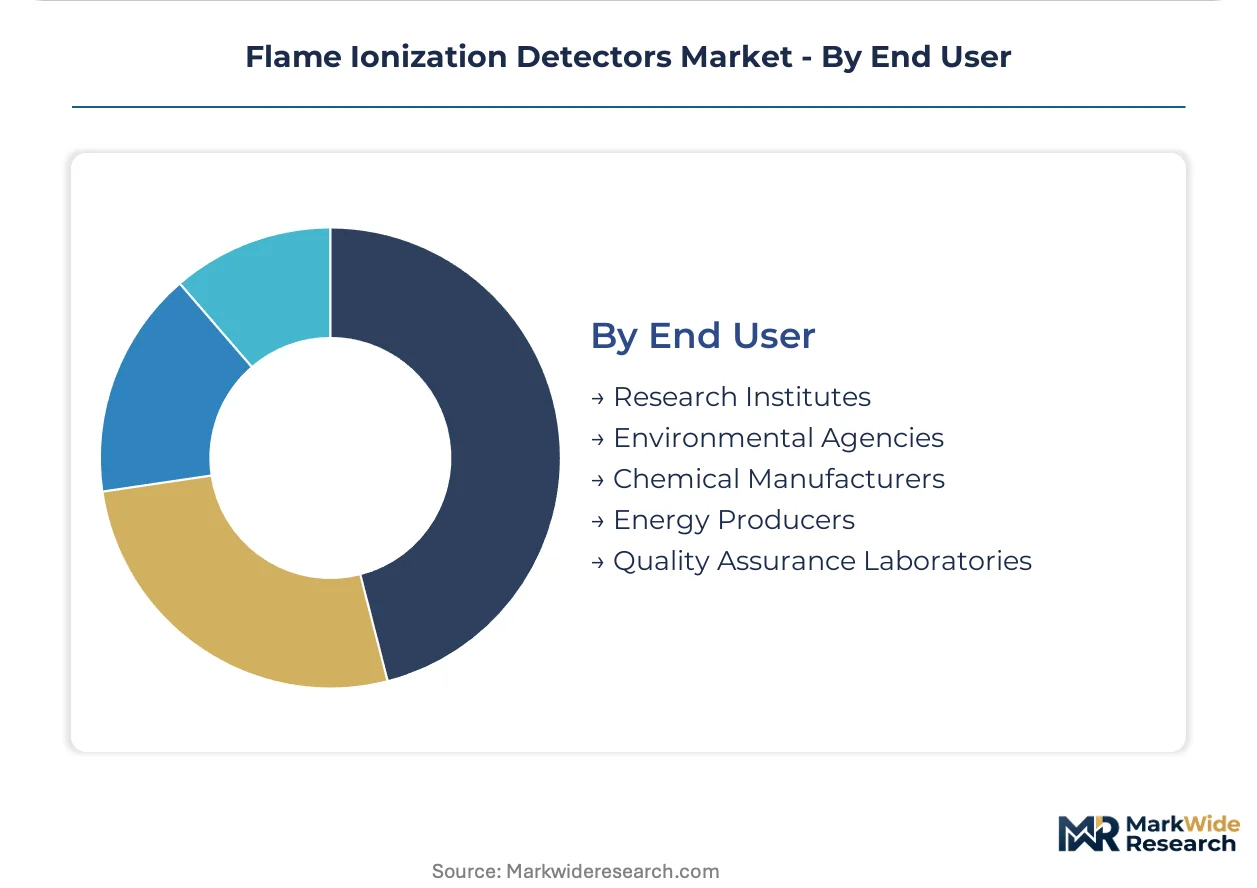
End User:
Buyer sophistication ranges from certified analytical laboratories with dedicated chromatography specialists to field service organizations facing technician scarcity.
- Quality Assurance Laboratories:Pharmaceutical and chemical manufacturers operate under FDA, EMA, and NMPA validation protocols that mandate recurring calibration and electrode replacement. Service unbundling is fragmenting traditional bundled maintenance contracts in Massachusetts and Basel facilities, pressuring vendors to restructure recurring revenue models around certified consumables.
- Environmental Agencies:Federal and state regulators deploy portable and fixed analyzers for enforcement monitoring and perimeter surveillance. The US EPA's tightened methane monitoring rules and China's MEE ambient air quality standards are forcing detector upgrades across industrial facility inspections.
- Research Institutes:Academic and government laboratories conduct method development and analytical validation studies.
- Chemical Manufacturers:Process control teams integrate online analyzers for stream monitoring and emissions compliance.
- Energy Producers:Refinery and upstream operators deploy continuous monitoring for EPA and EU regulatory compliance.
Validated laboratory procurement sustains premium margins. Environmental enforcement deployment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hydrogen feedstock logistics anchor geographic demand patterns for flame ionization detector deployment. Compressed gas infrastructure availability shapes procurement feasibility across industrial clusters.
United States
Petrochemical refineries along the Gulf Coast compress replacement cycles for legacy thermal conductivity detectors. EPA Method 25A enforcement mandates calibrated hydrocarbon monitoring at energy production facilities. The Permian Basin extraction zones pilot integrated MEMS detector units for continuous perimeter monitoring.
Germany
REACH authorization requirements tighten substance restrictions on electrode coatings and housing materials. German chemical manufacturers document full material flows for platinum-group metal sourcing in process analyzers. The Rhine-Ruhr industrial corridor accelerates RoHS-compliant redesigns to maintain EU market access.
China
Provincial environmental bureaus expand stationary source monitoring networks for total hydrocarbon reporting. MEE ambient air quality standards require flame-based detection at industrial facilities. The Yangtze River Delta concentrates procurement growth for portable field units among environmental contractors.
India
Central Pollution Control Board enforcement protocols compress replacement cycles for legacy detection systems. State pollution control boards deploy expanded ambient network analyzers in industrial zone perimeter arrays. Gujarat and Maharashtra industrial corridors accelerate field emission survey capabilities.
Netherlands
Rotterdam-Antwerp petrochemical clusters drive continuous emissions tracking requirements under EU Industrial Emissions Directive. Tightened methane and volatile organic compound thresholds compel systematic detector upgrades. The Randstad region anchors European sensor foundry realignment toward modular assembly formats.
Flame Ionization Detectors Market Competitive Landscape
Global majors compete with regional champions across chromatography platform integration and field-hardened portable design. The vendor base stratifies between laboratory instrument conglomerates with bundled analytical workflows and specialized detector fabricators targeting environmental compliance channels. Three archetypes dominate: chromatography-integrated system houses, compact field-unit specialists, and process analyzer bundlers. Capacity expansion in hydrogen safety certification capabilities and strategic partnerships for electrode supply security represent the dominant competitive moves.
Within the chromatography-integrated tier, Agilent Technologies and Thermo Fisher Scientific occupy positions anchoring premium laboratory demand through bundled analytical workflows. PerkinElmer exemplifies the compact field-hardened design archetype targeting rapid deployment capabilities for environmental monitoring agencies. These three companies represent the strategic positioning spectrum from research-grade platform dominance to regulatory-driven field portability.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| PerkinElmer |
| Shimadzu Corporation |
| INFICON |
| Buck Scientific |
| GOW-MAC Instrument |
| Control Instruments Corporation |
| SRI Instruments |
| Others |
Supply & Pricing Matrix
Modular assembly transitions in European sensor foundries are simultaneously compressing production costs for standardized detector heads and concentrating procurement leverage among hydrogen safety-certified fabricators. This dual effect reshapes margin structures across laboratory and field-deployable product tiers.
Pricing Analysis
Service-bundling fragmentation distinguishes laboratory detector procurement, where pharmaceutical quality teams in Massachusetts and Basel now unbundle electrode replacement and calibration from hardware acquisition. Three-tier pricing structure across premium, standard, and economy levels separates chromatography-integrated systems from portable field units and basic online analyzers. Price differentiation hinges on certification grade and after-sales service tiers. Cost compression in standard-grade portable units is intensifying because environmental agencies in China and India prioritize procurement volume over precision specifications. Field-deployable segments exhibit highest price sensitivity, while validated laboratory systems retain lowest sensitivity due to FDA and EMA compliance mandates.
Supply Chain Analysis
Qualified technicians capable of polarized electrode calibration remain scarce in German, Dutch, and Swiss precision manufacturing clusters, constraining foundry expansion timelines. Supply concentrates in Germany, Netherlands, and China for precision electrode assembly, hydrogen safety module fabrication, and compact detector head production. The chain draws from platinum-group metals, specialized ceramics for flame stabilization chambers, and compressed hydrogen logistics networks. Single-source vulnerability in European precision electrode sourcing creates geographic concentration risk. Distribution runs through analytical instrument distributors, direct OEM channels to petrochemical operators, and government procurement frameworks for environmental agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flame ionization detector manufacturing is consolidating around hydrogen safety certification capabilities and electrode supply security, with REACH authorization timelines and precious metal volatility forcing sub-scale fabricators toward exit or acquisition.
For Market Incumbents: Lock in electrode supply security through captive sourcing agreements or backward integration into platinum-group metal recovery streams. Expand hydrogen safety certification capacity in Rotterdam-Antwerp and Yangtze River Delta corridors to compress ATEX and IECEx compliance timelines that currently extend product launches. Defend against MEMS-based substitute technologies by anchoring chromatography platform dominance in pharmaceutical quality assurance workflows. For New Entrants and Emerging Players: Begin with portable field-hardened designs targeting India's state pollution control boards and China's provincial environmental bureaus, where procurement acceleration outpaces incumbent service capacity. Environmental enforcement channels offer the most penetrable entry point given technician scarcity at established vendors. Pursue direct contracting relationships with petrochemical perimeter monitoring contractors rather than competing for laboratory instrument distributor shelf space. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by chromatography-integrated system houses seeking field-deployment capabilities or process analyzer bundlers requiring hydrogen safety expertise. Long-term viability favors vendors with dual laboratory and field product portfolios that span recurring consumables and capital equipment revenue. Watch for inflection in China's MEE enforcement intensity at provincial industrial corridors as the signal for portable detector demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Safety Certification Investment | Compresses ATEX and IECEx compliance timelines by 8-14 months for flame-based instruments. |
| Electrode Supply Security Partnership | Captures platinum-group metal sourcing stability against precious metal price volatility. |
| Modular Assembly Format Adoption | Enables field-swappable detector heads that reduce downtime in remote environmental stations. |
| Chromatography Platform Integration | Bundles FID modules with mass spectrometry workflows for pharmaceutical quality assurance. |
| Provincial Environmental Bureau Direct Contracting | Bypasses distributor channels to capture China's MEE stationary source monitoring expansion. |
Research Methodology
Multi-period observation of EPA enforcement intensity, EU Industrial Emissions Directive implementation timelines, and China MEE procurement patterns anchored the trend analysis, supplemented by interviews with analytical instrument procurement managers at pharmaceutical quality laboratories, environmental agency field service directors, petrochemical process control engineers, and chromatography specialist technicians. Secondary validation drew from EPA Method 25A regulatory filings, EU ETS monitoring reports, China MEE ambient air quality standard disclosures, and SEC 10-K filings of laboratory instrument conglomerates. Bottom-up segment sizing and top-down macro constraint triangulation reconciled volume and value estimates.
Input-output matrices modeled detector unit shipments against hydrogen feedstock availability, regulatory compliance deadlines, and replacement cycle compression factors across the projection horizon. Segmentation dimensions included product type, technology integration level, application enforcement intensity, and end-user sophistication tier. CAGRs derived from regression analysis of historical procurement patterns against regulatory mandate implementation curves, with specific incorporation of methane threshold tightening schedules and portable field unit adoption curves in Asian environmental agencies.
Underlying measurement precision varies by segment; laboratory detector value estimates carry tighter precision than portable unit volume projections given service unbundling fragmentation. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and hydrogen logistics infrastructure expansion. Supply chain concentration risk, precious metal price volatility, and MEMS substitution acceleration warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
Analytical Ultracentrifuge Systems Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Gas Analyzer Market
Analytical Instruments
Discrete Analyzers Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
3D Touch Probe Market
Analytical Instruments
EPR (ESR) Spectrometer Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
Flame Photometer Market
Analytical Instruments
Global Fixed Zirconia Oxygen Analyzer Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
Microfluidics Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Precision Balances Market