
 ASEAN Smart Homes Market | 2026-2036
ASEAN Smart Homes Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Smart Homes Market Outlook
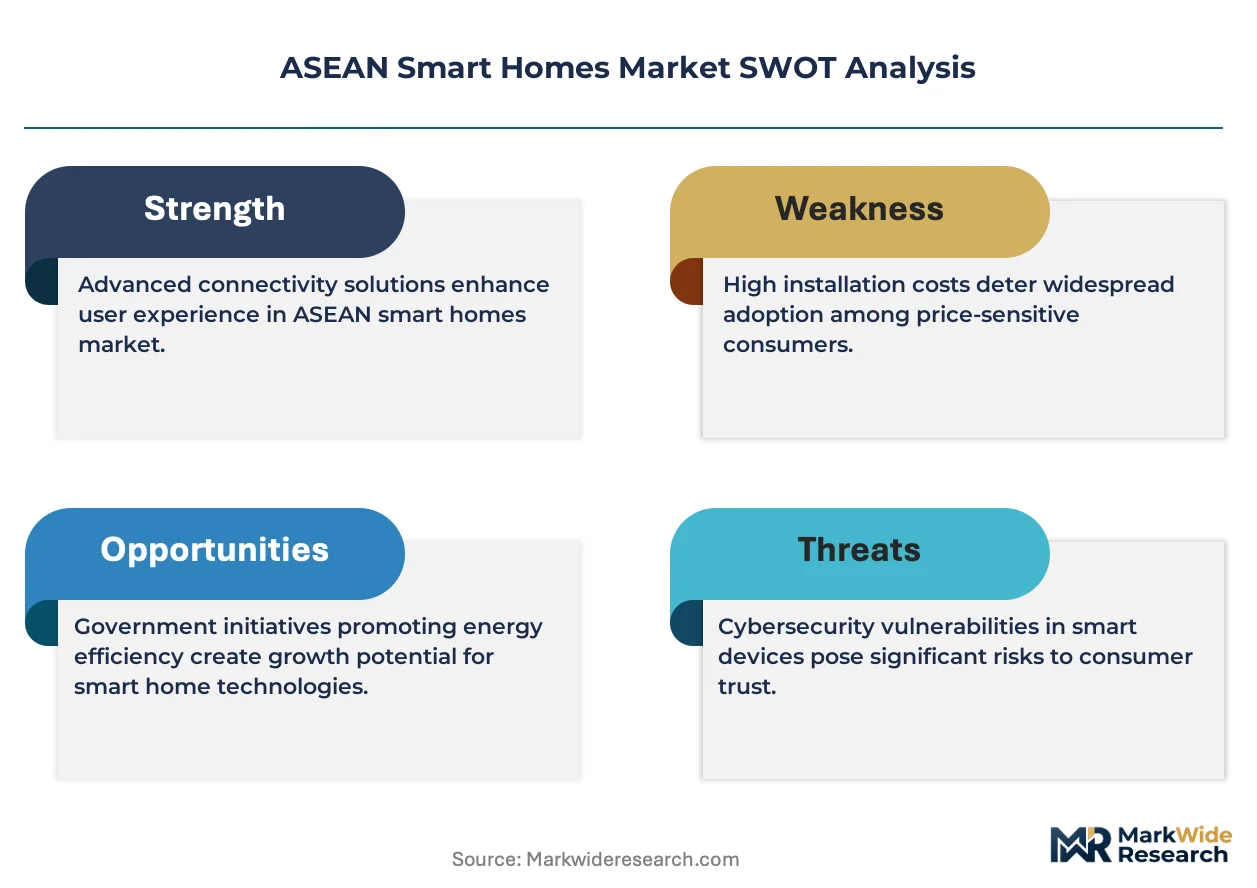
Subscription-based leasing for smart home infrastructure is narrowing the competitive field for capital-constrained entrants. Xiaomi Corp. leverages its ecosystem play across price-sensitive ASEAN households. Honeywell International Inc. anchors its position through building-grade HVAC controls that property managers favor. Samsung Electronics Co. Ltd competes on integrated appliance-to-hub connectivity that reduces installation complexity.
ASEAN smart homes comprise networked sensor, actuator, and control systems operating over wireless protocols with typical latency thresholds below 100 milliseconds for real-time automation. These installations reduce household energy consumption and enable remote property oversight. Smart Security Systems command premium pricing due to insurance-linked installation mandates in several ASEAN jurisdictions. Wi-Fi technology dominates connectivity volumes while Zigbee gains traction in energy management applications where mesh resilience matters. Home Automation as an application category absorbs the largest deployment budgets as builders pre-wire developments in Vietnam and the Philippines.
Singapore's IMDA governs cybersecurity certification for connected devices while Thailand's NBTC sets radio-frequency standards for home networking hardware. Malaysia's SIRIM administers product safety marks that gate retail distribution. Stakeholders must track which ASEAN member states harmonize standards fastest, as regulatory alignment will determine cross-border supply chain economics and vendor scale potential.
Market Dynamics
Property developers in Vietnam and the Philippines are pre-wiring residential towers with centralized smart home infrastructure, compressing installation timelines and locking in ecosystem vendors before individual homeowners make purchasing decisions.
Growth Catalysts
- Singapore's IMDA cybersecurity certification:Mandatory device testing accelerates insurance-linked smart security deployments across high-density residential complexes.
- Mesh protocol adoption:Zigbee's resilience in energy management applications is displacing proprietary RF systems in Indonesian multi-unit housing.
- Greater Jakarta corridor digitization:Middle-class housing stock conversion creates concentrated demand pockets for integrated automation packages.
Market Restraints
- Silicon supply concentration:ASEAN device assemblers remain dependent on imported semiconductor modules from concentrated East Asian foundry networks.
- Interoperability friction:Malaysia's SIRIM-equivalent frameworks impose certification timelines that delay cross-border product launches by 4-8 months.
- Technical fragmentation:Wi-Fi 6E spectrum allocation inconsistencies between Thailand's NBTC and Singapore's IMDA complicate regional SKU planning.
Strategic Opportunities
- Philippine secondary cities:Cebu and Davao housing developments lack smart infrastructure penetration, creating first-mover positioning for subscription-based leasing models.
- Thailand's NBTC radio-frequency harmonization:Pending 2.4 GHz band standardization would unlock cross-border manufacturing economies for hub manufacturers.
- Voice-AI convergence:Integration of natural language processing with building management systems opens retrofit markets in aging Bangkok condominium stock.
Industry Challenges
- Installation technician scarcity:Vietnam and Indonesia lack certified low-voltage wiring specialists capable of mesh network commissioning at scale.
- Legacy electrical compatibility:Pre-2010 housing stock across ASEAN markets requires costly electrical panel upgrades to support centralized smart home hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Smart Homes Market |
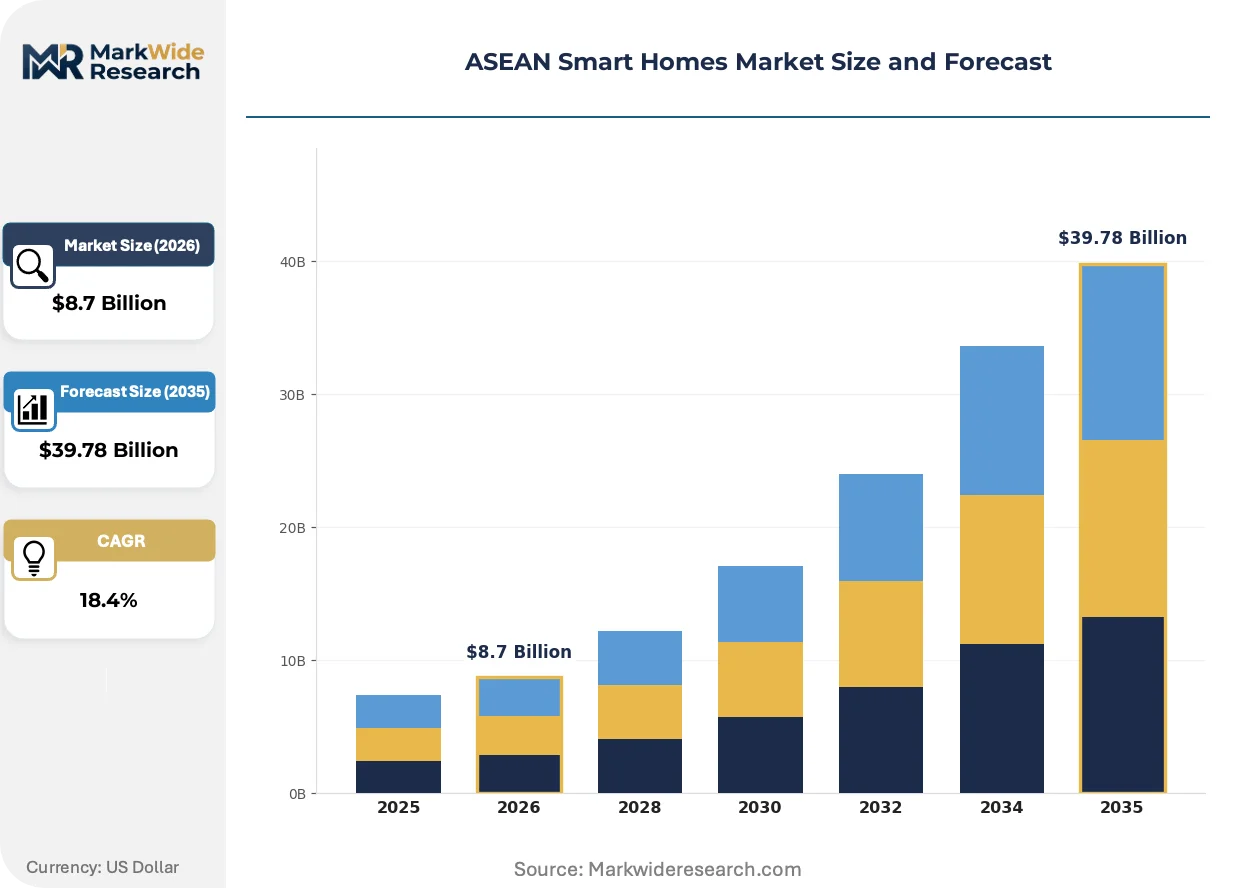
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Security Systems, HVAC Controls, Smart Appliances End User: Homeowners, Property Managers, Builders, Renters Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Application: Home Automation, Energy Management, Security Monitoring, Remote Access |
| Companies Covered | Xiaomi Corp., Honeywell International Inc., Amazon.com Inc., Siemens AG, Schneider Electric SE, Google LLC, Signify N.V., Cisco Systems Inc., Samsung Electronics Co. Ltd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Smart Homes Market Strategic Shifts
Wireless protocol evolution and regulatory harmonization efforts are compressing vendor response cycles while reshaping how property developers specify infrastructure before construction completion.
Matter-over-Thread implementations are rendering obsolete single-protocol hub architectures that locked consumers into proprietary ecosystems. Bangkok and Singapore property managers are specifying Matter-compatible infrastructure in new tenders issued since late 2024. This convergence is rendering obsolete the fragmented Zigbee-Z-Wave-Wi-Fi gateway stacks that previously dominated ASEAN retrofit markets.
Thailand's NBTC has proposed unified 2.4 GHz and 5 GHz device certification procedures that would eliminate duplicate testing for products sold across Singapore, Malaysia, and Thailand. This regulatory streamlining compresses time-to-market for hub manufacturers. Vietnamese builders targeting cross-border sales are restructuring procurement specifications to align with these anticipated harmonized standards.
Subscription-based infrastructure leasing is displacing upfront hardware purchases in Philippine and Indonesian mass-market housing. Property developers in Manila's Quezon City corridor now bundle 36-month smart home service contracts into mortgage packages. This financing innovation concentrates vendor selection power with institutional developers rather than individual homeowners.
ASEAN Smart Homes Market Segmentation
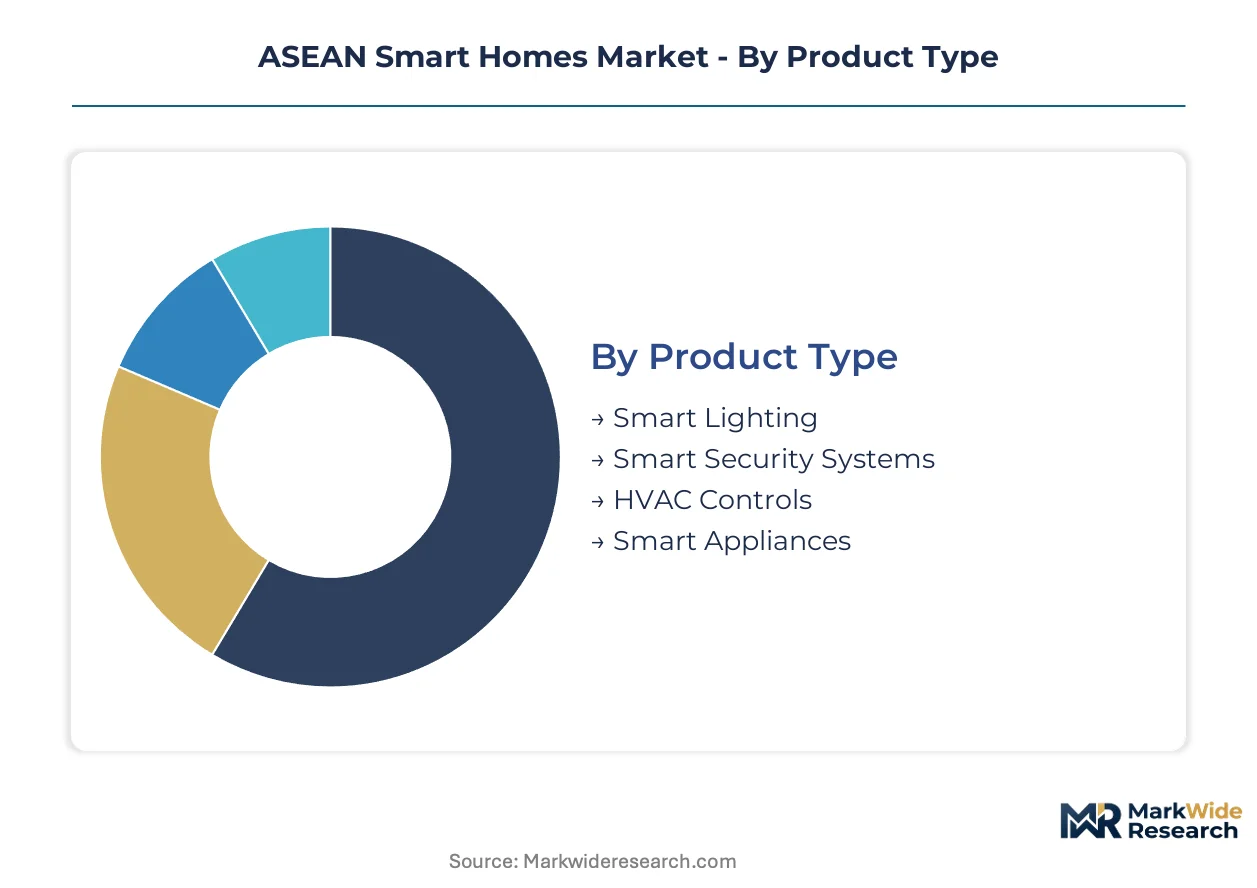
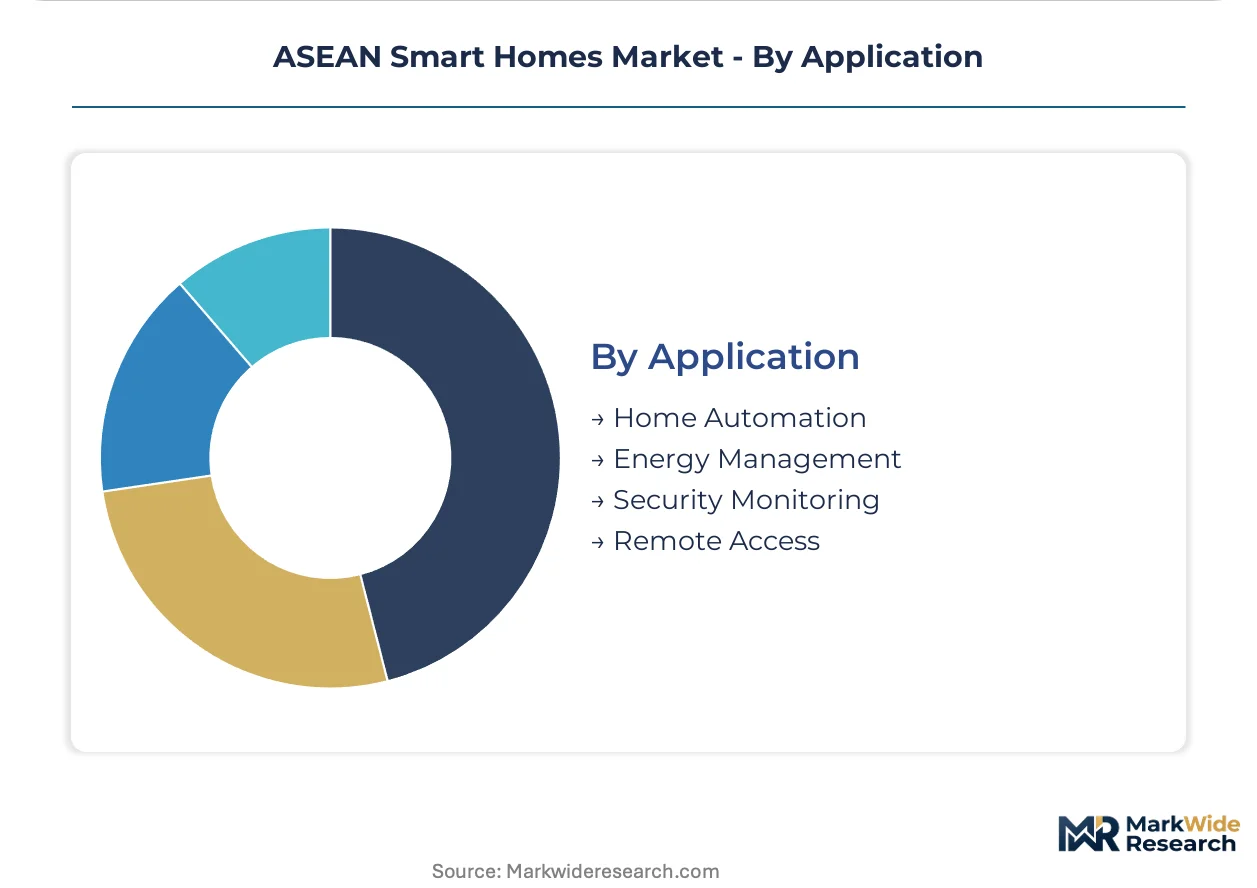
ASEAN smart home deployments fragment across four critical dimensions: hardware categories, buyer archetypes, connectivity protocols, and functional use cases. Each dimension carries distinct procurement rhythms and margin structures that vendors must navigate.
Product Type:
The use-case spectrum spans ambient comfort through threat mitigation, with installation complexity and insurance linkage driving pricing power differentiation.
- Smart Lighting:LED-integrated fixtures with tunable white and RGB capabilities, typically operating over mesh protocols. Demand clusters in Vietnamese pre-wired residential towers where builders specify centralized control panels during construction.
- Smart Security Systems:Camera arrays, motion sensors, and access control modules with sub-100ms alert latency. Singapore high-density complexes absorb premium units due to IMDA cybersecurity certification mandates tied to insurance coverage.
- HVAC Controls:Thermostats and zone dampers optimizing cooling loads across tropical climates. Bangkok property managers favor building-grade units from established industrial suppliers.
- Smart Appliances:Connected refrigerators, washing machines, and cooking equipment with appliance-to-hub integration. Indonesian middle-class households in Greater Jakarta drive replacement cycles.
The dominant share belongs to Smart Security Systems, while Smart Lighting is closing the gap fastest.
End User:
Procurement authority concentrates with institutional actors who control specification timing and ecosystem lock-in.
- Homeowners:Individual purchasers selecting retrofit devices through retail channels. Malaysian SIRIM certification requirements delay their access to newest product generations.
- Property Managers:Professional operators overseeing multi-unit residential portfolios across Singapore and Bangkok. Their tender specifications increasingly mandate Matter-compatible infrastructure.
- Builders:Developers pre-wiring towers in Vietnam and the Philippines, compressing installation timelines and locking vendors before homeowner involvement. Cebu and Davao developments represent untapped penetration.
- Renters:Tenants accessing smart home capabilities through subscription leases bundled into mortgage packages in Manila's Quezon City corridor.
Builders command the dominant procurement volume, while Property Managers are expanding their specification authority fastest.
Technology:
Protocol selection determines mesh resilience, power consumption, and cross-border SKU compatibility.
- Wi-Fi:Dominant connectivity volume leveraging existing household infrastructure. Thailand's NBTC and Singapore's IMDA spectrum allocation inconsistencies complicate regional product planning for 6E implementations.
- Zigbee:Mesh topology excelling in energy management applications where node-to-node resilience matters. Indonesian multi-unit housing is displacing proprietary RF systems with this standard.
- Z-Wave:Sub-GHz protocol with strong penetration in legacy ASEAN retrofit markets. Matter-over-Thread convergence is rendering single-protocol hub architectures obsolete.
- Bluetooth:Low-energy implementations for direct device-to-phone commissioning and temporary guest access scenarios.
Wi-Fi retains the dominant connectivity share, though Zigbee is gaining traction fastest in energy-intensive applications.
Application:
Functional deployment priorities reflect regulatory pressure, utility cost structures, and remote oversight needs.
- Home Automation:Integrated control of lighting, climate, and entertainment systems. Vietnamese and Philippine builders allocate largest deployment budgets to this category in new construction.
- Energy Management:Load balancing and consumption analytics responding to tariff structures. Zigbee mesh networks dominate this segment where sensor density requires protocol resilience.
- Security Monitoring:Real-time surveillance and intrusion detection with insurance-linked installation mandates in several ASEAN jurisdictions.
- Remote Access:Cloud-connected oversight enabling property management from distance. Aging Bangkok condominium stock drives retrofit demand for voice-AI convergence.
Home Automation captures the dominant deployment budget, while Energy Management is climbing the fastest as electricity tariffs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASEAN smart home hardware flows through concentrated import channels, with Singapore and Thailand serving as regional distribution nodes while Vietnam and Indonesia absorb the largest installation volumes. Export competitiveness hinges on harmonized certification regimes that remain fragmented across national regulators.
Singapore
High-density residential towers drive premium security system deployments. The Infocomm Media Development Authority mandates cybersecurity certification for connected devices, accelerating insurance-linked installations. Property managers in Marina Bay and Orchard Road corridors specify Matter-compatible infrastructure in new tenders.
Thailand
Bangkok condominium retrofits create demand for voice-AI converged building management systems. The National Broadcasting and Telecommunications Commission proposes unified 2.4 GHz certification procedures to streamline cross-border manufacturing. Developers in the Rama IX corridor pre-wire towers with centralized smart infrastructure.
Vietnam
Ho Chi Minh City and Hanoi builders allocate largest deployment budgets to home automation in new residential towers. The national standards body tightens electrical safety marks for connected devices. Pre-wiring specifications in District 2 and Tay Ho developments lock ecosystem vendors before homeowner involvement.
Indonesia
Greater Jakarta middle-class housing stock digitizes fastest across ASEAN markets. The national standards administration imposes interoperability certification timelines that delay product launches. Multi-unit developments in Bekasi and Tangerang displace proprietary RF systems with Zigbee mesh networks.
Philippines
Manila's Quezon City corridor bundles 36-month smart home service contracts into mortgage packages. The Department of Trade and Industry oversees product safety marks that gate retail distribution. Cebu and Davao secondary city developments represent untapped penetration for subscription-based leasing models.
ASEAN Smart Homes Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying sensors, modules, and connectivity hardware. The vendor base organizes around three strategic archetypes: ecosystem players leveraging cross-device integration, industrial-grade suppliers anchoring property manager relationships, and consumer electronics firms competing on installation simplicity. Consolidation pressure concentrates among hub manufacturers as Matter-over-Thread convergence renders single-protocol architectures obsolete. Strategic moves center on certification pre-positioning ahead of regulatory harmonization and developer partnership lock-ins during pre-construction specification windows.
Within the ecosystem integrator tier, Xiaomi Corp. and Samsung Electronics Co. Ltd exemplify contrasting geographic positioning strategies, with the former anchoring price-sensitive mass-market penetration and the latter occupying integrated appliance-to-hub connectivity positioning. Honeywell International Inc. represents the industrial-grade archetype favored by Bangkok and Singapore property managers for building-grade HVAC specifications. These three entities collectively illustrate how vendor selection power concentrates with institutional developers rather than individual homeowners across ASEAN markets.
| Leading Market Players |
|---|
| Xiaomi Corp. |
| Honeywell International Inc. |
| Amazon.com Inc. |
| Siemens AG |
| Schneider Electric SE |
| Google LLC |
| Signify N.V. |
| Cisco Systems Inc. |
| Samsung Electronics Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Ho Chi Minh City's electronics assembly clusters concentrate smart home hub manufacturing capacity, with their output volumes directly determining pricing leverage for downstream ASEAN distributors. Malaysian SIRIM certification timelines compress margins for uncertified entrants while Singapore's IMDA cybersecurity tiers create premium pricing bands.
Pricing Analysis
Property developers anchor pricing power through bulk procurement contracts that lock ecosystem vendors during pre-construction phases. Three-tier pricing structure across IMDA-certified premium, SIRIM-standard mid-tier, and uncertified economy levels reflects compliance cost layering. Pricing pressure stems from subscription-based leasing models displacing upfront hardware purchases in Philippine mass-market housing. Individual homeowners in retail channels exhibit highest price sensitivity, while Bangkok property managers prioritize building-grade reliability over unit cost.
Supply Chain Analysis
Semiconductor module feedstocks draw from concentrated East Asian foundry networks in Taiwan, South Korea, and mainland China. Zigbee radio chips, Wi-Fi 6E chipsets, and Matter-compatible system-on-modules constitute critical input dependencies. Single-source vulnerability in advanced node fabrication creates supply chain risk for hub manufacturers. Distribution runs through Singapore and Thailand as regional consolidation nodes before final installation across Vietnamese and Indonesian developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN smart home market fragmentation creates positioning openings as Matter-over-Thread convergence disrupts incumbent protocol lock-ins. Developer-led procurement centralization enables ecosystem capture before homeowner decision involvement.
For Market Incumbents: Build certification moats through pre-positioning against Thailand's NBTC harmonization proposals and Malaysia's tightening interoperability frameworks. Secure developer partnership lock-ins during District 2 and Tay Ho pre-wiring windows. Counter Xiaomi's ecosystem bundling with building-grade HVAC integration that property managers favor. Invest in Matter-compatible hub architectures before single-protocol legacy stocks become obsolete.
For New Entrants and Emerging Players: Build out subscription infrastructure leasing capabilities targeting Cebu and Davao secondary city developments where smart penetration remains minimal. Capture Philippine renter segments through 36-month service contracts bundled into Quezon City mortgage packages. Deploy voice-AI convergence for aging Bangkok condominium retrofits as differentiated entry angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hub manufacturers with Matter-over-Thread software stacks over hardware-dependent component suppliers. Five-to-ten year viability hinges on regulatory harmonization capture across Singapore-Malaysia-Thailand corridors. Monitor Thailand's NBTC 2.4 GHz standardization announcements as inflection signal for cross-border manufacturing economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter-over-Thread Platform Migration | Eliminates proprietary gateway lock-in and renders Zigbee-Z-Wave stacks obsolete across ASEAN retrofit markets. |
| Developer Partnership Lock-in | Pre-wiring specifications in Vietnamese towers compress vendor selection windows before homeowner involvement. |
| Certification Pre-positioning | Early alignment with Thailand's NBTC harmonization unlocks cross-border SKU economies for hub manufacturers. |
| Subscription Infrastructure Leasing | 36-month service contracts bundled into Philippine mortgages concentrate vendor power with institutional developers. |
| Voice-AI Building Management Integration | Natural language processing convergence opens retrofit demand in aging Bangkok condominium stock. |
Study Parameters
A standing panel of property development executives, building automation engineers, IMDA certification specialists, and NBTC regulatory affairs leads provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with Vietnamese pre-wiring procurement directors and Singaporean property management tender officers. Secondary validation drew from SIRIM product safety mark databases, Thailand NBTC radio-frequency filings, and ASEAN customs trade flows for connected device imports. Bottom-up installation volume estimates triangulated against top-down builder capex allocations.
Scenario-bracketing framed projections across the analysis window using conservative, baseline, and accelerated regulatory harmonization tracks. Segmentation dimensions modeled include product category, buyer archetype, connectivity protocol, and functional application alongside jurisdiction-specific certification tier. CAGRs derived from logistic adoption curves fitted to smart security penetration rates in Singapore high-density housing and home automation deployment ratios in Vietnamese new construction. Electricity tariff trajectories and insurance mandate expansion timelines fed sensitivity testing.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem bundling by consumer electronics platforms or accelerated NBTC-IMDA-SIRIM alignment would shift outcomes beyond modeled ranges. Semiconductor supply concentration and installation technician scarcity constitute primary revision triggers. Cross-checking against IMDA cybersecurity certification issuance rates and Vietnamese building permit automation specifications is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Battery E-Commerce Market
Others
Bitcoin Mining Servers Market
Others
North America Printed Signage Market
Others
Asia-Pacific Telecom Transformers Market
Others
Mini Personal Computer Market
Others
India 3D Printing Construction Market
Others
Global Food Fiber Market
Others
Short Video Applications Market
Others
Global Geotechnical Instrumentation and Monitoring Market
Others
Asia-Pacific Social Media Management Market
Others
Thailand Travel Retail Market
Others
Mobile MRI Services Market
Others
5G Devices Market
Others
LED Packaging Market
Others
Tobacco Packaging Market
Others
Hybrid Switchgear Market