
 Dry Wall Tapes Market | 2026-2036
Dry Wall Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Wall Tapes Market Analytics
Modular bundling of drywall tapes with joint compounds and corner beads is pivoting how contractors specify finishing systems. Saint-Gobain leverages its integrated building materials portfolio to control specification channels across major metropolitan construction markets. 3M Company differentiates through adhesive chemistry leadership in self-adhesive tape formulations. CertainTeed Corporation anchors its position with manufacturing scale in gypsum-adjacent finishing products distributed through pro-oriented dealer networks.
Dry wall tapes are reinforcing strips manufactured from paper, fiberglass mesh, or composite substrates, typically ranging from two to four inches in width, designed to bridge joints between gypsum board panels and prevent cracking under structural movement or thermal cycling. Their primary purpose is to create seamless, durable wall and ceiling surfaces ready for paint or texture application. Fiberglass mesh tapes command expanding share in repair work and speed-focused commercial jobs where self-adhesive backing eliminates embedding coat requirements. Paper tape retains dominance in interior finishing among union-trained contractors who value its superior crack resistance and lower material cost per linear foot. Specialty tapes, including flexible corner and fire-rated variants, capture concentrated margin pools in complex architectural geometries and code-stringent commercial builds.
ASTM International sets dimensional and performance baselines for paper and fiberglass drywall tapes in North America, while the European Committee for Standardization enforces EN 13963 for jointing materials under the Construction Products Regulation. OSHA workplace exposure limits for respirable silica during sanding operations indirectly shape demand toward low-dust or pre-finished tape systems that reduce finishing labor. Stakeholders must monitor evolving building code cycles in California, Florida, and Texas, where wind-load and moisture-resistance amendments increasingly specify tape-grade performance in rated assemblies.
Market Dynamics
ASTM C475 and EN 13963 standards are tightening crack-resistance and fire-rating thresholds, forcing tape manufacturers to reformulate substrates and adhesive systems while residential renovation cycles accelerate specification velocity across North America and Western Europe.
Growth Catalysts
- Housing stock aging:Decades-old residential inventory across the United States and Germany requires systematic interior retrofitting, expanding repair-grade tape consumption through professional contractor channels.
- ASTM C475 performance tiering:Enhanced crack-resistance mandates in North American commercial construction are elevating specification standards for paper and composite tape grades.
- Fiberglass mesh self-adhesion:Self-adhesive backing chemistry eliminates embedding coat labor, accelerating adoption in speed-driven commercial maintenance contracts.
Market Restraints
- Gypsum price volatility:Input cost swings for gypsum-adjacent finishing materials compress margin stability for tape producers without captive mineral supply.
- Union-trained contractor concentration:Paper tape preference among established trades limits mesh tape penetration in premium residential finishing segments.
- Silica exposure compliance:OSHA respirable silica limits during sanding operations add PPE and ventilation costs that offset labor savings from faster tape systems.
Strategic Opportunities
- Pre-finished low-dust systems:OSHA compliance pressure creates white space for factory-coated tapes that minimize on-site sanding requirements.
- Modular specification bundling:Joint compound and corner bead integration with tape selection is shifting contractor procurement toward single-source finishing systems.
- Florida wind-load amendments:Enhanced structural rating requirements in hurricane-prone construction zones specify performance-grade tape assemblies in rated wall systems.
Industry Challenges
- Skilled finisher shortage:Declining union apprenticeship enrollment in taping trades extends project timelines and increases callback rates for defect remediation.
- Multi-standard certification lag:Simultaneous ASTM C475 and EN 13963 testing protocols delay product launches for suppliers serving transatlantic project portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Wall Tapes Market |
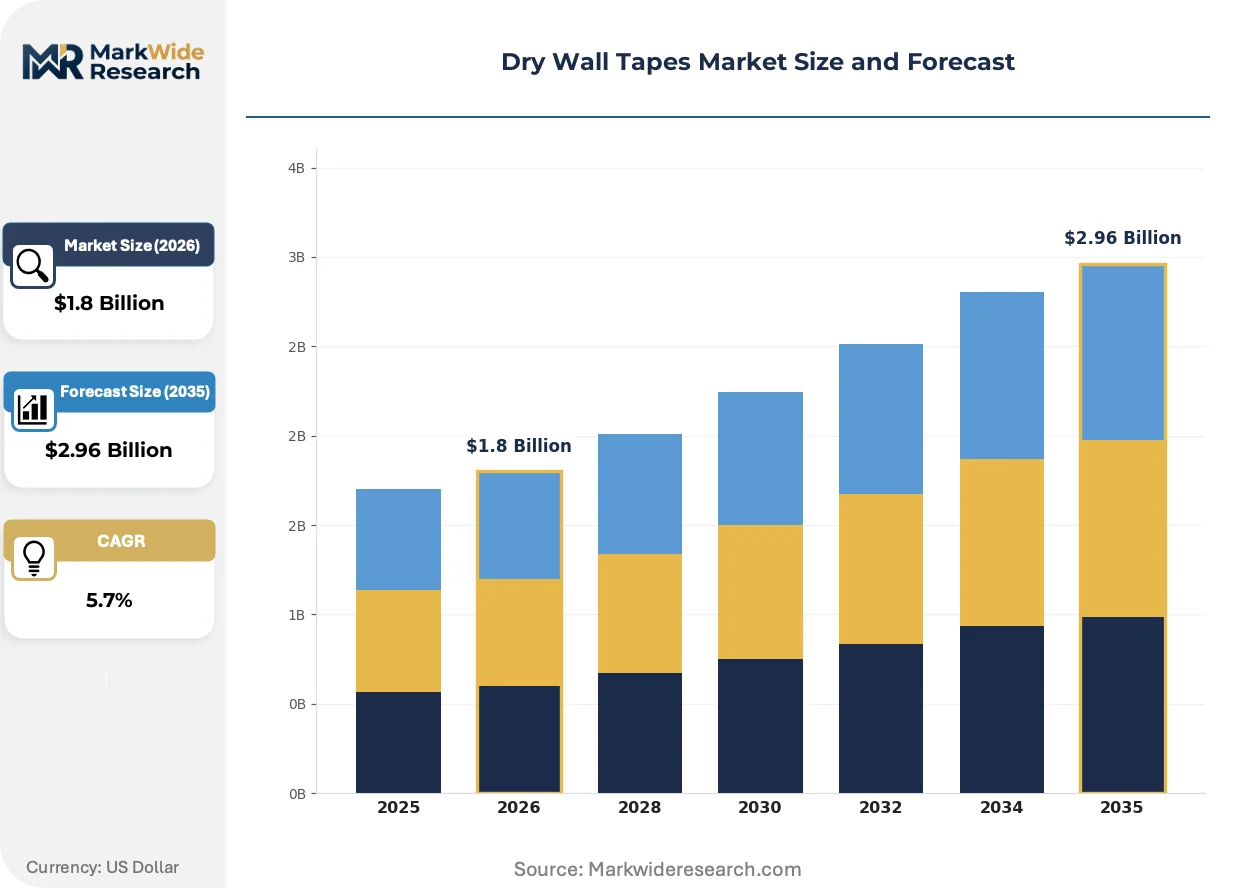
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Tape, Fiberglass Mesh, Self-Adhesive Tape, Specialty Tape Application: Interior Finishing, Repair Work, Decorative Applications, Ceiling Installation End User: Construction Contractors, DIY Enthusiasts, Renovators, Industrial Users Packaging Type: Roll, Strip, Box, Bulk |
| Companies Covered | Saint-Gobain, 3M Company, USG Corporation, PPG Industries, Nippon Paper Industries, FibaTape, Strait-Flex, National Gypsum Company, CertainTeed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Wall Tapes Market Evolving Landscape
Material science advances in adhesive polymers and substrate composites are compressing installation cycles while regulatory pressure on fire performance and workplace exposure is reshaping product architecture and jobsite protocols.
Self-adhesive fiberglass mesh tape is automating labor allocation on commercial maintenance crews by eliminating the embedding coat step entirely. Large-scale property management firms and national retail renovation contractors are standardizing mesh specifications across their vendor manuals. This compression is automating cost structures in high-volume repair segments where speed-to-occupancy drives vendor selection.
EN 13963 crack-resistance amendments under the EU Construction Products Regulation are elevating performance thresholds for jointing materials in commercial rated assemblies. Manufacturers serving German and French markets must reformulate paper tape substrates or add reinforcing fibers to maintain CE marking compliance. Premium commercial contractors in the Netherlands and Belgium are already specifying upgraded tape grades to preempt code-cycle changes.
Specification bundling is consolidating procurement decisions around integrated finishing systems rather than discrete commodity purchases. Regional pro-oriented dealer networks are displacing traditional two-step distribution for mid-size commercial contractors. This channel compression is most visible in Texas and California metropolitan construction markets where single-source accountability reduces project coordination overhead.
Dry Wall Tapes Market Segmentation
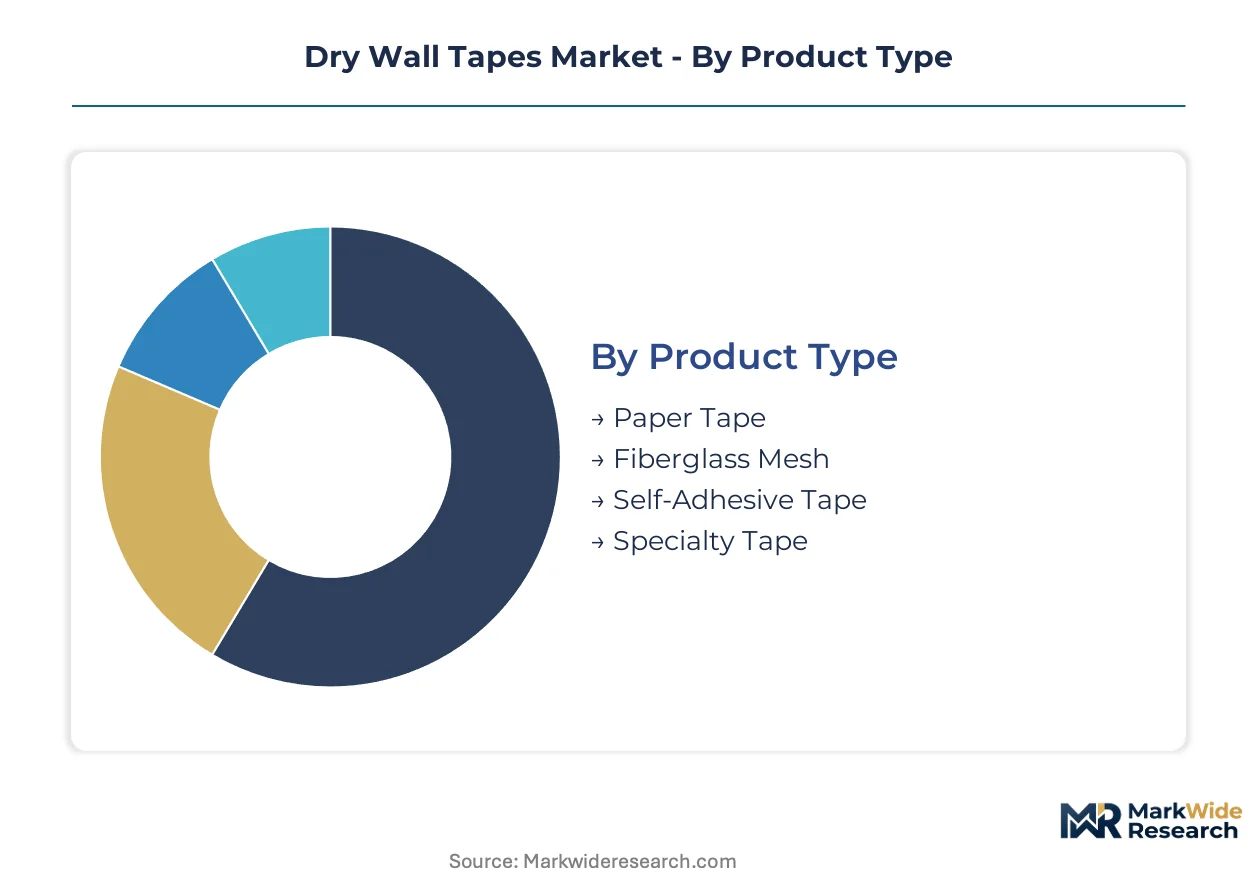
Segmentation in the dry wall tapes market reveals how material specifications, application intensity, and procurement patterns fragment demand across distinct buyer workflows. Understanding these divisions exposes where specification power concentrates and where margin pools shift between commodity and performance-grade products.
Product Type:
Upgrade cycles in residential renovation and commercial retrofit are reshaping which tape substrates contractors specify for durability versus speed.
- Paper Tape:Manufactured from creased kraft paper designed to embed within joint compound layers, delivering superior crack resistance through mechanical bonding with finishing mud. Union-trained contractors across the United States and Germany specify this grade for premium residential interiors where callback liability drives material selection.
- Fiberglass Mesh:Woven glass fiber substrate with open-weave architecture allows joint compound to penetrate and lock the tape matrix. Self-adhesive variants eliminate embedding coat labor, accelerating adoption among commercial maintenance crews in speed-driven repair contracts.
- Self-Adhesive Tape:Pressure-sensitive adhesive backing enables direct-to-drywall application without initial compound embed. Property management firms standardize this format across national retail renovation vendor manuals.
- Specialty Tape:Includes flexible corner beads, fire-rated assemblies, and moisture-resistant formulations engineered for complex geometries and code-stringent commercial builds.
Paper tape sits at the top of the volume ranking, with fiberglass mesh climbing the fastest.
Application:
Application intensity varies sharply between new construction finishing cycles and reactive repair workflows, fragmenting demand by project duration and labor allocation.
- Interior Finishing:Primary drywall joint treatment in residential and commercial new construction, requiring seamless surface preparation for paint or texture. ASTM C475 compliance mandates govern specification in North American commercial builds.
- Repair Work:Patch-and-blend operations on aging housing stock across the United States and Western Europe, where speed-to-occupancy pressures favor self-adhesive mesh systems.
- Decorative Applications:Architectural detail work including curved soffits, archways, and custom ceiling treatments demanding flexible or pre-formed tape products.
- Ceiling Installation:Overhead joint treatment where gravity loading and thermal cycling stress tape performance, driving specification toward reinforced grades in commercial high-bay construction.
Interior finishing commands the largest addressable base, while repair work expands most quickly.
End User:
Buyer sophistication and procurement scale separate professional channels from consumer-grade purchasing, concentrating margin in specification-controlled contractor networks.
- Construction Contractors:Professional finishing crews purchasing through pro-oriented dealer networks, driving bundled specification of tapes with joint compounds and corner beads. EN 13963 compliance requirements in France and Germany elevate performance-grade procurement.
- DIY Enthusiasts:Home improvement retailers capture this segment through pre-packaged repair kits, though volume per transaction remains minimal compared to contractor channels.
- Renovators:Specialized retrofit contractors targeting aging residential inventory, where systematic interior refurbishment sustains repair-grade tape demand.
- Industrial Users:Manufacturing facility maintenance departments and commercial property management firms standardizing mesh tape specifications across vendor manuals.
Construction contractors dominate procurement volume, with industrial users gaining share fastest.
Packaging Type:
Packaging configuration aligns with project scale and inventory velocity, separating retail-ready formats from bulk logistics optimized for high-volume commercial sites.
- Roll:Standard 250-foot and 500-foot lengths for professional finishing crews, enabling continuous application without splice points. Pro-oriented dealer networks stock this format as the baseline specification.
- Strip:Pre-cut lengths for repair kits and patch applications, common in DIY retail channels and property management maintenance carts.
- Box:Multi-roll cases for mid-size commercial contractors managing inventory across multiple active job sites.
- Bulk:Palletized shipments for national retail renovation contractors and large-scale property management firms with centralized warehousing.
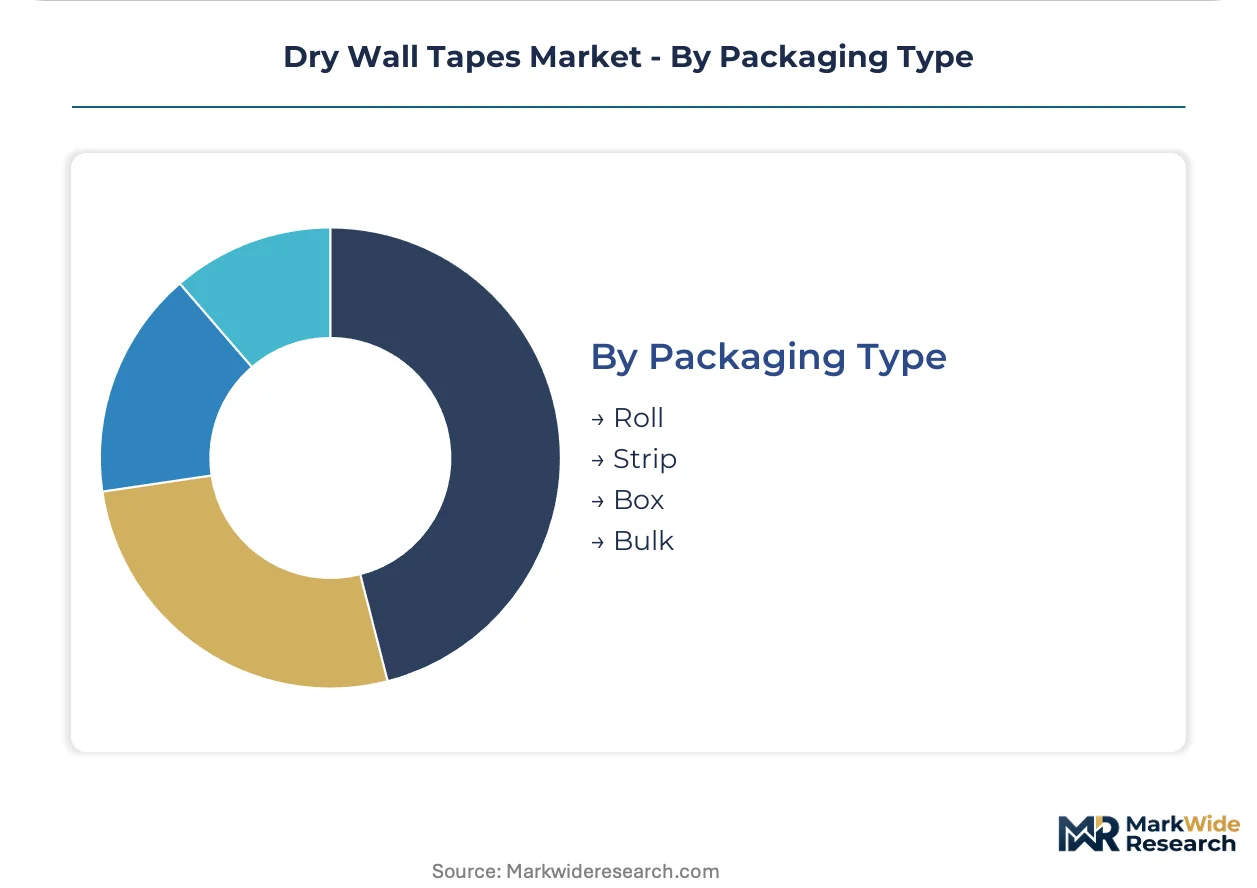
Roll packaging leads absolute volume, with bulk formats showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The drywall finishing industry traces its modern standardization to post-war American construction methods, with ASTM protocols later diffusing to Western European markets through multinational building materials firms. This historical foundation explains why specification power and regulatory influence remain concentrated in transatlantic construction corridors.
United States
Single-family renovation spending and commercial interior retrofit cycles sustain elevated demand for both paper and mesh tape grades. OSHA respirable silica exposure limits during sanding operations indirectly shape procurement toward low-dust finishing systems. Texas and California metropolitan construction markets exhibit concentrated specification bundling through pro-oriented dealer networks.
Germany
Aging housing stock across former West German industrial regions drives systematic interior refurbishment, expanding repair-grade tape consumption through professional contractor channels. EN 13963 crack-resistance amendments under the EU Construction Products Regulation mandate substrate reformulation for CE marking compliance. The Rhine-Ruhr corridor anchors manufacturing scale for gypsum-adjacent finishing products distributed throughout Central Europe.
France
Premium commercial contractors in the Paris Basin and Lyon region preemptively specify upgraded tape grades ahead of anticipated code-cycle changes. The country's national building regulator enforces performance-tiered procurement for rated commercial assemblies. French specification channels increasingly favor integrated finishing systems over discrete commodity purchases.
United Kingdom
Post-grenfell fire safety reforms elevate fire-rated tape assembly requirements in multi-occupancy residential construction. The Health and Safety Executive workplace exposure frameworks parallel OSHA silica constraints, favoring pre-finished systems. Greater London and Southeast England concentrate specification influence for national retail renovation and property management contracts.
Canada
Residential construction contractors in Ontario and British Columbia represent expanding buyer segments as housing stock ages across major metropolitan areas. Health Canada and the PMRA influence material safety standards for interior finishing products. Toronto and Vancouver construction markets exhibit procurement patterns mirroring American specification bundling trends.
Dry Wall Tapes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across specification control and adhesive chemistry dimensions, with integrated building materials portfolios commanding superior channel positioning. The vendor base clusters around three strategic archetypes: diversified construction materials conglomerates with captive gypsum supply, adhesive technology specialists leveraging polymer science differentiation, and regional manufacturing scale players optimizing logistics for pro-dealer networks. Dominant competitive moves include backward integration into mineral substrates and strategic partnerships with national property management firms for vendor manual standardization.
Within the diversified materials tier, Saint-Gobain and CertainTeed Corporation exemplify integrated portfolio strategies that bundle tape specification with adjacent finishing products. Among adhesive technology specialists, 3M Company occupies a position defined by self-adhesive formulation expertise rather than gypsum-adjacent manufacturing scale. These three anchors illustrate how competitive positioning separates specification-channel controllers from component technology providers in contractor-facing procurement decisions.
| Leading Market Players |
|---|
| Saint-Gobain |
| 3M Company |
| USG Corporation |
| PPG Industries |
| Nippon Paper Industries |
| FibaTape |
| Strait-Flex |
| National Gypsum Company |
| CertainTeed Corporation |
| Others |
Value Network & Pricing Analysis
Specification bundling by pro-oriented dealer networks is compressing procurement autonomy for mid-size commercial contractors, forcing tape manufacturers to absorb logistics coordination costs or surrender margin to integrated finishing system providers. ASTM C475 performance tiering and OSHA silica compliance mandates simultaneously elevate R&D outlays and qualify premium grades for price premiums, fragmenting manufacturer margin structures between commodity paper tape and reinforced mesh formulations.
Pricing Analysis
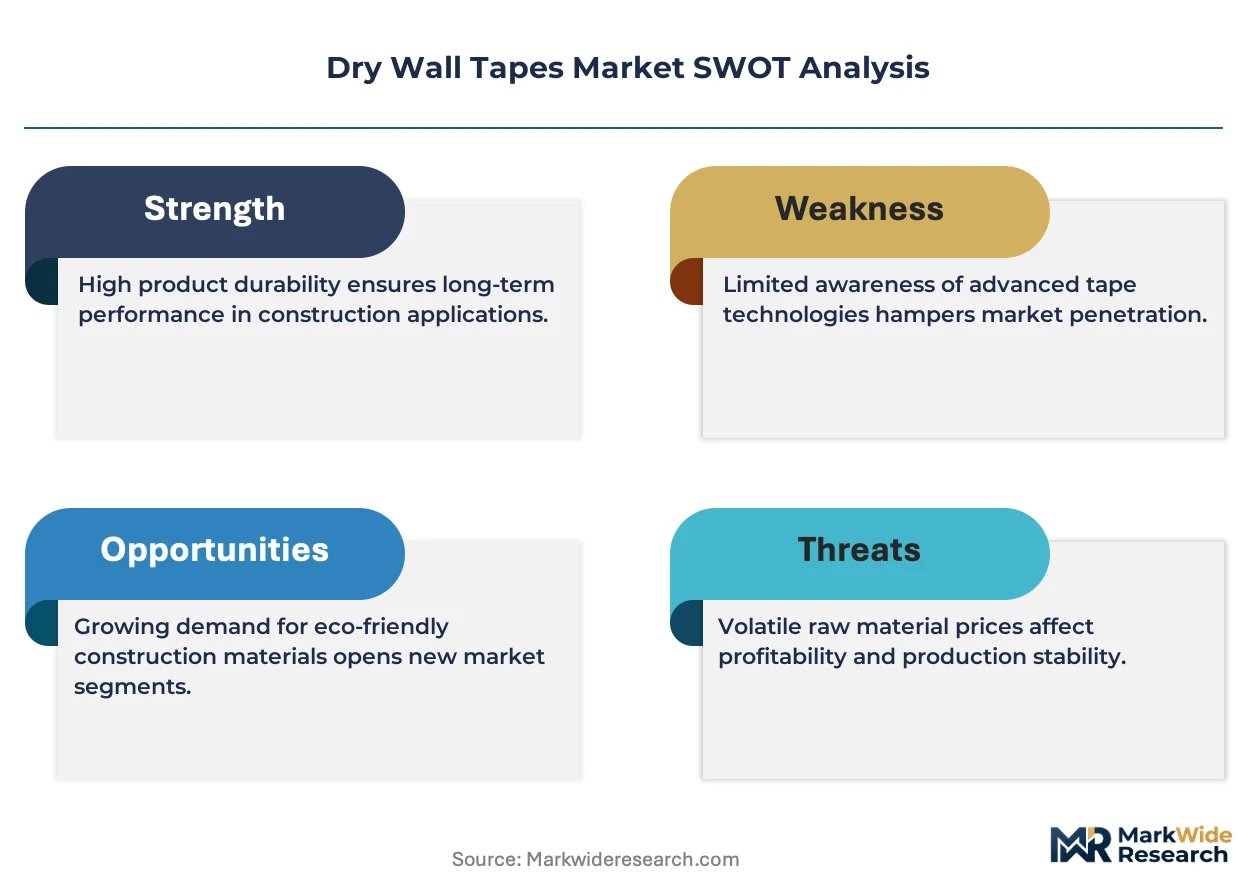
Three-tier pricing structure across premium, standard, and economy levels separates fire-rated and pre-finished specialty tapes from commodity paper grades and basic mesh products. Price differentiation hinges on certification grade—ASTM C475 commercial tier versus residential grade—and volume scale through national property management contracts. Pricing pressure stems from gypsum price volatility compressing margin stability for non-integrated producers. DIY enthusiasts exhibit highest price sensitivity, while union-trained contractors prioritize crack-resistance performance over per-foot cost.
Supply Chain Analysis
Domestic-content preferences in Texas and California municipal procurement are redirecting sourcing toward North American substrate manufacturers. Supply concentration centers on the United States, Germany, and China for kraft paper and glass fiber raw inputs. The chain draws from petrochemical feedstocks for adhesive polymers and mineral sources for gypsum-adjacent finishing materials. Single-source vulnerability in fiberglass roving supply creates exposure to energy-cost fluctuations. Distribution runs through pro-oriented dealer networks displacing traditional two-step channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry wall tapes constitute a late-cycle quality story as housing stock aging and code-cycle tightening shift contractor specification toward crack-resistant, fire-rated premium grades. EN 13963 amendments and OSHA silica frameworks reward manufacturers with pre-certified, low-dust system capabilities.
For Market Incumbents: Cement specification control through backward integration into mineral substrates and captive adhesive polymer production. Defend channel position by embedding tape specification within bundled joint compound and corner bead procurement at pro-oriented dealer networks. Counter fiberglass mesh commoditization by investing in pre-finished low-dust formulations that offset OSHA compliance costs for commercial maintenance crews. For New Entrants and Emerging Players: Launch via direct vendor manual standardization with national property management firms and large-scale retail renovation contractors. Target the repair-grade self-adhesive mesh segment where speed-to-occupancy pressures override brand loyalty and union-trained contractor concentration is weakest. Penetrate Florida and California metropolitan markets through hurricane-rated and seismic-performance tape assemblies ahead of anticipated code amendments. For Investors and Strategic Acquirers: Asymmetric upside sits with adhesive chemistry specialists possessing self-adhesive formulation IP and regional manufacturing scale players with logistics optimization for pro-dealer networks. Five-to-ten-year viability favors suppliers with ASTM C475 and EN 13963 dual-certification capabilities serving transatlantic project portfolios. Watch EN 13963 crack-resistance amendment implementation timelines across Germany and France as inflection indicators for premium grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Substrates | Captive gypsum supply insulates margin stability from input cost volatility. |
| Pre-Finished Low-Dust System Development | OSHA silica compliance creates specification premium for factory-coated tape grades. |
| Vendor Manual Standardization Partnerships | National property management firms lock in mesh tape specifications across maintenance contracts. |
| Dual-Certification Capacity Investment | ASTM C475 and EN 13963 testing protocols accelerate transatlantic commercial project access. |
| Pro-Oriented Dealer Network Expansion | Channel compression in Texas and California metros reduces project coordination overhead. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with finishing contractors, pro-dealer procurement managers, building code officials, and adhesive polymer R&D directors with secondary validation through ASTM standards documentation, EN 13963 regulatory filings, OSHA silica exposure guidelines, and construction spending databases. Customs records and gypsum industry trade data provided input cost benchmarking. Bottom-up tape consumption modeling and top-down construction activity indices were triangulated for volume reconciliation.
Comparable-period anchoring linked projection assumptions to historical renovation cycle patterns and commercial retrofit spending trajectories across the analysis window. Segmentation modeling incorporated product type, application intensity, end-user procurement scale, and packaging format dimensions. CAGRs were derived from installed base aging curves and specification velocity in code-amendment jurisdictions. Forecast inputs included union apprenticeship enrollment trends and property management firm vendor manual revision cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under gypsum price spike scenarios or accelerated EN 13963 implementation timelines. Projections reflect assumptions about contractor training pipeline continuity and silica compliance enforcement intensity. A small set of named triggers—Florida wind-load amendment passage, major property management firm consolidation events, and adhesive polymer feedstock disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Galley Tapes Market
Tapes
Coding Foils and Tapes Market
Tapes
Tissue Tapes Market
Tapes
Thread Seal Tape Market
Tapes
Application Tapes Market
Tapes
Nylon Cable Ties Market
Tapes
Freezer Tape Market
Tapes
Gaffers Tape Market
Tapes
India Reflective Tapes Market
Tapes
Utility Grade Duct Tapes Market
Tapes
Acoustic Tape Market
Tapes
Electrical Shielding Tape Market
Tapes
Holographic Tear Tape Market
Tapes
Plastic Adhesive Tapes Market
Tapes
Thermal Transfer Tapes Market
Tapes
Tapes Market