
 Global Premium Alcoholic Beverage Market | 2026-2036
Global Premium Alcoholic Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Premium Alcoholic Beverage Market Outlook
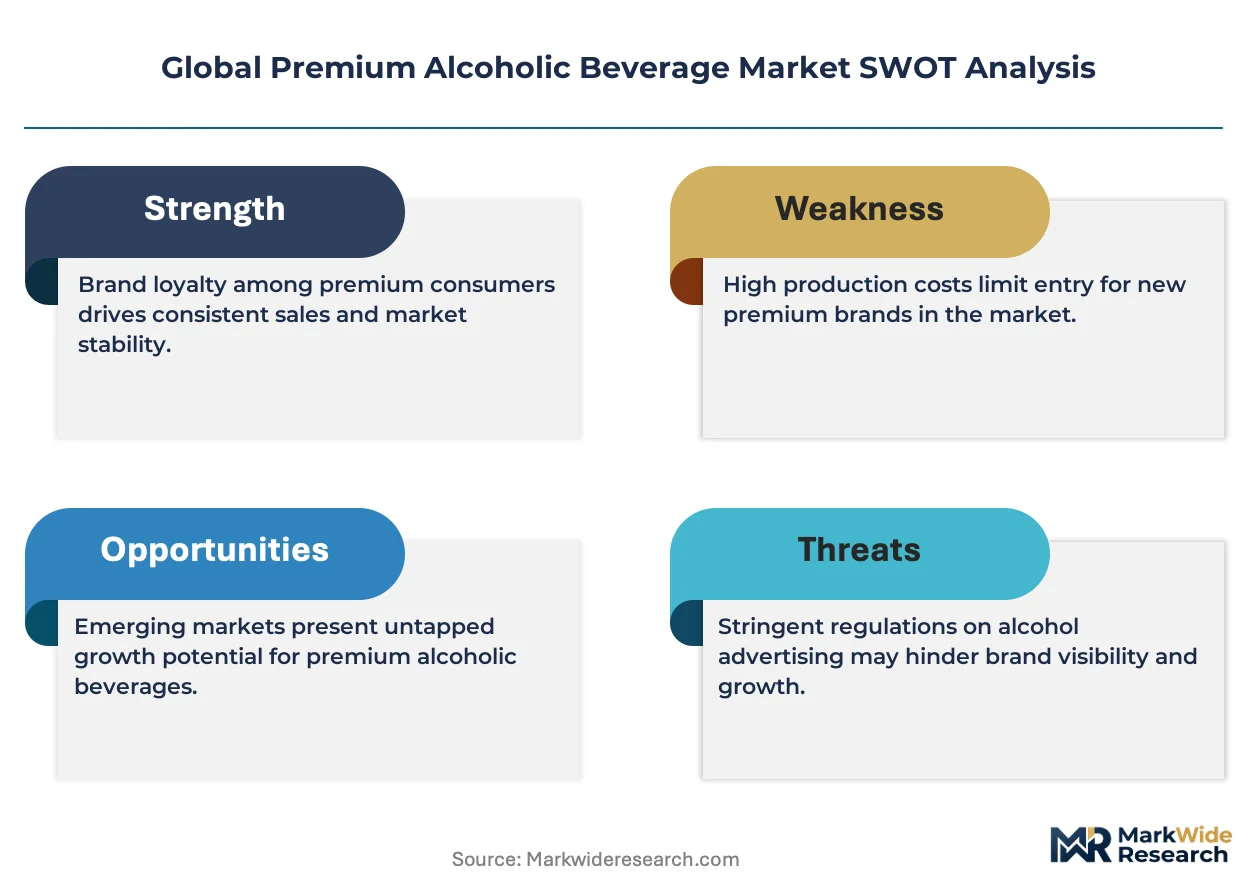
Asset-light contract distilling and third-party barrel leasing is narrowing the capital barrier for new entrants in the premium spirits arena. Diageo plc leverages its extensive aged stock reserves to sustain pricing power across super-premium whiskey tiers. Pernod Ricard S.A. anchors its competitiveness through deep vineyard and estate ownership in Cognac and Champagne. LVMH Moët Hennessy differentiates via controlled scarcity models and direct allocation to on-trade accounts.
Premium alcoholic beverages encompass distilled spirits, wines, and brewed products commanding price multiples above mass-market equivalents through extended aging protocols, provenance-limited raw materials, or small-batch production methods. These products serve ceremonial, gifting, and experiential consumption occasions where sensory differentiation and brand narrative justify elevated expenditure. Whiskey occupies the deepest margin pool among product types due to multi-decade inventory cycles and collector-driven secondary markets. Gin competes through botanical innovation and provenance storytelling, particularly in craft distilling sub-segments. Online platforms represent the fastest-expanding end-user channel as direct-to-consumer regulations loosen in select jurisdictions.
The FDA governs labeling and health claim restrictions for alcohol sold in the United States, while the EU Green Deal and REACH frameworks impose carbon accounting and packaging material compliance burdens across European production. EMA-aligned health warning standards and WHO tax recommendation benchmarks further constrain formulation and marketing latitude in multiple jurisdictions. Stakeholders must monitor evolving excise tax harmonization proposals and carbon border adjustment mechanisms that could reshape competitive cost structures.
Market Dynamics
Capital-light contract distilling is fragmenting production ownership across the premium spirits value chain, enabling new entrants to bypass multi-decade barrel aging investments while established players monetize excess inventory through white-label partnerships.
Growth Catalysts
- Direct-to-consumer regulatory relaxation:Loosened shipping laws in select US states and Australian territories enable craft distillers to bypass three-tier distribution, capturing margin previously lost to wholesale intermediaries.
- EU F-Gas Regulation compliance:Refrigeration-dependent warehousing and climate-controlled aging facilities face phasedown of hydrofluorocarbon coolants, accelerating retrofit demand for energy-efficient barrel storage infrastructure.
- Experiential hospitality clustering:Metropolitan on-trade venues in Shanghai, London, and New York are dedicating floor space to single-cask programs and tableside service rituals that command price premiums.
Market Restraints
- Oak supply concentration:French and American cooperage industries dominate premium barrel production, exposing aged-spirit producers to tariff volatility and multi-year order backlogs.
- Excise tax harmonization friction:Divergent WHO tax recommendation implementations across EU member states and US jurisdictions create arbitrage complexity for cross-border e-commerce fulfillment.
- Climate volatility in viticulture:Cognac and Champagne grape-growing regions face compressed harvest windows and alcohol accumulation challenges that threaten appellation yield consistency.
Strategic Opportunities
- Underpenetrated Indian metropolitan markets:Mumbai, Delhi, and Bangalore hospitality sectors show accelerating appetite for super-premium whiskey and single malt portfolios despite restrictive state-level distribution.
- Carbon border adjustment readiness:Early adoption of supply chain carbon accounting aligned with EU Green Deal frameworks positions exporters for preferential access as CBAM mechanisms expand.
- Non-alcoholic premium adjacencies:Distillers are leveraging botanical extraction capabilities and brand equity to capture occasion expansion in zero-proof cocktail programs at high-end venues.
Industry Challenges
- Master distiller talent scarcity:Multi-generational knowledge transfer in cask management and blending protocols faces demographic compression as retirement waves outpace apprenticeship pipeline development.
- Aged stock forecasting complexity:Twenty-plus-year inventory commitments require demand prediction across volatile macroeconomic cycles, with misalignment risking stranded capital or supply shortfalls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Premium Alcoholic Beverage Market |
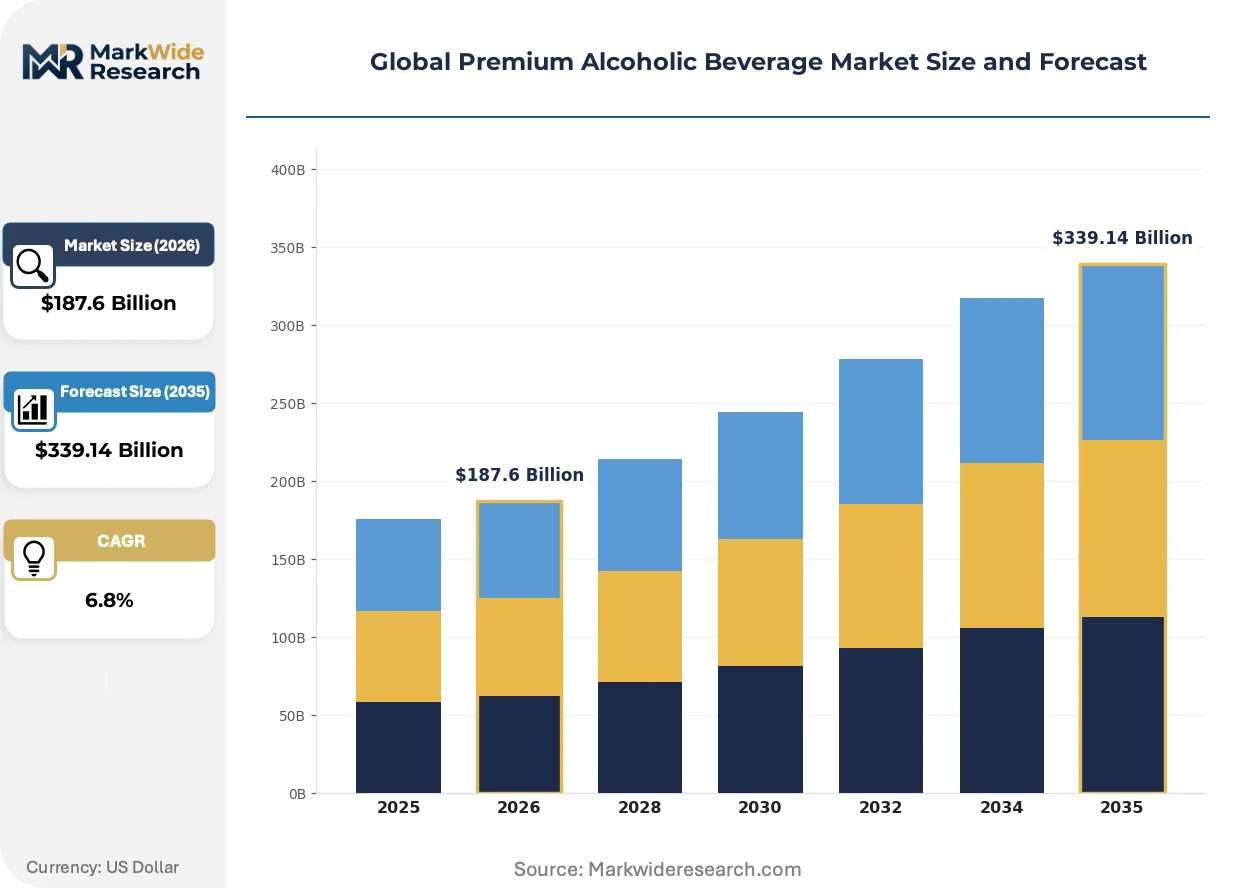
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whiskey, Vodka, Gin, Rum End User: Bars, Restaurants, Retail Outlets, Online Platforms Packaging Type: Glass Bottles, Cans, Tetra Paks, Kegs Distribution Channel: Direct Sales, Wholesale, E-commerce, Duty-Free |
| Companies Covered | Anheuser-Busch InBev, Constellation Brands, Diageo plc, Asahi Group Holdings, Brown-Forman Corporation, Pernod Ricard S.A., Heineken N.V., Campari Group, LVMH Moët Hennessy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Premium Alcoholic Beverage Market Strategic Shifts
Digital traceability infrastructure and climate-responsive production methods are reconfiguring how provenance claims are validated and how supply chains adapt to environmental constraints.
Blockchain-enabled provenance verification is hybridizing traditional paper-based cellar records with immutable ledger systems. Luxury collectors and auction houses in Hong Kong and London are piloting tokenized ownership of single casks. This technology is compressing authentication timelines and reducing fraud exposure in secondary markets.
REACH framework amendments are tightening disclosure requirements for packaging adhesives and decorative coatings used in premium gift boxes. European producers face reformulation deadlines for metallic foils and lacquers. Super-premium Champagne houses are accelerating transitions to molded pulp and glass-heavy formats that eliminate composite material complexity.
Buyers are consolidating purchasing authority through centralized procurement desks at multinational hospitality groups. Independent bar operators in Tokyo, Sydney, and Berlin are losing direct supplier relationships as group-level beverage directors negotiate global volume agreements. This concentration is visible most acutely in managed on-trade accounts where menu autonomy has narrowed.
Global Premium Alcoholic Beverage Market Segmentation
Premium alcoholic beverage producers calibrate portfolio allocation across product categories and channel structures to capture margin concentration and occasion-based consumption patterns. Segment boundaries shift as regulatory frameworks reshape distribution access and as metropolitan hospitality clusters redefine on-trade engagement models.
Product Type:
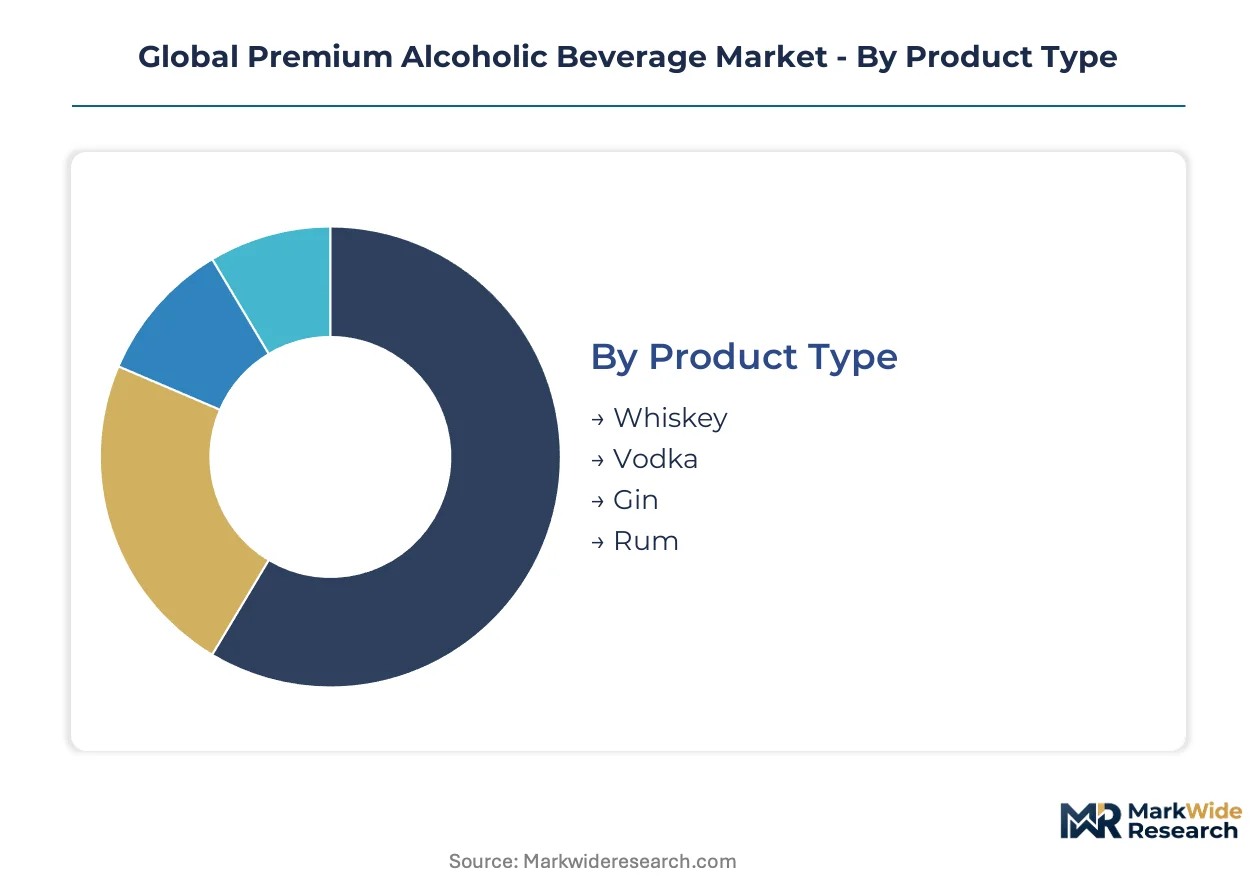
Cost tier differentiation separates inventory-intensive aged spirits from botanical-driven clear categories with compressed production cycles.
- Whiskey:Extended barrel aging protocols spanning 12-30 years create scarcity-driven pricing architecture. Collector markets in the United States, Japan, and Scotland absorb limited releases through auction channels and private allocation lists. Secondary market premiums often exceed retail multiples by factors of 5-10x for discontinued expressions.
- Gin:Botanical innovation cycles operate on 6-18 month timelines, enabling rapid flavor profile iteration. London, Barcelona, and Melbourne distilleries compete through hyper-local ingredient sourcing and terroir-specific juniper cultivars. The category captures experiential consumption occasions where provenance storytelling justifies super-premium positioning.
- Vodka:Filtration methodology and base material provenance drive differentiation in an otherwise neutral spirit category. Quartz filtration and heritage grain varieties command attention in Russian and Polish export markets.
- Rum:Solera aging systems and single-estate sugarcane sourcing anchor premium positioning. Caribbean and Latin American producers leverage appellation-like geographic indicators.
Whiskey commands the established base. The steepest expansion runs through Gin.
End User:
Application context determines pricing tolerance, with ceremonial and experiential occasions supporting the widest margins.
- Bars:Mixology-forward venues in New York, London, and Tokyo deploy tableside service rituals and single-cask programs. Beverage directors negotiate direct allocation from producers, bypassing traditional wholesale intermediaries for limited releases.
- Restaurants:Sommelier-guided pairing menus and chef-collaborative spirit dinners drive attachment rates. Michelin-tier establishments in Paris, Copenhagen, and Singapore maintain dedicated spirits programs with vertical vintage depth.
- Retail Outlets:Specialist merchants in Edinburgh, Louisville, and Cognac offer cask-strength exclusives and private barrel selections unavailable through mass retail.
- Online Platforms:Direct-to-consumer regulations in select US states and Australian territories enable craft distillers to capture margin previously surrendered to three-tier distribution. Subscription models and virtual tasting formats deepen customer lifetime value.
Restaurants anchor volume concentration. Online Platforms are climbing the fastest.
Packaging Type:
Volume and occasion mechanics dictate format selection, with single-serve and large-format options serving divergent consumption contexts.
- Glass Bottles:Heavy-base decanters and etched crystal closures signal luxury positioning in gifting channels. Champagne houses and Cognac producers invest in proprietary mold designs for shelf differentiation.
- Cans:Single-serve formats penetrate outdoor and festival occasions where glass restrictions apply. Premium wine and ready-to-drink cocktails adopt can linings that preserve aromatic integrity.
- Tetra Paks:Bag-in-box configurations serve hospitality back-of-house and large-format private events. Oxygen barrier technology extends post-opening freshness for by-the-glass programs.
- Kegs:Draught cocktails and wine-on-tap systems reduce packaging waste and accelerate pour speed in high-volume on-trade accounts. Sankey coupling standardization enables equipment interoperability.
Glass Bottles retain ceremonial dominance. Cans are gaining share fastest in outdoor occasion expansion.
Distribution Channel:
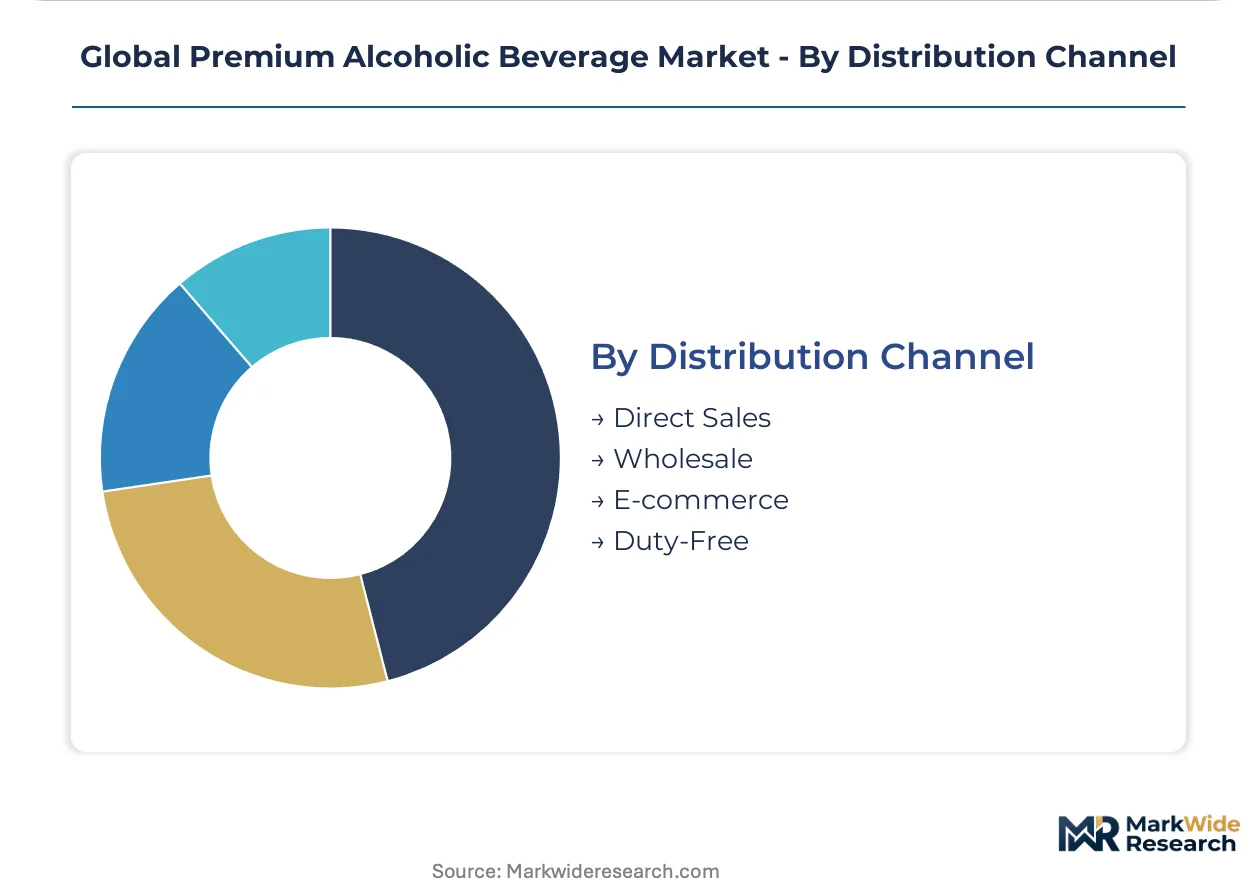
Customer type and regulatory environment shape channel economics, with control-state frameworks and duty-free zones creating divergent margin structures.
- Direct Sales:Estate visitation and membership programs capture full retail margin while building brand advocacy. Napa Valley, Speyside, and Champagne producers operate hospitality infrastructure that converts tourism into recurring purchase relationships.
- Wholesale:Three-tier system compliance in the United States and state-level distribution monopolies in India constrain route-to-market flexibility. Consolidated beverage distributors in Germany and Japan wield pricing leverage through portfolio breadth.
- E-commerce:Platform-specific fulfillment capabilities and age-verification infrastructure determine market access. Amazon, specialized spirits marketplaces, and producer-direct sites compete on delivery speed and allocation exclusivity.
- Duty-Free:Travel retail exclusives and limited editions target high-net-worth transit passengers. Dubai, Singapore, and Heathrow airports generate disproportionate volume for luxury spirits portfolios.
Wholesale maintains volume concentration. E-commerce shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation compliance deadlines and REACH packaging amendments are reshaping production infrastructure decisions across major spirits-producing jurisdictions. Distillers in France, the United States, Japan, and the United Kingdom face accelerated capital deployment timelines for warehouse climate systems and sustainable packaging transitions.
United States
Kentucky and Tennessee bourbon producers absorb rising American white oak costs while expanding single-barrel programs for metropolitan on-trade accounts. FDA labeling requirements and state-level direct-to-consumer shipping laws create fragmented regulatory terrain. Louisville and Nashville hospitality clusters now command allocated releases through direct producer relationships.
France
Cognac houses navigate compressed harvest windows in Charente-Maritime while Champagne maisons invest in molded pulp packaging to meet REACH adhesive disclosure deadlines. ANSM-aligned health warning standards constrain export label design. Paris and Reims on-trade venues dedicate floor space to vertical vintage programs and tableside service rituals.
Japan
Whiskey distilleries in Yamazaki and Yoichi face METI energy efficiency mandates for climate-controlled aging warehouses. Domestic collectors drive secondary market premiums for discontinued single malt expressions. Tokyo and Osaka bar operators negotiate direct allocation from producers, bypassing traditional wholesale channels for limited releases.
United Kingdom
Scotch producers in Speyside and Islay retrofit barrel storage facilities to comply with EU F-Gas hydrofluorocarbon phasedown requirements post-Brexit. HMRC excise frameworks and emerging carbon border adjustment mechanisms shape export cost structures. Edinburgh and London specialist merchants maintain cask-strength exclusives unavailable through mass retail.
India
Mumbai, Delhi, and Bangalore hospitality sectors show accelerating appetite for super-premium whiskey portfolios despite restrictive state-level distribution monopolies. FSSAI labeling standards and divergent excise regimes across Maharashtra, Karnataka, and the National Capital Territory complicate national rollout strategies for imported spirits.
Global Premium Alcoholic Beverage Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: integrated luxury conglomerates with estate-owned vineyard and distillery assets, multinational spirits houses with deep aged stock reserves, and regional specialists leveraging appellation-limited raw materials. Dominant competitive moves include portfolio diversification into non-alcoholic adjacencies and direct-to-consumer channel expansion where regulatory frameworks permit.
Among integrated luxury conglomerates, LVMH Moët Hennessy exemplifies controlled scarcity models through direct allocation to on-trade accounts. Diageo plc and Pernod Ricard S.A. represent the multinational spirits house archetype, with the former leveraging extensive aged stock reserves and the latter anchoring competitiveness through deep vineyard ownership in Cognac and Champagne. These three players occupy positions across super-premium whiskey, Cognac, and Champagne tiers where multi-decade inventory cycles create defensive moats.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Constellation Brands |
| Diageo plc |
| Asahi Group Holdings |
| Brown-Forman Corporation |
| Pernod Ricard S.A. |
| Heineken N.V. |
| Campari Group |
| LVMH Moët Hennessy |
| Others |
Value Chain & Pricing Dynamics
French and American cooperage industries dominate premium barrel production, concentrating oak supply in two jurisdictions and anchoring margin capture at the aged-spirit tier where multi-decade inventory cycles justify 5-10x retail multiples in secondary markets.
Pricing Analysis
Inventory maturity creates the primary spread between super-premium and entry-tier expressions, with 12-30 year aging protocols separating collector-driven price architecture from volume-oriented releases. Brand provenance and appellation-limited raw materials command secondary premiums in whiskey and Cognac, while botanical innovation cycles compress gin pricing windows to 6-18 months. Cost compression in clear spirits is intensifying as craft entrants proliferate, whereas aged categories show pricing resilience due to barrel scarcity. Mass-market buyers exhibit highest price sensitivity, while metropolitan hospitality clusters and auction collectors absorb substantial premiums for allocated releases.
Supply Chain Analysis
Heritage grain varieties and French oak staves feed from concentrated agricultural bases in the United States, France, and Scotland, with cooperage order backlogs extending to multi-year timelines. American white oak and Charente-Maritime vineyard sourcing anchor whiskey and Cognac production, while juniper cultivars from Mediterranean and Himalayan terroirs supply gin distilleries. Tariff volatility on transatlantic oak shipments poses structural risk to aged-spirit producers with committed inventory pipelines. Distribution runs through three-tier wholesale networks in the United States, state-level monopolies in India, and direct allocation relationships in Japanese and European metropolitan hospitality clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer regulatory relaxation across select US states and Australian territories is disrupting traditional three-tier distribution, creating margin recapture opportunities for craft distillers and inventory monetization channels for established houses.
For Market Incumbents: Build aged stock moats through accelerated barrel acquisition and climate-controlled warehousing investments before EU F-Gas hydrofluorocarbon phasedown deadlines tighten. Deepen direct allocation relationships with metropolitan beverage directors in Shanghai, London, and New York to defend against wholesale distributor consolidation. Secure multi-year cooperage contracts to neutralize oak supply concentration risk.
For New Entrants and Emerging Players: Build out contract distilling partnerships to bypass capital-intensive barrel aging while accessing established climate-controlled infrastructure. Target Mumbai, Delhi, and Bangalore hospitality sectors where super-premium whiskey appetite accelerates despite restrictive state-level distribution. Deploy subscription-based direct-to-consumer models where regulatory frameworks permit margin capture previously surrendered to wholesale intermediaries.
For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with appellation-limited raw material access and proven direct-to-consumer regulatory navigation. Long-term viability rests on inventory depth and hospitality channel control rather than brand marketing expenditure alone. Monitor EU carbon border adjustment mechanism expansion as signal for preferential export positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Captures margin surrendered to three-tier wholesale intermediaries in compliant US states and Australian territories. |
| Cooperage Supply Agreement | Secures multi-year French and American oak allocations before tariff volatility and order backlogs intensify. |
| Climate-Controlled Warehouse Retrofit | Ensures EU F-Gas Regulation compliance for hydrofluorocarbon phasedown in barrel aging facilities. |
| Metropolitan Hospitality Direct Allocation | Bypasses consolidated beverage distributors through relationships with group-level beverage directors. |
| Non-Alcoholic Premium Adjacency | Leverages botanical extraction capabilities for zero-proof cocktail programs at high-end venues. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs records, SEC filings, and regulatory frameworks across FDA, EMA, and EU Green Deal documentation. Interviews with master distillers, beverage directors at multinational hospitality groups, cooperage procurement managers, and state-level distribution regulators informed supply chain and pricing dynamics assessment. Secondary validation drew from excise tax databases, auction house transaction records, and climate volatility projections for viticulture regions. Bottom-up triangulation across producer-level inventory data and top-down reconciliation against trade flow statistics ensured consistency.
Forecast inputs span product type segmentation across whiskey, gin, vodka, and rum; end-user channels including bars, restaurants, retail, and online platforms; and packaging format differentiation. CAGRs were derived through trend extrapolation adjusted for regulatory inflection points and channel shift velocities. The modeling period incorporates EU F-Gas compliance deadlines, direct-to-consumer shipping law relaxation trajectories, and carbon border adjustment mechanism expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated luxury conglomerates or craft distiller collectives would shift outcomes. Quarterly review of cooperage order backlogs, metropolitan hospitality allocation patterns, and excise tax harmonization proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
US Wine Cooler Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Asia Pacific Beer Market
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
US Alcohol E-Commerce Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Beer Dispensing Machine Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Low Alcohol Beverages Market
Alcoholic Beverages
Wine Cellar Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market