
 Gluten-Free Beer Market | 2026-2036
Gluten-Free Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Beer Market Outlook
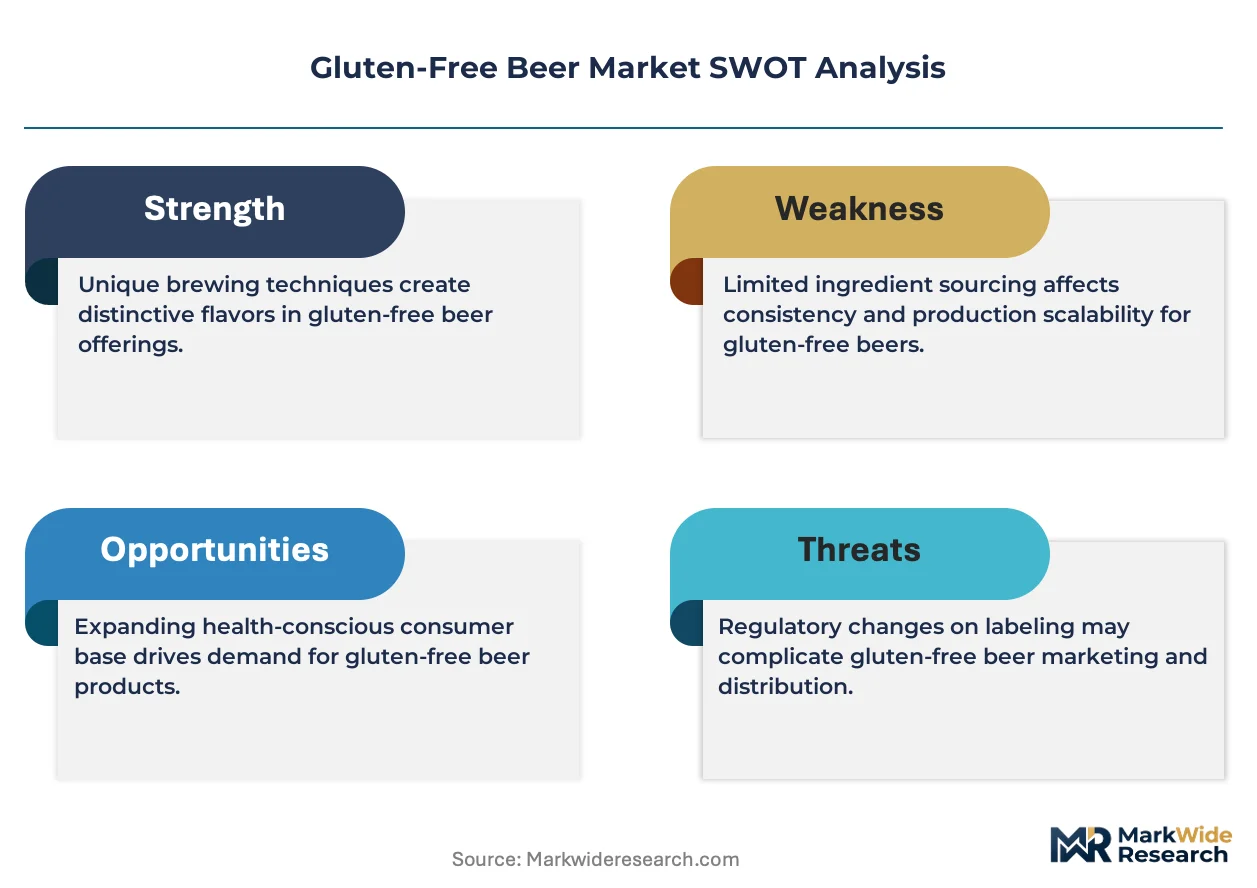
Restaurant and bar adoption is broadening as celiac-aware menus expand across hospitality chains. Ghostfish Brewing Company leverages Pacific Northwest sourcing to anchor its specialty grain supply chain. Anheuser-Busch InBev sustains mass-market reach through scaled sorghum-based production lines. New Belgium Brewing Company differentiates via certified gluten-free facility investments that command premium shelf placement.
Gluten-free beer denotes fermented malt beverages brewed without wheat, barley, or rye, typically substituting rice, millet, or sorghum as fermentable starches and requiring enzymatic protocols to achieve sub-20 ppm gluten thresholds. Craft beer commands margin pools through terroir storytelling and small-batch pricing, while lager competes on volume accessibility in conventional retail. Sorghum-based formulations lead ingredient innovation due to drought-resilient supply chains, though rice dominates current output scale.
The FDA enforces gluten-free labeling thresholds below 20 ppm, compelling brewery facility segregation and third-party certification costs. The USDA oversees organic adjunct sourcing claims that intersect with ingredient transparency trends. Brewers must monitor evolving celiac association certification standards and state-level alcohol distribution franchise laws that constrain direct-to-consumer channel expansion.
Market Dynamics
Facility segregation mandates under the FDA's gluten-free labeling rule are compressing brewery capital allocation, forcing dedicated equipment investments that reshape competitive economics across production scales.
Growth Catalysts
- Celiac-Aware Menu Expansion:Hospitality chains in Germany and the United States are integrating certified gluten-free taps, creating pull-through demand for keg-format supply contracts.
- REACH-Compliant Adjunct Sourcing:European maltsters are certifying sorghum and millet supply chains under ECHA chemical safety protocols, reducing cross-contamination liability for brewers.
- Enzymatic Gluten Reduction:Brewers employing Brewers Clarex and similar protease protocols are achieving sub-20 ppm thresholds without facility segregation, lowering barrier-to-entry for craft entrants.
Market Restraints
- Sorghum Supply Concentration:Drought-resilient grain sourcing clusters in the Texas High Plains and Nigerian savanna, exposing price volatility to regional weather shocks.
- Third-Party Certification Costs:Gluten Intolerance Group and Celiac Association facility audits impose recurring fees that disproportionately burden sub-10,000 barrel producers.
- Flavor Profile Limitations:Rice-based formulations lack the protein backbone for stable head retention, constraining acceptance among lager-traditionalist demographics.
Strategic Opportunities
- Direct-to-Consumer Channel Expansion:Brewery taprooms in Colorado and Oregon are leveraging state-level franchise law exemptions to bypass three-tier distribution markups.
- Organic Adjunct Certification:USDA organic sorghum sourcing commands shelf placement premiums in Whole Foods and Sprouts regional sets.
- Canning Line Convergence:Mobile canning services are reducing packaging capex for gluten-free-only facilities, enabling geographic arbitrage into underserved Mountain West markets.
Industry Challenges
- Cross-Contamination Protocol Talent:Breweries face scarcity of quality managers trained in HACCP-adjacent gluten segregation procedures.
- Dual-Certification Timeline Compression:Simultaneous pursuit of FDA compliance and organic certification creates documentation bottlenecks extending launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Beer Market |
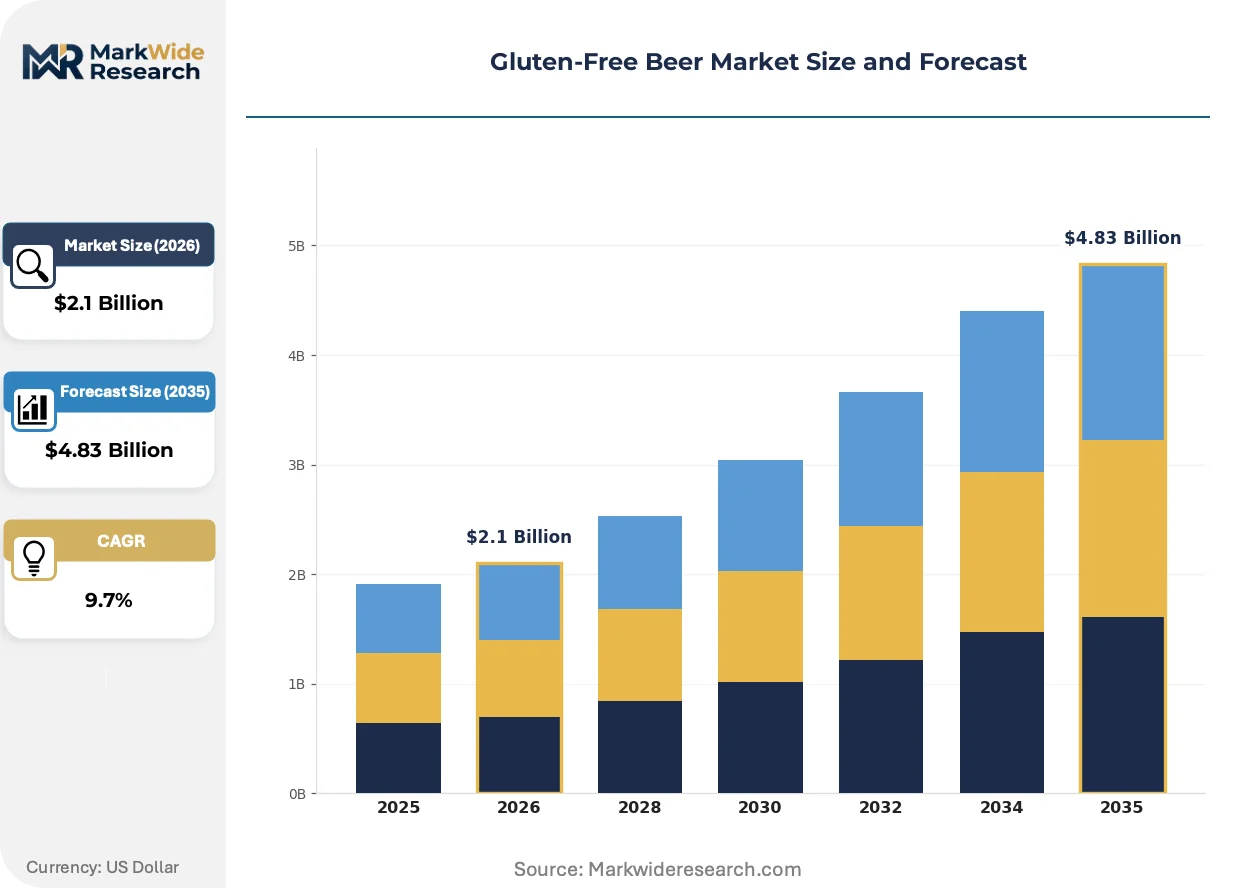
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Craft Beer, Lager, Ale, Stout Ingredients: Rice, Corn, Millet, Sorghum Packaging Type: Bottle, Can, Keg, Draft Distribution Channel: Retail Stores, Online Stores, Breweries, Restaurants |
| Companies Covered | Ghostfish Brewing Company, Lakefront Brewery, Anheuser-Busch InBev, Omission Brewing, New Belgium Brewing Company, Glutenberg, Holidaily Brewing Company, Bell's Brewing, Ground Breaker Brewing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Beer Market Strategic Shifts
Enzymatic processing advances are collapsing the traditional trade-off between facility purity and production flexibility, while regulatory harmonization efforts across North America and Europe are reshaping certification economics.
Protease-based gluten reduction is converging with conventional brewing infrastructure, allowing multi-product facilities to switch between standard and gluten-free batches within single production cycles. Mid-size regional brewers in the Pacific Northwest are adopting this hybrid protocol to avoid dedicated facility capex. The technology is converging with legacy equipment depreciation schedules, extending asset life for brewers facing margin compression.
The FDA's 20 ppm gluten-free labeling threshold, mirrored by Health Canada's equivalent standard, is creating transatlantic regulatory alignment that simplifies export documentation for North American producers. Breweries achieving dual certification are securing placement in Canadian provincial liquor board listings previously blocked by standard-specific import barriers. Craft producers in Vermont and Quebec are responding by pooling third-party audit costs through cooperative certification arrangements.
Restaurant procurement teams are unbundling beverage programs from broadline distributors, establishing direct relationships with gluten-free specialists to secure menu differentiation. Foodservice operators in Minneapolis and Portland are replacing legacy beer portfolios with rotating tap commitments from certified-only breweries. This pattern concentrates in urban markets where celiac association chapter density correlates with consumer education levels and willingness-to-pay premiums.
Gluten-Free Beer Market Segmentation
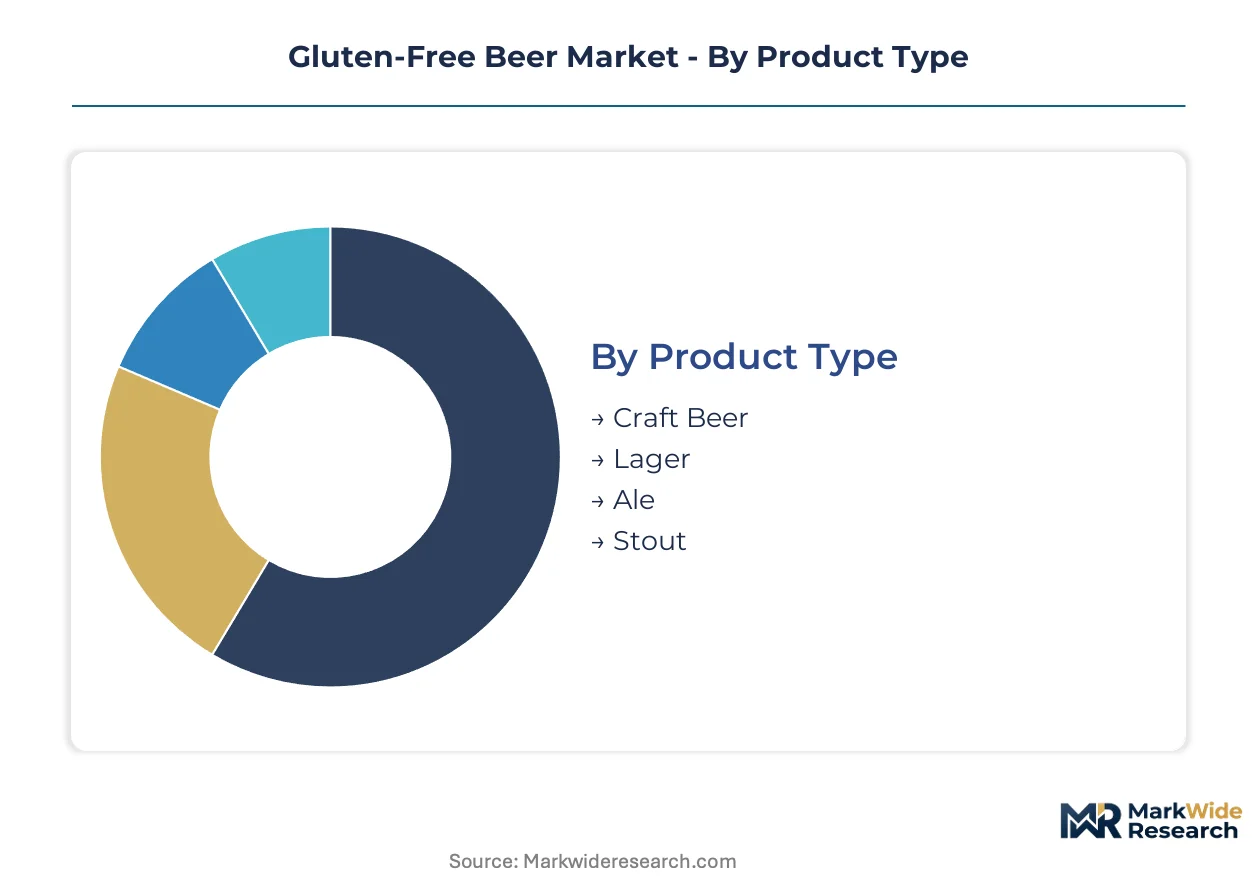
Gluten-free beer segmentation reveals divergent margin economics across production methods and channel access. Ingredient sourcing constraints and facility certification requirements reshape competitive boundaries within each category.
Product Type:
Buyers in this category separate by price tolerance and occasion-based consumption patterns rather than traditional style loyalty.
- Craft Beer:Small-batch production using specialty grains like buckwheat and quinoa commands taproom premiums. Demand concentrates in Portland and Denver where celiac association chapter density supports direct-to-consumer pricing power.
- Lager:Sorghum-based formulations dominate mass-market shelf placement through scaled fermentation protocols. German Reinheitsgebot-adjacent purity expectations drive ingredient transparency requirements in Bavaria and North Rhine-Westphalia.
- Ale:Top-fermented rice and millet variants serve pub-format consumption with shorter production cycles.
- Stout:Roasted buckwheat and chestnut adjuncts replicate dark malt profiles for winter seasonal releases.
Craft beer leads volumes today; lager is gaining share fastest through grocery channel expansion.
Ingredients:
Raw material selection determines supply chain resilience and cross-contamination risk exposure for brewers.
- Rice:Domestic sourcing from Arkansas and California delta regions anchors current output scale. FDA facility segregation mandates compress margins for rice-dependent producers lacking dedicated gluten-free infrastructure.
- Sorghum:Drought-resilient grain from Texas High Plains and Nigerian savanna enables climate-adaptive sourcing. REACH-compliant European maltsters are certifying sorghum supply chains under ECHA chemical safety protocols.
- Corn:High-fructose syrup adjacency creates consumer perception challenges in premium positioning.
- Millet:Ancient grain narratives support organic certification premiums in Sprouts and Whole Foods regional sets.
Rice dominates current production scale; sorghum shows the steepest expansion trajectory as climate volatility intensifies.
Packaging Type:
Format choice reflects channel strategy and margin preservation under distribution law constraints.
- Can:Mobile canning services reduce packaging capex for dedicated gluten-free facilities. Colorado and Oregon taprooms leverage state franchise law exemptions to bypass three-tier markups via direct can sales.
- Bottle:Amber glass dominates import positioning for German and Belgian heritage brands.
- Keg:Hospitality chains in Minneapolis integrate certified gluten-free taps through direct brewery relationships.
- Draft:Rotating tap commitments from certified-only breweries replace legacy beer portfolios in Portland foodservice.
Can format leads volume growth; keg shows strongest foodservice penetration.
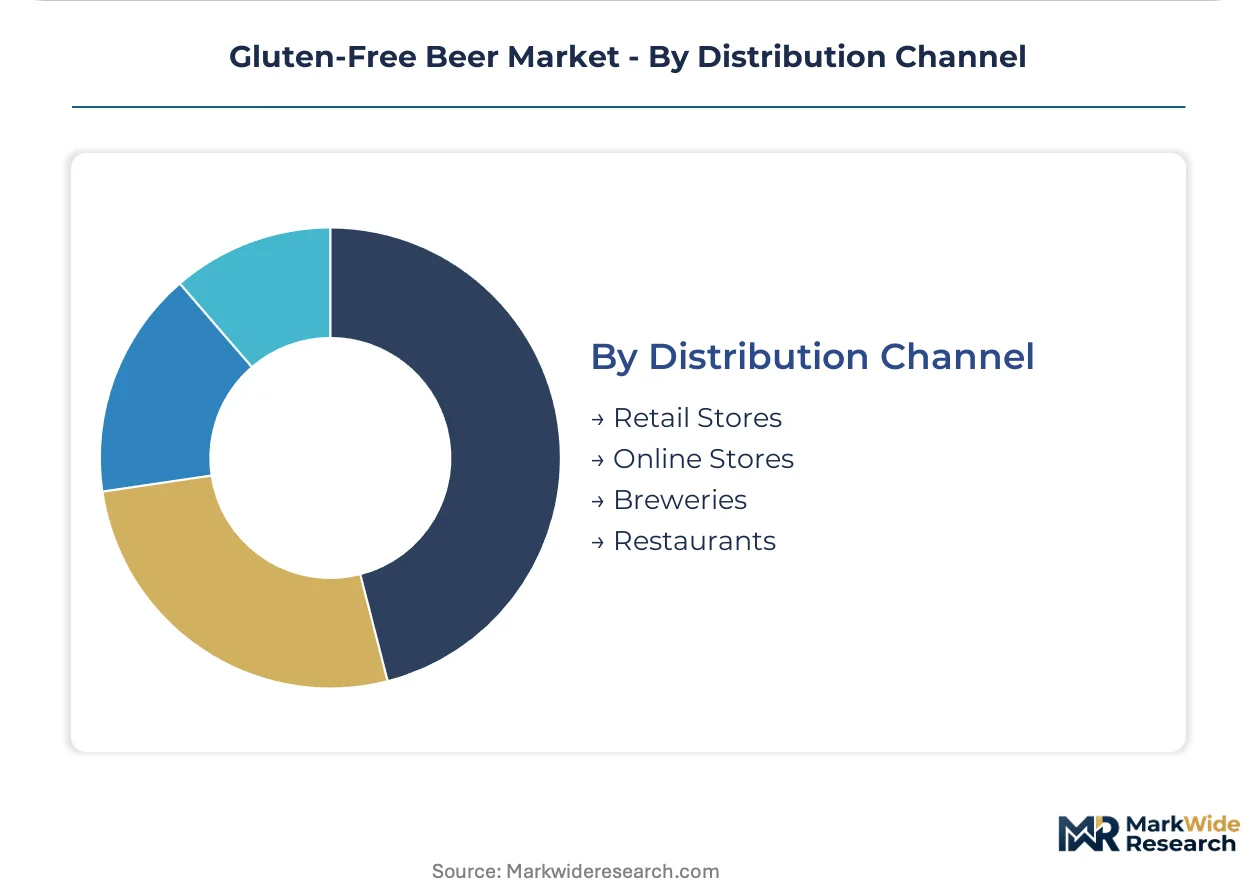
Distribution Channel:
Channel selection determines certification burden and consumer education requirements.
- Retail Stores:Shelf placement premiums require Gluten Intolerance Group or Celiac Association facility audits. USDA organic sorghum sourcing commands position in natural grocery sets.
- Restaurants:Celiac-aware menu expansion drives keg-format supply contracts with direct brewery procurement.
- Breweries:Taproom direct sales capture highest margins under state-level franchise law exemptions.
- Online Stores:Subscription models face interstate shipping compliance complexity for alcohol distribution.
Retail stores anchor volume today; restaurants are climbing the fastest through menu integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling production toward jurisdictions with streamlined certification pathways. Breweries in countries with mutual recognition agreements between FDA and Health Canada are consolidating cross-border supply chains to amortize audit costs across larger addressable markets.
United States
Celiac association chapter density in Portland and Denver sustains direct-to-consumer pricing power for craft specialists. The FDA's 20 ppm gluten-free labeling threshold mandates facility segregation protocols that compress margins for sub-10,000 barrel producers. Pacific Northwest brewing clusters in Seattle and Portland are adopting enzymatic gluten reduction to avoid dedicated facility capex.
Germany
Reinheitsgebot-adjacent purity expectations drive demand for ingredient transparency in Bavaria and North Rhine-Westphalia. ECHA REACH compliance requirements for sorghum and millet supply chains reduce cross-contamination liability exposure. Munich and Hamburg host the densest concentrations of certified gluten-free tap installations across hospitality chains.
Canada
Health Canada's equivalent 20 ppm standard creates transatlantic regulatory alignment with FDA protocols. Provincial liquor board listings in Ontario and British Columbia previously blocked by standard-specific import barriers now accept dual-certified North American producers. Quebec craft brewers are pooling third-party audit costs through cooperative certification arrangements.
Australia
Coeliac Australia certification standards intersect with TGA food labeling requirements to create dual compliance burdens. Melbourne and Sydney restaurant procurement teams are unbundling beverage programs from broadline distributors to secure certified-only rotating taps. Drought-resilient sorghum sourcing from Queensland grain belts anchors climate-adaptive supply chains.
United Kingdom
Coeliac UK awareness campaigns drive menu integration across London and Manchester hospitality chains. FSA guidance on gluten-free claims enforcement shapes brewery investment in dedicated canning lines. Scottish craft producers in Edinburgh and Glasgow are leveraging mobile canning services to reduce packaging capex for geographic expansion.
Gluten-Free Beer Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with dedicated gluten-free facilities commanding shelf placement premiums while enzymatic processors compete on volume accessibility. The vendor base organizes around three archetypes: certified-only craft specialists with taproom direct sales, mass-market brewers with scaled sorghum production lines, and hybrid facilities employing protease protocols for batch flexibility. Dominant competitive moves include state-level franchise law arbitrage for direct-to-consumer channel expansion and cooperative third-party audit cost pooling among regional craft collectives.
Within the certified-facility tier, Ghostfish Brewing Company and New Belgium Brewing Company exemplify divergent scale strategies. Anheuser-Busch InBev occupies a position at the mass-market vector with sorghum-based production infrastructure. These three anchors illustrate how capital allocation between dedicated facility investments and enzymatic processing capabilities is reshaping competitive economics across production scales.
| Leading Market Players |
|---|
| Ghostfish Brewing Company |
| Lakefront Brewery |
| Anheuser-Busch InBev |
| Omission Brewing |
| New Belgium Brewing Company |
| Glutenberg |
| Holidaily Brewing Company |
| Bell's Brewing |
| Ground Breaker Brewing |
| Others |
Value Chain & Pricing Dynamics
Sorghum procurement costs from Texas High Plains and Nigerian savanna flow through three-tier pricing structures separating certified-facility premiums from enzymatic-processed volume tiers, with distributor markups compressing margins for sub-scale craft producers lacking direct-to-consumer exemptions.
Pricing Analysis
Three-tier markups from broadline distributors through retail grocers to on-premise accounts stratify pricing across certified gluten-free, enzymatic-reduced, and imported heritage tiers. Certification level from Gluten Intolerance Group or Celiac Association drives shelf placement premiums, while volume scale determines access to mobile canning services that bypass packaging capex. Pricing pressure stems from sorghum supply volatility tied to regional drought patterns, with hospitality chains exhibiting lowest price sensitivity due to menu differentiation value and mass-market retailers demanding promotional support.
Supply Chain Analysis
Certification gating through FDA facility segregation mandates and ECHA REACH-compliant European maltster protocols concentrates qualified supply among dedicated gluten-free producers in Germany, the United States, and Canada. Raw material flows draw from Arkansas rice deltas, Texas sorghum belts, and Queensland grain regions, with cross-contamination liability creating single-source vulnerability for specialty grain inputs. Distribution runs through three-tier alcohol franchise systems constrained by state-level exemptions in Colorado and Oregon that enable taproom direct sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facility segregation costs in the United States run triple those under Health Canada equivalency agreements, creating arbitrage opportunity for dual-certified producers amortizing audit expenses across North American provincial liquor board listings.
For Market Incumbents: Anticipate enzymatic processing adoption by mid-size regional brewers as a margin compression threat, and respond through backward integration into sorghum sourcing from drought-resilient supply clusters. Secure capacity expansion in jurisdictions with mutual FDA-Health Canada recognition to consolidate cross-border certification economics. Defend taproom channel control through state franchise law lobbying that preserves direct-to-consumer exemptions.
For New Entrants and Emerging Players: Foodservice procurement teams unbundling beverage programs from broadline distributors represent the most penetrable channel entry point. Target rotating tap commitments in Portland and Minneapolis where celiac association chapter density supports premium pricing. Pursue cooperative certification arrangements with regional craft collectives to distribute third-party audit burdens.
For Investors and Strategic Acquirers: Consolidation pressure builds where sub-10,000 barrel producers face disproportionate certification cost burdens relative to scalable enzymatic processors. Long-term viability favors dual-certified assets with Health Canada-FDA alignment and established keg-format hospitality contracts. Watch enzymatic gluten reduction patent filings as signal of technology-driven margin compression timeline.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Facility Investment | FDA segregation mandates command shelf placement premiums in natural grocery sets. |
| Enzymatic Processing Adoption | Brewers Clarex protocols collapse dedicated facility capex requirements for craft entrants. |
| Direct-to-Consumer Channel Expansion | Colorado and Oregon franchise exemptions bypass three-tier distribution markups. |
| Cooperative Certification Pooling | Quebec and Vermont craft collectives distribute third-party audit cost burdens. |
| Climate-Adaptive Sourcing | Texas High Plains sorghum supply chains reduce exposure to drought-driven price volatility. |
Study Parameters
Coverage spans North America, Europe, and Australia-Pacific, with primary inputs from each combining interviews with brewery operations directors, celiac association certification officers, hospitality procurement managers, and specialty grain maltsters alongside secondary validation from FDA labeling guidance documents, Health Canada food standards, ECHA REACH substance databases, and provincial liquor board import listings. Bottom-up volume triangulation against top-down category spend estimates anchors market sizing.
Rate-of-change decomposition across the projection horizon segments volume and value by product type, ingredient source, packaging format, and distribution channel, with CAGRs derived from regression analysis against celiac diagnosis prevalence, restaurant menu integration rates, and certification facility buildout timelines. Sorghum supply elasticity and enzymatic processing adoption curves feed industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization progress between FDA and Health Canada protocols, climate volatility impacts on specialty grain yields, and franchise law exemption revisions in key taproom states. A model refresh is warranted upon material change in enzymatic gluten reduction patent litigation or ECHA REACH substance restriction expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Champagne Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market
Alcoholic Beverages
Coconut Alcohol Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Lager Market
Alcoholic Beverages
Electrolyte Beer Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Gin Market
Alcoholic Beverages
Irish Whiskey Market
Alcoholic Beverages
Beer Kegs Market