
 Asia Pacific Beer Market | 2026-2036
Asia Pacific Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Beer Market Analysis
Market Context
The on-trade channel is fragmenting across Asia Pacific as traditional bars and restaurants lose share to direct-to-consumer platforms and specialty craft taprooms. Anheuser-Busch InBev leverages its scale to secure shelf space in modern retail formats across Southeast Asia. Tsingtao Brewery anchors its position through deep distribution networks in China's provincial capitals. Kirin Holdings Company differentiates via premium positioning in Japan's convenience store channel.
Technical and Segment Structure
Beer is a fermented alcoholic beverage produced from malted cereal grains, hops, yeast, and water, typically brewed through mashing, boiling, fermentation, and conditioning processes at alcohol concentrations ranging from 4% to 6% ABV for standard lagers. Lager dominates volume across Asia Pacific due to its crisp profile suiting tropical climates, while ale and stout segments capture margin in premium urban outlets. Can packaging is expanding fastest as breweries target outdoor consumption and e-commerce logistics, whereas keg demand tracks the recovery of bars and restaurants in post-restriction markets.
Regulatory Outlook
China's SAMR enforces GB standards on labeling and alcohol content, while India's FSSAI mandates nutritional disclosure and advertising restrictions that reshape brand communication strategies. Japan's METI oversees container recycling laws affecting packaging material choices across the supply chain. Stakeholders must monitor evolving excise structures and digital sales regulations as governments balance revenue collection with public health objectives.
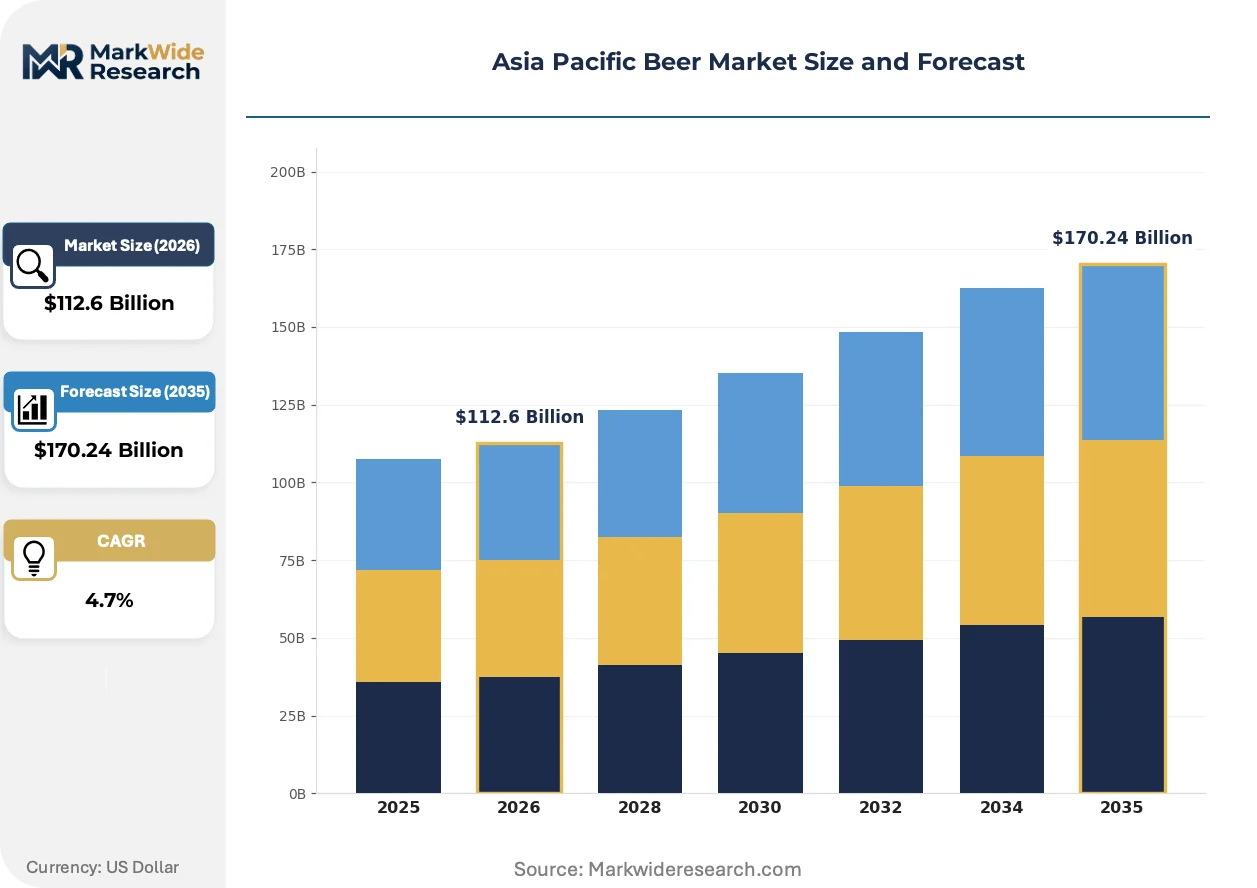
Market Dynamics
Channel fragmentation across Asia Pacific is compressing traditional on-trade margins while direct-to-consumer platforms and specialty craft taprooms capture volume and consumer data simultaneously.
Growth Catalysts
- Thailand's premium craft shift:Young adult consumers in Bangkok and Chiang Mai are trading mass-market lagers for locally brewed ales and IPAs, expanding addressable margin pools for regional brewers.
- India's FSSAI labeling clarity:Standardized nutritional disclosure mandates are reducing information asymmetry, enabling premium positioning through transparent ingredient storytelling.
- Can packaging automation:High-speed aluminum filling lines are reducing per-unit logistics costs, unlocking e-commerce and outdoor consumption channels previously constrained by glass bottle weight.
Market Restraints
- Malted barley import dependence:Australian and Canadian grain supply volatility exposes Vietnamese and Indonesian brewers to input cost swings and currency mismatch risks.
- China's GB standards compliance:SAMR-mandated alcohol content disclosure and labeling precision requirements are extending product development timelines and raising quality assurance overhead.
- Non-alcoholic beverage substitution:Functional drinks and premium soft beverages are capturing occasions previously dominated by sessionable lagers in health-conscious urban demographics.
Strategic Opportunities
- Vietnam's underpenetrated provincial cities:Da Nang, Hai Phong, and Can Tho lack dedicated craft distribution, creating first-mover whitespace for taproom-forward entrants.
- India's metropolitan corridor expansion:Hyderabad, Pune, and Ahmedabad exhibit rising disposable income without proportional premium beer penetration.
- Japan's METI container recycling incentives:Lightweight aluminum and biodegradable packaging innovations qualify for regulatory credits, reducing effective material costs.
Industry Challenges
- Master brewer talent scarcity:Asia Pacific lacks sufficient trained personnel in traditional ale and wild fermentation techniques, constraining craft segment expansion.
- Cold chain capex intensity:Maintaining 2-4°C integrity from brewery to convenience store requires refrigerated fleet investment that strains mid-tier operator balance sheets.
- Dual certification complexity:Navigating simultaneous FSSAI, GB standards, and METI compliance creates documentation bottlenecks for multi-country portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Beer Market |
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $170.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lager, Ale, Stout, Porter Packaging Type: Bottle, Can, Keg, Growler Distribution Channel: Supermarkets, Convenience Stores, Bars, Restaurants Customer Type: Consumers, Wholesalers, Retailers, Distributors |
| Companies Covered | Carlsberg Group, China Resources Holdings, Anheuser-Busch InBev, Beijing Yanjing Brewery, Tsingtao Brewery, Asahi Group Holdings, Kirin Holdings Company, San Miguel Corporation, Heineken NV, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Beer Market Emerging Trajectories
Brewing technology and regulatory frameworks are converging to reshape how beer reaches consumers across Asia Pacific, with packaging innovation and channel restructuring dominating capital allocation decisions.
Flash pasteurization and aseptic cold-filling technology is collapsing the shelf-life gap between draft and packaged beer, enabling breweries to distribute unpasteurized craft products through retail without keg infrastructure. Japanese and South Korean convenience store chains are adopting these systems fastest, compressing the traditional three-tier distribution model into direct brewery-to-retailer relationships. This structural compression is eliminating wholesaler margins and redirecting value capture toward production and retail endpoints.
China's SAMR is tightening GB standards enforcement on alcohol content accuracy and nutritional labeling, requiring laboratory-grade testing equipment across all production facilities. Breweries must now maintain in-house chromatography capabilities or contract third-party verification, raising fixed cost structures disproportionately for smaller operators. The compliance burden is heaviest in tier-one cities where inspection frequency and consumer litigation risk concentrate.
Digital native consumers are bypassing traditional bar and restaurant channels through subscription-based direct-to-consumer platforms, unbundling the social experience from the purchase occasion. Specialty craft taprooms in Ho Chi Minh City and Bangkok are responding by integrating on-site brewing visibility with membership programs, converting transactional buyers into recurring revenue relationships. This behavioral shift is most pronounced among 25-35 year old urban professionals with limited brand loyalty to established multinational portfolios.
Asia Pacific Beer Market Segmentation
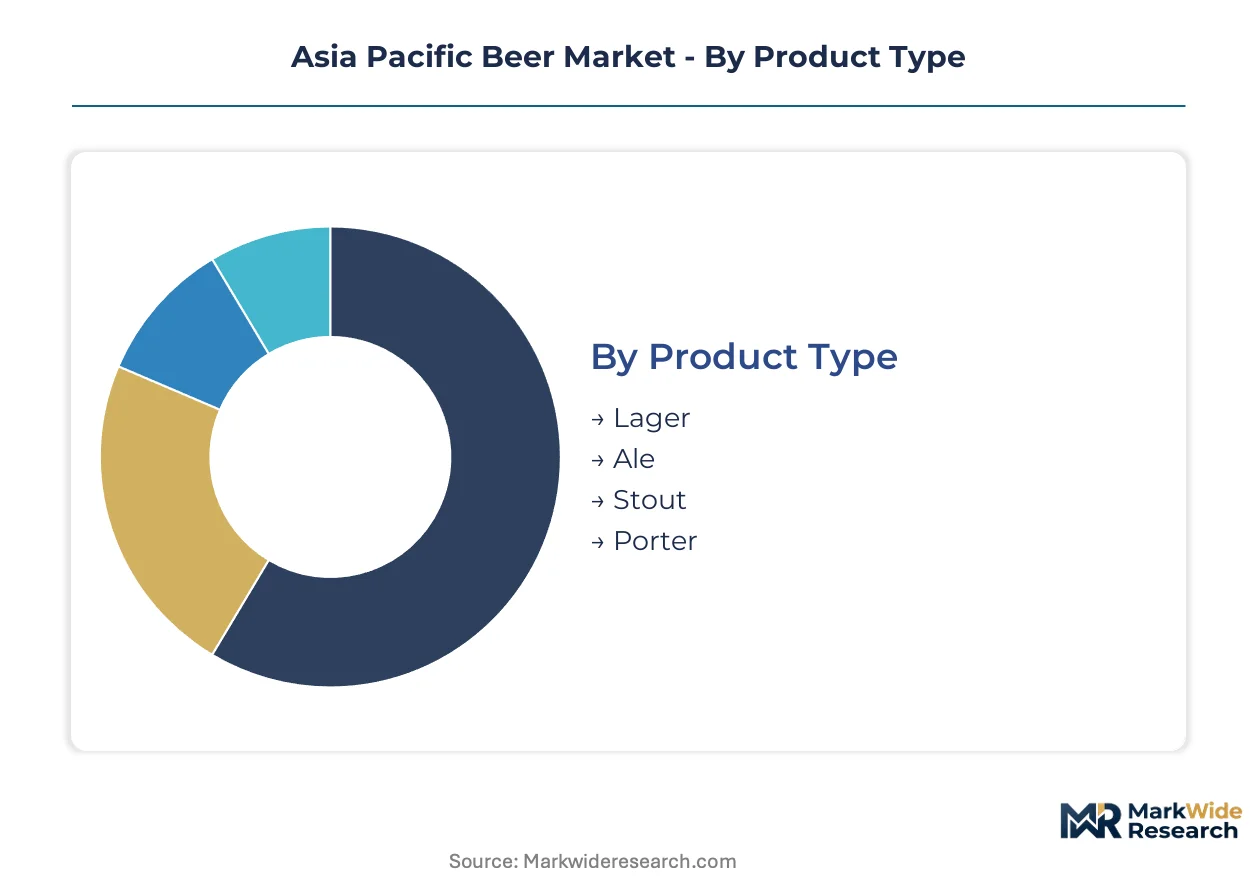
Segmentation in the Asia Pacific beer market determines capital allocation across divergent margin profiles. Product type dictates brewing complexity and shelf stability requirements. Packaging and channel choices reshape logistics networks and consumer access points.
Product Type:
After-sales service intensity varies sharply across fermentation categories, with live culture ales requiring cold chain maintenance that lagers do not.
- Lager:Bottom-fermented at cooler temperatures producing crisp, highly carbonated profiles suited to tropical climates. Demand concentrates in Vietnam's outdoor dining corridors and Thailand's beach tourism zones where sessionability drives volume. Mass-market pricing and extended shelf stability support broad distribution reach.
- Ale:Top-fermented with warmer fermentation cycles yielding fruit-forward ester profiles. India's metropolitan corridors and Japan's craft-focused urban districts exhibit concentrated demand as consumers trade up from standardized lagers. Shorter freshness windows necessitate localized production or premium logistics infrastructure.
- Stout:Dark roasted malt character with higher gravity profiles. Niche positioning in specialty bars across Singapore and Hong Kong.
- Porter:Historical English style with moderate roast complexity. Limited penetration outside expatriate-dense districts in major Asian capitals.
By volume, Lager leads. By growth pace, Ale is ahead.
Packaging Type:
Cost tier stratification separates premium positioning from mass-market accessibility across material choices.
- Can:Aluminum containers with superior light protection and logistics efficiency. E-commerce platforms across China and outdoor consumption occasions in Southeast Asia are driving adoption. Automated high-speed filling lines reduce per-unit production costs at scale.
- Bottle:Glass packaging maintaining traditional premium associations. On-trade recovery in post-restriction markets like Japan and South Korea sustains demand despite weight disadvantages.
- Keg:Stainless steel returnable containers for draft service. Bars and restaurants in Australia's metropolitan zones anchor demand as hospitality rebuilds.
- Growler:Refillable vessels for direct brewery sales. Craft taprooms in Ho Chi Minh City and Bangkok utilize growler programs to build recurring customer relationships.
By volume, Bottle retains dominance. By expansion trajectory, Can is climbing the fastest.
Distribution Channel:
Application-specific channel strategies align product formats with consumption occasion timing and social context.
- Supermarkets:Large-format retail with extended SKU breadth. China's tier-one cities and India's organized retail corridors concentrate volume as modern trade expands.
- Convenience Stores:High-frequency purchase points with chilled single-serve availability. Japan's 7-Eleven and Lawson networks set the regional standard for refrigerated beer placement.
- Bars:On-premise draft and bottle service with experiential positioning. Bangkok and Singapore's nightlife districts sustain premium pricing power.
- Restaurants:Food-paired consumption with localized menu integration. Vietnam's bia hoi street culture and South Korea's hof chains demonstrate occasion-specific volume concentration.
By volume, Supermarkets lead. By margin expansion, Bars are gaining share fastest.
Customer Type:
Volume concentration versus margin capture splits across buyer categories with divergent negotiation leverage.
- Consumers:End purchasers making individual transaction decisions. Digital-native demographics in urban India and Vietnam bypass traditional retail through direct-to-consumer platforms.
- Wholesalers:Intermediary aggregators managing multi-brand portfolios. Regulatory fragmentation across FSSAI, GB standards, and METI compliance zones raises operational complexity for cross-border wholesalers.
- Retailers:Point-of-sale operators controlling shelf placement and chilled display. Modern trade chains in China and Japan extract slotting fees that compress supplier margins.
- Distributors:Logistics specialists managing cold chain integrity from brewery to outlet. Mid-tier operators in Indonesia and the Philippines face fleet investment pressures to maintain 2-4°C standards.
By transaction volume, Consumers dominate. By value chain restructuring, Retailers are advancing most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Japan's convenience store channel exceeds Vietnam's fragmented bia hoi street market by substantial margins, creating a two-tier revenue architecture across the region. This asymmetry shapes where multinational brewers allocate premium portfolio investments versus where local operators defend volume positions.
China
Tier-one city consumers in Shanghai and Beijing trade toward premium lagers and craft-adjacent offerings as disposable incomes rise. SAMR's GB standards on alcohol content disclosure and labeling precision extend product development timelines for all market participants. Yangtze River Delta manufacturing clusters anchor production capacity expansion for both domestic and joint-venture breweries.
Japan
Convenience store chains 7-Eleven and Lawson drive single-serve chilled beer demand through refrigerated placement standards unmatched regionally. METI container recycling laws incentivize lightweight aluminum packaging innovations that reduce effective material costs. Kanto region breweries concentrate premium portfolio development targeting urban professionals with limited brand loyalty to traditional portfolios.
India
Metropolitan corridors in Hyderabad, Pune, and Ahmedabad exhibit rising disposable income without proportional premium beer penetration, creating whitespace for first movers. FSSAI labeling mandates on nutritional disclosure reduce information asymmetry and enable ingredient-based premium positioning. Maharashtra and Karnataka state excise structures vary sharply, complicating national pricing architecture for multi-state operators.
Vietnam
Young adult consumers in Ho Chi Minh City and Hanoi shift from mass-market lagers toward locally brewed ales and IPAs, expanding addressable margin pools. Provincial cities including Da Nang, Hai Phong, and Can Tho lack dedicated craft distribution infrastructure. Australian malted barley import dependence exposes brewers to currency mismatch risks and supply volatility.
Thailand
Bangkok and Chiang Mai urban demographics drive premium craft shift away from standardized lager consumption. Tourism corridor recovery in Phuket and Pattaya sustains on-trade draft demand despite channel fragmentation pressures. Excise structure complexity rewards local production over import-dependent portfolios for multinational participants.
Asia Pacific Beer Market Vendor Landscape
Scale-driven multinationals and regionally anchored domestic brewers split the market across divergent margin and volume vectors. Consolidation pressure concentrates in tier-one city modern trade where slotting fees and cold chain requirements filter out mid-tier participants. Three archetypes dominate: global portfolio operators leveraging cross-border brand equity, national champions with provincial distribution depth, and craft-forward specialists capturing premium urban occasions. Competitive moves center on direct-to-consumer platform construction and aluminum can line automation to unlock e-commerce logistics.
Within the global portfolio tier, Anheuser-Busch InBev and Heineken NV exemplify scale-driven market presence across multiple national jurisdictions. Tsingtao Brewery and Kirin Holdings Company occupy positions as national champions with deep distribution infrastructure in their respective home markets. These four names anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Carlsberg Group |
| China Resources Holdings |
| Anheuser-Busch InBev |
| Beijing Yanjing Brewery |
| Tsingtao Brewery |
| Asahi Group Holdings |
| Kirin Holdings Company |
| San Miguel Corporation |
| Heineken NV |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta manufacturing clusters anchor regional brewing capacity, concentrating production scale that translates into pricing leverage for malt procurement and finished goods distribution across eastern China. This geographic density compresses logistics costs for tier-one city deliveries while exposing peripheral markets to freight-driven price premiums.
Pricing Analysis
The customization-premium spread between craft taproom direct sales and mass-market lager retail widens as ingredient transparency and small-batch positioning command margin separation. Three-tier pricing structure across premium, standard, and economy levels stratifies by fermentation complexity and channel format. Cost compression in economy lagers intensifies because aluminum commodity volatility and malt import currency mismatches squeeze producer margins. Price-sensitive rural wholesalers in Vietnam and Indonesia face the tightest budget constraints, while urban craft consumers in Tokyo and Singapore exhibit minimal elasticity.
Supply Chain Analysis
Contract-manufacturing concentration among Yangtze River Delta joint-venture facilities and Thai Beverage production hubs shapes regional capacity allocation for multinational brand owners. Geographic supply concentration centers on China, Vietnam, and Thailand for finished goods, with Australia and Canada anchoring malted barley feedstock. Raw material dependencies rest on imported hops from Germany and the Pacific Northwest, aluminum sheet from Chinese smelters, and yeast cultures from proprietary laboratories. Single-source vulnerability in Australian grain exports exposes Southeast Asian brewers to climate-driven harvest volatility. Distribution runs through refrigerated fleet operators maintaining cold chain integrity from brewery to convenience store.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific beer is experiencing high-growth disruption as flash pasteurization and aseptic cold-filling technology collapse shelf-life differentials between draft and packaged formats. China's SAMR tightening of GB standards on alcohol content accuracy creates regulatory inflection that rewards laboratory-capable producers.
For Market Incumbents: Harden quality assurance infrastructure by installing in-house chromatography capabilities or securing third-party verification contracts to meet SAMR inspection frequency in tier-one cities. Deepen backward integration into malted barley through offtake agreements with Australian grain cooperatives to neutralize currency mismatch exposure. Channel control via direct-to-consumer platform construction captures consumer data and defends against specialty craft taproom encroachment.
For New Entrants and Emerging Players: Pursue whitespace in Vietnam's provincial cities—Da Nang, Hai Phong, and Can Tho lack dedicated craft distribution infrastructure and present first-mover taproom opportunities. Target India's metropolitan corridor expansion in Hyderabad, Pune, and Ahmedabad where disposable income growth outpaces premium beer penetration. Go-to-market through membership-integrated brewing visibility programs converts transactional buyers into recurring revenue relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a premiumization play because craft segment margin expansion outpaces volume growth in standardized lagers. Acquisition target archetype: regional craft specialists with localized production licenses and established taproom footprints in underpenetrated provincial markets. Signal to watch: FSSAI enforcement intensity on nutritional disclosure as indicator of premium positioning viability in India.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Can Line Automation | High-speed filling reduces per-unit logistics costs and unlocks e-commerce channel viability. |
| Direct-to-Consumer Platform Launch | Subscription models capture consumer data and bypass fragmented traditional wholesale networks. |
| Craft Taproom Expansion | On-site brewing visibility with membership programs builds recurring revenue in urban Vietnam. |
| Backward Integration into Malt | Captive supply of Australian grain hedges currency volatility for Southeast Asian production. |
| GB Standards Compliance Investment | Laboratory-grade testing capabilities satisfy SAMR enforcement concentration in tier-one cities. |
Methodological Framework
A standing panel of master brewers, cold chain logistics directors, retail category buyers, and regulatory affairs specialists provided ongoing calibration against secondary validation from SAMR filings, FSSAI notifications, METI circulars, and customs trade records. Bottom-up volume triangulation across brewery production disclosures converged with top-down expenditure analysis from organized retail audit data.
Scenario-bracketing framed projections across the analysis window, modeling fermentation category, packaging format, distribution channel, and metropolitan corridor penetration as core segmentation dimensions. CAGRs derived from historical trajectory analysis adjusted for regulatory enforcement intensity and technology adoption curves in flash pasteurization deployment.
Sensitivities concentrate around Australian grain harvest volatility, SAMR inspection frequency escalation, and craft consumer cohort expansion rates in provincial Vietnam. Quarterly review of malt futures pricing, FSSAI labeling enforcement actions, and convenience store refrigerated SKU counts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Italy Alcohol E-Commerce Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Rhum Agricole Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Canned Wine Market