
 Middle East and Africa Alcoholic Beverage Market | 2026-2036
Middle East and Africa Alcoholic Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Alcoholic Beverage Market Foresight
Single-serve and ready-to-drink format bundling is consolidating shelf presence across licensed retail channels in the Middle East and Africa. Diageo PLC leverages its spirits portfolio breadth to anchor premium positioning in South Africa's controlled distribution environment. Castel Group dominates brewing capacity across Francophone West Africa through captive malt supply chains and licensed production facilities.
Alcoholic beverages in the Middle East and Africa encompass fermented and distilled products with ethanol content ranging from approximately 4% ABV in mass-market beer to over 40% ABV in aged spirits, produced through controlled yeast fermentation followed by distillation, filtration, and maturation processes designed for recreational consumption and social occasion use. Beer occupies the largest volume share across the region due to established brewing infrastructure and accessible price points, while spirits capture disproportionate margin pools in premium and luxury tiers driven by connoisseur and tourist consumer segments. The distributor type dimension reveals structural tension between state-controlled wholesale monopolies in Gulf markets and fragmented independent retail networks in Sub-Saharan Africa.
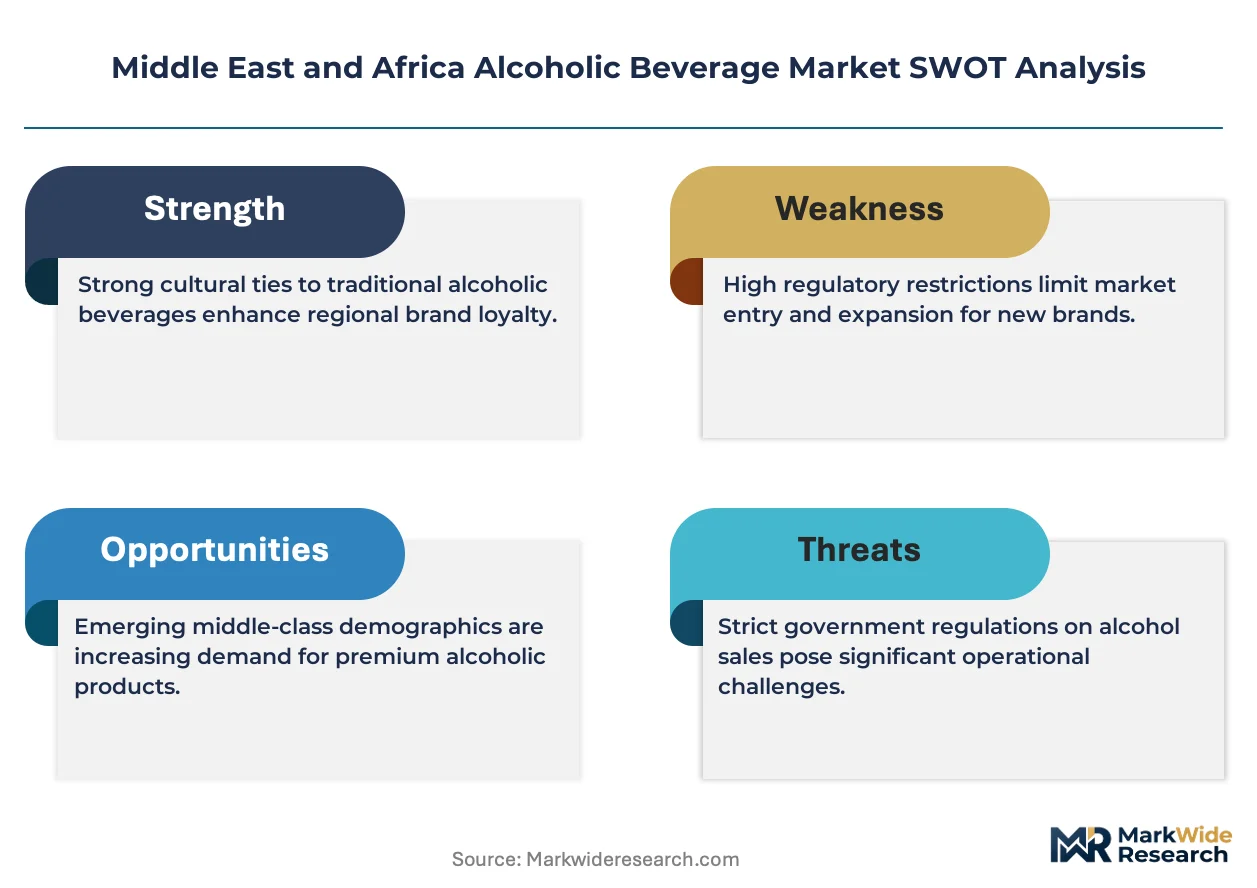
South Africa's National Liquor Authority and Kenya's Alcoholic Drinks Control Act impose licensing tiers that directly constrain market entry density and trading hours, while Nigeria's Standards Organisation regulates product labeling and ethanol disclosure requirements that shape import compliance costs. Gulf Cooperation Council member states maintain prohibitive federal frameworks with emirate-level licensing exceptions that create asymmetric access corridors for non-Muslim residents and hospitality zones. Stakeholders must monitor regulatory divergence between prohibition-adjacent Gulf markets and liberalizing Sub-Saharan economies when allocating capital across production, import, and distribution assets.
Market Dynamics
South Africa's excise tax escalator and Kenya's Alcoholic Drinks Control Act licensing tiers are compressing trading-hour windows and import compliance margins, forcing distributors to consolidate warehousing footprints and accelerate route-to-market automation.
Growth Catalysts
- Premium spirits portfolio expansion:Urban hospitality venues in Gauteng and Western Cape provinces are extending aged whiskey and craft gin listings to capture tourist and connoisseur spend.
- Licensing reform momentum:Nigeria's Standards Organisation labeling disclosure requirements are streamlining import documentation, reducing customs clearance friction for compliant entrants.
- Controlled distribution environment maturation:South Africa's National Liquor Authority tiered licensing is professionalizing wholesale consolidation, advantaging capitalized distributors with multi-province permits.
Market Restraints
- Malt input cost volatility:Francophone West Africa's captive barley supply chains face climate-driven yield compression, elevating brewing cost structures.
- Regulatory friction asymmetry:Gulf Cooperation Council federal prohibition frameworks with emirate-level licensing exceptions fragment market access corridors for non-Muslim resident segments.
- Substitution threat from non-alcoholic alternatives:Zero-ABV spirit analogs and premium mixers are capturing trial occasions among health-conscious urban consumers in Nairobi and Lagos.
Strategic Opportunities
- Underpenetrated Francophone West Africa brewing capacity:Licensed production facility expansion in Côte d'Ivoire and Senegal offers malt supply chain leverage and tariff-advantaged distribution into landlocked neighbors.
- Ready-to-drink format channel innovation:Single-serve bundling in licensed retail chains is compressing shelf-space competition and enabling impulse-purchase trial in South Africa's controlled environment.
- Regulatory tailwind from Kenya's county-level licensing devolution:Nairobi and Mombasa municipal authorities are piloting extended trading-hour permits for compliant on-premise operators.
Industry Challenges
- Route-to-market automation capex intensity:Distributors must deploy inventory management systems to satisfy South Africa's National Liquor Authority real-time excise tracking mandates.
- Cross-border excise harmonization complexity:Divergent ethanol disclosure standards between Nigeria's Standards Organisation and Kenya's Alcoholic Drinks Control Act inflate multi-country portfolio compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Alcoholic Beverage Market |
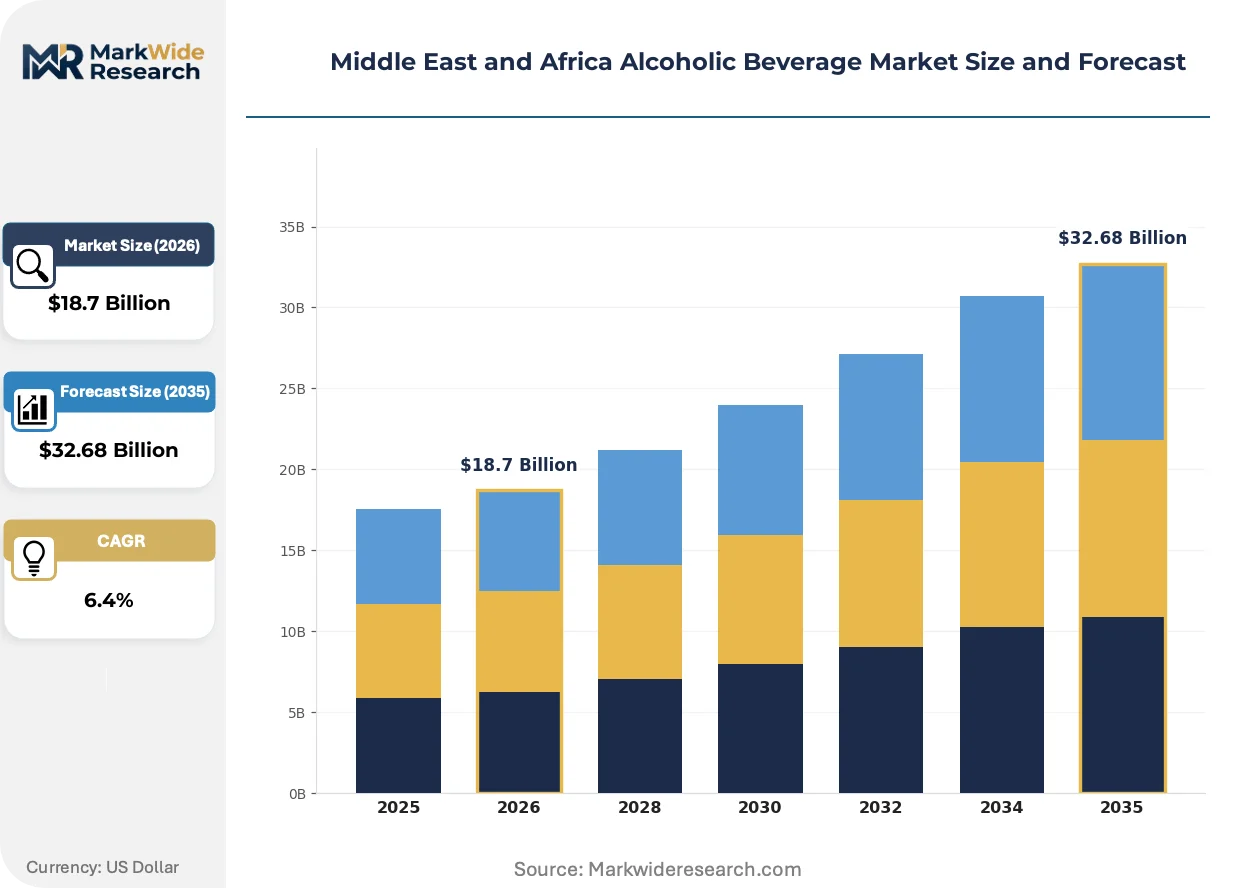
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Ciders Distributor Type: Retail, Online, Wholesale, Supermarkets Price Tier: Premium, Mid-Range, Economy, Luxury Consumer Type: Casual Drinkers, Connoisseurs, Occasional Consumers, Tourists |
| Companies Covered | Diageo PLC, Anheuser-Busch InBev SA/NV, Pernod Ricard SA, Heineken Holdings N.V., Bacardi Limited, Castel Group, Suntory Holdings Limited, Davide Campari-Milano N.V., South African Breweries, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Alcoholic Beverage Market Shifts & Advancements
Digital inventory tracking and automated excise compliance systems are compressing distributor margin structures while enabling real-time route optimization across fragmented Sub-Saharan retail networks.
Blockchain-enabled provenance verification is decentralizing authenticity assurance for premium spirits categories. High-end hospitality venues in Johannesburg and Cape Town are adopting bottle-level scanning to validate aged whiskey maturation claims. This transparency infrastructure is compressing gray-market substitution and enabling direct-to-venue contracting that bypasses traditional wholesale layers.
Kenya's Alcoholic Drinks Control Act amendments are tightening advertising restrictions and mandatory health-warning label specifications. Brewers and distillers are reallocating marketing spend toward on-premise experience design and influencer partnerships that operate within regulatory safe harbors. The compliance cost burden falls disproportionately on imported premium brands with smaller in-country legal teams.
Buyer concentration among South African supermarket chains is compressing supplier negotiation cycles and unbundling traditional promotional allowances. Retail procurement teams at Pick n Pay and Woolworths are demanding data-sharing agreements that expose distributor margin structures. This transparency mandate is visible across Gauteng and Western Cape supply agreements, where volume commitments now tie directly to inventory velocity metrics rather than upfront slotting fees.
Middle East and Africa Alcoholic Beverage Market Segmentation
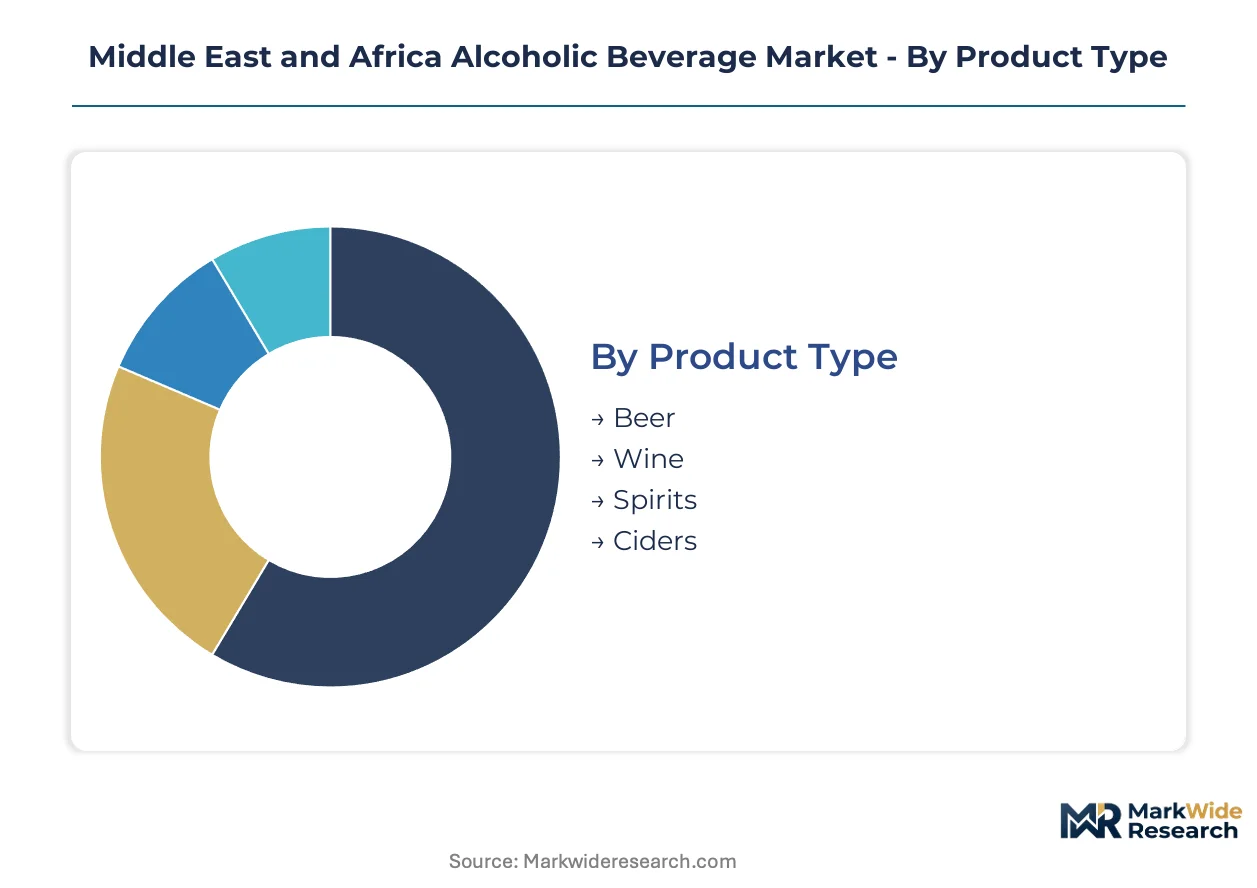
Segmentation in the Middle East and Africa Alcoholic Beverage Market reveals how capital deployment, regulatory exposure, and route-to-market complexity vary across product formats and channel structures. Distinct margin profiles and licensing requirements shape where producers and distributors concentrate investment across this heterogeneous region.
Product Type:
Capital intensity diverges sharply across fermentation versus distillation assets, with maturation inventory and excise bonding requirements driving facility investment thresholds.
- Beer:Mass-market lager production relies on continuous brewing infrastructure with substantial malt silo and fermentation tank requirements. Demand concentrates in South Africa's Gauteng and Western Cape provinces where SABMiller and Heineken maintain captive brewing networks, though excise escalators are compressing per-unit margins.
- Spirits:Aged whiskey and craft gin require bonded warehousing for multi-year maturation cycles, tying up working capital for extended periods. Urban hospitality venues in Johannesburg and Cape Town are extending premium spirits listings to capture tourist and connoisseur spend, driving disproportionate margin pools despite smaller volume bases.
- Wine:Western Cape's established vineyard infrastructure supports varietal production with lower capital barriers than distillation, though climate volatility elevates yield risk.
- Ciders:Fermented apple or pear bases target younger demographics with accessible price points and shorter production cycles, requiring modest equipment investment compared to beer brewing.
Most installed capacity flows through Beer. Expansion is steepest in Spirits.
Distributor Type:
Route-to-market economics shift dramatically between state-controlled wholesale monopolies in Gulf markets and fragmented independent retail networks across Sub-Saharan Africa.
- Wholesale:Licensed distributors with multi-province permits in South Africa's National Liquor Authority framework consolidate warehousing footprints to satisfy real-time excise tracking mandates. Professionalizing wholesale consolidation advantages capitalized operators capable of automation capex.
- Retail:Licensed independent outlets and specialist chains dominate volume in Nigeria's Lagos corridor and Kenya's Nairobi hub, though trading-hour restrictions compress revenue windows.
- Supermarkets:Pick n Pay and Woolworths in South Africa demand data-sharing agreements that expose distributor margin structures, unbundling traditional promotional allowances.
- Online:E-commerce penetration remains constrained by licensing verification requirements and last-mile delivery restrictions in alcohol-controlled jurisdictions.
Wholesale commands the greatest capital deployment. Retail is gaining share fastest.
Price Tier:
Margin architecture stratifies across excise incidence, import duty exposure, and consumer occasion targeting.
- Premium:Aged spirits and craft offerings carry elevated excise burdens but capture connoisseur and tourist segments in South African urban hospitality venues. Blockchain-enabled provenance verification is compressing gray-market substitution.
- Mid-Range:Standard lager and table wine balance volume scale with acceptable margins, dominating household consumption in Nigeria and Kenya.
- Economy:Value beer and local spirits target price-sensitive mass markets with minimal branding investment and thin per-unit profitability.
- Luxury:Ultra-premium aged whiskey and limited releases serve gift occasions and high-end tourism with substantial markups but concentrated demand in Johannesburg and Cape Town.
Premium generates the highest margin per liter. Mid-Range moves the greatest absolute volume.
Consumer Type:
Occasion-based targeting determines product development and channel placement priorities.
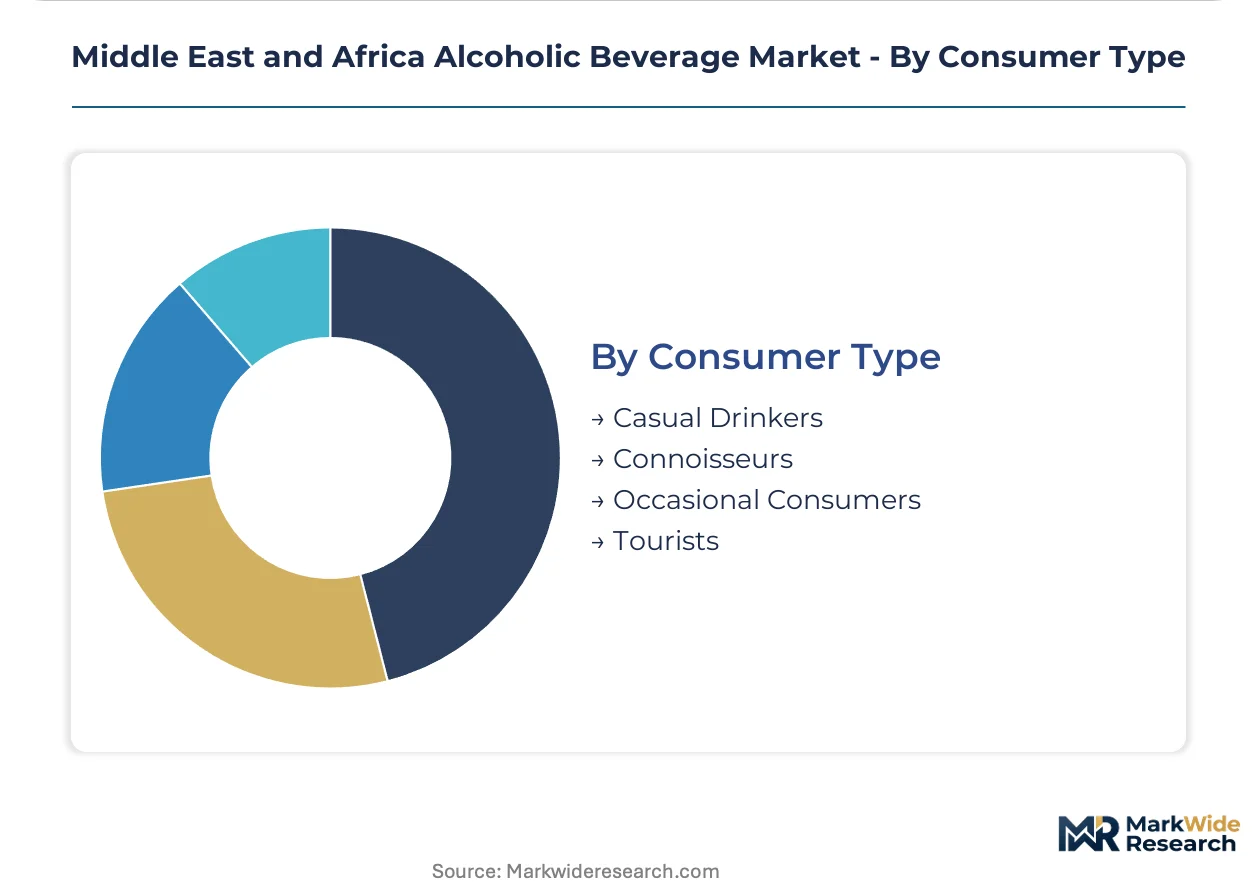
- Casual Drinkers:Regular beer and ready-to-drink consumers drive baseline volume through supermarket and licensed retail channels, with single-serve bundling enabling impulse trial.
- Connoisseurs:Aged whiskey and craft gin enthusiasts validate authenticity through bottle-level scanning in high-end Johannesburg and Cape Town venues, supporting direct-to-venue contracting.
- Occasional Consumers:Health-conscious urban demographics in Nairobi and Lagos are substituting toward zero-ABV analogs, threatening traditional trial occasions.
- Tourists:International visitors concentrate demand in Western Cape wine routes and Gauteng hospitality clusters, with seasonal fluctuations requiring flexible inventory planning.
Casual Drinkers anchor volume stability. Connoisseurs command the steepest price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colonial-era brewing infrastructure established South Africa's foundational production capacity, while post-independence import substitution policies seeded manufacturing clusters across Francophone West Africa and East African hubs. Contemporary demand concentrates in urban corridors shaped by divergent regulatory regimes.
South Africa
Gauteng and Western Cape provinces anchor consumption through Johannesburg's hospitality clusters and Cape Town's tourism-driven wine routes. The National Liquor Authority's tiered licensing framework constrains trading-hour windows while advantaging capitalized distributors with multi-province permits. Cape Town's Atlantic Seaboard venues are extending aged whiskey and craft gin listings to capture international visitor spend.
Nigeria
Lagos corridor demand concentrates in Victoria Island and Ikeja entertainment districts with strong mid-range lager consumption. The Standards Organisation's labeling disclosure requirements streamline import documentation for compliant entrants, reducing customs clearance friction. Port Harcourt's petroleum-sector expatriate communities sustain premium spirits demand despite broader economic volatility.
Kenya
Nairobi's Westlands and Kilimani neighborhoods host the densest on-premise concentration, with Mombasa coastal tourism adding seasonal volume. County-level licensing devolution pilots extended trading-hour permits for compliant operators in Nairobi and Mombasa municipalities. Mount Kenya region supply chains face climate-driven barley yield compression elevating brewing input costs.
United Arab Emirates
Dubai's Jumeirah and Downtown hospitality zones operate under emirate-level licensing exceptions within federal prohibition frameworks. MOHAP and municipal authorities administer asymmetric access corridors for non-Muslim residents and tourism zones. Abu Dhabi's Saadiyat Island developments are attracting premium hotel-managed bar investments targeting Gulf visitor segments.
Côte d'Ivoire
Abidjan's Plateau and Cocody districts concentrate Francophone West Africa's most sophisticated on-premise infrastructure. Castel Group's licensed production facilities leverage captive malt supply chains for tariff-advantaged distribution into landlocked Mali and Burkina Faso. San Pedro port expansion is reducing import lead times for containerized spirits shipments.
Middle East and Africa Alcoholic Beverage Market Competitive Landscape
Premium-margin players sit above commodity-margin players across licensing-tier access and maturation-investment thresholds. The market exhibits bifurcated consolidation: multinational brewers dominate volume through captive production networks, while spirits portfolios concentrate around aged-inventory specialists. Two archetypes prevail—integrated brewing conglomerates with Francophone West African manufacturing footprints, and premium spirits houses leveraging blockchain-enabled provenance verification. Competitive moves center on licensed production facility expansion and direct-to-venue contracting that compresses wholesale layers.
Within the integrated brewing tier, Anheuser-Busch InBev SA/NV and Heineken Holdings N.V. exemplify scale-driven operators with established fermentation infrastructure across multiple jurisdictions. Castel Group occupies a distinct position as a Francophone Africa specialist with captive supply chain integration. On the premium spirits vector, Diageo PLC and Pernod Ricard SA represent archetypal portfolio-breadth players anchoring controlled distribution environments through aged-inventory depth and hospitality-channel relationships.
| Leading Market Players |
|---|
| Diageo PLC |
| Anheuser-Busch InBev SA/NV |
| Pernod Ricard SA |
| Heineken Holdings N.V. |
| Bacardi Limited |
| Castel Group |
| Suntory Holdings Limited |
| Davide Campari-Milano N.V. |
| South African Breweries |
| Others |
Supply & Pricing Matrix
Malt barley procurement costs cascade through Francophone West Africa's brewing economics, with climate-driven yield compression in the Mount Kenya region elevating input expenses that ultimately concentrate in mid-range lager price points across Nigeria's Lagos corridor and Kenya's Nairobi hub. This upstream cost pressure intersects with excise escalator mechanics in South Africa's National Liquor Authority framework, compressing per-unit margins while licensing tier differentials amplify pricing power asymmetries between capitalized multi-province distributors and fragmented independent retailers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the Middle East and Africa Alcoholic Beverage Market, with excise incidence and import duty exposure serving as the primary price differentiation drivers. Pricing pressure stems from South Africa's excise tax escalator compressing trading-hour revenue windows, forcing distributors to absorb cost increases rather than pass through to supermarket chains. Casual drinkers in mass-market beer segments exhibit the highest price sensitivity, while connoisseurs in Johannesburg and Cape Town hospitality venues accept substantial premiums for blockchain-verified aged spirits.
Supply Chain Analysis
Containerized freight costs from San Pedro port through Abidjan's distribution hubs anchor logistics economics for Francophone West Africa's brewing networks. Supply concentration centers on South Africa's Gauteng and Western Cape provinces, Nigeria's Lagos corridor, and Kenya's Nairobi hub, with raw material dependencies spanning captive barley supply chains, bonded warehousing for maturation inventory, and imported malt for licensed production facilities. Single-source vulnerability in climate-exposed barley regions elevates input cost volatility. Distribution runs through state-controlled wholesale monopolies in Gulf Cooperation Council markets and fragmented independent retail networks across Sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Alcoholic Beverage Market functions as a regulatory compounder, with Kenya's Alcoholic Drinks Control Act county-level devolution creating asymmetric access corridors that directly shape competitive entry economics and margin architecture.
For Market Incumbents: Lock in multi-province licensing permits across South Africa's National Liquor Authority tiers before regulatory consolidation advantages further narrow. Deepen captive malt supply chain control in Francophone West Africa to defend against climate-driven yield compression threatening brewing cost structures. Accelerate route-to-market automation capex to satisfy real-time excise tracking mandates that smaller distributors cannot match.
For New Entrants and Emerging Players: Capture underpenetrated ready-to-drink format shelf space in South Africa's controlled retail environment through single-serve bundling innovations that bypass entrenched wholesale relationships. Target extended trading-hour permit pilots in Nairobi and Mombasa municipalities where county-level licensing devolution creates temporary regulatory whitespace. Pursue direct-to-venue contracting with high-end Cape Town and Johannesburg hospitality clusters leveraging blockchain provenance verification as a trust-building mechanism.
For Investors and Strategic Acquirers: Consolidation pressure builds where distributor automation capex requirements intersect with excise compliance mandates that fragment smaller players. Long-term viability favors capitalized operators with multi-jurisdiction licensing depth and captive supply chain integration across malt input and bonded warehousing. Acquisition target archetypes include licensed production facilities in Côte d'Ivoire and Senegal with tariff-advantaged distribution reach into landlocked neighbors. Monitor Kenya's county-level licensing devolution velocity as the critical inflection signal for regulatory arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Licensed Production Facility Expansion | Castel Group's captive malt supply chains in Francophone West Africa demonstrate tariff-advantaged distribution leverage into landlocked Mali and Burkina Faso. |
| Blockchain-Enabled Provenance Verification | High-end Johannesburg and Cape Town venues adopt bottle-level scanning to compress gray-market substitution and enable direct-to-venue contracting. |
| Route-to-Market Automation | Distributors deploy inventory management systems to satisfy South Africa's National Liquor Authority real-time excise tracking mandates. |
| Ready-to-Drink Format Channel Innovation | Single-serve bundling in licensed retail chains compresses shelf-space competition and enables impulse-purchase trial in controlled environments. |
| County-Level Licensing Devolution Exploitation | Nairobi and Mombasa municipal pilots of extended trading-hour permits create temporary regulatory whitespace for compliant on-premise operators. |
Research Methodology
Direct dialogue with brand managers at multinational brewers, category buyers at South African supermarket chains, regulatory affairs leads at National Liquor Authority licensees, and distribution channel heads across Lagos and Nairobi grounded qualitative insights. Secondary validation drew from customs and excise records, National Liquor Authority licensing databases, Kenya's Alcoholic Drinks Control Act amendment filings, and Standards Organisation of Nigeria labeling disclosure requirements. Bottom-up and top-down triangulation reconciled route-to-market volume estimates with excise revenue projections across the analysis window.
Bottom-up modeling segmented volume and value outputs by product type, distributor type, price tier, and consumer occasion across the projection horizon. CAGRs derived from weighted average growth trajectories across South Africa's Gauteng and Western Cape provinces, Nigeria's Lagos corridor, Kenya's Nairobi hub, and Francophone West Africa's brewing clusters. Industry-specific forecast inputs incorporated excise escalator mechanics, licensing tier penetration rates, and climate-adjusted barley yield assumptions.
Regulatory amendment timing, excise rate adjustments, and climate-driven agricultural yield volatility are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about licensing devolution momentum and import substitution policy continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
Beer Pasteurization Equipment Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
North America Alcoholic Beverages Market
Alcoholic Beverages
India Alcohol Market
Alcoholic Beverages
Beer Dispensing Machine Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
Frozen Cocktails Market
Alcoholic Beverages
India Tequila Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Fortified Wine Market