
 A2P Messaging Market | 2026-2036
A2P Messaging Market Size, Share, and Industry Trends Forecast 2026-2036
A2P Messaging Market Intelligence
A chronic shortage of cloud-native telecom engineers is unwinding deployment timelines for next-generation messaging platforms. Twilio Inc. leverages its developer-first API ecosystem to capture high-margin enterprise accounts. Infobip Ltd. anchors its position through direct carrier relationships across emerging markets. Sinch AB competes aggressively on RCS infrastructure, differentiating from SMS-centric rivals.
Application-to-person messaging denotes automated text, multimedia, or rich communication transmissions from software applications to individual mobile subscribers, typically routed through SS7 or IP-based signaling protocols with delivery receipts and throughput controls of 10-50 messages per second per channel. Its primary commercial purpose centers on scalable, programmable customer touchpoints for authentication codes, appointment alerts, and marketing outreach. Transactional messaging dominates revenue pools due to mandatory two-factor authentication and payment confirmation requirements across banking and retail end users. RCS messaging represents the fastest-expanding service type as Apple and Google converge on universal support, though SMS messaging sustains the largest absolute volume base due to universal handset compatibility. Cloud-based solutions command expanding share as enterprises abandon on-premises gateways for elastic, pay-per-use infrastructure.
The FCC enforces strict anti-robocall frameworks including STIR/SHAKEN caller ID authentication that reshape how A2P traffic traverses US carrier networks. GDPR and the EU AI Act impose consent documentation and automated decision transparency obligations on promotional messaging flows into Europe. India's TRAI mandates scrubbing of commercial SMS against distributed ledger registries to curb unsolicited traffic. Stakeholders must monitor regulatory divergence between privacy-first jurisdictions and authentication-heavy markets to calibrate routing investments and compliance architecture.
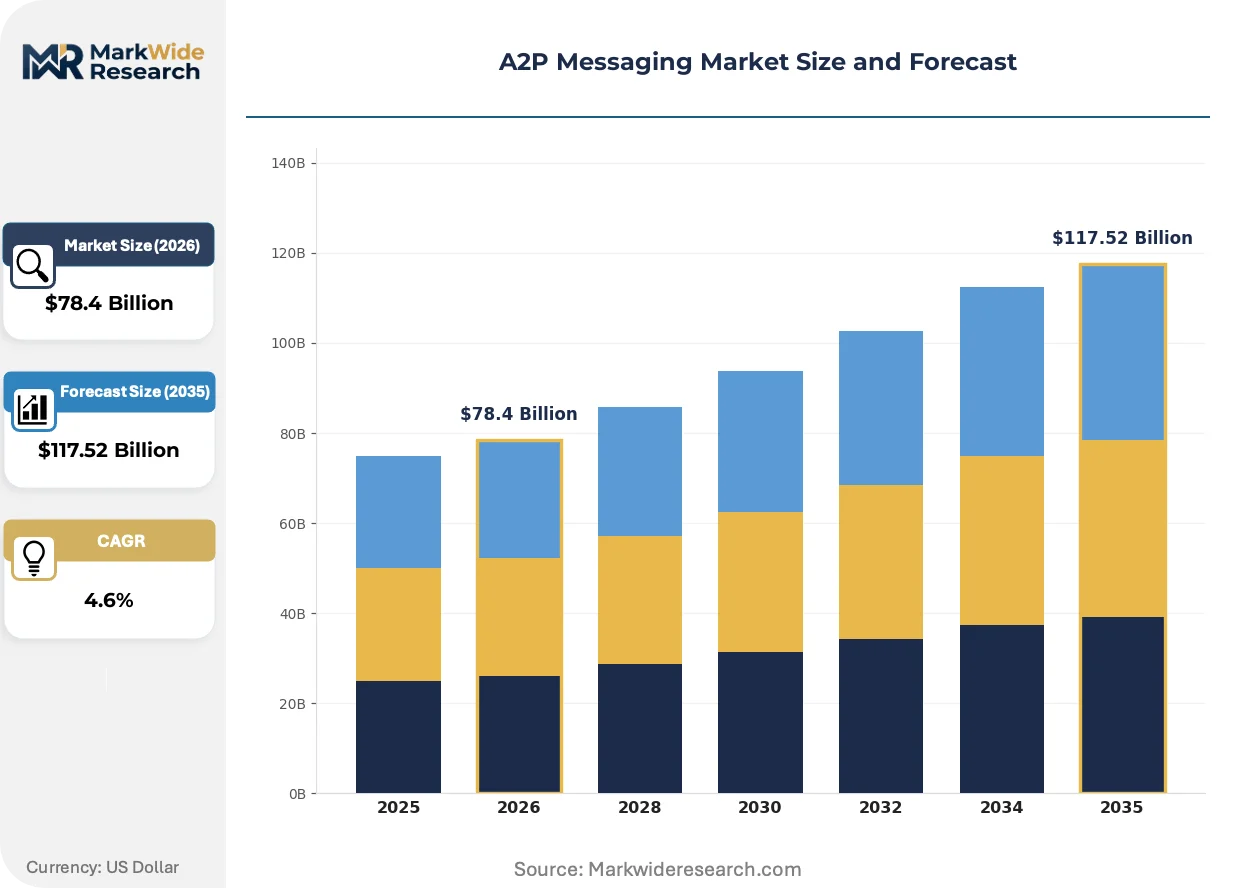
Market Dynamics
Enterprise migration from on-premises SMS gateways to cloud-native API platforms is compressing vendor margins while expanding total addressable volume across banking and retail authentication workflows.
Growth Catalysts
- GDPR Consent Frameworks:European data protection mandates are forcing enterprises to upgrade to traceable, auditable messaging infrastructure with documented opt-in trails.
- India's DLT Scrubbing Mandate:TRAI's distributed ledger registry requirement for commercial SMS is driving carrier investment in verified routing channels and filtering infrastructure.
- RCS Protocol Convergence:Universal handset support for rich communication services is opening multimedia engagement channels previously constrained by SMS character limits.
Market Restraints
- SS7 Interconnect Vulnerability:Legacy signaling protocol exposure to interception and spoofing attacks creates persistent security liabilities for high-value authentication traffic.
- Carrier Revenue Protection:Tier-1 mobile network operators impose artificial rate floors and volume caps to defend SMS termination revenues against OTT messaging substitution.
- Cloud Talent Scarcity:Chronic shortage of Kubernetes-certified telecom engineers extends deployment timelines for containerized messaging platforms by 40-60 percent.
Strategic Opportunities
- Conversational Commerce Integration:WhatsApp Business API and similar messaging app channels are capturing customer service budgets previously allocated to voice call centers.
- IoT Device Authentication:Machine-to-person alert flows from connected vehicles, industrial sensors, and smart home devices represent unpenetrated volume pools outside traditional B2C messaging.
- STIR/SHAKEN Verification:FCC-mandated caller ID authentication creates demand for certified A2P identity services that command premium routing fees.
Industry Challenges
- API Integration Complexity:Enterprise IT teams struggle to reconcile modern REST-based messaging stacks with legacy SOAP protocols and mainframe-era customer databases.
- Throughput Bottlenecks:Real-time payment notification SLAs of sub-5-second delivery collide with carrier-imposed rate limiting during peak traffic windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | A2P Messaging Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $117.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Promotional Messaging, Transactional Messaging, Customer Engagement, Notification Services Service Type: SMS Messaging, MMS Messaging, RCS Messaging, Voice Messaging End User: Retail, Banking, Travel, Healthcare Technology: Cloud-Based Solutions, On-Premises Solutions, API Integrations, Multimedia Messaging |
| Companies Covered | Orange S.A., Sinch AB, China Mobile Limited, Vonage Holdings Corp., Tata Communications Limited, Twilio Inc., Infobip Ltd., MessageBird B.V., AT&T Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
A2P Messaging Market Strategic Shifts & Innovations
Rich Communication Services is eroding SMS dominance as Apple and Google align on universal RCS support, while regulatory authentication mandates reshape carrier economics and enterprise procurement priorities.
RCS Business Messaging is supplanting conventional SMS for high-value customer journeys. Retail banks and e-commerce platforms are adopting verified sender profiles, carousel product displays, and suggested reply buttons. This technology is compressing the gap between messaging utility and full application experiences, reducing customer drop-off in onboarding funnels.
The FCC's STIR/SHAKEN framework is mandating cryptographic attestation of originating identity for voice and messaging traffic traversing US carrier networks. This policy is forcing A2P aggregators to deploy certificate-based authentication infrastructure or face degraded routing priority. Financial services and healthcare verticals are most affected, with compliance timelines compressing vendor certification cycles.
Enterprise buyers are consolidating messaging spend under platform-as-a-service contracts with unified API layers. Procurement teams are replacing fragmented point solutions for SMS, push, and email with single-vendor orchestration suites. This pattern is most visible in North American and Western European banking, where vendor reduction mandates follow core system modernization programs.
A2P Messaging Market Segmentation
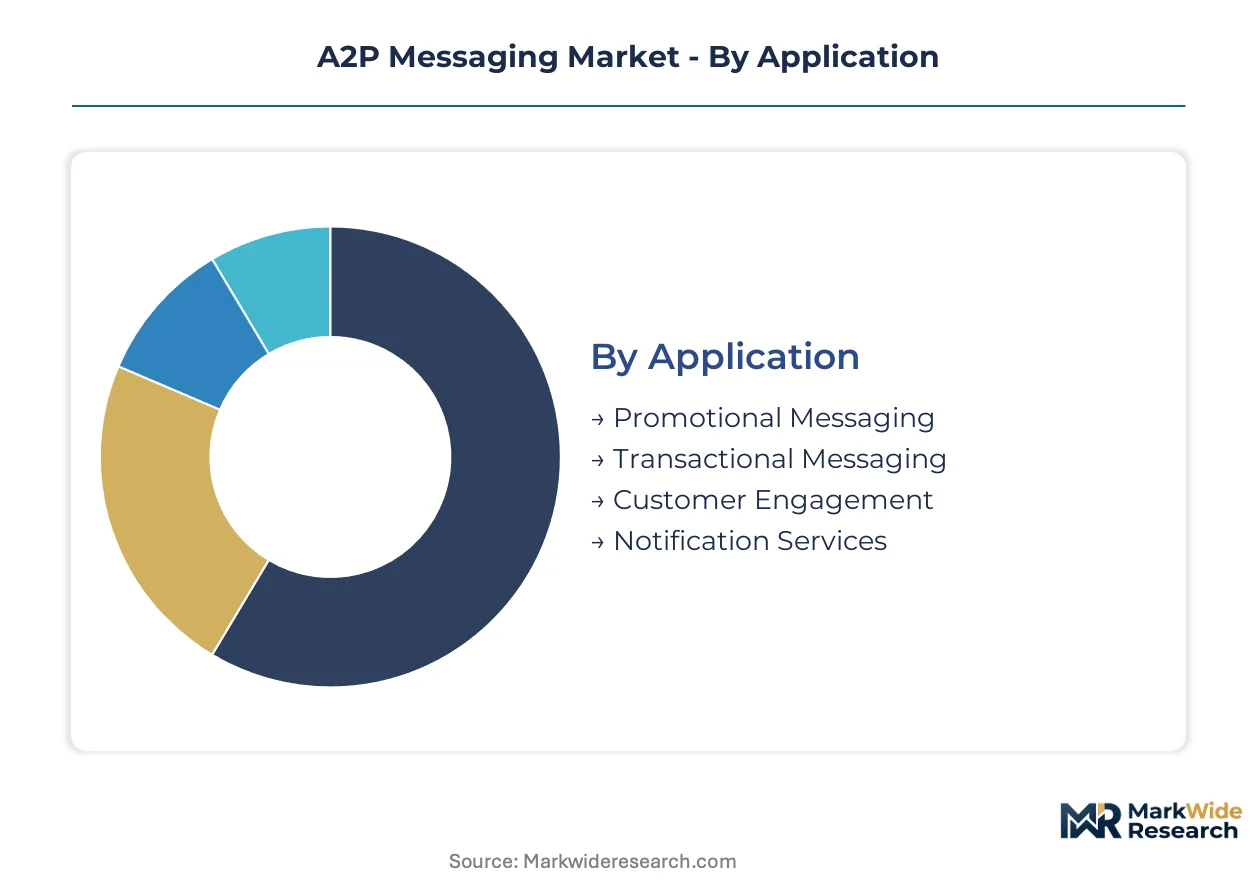
Segmentation in A2P messaging reveals how infrastructure investments, regulatory mandates, and enterprise procurement patterns concentrate value across distinct commercial lanes. Understanding these divisions exposes where platform vendors must anchor their technical roadmaps to capture durable revenue pools.
Application:
Margin pools concentrate in authentication-dependent use cases where delivery SLAs command premium pricing and long-term platform stickiness.
- Transactional Messaging:Automated transmissions of one-time passwords, payment confirmations, and account alerts through SS7 or IP channels with sub-5-second delivery requirements. Banking networks in India and retail payment platforms in Brazil drive volume concentration as regulatory mandates for two-factor authentication harden. Carrier rate floors and scrubbing compliance costs compress aggregator margins while securing enterprise platform loyalty.
- Promotional Messaging:Consent-based marketing broadcasts with documented opt-in trails required under GDPR and TRAI frameworks. European retailers and Indian e-commerce platforms face escalating compliance costs for audit-ready infrastructure, shifting procurement toward vertically integrated platform providers with native consent management.
- Customer Engagement:Two-way conversational flows including appointment scheduling and service inquiries through API-driven channels.
- Notification Services:Operational alerts for logistics, utilities, and workforce management with lower authentication requirements but higher throughput demands.
The dominant share belongs to Transactional Messaging, while Promotional Messaging is closing the gap fastest as consent infrastructure investments mature into scalable competitive advantages.
Service Type:
Technology transitions are redistributing volume from legacy protocols toward rich media channels that support verified sender identity and interactive elements.
- SMS Messaging:Plain-text transmissions over SS7 signaling with universal handset compatibility and 160-character constraints. Universal device coverage sustains absolute volume leadership, particularly in emerging markets with fragmented smartphone penetration and for authentication flows requiring lowest-common-denominator reach.
- RCS Messaging:Rich Communication Services delivering verified branding, carousel displays, and suggested replies over IP infrastructure. Retail banking onboarding and e-commerce purchase journeys in South Korea and Japan adopt RCS to compress drop-off rates, with Apple's protocol convergence removing the final handset compatibility barrier.
- MMS Messaging:Multimedia transmissions supporting images and audio with intermediate richness between SMS and RCS.
- Voice Messaging:Automated spoken alerts and IVR handoffs for accessibility requirements and high-attention notifications.
SMS Messaging retains volume leadership across all geographies, though RCS Messaging is climbing the fastest as carrier certification programs and handset manufacturer alignment accelerate enterprise adoption curves.
End User:
Vertical procurement patterns diverge sharply based on regulatory intensity, authentication complexity, and legacy system integration burdens.
- Banking:Financial institutions replacing legacy notification gateways with cloud-native API stacks for payment alerts, fraud warnings, and KYC verification. India's digital payment expansion and Brazil's instant payment system drive regional concentration, with FCC STIR/SHAKEN mandates and GDPR audit requirements forcing infrastructure upgrades in North America and Europe.
- Retail:E-commerce platforms and brick-and-mortar chains deploying promotional and transactional messaging across omnichannel customer journeys. High-volume promotional sends in India face TRAI DLT scrubbing costs, while European operators absorb GDPR consent infrastructure investments that smaller merchants struggle to internalize.
- Healthcare:Appointment reminders, prescription alerts, and patient outreach with HIPAA compliance requirements in the US.
- Travel:Booking confirmations, boarding passes, and disruption notifications with seasonal volume volatility and partnership-dependent routing.
Banking commands the deepest platform integration investments, while Retail is expanding most quickly as conversational commerce budgets shift from voice call centers to messaging channels.
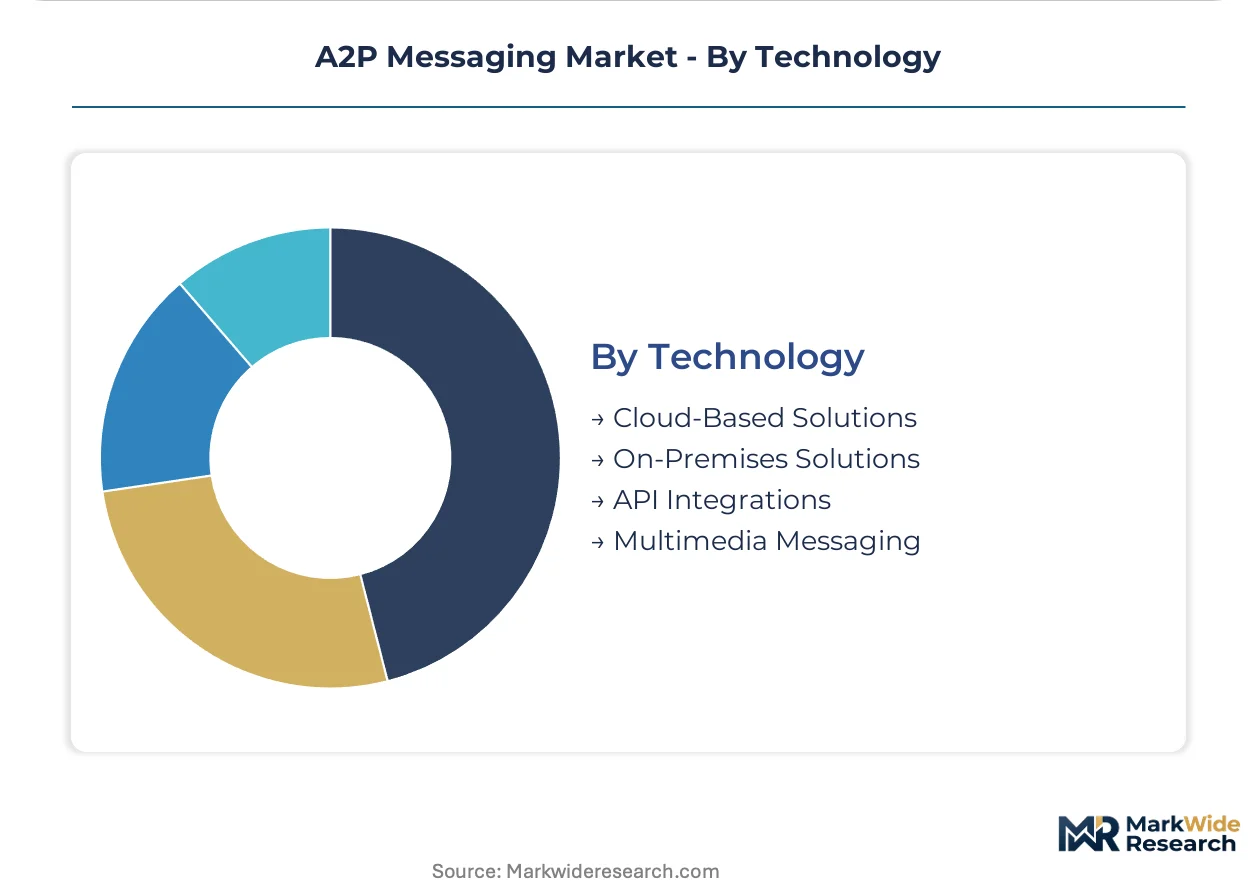
Technology:
Infrastructure deployment models determine operational leverage, with cloud elasticity displacing fixed-cost on-premises installations across enterprise tiers.
- Cloud-Based Solutions:Elastic, pay-per-use messaging infrastructure with REST API access and Kubernetes-orchestrated scaling. North American and Western European banking consolidation under platform-as-a-service contracts accelerates adoption, though chronic shortages of cloud-native telecom engineers extend deployment timelines.
- API Integrations:Programmable interfaces connecting enterprise CRM and core banking systems to carrier networks. Developer experience and documentation quality differentiate vendor selection, with procurement teams favoring unified orchestration layers over fragmented point solutions.
- On-Premises Solutions:Dedicated gateway hardware with fixed capacity and capital-intensive refresh cycles.
- Multimedia Messaging:Infrastructure supporting rich content transcoding and device capability negotiation.
Cloud-Based Solutions anchor new enterprise commitments, while API Integrations are gaining share fastest as procurement teams consolidate vendor relationships under single-platform messaging orchestration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TRAI's distributed ledger mandate anchors India as the most tightly regulated major A2P messaging jurisdiction, with carrier scrubbing requirements and digital payment growth reshaping enterprise procurement patterns across banking and retail verticals.
United States
FCC STIR/SHAKEN enforcement compresses vendor certification timelines for financial services and healthcare authentication flows. Banking consolidation under platform-as-a-service contracts accelerates cloud migration, though carrier rate floors defend SMS termination revenues. Silicon Valley API providers and Chicago-based financial institutions anchor demand concentration for verified identity services.
India
TRAI's DLT scrubbing mandate drives carrier investment in verified routing channels, while RBI's digital payment push expands two-factor authentication volumes. PLI scheme support for telecom infrastructure reduces deployment friction for cloud-native messaging stacks. Mumbai and Bangalore financial technology clusters concentrate enterprise platform procurement for payment alerts and KYC verification.
Germany
GDPR consent documentation requirements and EU AI Act automated decision transparency obligations force promotional messaging infrastructure upgrades. Deutsche Bundesbank's instant payment system drives transactional volume concentration. Frankfurt banking networks and Munich industrial clusters anchor enterprise demand for auditable opt-in trail systems.
Brazil
Banco Central do Brasil's instant payment system PIX mandates real-time payment confirmation flows with sub-5-second delivery SLAs. ANVISA's healthcare notification requirements create compliance-driven infrastructure investments. São Paulo fintech clusters and Rio de Janeiro retail platforms concentrate conversational commerce adoption for customer service automation.
South Korea
Financial Services Commission mandates for mobile banking authentication compress platform reliability requirements. MFDS healthcare alert regulations drive verified sender profile adoption. Seoul digital banking clusters and Busan logistics hubs anchor RCS Business Messaging deployment for retail onboarding and supply chain notifications.
A2P Messaging Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the A2P messaging ecosystem, with API-native developers commanding premium pricing for enterprise orchestration while carrier-direct aggregators compete on emerging market volume. The vendor base organizes into three strategic archetypes: developer-first platform providers with unified messaging stacks, carrier-relationship specialists with direct SS7 interconnect access, and telecom-owned infrastructure players leveraging captive network assets. Competitive moves concentrate on M&A for API talent acquisition and strategic partnerships for RCS certification acceleration.
Within the developer-first tier, Twilio Inc. and Infobip Ltd. exemplify contrasting geographic anchoring strategies, with the former representing North American platform-as-a-service consolidation and the latter occupying a position across emerging market carrier ecosystems. Sinch AB sits within the RCS infrastructure specialization vector, reflecting premium-tier positioning as Apple-Google protocol convergence accelerates enterprise rich messaging procurement.
| Leading Market Players |
|---|
| Orange S.A. |
| Sinch AB |
| China Mobile Limited |
| Vonage Holdings Corp. |
| Tata Communications Limited |
| Twilio Inc. |
| Infobip Ltd. |
| MessageBird B.V. |
| AT&T Inc. |
| Others |
Cost & Logistics Intelligence
Carrier-scale message routing infrastructure in India and the United States generates steep unit-cost advantages that compress price floors for regional aggregators while elevating margins for cloud-native platform providers with direct API relationships. This scale asymmetry concentrates procurement power among tier-1 mobile network operators who impose volume-commitment thresholds and artificial rate floors to defend SMS termination revenues against over-the-top substitution.
Pricing Analysis
Geographic price spreads between North American and South Asian routing corridors exceed threefold for equivalent authentication-grade delivery, reflecting carrier revenue protection intensity and regulatory compliance cost layering. The dominant pricing model runs on per-unit transactional structures with volume-tiered discounts, though platform-as-a-service subscriptions are gaining share among consolidated enterprise buyers. Price differentiation hinges on certification level — STIR/SHAKEN attestation and GDPR audit trails command premium routing fees — and geographic delivery cost, with FCC-mandated identity verification inflating US-origin message pricing. Pricing pressure stems from cloud-native vendor margin compression as Kubernetes-orchestrated infrastructure reduces deployment friction. Retail e-commerce platforms exhibit highest price sensitivity, while banking networks prioritize delivery SLA reliability over unit cost.
Supply Chain Analysis
Inventory and lead-time constraints for SS7 interconnect capacity extend platform deployment cycles by 40-60 percent as cloud-native telecom engineer scarcity constrains carrier certification velocity. Supply concentration centers on India, the United States, and Germany, where regulatory mandates for scrubbing infrastructure and consent documentation drive capital deployment. Raw material dependencies include distributed ledger registry hardware, cryptographic certificate infrastructure, and IP-based signaling protocol stacks. Supply chain risk rests on single-source vulnerability for RCS certification pathways as Apple-Google protocol convergence concentrates handset compatibility gates. Distribution runs through tier-1 carrier direct interconnects, API aggregator platforms, and enterprise self-serve developer portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as enterprise migration from on-premises SMS gateways to cloud-native API platforms accelerates replacement demand across banking and retail authentication workflows.
For Market Incumbents: Shield core enterprise relationships through backward integration into RCS certification infrastructure and captive supply of STIR/SHAKEN attestation services. Defend against API-native challengers by embedding consent-management modules directly into banking core system modernization programs, leveraging GDPR audit trail investments as switching-cost anchors. For New Entrants and Emerging Players: Anchor in IoT device authentication flows from connected vehicles and industrial sensors, a white-space segment outside traditional B2C messaging volume pools. Target conversational commerce integration for WhatsApp Business API channels, where customer service budget shifts from voice call centers create penetrable procurement entry points. Lead with developer-experience differentiation and unified orchestration layers rather than fragmented point solutions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors carrier-direct aggregators with verified routing channel access in emerging markets, as RCS protocol convergence accelerates rich messaging procurement curves. Long-term viability over the next decade hinges on regulatory compliance infrastructure ownership rather than pure volume scale. Monitor TRAI DLT scrubbing mandate expansion and FCC STIR/SHAKEN enforcement intensity as inflection indicators for carrier economics and enterprise platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| RCS Certification Acceleration | Apple-Google protocol convergence removes handset compatibility barriers for rich messaging procurement. |
| STIR/SHAKEN Infrastructure Deployment | FCC mandates force cryptographic attestation investment for premium routing priority in financial services. |
| DLT Registry Integration | TRAI scrubbing requirements create verified channel scarcity for commercial SMS in Indian banking networks. |
| API Talent Acquisition | Kubernetes-certified telecom engineer scarcity extends deployment timelines for containerized messaging platforms. |
| Conversational Commerce Partnership | WhatsApp Business API captures customer service budgets shifting from voice call centers to messaging channels. |
Research Approach
Desk research of carrier regulatory filings, enterprise API documentation, and distributed ledger registry technical specifications preceded structured interviews with cloud platform engineering directors, telecom carrier interconnect managers, banking IT procurement leads, and messaging aggregator operations heads. Secondary validation drew from TRAI enforcement circulars, FCC STIR/SHAKEN certification databases, SEC 10-K infrastructure disclosures, and European data protection authority consent-guidance documents. Bottom-up volume estimates from country-level carrier traffic disclosures were triangulated against top-down enterprise messaging spend surveys.
Variance decomposition across service type, application use case, deployment technology, and end-user vertical shaped the analytical framework for value projections over the analysis window. Segmentation dimensions modeled included transactional versus promotional messaging intent, SMS versus RCS protocol infrastructure, cloud-based versus on-premises deployment, and banking versus retail versus healthcare vertical procurement patterns. CAGRs were derived from elasticity-adjusted volume trajectories and carrier rate-floor evolution assumptions, with RBI digital payment expansion curves and Banco Central do Brasil PIX notification mandates serving as regional growth anchors.
Material uncertainties — regulatory divergence between privacy-first jurisdictions and authentication-heavy markets, carrier revenue protection intensity variation, and cloud-native talent supply constraints — sit outside the modeled envelope. Forecasts reflect assumptions about protocol convergence velocity and enterprise procurement consolidation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
North America Telecom Expense Management Market
Telecommunications
Indonesia Telecom Towers Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
Belgium ICT Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Fixed Voice Market
Telecommunications
Denmark Telecom Market
Telecommunications
Underwater Modems Market
Telecommunications
LTE Emergency Networks Market
Telecommunications
5G Equipment Market
Telecommunications
Iceland Telecom Market
Telecommunications
GSM Mobile Phone Market
Telecommunications
Global IP Phone Market
Telecommunications
5G Transport Networks Market
Telecommunications
5G Monetization Market
Telecommunications
Indonesia Volte Market