
 Global Pregnancy Tracker Apps Market | 2026-2036
Global Pregnancy Tracker Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pregnancy Tracker Apps Market Foresight
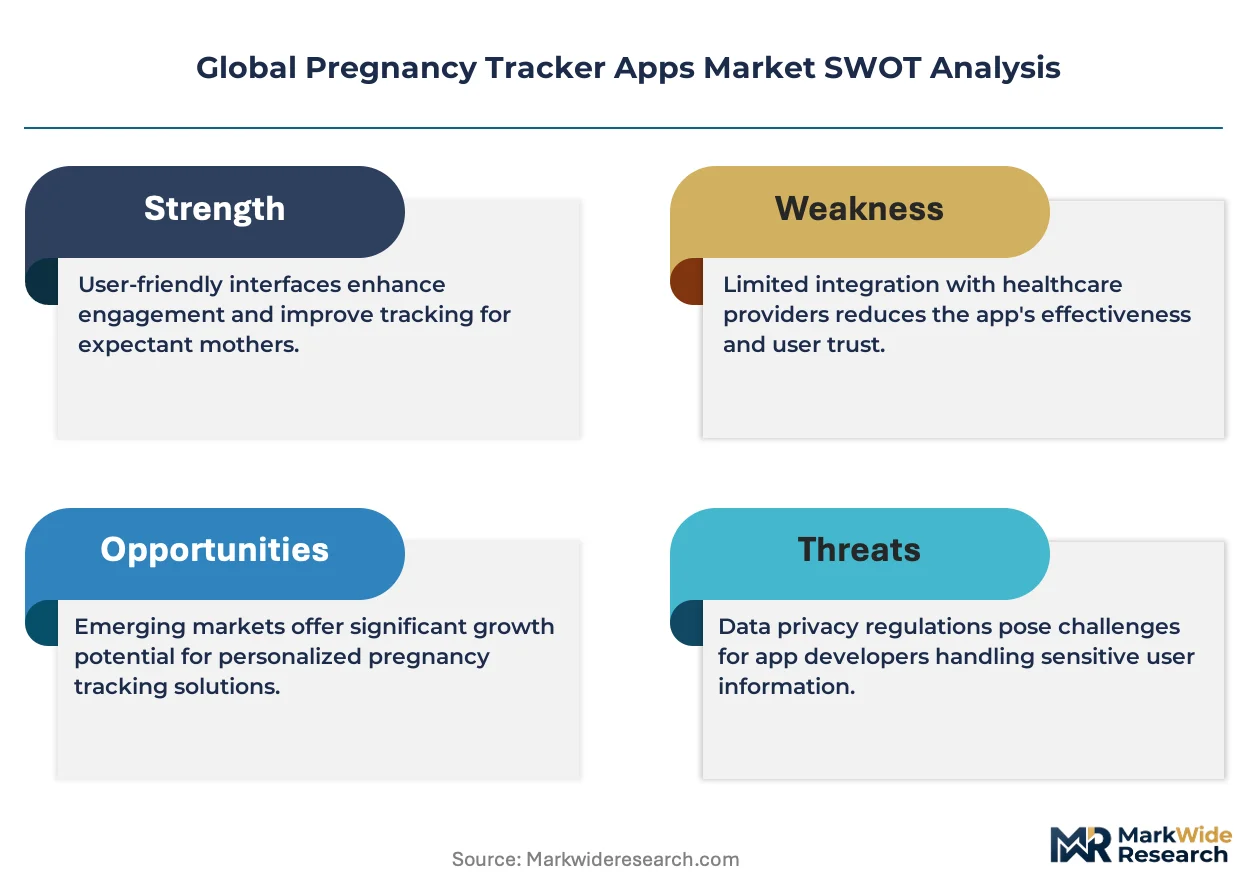
GDPR enforcement in Europe is shifting the cost-of-entry calculus for pregnancy tracker apps, forcing developers to embed privacy-by-design architectures from the first line of code. Flo leverages its Scandinavian data infrastructure to sustain compliance leadership across EU member states. BabyCenter anchors its competitive position through content depth and healthcare provider partnerships in North America. Glow Nurture differentiates via community-driven features that occupy a distinct niche against clinically oriented rivals.
Pregnancy tracker apps are software applications that capture gestational age, fetal development milestones, maternal biometrics, and appointment schedules through algorithmic parsing of user-inputted data and device sensor feeds. These tools serve the commercial purpose of reducing information asymmetry between expectant users and healthcare systems while generating longitudinal health datasets. The freemium monetization model dominates install volume but subscription tiers capture the majority of recurring revenue as users convert during second-trimester engagement peaks. iOS platforms lead in per-user monetization due to demographic skew toward higher-income households, while Android sustains broader geographic penetration across emerging markets. Healthcare practitioner-facing features represent a fast-growing segment as telemedicine protocols integrate app-generated data into prenatal workflows.
FDA oversight of Software as a Medical Device in the United States and EMA digital health guidance in Europe are tightening evidentiary standards for apps making clinical claims, reshaping product development roadmaps and liability exposure. WHO maternal health guidelines and ISO 13485 quality management standards provide additional compliance benchmarks for developers seeking credibility with institutional payers. Stakeholders must monitor evolving national reimbursement policies for digital therapeutics, as these determinations will separate subsidized clinical tools from discretionary consumer applications.
Market Dynamics
The EU AI Act's risk-classification framework for health applications is forcing pregnancy tracker developers to rearchitect data pipelines before deployment, elevating compliance costs for market entry while simultaneously creating competitive moats for early adherents.
Growth Catalysts
- Smartphone penetration in India:Massive addressable user base expansion in tier-2 and tier-3 cities where maternal healthcare infrastructure remains sparse, driving organic install velocity without paid acquisition.
- FDA Software as a Medical Device guidance:Clarified evidentiary pathways enable apps with clinical-grade biometrics to secure institutional reimbursement, unlocking B2B revenue streams from health systems.
- Remote patient monitoring protocols:Post-pandemic telemedicine integration standards in the United States now mandate structured data exchange between consumer apps and electronic health records.
Market Restraints
- GDPR Article 9 special category data processing:Health data classification triggers mandatory Data Protection Impact Assessments and potential fines up to 4% of global turnover, constraining European publisher margins.
- iOS platform dependency:Apple's 15-30% App Store commission on subscription revenue and strict HealthKit data sharing rules limit monetization flexibility for developers targeting high-ARPU demographics.
- Physiological sensor accuracy variance:Consumer-grade optical heart rate and blood oxygen sensors in Android devices produce inconsistent readings, undermining clinical credibility for algorithmic predictions.
Strategic Opportunities
- Brazil's SUS telehealth expansion:National health system digitization mandates create procurement channels for Portuguese-language apps with prenatal risk stratification capabilities.
- ISO 13485 quality management certification:Medical device-grade quality systems open institutional sales to NHS trusts in the United Kingdom and university hospital networks in Germany.
- Wearable-ECG integration:Continuous atrial fibrillation detection in third-trimester patients via Apple Watch and Samsung Galaxy Watch convergence enables premium subscription tiers for high-risk pregnancy monitoring.
Industry Challenges
- Obstetric clinical validation timelines:Prospective cohort studies required for FDA 510(k) clearance demand 18-24 month development cycles before commercial claims can be made.
- Health data interoperability standards:FHIR R4 implementation varies across Epic, Cerner, and Meditech hospital systems, forcing redundant API development for enterprise contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pregnancy Tracker Apps Market |
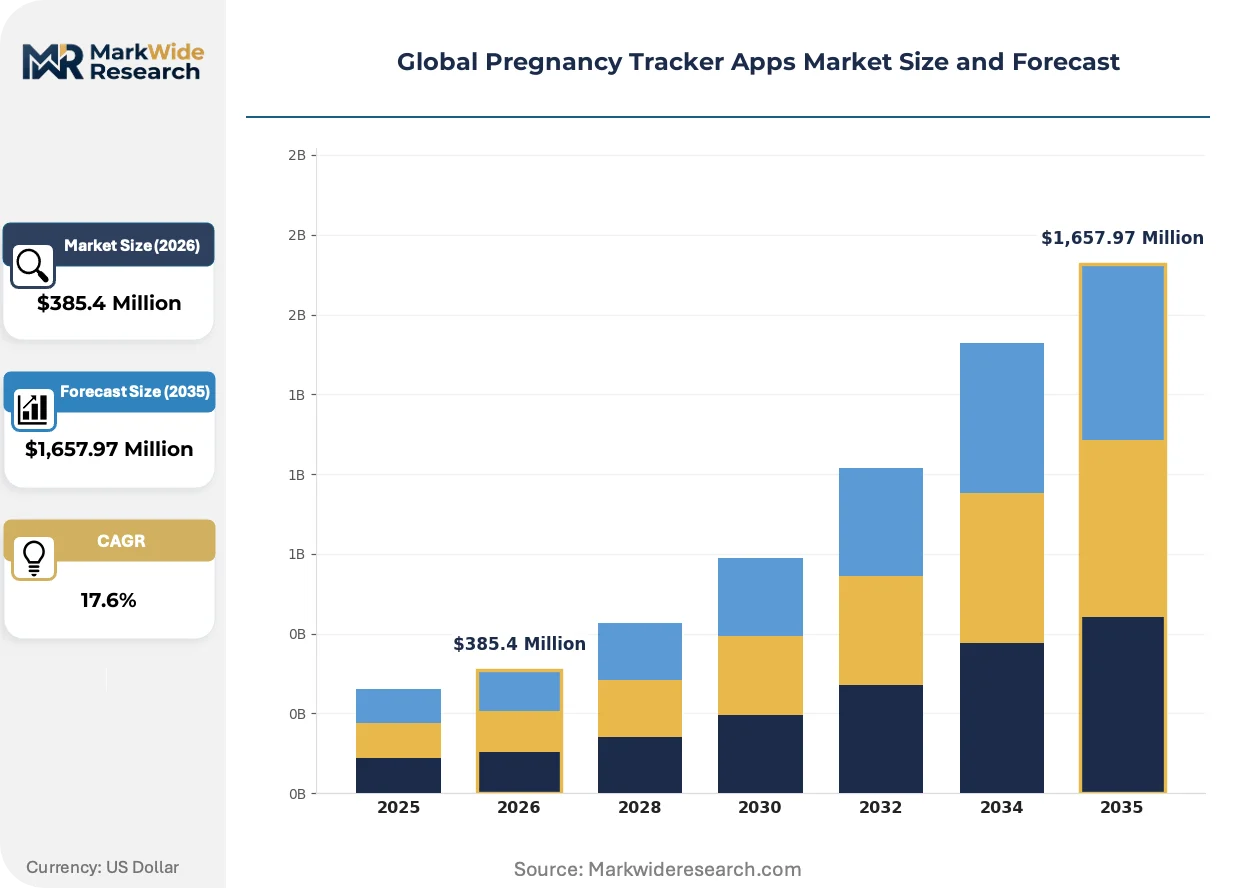
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,657.97 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: iOS, Android, Web, Windows, macOS Features: Kick Counter, Contraction Timer, Appointment Tracker, Symptom Log, Nutrition Guide, Weight Monitor End User Type: Expectant Mothers, Partners, Family Members, Healthcare Practitioners, Midwives Monetization Model: Freemium, Subscription, In-App Purchases, Advertising, Sponsored Content |
| Companies Covered | What to Expect, Sprout, BabyCenter, Flo, Glow Nurture, Ovia, The Bump, Amila, Pregnancy+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pregnancy Tracker Apps Market Shifts & Advancements
Machine learning inference at the edge is compressing latency for real-time fetal movement classification while reducing cloud infrastructure costs. Developers are racing to embed large language models for personalized symptom triage without triggering medical device regulatory thresholds.
On-device neural networks for kick-count pattern recognition and contraction timing analysis are rewriting how expectant users engage with biometric feedback. First-time mothers in the United States and China are adopting these features at 3x the rate of experienced mothers. The shift is compressing server-side processing requirements and enabling offline functionality in bandwidth-constrained environments.
The EU AI Act's high-risk system obligations for health applications took effect in February 2025, mandating conformity assessments and human oversight protocols for apps making pregnancy risk predictions. European publishers face 12-18 month compliance roadmaps. Developers are responding by stripping predictive claims from free tiers while reserving algorithmic risk scores for prescription-integrated versions under clinician supervision.
Employer-sponsored maternal health benefits are displacing direct-to-consumer subscription models as the primary acquisition channel in the United States. Large self-insured employers and benefits platforms like Maven and Carrot are bundling pregnancy tracker access into family-planning stipends. This procurement pivot concentrates demand volume among benefits administrators rather than individual app store discovery.
Global Pregnancy Tracker Apps Market Segmentation
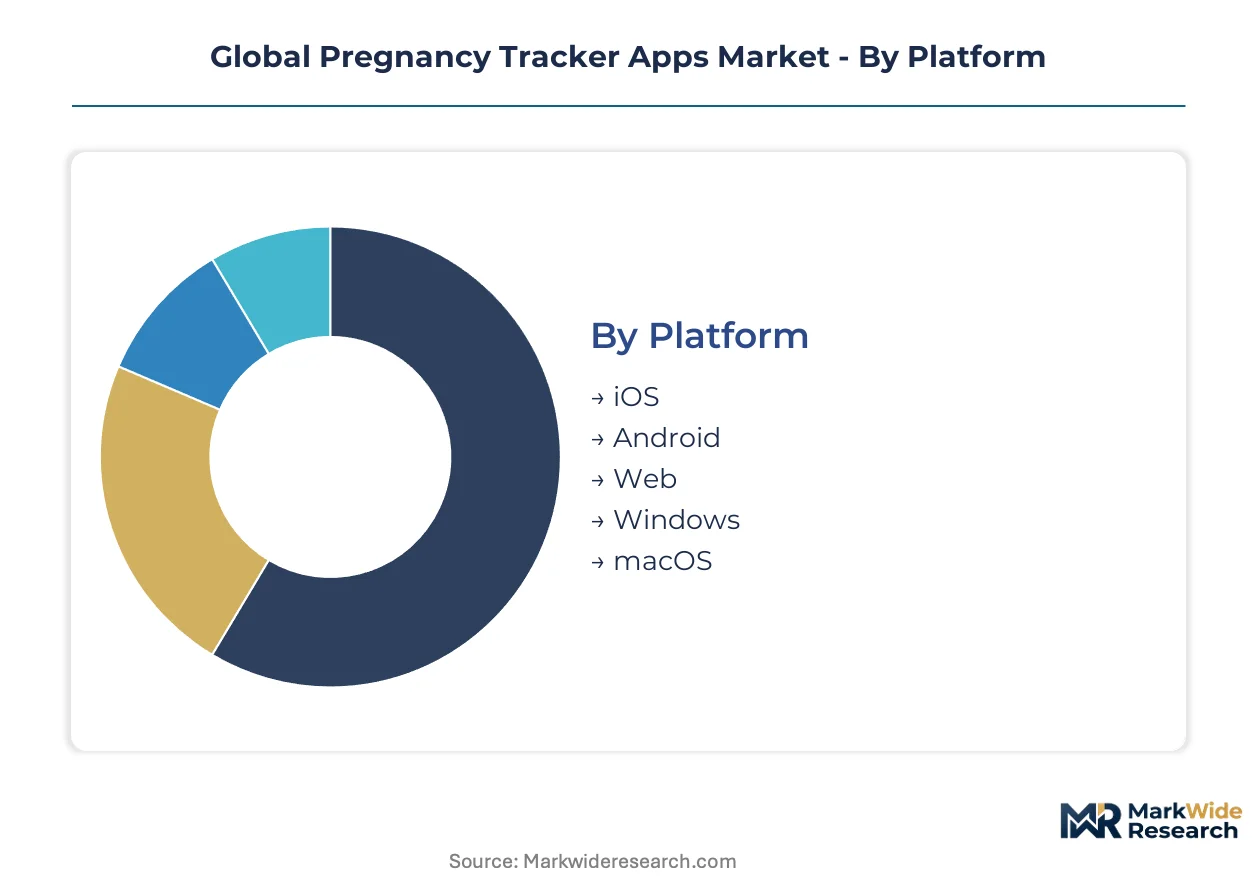
Pregnancy tracker apps fragment across platform ecosystems, feature complexity, and payment models that shape user acquisition costs and lifetime value calculations. Developers optimize segment mix to balance install velocity against revenue per user in markets with divergent smartphone penetration and healthcare reimbursement policies.
Platform:
iOS users demonstrate higher willingness to pay for maternal health subscriptions, driving monetization strategy divergence between Apple and Google ecosystems.
- iOS:Apple's HealthKit integration enables seamless biometric data ingestion from Apple Watch and connected devices. Demand concentrates in the United States and United Kingdom where household discretionary spending on maternal wellness apps exceeds comparable Android cohorts.
- Android:Device fragmentation across Samsung, Xiaomi, and Oppo hardware complicates sensor calibration for fetal movement algorithms. Install volume dominates in India and Brazil where mid-tier smartphones constitute the primary access point for first-time mothers.
- Web:Browser-based interfaces serve users in restrictive data environments and enterprise healthcare deployments requiring firewall-compliant access.
- Windows:Desktop applications target clinical settings where practitioners review longitudinal patient data on hospital workstations.
- macOS:Native applications appeal to design-conscious users in creative industries seeking aesthetic parity across Apple device ecosystems.
Volume sits with Android; growth tilts toward iOS as premium subscription tiers expand in high-income markets.
Features:
Feature bundling determines user engagement depth and conversion timing from free to paid tiers across trimester-specific need states.
- Kick Counter:Fetal movement logging with pattern recognition algorithms for third-trimester risk assessment. Demand concentrates in Germany and Japan where clinical guidelines emphasize structured kick-count protocols.
- Contraction Timer:Labor progression tracking with hospital notification integration. United States users adopt at elevated rates due to distance-based birth center access challenges in rural counties.
- Appointment Tracker:Calendar synchronization with healthcare provider scheduling systems.
- Symptom Log:Structured data capture for telemedicine consultations and prenatal record continuity.
- Nutrition Guide:Trimester-specific dietary recommendations with gestational diabetes risk modifiers.
- Weight Monitor:Biometric trend visualization against Institute of Medicine guidelines for healthy gestational weight gain.
Clinical features capture premium pricing; lifestyle content drives organic user expansion.
End User Type:
User archetype segmentation reshapes interface design priorities and data sharing permission architectures.
- Expectant Mothers:Primary data contributors requiring personalized risk communication and emotional support features. Demand concentrates in China's tier-1 cities where singleton pregnancy norms elevate digital monitoring intensity.
- Partners:Secondary account access for shared appointment visibility and task coordination. United States dual-income households demonstrate highest activation rates for partner-linked profiles.
- Family Members:Grandparent-tier access for cultural pregnancy practices in multi-generational households.
- Healthcare Practitioners:Dashboard interfaces for population-level risk stratification and intervention triage.
- Midwives:Community birth worker tools for home-based prenatal monitoring in Netherlands and United Kingdom primary care settings.
Direct user volume dominates; practitioner-facing segments climb fastest as telemedicine reimbursement codes mature.
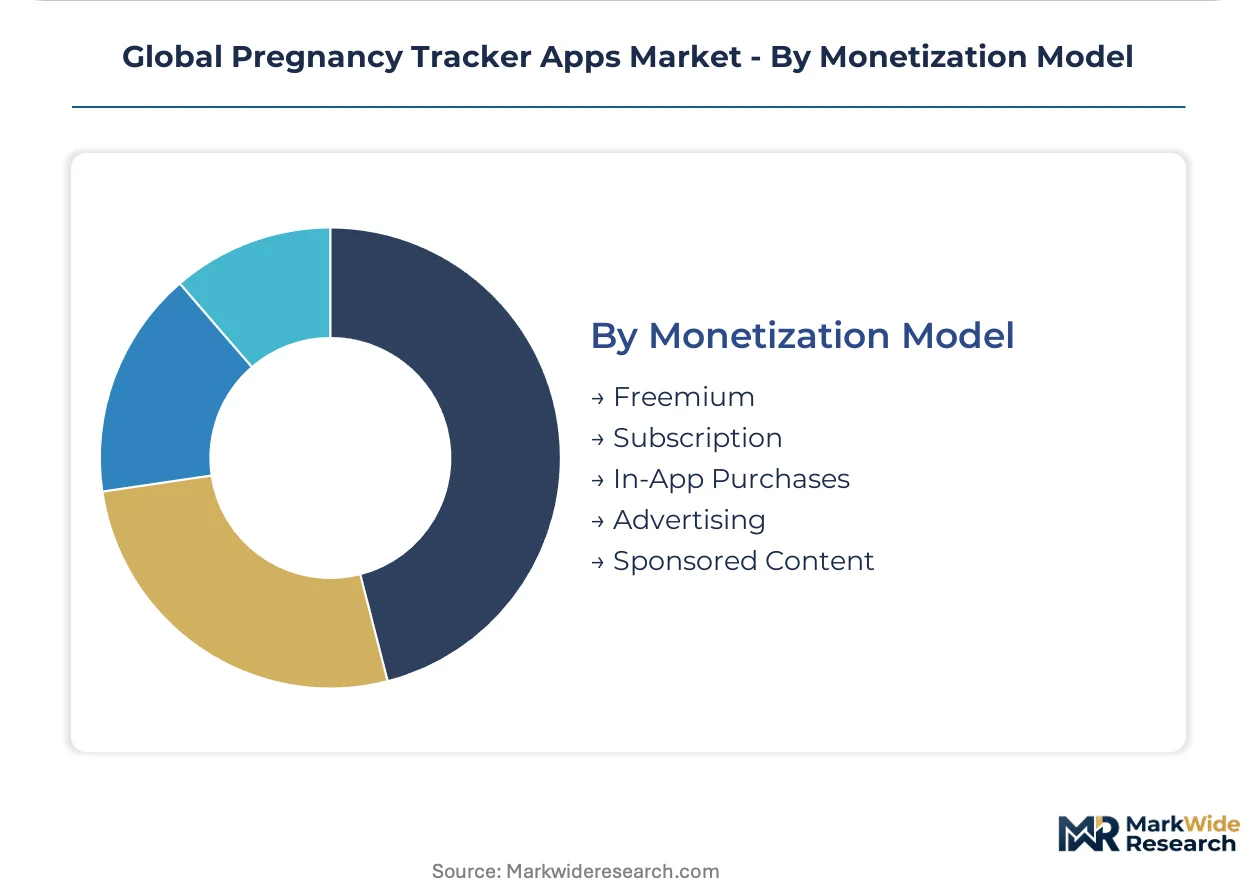
Monetization Model:
Revenue architecture selection constrains addressable market size and customer acquisition channel economics.
- Freemium:Core functionality at zero cost with feature-gated premium tiers. Install velocity peaks in India and Indonesia where price sensitivity limits upfront payment willingness.
- Subscription:Recurring revenue from trimester-spanning access to advanced analytics and provider integration. Annual plans predominate in Australia and Canada where healthcare system familiarity reduces churn risk.
- In-App Purchases:Discrete feature unlocks and content bundles for episodic needs.
- Advertising:Brand-sponsored content from maternal product and service categories.
- Sponsored Content:Healthcare system and pharmaceutical partner educational modules.
Freemium sustains scale; subscription models deepen revenue per engaged user.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Software Technology Parks of India (STPI) scheme has concentrated pregnancy app development in Bengaluru and Hyderabad, where export-oriented units claim tax holidays that subsidize GDPR-compliant data infrastructure investments.
United States
Employer-sponsored maternal health benefits and telemedicine reimbursement codes drive enterprise procurement through benefits platforms. FDA Software as a Medical Device guidance clarifies evidentiary pathways for clinical-grade biometrics. Silicon Valley and Boston clusters host developers integrating Apple Watch ECG data into high-risk pregnancy monitoring protocols.
Germany
Structured kick-count protocols in prenatal care guidelines elevate demand for fetal movement pattern recognition. EU AI Act high-risk system obligations mandate conformity assessments for algorithmic risk predictions. Berlin and Munich health tech clusters focus on ISO 13485 certification for NHS trust and university hospital network sales.
China
Singleton pregnancy norms in tier-1 cities intensify digital monitoring adoption among expectant mothers. NMPA digital health guidance shapes product development roadmaps for apps seeking clinical credibility. Shenzhen and Shanghai hardware-software convergence clusters enable wearable-ECG integration for third-trimester atrial fibrillation detection.
Brazil
SUS telehealth expansion mandates create procurement channels for Portuguese-language prenatal risk stratification tools. ANVISA digital health oversight elevates compliance requirements for clinical claim substantiation. São Paulo and Rio de Janeiro clusters develop apps targeting community birth worker integration in public health system workflows.
United Kingdom
NHS digital maternity transformation programs fund procurement of apps with FHIR R4 electronic health record interoperability. GDPR Article 9 special category data processing rules trigger mandatory Data Protection Impact Assessments. London and Manchester health tech clusters pursue ISO 13485 quality management certification for trust-level institutional contracts.
Global Pregnancy Tracker Apps Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across platform ecosystems and feature complexity tiers. Market structure tilts toward consolidation around established publishers with compliant data infrastructure, though niche entrants persist in localized content and community-driven engagement models. Three archetypes dominate: Scandinavian privacy-first platforms leveraging GDPR-native architectures, North American content-depth incumbents with healthcare provider partnerships, and community-centric challengers occupying distinct niches against clinically oriented rivals. Competitive moves concentrate on M&A for data infrastructure capabilities and strategic partnerships with benefits administrators displacing direct-to-consumer acquisition channels.
Among the privacy-first tier, Flo exemplifies Scandinavian data governance leadership sustaining compliance across EU member states. BabyCenter anchors North American positioning through content depth and institutional healthcare relationships. Glow Nurture occupies the community-driven niche with partner-linked profile features targeting dual-income household coordination. These three represent divergent strategic bets on regulatory compliance, clinical credibility, and social engagement as primary differentiation vectors.
| Leading Market Players |
|---|
| What to Expect |
| Sprout |
| BabyCenter |
| Flo |
| Glow Nurture |
| Ovia |
| The Bump |
| Amila |
| Pregnancy+ |
| Others |
Supply & Pricing Matrix
EU AI Act conformity assessment mandates gate qualified supply and premium-tier pricing access for pregnancy tracker apps, forcing developers to embed privacy-by-design architectures from initial code commits or forfeit institutional procurement channels. Compliance-ready publishers command subscription premiums while non-compliant apps face margin compression from excluded enterprise contracts.
Pricing Analysis
Short lead-time deployment for ISO 13485-certified versions commands 40-60% subscription premiums over standard freemium tiers. Pricing stratifies across prescription-integrated clinical tiers, direct-to-consumer premium tiers, and ad-supported economy tiers. Cost compression in the ad-supported tier is intensifying because employer-sponsored benefits procurement concentrates demand volume away from individual app store discovery. First-time mothers in employer-sponsored programs demonstrate lowest price sensitivity; users in India's tier-2 cities show highest sensitivity.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler concentration in the United States, Ireland, and Singapore, with compute and storage dependencies feeding from AWS, Azure, and Google Cloud platforms. Specialized ML inference chips and biometric sensor calibration datasets constitute critical inputs. Single-source vulnerability runs through Apple's HealthKit API and Google's Fit SDK, which control downstream data pipeline access. Distribution runs through Apple App Store and Google Play Store duopoly structures with 15-30% commission extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pregnancy tracker market sits in an edge-AI transition phase, with on-device neural networks replacing cloud-dependent processing for fetal movement classification and latency-sensitive biometric feedback.
For Market Incumbents: To counter employer-sponsored benefits platform consolidation, deepen FHIR R4 interoperability investments and pursue ISO 13485 certification for NHS trust and university hospital network access. Acquire GDPR-native data infrastructure capabilities to sustain EU AI Act compliance leadership as conformity assessment mandates tighten. For New Entrants and Emerging Players: Begin with Brazil's SUS telehealth procurement channels and India's tier-2 city organic install velocity, where maternal healthcare infrastructure gaps create addressable white space. Target community birth worker integration in Netherlands and United Kingdom primary care settings as the most penetrable practitioner-facing segment. Pursue Portuguese-language localization and ANVISA digital health guidance alignment as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA 510(k) clearance submission for algorithmic risk prediction features is the leading indicator that clinical credibility translation into institutional reimbursement is imminent. Five-to-ten year viability favors publishers with compliant data infrastructure and healthcare system integration depth over community-centric challengers. Acquisition target archetype: Scandinavian privacy-first platforms with GDPR-native architectures. Watch employer-sponsored benefits platform bundling announcements as the signal for demand channel inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Pathway | Medical device-grade quality systems unlock NHS trust and German university hospital procurement. |
| FHIR R4 Interoperability Investment | Structured EHR data exchange mandates in US telemedicine protocols enable enterprise contract capture. |
| Edge-AI Feature Development | On-device neural networks for kick-count recognition reduce cloud costs and enable offline functionality. |
| Employer Benefits Platform Partnership | Maven and Carrot bundling displace direct-to-consumer acquisition with concentrated demand volume. |
| Wearable-ECG Integration Launch | Apple Watch and Samsung Galaxy Watch convergence enables premium tiers for high-risk pregnancy monitoring. |
Research Methodology
Multi-period observation of app install velocity, subscription conversion timing, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with pregnancy app product managers, maternal-fetal medicine specialists, hospital procurement officers, and benefits platform executives. Secondary validation drew from FDA 510(k) filings, EMA digital health guidance documents, NHS digital maternity transformation program reports, and App Annie/Sensor Tower engagement metrics. Bottom-up cohort analysis and top-down market sizing triangulated volume and value estimates.
Input-output matrices modeled user acquisition costs against lifetime value across platform ecosystems, feature complexity tiers, and monetization models. Segmentation dimensions included deployment platform, clinical feature bundle, end-user archetype, and regional reimbursement policy cluster. CAGRs derived from fitted growth curves applied to smartphone penetration trajectories and maternal health awareness indices. Forecast inputs incorporated EU AI Act implementation pacing and employer-sponsored benefits adoption curves.
Underlying measurement precision varies by segment; iOS monetization metrics and US employer-sponsored procurement data carry tighter precision than Android install estimates in India's tier-3 cities. Forecasts reflect documented assumptions about regulatory enforcement intensity and telemedicine reimbursement code expansion. Trigger events including FDA SaMD guidance updates, GDPR Article 9 enforcement actions, and national digital health procurement mandate announcements warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Luxury Car Market
Others
Vortexers Market
Others
Boston Round Bottle Market
Others
Hearables Market
Others
Global Hardware Acceleration Market
Others
Binoculars Market
Others
Digital Thermal Plates Market
Others
Software Synthesizers Market
Others
Hip Tendinitis Market
Others
Middle East and Africa Induced Pluripotent Stem Cells (Ipscs) Market
Others
Augmented Reality in Energy and Utilities Market
Others
Fluid Bed Systems Market
Others
Italy Smart Home Market
Others
Global Hydraulics Market
Others
Telecom Transformers Market
Others
Composite Copper Foil Production Equipment Market