
 Composite Copper Foil Production Equipment Market | 2026-2036
Composite Copper Foil Production Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Copper Foil Production Equipment Market Insights
Direct sales from equipment builders to battery cell manufacturers is reshaping channel economics in composite copper foil production equipment. PNT (People and Technology Inc.) anchors Korean supply relationships through localized service networks. Xi'an Taijin Xinneng Technology dominates domestic Chinese installations with vertically integrated commissioning capabilities. De Nora Permelec leverages electrochemical expertise to differentiate its electroplating unit portfolio.
Composite copper foil production equipment encompasses machinery engineered to manufacture ultra-thin copper layers bonded to polymer substrates, typically achieving thicknesses below six micrometers for current collector applications in energy storage systems. Electroplating units and vacuum coating systems constitute the highest-margin equipment categories as cell producers demand pinhole-free barrier layers. Hot rolling technology occupies mature installed bases while electrochemical deposition captures fastest-growing adoption among flexible circuit board fabricators. Surface treatment systems sustain premium pricing through proprietary adhesion chemistry integration.
China's MIIT enforces GB standards for electrolytic copper foil used in power batteries, compelling equipment upgrades that eliminate surface contamination. South Korea's MFDS aligns with OECD chemical safety frameworks for battery material processing, shaping export qualification protocols for foil producers. Japan's METI subsidizes domestic equipment replacement under green transformation bonds. Stakeholders must monitor which regulatory convergence between Asian battery material standards determines equipment interoperability specifications.
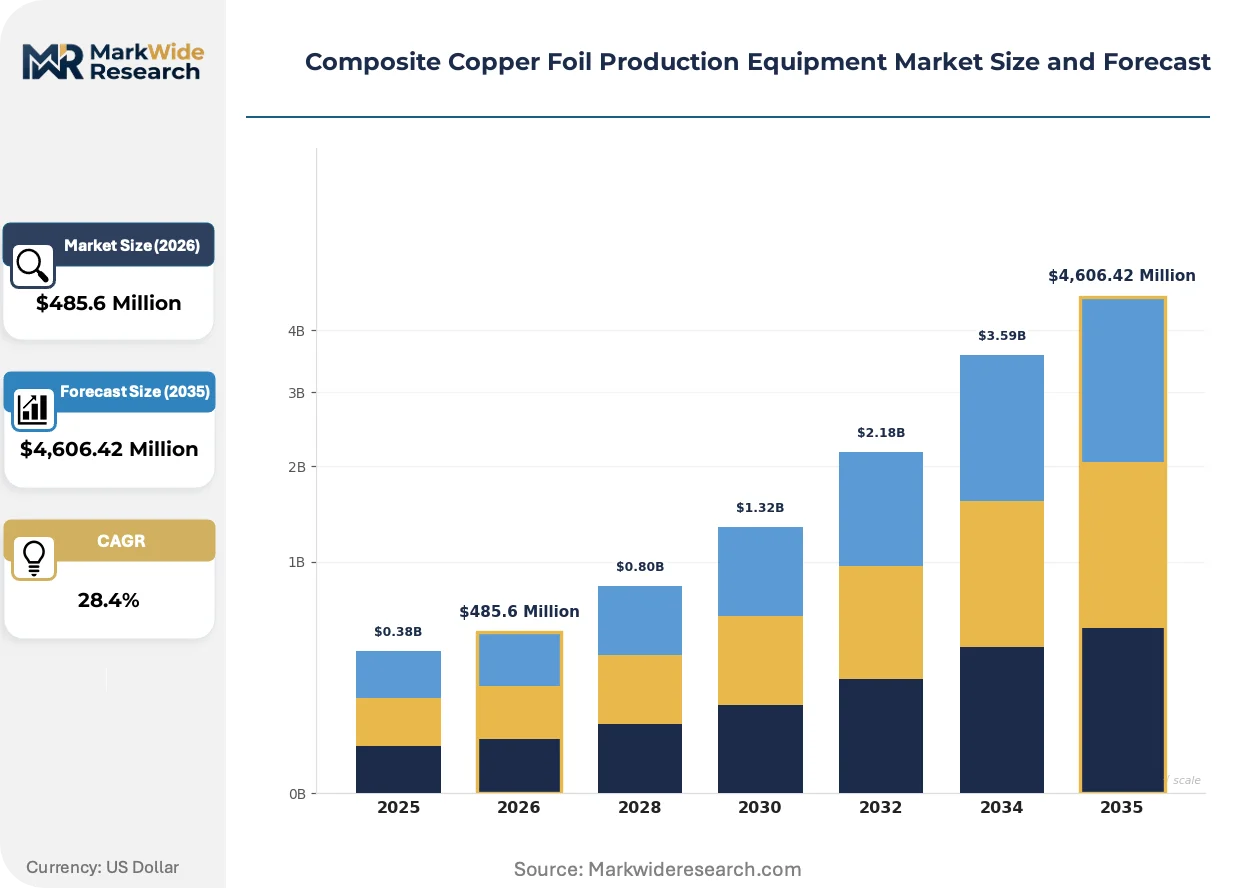
Market Dynamics
Equipment procurement patterns in composite copper foil production are restructuring around battery cell manufacturers' migration toward polymer-substrate current collectors, with China's NMPA purity mandates and South Korea's MFDS chemical safety protocols forcing simultaneous compliance investments across Asian supply chains.
Growth Catalysts
- MIIT GB Standard Enforcement:China's power battery electrolytic copper foil regulations mandate contamination-free surface processing, compelling equipment replacement cycles among domestic manufacturers.
- Electrochemical Deposition Adoption:Flexible circuit board fabricators are accelerating uptake of electroplating units over hot rolling systems for sub-six-micrometer precision.
- Gumi-Cheonan Industrial Corridor Concentration:South Korean cathode makers cluster demand within specific Korean industrial zones, creating localized equipment procurement density.
Market Restraints
- High-Purity Copper Input Volatility:Electrolytic copper cathode price swings directly compress margins on electroplating unit operations.
- East Asian Equipment Supply Concentration:Korean and Chinese builders dominate vacuum coating system fabrication, creating single-source vulnerability for Western buyers.
- Pinhole Detection Technical Ceiling:Current optical inspection systems struggle to reliably identify sub-micrometer barrier layer defects at production speeds.
Strategic Opportunities
- Japan METI Green Transformation Bonds:Domestic equipment replacement subsidies create captive demand for precision coating system upgrades.
- Solid-State Battery Current Collector Requirements:Next-generation cell architectures demand novel composite foil geometries that legacy rolling equipment cannot produce.
- Direct Manufacturer-to-Cell-Producer Channels:Equipment builders bypass distribution intermediaries to capture service revenue through embedded commissioning contracts.
Industry Challenges
- Electrochemical Process Engineering Talent Scarcity:Plating chemistry expertise for polymer substrate adhesion remains concentrated among Korean and Japanese specialist workforces.
- Proprietary Adhesion Chemistry IP Complexity:Surface treatment system vendors face patent thickets around polymer-copper bonding agents that delay new market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Copper Foil Production Equipment Market |
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $4,606.42 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Rolling Machines, Annealing Furnaces, Electroplating Units, Surface Treatment Systems, Slitting Machines Technology: Hot Rolling, Cold Rolling, Electrochemical Deposition, Vacuum Coating, Thermal Lamination Application: Flexible Circuit Boards, Battery Separators, Electromagnetic Shielding, Printed Wiring Boards, Thermal Management Solutions End User Industry: Consumer Electronics, Renewable Energy, Aerospace Components, Telecommunications, Electric Vehicles |
| Companies Covered | Newlong Akita, Xi'an Taijin Xinneng Technology, PNT (People and Technology Inc.), Akahoshi, Shanghai Zhaosheng Electromechanical Equipment, De Nora Permelec, MIFUNE Corporation, Core Steel, Wuxi Lead Intelligent Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Copper Foil Production Equipment Market Trends and Innovations
Manufacturing technology trajectories in composite copper foil production are converging on precision deposition methods that eliminate mechanical stress on ultra-thin substrates, while regulatory chemistry restrictions and procurement centralization reshape how equipment value is captured.
Roll-to-roll magnetron sputtering systems for polymer substrate metallization are achieving thickness uniformity below three percent across meter-scale widths. Korean battery cell producers are specifying these vacuum coating platforms for pilot lines ahead of mass production scaling. Hot rolling mills for traditional foil production are rendering obsolete for current collector applications below eight micrometers.
REACH chemical authorization requirements for chromium-based surface treatments are restricting adhesion promoter chemistries in European-bound foil production. Equipment vendors must qualify alternative polymer activation processes that maintain peel strength without hexavalent chromium. Surface treatment system configurations for EU export markets are shifting toward plasma-based activation modules.
Cell manufacturers now bundle equipment procurement with multi-year technical service agreements that transfer commissioning risk to builders. Korean cathode producers lead this contracting evolution, unbundling hardware purchase from operational qualification support. Equipment margins are compressing on unit sales while expanding on embedded service contracts.
Composite Copper Foil Production Equipment Market Segmentation
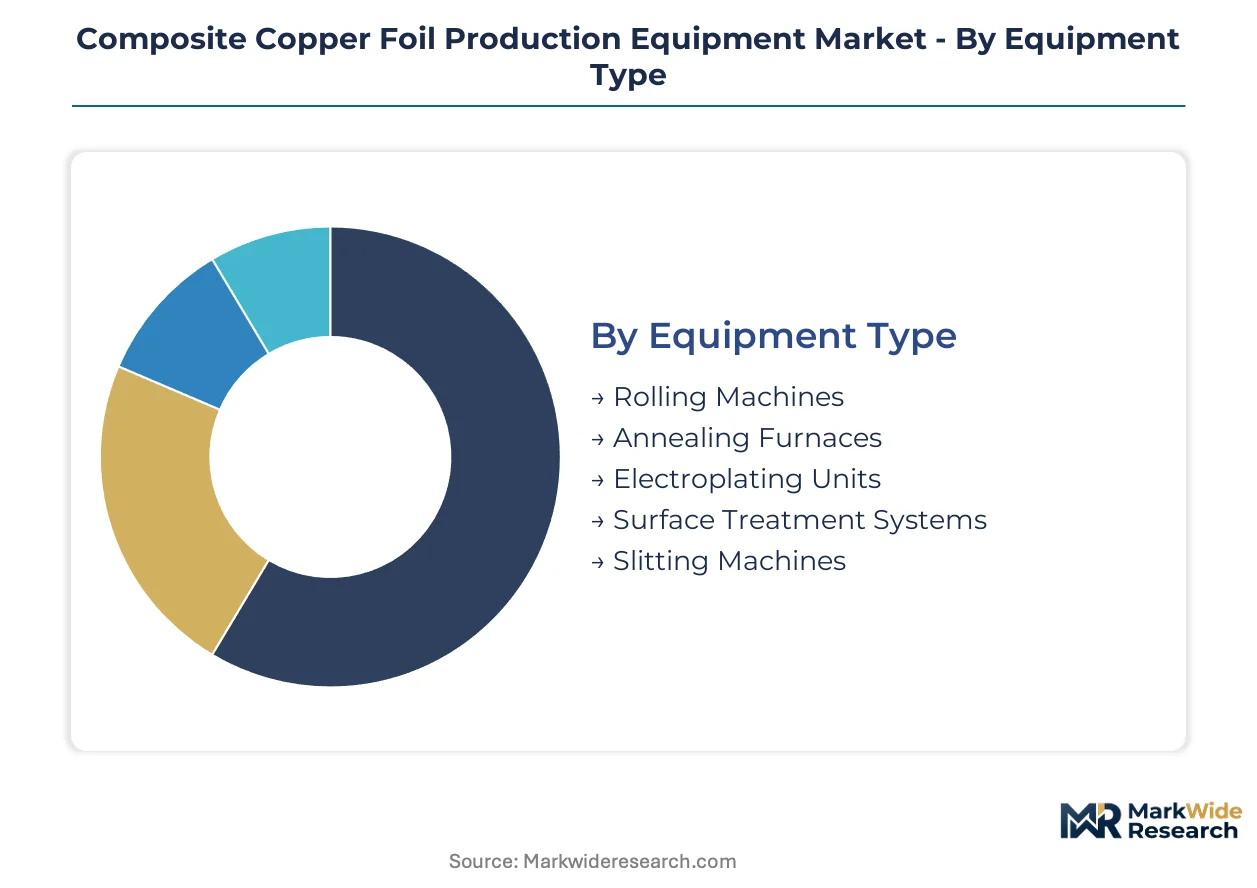
Equipment procurement in composite copper foil production fragments across multiple technical dimensions. Cell manufacturers prioritize deposition precision over mechanical forming, while regulatory chemistry constraints reshape surface treatment specifications across Asian supply chains.
Equipment Type:
Cost tier separation in machinery procurement reflects margin capture potential from process-critical versus auxiliary functions.
- Electroplating Units:These systems deposit sub-six-micrometer copper layers onto polymer substrates through controlled electrochemical cells. Korean cathode producers in the Gumi-Cheonan corridor specify these for pilot line qualification ahead of mass production scaling.
- Surface Treatment Systems:Proprietary adhesion chemistry modules activate polymer substrates before metallization, sustaining premium pricing through integrated process control. China's MIIT GB standards for contamination-free surfaces compel upgrades among domestic battery material producers.
- Rolling Machines:Mechanical reduction mills for traditional foil production above eight micrometers.
- Annealing Furnaces:Heat treatment systems for grain structure refinement in rolled copper.
- Slitting Machines:Width customization equipment for downstream coil processing.
Electroplating units hold installed capacity. Surface treatment systems are rotating up the share rankings.
Technology:
Application requirements determine which deposition method captures volume, with precision thresholds and substrate compatibility driving selection.
- Vacuum Coating:Roll-to-roll magnetron sputtering achieves thickness uniformity below three percent across meter-scale polymer webs. Japanese equipment builders leverage METI green transformation subsidies to displace legacy mechanical forming in domestic installations.
- Electrochemical Deposition:Plating chemistry expertise for polymer substrate adhesion concentrates among Korean and Japanese specialist workforces, creating capability scarcity that extends delivery timelines for Western buyers.
- Hot Rolling:Mature mechanical reduction for foil above eight micrometers, now obsolete for EV battery current collectors.
- Cold Rolling:Room-temperature thickness reduction with work hardening for structural foil grades.
- Thermal Lamination:Bonding pre-formed copper foils to carrier substrates for specific shielding applications.
Vacuum coating commands the steepest expansion trajectory. Electrochemical deposition retains the largest operational installed base.
Application:
End-use performance specifications create divergent equipment requirements across electronics and energy storage segments.
- Battery Separators:Composite foil architectures for lithium-ion current collectors demand pinhole-free barrier layers below six micrometers. China's NMPA purity mandates and dual carbon goals tighten material standards that equipment must achieve.
- Flexible Circuit Boards:Substrate conformability requirements drive electrochemical deposition adoption over mechanical forming for precision traces.
- Electromagnetic Shielding:Conductive laminate specifications for consumer electronics enclosures.
- Printed Wiring Boards:Traditional rigid substrate metallization with established hot rolling supply chains.
- Thermal Management Solutions:Heat spreader applications with thickness tolerances less stringent than battery grades.
Battery separators concentrate new order intake. Flexible circuit boards maintain steady replacement demand.
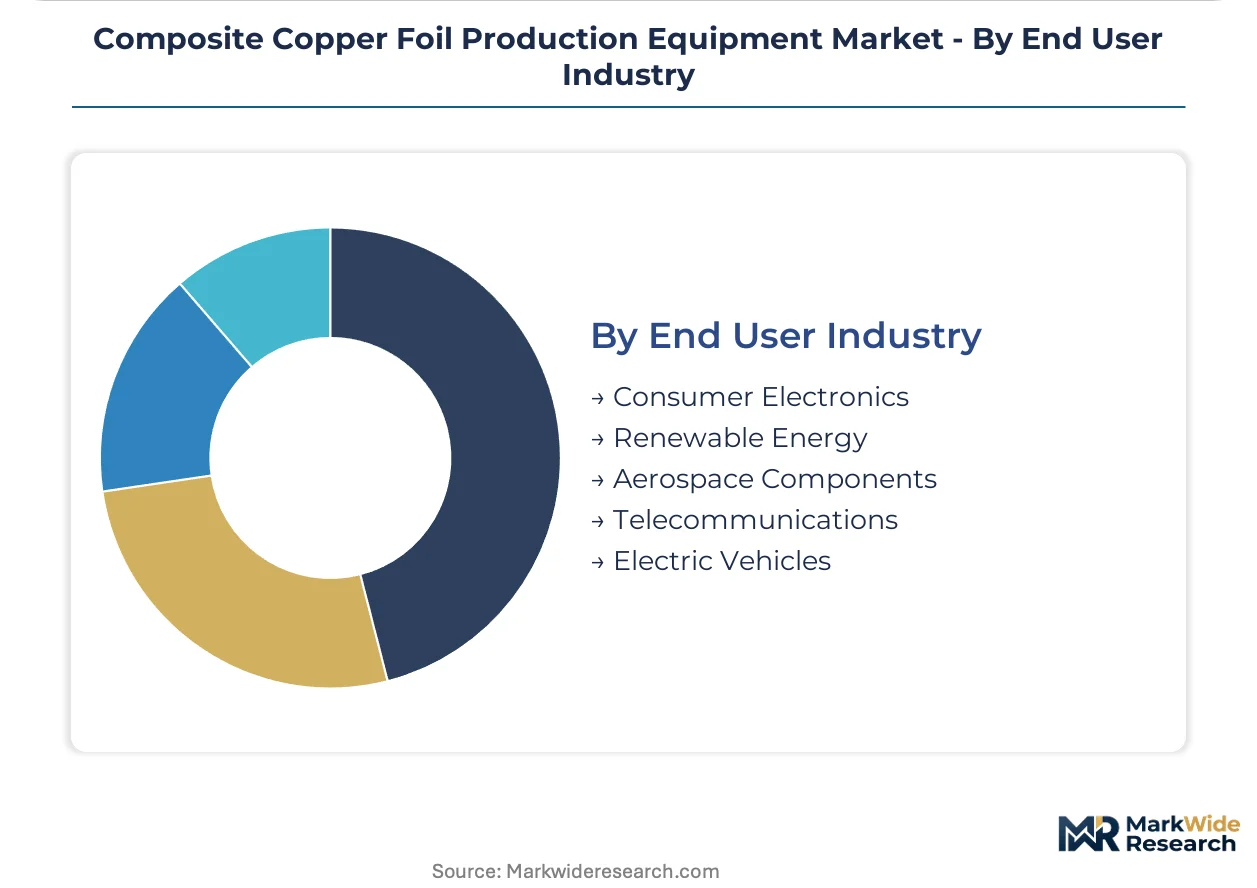
End User Industry:
Customer type segmentation reveals which downstream sectors command equipment builder attention through multi-year contracting volume.
- Electric Vehicles:Cell producers specify composite foil equipment for next-generation current collector architectures that reduce weight and improve safety. Direct manufacturer-to-cell-producer channels are displacing distribution intermediaries through embedded commissioning contracts.
- Consumer Electronics:Smartphone and wearable OEMs drive flexible circuit board equipment demand with annual model cycles requiring rapid reconfiguration capability.
- Renewable Energy:Grid storage battery producers with longer qualification timelines than automotive.
- Telecommunications:5G infrastructure shielding and antenna substrate requirements.
- Aerospace Components:Qualification-intensive applications with extended certification periods.
Electric vehicles anchor forward equipment commitments. Consumer electronics provides the most predictable near-term revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT enforces GB standards that compel equipment upgrades across battery material supply chains, while South Korea's MFDS chemical safety protocols and Japan's METI green transformation subsidies create parallel regulatory momentum in East Asia.
China
Domestic battery cell producers drive electroplating unit procurement as NMPA purity mandates tighten material standards. The MIIT GB standard enforcement for power battery electrolytic copper foil eliminates surface contamination risks. Xi'an and Wuxi industrial zones concentrate equipment installations where vertically integrated builders capture commissioning contracts.
South Korea
Cathode manufacturers cluster demand within the Gumi-Cheonan corridor for pilot line qualification ahead of mass production scaling. The MFDS aligns with OECD chemical safety frameworks for battery material processing. PNT anchors localized service networks that secure multi-year technical service agreements with cell producers.
Japan
Domestic equipment replacement accelerates under METI green transformation bond subsidies for precision coating system upgrades. Roll-to-roll magnetron sputtering platforms displace legacy mechanical forming in domestic installations. Nagoya and Osaka metropolitan areas host specialized plating chemistry expertise for polymer substrate adhesion.
Germany
REACH chemical authorization requirements for chromium-based surface treatments restrict adhesion promoter chemistries in European-bound foil production. Equipment vendors qualify alternative polymer activation processes that maintain peel strength without hexavalent chromium. Bavaria and Baden-Württemberg concentrate automotive battery material research facilities.
United States
Solid-state battery current collector requirements drive novel composite foil geometries that legacy rolling equipment cannot produce. The EPA oversees chemical safety in surface treatment processes while state-level clean energy mandates accelerate EV battery supply chain localization. Michigan and Texas industrial corridors attract equipment pilot installations.
Composite Copper Foil Production Equipment Market Competitive Landscape
Electrochemical specialists and vacuum coating fabricators split the market along deposition technology lines. Korean and Chinese builders dominate vacuum coating system fabrication, creating concentrated supply relationships with battery cell manufacturers. Three strategic archetypes define competitive positioning: vertically integrated domestic champions, precision coating technology licensors, and electrochemical process engineering specialists. Capacity expansion and embedded service contracting represent the dominant competitive moves as hardware margins compress.
Among East Asian equipment specialists, Xi'an Taijin Xinneng Technology and PNT (People and Technology Inc.) exemplify the vertically integrated archetype through localized commissioning capabilities. De Nora Permelec occupies a position within the electrochemical technology tier, representing precision coating expertise derived from electrochemical process heritage. These three companies anchor the competitive structure through differentiated access to plating chemistry talent and polymer substrate adhesion intellectual property.
| Leading Market Players |
|---|
| Newlong Akita |
| Xi'an Taijin Xinneng Technology |
| PNT (People and Technology Inc.) |
| Akahoshi |
| Shanghai Zhaosheng Electromechanical Equipment |
| De Nora Permelec |
| MIFUNE Corporation |
| Core Steel |
| Wuxi Lead Intelligent Equipment |
| Others |
Pricing and Supply Chain Analysis
Single-source vulnerability in Korean vacuum coating system fabrication determines both pricing tier spreads and supply chain shape, as Western battery cell producers face extended delivery timelines and limited negotiation leverage against concentrated East Asian equipment builders.
Pricing Analysis
Configured-to-order pricing for electroplating units commands spreads of 40-60% above standard surface treatment system baselines, driven by integration complexity and proprietary adhesion chemistry modules. Three-tier pricing structure across premium, standard, and economy levels separates turnkey commissioning packages from bare equipment sales. Pricing pressure stems from high-purity copper cathode input volatility compressing margins on electrochemical deposition operations. EV battery cell manufacturers exhibit lowest price sensitivity due to qualification timelines, while flexible circuit board fabricators drive hardest bargain on replacement cycles.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for Western equipment buyers seeking to localize composite foil production capabilities. Equipment fabrication concentrates in China, South Korea, and Japan, with vacuum coating system assembly anchored in Korean industrial corridors. Raw material dependencies span high-purity electrolytic copper cathodes, specialized polymer substrates, and precision magnetron sputtering targets. Distribution runs through direct manufacturer-to-cell-producer channels that displace traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The composite copper foil production equipment market represents a high-growth disruption as solid-state battery architectures force obsolescence of legacy mechanical forming equipment and create captive demand for precision deposition systems.
For Market Incumbents: Build captive plating chemistry expertise as the primary moat against emerging vacuum coating specialists. Acquire Korean or Japanese electrochemical process engineering talent pools before capability scarcity extends delivery timelines further. Expand surface treatment system service revenue through embedded multi-year technical agreements that transfer commissioning risk. Lock in Gumi-Cheonan corridor relationships through localized spare parts inventories. For New Entrants and Emerging Players: Geographic underpenetration in North American equipment installation base offers the most accessible white-space target. Target solid-state battery pilot line qualification contracts in Michigan and Texas industrial corridors where legacy rolling equipment cannot meet novel current collector geometries. Qualify plasma-based polymer activation modules for REACH-compliant European export markets as differentiation angle. Partner with domestic copper foil producers seeking to bypass Korean and Chinese supply concentration. For Investors and Strategic Acquirers: China's NMPA purity mandate enforcement reshapes the acquisition landscape toward equipment builders with vertically integrated commissioning capabilities. Frame long-term viability around electrochemical deposition technology retention as vacuum coating captures fastest growth but plating retains largest installed base. Target acquisition archetype: mid-cap specialists with proprietary adhesion chemistry IP and established Korean or Japanese technical workforces. Monitor solid-state battery cell producer capital expenditure announcements as inflection indicator for composite foil equipment order acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plating Chemistry | Captive supply of proprietary adhesion agents locks in surface treatment system margins against REACH chemical restrictions. |
| Direct Manufacturer-to-Cell-Producer Channel Expansion | Embedded commissioning contracts with Korean cathode producers in Gumi-Cheonan corridor displace distribution intermediaries. |
| Plasma-Based Polymer Activation Module Qualification | Alternative surface treatment configurations maintain EU export market access without hexavalent chromium chemistries. |
| Electrochemical Process Engineering Talent Acquisition | Korean and Japanese specialist workforce concentration creates capability scarcity that extends delivery timelines for competitors. |
| Roll-to-Roll Magnetron Sputtering Platform Deployment | Thickness uniformity below three percent across meter-scale widths meets NMPA purity mandates for battery separator applications. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with equipment procurement directors at battery cell manufacturers, electroplating unit commissioning engineers, surface treatment system vendors, and MIIT regulatory compliance officers; and secondary validation through SEC filings of listed equipment builders, Korean MFDS chemical safety framework documentation, Japanese METI green transformation bond disbursement records, and China customs trade data for electroplating unit imports. Bottom-up equipment installation tracking and top-down battery cell production capacity modeling provided triangulation.
Forecast inputs considered equipment type segmentation across electroplating units, vacuum coating systems, surface treatment systems, and mechanical forming equipment; technology trajectories spanning electrochemical deposition, magnetron sputtering, and thermal lamination; and application demand from battery separators, flexible circuit boards, and electromagnetic shielding. CAGRs were derived from segment-level growth rate blending weighted by projected order intake mix. Industry-specific forecast inputs incorporated NMPA purity mandate compliance timelines and solid-state battery pilot line qualification schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic champions or accelerated METI subsidy disbursement would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Learning Analytics Market
Others
Global Optical Comparator Market
Others
Stichtite Market
Others
HPHT Diamond Cubic Press Market
Others
Global ESD Protection Devices Market
Others
Mine Rescue Vehicle Market
Others
Short Video Applications Market
Others
Next Gen Video Codecs Market
Others
Mainframe Market
Others
Retail Digital Signage Market
Others
Thailand Travel Retail Market
Others
DNA Data Storage Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Embedded Computer Market
Others
Global Hardware As a Service (Haas) Market
Others
Global Automotive LED Lighting Market