
 Isovaleryl Chloride Market | 2026-2036
Isovaleryl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Isovaleryl Chloride Market Analytics
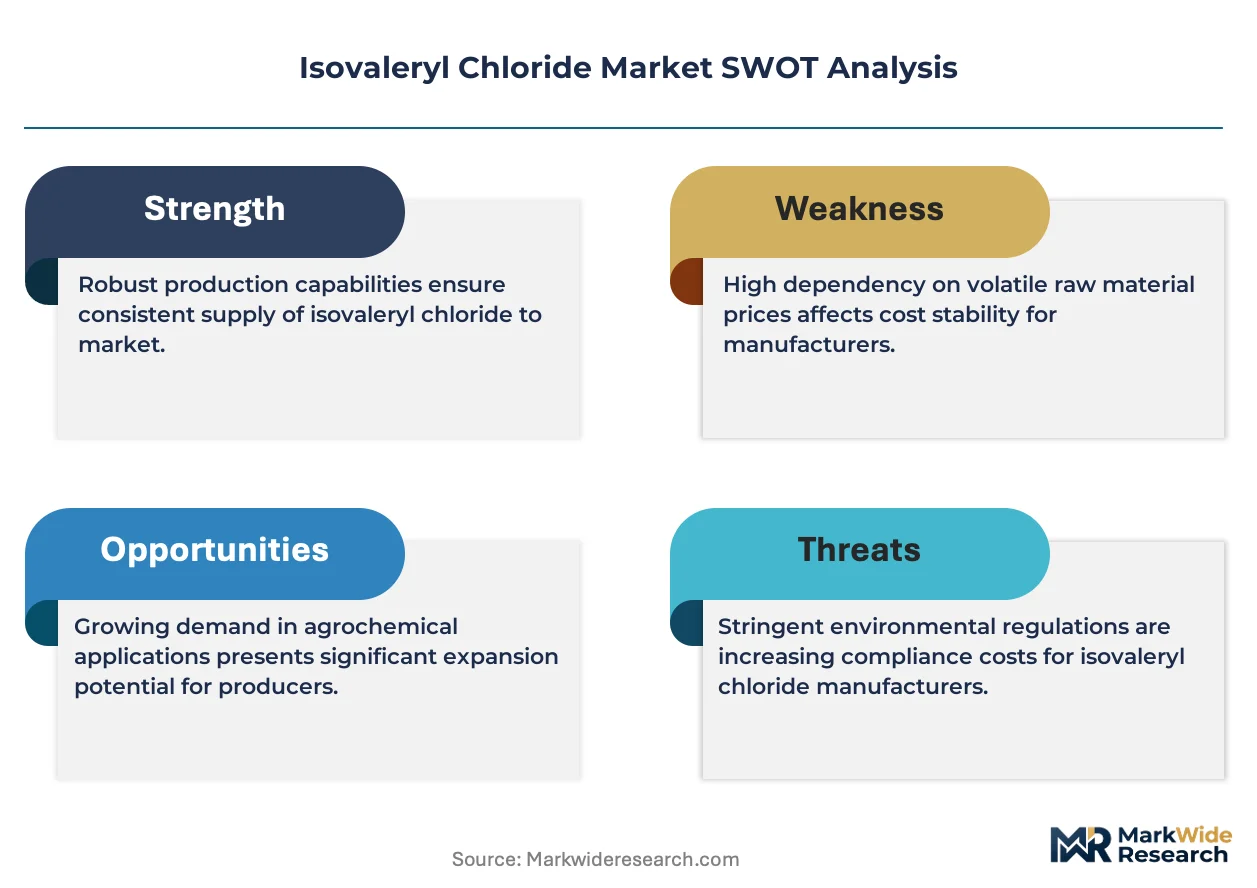
The gap between pharmaceutical-grade and industrial-grade isovaleryl chloride is realigning procurement strategies across the supply base. BASF SE leverages its integrated acyl chloride platform to sustain margin capture in high-specification segments, while CABB Group GmbH anchors European supply through dedicated chlorination infrastructure. Shiva Pharmachem Ltd. competes on cost-optimized batches for fragrance and agrochemical buyers, occupying a distinct tier below pharma-focused rivals.
Isovaleryl chloride is an acyl halide with the formula (CH₃)₂CHCH₂COCl, synthesized via thionyl chloride or phosgene-mediated chlorination of isovaleric acid, and serves primarily as an acylation agent in organic synthesis and pharmaceutical intermediate production. The intermediates segment leads volume throughput due to its centrality in downstream active-ingredient manufacturing, while the reagents category captures premium pricing from custom synthesis houses demanding sub-ppm impurity profiles. Pharmaceutical end users dominate value absorption, whereas agrochemical applications extend volume growth through herbicide and fungicide precursor demand.
EPA oversight in the United States and REACH registration under ECHA in Europe impose stringent handling, transport, and purity documentation requirements that elevate compliance costs for smaller producers. FDA alignment with ICH Q3C guidelines further restricts residual solvent thresholds in pharmaceutical-grade material, filtering market access to qualified suppliers. Stakeholders must monitor regulatory divergence between jurisdictions and assess backward integration into chlorination feedstocks as a buffer against raw-material volatility and qualification bottlenecks.
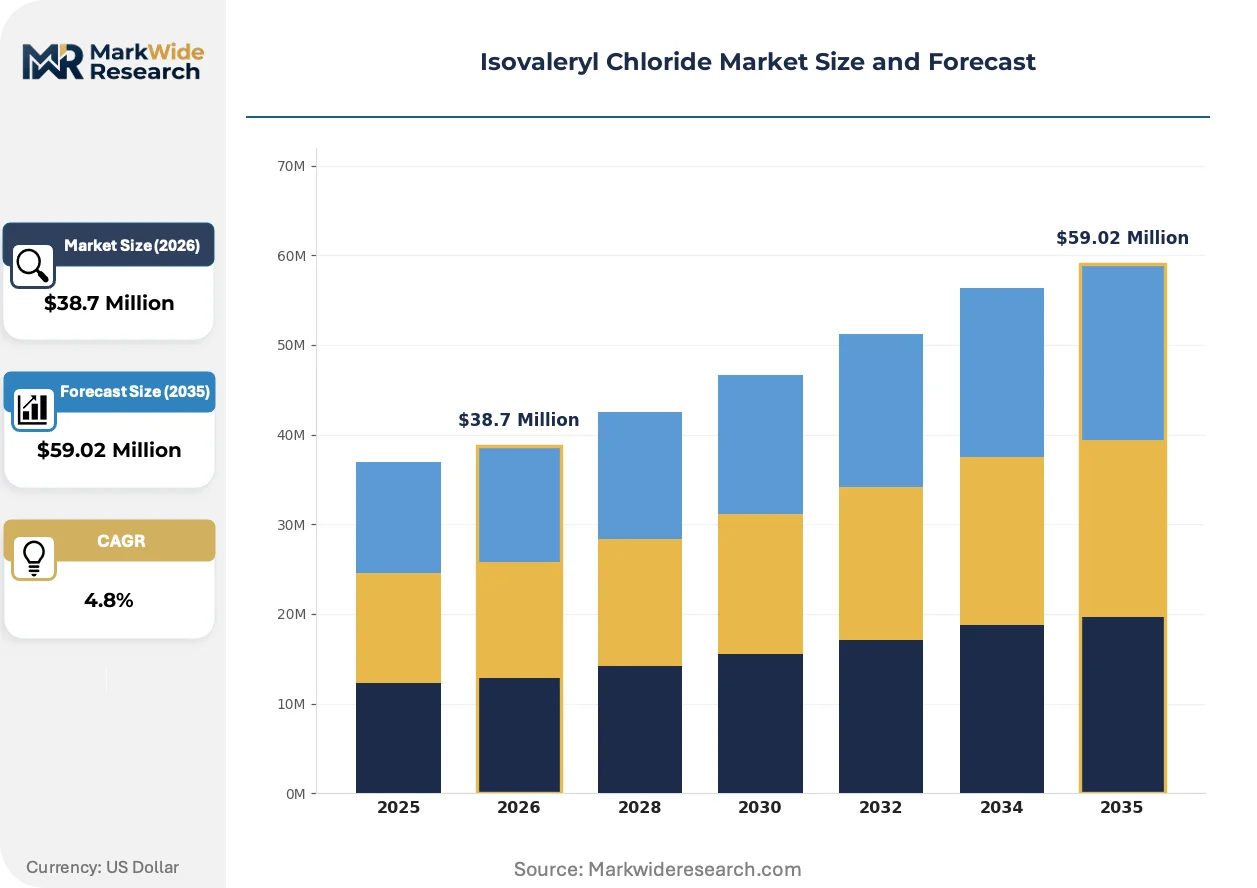
Market Dynamics
Pharmaceutical-grade purity specifications are compressing supplier margins and forcing capital redeployment toward dedicated chlorination infrastructure, splitting the competitive field between integrated acyl chloride platforms and batch-optimized specialists.
Growth Catalysts
- REACH Registration Mandates:ECHA's tightened substance dossier requirements for acyl chlorides are filtering out unqualified European suppliers, concentrating volume with REACH-registered producers capable of sub-ppm impurity documentation.
- Herbicide Precursor Demand:Agrochemical formulators in China are scaling isovaleryl chloride procurement for novel fungicide intermediates, pulling volume through domestic chlorination capacity expansions.
- Thionyl Chloride Process Optimization:Continuous-flow chlorination systems are reducing solvent residuals below ICH Q3C thresholds, qualifying more batches for FDA-aligned pharmaceutical applications without reprocessing.
Market Restraints
- Phosgene Input Volatility:Security restrictions on phosgene transport and storage are elevating logistics costs for producers lacking on-site chlorination feedstock generation.
- Specialty Chemical Concentration:European supply chains depend heavily on dedicated chlorination infrastructure at a limited number of industrial sites, creating single-point vulnerability.
- Pivaloyl Chloride Substitution:Bulk agrochemical buyers are evaluating sterically hindered acyl chloride alternatives where reaction selectivity permits, pressuring isovaleryl chloride volume in price-sensitive applications.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are building captive acyl chloride capabilities to serve export-oriented pharmaceutical synthesis.
- Fragrance Ester Convergence:Isovaleryl chloride is penetrating high-value fragrance ester synthesis as perfumery houses seek differentiated odorant profiles beyond conventional fatty acid derivatives.
- EPA Green Chemistry Incentives:The United States agency's grant programs for solvent-reduced synthetic routes are accelerating adoption of catalytic chlorination methods with lower environmental footprint.
Industry Challenges
- Process Safety Expertise Scarcity:Qualified chemical engineers with acyl chloride handling certification are concentrated at legacy chlorination sites, constraining new facility staffing.
- Multi-Jurisdiction Qualification Timelines:Simultaneous FDA, EMA, and NMPA filing requirements for pharmaceutical-grade material are extending approval cycles and freezing working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isovaleryl Chloride Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $59.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Intermediates, Reagents, Additives End User: Pharmaceuticals, Agrochemicals, Plastics, Fragrances Application: Chemical Synthesis, Flavoring Agents, Manufacturing, Solvent Extraction Form: Liquid, Solid, Gas, Powder |
| Companies Covered | BASF SE, CABB Group GmbH, Cayman Chemicals, Sisco Research Laboratories Pvt. Ltd., Dongli, Jiangsu WNC, Hangzhou KieRay Chem Co.,LTD, Shiva Pharmachem Ltd., Omega Finechem Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isovaleryl Chloride Market Evolving Landscape
Acyl chloride production is bifurcating between continuous-flow pharmaceutical systems and batch-optimized industrial platforms, with regulatory data requirements becoming the primary axis of technical differentiation.
Membrane-based chlorination reactor technology is modularizing production scale for isovaleryl chloride synthesis. Mid-size pharmaceutical intermediates producers in Germany and Switzerland are adopting skid-mounted units to reduce campaign changeover losses. This modularization is fragmenting what was previously concentrated toll-manufacturing demand into distributed captive production.
REACH's 2023 updated guidance on respiratory sensitizers is reclassifying handling protocols for acyl chlorides across EU manufacturing sites. Industrial consequence includes mandatory closed-system transfer requirements elevating capital intensity for open-vessel producers. Fragrance compounders in France and the Netherlands are accelerating qualification of pre-packaged reagent solutions to bypass on-site handling restrictions.
Specification-driven procurement is compressing supplier panels as pharmaceutical buyers consolidate qualified sources. Custom synthesis houses are displacing spot-market purchasing with multi-year offtake agreements tied to audit rights and batch documentation. This concentration is most visible in the United States, where FDA inspection history has become a binary qualifier excluding newer market entrants from active pharmaceutical ingredient supply chains.
Isovaleryl Chloride Market Segmentation
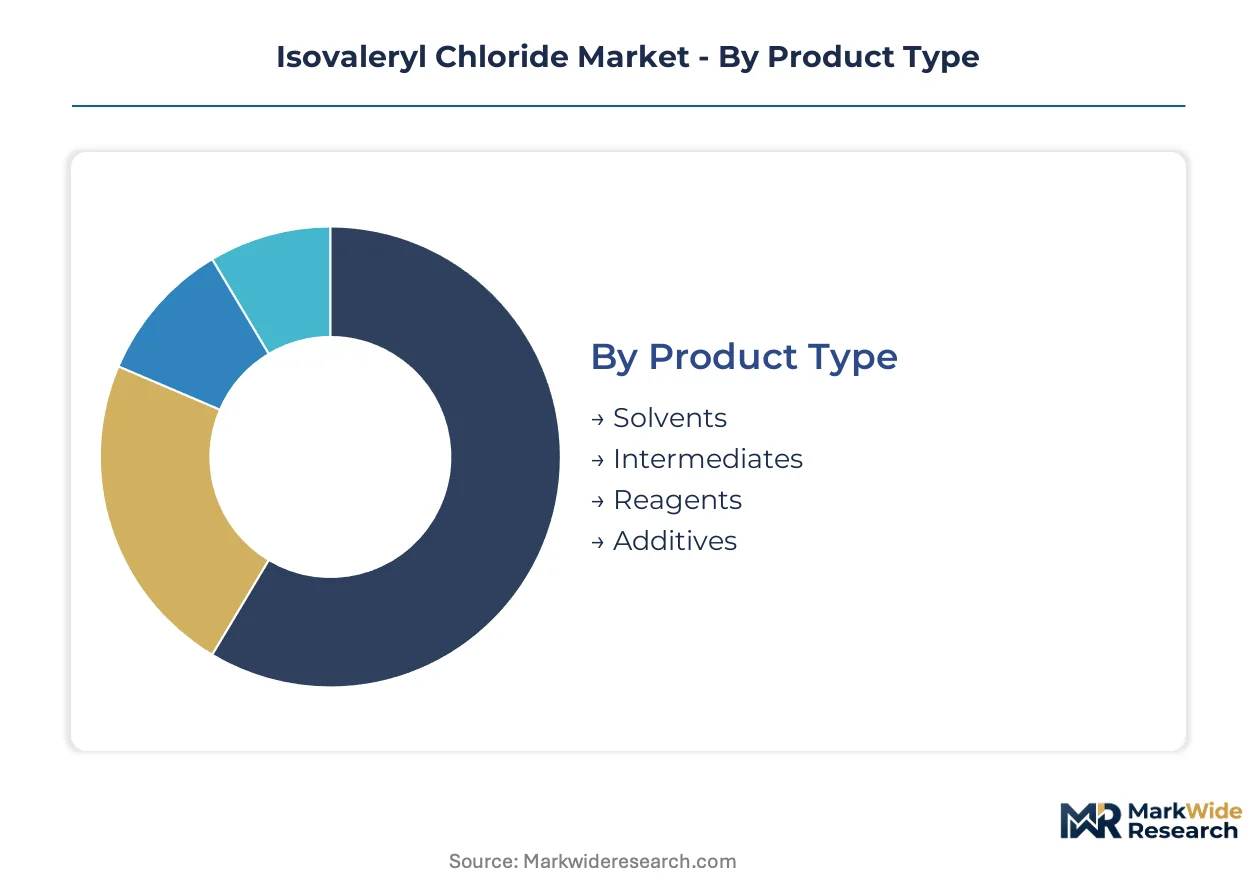
Isovaleryl chloride procurement splits sharply across purity grades and handling requirements. Specification thresholds determine supplier qualification, while end-use toxicity standards dictate formulation chemistry and packaging protocols.
Product Type:
Purity specifications and batch documentation requirements create distinct commercial tiers.
- Intermediates:These batches serve as acylation precursors in active pharmaceutical ingredient synthesis, with residual solvent thresholds governed by FDA-aligned ICH Q3C guidelines. Pharmaceutical manufacturers in the United States and Europe concentrate procurement here, driven by downstream regulatory filing requirements that demand sub-ppm impurity profiles and complete batch pedigree documentation.
- Reagents:Custom synthesis houses purchase these high-specification grades for route-of-synthesis development, where reaction efficiency depends on precise acyl chloride activity. Demand clusters in Basel and Hyderabad CDMO corridors, constrained by qualified chemical engineer scarcity for acyl chloride handling certification.
- Solvents:Industrial-grade material for non-pharmaceutical extraction processes.
- Additives:Niche polymerization initiator applications with limited volume throughput.
Intermediates lead on scale; reagents lead on momentum.
End User:
Regulatory intensity and margin capture potential vary sharply across buyer categories.
- Pharmaceuticals:FDA, EMA, and NMPA filing requirements enforce the strictest purity protocols, with multi-jurisdiction qualification timelines extending approval cycles. German and Swiss producers dominate supply to this segment through REACH-registered chlorination infrastructure.
- Agrochemicals:Chinese formulators scale procurement for novel fungicide precursors, pulling volume through domestic capacity expansions. This segment tolerates wider impurity bands in exchange for cost-optimized batch economics.
- Fragrances:High-value ester synthesis for differentiated odorant profiles in French and Dutch perfumery houses.
- Plastics:Polymerization catalyst applications with commodity-grade pricing.
Pharmaceuticals command premium positioning; agrochemicals drive volume expansion.
Application:
Process chemistry requirements segment demand by reaction environment and throughput scale.
- Chemical Synthesis:Acylation reactions in pharmaceutical intermediate production demand anhydrous handling and closed-system transfer protocols under REACH's updated respiratory sensitizer guidance. Continuous-flow chlorination systems are displacing batch campaigns in German modular installations.
- Flavoring Agents:Fragrance ester convergence in high-value perfumery applications requires food-grade or fragrance-grade certification, with French compounders accelerating pre-packaged reagent qualification to bypass on-site handling restrictions.
- Manufacturing:Industrial-scale acylation for polymer and agrochemical precursor production.
- Solvent Extraction:Separation chemistry applications with lower specification barriers.
Chemical synthesis anchors value capture; flavoring agents climb fastest on premium positioning.
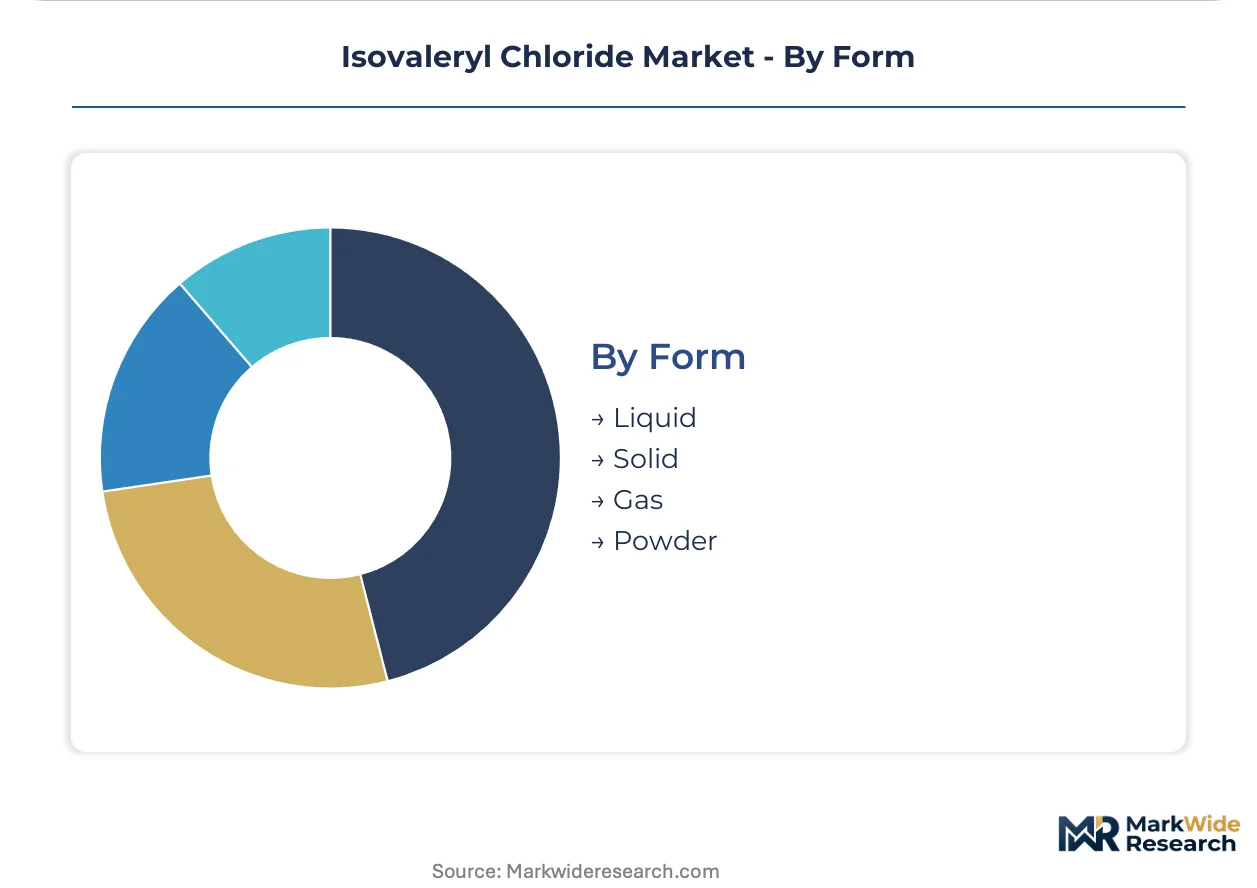
Form:
Physical state determines packaging, transport security classification, and handling infrastructure investment.
- Liquid:Standard commercial presentation for isovaleryl chloride, shipped in corrosion-resistant containers with phosgene-derived security restrictions elevating logistics costs for producers lacking on-site chlorination feedstock generation. EPA and ECHA transport documentation applies.
- Solid:Stabilized or complexed forms for specialized handling environments.
- Gas:Vapor-phase applications in specific reactor configurations.
- Powder:Encapsulated or adsorbed presentations for controlled-release chemistry.
Liquid dominates commercial throughput; solid forms gain traction in restricted-handling jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified chemical engineers with acyl chloride handling certification cluster at legacy chlorination sites in Germany, Switzerland, and the United States, anchoring pharmaceutical-grade production capacity while constraining geographic expansion of new facilities.
United States
Pharmaceutical manufacturers in New Jersey and Massachusetts drive procurement of FDA-aligned intermediates for active pharmaceutical ingredient synthesis. EPA oversight imposes stringent transport documentation and residual solvent thresholds under ICH Q3C guidelines. The Gulf Coast petrochemical corridor hosts integrated chlorination infrastructure serving agrochemical formulators.
Germany
REACH-registered producers in Ludwigshafen and Frankfurt-Höchst supply high-purity batches to EMA-regulated drug developers. ECHA's 2023 respiratory sensitizer guidance mandates closed-system transfer protocols, elevating capital requirements for open-vessel operators. Continuous-flow modular installations in Baden-Württemberg reduce campaign changeover losses.
China
Domestic agrochemical and fragrance producers in Jiangsu and Zhejiang provinces scale local sourcing to reduce import dependency. NMPA filing requirements for pharmaceutical-grade material extend qualification timelines for export-oriented manufacturers. Yangtze River Delta chlorination capacity expansions pull volume through captive thionyl chloride production.
Switzerland
Basel-based custom synthesis houses absorb premium-priced reagent grades for route-of-synthesis development. Swissmedic alignment with ICH quality guidelines enforces sub-ppm impurity documentation for pharmaceutical applications. The Rhine corridor concentration of CDMOs fragments toll-manufacturing demand into distributed captive production.
India
Contract development and manufacturing organizations in Hyderabad and Ahmedabad build captive acyl chloride capabilities for export-oriented synthesis. CDSCO regulatory convergence with FDA and EMA standards filters market access to qualified suppliers. Gujarat's specialty chemical belt attracts backward integration investments from fragrance and agrochemical intermediates producers.
Isovaleryl Chloride Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered purity specifications. The supplier base splits between integrated acyl chloride platforms sustaining margin capture in pharmaceutical segments and batch-optimized specialists serving cost-sensitive industrial buyers. Three archetypes dominate: REACH-registered European incumbents with dedicated chlorination infrastructure, Asian cost-optimized producers leveraging domestic feedstock access, and Indian CDMOs building captive capabilities for export markets. Competitive moves center on multi-year offtake agreements with audit rights and backward integration into thionyl chloride feedstocks to buffer raw-material volatility.
Among European-registered producers, BASF SE and CABB Group GmbH exemplify the integrated platform archetype, anchoring supply to EMA-regulated pharmaceutical manufacturers through REACH-compliant chlorination infrastructure. Shiva Pharmachem Ltd. occupies a distinct tier below pharma-focused rivals, representing the cost-optimized batch specialist model serving fragrance and agrochemical buyers with wider impurity tolerance. These three company profiles illustrate the market's structural bifurcation between specification-driven premium positioning and volume-driven industrial supply.
| Leading Market Players |
|---|
| BASF SE |
| CABB Group GmbH |
| Cayman Chemicals |
| Sisco Research Laboratories Pvt. Ltd. |
| Dongli |
| Jiangsu WNC |
| Hangzhou KieRay Chem Co.,LTD |
| Shiva Pharmachem Ltd. |
| Omega Finechem Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Continuous-flow chlorination systems are redrawing cost curves and supplier concentration simultaneously, compressing batch-optimized producers while rewarding REACH-registered platforms with dedicated infrastructure in Germany and Switzerland. This technological pivot elevates capital barriers for pharmaceutical-grade supply, concentrating pricing power among integrated acyl chloride producers capable of sub-ppm impurity documentation under FDA-aligned ICH Q3C guidelines.
Pricing Analysis
Bundled reagent solutions with closed-system transfer protocols command premium positioning against unbundled bulk liquid sales, separating pharmaceutical buyers from fragrance and agrochemical procurement. Pricing stratifies across pharmaceutical-grade, industrial-grade, and commodity-grade tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in industrial-grade batches is intensifying because Chinese domestic capacity expansions are flooding spot markets with cost-optimized material. Agrochemical formulators exhibit highest price sensitivity, while Basel-based CDMOs absorb premium reagent pricing without volume elasticity.
Supply Chain Analysis
Thionyl chloride feedstock supply rests on German, Chinese, and Indian specialty chemical producers, with phosgene-derived security restrictions elevating logistics costs for non-integrated manufacturers. Raw material dependencies span isovaleric acid precursors, chlorination catalysts, and corrosion-resistant packaging materials. Single-source vulnerability concentrates at legacy chlorination sites in Ludwigshafen and the Yangtze River Delta. Distribution runs through qualified chemical distributors with acyl chloride handling certification, bypassing open-market channels for pharmaceutical-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isovaleryl chloride functions as a regulatory compounder where REACH's 2023 respiratory sensitizer guidance and FDA-aligned ICH Q3C thresholds are accelerating demand concentration among qualified suppliers capable of closed-system transfer protocols and sub-ppm documentation.
For Market Incumbents: Cement REACH-registered supply positions by expanding continuous-flow modular capacity in Baden-Württemberg and reinforcing captive thionyl chloride generation to buffer phosgene input volatility. Pivaloyl chloride substitution threats in agrochemical applications demand defensive certification investments to lock pharmaceutical-grade offtake agreements with audit rights. For New Entrants and Emerging Players: EPA Green Chemistry incentives in the United States open a window for catalytic chlorination specialists to penetrate solvent-reduced synthetic routes. Target fragrance ester convergence in French and Dutch perfumery houses as the most penetrable segment, leveraging pre-packaged reagent qualification to bypass on-site handling restrictions and secure toll-manufacturing partnerships with established compounders. For Investors and Strategic Acquirers: Valuations sit cheapest among batch-optimized Indian CDMOs building captive acyl chloride capabilities for export-oriented pharmaceutical synthesis. Long-term viability hinges on backward integration into chlorination feedstocks and multi-jurisdiction qualification timelines spanning FDA, EMA, and NMPA filings. Watch for inflection when Yangtze River Delta capacity expansions trigger price erosion in industrial-grade material.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thionyl Chloride | Captive feedstock generation buffers phosgene transport security restrictions and raw-material volatility. |
| Continuous-Flow Modular Installation | Skid-mounted units in Germany and Switzerland reduce campaign changeover losses for pharmaceutical batches. |
| REACH Respiratory Sensitizer Compliance | Closed-system transfer protocols qualify suppliers for EMA-regulated pharmaceutical supply chains. |
| Multi-Year Offtake Agreement with Audit Rights | Custom synthesis houses displace spot-market purchasing with documented batch pedigree requirements. |
| Pre-Packaged Reagent Solution Qualification | French fragrance compounders bypass on-site handling restrictions under ECHA's updated guidance. |
Research Methodology
Coverage spans the United States, Germany, China, Switzerland, and India, with primary inputs from each market cluster combining interviews with plant managers at chlorination facilities, procurement leads at pharmaceutical and agrochemical formulators, distribution channel partners with handling certification, and technical R&D directors at CDMOs. Secondary validation draws from FDA filings, ECHA REACH registrations, SEC 10-K disclosures, and customs trade data. Bottom-up volume modeling triangulates against top-down value estimates across purity grades and end-use segments.
Granularity extends to pharmaceutical-grade versus industrial-grade tiering, with end-use industry splits across pharmaceuticals, agrochemicals, fragrances, and plastics, plus regional production hub differentiation. CAGRs derive from segment-level volume trajectories and value-per-unit assumptions across the projection horizon, incorporating thionyl chloride process optimization adoption curves and REACH registration mandate compliance timelines as industry-specific forecast inputs.
Revisions become necessary when phosgene security restrictions tighten, pivaloyl chloride substitution accelerates in price-sensitive applications, or multi-jurisdiction qualification timelines extend beyond baseline assumptions. Material deviation in these triggers warrants pause and re-evaluation of supplier concentration and pricing power assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Levulinic Acid Market
Bulk Chemicals
Atrazine Market
Bulk Chemicals
Butachlor Market
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
Propionaldehyde Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Global Sebacic Acid Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Encapsulated Sodium Bicarbonate Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Dextrin Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Europe Calcium Chloride Market