
 Distributed Storage System Market | 2026-2036
Distributed Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Storage System Market Outlook
Storage-as-a-service financing and operational lease structures for edge infrastructure is rewriting competitive entry conditions for mid-sized enterprises. Cohesity leverages subscription-based consumption models to reduce upfront capital barriers for healthcare and BFSI clients. Nutanix anchors its position through integrated hyperconverged platforms that bundle compute with distributed storage software. Cloudian differentiates by specializing in S3-compatible object storage for hybrid cloud deployments.
A distributed storage system pools storage resources across multiple networked nodes, geographically dispersed data centers, or edge locations, using software-defined architectures with erasure coding, replication factors of three or higher, and consensus protocols to maintain consistency. Its primary purpose is to deliver scalable, fault-tolerant data access for applications requiring low-latency retrieval without single points of failure. Object storage leads in revenue contribution due to its native fit for unstructured data growth in media and analytics workloads, while hybrid cloud deployment captures the fastest expansion as organizations balance on-premise latency requirements with public cloud burst capacity. File storage retains entrenched positions in healthcare imaging and financial trading environments where POSIX compliance remains mandatory.
The EU AI Act imposes data provenance and auditability mandates that favor distributed architectures with immutable logging, while GDPR residency requirements restrict cross-border data flows and stimulate regional node deployment. In the US, HIPAA security rules and NIST cybersecurity frameworks enforce encryption-at-rest and access control standards that shape product certification requirements for healthcare-facing vendors. Stakeholders must monitor how fragmentation between national cloud sovereignty laws and industry-specific data governance standards will determine architectural choices for multi-tenant platform designs.
Market Dynamics
Data sovereignty mandates and edge computing proliferation are forcing architectural fragmentation across national boundaries, compelling vendors to engineer jurisdictional compliance directly into storage topology rather than retrofitting it.
Growth Catalysts
- GDPR residency enforcement:Cross-border data flow restrictions under EU regulation are mandating localized node deployment across member states, expanding hardware procurement cycles for distributed architectures.
- Healthcare imaging archives:PACS and DICOM storage requirements for radiology departments are driving petabyte-scale object storage adoption with erasure coding for fault tolerance.
- Industrial IoT telemetry:Automotive manufacturing lines in Germany are generating continuous sensor streams that require edge-localized storage nodes to meet sub-10ms latency thresholds.
Market Restraints
- Flash memory supply concentration:NAND fabrication capacity concentrates in South Korea and Taiwan, exposing storage array vendors to geopolitical disruption and input cost volatility.
- EU AI Act audit trails:Immutable logging requirements for machine learning training data impose storage overhead ratios that degrade effective capacity utilization by 15-25%.
- Erasure coding latency penalties:Distributed reconstruction operations for failed nodes introduce read amplification that disqualifies the architecture from high-frequency trading workloads.
Strategic Opportunities
- Sovereign cloud architectures:France and Germany are deploying Gaia-X compliant federated storage pools that exclude non-EU jurisdiction control, creating certified vendor qualification pathways.
- Healthcare BFSI subscription models:Storage-as-a-service financing structures are eliminating upfront capital barriers for mid-sized hospital networks and regional banking cooperatives.
- AI training data lakes:Convergence of vector databases with S3-compatible object storage is enabling unified repositories for embeddings and unstructured source material.
Industry Challenges
- Distributed systems engineering talent:Consensus protocol implementation and CAP theorem optimization require specialized expertise that commands premium compensation in competitive labor markets.
- Hyperconverged integration complexity:Migrating from siloed SAN/NAS environments to software-defined architectures demands application downtime windows that risk operational continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Storage System Market |
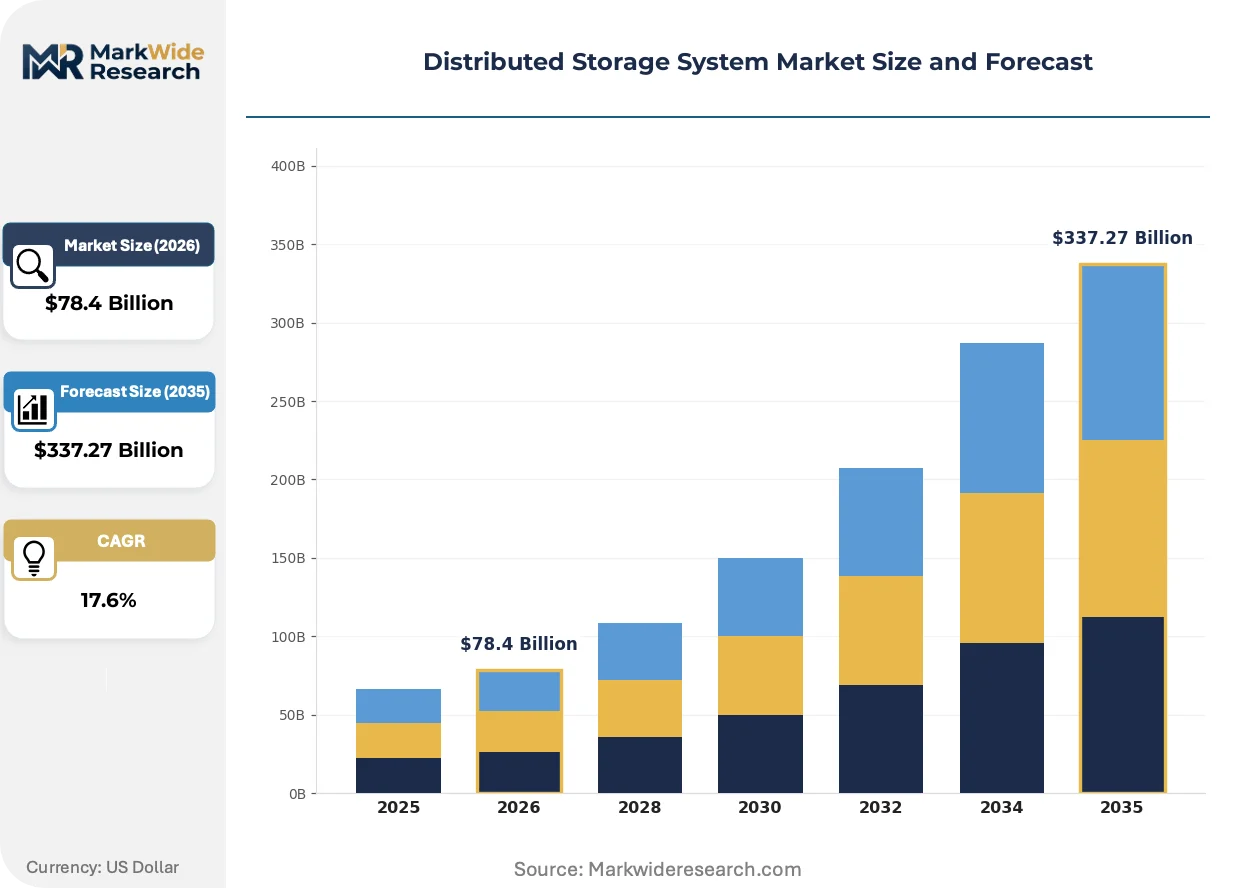
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $337.27 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Type: Object Storage, Block Storage, File Storage, Archive Storage Use Case: Data Backup, Disaster Recovery, Big Data Analytics, Content Distribution End User: Healthcare Providers, BFSI, Retailers, Media Companies |
| Companies Covered | Panzura, Cohesity, DataCore, Veeam Software, Qumulo, DDN, Cloudian, Nutanix, MinIO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Storage System Market Strategic Shifts
Storage software is decoupling from proprietary hardware lock-in, enabling commodity server deployment with vendor-agnostic orchestration layers that abstract physical infrastructure from data services.
Computational storage drives with onboard processing capability are collapsing the data movement bottleneck between storage and compute tiers. Hyperscale operators and financial services firms are deploying these devices at rack scale to reduce host CPU overhead for analytics workloads. The architecture is collapsing traditional SAN/NAS boundary distinctions by embedding query execution directly at the drive level.
The EU AI Act's data provenance mandates are compelling immutable ledger integration for training dataset lineage tracking. Healthcare AI developers in Germany and France must now maintain cryptographically verifiable audit trails for diagnostic model inputs. This regulatory pressure is accelerating adoption of WORM-enabled object storage with blockchain-anchored metadata verification.
Consumption-based procurement models are displacing perpetual license purchases across enterprise storage refresh cycles. Mid-market buyers in the United States and United Kingdom are prioritizing opex-aligned contracts with burst capacity guarantees over capital-intensive owned infrastructure. Managed service providers are capturing margin expansion by aggregating multi-tenant capacity and reselling with SLAs that internal IT organizations cannot match.
Distributed Storage System Market Segmentation
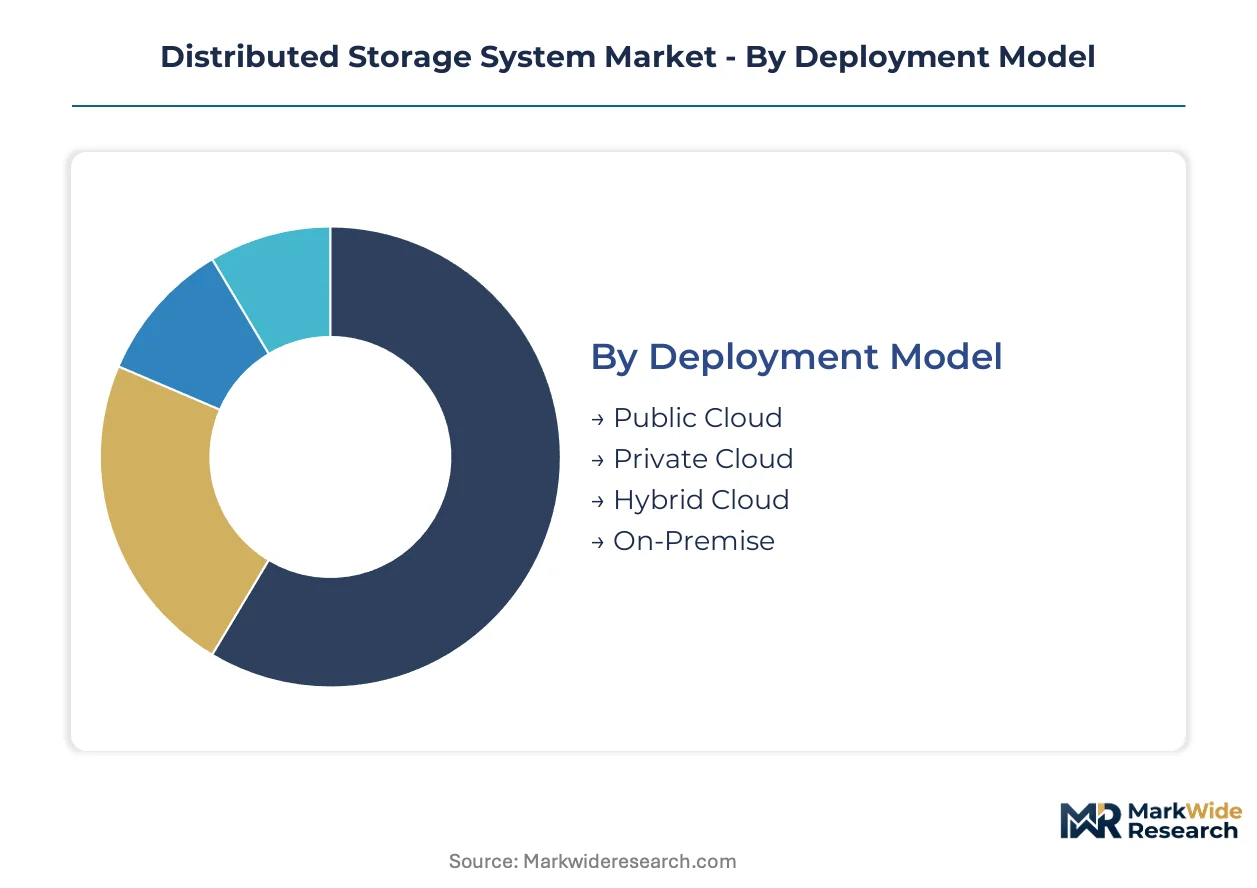
Distributed storage architectures diverge sharply across deployment topologies, storage protocols, and workload requirements. Understanding these fault lines reveals where infrastructure investments concentrate and which configurations deliver competitive advantage for specific regulatory and latency constraints.
Deployment Model:
Use-case spectrum spans sovereign data mandates at one extreme and elastic burst capacity at the other, with hybrid configurations capturing organizations balancing both imperatives.
- Hybrid Cloud:Organizations deploy edge-localized nodes for latency-sensitive operations while maintaining public cloud burst pools for batch analytics. GDPR residency enforcement and EU AI Act audit mandates accelerate this architecture across German automotive telemetry and French healthcare AI deployments.
- Private Cloud:Dedicated infrastructure delivers jurisdictional control for BFSI clients and government contractors. German industrial IoT data lakes and Gaia-X compliant federations favor this model for exclusion of non-EU jurisdiction control.
- Public Cloud:Shared multi-tenant capacity serves mid-market retailers and media companies with variable workloads. Procurement concentrates through consumption-based contracts with burst guarantees.
- On-Premise:Captive infrastructure persists in financial trading floors where sub-millisecond latency requirements disqualify network-dependent architectures.
The dominant share belongs to Hybrid Cloud, while On-Premise is closing the gap fastest among sovereign cloud initiatives.
Type:
Protocol selection maps directly to data structure—unstructured growth favors object architectures while transactional workloads retain block dependencies.
- Object Storage:S3-compatible APIs dominate unstructured data repositories. Media companies deploy petabyte-scale pools with erasure coding; healthcare PACS archives leverage immutable WORM configurations for diagnostic imaging retention.
- File Storage:POSIX-compliant namespaces retain mandatory status in healthcare imaging workstations and financial risk calculation clusters where legacy application compatibility governs procurement.
- Block Storage:Raw volume presentation serves database workloads and virtual machine hypervisors requiring direct SCSI or NVMe protocol access.
- Archive Storage:Cold tier repositories with extended retrieval latency trade access speed for media cost reduction in compliance-driven retention scenarios.
Object Storage commands the installed base, though File Storage maintains defensive positions in regulated verticals.
Use Case:
Workload priority determines capacity allocation—operational continuity drives backup investment while AI training pipelines reshape analytics infrastructure.
- Big Data Analytics:Vector database convergence with S3-compatible repositories enables unified embedding storage for machine learning pipelines. German automotive manufacturers and French healthcare AI developers drive capacity expansion.
- Disaster Recovery:Geographically dispersed replication with consensus protocols ensures RPO targets for BFSI clearing operations. GDPR cross-border restrictions mandate intra-EU node distribution.
- Data Backup:Immutable snapshot chains protect against ransomware encryption attacks. Healthcare providers prioritize air-gapped vault architectures.
- Content Distribution:Edge-cached object delivery reduces origin load for media streaming platforms and retail digital asset libraries.
Big Data Analytics exhibits steepest expansion trajectory as AI training data lakes proliferate, while Disaster Recovery absorbs the largest absolute capacity deployment.
End User:
Vertical requirements fragment procurement—regulatory density in healthcare and finance contrasts with throughput optimization in media and retail.
- Healthcare Providers:Radiology PACS and DICOM archives demand petabyte-scale object storage with HIPAA encryption-at-rest and EU AI Act immutable lineage tracking. German university hospitals and French diagnostic networks lead deployment velocity.
- BFSI:Trading infrastructure requires block storage with deterministic latency; retail banking favors subscription-based consumption models eliminating upfront capital barriers.
- Media Companies:Unstructured content libraries with global distribution requirements prioritize CDN-integrated object tiers.
- Retailers:Seasonal demand volatility drives preference for burst-capacity contracts across customer data lakes and supply chain analytics.
Healthcare Providers anchor revenue concentration, with BFSI expanding most quickly through storage-as-a-service financing structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The distributed storage system market exhibits a pronounced import dependency in flash memory components, with NAND fabrication concentrated in South Korea and Taiwan, while software-defined storage vendors cluster in the United States, Germany, and Israel. Net trade flows favor component exporters in East Asia against integrated solution providers in North America and Europe.
United States
Hyperscale cloud operators and financial services firms drive petabyte-scale deployments for AI training data lakes and real-time risk analytics. HIPAA security rules and NIST cybersecurity frameworks enforce encryption-at-rest standards that shape vendor certification requirements. The San Francisco Bay Area and Seattle tech corridors host the highest density of software-defined storage engineering talent.
Germany
Industrial IoT data lakes and automotive telemetry platforms require edge-localized storage nodes to meet sub-10ms latency thresholds for manufacturing automation. Gaia-X compliance mandates and GDPR residency enforcement stimulate sovereign cloud architecture procurement. The Stuttgart automotive cluster and Munich industrial technology corridor anchor deployment velocity for federated storage pools.
China
Domestic cloud service providers and state-backed data center operators are expanding captive storage software development to reduce reliance on Western intellectual property. MIIT data localization requirements and GB standards for critical information infrastructure restrict cross-border data flows. The Yangtze River Delta and Beijing-Tianjin-Hebei corridor concentrate hyperscale facility construction.
France
Healthcare AI developers and university hospital networks demand immutable lineage tracking for diagnostic model training datasets under EU AI Act mandates. ANSM and CNIL oversight reinforces GDPR-aligned residency requirements for patient imaging archives. The Paris-Saclay research cluster and Lyon biomedical corridor lead Gaia-X compliant federated storage adoption.
United Kingdom
Financial services clearing operations and retail banking cooperatives prioritize disaster recovery architectures with geographically dispersed replication. The Financial Conduct Authority's operational resilience requirements and post-Brexit data adequacy negotiations complicate cross-border node placement. The City of London and Edinburgh fintech corridor concentrate subscription-based storage-as-a-service procurement.
Distributed Storage System Market Competitive Environment
On the supply side, the industry is bifurcated between integrated hyperconverged platform vendors and specialized object storage software providers, with a fragmented mid-tier of regional systems integrators filling deployment gaps. Three archetypes dominate: subscription-based consumption model specialists, S3-compatible hybrid cloud architects, and hyperconverged compute-storage bundlers. Competitive moves concentrate on strategic partnerships for edge infrastructure deployment and portfolio diversification into sovereign cloud certifications.
Within the subscription-based tier, Cohesity and Nutanix exemplify divergent approaches to reducing upfront capital barriers for healthcare and BFSI clients. Cloudian occupies a position among S3-compatible hybrid cloud specialists, anchoring the object storage segment for media and analytics workloads. These three entities represent the strategic archetypes—consumption financing, integrated platforms, and protocol specialization—that competitors must navigate against.
| Leading Market Players |
|---|
| Panzura |
| Cohesity |
| DataCore |
| Veeam Software |
| Qumulo |
| DDN |
| Cloudian |
| Nutanix |
| MinIO |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Rotterdam container freight corridors transmit NAND flash memory cost volatility directly into European storage array pricing, amplifying differentiation between subscription-based consumption models and perpetual license procurement for healthcare and automotive OEM buyers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with Gaia-X certification and EU AI Act compliance status serving as primary price differentiation drivers. Cost compression in the standard tier is intensifying because hyperscale cloud providers are consolidating procurement volumes and extracting volume-scale concessions. Healthcare providers exhibit the highest price sensitivity due to constrained capital budgets, while sovereign cloud contractors in Germany demonstrate lowest sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Extended payment terms from South Korean and Taiwanese NAND fabricators are tightening working capital requirements for storage array vendors assembling systems in the United States and Germany. Supply chain architecture draws from concentrated flash memory fabrication in East Asia, controller silicon from Israel and the United States, and enclosure manufacturing in Mexico and China. Single-source vulnerability around advanced NAND nodes presents structural risk. Distribution runs through direct enterprise sales teams and certified systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors face substitution pressure from hyperscale cloud storage services that commoditize S3-compatible object tiers, forcing architectural differentiation around sovereign data residency and edge-localized latency guarantees.
For Market Incumbents: Pre-empt hyperscale encroachment by deepening Gaia-X certification portfolios and anchoring subscription financing structures for mid-sized hospital networks. Backward integration into flash memory procurement through long-term offtake agreements with South Korean fabricators defends margin position against input cost volatility. Sovereign cloud compliance represents the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in French healthcare AI developer segments where EU AI Act audit trail mandates outpace incumbent response timelines. Vector database convergence with object storage pipelines offers the most penetrable white-space target. Lead with consumption-based pricing and immutable logging capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with captive storage software divisions that lack standalone scale. Long-term viability hinges on recurring revenue ratios and sovereign cloud certification breadth rather than perpetual license backlog. Monitor Gaia-X qualified vendor list expansions as the inflection signal for platform consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Gaia-X Certification Investment | Unlocks procurement eligibility for German automotive and French healthcare sovereign cloud mandates. |
| Subscription Model Transition | Aligns revenue recognition with healthcare BFSI buyer preference for opex-aligned infrastructure consumption. |
| Edge Node Deployment Partnership | Addresses sub-10ms latency requirements for Stuttgart automotive telemetry and industrial IoT data lakes. |
| Immutable Logging Integration | Satisfies EU AI Act audit trail mandates for diagnostic model training dataset lineage verification. |
| NAND Supply Agreement | Reduces exposure to South Korean and Taiwanese fabrication concentration and geopolitical disruption risk. |
Study Parameters
Cross-validation between executive interviews and secondary regulatory filings anchors the qualitative findings for this distributed storage system assessment. Primary fieldwork encompassed CTOs at healthcare systems, IT procurement officers in automotive manufacturing, platform engineers at sovereign cloud operators, and channel partners serving BFSI clients. Secondary sources included SEC filings from storage software vendors, hyperscaler capex disclosures, EU AI Act implementation guidance, and Gaia-X framework documentation. Bottom-up deployment sizing and top-down market reconciliation provided triangulation.
Calibration against historical capacity deployment patterns and verified installation footprints shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass deployment topology, storage protocol type, workload use case, and end-user vertical. CAGRs were derived from regression analysis against verified node shipment data and storage software revenue recognition. Edge computing proliferation rates and regulatory compliance timeline acceleration served as industry-specific forecast inputs.
Stress conditions across NAND flash supply disruption, sovereign data residency enforcement intensity, and hyperscale pricing aggression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU AI Act implementation pace and GDPR cross-border enforcement consistency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Enterprise Hard Drive Market
Data Storage
Global Portable Data Storage Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
Object-Based Storage Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Blu-Ray Optical Disk Market
Data Storage
Solid State Drive (SSD) Market
Data Storage
NAND Flash Market
Data Storage
USB 3.1 Flash Drive Market
Data Storage
Powered Storage Devices Market
Data Storage
Taiwan Data Center Storage Market
Data Storage
Recordable Optical Disc Market
Data Storage
Solid State Array Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
SAS Hard Disk Drives Market
Data Storage
Channel Storage Systems Market