
 Australia Data Center Storage Market | 2026-2036
Australia Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Data Center Storage Market Insights
Cloud provider demand is expanding faster than enterprise uptake across Australian data center corridors. Dell Technologies leverages its integrated server-storage portfolio to anchor large-scale deployments in Sydney and Melbourne. Hewlett Packard Enterprise competes through its GreenLake as-a-service model, while Pure Storage specializes in all-flash arrays targeting latency-sensitive workloads. NetApp sustains its position in hybrid cloud data management for financial services and government clients.
Australia data center storage encompasses electromechanical and solid-state systems engineered for persistent data retention within climate-controlled facilities, typically operating across temperature ranges of 10°C to 35°C with N+1 redundancy on power and cooling infrastructure. These systems serve primary functions including transactional database support, unstructured data lakes, backup archival, and real-time analytics for cloud, enterprise, and telecommunications operators. Flash technology leads capital allocation due to performance density requirements, while hybrid configurations capture mid-tier deployments balancing cost per terabyte with input-output operations per second. Object storage segments are growing fastest among cloud providers managing exabyte-scale unstructured data from media streaming and artificial intelligence training pipelines.
The Australian government's Critical Infrastructure Protection Act and the Privacy Act impose stringent data sovereignty and breach notification requirements that directly shape storage procurement specifications. TGA guidelines for health data and APRA prudential standards for financial records further segment compliance-driven demand across verticals. Stakeholders must monitor evolving encryption mandates and carbon disclosure rules affecting storage hardware refresh cycles and facility energy ratings.
Market Dynamics
Hyperscale cloud buildouts across Sydney and Melbourne are compressing procurement cycles and forcing incumbent vendors to reconfigure service models around consumption-based billing.
Growth Catalysts
- Critical Infrastructure Protection Act:Mandatory security standards for data center operators are accelerating replacement of legacy storage systems with encrypted, sovereign-certified hardware.
- NVMe flash technology:Latency-sensitive AI training and real-time analytics workloads in New South Wales financial services are pulling high-performance storage deployments forward.
- Melbourne-Sydney corridor concentration:Hyperscale facility expansion is creating clustered demand that justifies dedicated distribution channels and local technical support infrastructure.
Market Restraints
- Power and cooling input costs:Electricity price volatility in eastern Australia directly compresses total cost of ownership calculations for high-density flash deployments.
- Component supply concentration:NAND flash and controller chip sourcing remains concentrated among East Asian foundries, exposing Australian buyers to extended lead times.
- Skills scarcity:Certified storage architects and data center infrastructure specialists command premium wages, constraining deployment velocity for mid-tier enterprises.
Strategic Opportunities
- Western Australia and Queensland buildouts:Underpenetrated secondary markets offer first-mover positioning as cloud providers diversify beyond Sydney-Melbourne saturation.
- Sustainability-linked procurement:Federal carbon disclosure mandates and NABERS energy ratings are creating preference premiums for storage vendors with verified lifecycle emissions data.
- Object storage-AI pipeline convergence:Unstructured data lakes for media streaming and machine learning training represent white-space demand distinct from traditional block storage.
Industry Challenges
- Legacy system integration:Enterprise migration from aging SAN architectures to software-defined storage requires specialized professional services that outstrip local supply.
- Compliance timeline compression:APRA prudential standard updates and TGA health data guidelines are forcing simultaneous hardware refreshes across regulated verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Data Center Storage Market |
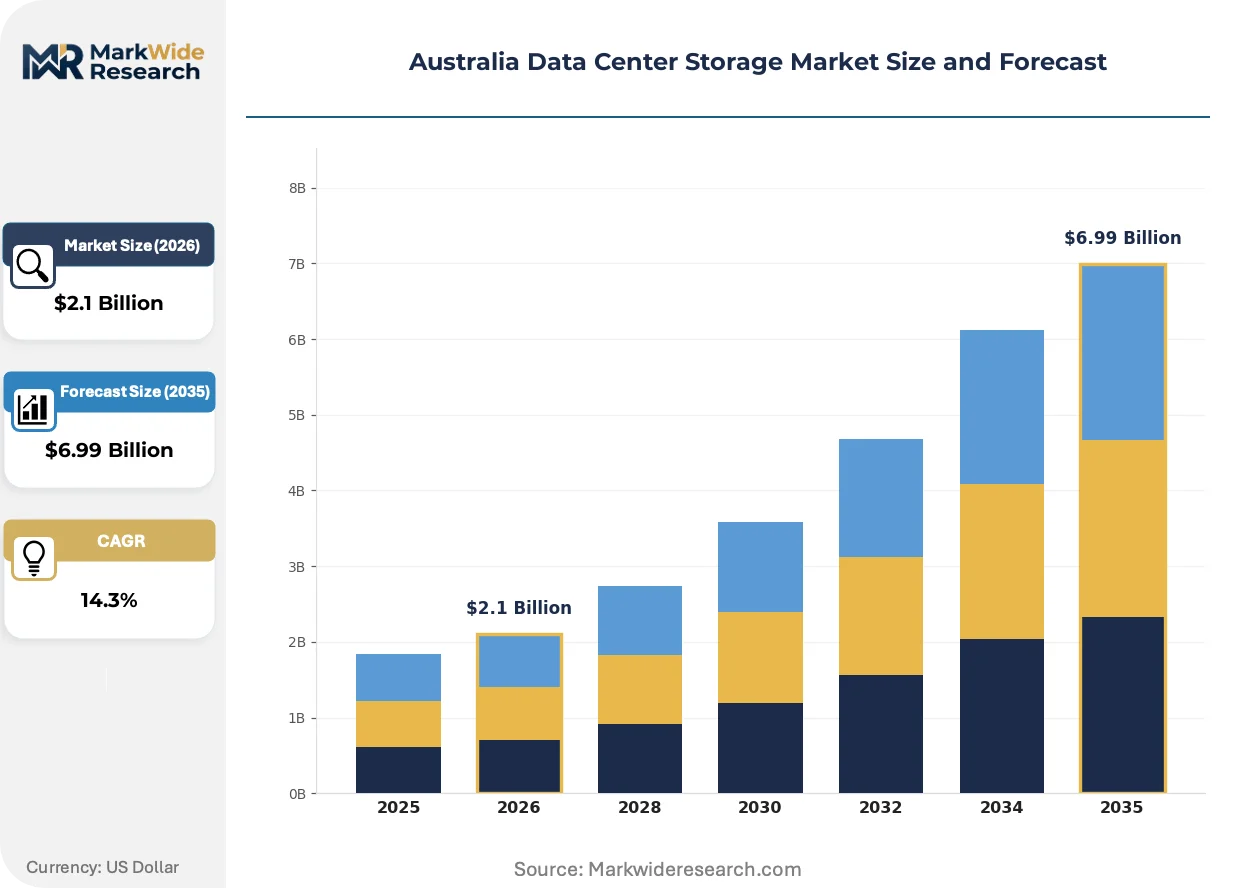
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.99 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: NAS, SAN, DAS, Object Storage Technology: Flash, HDD, SSD, Hybrid Capacity: 1TB, 10TB, 100TB, 1PB End User: Enterprise, SMEs, Telecom, Cloud Providers |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, Pure Storage, IBM, Hitachi Vantara, Huawei Technologies, Cisco Systems, NEXTDC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Data Center Storage Market Trends and Innovations
Storage architecture in Australian facilities is pivoting from capacity-centric designs toward performance-density optimization driven by AI workload requirements and energy efficiency mandates.
QLC NAND flash is expanding into primary storage tiers previously reserved for TLC configurations. Hyperscale operators in Sydney are deploying QLC arrays for warm data lakes where cost per terabyte outweighs endurance concerns. This compression of the flash hierarchy is expanding into mid-market enterprise procurement as vendors bundle intelligent data placement software.
The Privacy Act's notifiable data breach scheme and Critical Infrastructure Protection Act security obligations are mandating encryption-at-rest and key management infrastructure. Financial services and healthcare operators must demonstrate sovereign data control, favoring storage systems with certified Australian key escrow and tamper-evident hardware modules. Compliance documentation now precedes technical evaluation in procurement scorecards.
Consumption-based billing models are displacing traditional capital purchase cycles for enterprise storage. HPE GreenLake and Dell APEX-style offerings allow New South Wales and Victoria enterprises to align storage costs with actual utilization, transferring obsolescence risk to vendors. This shift is most visible among mid-tier organizations lacking dedicated infrastructure capital planning functions.
Australia Data Center Storage Market Segmentation
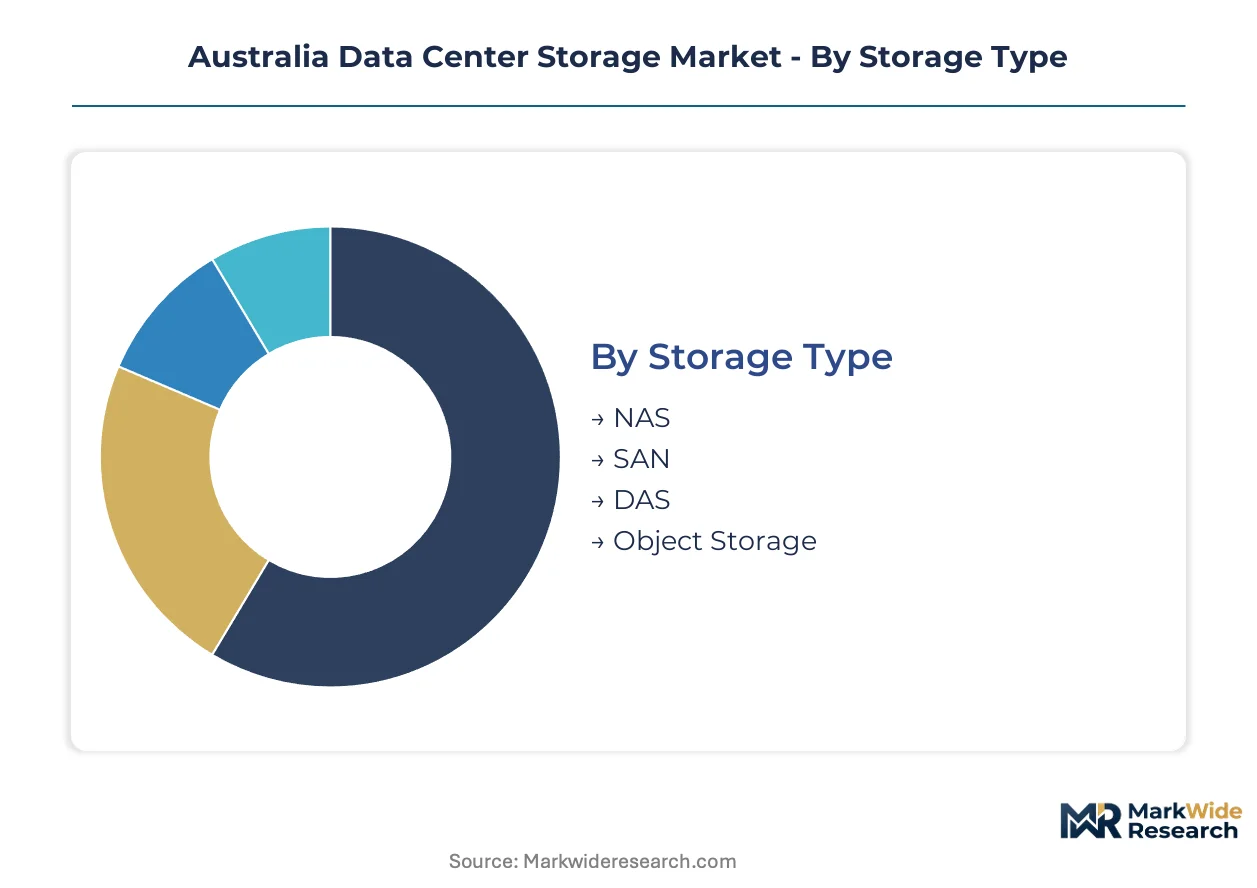
Storage procurement patterns across Australian facilities diverge sharply by workload type and buyer scale. Cloud operators prioritize density and throughput, while regulated enterprises weigh compliance certification above raw performance metrics.
Storage Type:
Buyers differentiate primarily by data access patterns and integration complexity with existing infrastructure.
- NAS:File-level access protocols serve unstructured content repositories and collaborative workloads across New South Wales government agencies. Network-attached configurations simplify deployment for mid-tier enterprises lacking dedicated storage administrators.
- SAN:Block-level Fibre Channel and iSCSI architectures dominate transactional database workloads in Melbourne financial services. Latency-sensitive trading platforms and core banking systems require the deterministic performance SAN fabrics deliver.
- DAS:Direct-attached configurations persist in edge computing nodes and high-performance computing clusters where network overhead is unacceptable.
- Object Storage:Flat namespace architectures scale to exabyte capacity for cloud-native applications and AI training pipelines.
Volume sits with SAN deployments in established financial corridors; growth tilts toward object storage as hyperscale facilities expand.
Technology:
Cost-per-IOPS versus cost-per-terabyte tradeoffs segment procurement decisions across buyer tiers.
- Flash:NVMe and SATA SSD arrays deliver sub-millisecond latency for real-time analytics and virtualization density. Sydney hyperscale operators specify all-flash configurations for primary workloads where power constraints outweigh capital premiums.
- HDD:Magnetic spinning media retains dominance in archival and backup tiers where access frequency is measured in days. Western Australia mining operations deploy high-capacity HDD enclosures for seismic data retention.
- SSD:Solid-state drives bridge performance and endurance requirements in mixed workload environments.
- Hybrid:Automated tiering software migrates hot data to flash while retaining cold data on disk.
Flash commands the steepest expansion trajectory; HDD maintains installed base in secondary markets.
Capacity:
Facility power density and rack space economics determine scale thresholds for procurement.
- 1TB:Entry-level configurations address remote office and small business backup requirements.
- 10TB:Mid-range enclosures serve departmental virtualization and development environments.
- 100TB:Enterprise-scale arrays consolidate multiple workload types in Sydney and Melbourne colocation facilities.
- 1PB:Hyperscale object storage clusters support media streaming and machine learning training datasets.
100TB systems dominate current procurement volume; 1PB configurations are climbing fastest among cloud providers.
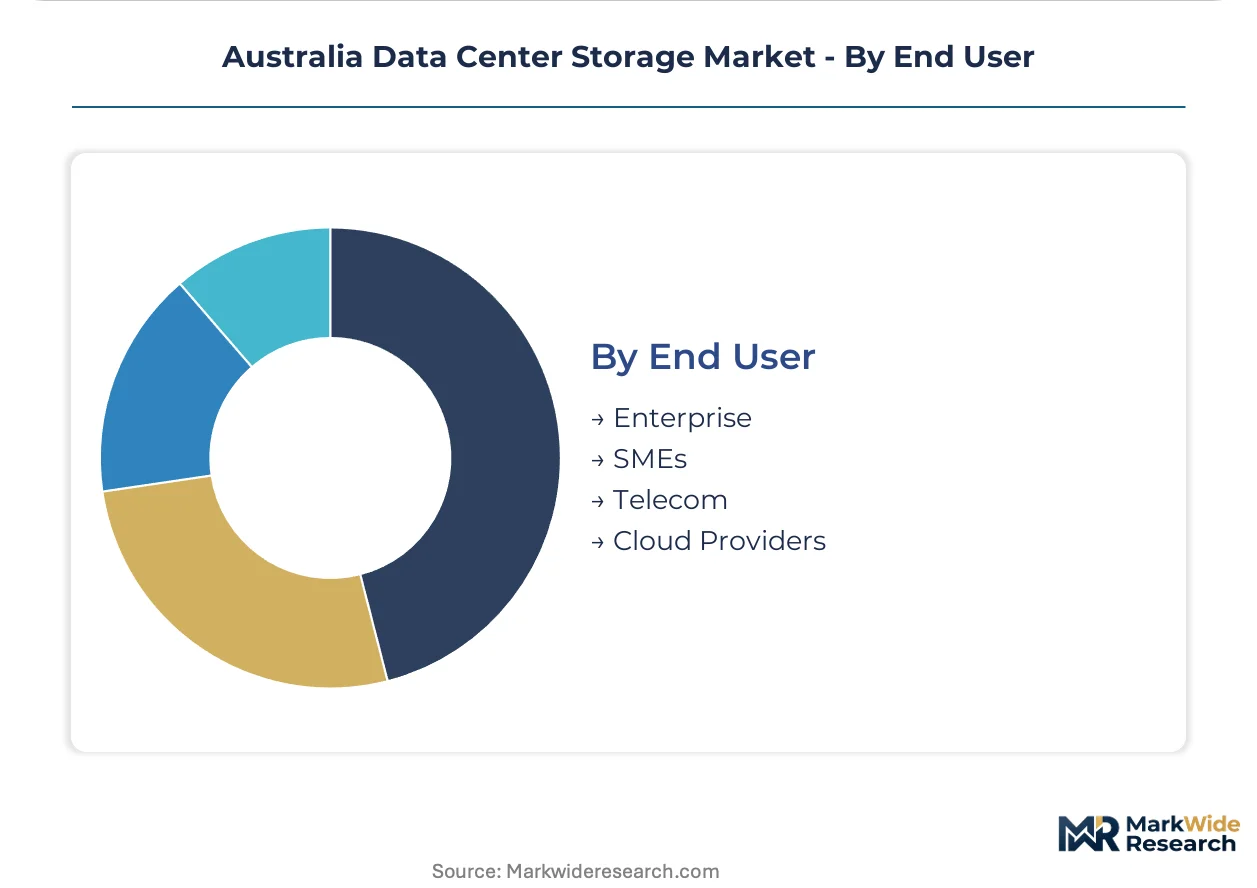
End User:
Capital availability and compliance burden separate buyer behaviors across segments.
- Enterprise:ASX-listed corporations and federal agencies mandate sovereign-certified hardware with encryption-at-rest. APRA prudential standards and the Critical Infrastructure Protection Act drive replacement cycles in banking and critical infrastructure operators.
- Cloud Providers:Hyperscale operators in Sydney's Macquarie Park and Melbourne's Dandenong South corridors specify commodity-scale storage with software-defined management. Procurement centers on total cost of ownership across five-year depreciation horizons.
- SMEs:Small and medium enterprises favor consumption-based service models over capital acquisition.
- Telecom:Telstra and Optus infrastructure divisions deploy edge storage for 5G content caching and low-latency services.
Enterprise buyers represent current volume concentration; cloud providers are gaining share fastest in absolute capacity terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Storage infrastructure consumption concentrates in New South Wales and Victoria while Western Australia and Queensland emerge as underpenetrated expansion zones. Cloud providers and financial services anchor demand in established eastern corridors. Secondary states are attracting hyperscale diversification investments.
New South Wales
Hyperscale cloud buildouts in Sydney's Macquarie Park and Eastern Creek corridors drive exabyte-scale storage procurement. The state's Critical Infrastructure Protection Act mandates encrypted, sovereign-certified hardware for data center operators. Sydney anchors Australia's densest concentration of financial services storage for latency-sensitive trading platforms.
Victoria
Melbourne's Dandenong South and Fishermans Bend precincts host expanding colocation capacity serving AI training and media streaming workloads. APRA prudential standards accelerate compliance-driven storage refreshes across banking and insurance sectors. The Melbourne-Sydney corridor justifies dedicated distribution channels and local technical support infrastructure.
Western Australia
Mining and energy operations in Perth and the Pilbara region generate seismic data retention demand for high-capacity HDD deployments. The state's remoteness from eastern infrastructure creates latency penalties favoring local edge storage nodes. Perth's emerging data center precincts attract cloud provider interest for geographic diversification beyond saturated eastern markets.
Queensland
Brisbane and Gold Coast facilities serve government and healthcare workloads under TGA health data guidelines requiring sovereign data control. The state's subtropical climate challenges cooling efficiency for high-density flash deployments. Southeast Queensland buildouts target underpenetrated enterprise demand outside Sydney-Melbourne saturation.
South Australia
Adelaide's defense and space technology clusters generate specialized storage requirements for classified and research data. The Australian Space Agency and defense primes anchor secure, air-gapped storage procurement. Lower land and power costs relative to eastern states attract secondary data center investment.
Australia Data Center Storage Market Competitive Landscape
Top-tier vendors anchor hyperscale and enterprise procurement, while mid-tier specialists capture niche compliance and performance segments. The market exhibits tiered concentration with integrated infrastructure providers holding volume positions against pure-play storage specialists. Three archetypes dominate: full-stack server-storage integrators, all-flash performance specialists, and hybrid cloud data managers. Competitive moves center on consumption-based billing reconfiguration and sovereign certification alignment with federal security mandates.
Within the integrated infrastructure tier, Dell Technologies and Hewlett Packard Enterprise exemplify vendors bundling storage with server and networking portfolios. Pure Storage occupies a position as the all-flash specialist archetype targeting latency-sensitive workloads. NetApp represents hybrid cloud data management for regulated verticals requiring seamless on-premises and cloud orchestration.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| Pure Storage |
| IBM |
| Hitachi Vantara |
| Huawei Technologies |
| Cisco Systems |
| NEXTDC |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between sovereign-certified encrypted hardware and commodity unvalidated storage creates parallel pricing tracks that map directly onto supply chain sourcing strategies. Premium-tier procurement through Dell APEX and HPE GreenLake channels commands 40-60% cost premiums over direct import routes, reflecting the embedded compliance documentation and local technical support infrastructure that vendors must maintain under Australia's Critical Infrastructure Protection Act.
Pricing Analysis
Short lead-time premiums dominate transaction economics as hyperscale operators in Sydney's Macquarie Park corridor pay steep markups for NVMe flash arrays deliverable within 30-day windows versus 90+ day standard procurement. Subscription-based consumption models are displacing capital purchase cycles across mid-tier enterprises, with pricing differentiation anchored in encryption certification grade and sovereign key escrow capabilities. Cost compression in HDD archival tiers is intensifying because Western Australia mining operations are consolidating seismic data retention contracts around multi-petabyte volume scales. Cloud providers exhibit least price sensitivity due to five-year total cost of ownership depreciation horizons, while SMEs face acute budget constraints favoring refurbished hardware channels.
Supply Chain Analysis
Freight cost volatility from East Asian manufacturing hubs to Australian ports directly inflates landed costs for NAND flash modules and storage controller chips. Supply concentration rests on Taiwan, South Korea, and China for semiconductor fabrication, with specialized HDD components sourcing from Thailand and Malaysia. Raw material dependencies span silicon wafers, rare earth elements for magnet assemblies, and cobalt-based battery materials for enterprise SSD power-loss protection. Single-source vulnerability around advanced NAND process nodes exposes Australian buyers to allocation rationing during foundry capacity crunches. Distribution runs through Sydney and Melbourne-based value-added resellers who bundle installation services with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NAND foundry capacity constraints in East Asia are propping pricing power for incumbent storage vendors serving Australian hyperscale facilities. Component scarcity favors vendors with pre-allocated supply agreements.
For Market Incumbents: Deepen vertical integration into firmware development and encryption key management to differentiate against Pure Storage's all-flash specialization. Anchor Sydney and Melbourne technical support density to defend service attach rates as HPE GreenLake expands consumption-based penetration. Prioritize sovereign certification investment ahead of anticipated Critical Infrastructure Protection Act amendments tightening data residency requirements. For New Entrants and Emerging Players: Queensland government and healthcare buyers represent an underserved archetype with procurement authority fragmented across Brisbane and Gold Coast facilities. Object storage for AI training pipelines in Perth's emerging data center precincts offers white-space positioning outside Sydney-Melbourne saturation. Lead with sustainability-linked procurement credentials under NABERS energy rating frameworks to bypass entrenched vendor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid cloud data management specialists given APRA prudential standard updates accelerating compliance-driven refresh cycles. Long-term viability over the next decade hinges on software-defined storage orchestration capabilities bridging on-premises and multi-cloud deployments. Monitor TGA health data guideline enforcement as the signal indicating inflection in healthcare vertical storage spend.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Certification Investment | Critical Infrastructure Protection Act compliance creates procurement preference for encrypted, Australian-key-escrow hardware. |
| Consumption-Based Service Model Expansion | HPE GreenLake and Dell APEX offerings align storage costs with utilization for capital-constrained mid-tier enterprises. |
| Secondary Market Geographic Expansion | Perth and Brisbane data center buildouts diversify hyperscale presence beyond saturated Sydney-Melbourne corridors. |
| AI Pipeline Storage Architecture Development | Object storage for exabyte-scale unstructured data lakes serves media streaming and machine learning training workloads. |
| Sustainability Disclosure Program | NABERS energy ratings and federal carbon mandates favor vendors with verified lifecycle emissions documentation. |
Research Methodology
ASIC corporate filings, Australian Bureau of Statistics trade data, and TGA regulatory guidance documents formed the secondary backbone for market sizing and compliance trajectory analysis. Primary interviews with data center infrastructure directors, storage procurement leads at ASX-listed financial institutions, cloud provider capacity planners, and value-added reseller technical architects combined with secondary validation to construct demand forecasts. Bottom-up facility-level capacity tracking and top-down vendor revenue triangulation anchored segmentation outputs across the analysis window.
Historical trendline analysis of hyperscale capex disclosures and enterprise storage refresh cycles established baseline growth trajectories without forward-year specificity. The analytical framework modeled segmentation across storage type, technology tier, capacity scale, and end-user vertical throughout the forecast period. CAGRs derived from facility pipeline tracking and vendor order book analysis incorporated NVMe flash adoption curves, compliance-driven replacement timelines, and cloud provider expansion commitments as industry-specific inputs.
Revisions become necessary when NAND foundry capacity allocations shift, Australian electricity price volatility alters total cost of ownership calculations, or Critical Infrastructure Protection Act amendments impose new encryption mandates. Forecasts reflect documented assumptions around hyperscale buildout schedules and sovereign certification adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
NOR Flash Market
Data Storage
Multiprotocol Storage Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
Hardware Storage Market
Data Storage
Optical Disk Market
Data Storage
Next-Generation Storage Market
Data Storage
Next Generation Data Storage Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Germany Data Center Storage Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
SSD Controller Market
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
Blu-Ray Optical Disk Market
Data Storage
Data Center Ssds Market
Data Storage
Ethernet Storage Market