
 Enterprise Hard Drive Market | 2026-2036
Enterprise Hard Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Hard Drive Market Insights
Cloud computing providers is realigning procurement patterns across the enterprise storage landscape. Seagate Technology leverages helium-sealed platform manufacturing to sustain cost leadership in high-capacity nearline drives. Western Digital Corporation anchors its position through vertical integration into NAND flash and HDD substrate operations. Toshiba Corporation specializes in enterprise SAS interfaces for mission-critical workloads where reliability premiums command durable margins.
Enterprise hard drives are electromechanical data storage devices utilizing magnetic recording on rotating platters, typically spinning at 7200 or 15000 RPM with areal densities exceeding 1 terabit per square inch, designed for continuous operation in networked storage arrays and server environments. Their primary commercial purpose centers on delivering cost-optimized capacity for cold and warm data tiers where flash storage economics prove prohibitive at petabyte scale. SAS interface deployments continue to dominate transaction-intensive applications in financial services and healthcare imaging, while SATA configurations absorb bulk archival demand from video surveillance and compliance-driven backup solutions. SSD product categories are displacing performance-tier HDD placements in primary databases, though HDD retains structural advantage in total cost of ownership for sequential write workloads.
The EPA ENERGY STAR program and EU Ecodesign requirements enforce standby and active power thresholds that constrain mechanical design choices and platter stack configurations. NIST and ISO 27001 frameworks further mandate encryption standards and supply chain attestation that filter vendor eligibility for federal and healthcare procurement channels. Stakeholders must monitor the trajectory of heat-assisted magnetic recording commercialization against solid-state density roadmaps to calibrate capacity investment timing and interface portfolio weightings.
Market Dynamics
Heat-assisted magnetic recording commercialization timelines are compressing nearline HDD refresh cycles while EU F-Gas Regulation enforcement is forcing platter stack redesigns across manufacturing footprints.
Growth Catalysts
- Hyperscale data center expansion:Cloud providers in Virginia, Texas, and Oregon are commissioning exabyte-scale storage clusters for AI training datasets. This infrastructure buildout sustains procurement velocity for high-capacity nearline drives.
- EU Ecodesign standby power mandates:The directive's 2027 thresholds for idle consumption are accelerating helium-sealed platform adoption. Manufacturers must achieve sub-5W idle targets to maintain market access.
- Data sovereignty legislation:National data localization requirements in France, Germany, and India are forcing cloud operators to provision in-region storage capacity. This geographic fragmentation multiplies physical drive deployment requirements.
Market Restraints
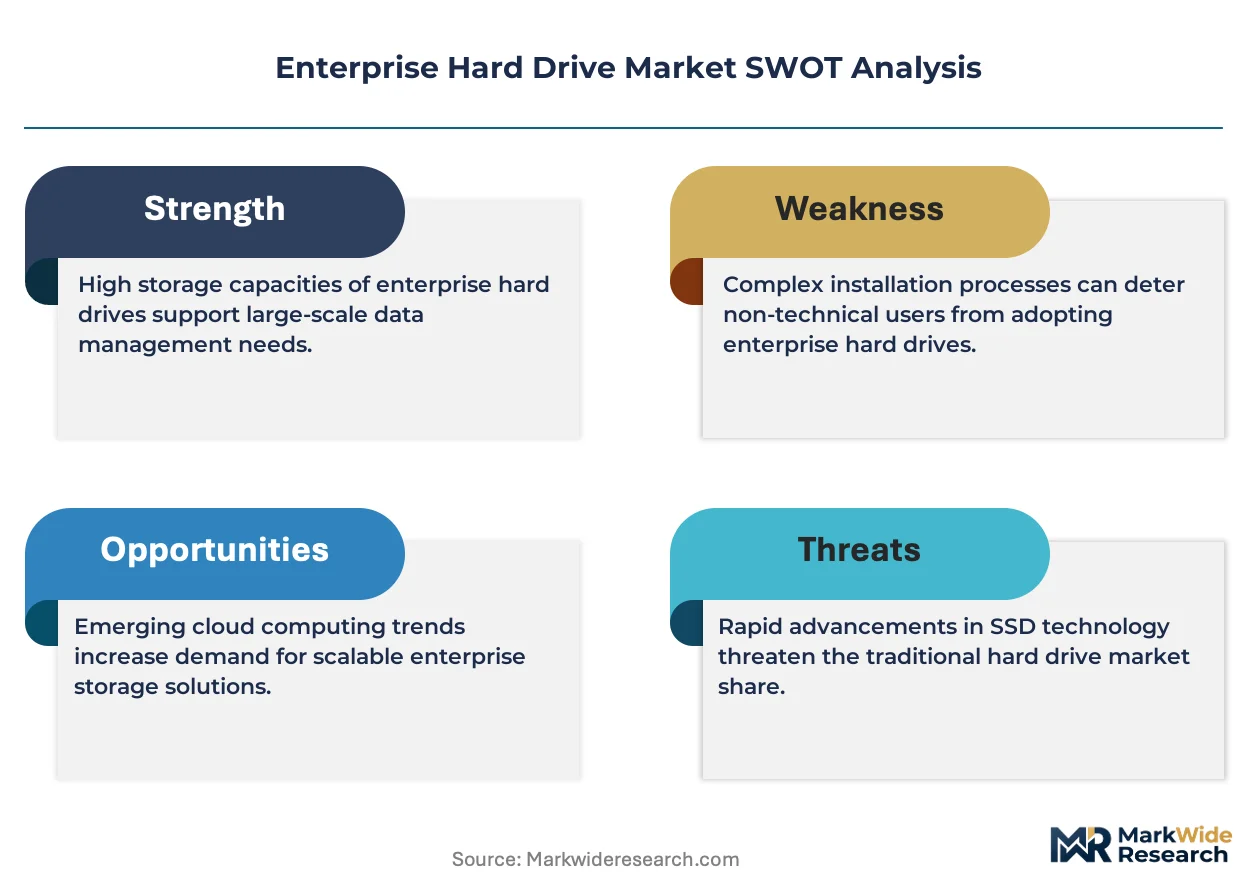
- NAND flash cost curves:QLC solid-state density improvements are encroaching on warm-tier HDD economics below 4TB capacities. Enterprise SSDs now achieve total cost of ownership parity for random read-intensive workloads.
- Platter substrate supply concentration:Aluminum-magnesium alloy and glass substrate production clusters in Japan and Malaysia create single-source vulnerability. Any disruption propagates through the entire HDD supply chain.
- Areal density physics ceiling:Perpendicular magnetic recording approaches superparamagnetic limits without heat-assisted or microwave-assisted recording implementation. This technical boundary constrains capacity-per-drive scaling.
Strategic Opportunities
- India data center buildout:The country's PLI scheme for electronics manufacturing is attracting hyperscale investments in Mumbai, Chennai, and Hyderabad. Local assembly requirements create captive demand for enterprise storage hardware.
- Video analytics cold storage:Smart city surveillance deployments in Brazil and Saudi Arabia generate petabyte-scale sequential write archives. These workloads favor HDD economics over flash for 90-day retention tiers.
- ISO 27001 attestation services:Federal and healthcare procurement channels now mandate supply chain documentation. Vendors offering pre-certified encryption and provenance tracking command premium positioning.
Industry Challenges
- Magnetic recording physics talent scarcity:The specialized expertise required for heat-assisted recording head design concentrates within a narrow demographic of engineers. Succession planning gaps threaten R&D continuity.
- Cleanroom capex intensity:Helium-sealed drive assembly requires Class 10 manufacturing environments. Facility construction timelines exceed 24 months, constraining capacity responsiveness to demand spikes.
- NIST FIPS 140-3 certification timelines:Hardware encryption module validation cycles now extend 18-22 months. This delay window risks disqualification from federal procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Hard Drive Market |
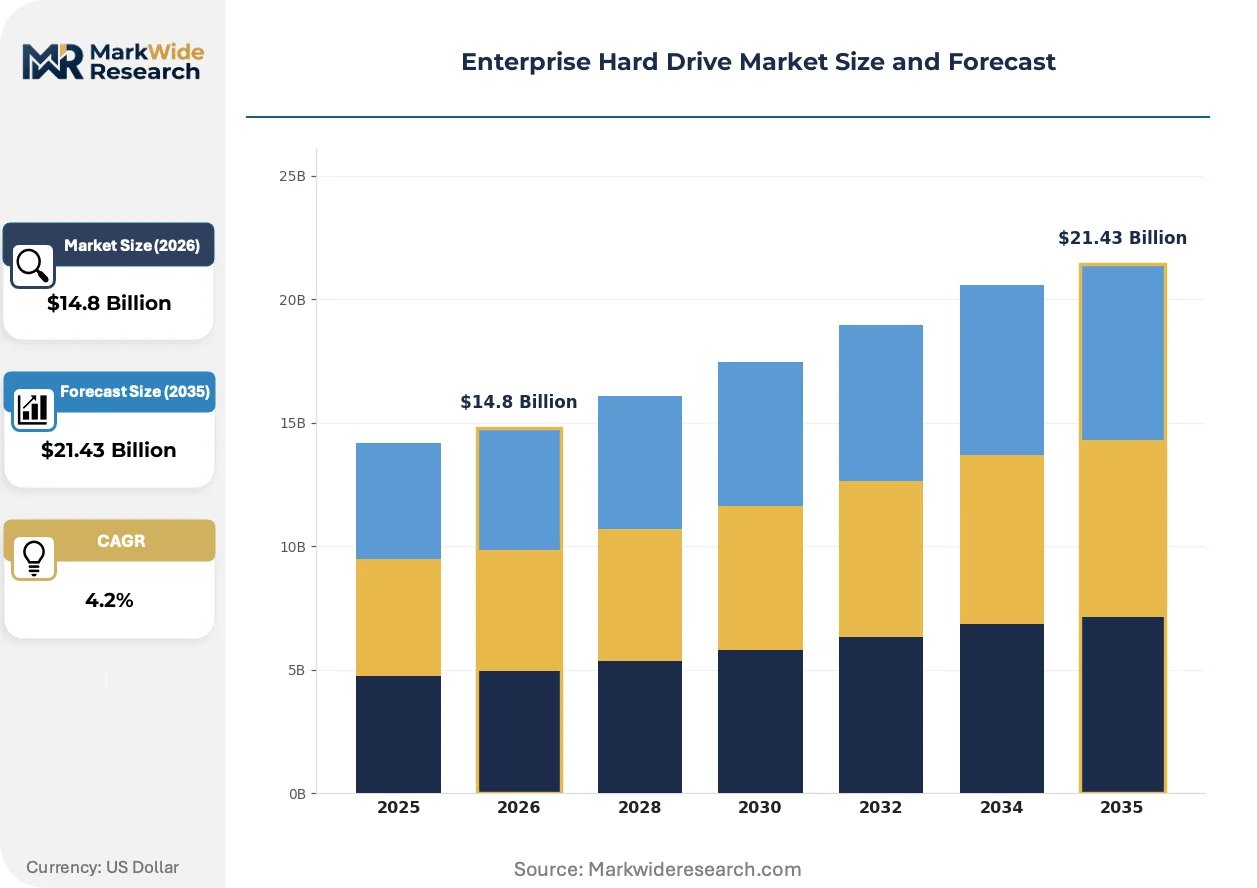
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SATA, SAS, SSD, HDD Application: Data Storage, Cloud Computing, Backup Solutions, Video Surveillance End User: IT Firms, Healthcare Organizations, Financial Institutions, Educational Institutions Capacity: 1TB, 2TB, 4TB, 8TB |
| Companies Covered | Seagate Technology, Western Digital Corporation, Toshiba Corporation, Hewlett Packard Enterprise Development LP, Dell Technologies Inc., Lenovo Group Limited, Samsung Electronics, Fujitsu Limited, Kioxia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Hard Drive Market Trends and Innovations
Recording technology roadmaps and regulatory energy thresholds are converging to reshape mechanical storage architectures. The transition from air-filled to hermetically sealed platforms exemplifies how physics constraints and policy mandates now co-design product form factors.
Heat-assisted magnetic recording (HAMR) is modularizing nearline drive architectures by separating the thermal write element from conventional read heads. Hyperscale operators in the United States are piloting 30TB+ HAMR units for video streaming archives. This bifurcation is compressing product lifecycles as manufacturers maintain parallel air and helium platform inventories.
EU F-Gas Regulation phase-down schedules are prohibiting hydrofluorocarbon-based cleaning processes in European manufacturing facilities. Drive assemblers must retrofit production lines with fluorinated gas-free solvent systems or relocate final assembly outside the customs union. Nearline products destined for EU public sector tenders face the strictest compliance verification requirements.
Consumption-based storage contracts are displacing capital-intensive procurement among mid-market enterprises. Managed service providers in Germany and the Netherlands now bundle physical drive infrastructure with operational expenditure pricing. Healthcare imaging networks in Bavaria and North Rhine-Westphalia represent the fastest-adopting vertical for this hardware-as-a-service transition.
Enterprise Hard Drive Market Segmentation
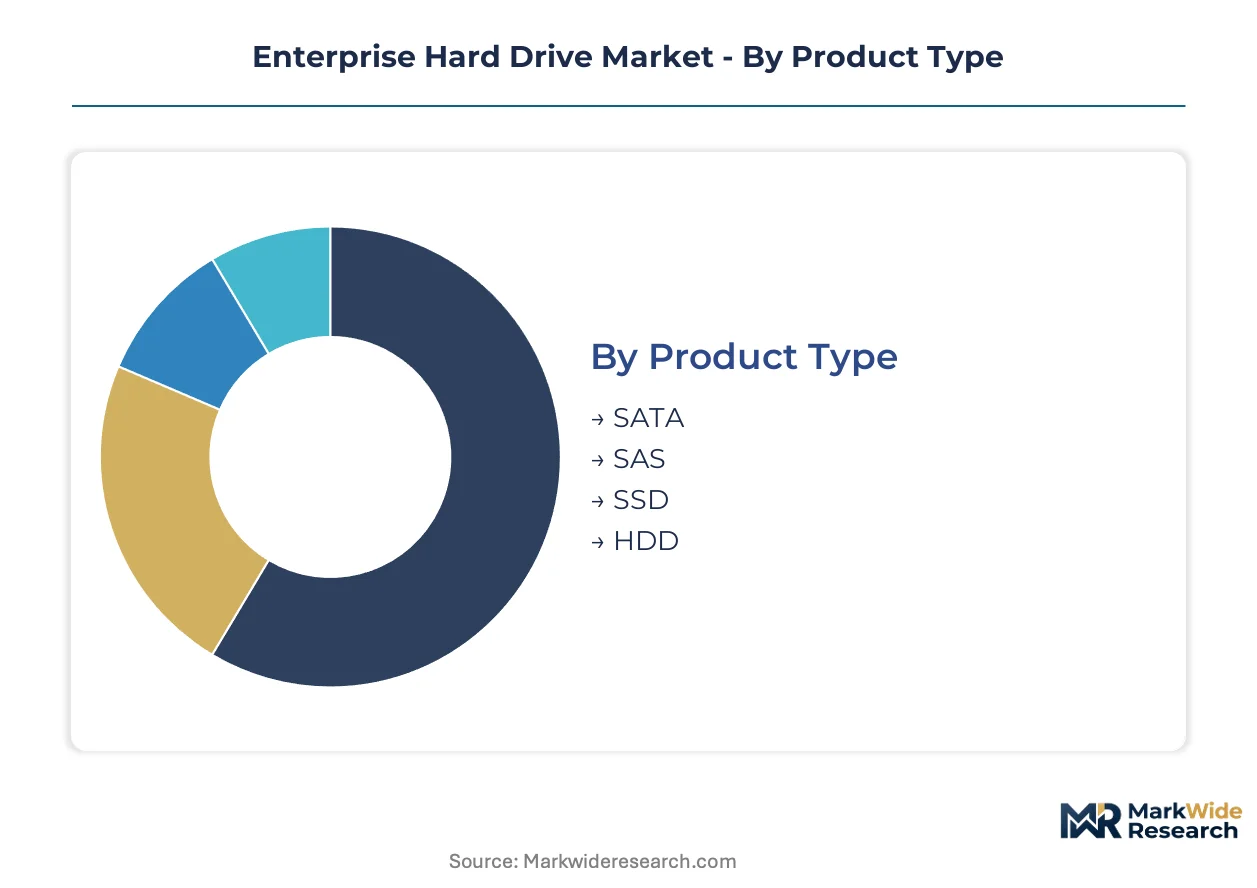
Enterprise storage procurement decisions hinge on workload-specific requirements that vary dramatically across interface protocols, application intensity, and data retention policies. Segmentation reveals how hyperscale operators, healthcare networks, and financial services prioritize different performance-cost tradeoffs when provisioning petabyte-scale infrastructure.
Product Type:
Refresh cycles diverge sharply across interface standards, with SATA deployments stretching to five-year replacement windows while SAS arrays turn over every three years to maintain transaction latency guarantees.
- SATA:6Gb/s interface dominates bulk archival tiers where sequential throughput suffices. Hyperscale data centers in Virginia and Texas favor 16TB+ SATA units for video streaming cold storage, driven by petabyte-scale economics that flash cannot match.
- SAS:12Gb/s dual-port architecture targets mission-critical databases requiring sub-10ms random access. Financial institutions in Frankfurt and Singapore maintain SAS dominance for high-frequency trading platforms where downtime costs exceed hardware premiums.
- SSD:NAND-based solid-state arrays displace 10K RPM HDDs in primary tier-0 storage. Healthcare imaging networks in Bavaria accelerate PACS retrieval through all-flash configurations, though cost curves still prohibit full HDD replacement.
- HDD:Conventional magnetic recording retains structural advantage in sequential write workloads. Compliance-driven backup solutions across German industrial zones sustain demand for air-filled enterprise units below 8TB capacities.
SATA sits at the top of the volume ranking, with SSD climbing the fastest as QLC density improvements compress warm-tier HDD economics.
Application:
Cost tier differentiation separates capital-intensive primary storage from operational expenditure models now penetrating archival and surveillance verticals.
- Data Storage:General-purpose enterprise arrays balance random and sequential performance. Indian hyperscale clusters in Mumbai and Chennai absorb mid-capacity nearline units as data localization mandates multiply physical deployment requirements.
- Cloud Computing:Exabyte-scale infrastructure demands maximum areal density per rack unit. Oregon and Virginia facilities pilot 30TB+ heat-assisted recording drives for AI training dataset repositories, compressing floor space and power draw per petabyte.
- Backup Solutions:Immutable air-gap archives satisfy ransomware recovery and regulatory retention. German healthcare networks adopt consumption-based backup contracts that bundle physical HDD infrastructure with operational expenditure pricing.
- Video Surveillance:Petabyte-scale sequential write streams from smart city deployments. Saudi Arabian municipal projects generate 90-day retention archives where HDD total cost of ownership undercuts flash by substantial margins.
Cloud Computing commands the steepest expansion trajectory, while Backup Solutions maintains the largest installed base across regulated industries.
End User:
Customer type determines encryption certification requirements and procurement channel access, with federal and healthcare mandates filtering vendor eligibility through NIST and ISO 27001 frameworks.
- IT Firms:Managed service providers bundle physical infrastructure with subscription pricing. Dutch and German providers lead hardware-as-a-service transitions among mid-market enterprises seeking to convert capital expenditure.
- Healthcare Organizations:HIPAA and GDPR compliance mandates hardware encryption with supply chain attestation. Bavarian imaging networks represent the fastest-adopting vertical for consumption-based storage contracts.
- Financial Institutions:Basel III operational resilience rules extend to data infrastructure redundancy. Singaporean trading platforms sustain SAS premium pricing for sub-millisecond latency guarantees.
- Educational Institutions:Budget-constrained procurement favors SATA configurations for research data lakes. Indian universities leverage PLI scheme benefits to access locally assembled enterprise storage hardware.
IT Firms generate the highest procurement velocity, with Healthcare Organizations gaining share fastest as imaging data volumes compound regulatory retention requirements.
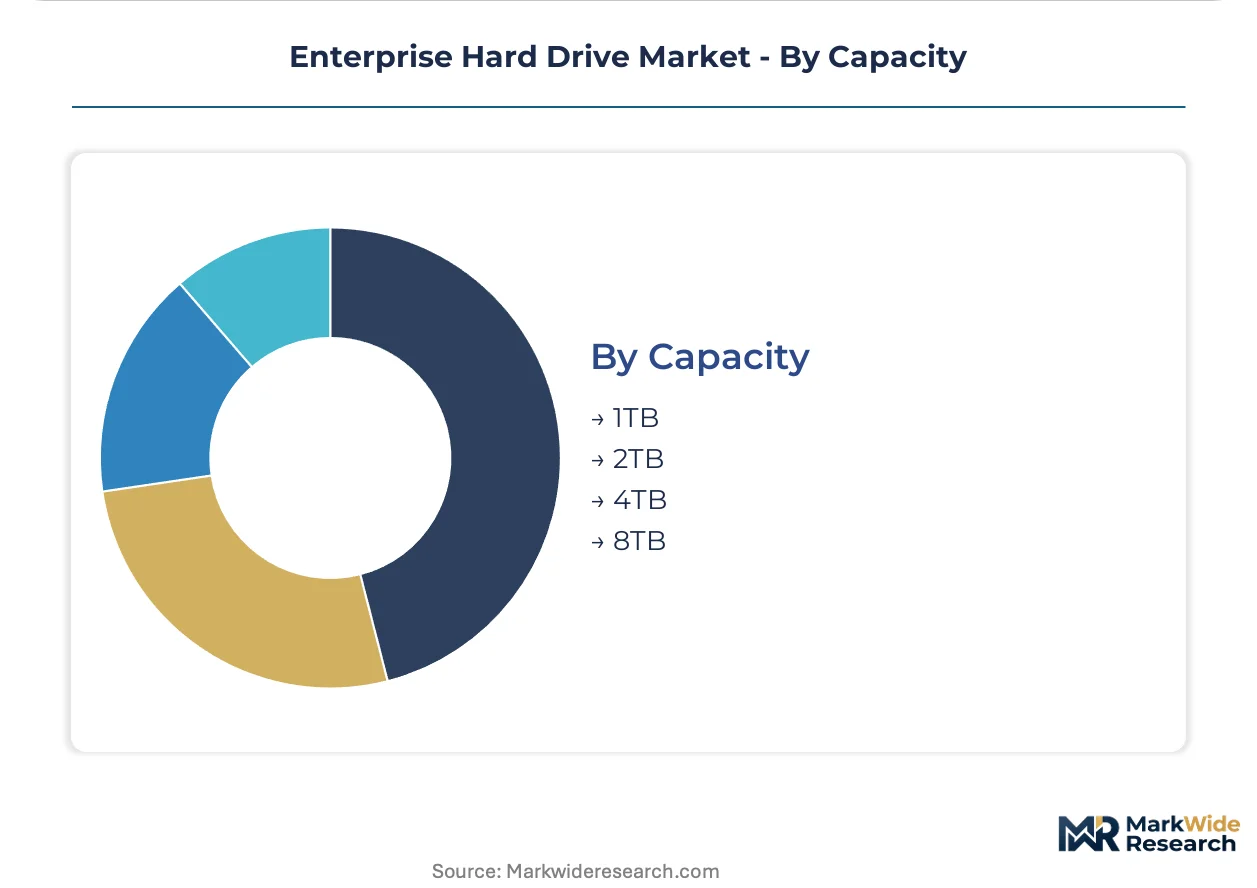
Capacity:
Supply concentration in substrate manufacturing creates tiered availability, with glass and aluminum-magnesium platter sources in Japan and Malaysia constraining responsiveness to demand spikes in higher-density segments.
- 1TB:Legacy enterprise boot drives and specialized industrial controllers. German manufacturing automation systems sustain residual demand for small-form-factor SAS units in legacy equipment refresh cycles.
- 2TB:Entry-level nearline configurations for distributed office servers. Educational institutions in the Netherlands favor this tier for departmental file shares where capital budgets preclude hyperscale density premiums.
- 4TB:QLC flash encroachment threshold where SSD total cost of ownership achieves parity. Financial services transaction logs in Frankfurt increasingly migrate to solid-state at this capacity breakpoint.
- 8TB:Current sweet spot for helium-sealed nearline platforms balancing rack density and power efficiency. Virginia hyperscale facilities standardize on this tier for warm data layers awaiting HAMR commercialization.
8TB dominates current procurement volumes, with 4TB facing displacement pressure as NAND cost curves compress its addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as EU F-Gas Regulation enforcement drives final assembly relocation toward jurisdictions with lower compliance costs. Manufacturers balance proximity to hyperscale demand clusters against cleanroom construction timelines and energy pricing differentials.
United States
Virginia, Texas, and Oregon host exabyte-scale data center buildouts for AI training workloads. EPA ENERGY STAR thresholds enforce sub-5W idle power targets for federal procurement eligibility. Northern Virginia's Loudoun County sustains the densest concentration of enterprise storage demand globally.
Germany
EU Ecodesign standby mandates accelerate helium-sealed platform adoption for public sector tenders. Frankfurt's financial institutions maintain SAS infrastructure for high-frequency trading latency requirements. Bavarian healthcare imaging networks pioneer consumption-based storage contract models.
India
PLI scheme incentives attract hyperscale investments in Mumbai, Chennai, and Hyderabad. Data localization requirements under the Digital Personal Data Protection Act multiply physical drive deployment needs. Local assembly mandates create captive demand for enterprise hardware manufacturing.
Japan
Aluminum-magnesium and glass substrate production clusters concentrate manufacturing vulnerability in domestic supply chains. METI efficiency standards align with EU regulatory trajectories for export market access. Tokyo-Osaka industrial corridor retains specialized magnetic recording head design expertise.
Saudi Arabia
Smart city surveillance deployments in Riyadh and Jeddah generate petabyte-scale sequential write archives. Municipal 90-day retention policies favor HDD economics over flash alternatives. Giga-project developments anchor regional demand for bulk storage infrastructure.
Enterprise Hard Drive Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit helium-sealed production lines to meet EU energy compliance deadlines. The vendor base concentrates around three integrated specialists controlling substrate supply and recording head fabrication. Strategic archetypes separate pure-play HDD fabricators from diversified storage conglomerates and captive cloud infrastructure operators. M&A activity and geographic production relocation constitute the primary competitive vectors as regulatory thresholds reshape cost structures.
Within the integrated specialist tier, Seagate Technology and Western Digital Corporation occupy positions defined by captive control over upstream substrate and head manufacturing operations. Toshiba Corporation exemplifies the interface-specialist archetype, with its enterprise SAS focus serving mission-critical reliability premiums. Among diversified technology conglomerates, Samsung Electronics and Kioxia Corporation sit within broader semiconductor portfolios where NAND flash and HDD product lines coexist under unified storage strategies.
| Leading Market Players |
|---|
| Seagate Technology |
| Western Digital Corporation |
| Toshiba Corporation |
| Hewlett Packard Enterprise Development LP |
| Dell Technologies Inc. |
| Lenovo Group Limited |
| Samsung Electronics |
| Fujitsu Limited |
| Kioxia Corporation |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud operators in Virginia, Texas, and Oregon command volume-based contract structures that compress distributor margins and force direct-to-OEM pricing models. Their exabyte-scale procurement leverage extracts per-drive discounts while shifting inventory risk upstream to manufacturers.
Pricing Analysis
Distributor margins compress to single-digit percentages for hyperscale direct accounts while value-added resellers retain 15-20% markups on mid-market SATA deployments. Three-tier pricing structure across premium SAS, standard helium-sealed nearline, and economy air-filled tiers reflects certification grade and interface protocol differentiation. Cost compression in entry-level SATA segments intensifies as QLC flash achieves total cost of ownership parity below 4TB capacities. Healthcare organizations and financial institutions exhibit lowest price sensitivity, prioritizing FIPS 140-3 certification and sub-10ms latency guarantees over per-gigabyte economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand while distribution partners serve mid-market enterprises and educational institutions through value-added logistics. Substrate manufacturing concentrates in Japan and Malaysia for aluminum-magnesium and glass platter production. Magnetic recording head fabrication draws from specialized cleanroom facilities in the United States and Japan. Single-source vulnerability in Japanese glass substrate production creates propagation risk through the entire HDD supply chain. Distribution runs through authorized distributors with NIST and ISO 27001 attestation capabilities for federal and healthcare procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where data sovereignty mandates and AI training workloads shift procurement toward premium-certified, high-capacity helium-sealed platforms with extended reliability guarantees.
For Market Incumbents: Hedge against NAND flash encroachment by accelerating heat-assisted magnetic recording commercialization and securing captive substrate supply from Japanese glass manufacturing clusters. Maintain parallel air and helium platform inventories to serve fragmented regulatory requirements across EU F-Gas Regulation and EPA ENERGY STAR jurisdictions. Certification investment in NIST FIPS 140-3 validation cycles constitutes the critical defensive lever for federal procurement access. For New Entrants and Emerging Players: The price-point gap between premium SAS mission-critical drives and bulk SATA archival units offers white-space entry for mid-market managed service providers in Germany and the Netherlands. Target consumption-based storage contracts in Bavarian healthcare imaging networks where operational expenditure models displace capital-intensive procurement. Pursue ISO 27001 attestation services as a go-to-market angle to capture compliance-driven premium positioning. For Investors and Strategic Acquirers: Cloud infrastructure operators are the most active acquirer in this space, seeking captive storage supply for AI training dataset expansion. Long-term viability hinges on heat-assisted recording physics expertise concentration and cleanroom manufacturing asset scarcity. Monitor commercialization timelines for 30TB+ HAMR deployments as the inflection indicator for capacity-per-drive scaling sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Sealed Platform Expansion | EU Ecodesign standby mandates below 5W idle power require hermetic sealing technology retrofit. |
| Heat-Assisted Recording Commercialization | Hyperscale pilots in Oregon and Virginia validate 30TB+ architectures for AI training archives. |
| Substrate Supply Security | Japanese and Malaysian aluminum-magnesium and glass production clusters require captive offtake agreements. |
| FIPS 140-3 Certification Investment | Federal and healthcare procurement channels now mandate 18-22 month hardware encryption validation cycles. |
| Consumption-Based Contract Launch | German and Dutch managed service providers convert mid-market capital expenditure to operational expenditure models. |
Research Methodology
Multiple input streams — hyperscale data center procurement officers, enterprise storage array manufacturers, magnetic recording head design engineers, and healthcare imaging network IT directors — were reconciled against customs trade data, hyperscaler capital expenditure disclosures, SEC 10-K filings, and EU regulatory implementation documents. Bottom-up unit shipment estimates from substrate and component suppliers were triangulated against top-down infrastructure investment tracking across Virginia, Texas, and Oregon data center clusters.
Historical capacity deployment patterns were cross-referenced against panel input from cloud infrastructure planners and financial institution storage architects. The analytical framework modeled interface protocol, application intensity, capacity tier, and regional regulatory cluster segmentation across the projection horizon. CAGRs were derived from infrastructure investment trajectories, data sovereignty mandate implementation schedules, and recording technology roadmaps. Forecast inputs incorporated AI training dataset growth curves and EU F-Gas Regulation phase-down compliance timelines.
Caveats apply where NAND flash cost curve acceleration, substrate supply disruption, or heat-assisted recording commercialization delays could materially shift the outlook. Forecasts reflect assumptions about hyperscale procurement velocity, regulatory enforcement consistency, and magnetic recording physics advancement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Electrochromic Storage Devices Market
Data Storage
Powered Storage Devices Market
Data Storage
Storage Virtualization Market
Data Storage
NAND Flash Memory Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Global Portable Data Storage Market
Data Storage
Optical Disk Market
Data Storage
China Solid-State Drive Market
Data Storage
APAC Next Generation Storage Market
Data Storage
SAS Hard Disk Drives Market
Data Storage
Taiwan Data Center Storage Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
NOR Flash Market
Data Storage
Asia-Pacific Data Center Storage Market
Data Storage
SSD Controller Market
Data Storage
Next-Generation Storage Market