
 North America AMH and Storage Systems Market | 2026-2036
North America AMH and Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America AMH and Storage Systems Market Foresight
Autonomous mobile robotics is fragmenting the traditional fixed-conveyor architecture that dominated warehouse automation for decades. Honeywell Intelligrated leverages its integrated software-hardware stack to anchor large-scale distribution deployments. Daifuku Co. competes through deep manufacturing scale in automated storage and retrieval systems. Jungheinrich AG specializes in forklift-integrated robotics for European-headquartered multinationals operating North American facilities.
Automated material handling and storage systems encompass electromechanical equipment, control software, and sensor networks designed to transport, store, and retrieve goods with minimal human intervention, typically operating at throughput rates exceeding 200 cycles per hour in high-density configurations. These systems serve to compress facility footprints, reduce labor dependency, and synchronize inventory velocity with order fulfillment windows. Automated Storage and Retrieval Systems dominate capital allocation in cold-chain and pharmaceutical verticals where cubic density justifies vertical racking investments. Automated Guided Vehicles lead growth in automotive OEM body shops and finished-vehicle distribution yards where magnetic or LiDAR-guided transport replaces manned tugger routes. Vertical Lift Modules occupy the mid-market retrofit segment, offering modular footprint expansion for spare-parts operations with ceiling heights below forty feet.
The US Department of Labor's OSHA enforces machine guarding and lockout-tagout protocols that directly constrain robot speed envelopes and collaborative workspace geometries. The American National Standards Institute alongside the Robotics Industries Association publishes R15.06 safety standards that manufacturers must certify against for commercial deployment. Canada's CSA Group maintains parallel electrical and mechanical safety requirements that create dual-compliance obligations for cross-border suppliers. Stakeholders must monitor how forthcoming AI liability frameworks and state-level warehouse automation labor codes reshape total cost of ownership calculations and deployment timelines.
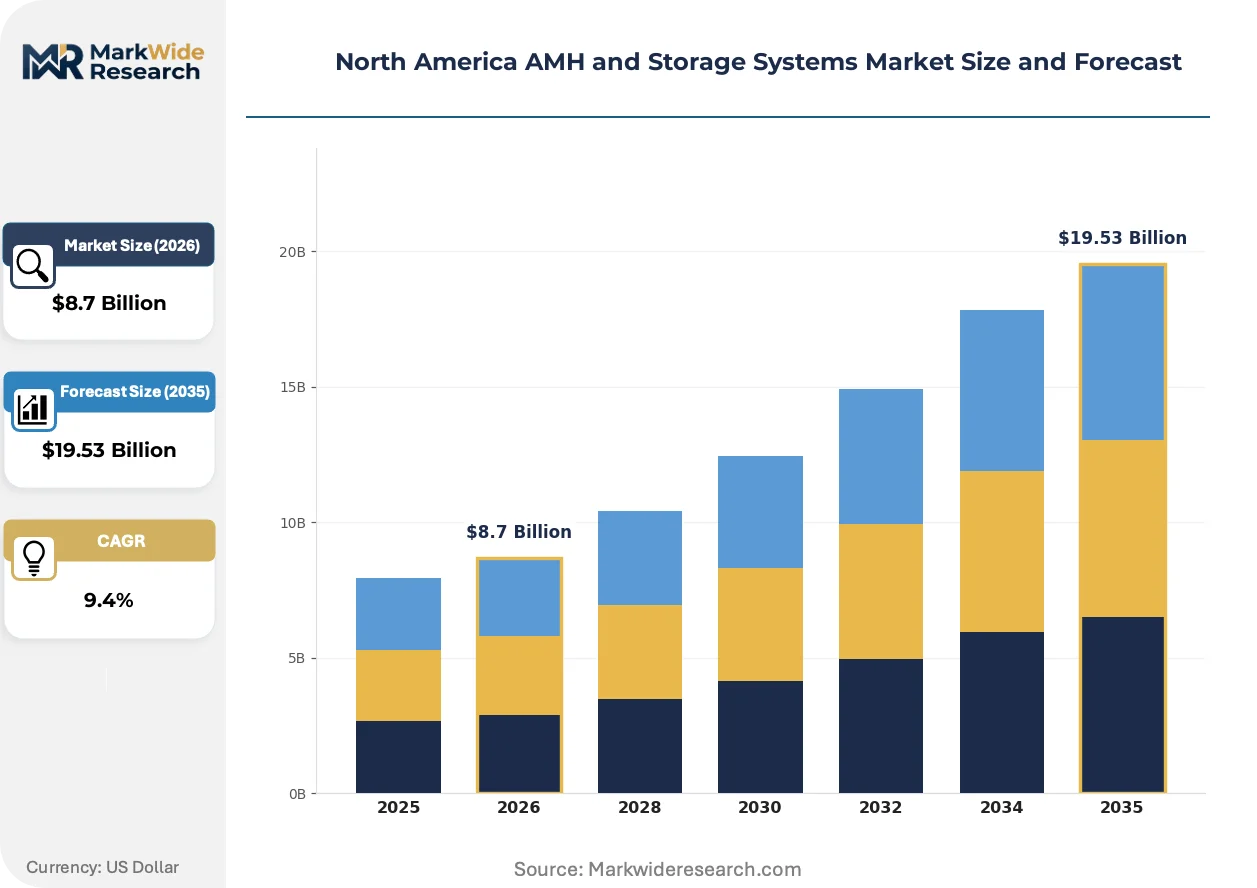
Market Dynamics
The migration from fixed-conveyor infrastructure to autonomous mobile robotics is compressing warehouse footprints while reconfiguring labor deployment across North American distribution networks.
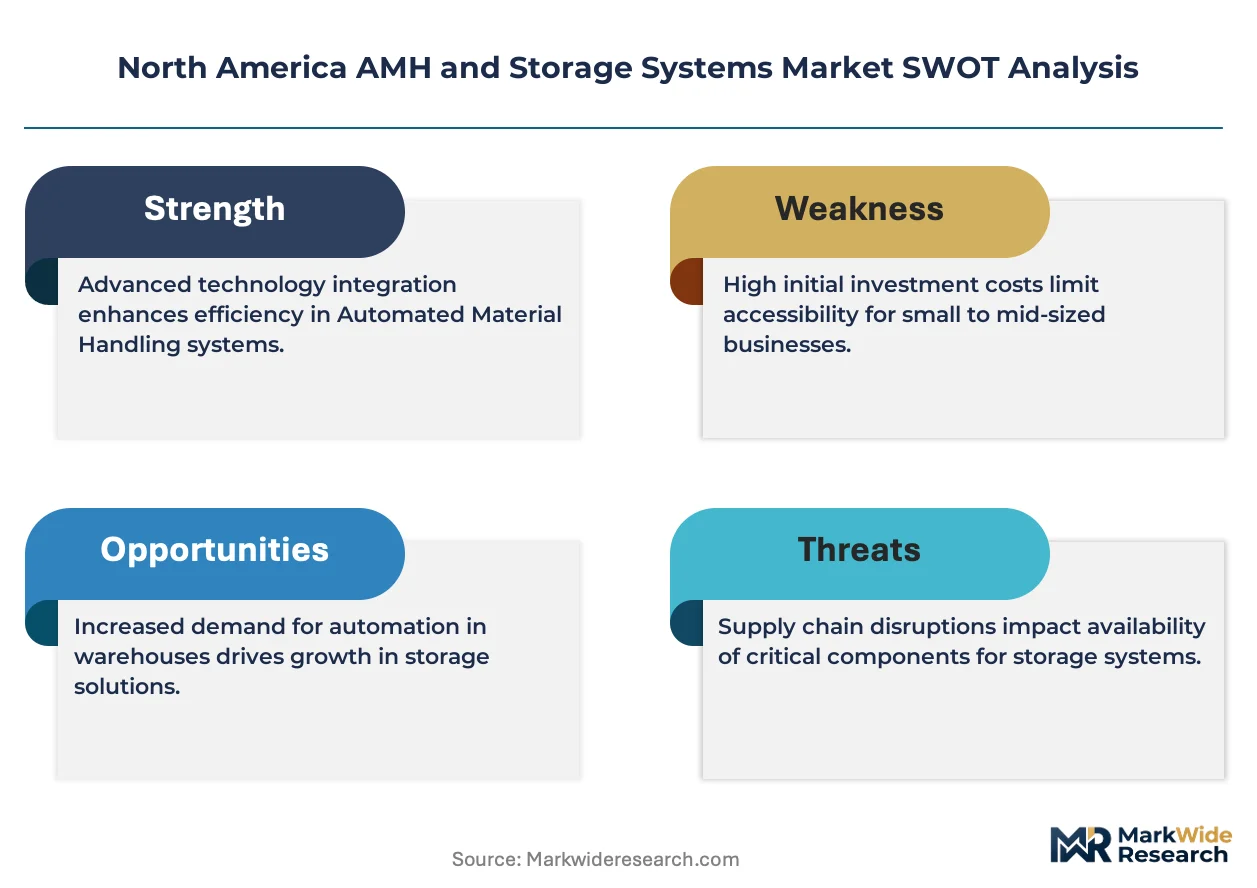
Growth Catalysts
- OSHA Machine Guarding Standards:Updated lockout-tagout protocols are accelerating collaborative robot deployments by clarifying human-robot workspace boundaries.
- Pharmaceutical Cold-Chain Vertical:Temperature-sensitive biologics distribution is driving vertical racking investments exceeding forty-foot clear heights.
- Southeast Logistics Corridor:Warehouse clusters spanning Georgia, Tennessee, and South Carolina are concentrating demand for high-throughput retrieval systems.
Market Restraints
- Steel Input Volatility:Structural racking and conveyor fabrication costs fluctuate with regional steel mill capacity and tariff exposure.
- Canadian CSA Dual-Compliance:Cross-border suppliers face redundant electrical and mechanical safety certification obligations.
- LiDAR Sensor Supply Concentration:Autonomous vehicle navigation depends on a narrow supplier base for industrial-grade sensing hardware.
Strategic Opportunities
- Mexico Nearshoring Wave:Automotive and electronics manufacturers are relocating assembly operations, creating greenfield automation demand.
- AI Liability Framework Gaps:Absence of federal autonomous equipment tort standards creates first-mover advantage for vendors with robust safety documentation.
- Vertical Lift Module Retrofits:Ceiling-constrained spare-parts operations present modular expansion opportunities below traditional AS/RS thresholds.
Industry Challenges
- Controls Engineering Talent Scarcity:PLC programming and warehouse management system integration expertise lags deployment timelines.
- ANSI/RIA R15.06 Certification Delays:Safety standard compliance testing extends product launch cycles by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America AMH and Storage Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Vertical Lift Modules, Automated Storage and Retrieval Systems, Carousel Systems End User: Retail, Automotive OEMs, E-Commerce, Manufacturing Technology: Robotics, Artificial Intelligence, Internet of Things, Cloud Computing Application: Order Fulfillment, Inventory Management, Packaging, Distribution |
| Companies Covered | Honeywell Intelligrated, Daifuku Co., Jungheinrich AG, Interroll Group, SSI SCHAEFER AG, Murata Machinery Limited, BEUMER Group, Kion Group, Toyota Industries Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America AMH and Storage Systems Market Shifts & Advancements
Digital twin environments are compressing system commissioning timelines while reshaping how warehouse operators validate automation configurations before physical deployment.
Simulation software is virtualizing the traditional physical prototyping phase for material handling system design. E-commerce fulfillment operators now model throughput scenarios in cloud-based environments before committing to steel and concrete. This shift is virtualizing capital allocation decisions by reducing engineering change orders during installation.
OSHA's evolving enforcement posture on collaborative robot speed envelopes is tightening workspace safety protocols. The agency's regional offices are applying stricter interpretations of existing machine guarding rules to autonomous deployments. Automotive OEM body shops are responding by segregating human and robot zones with physical barriers rather than relying solely on sensor-based slowing.
Third-party logistics providers are unbundling automation procurement from long-term facility leases. Retailers now contract directly with system integrators while 3PLs compete on operational execution alone. This pattern is most pronounced in California and Texas distribution markets where tenant improvement allowances no longer cover full automation stacks.
North America AMH and Storage Systems Market Segmentation
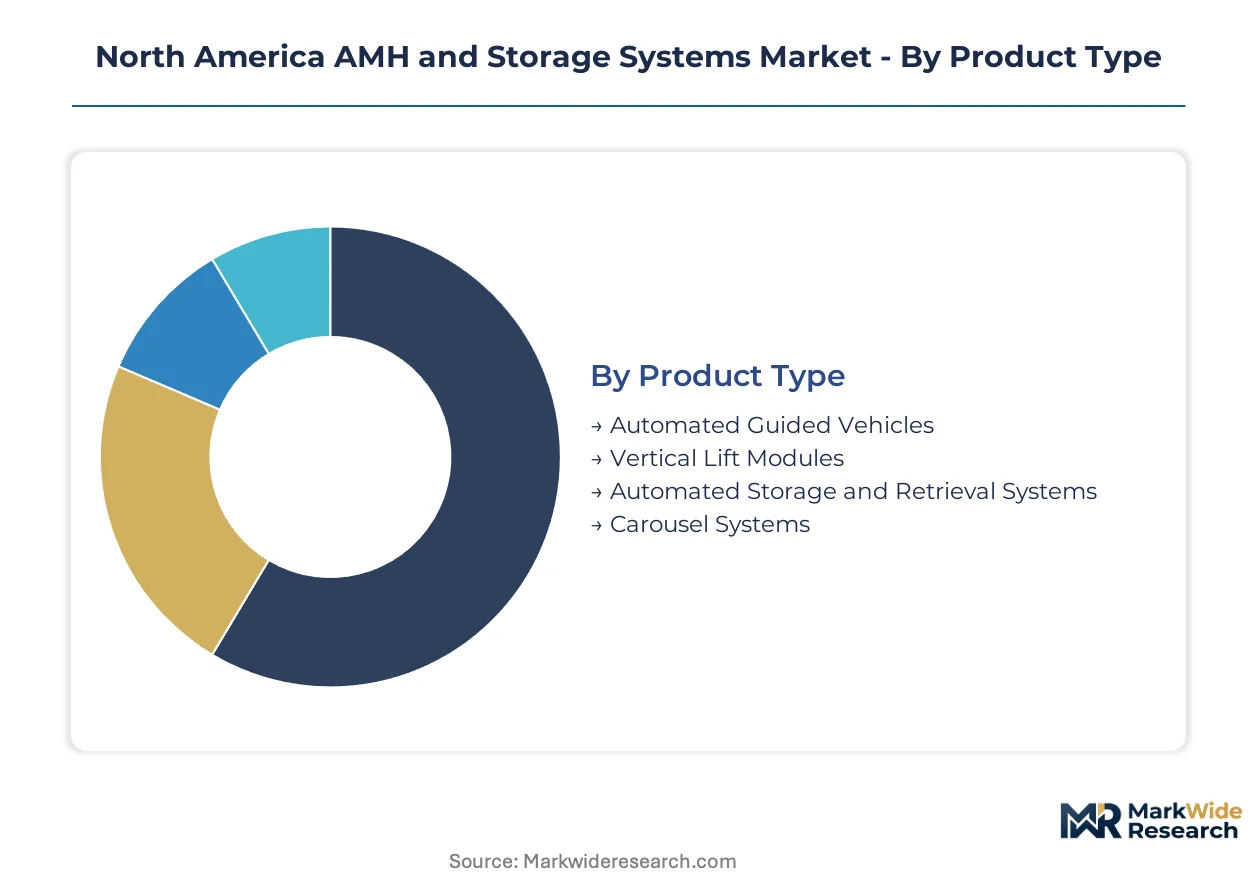
Segmentation in automated material handling reveals how capital allocation splits between fixed infrastructure and mobile robotics architectures. Understanding these divisions exposes where facility footprints compress and where labor substitution economics prove most compelling.
Product Type:
The use-case spectrum spans from ground-level transport to vertical cubic utilization, with each technology occupying distinct ceiling-height and throughput thresholds.
- Automated Storage and Retrieval Systems:Crane-based vertical racking systems retrieve pallets or totes from heights exceeding forty feet. Pharmaceutical cold-chain operators in the US Southeast deploy these configurations to maximize cubic density for temperature-sensitive biologics.
- Automated Guided Vehicles:Magnetic or LiDAR-guided mobile platforms transport loads across warehouse floors without fixed path infrastructure. Automotive OEM body shops in Tennessee and South Carolina favor these for flexibility in reconfiguring assembly-line feed routes.
- Vertical Lift Modules:Enclosed vertical storage carousels deliver items to an ergonomic access window. Spare-parts operations with ceiling constraints below forty feet adopt these for modular footprint expansion.
- Carousel Systems:Horizontal or vertical rotating shelf systems present stored items at fixed pick stations. Retail distribution centers employ these for moderate-velocity SKU buffering.
Established volume favors Automated Storage and Retrieval Systems; emerging adoption favors Automated Guided Vehicles.
End User:
Capital intensity and order-velocity requirements separate high-automation deployers from retrofit-oriented adopters.
- E-Commerce:Order profiles characterized by high SKU variety and compressed fulfillment windows drive demand for robotic piece-picking and autonomous mobile robot fleets. Georgia warehouse clusters concentrate multi-tenant fulfillment deployments.
- Automotive OEMs:Sequenced parts delivery to assembly lines requires precise timing and error-free kitting. Mexico nearshoring operations are expanding greenfield automation demand for these manufacturers.
- Retail:Seasonal demand volatility pushes investment toward scalable automation that handles peak volumes without year-round fixed costs.
- Manufacturing:Work-in-process inventory tracking and line-side replenishment dominate automation priorities in discrete production environments.
Capital deployment concentrates heaviest in E-Commerce; margin pressure is driving fastest expansion in Automotive OEMs.
Technology:
Software-hardware integration depth determines competitive differentiation and total cost of ownership trajectories.
- Robotics:Articulated arms and mobile platforms execute physical handling tasks with repeatability exceeding human capability. Collaborative robot deployments accelerate as OSHA clarifies human-robot workspace boundaries.
- Artificial Intelligence:Machine vision and predictive analytics optimize pick sequencing and equipment maintenance scheduling. Absence of federal autonomous equipment tort standards creates first-mover advantage for vendors with robust safety documentation.
- Internet of Things:Sensor networks feed real-time equipment status and inventory location data to centralized control systems.
- Cloud Computing:Remote hosting of warehouse management software reduces on-premise IT infrastructure and enables multi-site coordination.
Robotics anchors current installed base; Artificial Intelligence represents the steepest expansion trajectory.
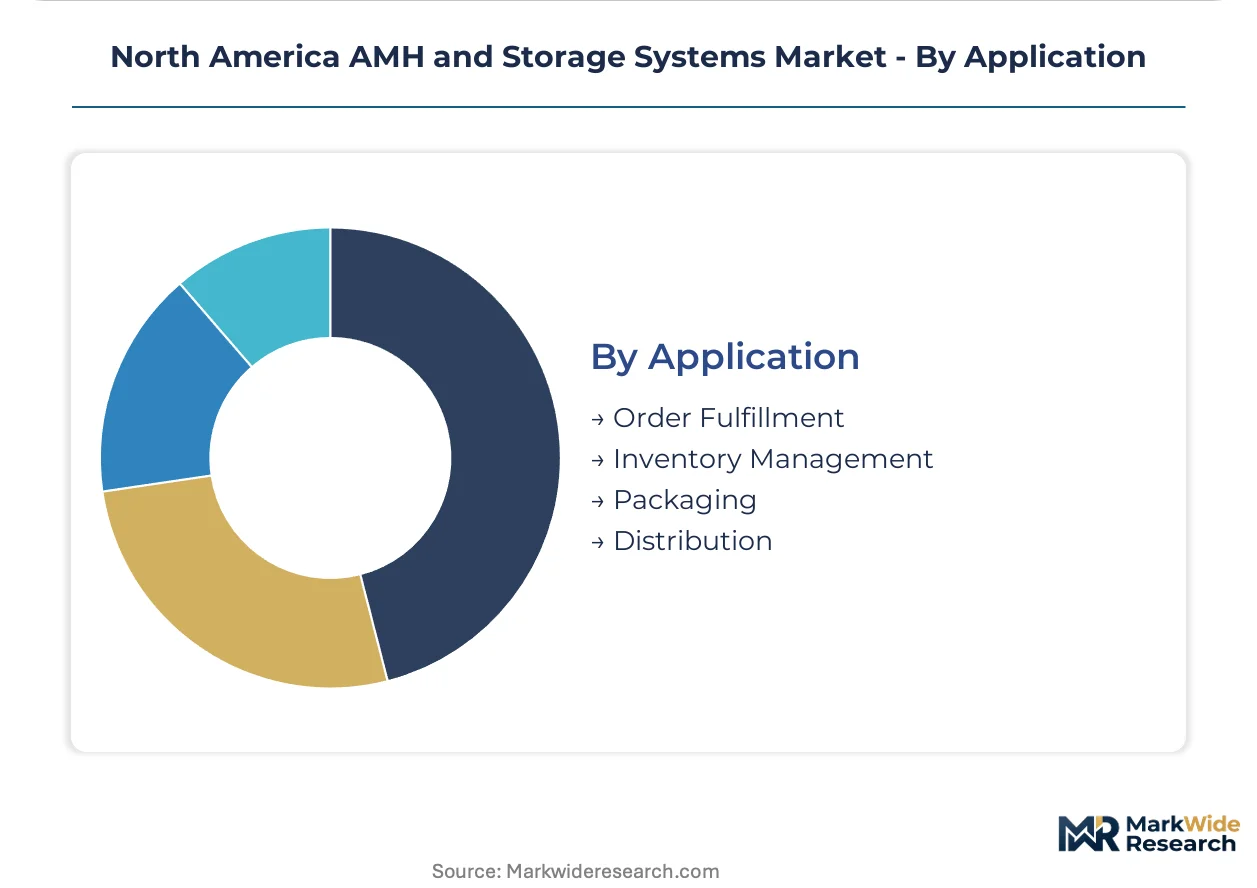
Application:
Process stage determines automation architecture, with upstream inventory handling differing fundamentally from downstream customer-facing operations.
- Order Fulfillment:Piece-picking, packing, and shipping preparation dominate labor content in e-commerce operations. Third-party logistics providers are unbundling automation procurement from long-term facility leases in California and Texas markets.
- Inventory Management:Cycle counting, put-away, and slotting optimization reduce carrying costs and stockout frequency.
- Packaging:Automated case forming, void fill, and label application integrate with conveyor networks for throughput consistency.
- Distribution:Cross-dock operations and outbound shipment sortation compress dwell time in transit facilities.
Labor substitution economics favor Order Fulfillment; inventory accuracy gains favor Inventory Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico exports automation hardware to US Southeast distribution hubs while Canadian integrators serve cross-border pharmaceutical cold-chain operators. This triangular trade flow concentrates equipment procurement decisions in three distinct regulatory environments.
United States
OSHA machine guarding standards and evolving ANSI/RIA R15.06 protocols accelerate collaborative robot deployments in Georgia, Tennessee, and South Carolina warehouse clusters. The Southeast logistics corridor concentrates demand for high-throughput retrieval systems serving e-commerce fulfillment centers.
Canada
CSA Group electrical and mechanical safety requirements create dual-compliance obligations for cross-border suppliers serving Ontario and Quebec pharmaceutical distribution networks. Toronto and Montreal cold-chain operators deploy vertical racking systems exceeding forty-foot clear heights for temperature-sensitive biologics.
Mexico
Automotive and electronics manufacturers relocating assembly operations to Nuevo León and the Bajío Region generate greenfield automation demand. Mexican federal labor codes and emerging state-level warehouse automation regulations reshape total cost of ownership calculations for foreign equipment vendors.
North America AMH and Storage Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented automation tiers. The vendor base spans integrated software-hardware stacks, manufacturing-scale fabricators, and forklift-integrated robotics specialists. Three archetypes dominate: full-stack system integrators, component-scale manufacturers, and regional equipment distributors. Competitive moves concentrate on strategic partnerships and technology licensing rather than vertical consolidation.
Within the full-stack integrator tier, Honeywell Intelligrated and Daifuku Co. occupy positions anchoring large-scale distribution deployments. Jungheinrich AG exemplifies the forklift-integrated robotics archetype serving European-headquartered multinationals operating North American facilities. These three entities represent distinct geographic origins and structural forms—US-based, Japanese, and German respectively—while sitting within differentiated automation value-chain positions.
| Leading Market Players |
|---|
| Honeywell Intelligrated |
| Daifuku Co. |
| Jungheinrich AG |
| Interroll Group |
| SSI SCHAEFER AG |
| Murata Machinery Limited |
| BEUMER Group |
| Kion Group |
| Toyota Industries Corporation |
| Others |
Supply & Pricing Matrix
The US Southeast logistics corridor spanning Georgia, Tennessee, and South Carolina channels freight cost volatility directly into equipment procurement decisions, compressing margins for cross-border suppliers while amplifying price differentiation between integrated system bundles and component-only sales.
Pricing Analysis
Cost-plus contracts with steel indexation dominate large-scale Automated Storage and Retrieval System procurements, tying final equipment pricing to regional mill capacity and tariff schedules. Three-tier pricing structure across premium, standard, and economy levels separates ANSI/RIA R15.06-certified collaborative robot deployments from uncertified legacy configurations. Pricing pressure stems from Canadian CSA dual-compliance obligations that inflate certification overhead for US-based vendors. E-commerce fulfillment operators exhibit the highest price sensitivity, while pharmaceutical cold-chain operators prioritize cubic density optimization over unit cost.
Supply Chain Analysis
Export controls on industrial-grade LiDAR sensors limit hardware flows from select Asian manufacturing hubs into North American autonomous vehicle deployments. Component sourcing draws from Germany for precision drive systems, Japan for crane-based retrieval mechanisms, and Mexico for structural steel fabrication. Single-source vulnerability concentrates in industrial-grade sensing hardware where qualified suppliers remain narrow. Distribution runs through certified system integrators who bundle installation, software configuration, and post-commissioning support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American warehouse automation sits in early-cycle expansion, with Mexico nearshoring operations creating greenfield demand that outpaces retrofit saturation in mature US distribution clusters.
For Market Incumbents: Insulate installed-base revenue by embedding proprietary warehouse management software deeper into customer operations, creating switching costs that counter emerging cloud-native competitors. Pursue backward integration into industrial-grade LiDAR calibration facilities to reduce exposure to sensor supply concentration. Anchor capacity additions in Nuevo León to capture automotive OEM automation demand before regional integrators consolidate relationships. For New Entrants and Emerging Players: Establish a beachhead in Vertical Lift Module retrofits for ceiling-constrained spare-parts operations below traditional AS/RS thresholds, where incumbent coverage remains thin. Target mid-market 3PLs in Texas and California markets where automation procurement is unbundling from long-term facility leases. Lead with AI-enabled predictive maintenance modules that differentiate against legacy PLC-dependent competitors. For Investors and Strategic Acquirers: Forklift-integrated robotics specialists with established European multinational relationships represent the most defensible acquisition archetype, offering immediate access to North American facilities operated by global manufacturers. Long-term viability hinges on software-hardware integration depth rather than manufacturing scale alone. Monitor OSHA regional enforcement posture on collaborative robot speed envelopes as the signal for whether safety documentation investments translate into sustainable competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| AI Safety Documentation Investment | First-mover advantage emerges where federal autonomous equipment tort standards remain undefined. |
| Mexico Manufacturing Footprint Expansion | Nuevo León and Bajío Region greenfield sites capture automotive OEM automation demand. |
| Digital Twin Platform Integration | Cloud-based simulation environments compress commissioning timelines for e-commerce operators. |
| CSA/OSHA Dual-Certification Program | Cross-border compliance streamlines procurement for Ontario and Quebec pharmaceutical networks. |
| Vertical Lift Module Product Line Launch | Modular retrofit solutions address spare-parts operations with sub-forty-foot ceiling constraints. |
Research Methodology
A standing panel of warehouse operations directors, system integrator project managers, OEM procurement leads, and 3PL automation strategists provided ongoing calibration across primary fieldwork. Secondary validation drew from OSHA enforcement bulletins, ANSI/RIA standards documentation, CSA Group certification registries, and customs trade data on automation hardware imports. Bottom-up equipment shipment analysis triangulated against top-down facility automation spend estimates from industrial real estate leasing disclosures.
Scenario-bracketing across steel price volatility bands, nearshoring acceleration rates, and regulatory enforcement intensity levels framed projections across the analysis window. Segmentation modeling incorporated product type, end-use vertical, technology stack depth, and application stage dimensions. CAGRs derived from equipment replacement cycles, greenfield facility completions, and retrofit penetration curves in ceiling-constrained operations.
Stress conditions across LiDAR sensor supply disruptions, CSA/OSHA regulatory divergence, and Mexico labor code evolution were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on e-commerce fulfillment velocity and automotive OEM reshoring momentum. Material shifts in federal AI liability framework adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Global Digital Storage Devices Market
Data Storage
Flash Memory Market
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
Americas Flash Memory Market
Data Storage
Europe Flash Memory Market
Data Storage
Next Generation Data Storage Market
Data Storage
Enterprise Flash Storage Market
Data Storage
USB Key Market
Data Storage
Optical Disk Market
Data Storage
Substrates for Magnetic Disks Market
Data Storage
USB 3.1 Flash Drive Market
Data Storage
SSD Controller Market
Data Storage
Serial EEPROM Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
Electrochromic Storage Devices Market