
 Ready Meal Trays Market | 2026-2036
Ready Meal Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Ready Meal Trays Market Analysis
Supermarket private-label supply chains is reshaping how ready meal trays move from converter to shelf. Amcor plc leverages its integrated film-to-tray operations across European retail networks. Huhtamaki sustains broad geographic coverage through regional thermoforming hubs. DS Smith Plc anchors its position in fiber-based alternatives, competing directly against incumbent plastic formats.
Ready meal trays are rigid or semi-rigid containers, typically thermoformed from CPET, APET, polypropylene, or aluminum, designed to withstand oven or microwave thermal cycles while preserving food integrity through distribution. Plastic segments still dominate unit volumes but face structural pressure from biodegradable and fiber-based alternatives where margin pools are migrating. Aluminum trays lead in premium chilled and frozen ready meals due to superior heat conductivity and recyclability credentials. Cardboard formats are capturing fastest growth in airline and healthcare catering where lightweight disposal regulations tighten.
The EU Single-Use Plastics Directive and REACH frameworks govern material migration limits and recyclability claims across European markets. EFSA standards on food contact materials determine which substrates qualify for heated ready meal applications. Stakeholders must monitor how ECHA substance restrictions and national extended producer responsibility schemes alter substrate economics before committing to capacity expansion.
Market Dynamics
Supermarket private-label supply chains are reshaping how ready meal trays move from converter to shelf, with the EU Single-Use Plastics Directive forcing rapid substrate transitions across European retail networks.
Growth Catalysts
- Regulatory Phase-Out Mandates:The EU Single-Use Plastics Directive accelerates replacement demand for conventional plastic formats, creating captive markets for fiber-based and aluminum alternatives in Germany, France, and the United Kingdom.
- Private-Label Expansion:Supermarket chains are consolidating tray procurement under direct converter relationships, bypassing traditional distributor tiers and expanding unit volumes across European retail networks.
- Aluminum Conductivity Advantages:Premium chilled and frozen ready meals favor aluminum substrates for superior oven heat distribution and established recyclability credentials with European consumers.
Market Restraints
- Petrochemical Input Volatility:CPET and APET resin prices fluctuate with crude oil derivatives, compressing margins for thermoformed plastic tray converters locked into annual retail contracts.
- Fiber-Based Performance Ceiling:Current molded fiber technologies face moisture-barrier limitations in high-fat ready meal applications, restricting penetration into sauced entrée categories.
- Extended Producer Responsibility Schemes:National EPR frameworks in France and Italy impose per-unit fees that alter substrate economics unpredictably before capacity commitments.
Strategic Opportunities
- Healthcare Catering White Space:Hospital and long-term care facilities in the United Kingdom are transitioning from reusable to single-serve formats, opening volume for lightweight fiber-based trays compliant with NHS disposal protocols.
- Dual-Ovenable Material Convergence:Combining CPET structural layers with aluminum foil lamination enables microwave-to-oven performance without substrate switching, capturing premium ready meal positioning.
- Airline Service Ware Innovation:Post-pandemic cabin service restoration in Germany and France drives demand for ultra-lightweight fiber trays meeting IATA weight-reduction targets and burn-rate regulations.
Industry Challenges
- EFSA Migration Testing Timelines:Novel barrier coatings for fiber-based trays require 18-24 month EFSA food contact material approvals, delaying product launches behind competitor plastic conversions.
- Thermoforming Tooling Capex Burden:Multi-cavity aluminum mold sets for high-speed CPET production demand seven-figure capital commitments with five-year payback horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready Meal Trays Market |
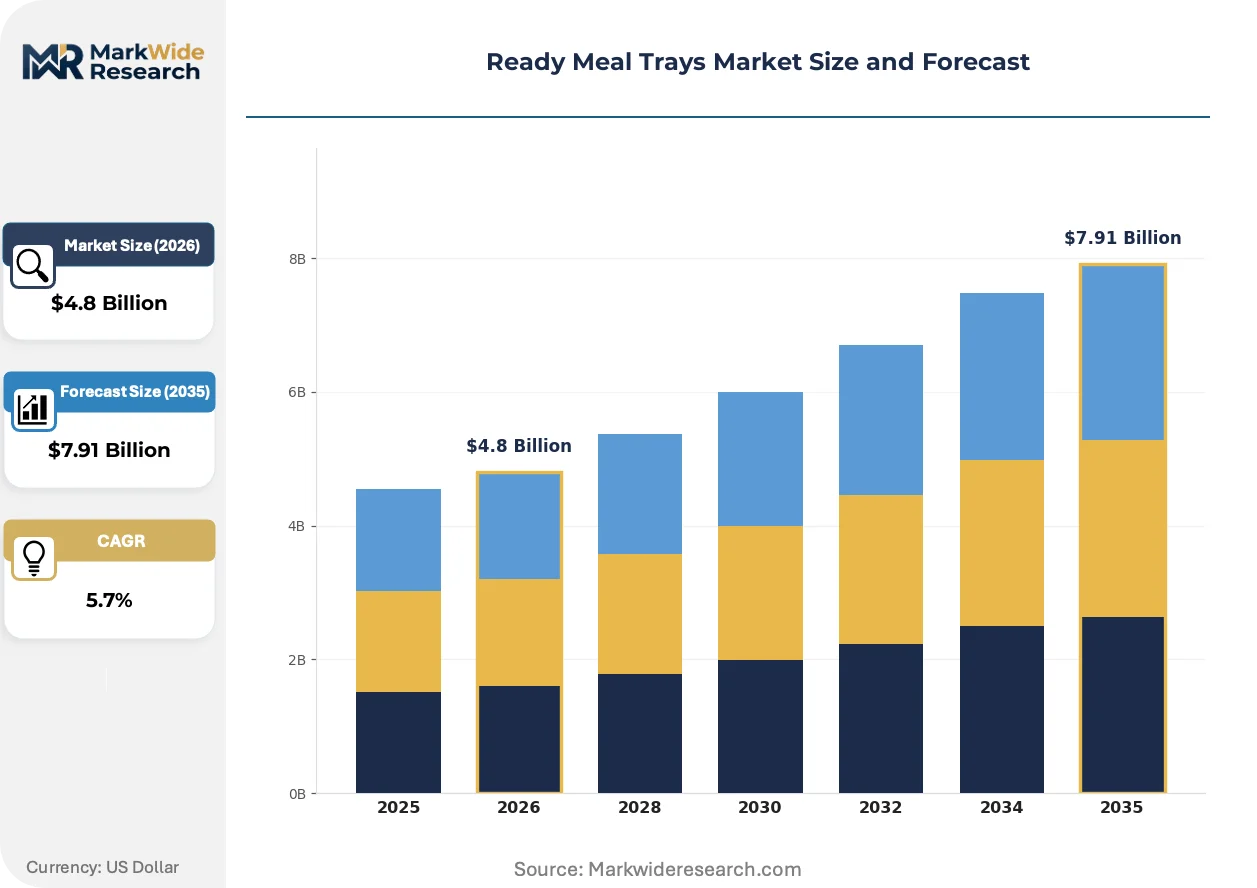
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Aluminum, Cardboard, Biodegradable Size: Small, Medium, Large, Extra Large End User: Retail Chains, Restaurants, Food Service Providers, Hospitals Distribution Channel: Online, Offline, Supermarkets, Wholesalers |
| Companies Covered | Silver Plastics GmbH & Co. KG, MCP Performance Plastic Ltd, Sonoco Products Company, DS Smith Plc, Versatile Packaging, Amcor plc, Faerch A/S, Huhtamaki, Quinn Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready Meal Trays Market Emerging Trajectories
Material science advances and regulatory compliance pressures are converging to redefine substrate selection criteria across European ready meal packaging value chains.
Barrier-coated molded fiber technology is migrating from niche airline applications toward mainstream retail ready meals. German converters are piloting aqueous-based grease barriers in chilled pasta segments. This migration from plastic dependency is compressing the premium pricing gap between sustainable and conventional formats.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistries from European fiber tray production. ECHA's 2023 PFAS restriction proposal forces coating reformulation across Spanish and Italian converter facilities. Chilled ready meal categories with high fat content face the steepest compliance timelines and substitution costs.
Retail procurement consolidation favors direct converter relationships over distributor-mediated supply. British supermarket chains are mandating tray-to-film compatibility certification from single-source suppliers. France and the Netherlands exhibit the most advanced vertical coordination between retailer technical teams and thermoforming operations.
Ready Meal Trays Market Segmentation
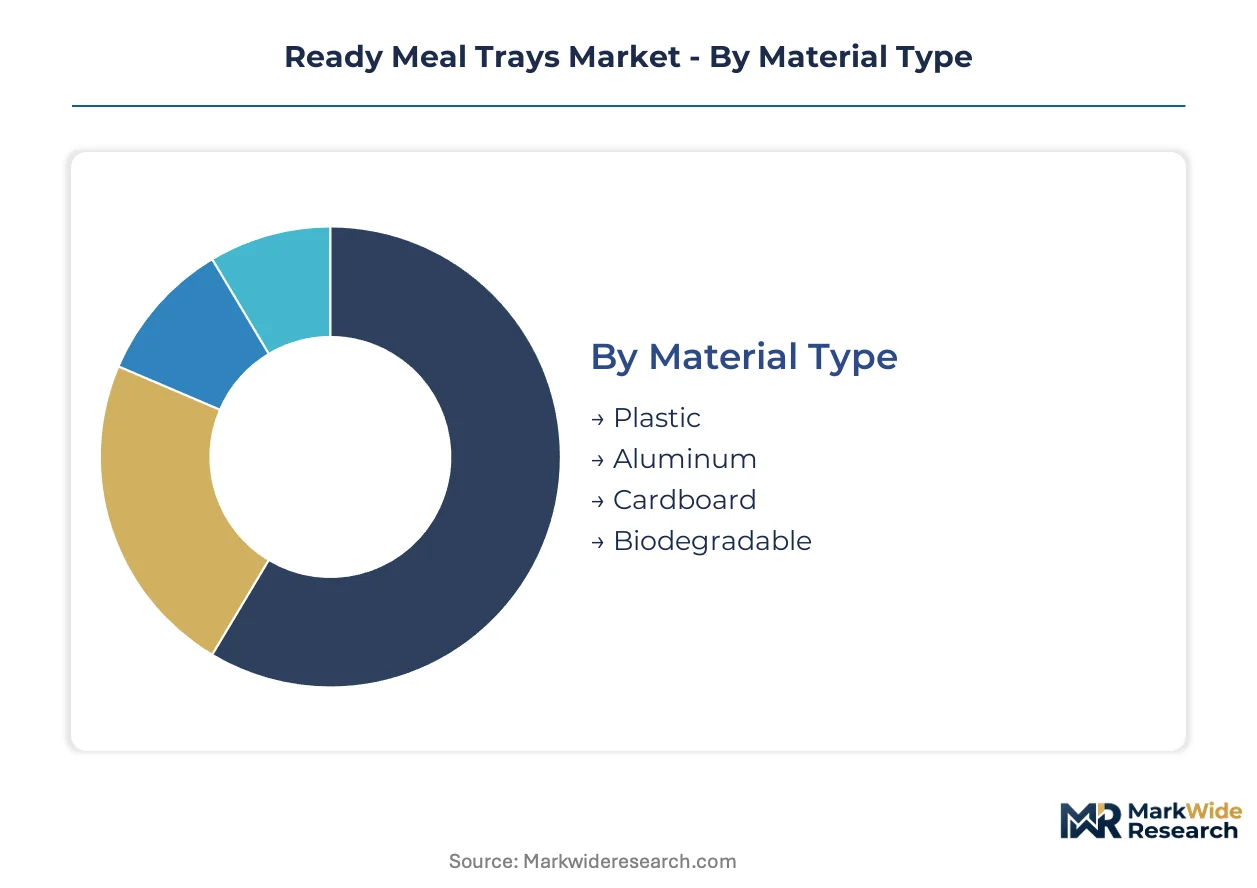
Material specifications and end-use thermal requirements create distinct procurement patterns across ready meal tray categories. Retail chains demand dual-ovenable performance while healthcare facilities prioritize lightweight disposal compliance.
Material Type:
After-sales service intensity varies sharply by substrate complexity, with plastic formats requiring technical support for sealing compatibility and aluminum demanding recycling infrastructure partnerships.
- Plastic:CPET and APET thermoformed substrates dominate unit volumes through established converter networks. Germany, France, and the United Kingdom concentrate replacement demand as EFSA migration limits tighten and retailers phase out conventional formats under EU Single-Use Plastics Directive timelines.
- Aluminum:Rolled foil and pressed tray formats deliver superior heat conductivity for premium chilled and frozen applications. Demand clusters in upscale retail segments across British and French markets where recyclability credentials command shelf positioning advantages.
- Cardboard:Fiber-based structures with barrier coatings serve airline and healthcare catering where weight restrictions dominate procurement criteria.
- Biodegradable:PLA and starch-based alternatives target sustainability-mandated contracts in Dutch and Scandinavian retail networks.
Plastic holds the largest share; momentum sits with aluminum as EPR schemes alter substrate economics.
Size:
Cost tier differentiation separates premium positioning from economy formats, with portion control specifications varying by end-use channel.
- Small:Single-serve dimensions align with healthcare and airline catering protocols requiring precise calorie portioning and reduced food waste metrics.
- Medium:Standard retail portions for individual consumption dominate supermarket private-label procurement across European chains.
- Large:Family-format dimensions serve multi-person households in French and German frozen meal categories.
- Extra Large:Catering-scale formats support institutional food service providers with bulk preparation requirements.
Medium captures the highest volume throughput; expansion concentrates in small formats for healthcare conversion.
End User:
Application requirements dictate barrier specifications and thermal performance thresholds across customer categories.
- Retail Chains:Supermarket private-label supply chains demand tray-to-film compatibility certification and direct converter relationships. British and French retailers are consolidating procurement under single-source technical partnerships.
- Restaurants:Takeaway and delivery formats require stackable designs with grease-resistant properties for hot food transport.
- Food Service Providers:Institutional catering contracts specify volume pricing with standardized dimensions for automated filling lines.
- Hospitals:NHS facilities in the United Kingdom are transitioning from reusable to single-serve formats, opening volume for lightweight fiber-based trays compliant with disposal protocols.
Retail chains anchor procurement volume; hospitals present the steepest expansion trajectory.
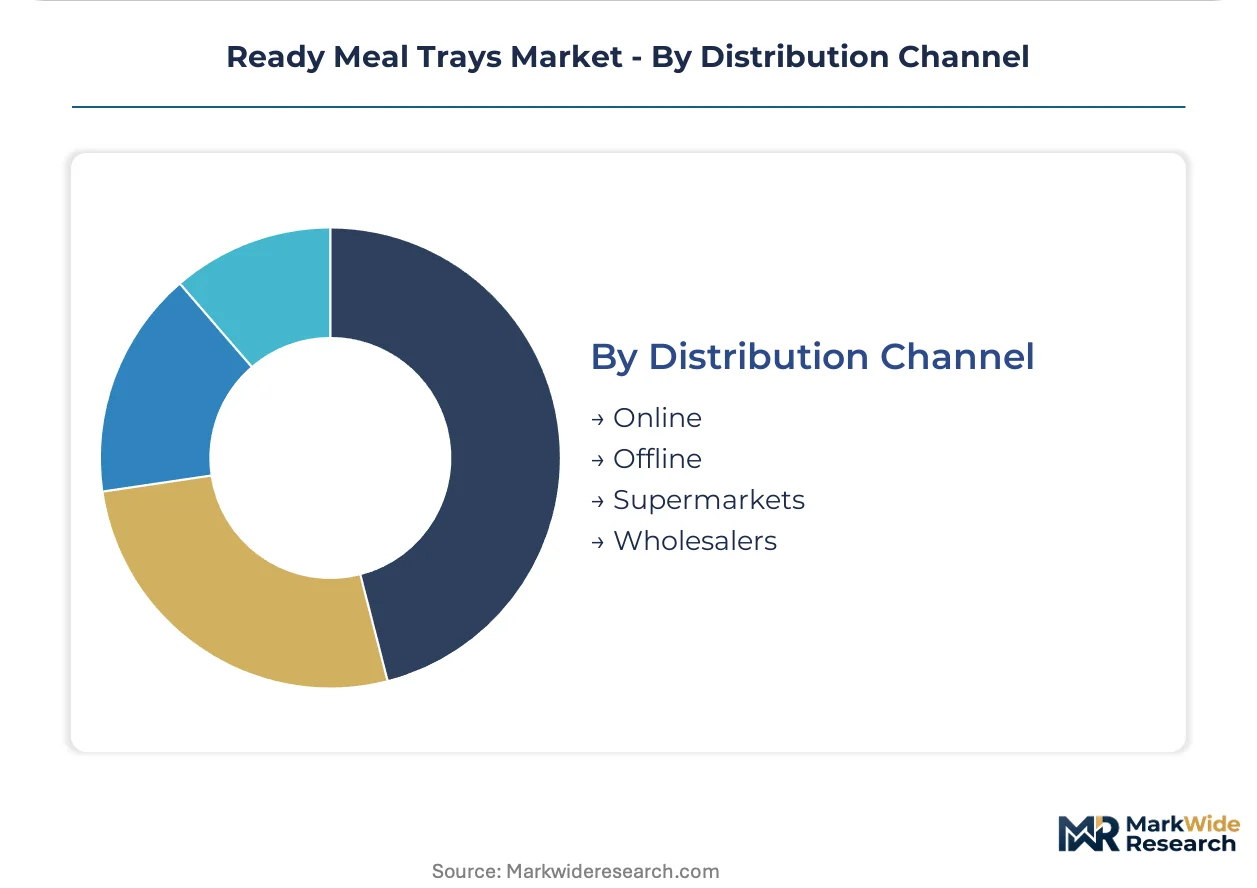
Distribution Channel:
Supply concentration patterns differ between direct retail integration and intermediary-mediated flows.
- Online:E-commerce procurement platforms serve small-format food service operators with fragmented order patterns.
- Offline:Traditional distributor networks retain relevance in southern European markets with less consolidated retail structures.
- Supermarkets:Direct converter relationships bypass distributor tiers, expanding unit volumes through centralized technical specification.
- Wholesalers:Cash-and-carry formats support independent restaurants and catering operations with immediate availability requirements.
Supermarkets command the dominant channel position; online is gaining share fastest in specialist catering segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command pricing premiums against southern European competitors through EFSA-certified dual-ovenable capacity. British retailers extract supply chain concessions via consolidated private-label procurement. French EPR schemes redistribute substrate economics toward aluminum formats.
Germany
Supermarket private-label consolidation and aluminum tray demand from premium frozen meals drive converter volumes. ECHA's PFAS restriction proposal forces aqueous barrier coating reformulation across Bavarian thermoforming clusters. The Rhine-Ruhr industrial corridor hosts integrated film-to-tray operations serving Aldi and Lidl centralized procurement.
France
EPR per-unit fees on plastic formats accelerate fiber-based substitution in chilled ready meals. ANSM food contact material oversight extends EFSA migration testing timelines for novel barrier coatings. The Lyon-Auvergne-Rhône-Alpes region concentrates molded fiber pilot production for sauced entrée categories.
United Kingdom
NHS single-serve format conversion opens volume for lightweight fiber trays in hospital catering. Extended producer responsibility schemes alter substrate economics unpredictably ahead of capacity commitments. The Midlands packaging belt anchors DS Smith fiber-based operations supplying Tesco and Sainsbury's technical partnerships.
Italy
Southern European retail fragmentation sustains distributor-mediated supply against northern direct-converter trends. REACH substance restrictions on legacy grease-resistant chemistries compress compliance timelines for high-fat ready meals. Emilia-Romagna thermoforming facilities serve Barilla and Nestlé Italia frozen pasta segments.
Netherlands
Scandinavian sustainability mandates filter through Dutch converter networks supplying PLA and starch-based alternatives. EFSA standards on food contact materials determine qualification for heated applications across Albert Heijn private-label ranges. The Randstad logistics hub enables just-in-time tray delivery to Rotterdam port-based food exporters.
Ready Meal Trays Market Vendor Landscape
Integrated packaging conglomerates and regional thermoforming specialists split the market along vertical coordination lines. Three archetypes dominate: multinational film-to-tray integrators with retailer direct relationships, fiber-based substrate pioneers competing against incumbent plastic formats, and aluminum-focused metal converters serving premium chilled segments. Competitive moves concentrate on backward integration into resin and pulp supply, plus geographic hub expansion to compress logistics costs.
Within the integrated conglomerate tier, Amcor plc and Huhtamaki exemplify divergent geographic strategies. Amcor leverages European retail network density through centralized technical specification teams. Huhtamaki sustains broad coverage via distributed regional thermoforming hubs. DS Smith Plc occupies a distinct position in fiber-based alternatives, competing directly against plastic incumbents as EPR schemes alter substrate economics. Silver Plastics GmbH & Co. KG anchors German private-label supply through EFSA-certified capacity.
| Leading Market Players |
|---|
| Silver Plastics GmbH & Co. KG |
| MCP Performance Plastic Ltd |
| Sonoco Products Company |
| DS Smith Plc |
| Versatile Packaging |
| Amcor plc |
| Faerch A/S |
| Huhtamaki |
| Quinn Packaging |
| Others |
Supply Flow & Price Mechanics
The Rhine-Ruhr industrial corridor anchors European thermoforming capacity, where EFSA-certified dual-ovenable production lines command premium positioning against southern European competitors. Converter concentration in this German cluster translates directly into pricing power over supermarket private-label procurement teams.
Pricing Analysis
Configured-to-order pricing for dual-ovenable CPET-aluminum laminations runs 40-60 percent above standard APET commodity trays. Three-tier pricing structure across premium, standard, and economy levels stratifies by EFSA migration certification and oven-to-microwave performance ratings. Cost compression in economy plastic tiers intensifies because petrochemical input volatility compresses margins for converters locked into annual retail contracts. Healthcare and airline catering buyers exhibit the highest price sensitivity due to disposal protocol compliance requirements, while premium chilled retail segments absorb aluminum premiums for recyclability credentials.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates raw material cost uncertainty for barrier-coated molded fiber inputs. Thermoforming capacity concentrates in Germany, France, and Italy, with resin supply drawing from Belgian and Dutch petrochemical hubs. Pulp feedstock for fiber-based alternatives hinges on Nordic and Baltic sources, creating single-source vulnerability during ECHA PFAS restriction transitions. Distribution runs through centralized retail technical partnerships in northern Europe, while southern markets retain fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier coating technical service contracts are expanding faster than tray hardware sales as EFSA approval timelines extend and coating reformulation cycles accelerate. Recurring revenue from migration testing support and retailer certification maintenance now anchors converter profitability.
For Market Incumbents: Build EFSA-certified dual-ovenable capacity moats in the Rhine-Ruhr and Midlands corridors to defend against aluminum substitution pressure. Backward integration into aqueous barrier coating chemistry reduces exposure to REACH substance restrictions on legacy PFAS formulations. Channel control through direct retailer technical partnerships locks out southern European distributor-dependent competitors. For New Entrants and Emerging Players: NHS hospital catering conversion in the United Kingdom represents the most penetrable entry point for lightweight fiber-based tray volumes. Mid-market airline service restoration across German and French carriers offers second-mover advantage in IATA-compliant ultra-lightweight formats. Partner with Nordic pulp suppliers for virgin fiber sourcing credibility against incumbent recycled-content positioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among coating technology specialists with EFSA approval track records and retailer technical service mandates. Long-term viability over the next decade favors substrate-agnostic converters with dual plastic-fiber competency as EPR schemes redistribute economics. Watch for ECHA PFAS restriction enforcement dates as inflection indicators for coating substitution demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA-Certified Dual-Ovenable Capacity Expansion | Captures premium positioning as Aldi and Lidl consolidate procurement under single-source technical partnerships. |
| Aqueous Barrier Coating Reformulation | Ensures compliance with ECHA PFAS restrictions across French and Spanish converter facilities. |
| NHS Hospital Catering Supply Agreements | Locks in volume for lightweight fiber trays as United Kingdom facilities transition from reusable formats. |
| Nordic Pulp Supply Partnerships | Secures virgin fiber sourcing for airline applications where burn-rate regulations tighten disposal protocols. |
| Retailer Technical Service Integration | Deepens direct converter relationships bypassing traditional distributor tiers in British and Dutch markets. |
Methodological Framework
A spread of perspectives from thermoforming plant managers, supermarket private-label procurement directors, EFSA regulatory consultants, and airline catering operations chiefs converged on the working assumptions for substrate transition timelines. Primary fieldwork combined structured interviews across German, French, and British converter clusters with secondary validation from ECHA restriction proposals, EFSA food contact material opinions, and national extended producer responsibility scheme filings. Bottom-up tray volume estimates from individual facility outputs triangulated against top-down retail procurement consolidation trends.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material substrate, thermal performance tier, end-use application, and geographic regulatory cluster. CAGRs derived from substrate-specific volume trajectories weighted by EPR fee impacts and retailer phase-out commitments. Forecast inputs incorporated EFSA migration testing pipeline durations and airline fleet restoration schedules.
Practitioners should monitor ECHA PFAS restriction enforcement dates and national EPR fee announcements for early signals of substrate economics shifts. Forecasts reflect assumptions about regulatory timeline adherence and retailer procurement consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Sausage Casing Market
Packaged Foods
Japan Packaged Food Products Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Cocoa Fillings Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
India Instant Noodles Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
North America Packaged Salad Market
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Fruit Filling Market