
 Industrial Drum Market | 2026-2036
Industrial Drum Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Drum Market Analysis
Direct-to-manufacturer supply contracts is reshaping how industrial drums reach end users across North America and Europe. Greif, Inc. leverages its integrated steel and fiber drum production network to control lead times for chemical sector buyers. Mauser Packaging Solutions sustains geographic dominance through its reconditioning and recycling infrastructure across multiple continents. SCHUTZ GmbH & Co. KGaA specializes in intermediate bulk containers and steel drums, anchoring its position in European hazardous goods logistics.
An industrial drum is a cylindrical shipping container fabricated from steel, plastic, fiber, or composite materials, typically featuring rolled rims, welded seams, and closure fittings engineered to meet UN performance standards for liquid and solid hazardous goods transport. Steel drums dominate volume in chemical and oil & gas applications where thermal tolerance and crush strength prove critical. Plastic drums are capturing share in food & beverage and pharmaceutical end uses where moisture resistance and reduced tare weight lower inbound freight costs. The 55-gallon capacity segment occupies the core of the market, reflecting its alignment with standard pallet footprints and regulatory filling limits across maritime and over-the-road modes.
EPA regulations in the United States mandate specific thickness, coating, and closure standards for drums carrying hazardous wastes, while REACH and the F-Gas Regulation in Europe impose material traceability and substance restriction requirements on drum manufacturers serving chemical exporters. FDA compliance for food-contact drums and UN certification for dangerous goods transport create layered compliance thresholds that filter market access. Stakeholders must monitor evolving extended producer responsibility frameworks and circular economy mandates that will determine whether reconditioning investments or virgin material production delivers stronger returns.
Market Dynamics
Direct-to-manufacturer contracting is collapsing traditional distributor layers in the industrial drum supply chain, concentrating procurement power with chemical majors and compressing margin pools for intermediaries.
Growth Catalysts
- EPA hazardous waste containment mandates:Chemical manufacturers in the United States are expanding drum procurement to meet stricter thickness, coating, and closure standards for hazardous material transport.
- Steel drum thermal tolerance advantages:Oil and gas applications favor steel drums where crush strength and thermal performance prove critical for upstream chemical containment.
- Germany:Rising industrial chemical output is concentrating steel drum demand in German manufacturing clusters serving export-oriented producers.
Market Restraints
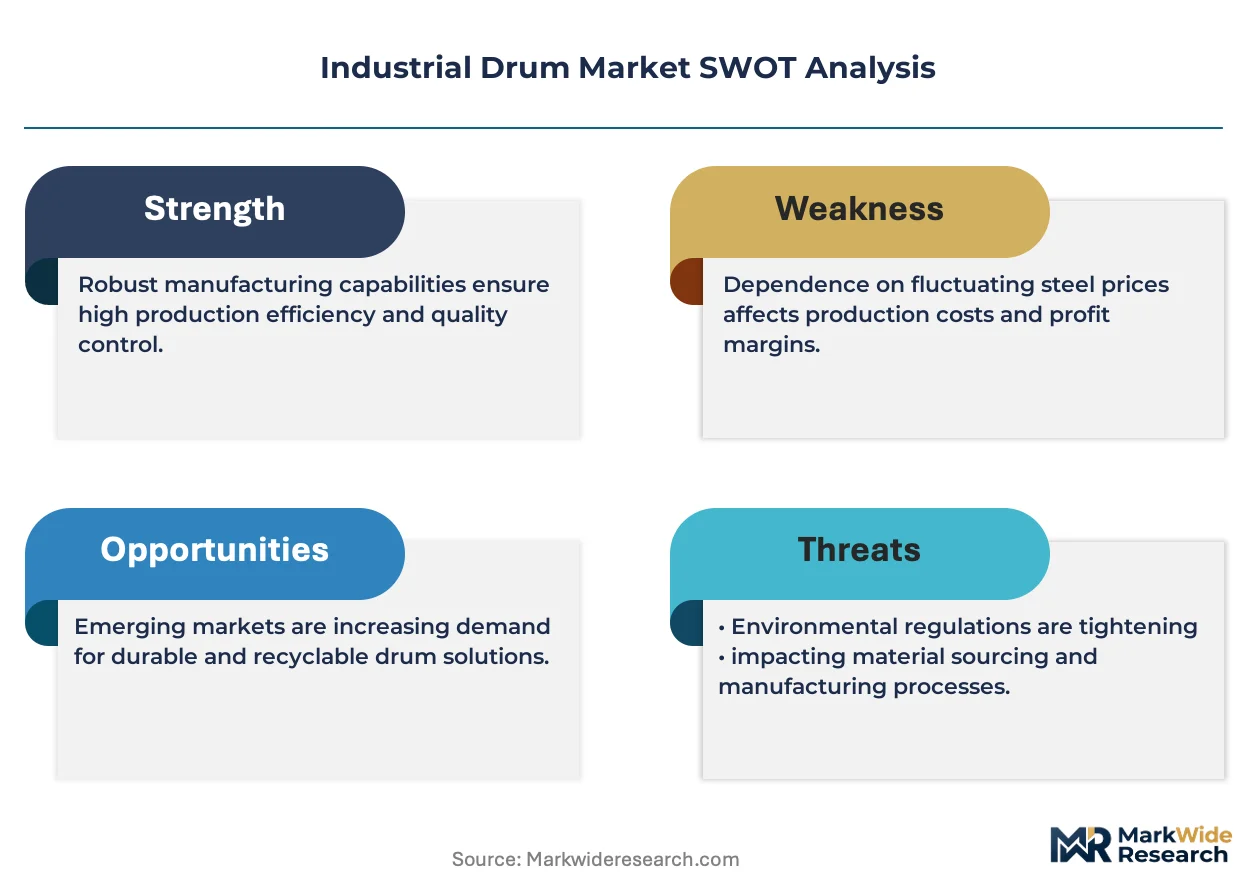
- Steel sheet volatility:Raw material input costs for steel drum fabrication fluctuate with global metallurgical commodity indices, squeezing fabricator margins.
- REACH substance traceability:European chemical exporters face layered compliance documentation requirements that increase drum procurement friction and extend qualification timelines.
- Intermediate bulk containers:IBCs are capturing liquid chemical volumes above 200 liters, displacing multiple-drum configurations in bulk chemical logistics.
Strategic Opportunities
- Extended producer responsibility frameworks:Circular economy mandates in the European Union are creating reconditioning investment incentives that favor operators with integrated recycling infrastructure.
- Food-contact certification:FDA-compliant plastic drums are penetrating pharmaceutical and food and beverage end uses where moisture resistance and reduced tare weight lower inbound freight costs.
- Reconditioning networks:Geographic expansion of drum reconditioning facilities offers margin recovery from virgin material production in mature industrial markets.
Industry Challenges
- UN certification timelines:Dangerous goods transport approval processes for new drum designs extend product launch cycles and delay revenue recognition.
- Coating formulation expertise:Specialized chemical resistance engineering for drum linings requires scarce polymer chemistry talent that concentrates with incumbent suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Drum Market |
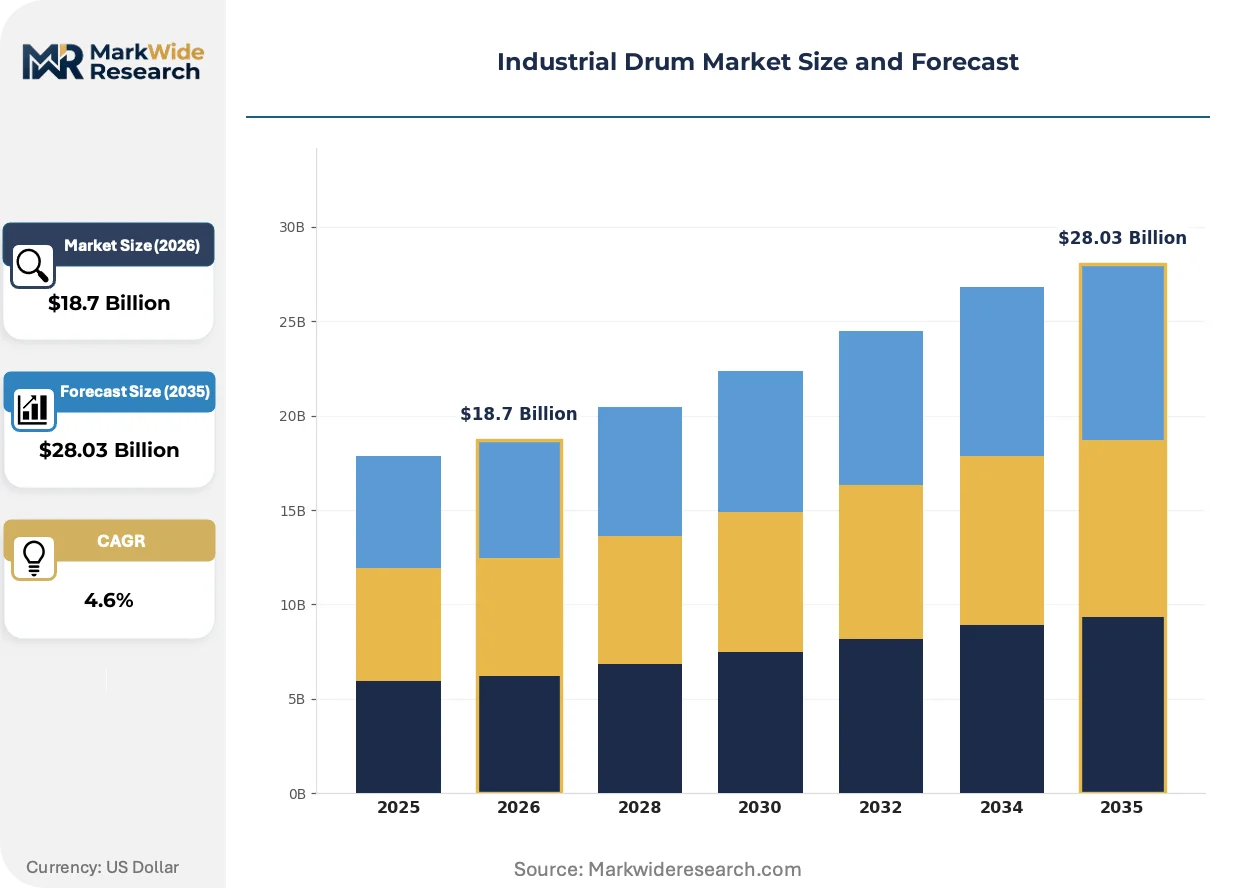
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Drum, Plastic Drum, Fiber Drum, Composite Drum End User: Chemicals, Food & Beverage, Pharmaceuticals, Oil & Gas Capacity: 30 Gallons, 55 Gallons, 100 Gallons, Others Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Greif, Inc., Mauser Packaging Solutions, SCHUTZ GmbH & Co. KGaA, Time Technoplast Ltd., Balmer Lawrie & Co. Ltd., Sicagen India Ltd., CL Smith, Snyder Industries, Inc., North Coast Container LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Drum Market Emerging Trajectories
Material science advances and regulatory stringency are compressing traditional drum specifications while opening premium niches for certified containment solutions.
Lightweight composite drum construction is collapsing the weight-based freight cost advantage of conventional steel drums in non-hazardous liquid transport. Food and beverage distributors are adopting fiber-reinforced plastic drums for edible oils and syrups. This technology is collapsing the total landed cost gap between steel and plastic alternatives for domestic distribution networks.
REACH and the F-Gas Regulation are imposing substance restriction requirements on drum manufacturers serving European chemical exporters. Material traceability documentation now extends through the coating supply chain to base resin sources. German drum fabricators are responding by qualifying domestic steel suppliers and consolidating coating vendor relationships to reduce compliance audit burden.
Long-term direct supply agreements are replacing spot procurement for chemical sector drum buyers. Distributor inventory positions are being displaced by vendor-managed stock programs at major chemical plant sites. This pattern is most visible in United States Gulf Coast petrochemical clusters where integrated producers demand synchronized drum delivery with batch production schedules.
Industrial Drum Market Segmentation
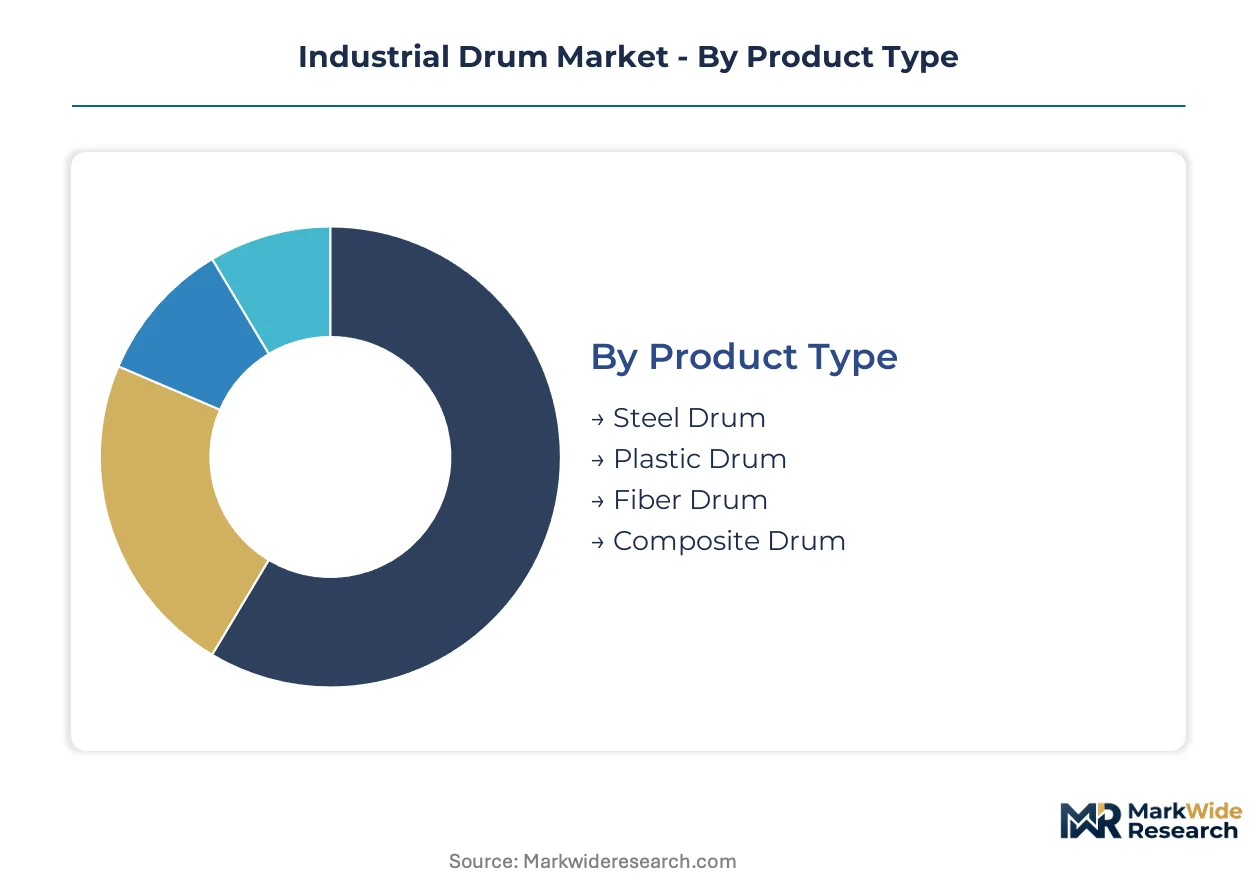
Industrial drum procurement patterns diverge sharply across material specifications, end-use hazards, and fulfillment models. Each segmentation axis carries distinct margin structures and compliance thresholds that reshape supplier positioning.
Product Type:
The use-case spectrum spans thermal extremes, chemical aggression, and weight-sensitive logistics networks.
- Steel Drum:Fabricated from cold-rolled carbon steel with welded seams and rolled rims engineered for UN-certified hazardous goods containment. Demand concentrates in German chemical manufacturing clusters where REACH substance traceability requirements favor domestically sourced steel with full coating documentation.
- Plastic Drum:High-density polyethylene or polypropylene construction delivers moisture resistance and reduced tare weight for food-contact and pharmaceutical applications. FDA-compliant grades are penetrating edible oil and syrup distribution networks where inbound freight cost reduction drives specification shifts.
- Fiber Drum:Kraft fiberboard with resin-impregnated walls serves dry solid and semi-liquid containment where crush strength requirements moderate.
- Composite Drum:Fiber-reinforced plastic laminates collapse the weight-cost gap for non-hazardous liquid transport in domestic distribution.
Established volume favors steel construction; emerging adoption favors plastic alternatives in food-contact and pharmaceutical channels.
End User:
Regulatory intensity and containment specifications create four distinct procurement tiers with diverging qualification timelines.
- Chemicals:EPA hazardous waste mandates in the United States mandate specific thickness, coating, and closure standards that extend drum qualification cycles. German chemical exporters face layered REACH documentation requirements that increase procurement friction.
- Oil & Gas:Upstream chemical containment favors steel drum thermal tolerance and crush strength for remote extraction sites.
- Food & Beverage:FDA compliance for food-contact surfaces drives plastic drum penetration where moisture resistance and reduced tare weight lower landed costs.
- Pharmaceuticals:Stringent material traceability and cleaning validation requirements concentrate procurement with certified suppliers.
Regulatory burden concentrates procurement power with chemical sector buyers; margin expansion favors pharmaceutical and food-contact certification holders.
Capacity:
Standardization against pallet footprints and modal constraints shapes volume distribution across capacity tiers.
- 55 Gallons:The cylindrical geometry aligns with standard pallet dimensions and maritime container optimization. This capacity dominates chemical and oil & gas logistics where regulatory filling limits and handling equipment standardization lock in procurement patterns.
- 30 Gallons:Reduced capacity serves specialty chemical batches and pharmaceutical intermediates where smaller production runs require flexible containment.
- 100 Gallons:Larger format competes with intermediate bulk container displacement in bulk liquid chemical logistics.
- Others:Non-standard capacities address niche applications including laboratory reagents and custom-blended industrial formulations.
Standardization economics favor 55-gallon formats; customization premiums sustain smaller capacity tiers in specialty chemical and pharmaceutical segments.
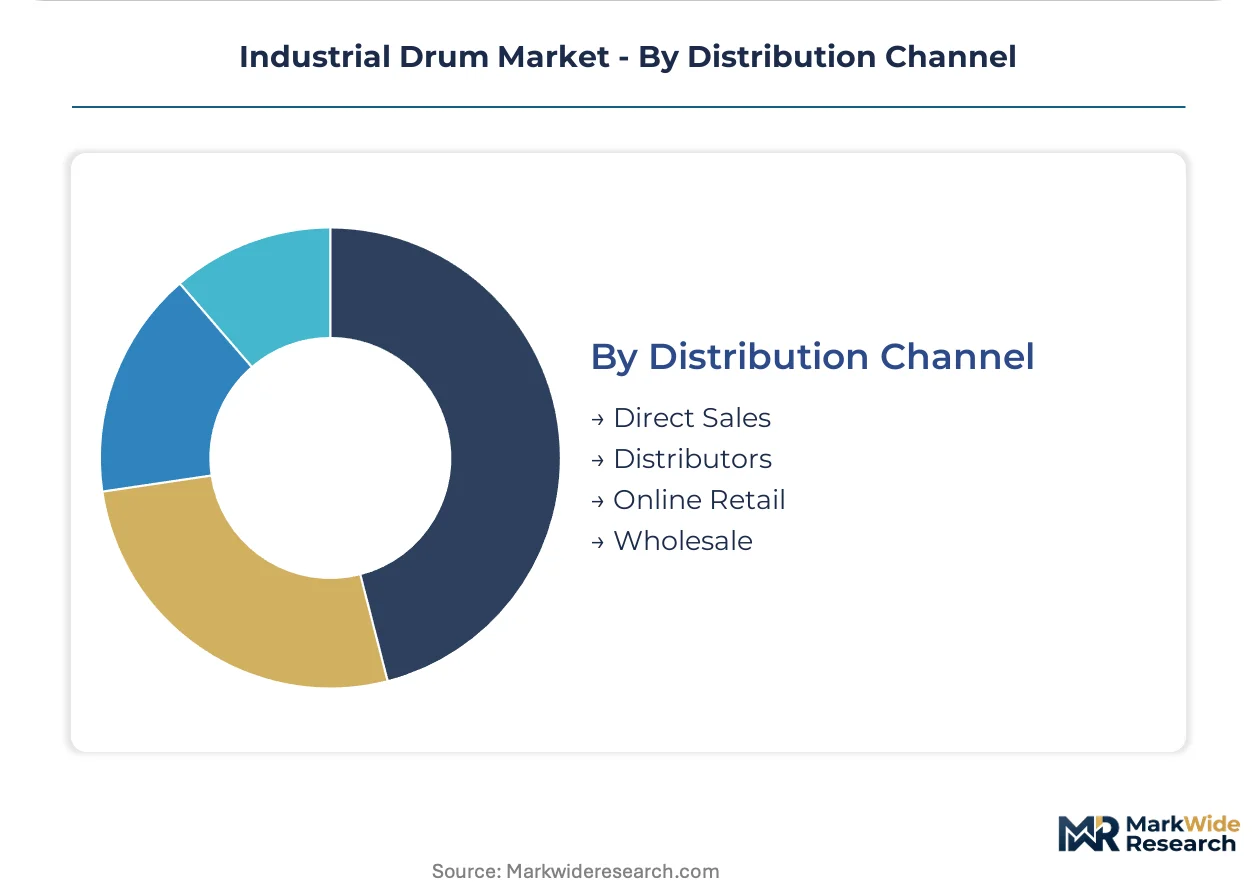
Distribution Channel:
Supply chain compression is collapsing traditional intermediary layers in favor of direct manufacturer relationships.
- Direct Sales:Long-term supply agreements with vendor-managed inventory programs are displacing spot procurement at United States Gulf Coast petrochemical clusters. Synchronized drum delivery with batch production schedules locks in supplier relationships.
- Distributors:Traditional inventory positions face margin compression as direct contracting concentrates procurement power with chemical majors.
- Wholesale:Bulk aggregation serves smaller chemical processors and regional food & beverage bottlers without scale for direct manufacturer negotiations.
- Online Retail:Digital procurement platforms are penetrating maintenance-repair-operations segments and smaller volume buyers.
Channel power is consolidating toward direct sales; wholesale and online channels capture fragmented demand below contract scale thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA mandates in the United States anchor the dominant geography, with chemical manufacturers expanding drum procurement for hazardous waste containment. German industrial chemical output concentrates steel drum demand in European manufacturing clusters. Asian chemical production growth and Middle Eastern petrochemical expansion reshape procurement patterns across three additional markets.
United States
Gulf Coast petrochemical clusters drive synchronized drum delivery programs with batch production schedules. EPA hazardous waste containment mandates enforce specific thickness, coating, and closure standards that extend qualification cycles. Houston and Port Arthur chemical corridors concentrate procurement power with integrated producers demanding vendor-managed inventory.
Germany
REACH substance traceability requirements favor domestically sourced steel with full coating documentation. The F-Gas Regulation imposes material restriction requirements on drum manufacturers serving chemical exporters. Ludwigshafen and Leverkusen chemical manufacturing clusters anchor demand for certified containment solutions with domestic supplier consolidation.
China
Industrial chemical output expansion drives drum procurement for hazardous goods logistics across coastal manufacturing zones. GB standards and MEE environmental compliance frameworks shape material specifications and coating formulations. Yangtze River Delta petrochemical corridors concentrate demand for thermal-tolerant steel drum configurations in bulk chemical transport.
India
Specialty chemical manufacturing growth accelerates drum adoption for export-oriented hazardous goods containment. BIS certification requirements and DGFT export documentation standards filter market access for domestic and international suppliers. Gujarat and Maharashtra chemical clusters drive procurement concentration with integrated producers qualifying certified drum fabricators.
Saudi Arabia
Petrochemical downstream expansion creates drum demand for intermediate chemical transport and hazardous material containment. SAMR technical regulations and dual carbon goals influence material selection and recycling infrastructure investment. Jubail and Yanbu industrial cities concentrate procurement with state-linked chemical producers demanding synchronized supply programs.
Industrial Drum Market Vendor Landscape
Integrated steel-fiber producers and reconditioning specialists split the market into distinct capability tiers. The vendor base concentrates around operators with captive recycling infrastructure and geographic density in chemical manufacturing corridors. Three archetypes dominate: vertically integrated metal-fiber fabricators, reconditioning-network operators, and regional plastic drum specialists. Competitive moves center on backward integration into steel sheet supply and geographic expansion of reconditioning facilities to capture circular economy incentives.
Within the integrated production tier, Greif, Inc. and Mauser Packaging Solutions exemplify scale-driven positioning through combined steel and fiber drum fabrication networks. SCHUTZ GmbH & Co. KGaA anchors the European hazardous goods logistics segment with intermediate bulk container and steel drum specialization. These three operators occupy positions that concentrate procurement relationships with chemical majors demanding synchronized delivery and full material traceability documentation.
| Leading Market Players |
|---|
| Greif, Inc. |
| Mauser Packaging Solutions |
| SCHUTZ GmbH & Co. KGaA |
| Time Technoplast Ltd. |
| Balmer Lawrie & Co. Ltd. |
| Sicagen India Ltd. |
| CL Smith |
| Snyder Industries, Inc. |
| North Coast Container LLC |
| Others |
Supply Flow & Price Mechanics
Jubail and Yanbu industrial cities concentrate Saudi petrochemical drum demand with state-linked chemical producers demanding synchronized supply programs, translating upstream steel sheet volatility into compressed fabricator margins across contract tiers. EPA hazardous waste containment mandates in the United States and REACH substance traceability in Europe create compliance-cost layering that separates certified premium suppliers from commodity-positioned competitors.
Pricing Analysis
North American-German price spreads reflect steel sheet input cost differentials and coating documentation burdens. Three-tier pricing structure across UN-certified premium, FDA food-contact standard, and economy non-hazardous grades separates procurement pools. Cost compression in economy steel drums is intensifying because distributor inventory positions face margin compression from direct manufacturer contracting. Chemical sector buyers exhibit lowest price sensitivity due to regulatory qualification lock-in; food and beverage distributors show highest sensitivity where tare weight drives freight economics.
Supply Chain Analysis
Extended payment terms from Gulf Coast petrochemical majors and supply-chain finance facilities from integrated producers anchor working capital structures for drum fabricators. Cold-rolled carbon steel capacity concentrates in China, Germany, and the United States; high-density polyethylene resin feeds from Saudi Arabia, South Korea, and the United States. Single-source vulnerability runs through specialized coating formulation suppliers with scarce polymer chemistry talent. Distribution runs through vendor-managed inventory programs at major chemical plant sites displacing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized chemical resistance engineering for drum linings requires scarce polymer chemistry talent that concentrates with incumbent suppliers, creating durable capability gaps that new entrants cannot bridge through capital alone. Coating formulation expertise and UN certification navigation represent the critical asset bottlenecks shaping competitive outcomes.
For Market Incumbents: Pre-empt reconditioning network expansion in European chemical corridors before circular economy mandates harden regulatory advantage. Lock in backward integration into domestic steel sheet supply to reduce REACH audit burden and defend margin position against raw material volatility. Capture coating vendor consolidation benefits through exclusive formulation partnerships that extend qualification timeline barriers for challengers. For New Entrants and Emerging Players: Establish a beachhead in FDA-compliant plastic drums for edible oil and syrup distribution networks where moisture resistance and reduced tare weight create specification-switching opportunities. Target pharmaceutical intermediates in India and Southeast Asia where BIS certification and material traceability requirements filter slower-moving incumbents. Lead with digital procurement platforms for maintenance-repair-operations segments below contract scale thresholds. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because extended producer responsibility frameworks and reconditioning investment incentives favor operators with integrated recycling networks over virgin material producers. Acquisition targets should display geographic density in chemical manufacturing corridors with captive steel-fiber fabrication and reconditioning capabilities. Monitor regulatory acceleration in EU circular economy mandates and EPA hazardous waste rulemakings as inflection signals for reconditioning asset valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Reconditioning Network Expansion | Captures circular economy incentives under EU extended producer responsibility frameworks ahead of regulatory hardening. |
| Backward Integration into Steel Sheet | Reduces REACH substance traceability audit burden for German chemical exporters demanding full coating documentation. |
| Coating Vendor Consolidation | Concentrates scarce polymer chemistry talent with incumbent suppliers to extend UN certification timeline barriers. |
| Vendor-Managed Inventory Programs | Locks in Gulf Coast petrochemical procurement relationships through synchronized drum delivery with batch schedules. |
| FDA Food-Contact Certification | Penetrates edible oil and syrup distribution networks where reduced tare weight drives inbound freight cost reduction. |
Methodological Framework
A standing panel of plant managers at chemical manufacturing facilities, procurement leads at downstream oil and gas operators, distribution channel partners in industrial packaging, and technical R&D directors in coating formulation provided ongoing calibration across the study. Primary interview intelligence combined with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from packaging manufacturers, and UN dangerous goods transport certification databases. Bottom-up drum volume modeling by material type and capacity tier triangulated against top-down chemical production output estimates.
Scenario-bracketing across steel sheet price volatility bands, regulatory acceleration timelines, and intermediate bulk container displacement rates bounded high-low forecast ranges. Segmentation dimensions modeled include material specification, end-use hazard class, capacity tier against pallet footprint standards, and fulfillment channel structure. CAGRs derived from production-weighted regression across petrochemical output forecasts and containment intensity ratios. Coating formulation innovation cycles and reconditioning facility capacity additions served as industry-specific forecast sensitivity inputs.
Stress conditions across metallurgical commodity indices, REACH documentation burden escalation, and IBC substitution thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation pace and chemical sector capital expenditure continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Powder Funnels Market
Industrial Materials
Tooling Board Market
Industrial Materials
Modified Wood Market
Industrial Materials
Industrial Silica Sand Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
Global Melamine Market
Industrial Materials
Diamond Wire Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Static Mixer Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Metal Based Safety Gratings Market