
 Flushing Systems Market | 2026-2036
Flushing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Flushing Systems Market Intelligence
EU Green Deal water-efficiency targets is hardening demand for low-flow flushing systems across European commercial construction. Geberit leverages its in-house ceramic and piping integration to sustain margin control across project tiers. TOTO Ltd. anchors premium positioning through sensor-integrated washlet-toilet hybrids in Japanese and export markets. Kohler competes on brand breadth, extending its portfolio from luxury hospitality to mid-market residential channels.
Flushing systems encompass the valve, tank, bowl, and actuation mechanisms engineered to evacuate waste through controlled water discharge, typically operating at 1.28 to 1.6 gallons per flush in regulated markets. These assemblies serve sanitation infrastructure across residential bathrooms, commercial restrooms, and institutional facilities where hygiene standards and water conservation mandates intersect. Gravity flush technology dominates installed volume due to mechanical simplicity and lower maintenance burden, while dual flush systems capture the fastest expansion as water-stressed municipalities revise building codes. Pressure assist configurations occupy niche commercial applications where drainline carry distance exceeds standard specifications.
EPA WaterSense certification in the United States and REACH material compliance in Europe shape product composition and market access requirements for manufacturers exporting across both jurisdictions. India's BIS fixture standards and China's GB water-efficiency grades further fragment compliance obligations for multinational suppliers. Stakeholders must monitor regulatory divergence between voluntary efficiency labeling and mandatory consumption caps as procurement specifications tighten across public infrastructure tenders.
Market Dynamics
Municipal water-efficiency mandates across water-stressed regions are compressing flush-volume specifications and forcing fixture replacement cycles in both new construction and renovation pipelines.
Growth Catalysts
- EPA WaterSense Certification:Federal procurement preference for labeled fixtures drives volume in US public infrastructure tenders and multi-family housing developments.
- Commercial Real Estate:LEED certification thresholds in Asia-Pacific office and retail construction specify dual-flush and sensor-actuated systems as baseline specifications.
- China's GB Standards:Tightening national water-consumption grades for ceramic fixtures accelerate replacement demand in existing building stock.
Market Restraints
- Brass and Copper Input Volatility:Valve casting alloys face price swings from concentrated Chilean and Peruvian mine supply, squeezing margin predictability for mid-tier manufacturers.
- Gravity Flush Dominance:Mechanical simplicity of incumbent technology creates inertia against pressure-assist and vacuum-assist adoption despite superior drainline carry performance.
- REACH Material Compliance:European chemical restrictions on certain seal compounds and surface coatings fragment formulation requirements for exporters serving multiple jurisdictions.
Strategic Opportunities
- Indonesia Urban Sanitation Scale-Up:National infrastructure programs in secondary cities create demand for complete bathroom systems rather than component sales.
- Sensor-Washlet Convergence:Integration of proximity detection with bidet functionality opens premium residential and hospitality specification channels.
- India BIS Standardization:Mandatory fixture grading creates first-mover advantage for suppliers achieving highest water-efficiency tiers ahead of enforcement deadlines.
Industry Challenges
- Cross-Border Certification Timelines:Divergent testing protocols between EPA WaterSense, EU CE marking, and national standards in India and China extend product launch cycles.
- Plumber Training Gaps:Installation complexity of dual-flush valve mechanisms and sensor calibration outpaces vocational curriculum updates in emerging markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flushing Systems Market |
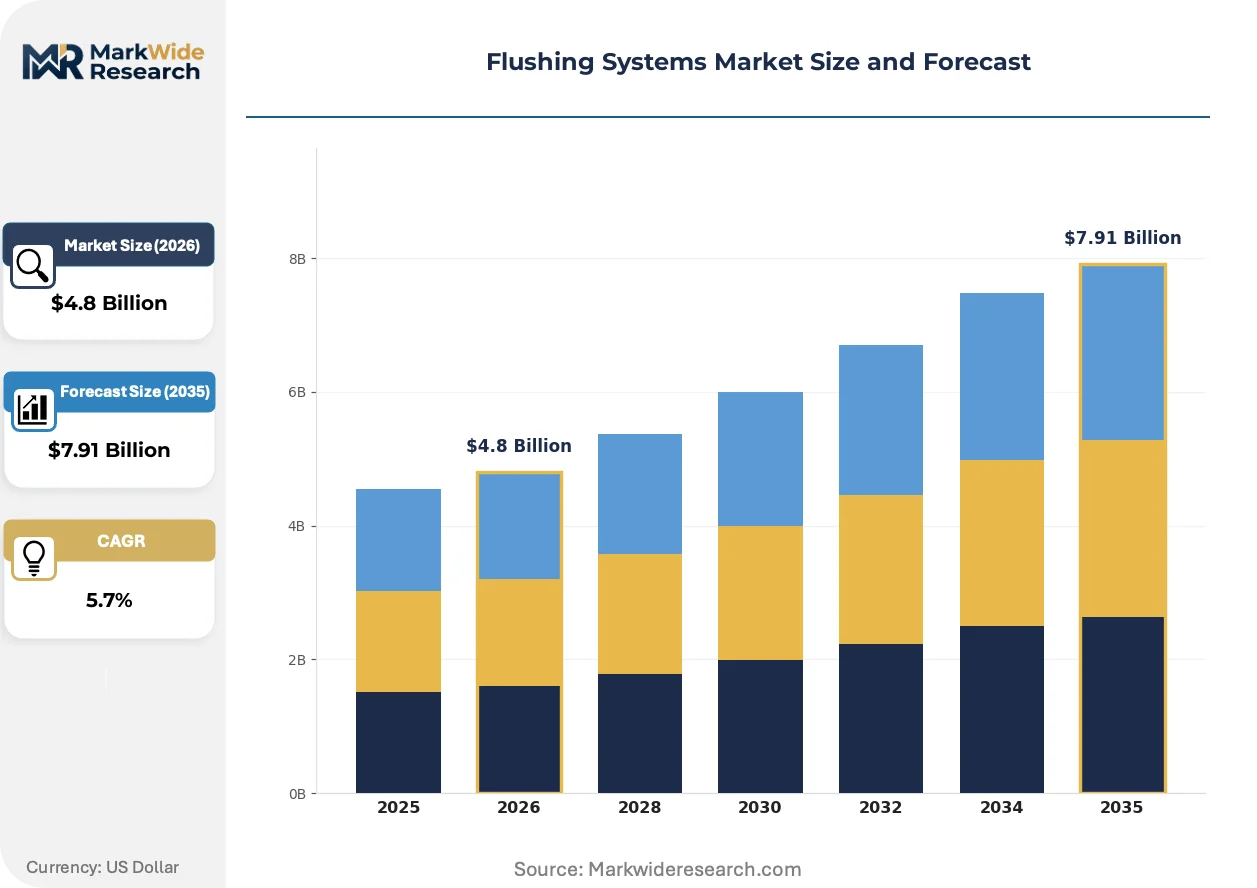
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilets, Urinals, Bidets, Flush Tanks Technology: Gravity Flush, Pressure Assist, Dual Flush, Vacuum Flush End User: Residential, Commercial, Industrial, Institutional Installation Type: Wall-mounted, Floor-mounted, Integrated, Portable |
| Companies Covered | Sloan Valve Company, Jaquar Group, Geberit, Fluidmaster Inc., Hindware Homes Limited, TOTO Ltd., Roca Sanitario S.A., Grohe Limited, Kohler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flushing Systems Market Strategic Shifts & Innovations
Water-stress mapping is redirecting R&D investment toward sub-one-gallon flush technologies and non-water alternatives, while digital actuation is penetrating price tiers previously served by purely mechanical systems.
Smart valve architectures with embedded flow sensors and wireless connectivity are decentralizing maintenance scheduling across commercial restroom portfolios. Facility management platforms at airports, stadiums, and corporate campuses adopt these systems to predict seal degradation and optimize water consumption. The technology is decentralizing service relationships from reactive truck rolls to continuous remote monitoring contracts.
EU Green Deal water-efficiency targets are hardening mandatory consumption caps for public building renovations across member states. The European Commission's building performance standards now embed fixture efficiency into whole-building energy calculations. Commercial construction in Germany, France, and the Netherlands responds by specifying only dual-flush or pressure-assist configurations in tender documents.
Specification authority is migrating from general contractors to facilities operators who bear long-term utility costs. Build-to-rent residential and hospitality REITs now source flushing systems directly through MRO distributors rather than accepting developer defaults. This pattern concentrates most visibly in US Sun Belt markets where water rates have climbed fastest and tenant utility pass-through structures sharpen payback sensitivity.
Flushing Systems Market Segmentation
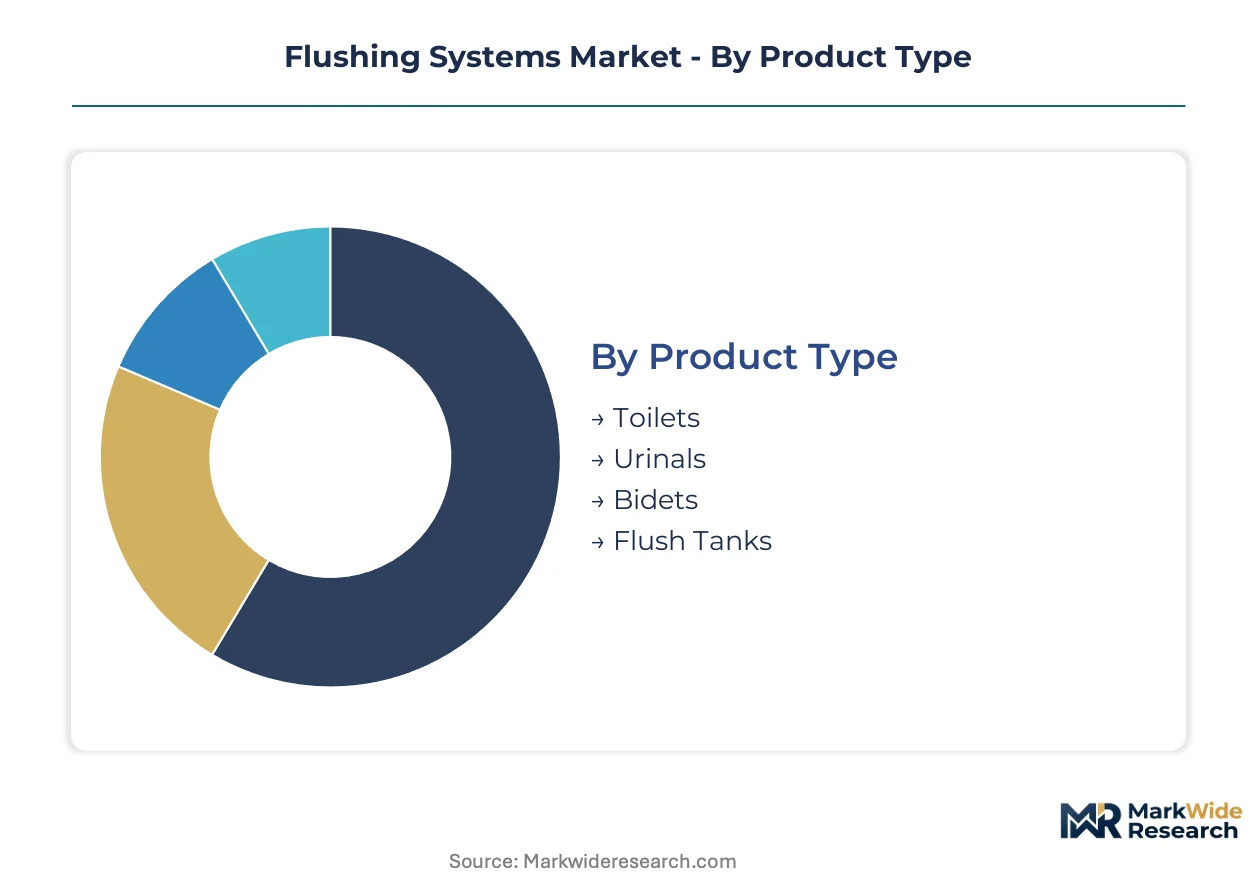
Segmentation in flushing systems reveals how specification authority migrates between architects, facilities managers, and procurement officers across project types. Product architecture and installation constraints determine margin structures and service attach rates for component suppliers.
Product Type:
Customization intensity spans from commodity ceramic bowls to electronically integrated bidet systems requiring field calibration and ongoing maintenance contracts.
- Toilets:Ceramic bowl-and-trap assemblies dominate installed base volume across residential and commercial construction. China's GB water-efficiency grades and EPA WaterSense certification create tiered specification lanes in new construction and renovation pipelines.
- Urinals:Wall-hung ceramic fixtures with ultra-low flush volumes or waterless cartridge systems serve high-traffic commercial restrooms. Water-stressed municipalities in the US Sun Belt specify these for payback sensitivity under tenant utility pass-through structures.
- Bidets:Electronic washlet seats and standalone fixtures integrate heating, drying, and deodorizing functions. Japanese and South Korean residential markets anchor demand, with hospitality channels driving export adoption.
- Flush Tanks:Concealed cisterns and exposed reservoir systems provide water storage and actuation pressure for bowl evacuation. European commercial construction favors in-wall installations for space efficiency and cleaning access.
Leading the category by volume: Toilets. Growing fastest: Bidets.
Technology:
Cost tier stratification separates mature mechanical systems from sensor-actuated architectures requiring electrical rough-in and commissioning support.
- Gravity Flush:Siphon-action evacuation relies on water head pressure without mechanical complexity. India's secondary cities and Southeast Asian urban sanitation programs specify these for plumber familiarity and spare parts availability.
- Pressure Assist:Compressed air within the tank amplifies flush velocity for superior drainline carry. Commercial restrooms in US airports and stadiums deploy these where horizontal waste runs exceed standard specifications.
- Dual Flush:Separate actuation buttons deliver reduced volumes for liquid waste and full volumes for solids. EU Green Deal building performance standards mandate these across member state public renovation tenders.
- Vacuum Flush:Negative pressure differential evacuates waste with minimal water consumption. Marine, rail, and aircraft applications dominate, with emerging interest in water-scarce terrestrial installations.
Gravity Flush commands the largest installed base. Dual Flush exhibits the steepest expansion trajectory.
End User:
Customer type determines procurement rhythm, with residential channels flowing through retail distribution and institutional buyers issuing multi-year framework agreements.
- Residential:Single-family and multi-family housing units specify through builders, architects, or direct consumer selection. India's BIS fixture standardization and Indonesia's urban sanitation scale-up concentrate demand growth in these channels.
- Commercial:Office towers, retail centers, and hospitality properties prioritize lifecycle cost over first cost. Build-to-rent REITs in US Sun Belt markets source directly through MRO distributors rather than accepting developer defaults.
- Industrial:Manufacturing facilities and logistics warehouses require durable fixtures for shift-worker density. Specification emphasizes vandal resistance and minimal maintenance interruption.
- Institutional:Schools, hospitals, and government buildings operate under public procurement rules with efficiency mandates. EPA WaterSense federal procurement preference shapes US public infrastructure tender outcomes.
Residential channels generate highest unit volume. Commercial specifications deliver strongest margin contribution.
Installation Type:
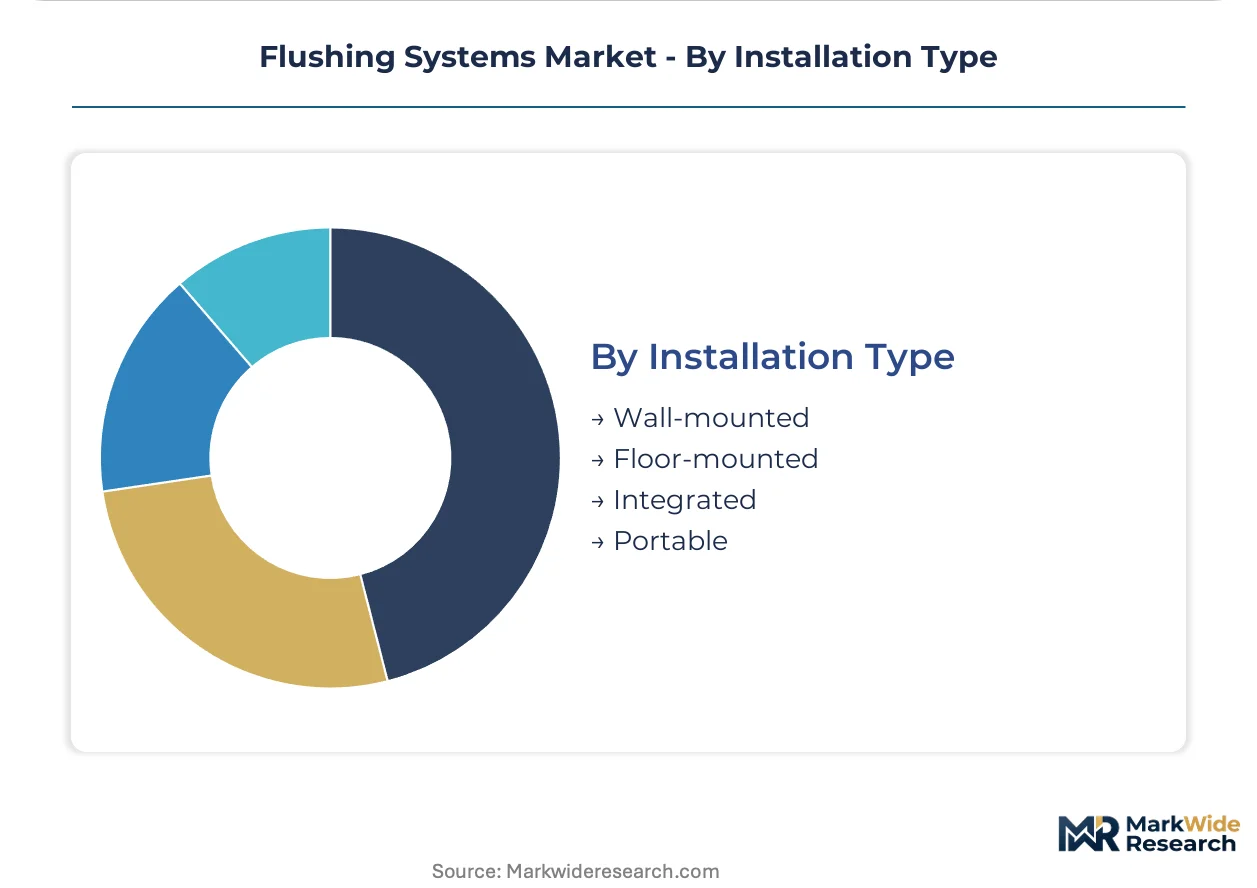
Volume concentration favors floor-mounted systems in renovation markets, while wall-mounted architectures gain share in new commercial construction prioritizing hygiene access and spatial flexibility.
- Wall-mounted:Concealed carriers support bowl and actuator installation with floor clearance for cleaning. German and Dutch commercial construction specifies these exclusively in healthcare and food-service environments.
- Floor-mounted:Traditional bolted-bowl designs accommodate existing flange locations in replacement scenarios. Dominates residential renovation and emerging market new construction.
- Integrated:Monolithic toilet-bidet systems combine ceramic, electronics, and plumbing in factory-assembled units. Japanese manufacturers anchor premium positioning through sensor-washlet convergence.
- Portable:Self-contained chemical or composting systems serve temporary construction sites, remote work camps, and disaster response. Event infrastructure and military applications sustain niche demand.
Floor-mounted systems retain volume leadership. Wall-mounted configurations gain specification share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta corridor concentrates the highest density of ceramic fixture manufacturing and water-efficiency R&D investment worldwide. The region's integration of GB standards compliance laboratories with production facilities accelerates certification cycles for domestic and export markets.
United States
EPA WaterSense federal procurement preference drives specification volume across public infrastructure tenders and multi-family housing developments. California's Title 24 building codes mandate sub-1.28 gallon flush volumes in new construction, tightening faster than national standards. Dallas-Fort Worth and Phoenix metropolitan areas concentrate commercial real estate renovation activity as water rates climb fastest in Sun Belt markets.
China
GB water-efficiency grades for ceramic fixtures are tightening nationwide, accelerating replacement demand in existing building stock. The Ministry of Ecology and Environment enforces consumption caps through municipal building performance audits. Foshan's ceramic industrial cluster dominates fixture production volume, with manufacturers integrating concealed cistern systems for European export markets.
Germany
EU Green Deal building performance standards embed fixture efficiency into whole-building energy calculations for public renovations. REACH material compliance restricts seal compounds and surface coatings, fragmenting formulation requirements for exporters. The Rhine-Ruhr metropolitan region concentrates specification authority for healthcare and food-service environments requiring wall-mounted hygiene-optimized systems.
India
BIS fixture standardization creates first-mover advantage for suppliers achieving highest water-efficiency tiers ahead of enforcement deadlines. The Jal Jeevan Mission urban sanitation scale-up concentrates demand growth in secondary cities. Maharashtra's Mumbai-Pune industrial corridor anchors domestic manufacturing expansion for complete bathroom system integration.
Indonesia
National infrastructure programs in secondary cities create demand for complete bathroom systems rather than component sales. The Ministry of Public Works and Housing prioritizes water-efficient fixtures in public facility construction tenders. Java's Surabaya-Malang corridor concentrates urban sanitation deployment as municipal budgets scale.
Flushing Systems Market Key Industry Players
The competitive structure tilts toward vertically integrated ceramic-and-piping specialists. Market concentration remains moderate, with premium-tier Japanese and European manufacturers commanding specification authority in hospitality and healthcare channels while mid-tier players compete on builder-direct volume. Three archetypes dominate: integrated system suppliers controlling ceramic-to-valve manufacturing, component specialists focusing on valve and actuator technology, and regional fabricators serving price-sensitive emerging markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing local certification partnerships to compress launch timelines.
Among the integrated system suppliers, Geberit exemplifies the European archetype of in-house ceramic and piping control, while TOTO Ltd. anchors Japanese premium positioning through factory-assembled toilet-bidet convergence. Sloan Valve Company represents the North American component specialist tier, focusing on valve and actuator architectures for commercial specification channels.
| Leading Market Players |
|---|
| Sloan Valve Company |
| Jaquar Group |
| Geberit |
| Fluidmaster Inc. |
| Hindware Homes Limited |
| TOTO Ltd. |
| Roca Sanitario S.A. |
| Grohe Limited |
| Kohler |
| Others |
Cost & Logistics Intelligence
Brass and copper alloy costs cascade from Chilean and Peruvian mine supply through valve casting foundries to tiered fixture pricing, with water-efficiency certification grades determining final positioning across residential, commercial, and institutional channels.
Pricing Analysis
Value-based pricing anchors on lifecycle water savings and maintenance burden reduction rather than first-cost metrics. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated washlet systems from dual-flush mechanical configurations and basic gravity-flush commodities. Cost compression in mid-tier mechanical systems intensifies as China's GB water-efficiency grades accelerate replacement demand and domestic manufacturers scale output. Institutional buyers exhibit lowest price sensitivity due to federal procurement preference for EPA WaterSense-labeled fixtures, while emerging market residential channels prioritize spare parts availability and plumber familiarity over efficiency premiums.
Supply Chain Analysis
Direct-to-contractor channels handle new construction volume, while MRO distributors serve renovation and facilities management demand. Ceramic fixture production concentrates in China's Foshan industrial cluster, brass valve manufacturing anchors in India and Southeast Asia, and electronic actuator assembly centers in Japan and South Korea. Raw material dependencies span Chilean copper concentrate, Chinese rare earth elements for sensor components, and European seal compounds subject to REACH restrictions. Single-source vulnerability in Chilean mine supply exposes margin predictability to commodity price swings. Distribution runs through builder-direct relationships for residential volume and specification-driven channels for commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flushing systems market sits in a technology-transition phase as sensor-actuated and dual-flush architectures displace legacy gravity-flush dominance in regulated markets.
For Market Incumbents: Deploy certification investment as the primary lever to compress cross-border launch timelines and defend specification authority against emerging market challengers. Deepen captive supply of ceramic and valve components to sustain margin control amid brass and copper input volatility. Counter pressure-assist and vacuum-flush substitutes by embedding smart valve architectures with predictive maintenance capabilities into commercial restroom portfolios.
For New Entrants and Emerging Players: Enter via Indonesia's urban sanitation scale-up, where national infrastructure programs demand complete bathroom system integration rather than component sales. Target India's secondary cities ahead of BIS fixture standardization enforcement deadlines to secure first-mover positioning in highest water-efficiency tiers. Pursue direct MRO distributor relationships with US Sun Belt build-to-rent REITs as facilities operators assume specification authority from general contractors.
For Investors and Strategic Acquirers: China's GB water-tightening enforcement is the leading indicator that replacement demand acceleration in existing building stock will outpace new construction cyclicality. Acquisition focus should center on vertically integrated ceramic-and-piping specialists with established concealed cistern capabilities for European export markets. Monitor divergence between voluntary efficiency labeling and mandatory consumption caps as the signal for regulatory risk concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Washlet Convergence Development | Integrates proximity detection with bidet functionality to capture premium hospitality and residential channels. |
| GB Standards Compliance Acceleration | Positions suppliers ahead of China's tightening water-consumption grades for ceramic fixtures nationwide. |
| Indonesia System Integration Partnership | Aligns with national infrastructure programs demanding complete bathroom solutions in secondary cities. |
| REACH Formulation Adaptation | Enables continued European market access as chemical restrictions fragment seal compound requirements. |
| Smart Valve Remote Monitoring Launch | Transforms service relationships from reactive maintenance to continuous monitoring contracts at airports and stadiums. |
Research Approach
Multi-period observation of fixture replacement cycles, water-efficiency regulation adoption timelines, and certification pipeline backlogs anchored the trend analysis, supplemented by interviews with ceramic manufacturing plant managers, commercial facilities operators, plumbing contractor business owners, and MRO distribution procurement leads. Secondary validation drew from EPA WaterSense product listings, EU Green Deal building performance standard drafts, China's GB standard revision notices, India's BIS fixture grading circulars, and customs trade data for brass and copper alloy flows. Bottom-up channel volume estimates triangulated against top-down construction activity indices.
Segment-weighting applied product type, technology architecture, end-user channel, and installation format dimensions across the projection horizon. CAGRs derived from regression analysis of historical replacement demand elasticity to water rate increases and regulatory mandate timing. Industry-specific forecast inputs included municipal water-efficiency mandate adoption curves and commercial real estate LEED certification penetration by metropolitan market.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory enforcement acceleration or sustained copper price volatility. Forecasts reflect assumptions regarding plumber training curriculum update speeds and cross-border certification timeline compression. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Integrated Building Management Systems Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Building Management System Market
Building Automation Systems
Platform Lifts Market
Building Automation Systems
Global Building Information Modeling (BIM) Market
Building Automation Systems
Signage Market
Building Automation Systems
Escalator Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Building Technologies Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Global Door Closers Market
Building Automation Systems
Smart Building Solutions Market