
 Japan Engineering Plastics Market | 2026-2036
Japan Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Engineering Plastics Market Insights
Market Context
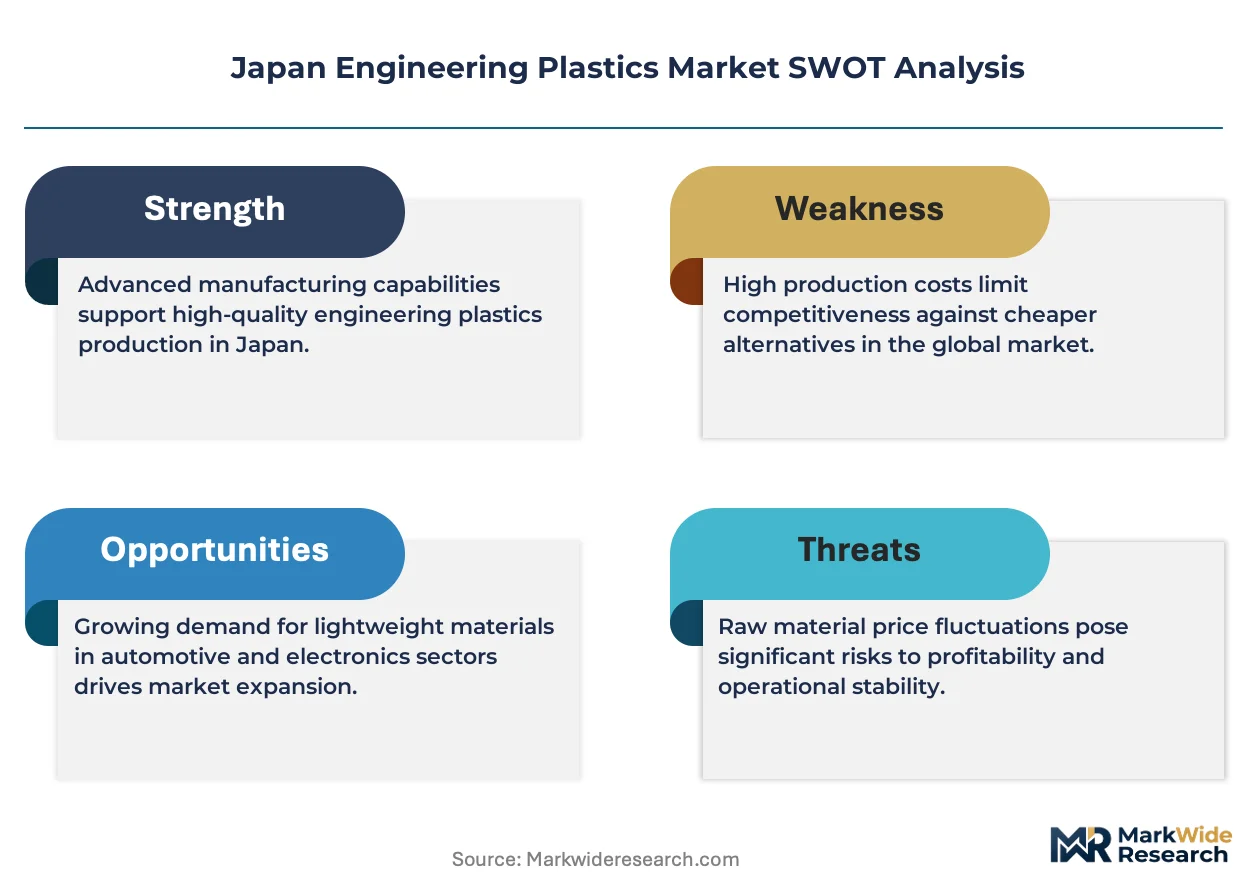
Japan's automotive emissions standards is hardening the cost-of-entry calculus for engineering plastics suppliers serving vehicle electrification programs. Toray Industries Inc. leverages its carbon fiber-polymer composite expertise to anchor premium positions in structural automotive applications. Mitsubishi Chemical Corporation sustains broad polycarbonate and nylon capabilities across multiple industrial verticals. Sumitomo Chemical Co., Ltd. specializes in high-heat polymer formulations that navigate tightening thermal performance thresholds for under-hood components.
Technical Definition and Segment Structure
Japan engineering plastics comprise thermoplastic polymers engineered to maintain mechanical integrity above 100°C, including aromatic polyamides with melting points exceeding 260°C and polycarbonate grades offering Izod impact resistance above 80 kJ/m², serving primarily as metal replacements in load-bearing and precision-tolerance applications. Polycarbonate dominates volume flows across electronics housings and optical media substrates where transparency and dimensional stability command premium positioning. Nylon captures expanding share in automotive powertrain components as OEMs pursue weight reduction without sacrificing creep resistance under continuous stress. PBT anchors electrical connector applications where moisture resistance and dielectric performance define procurement specifications.
Regulatory Framework
METI enforces Japan's Top Runner Program for automotive efficiency, directly shaping polymer selection criteria through mandated thermal management and weight reduction benchmarks. JIS standards govern material certification protocols, while PMDA oversees biocompatibility requirements for medical device-grade engineering plastics entering healthcare applications. Stakeholders must monitor evolving alignment between domestic automotive regulations and emerging EU battery passport requirements that will reshape supply chain documentation obligations for polymer feedstocks.
Market Dynamics
METI's Top Runner Program for automotive efficiency is hardening thermal performance thresholds and forcing polymer suppliers to reformulate high-heat nylon and polycarbonate grades for under-hood electrification components.
Growth Catalysts
- Vehicle Electrification Mandates:METI's tightening emissions standards compel automotive OEMs to substitute metal powertrain parts with lightweight aromatic polyamides. Polycarbonate battery housings capture expanding share as thermal management requirements intensify.
- Kanto Industrial Concentration:Tokyo-to-Yokohama manufacturing corridor anchors precision electronics and optical media substrate demand. Engineering plastics suppliers cluster within 100 kilometers of downstream compounders to minimize logistics friction.
- Medical Device Biocompatibility:PMDA oversight of implantable and diagnostic equipment creates certified-grade polymer demand. High-purity PBT and specialized polycarbonate formulations command sustained procurement premiums.
Market Restraints
- Caprolactam Feedstock Volatility:Nylon 6,6 production depends on benzene-derived intermediates subject to Asian refinery output fluctuations. Price instability compresses compounder margins and deters long-term supply contracts.
- Polymer-grade Bisphenol A Concentration:Polycarbonate resin supply concentrates among three domestic producers. Any unplanned aromatic unit outage ripples through electronics and automotive substrate channels within weeks.
- High-temperature PEEK Substitution Ceiling:Metal-to-polymer conversion stalls above 150°C continuous service temperature. Automotive turbocharger housings and exhaust-adjacent components retain cast aluminum despite weight penalties.
Strategic Opportunities
- Osaka-Kobe Medical Device Corridor:Hyogo and Osaka prefectures host concentrated diagnostic imaging and surgical equipment manufacturers. Biocompatible polycarbonate and sulfone polymer demand outpaces domestic formulation capacity.
- Battery Passport Alignment:Emerging EU documentation requirements for polymer feedstock traceability favor Japanese suppliers with established JIS-certified chain-of-custody systems. Early compliance investments secure European automotive export positioning.
- Carbon Fiber-Polymer Hybridization:Structural automotive applications increasingly specify continuous fiber-reinforced thermoplastic composites. Hybrid molding technologies reduce cycle times versus conventional autoclave curing.
Industry Challenges
- Specialized Polymer Rheology Expertise Gap:Formulation of high-flow grades for thin-wall electronics connectors requires scarce polymer physics specialization. Universities produce insufficient graduates with combined materials science and processing engineering training.
- Multi-standard Certification Complexity:Automotive suppliers must simultaneously satisfy JIS material protocols, METI efficiency benchmarks, and customer-specific OEM validation timelines. Parallel testing streams extend product qualification to 18-24 months.
- Legacy Injection Molding Asset Stranding:Existing machine parks optimized for commodity ABS and polypropylene lack precision temperature control for high-heat engineering grades. Retooling capex demands strain mid-tier compounder balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Engineering Plastics Market |
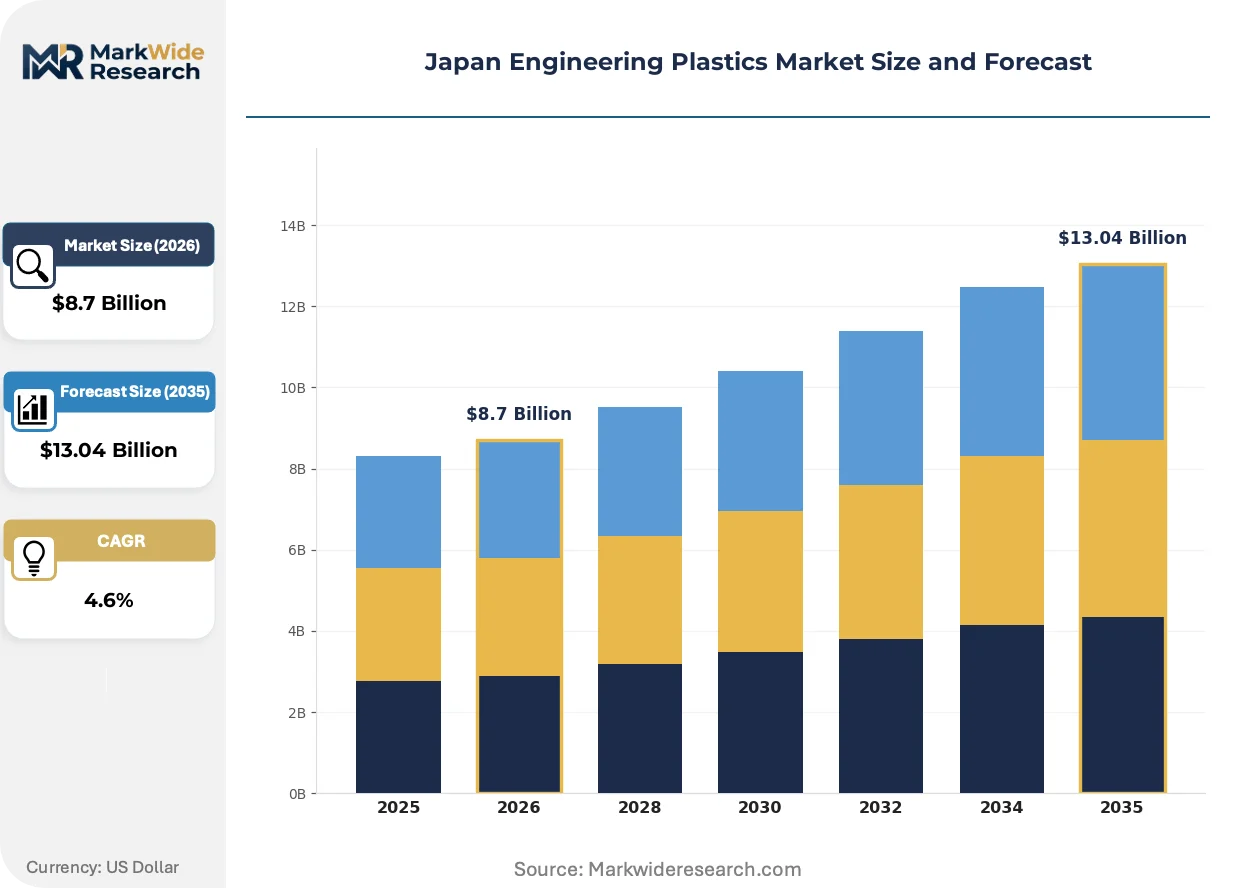
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Nylon, PBT, Acetal Application: Automotive Components, Electronics, Medical Devices, Industrial Machinery End User: OEMs, Tier-1 Suppliers, Healthcare Providers, Consumer Electronics Technology: Injection Molding, Extrusion, Thermoforming, 3D Printing |
| Companies Covered | Mitsubishi Chemical Corporation, Asahi Kasei Corporation, Toray Industries Inc., Sumitomo Chemical Co., Ltd., Daikin Industries Ltd., Polyplastics-Evonik Corporation, Kuraray Co., Ltd., Teijin Limited, UBE Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Engineering Plastics Market Trends and Innovations
Japanese engineering plastics suppliers are pivoting formulation priorities toward thermal management and circular feedstock integration as automotive electrification and regulatory compliance timelines compress.
Continuous fiber-reinforced thermoplastic composites are converging with automated fiber placement systems to enable structural automotive components previously reserved for thermoset prepregs. Tier-1 suppliers in Aichi and Shizuoka prefectures are qualifying hybrid bumper beams and seat structures for 2027 platform launches. This convergence is compressing the traditional separation between injection molding and structural composites manufacturing.
METI's revised Top Runner standards for passenger vehicle efficiency now explicitly weight powertrain thermal management in corporate average calculations. Polycarbonate and polyphenylene sulfide suppliers must document heat deflection temperature improvements under standardized JIS testing protocols. Battery enclosure manufacturers in the Kanto corridor are accelerating qualification of mineral-filled grades that satisfy both flame retardance and dielectric isolation requirements.
Compounders serving electronics OEMs are unbundling traditional resin-plus-distribution contracts into separate formulation development and logistics service lines. Sony and Panasonic procurement teams now negotiate masterbatch specifications independently from warehousing and just-in-time delivery terms. This unbundling is most visible in the Greater Tokyo Area, where specialized third-party logistics providers have captured material handling functions previously performed by resin suppliers.
Japan Engineering Plastics Market Segmentation
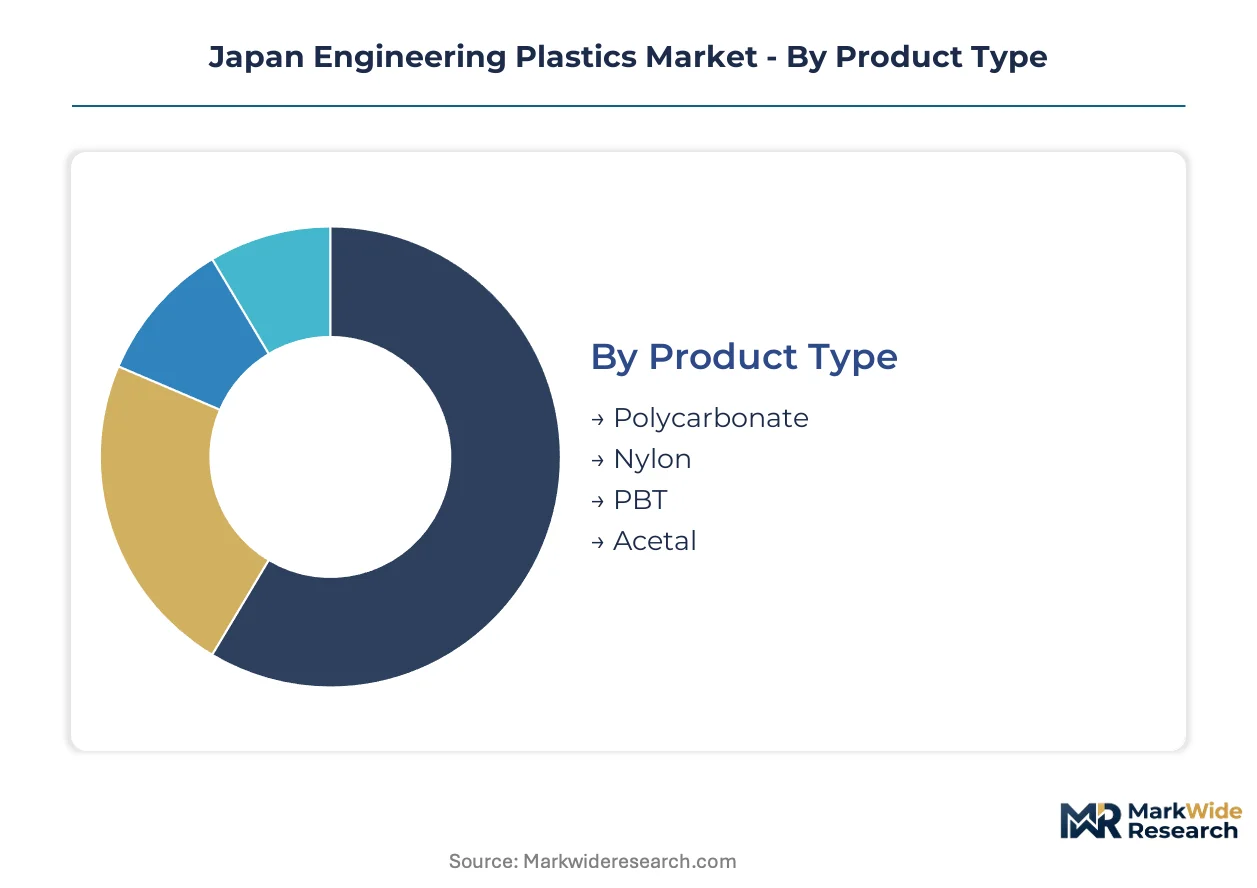
Japan's engineering plastics market fragments across multiple decision axes that reshape procurement priorities. Product chemistry determines thermal ceiling and mechanical performance for electrification applications. Manufacturing technology selection constrains which grades compounders can economically process at scale.
Product Type:
Material selection pivots on heat deflection temperature requirements and chemical resistance profiles demanded by downstream specifications.
- Polycarbonate:Amorphous thermoplastic delivering optical clarity above 85% light transmission and Izod impact resistance exceeding 80 kJ/m². Electronics housings in the Kanto corridor absorb the majority of polycarbonate volume as OEMs specify flame-retardant grades for battery enclosures and display substrates.
- Nylon:Semi-crystalline polyamide family spanning aliphatic grades to aromatic variants with melting points above 260°C. Automotive powertrain applications in Aichi and Shizuoka prefectures drive formulation investments as METI efficiency standards harden under-hood thermal performance thresholds.
- PBT:Crystalline polyester engineered for moisture resistance below 0.1% water absorption and dielectric stability across electrical connector applications. Medical device manufacturers in Osaka specify high-purity PBT grades for diagnostic equipment housings requiring PMDA biocompatibility certification.
- Acetal:High-crystallinity homopolymer and copolymer grades delivering low friction coefficients and dimensional precision for gear and bearing applications. Industrial machinery OEMs in the Nagoya manufacturing belt specify acetal for conveyor components and pump housings.
Volume sits with polycarbonate; growth tilts toward nylon.
Application:
End-use verticals impose divergent certification burdens and performance validation timelines that segment supplier capabilities.
- Automotive Components:Structural and under-hood applications spanning bumper beams to battery enclosures where weight reduction intersects with crashworthiness requirements. Tier-1 suppliers in Toyota City and Yokohama are qualifying continuous fiber-reinforced grades for platform launches.
- Electronics:Precision housings, optical media substrates, and connector bodies where dimensional stability and flame retardance dominate specifications. Sony and Panasonic procurement teams in Tokyo negotiate masterbatch specifications separately from logistics contracts.
- Medical Devices:Implantable and diagnostic equipment requiring PMDA biocompatibility validation and ISO 10993 compliance. The Osaka-Kobe corridor concentrates demand for sulfone polymers and specialized polycarbonate formulations.
- Industrial Machinery:Load-bearing gears, pump housings, and conveyor components where wear resistance and chemical exposure define material selection. Nagoya-based machinery OEMs prioritize acetal and nylon grades for continuous stress applications.
Electronics commands the largest volume position; medical devices are climbing the fastest.
End User:
Customer scale and integration depth determine whether procurement emphasizes formulation partnership or logistics efficiency.
- OEMs:Vertically integrated automotive and electronics manufacturers with captive compounding operations and direct resin supplier relationships. Toyota and Honda maintain dedicated engineering plastics development programs with domestic polymer producers.
- Tier-1 Suppliers:Component specialists serving multiple OEM platforms who negotiate masterbatch specifications and just-in-time delivery terms as separate procurement streams. Denso and Aisin source high-heat nylon grades for powertrain applications across hybrid and battery-electric vehicle programs.
- Healthcare Providers:Medical device manufacturers and contract manufacturers requiring PMDA-certified polymer grades with documented chain-of-custody. Olympus and Terumo specify biocompatible polycarbonate for endoscopic equipment and surgical instruments.
- Consumer Electronics:Brands and contract manufacturers prioritizing optical-grade polycarbonate for display substrates and portable device housings. Procurement concentrates in the Greater Tokyo Area with specialized third-party logistics providers handling material flows.
Tier-1 suppliers absorb the heaviest volume; healthcare providers are gaining share fastest.
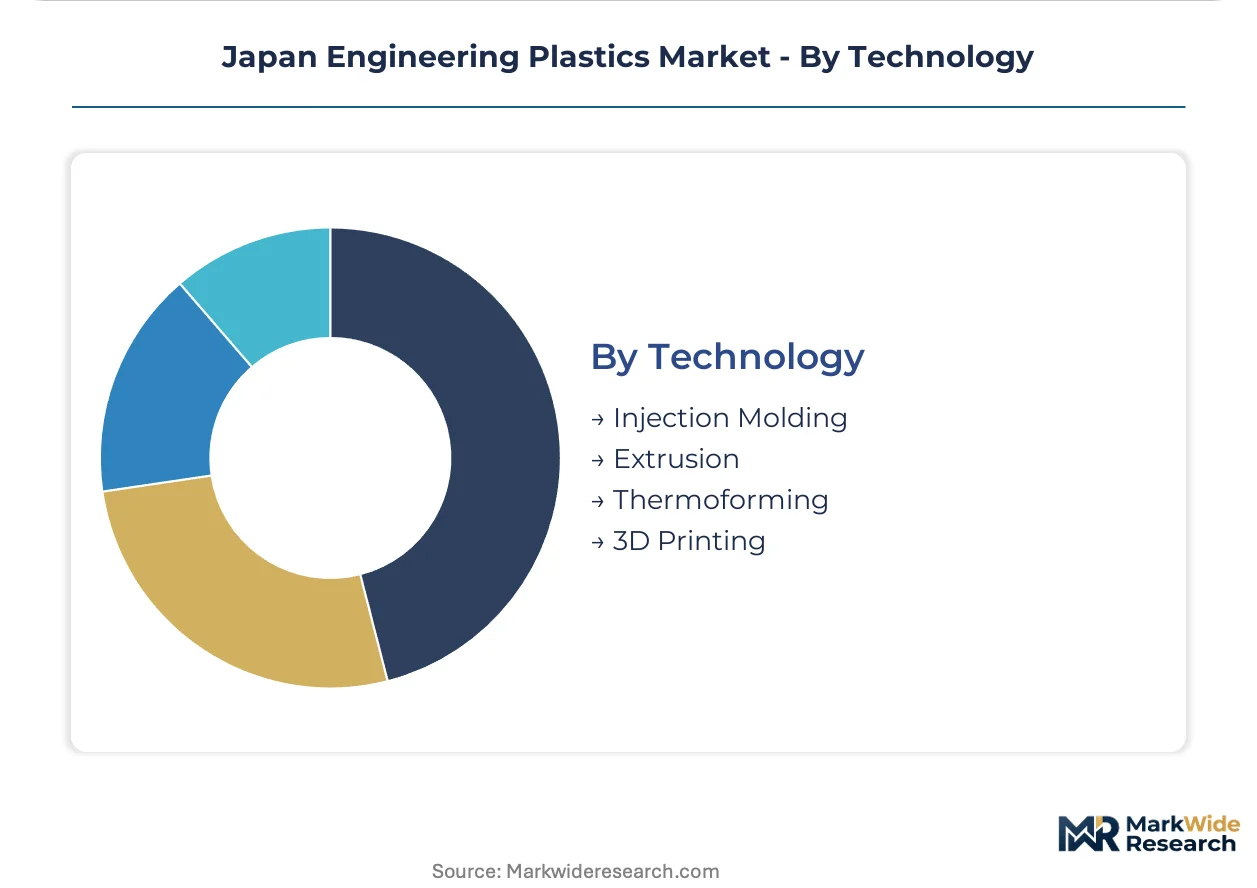
Technology:
Processing method selection constrains which polymer grades achieve economic viability at production scale.
- Injection Molding:Dominant forming method for complex geometries in automotive and electronics applications requiring tight dimensional tolerances. Legacy machine parks optimized for commodity ABS lack precision temperature control for high-heat engineering grades.
- Extrusion:Continuous profile production for sheet, film, and filament applications in optical media and industrial tubing. Polycarbonate sheet extrusion serves the Kanto electronics substrate market.
- Thermoforming:Secondary shaping of extruded sheet for large-format housings and protective covers where impact resistance outweighs structural load requirements. Medical device tray applications specify thermoformed polycarbonate grades.
- 3D Printing:Emerging additive manufacturing for prototyping and low-volume production of complex geometries previously requiring machined metal. Filament suppliers in Osaka are qualifying nylon and polycarbonate grades for fused deposition modeling.
Injection molding anchors volume; 3D printing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto's special economic zones and industrial clusters concentrate engineering plastics demand through tax incentives tied to automotive and electronics manufacturing.
Kanto/Tokyo
Tokyo-to-Yokohama corridor absorbs polycarbonate volume for electronics housings and optical substrates. METI's Top Runner Program mandates thermal management benchmarks that reshape polymer specifications for battery enclosures. Sony and Panasonic procurement teams in Greater Tokyo negotiate masterbatch terms separately from logistics contracts.
Kansai/Osaka
Osaka-Kobe medical device corridor drives biocompatible sulfone polymer and specialized polycarbonate demand. PMDA certification requirements for implantable equipment create procurement premiums for certified-grade materials. Olympus and Terumo specify high-purity formulations for endoscopic and surgical instrument applications.
Chubu/Nagoya
Toyota City and surrounding Aichi prefecture anchor automotive powertrain polymer consumption. METI efficiency standards harden under-hood thermal thresholds for nylon formulations. Denso and Aisin source high-heat aromatic polyamides across hybrid and battery-electric vehicle programs.
Kyushu
Fukuoka and Kitakyushu industrial zones host precision electronics and semiconductor packaging manufacturers. JIS material certification protocols govern resin selection for connector and substrate applications. Compounders cluster within logistics radius of downstream electronics OEMs to minimize supply friction.
Tohoku
Sendai and Fukushima prefectures concentrate chemical intermediate production feeding domestic nylon and polycarbonate supply chains. Caprolactam and bisphenol A processing facilities face feedstock volatility from Asian refinery output fluctuations. Regional producers balance captive consumption against spot market exposure.
Japan Engineering Plastics Market Competitive Landscape
Kanto-based integrated chemical conglomerates anchor one tier; Osaka-Kobe specialty compounders hold differentiated positions in medical-grade segments. Market structure consolidates around diversified resin producers with captive feedstock integration and formulation depth. Three archetypes dominate: vertically integrated petrochemical giants, medical-device certification specialists, and carbon fiber-polymer hybrid technology developers. Capacity expansion and JIS certification portfolio diversification represent the primary competitive vectors as electrification timelines compress.
Within the integrated chemical conglomerate tier, Mitsubishi Chemical Corporation, Toray Industries Inc., and Sumitomo Chemical Co., Ltd. exemplify divergent strategic positioning. Mitsubishi Chemical Corporation represents broad polycarbonate and nylon capabilities across multiple industrial verticals. Toray Industries Inc. anchors premium positions in structural automotive applications through carbon fiber-polymer composite expertise. Sumitomo Chemical Co., Ltd. occupies a specialization in high-heat polymer formulations navigating tightening thermal performance thresholds for under-hood components.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Asahi Kasei Corporation |
| Toray Industries Inc. |
| Sumitomo Chemical Co., Ltd. |
| Daikin Industries Ltd. |
| Polyplastics-Evonik Corporation |
| Kuraray Co., Ltd. |
| Teijin Limited |
| UBE Corporation |
| Others |
Pricing and Supply Chain Analysis
Caprolactam spot pricing in Asian refinery corridors cascades through Japanese nylon compounders into three distinct procurement tiers: JIS-certified automotive grades command premiums, standard electronics grades trade at mid-market clearing levels, and spot-volume commodity nylon faces persistent margin compression from benzene feedstock volatility.
Pricing Analysis
Short-lead-time premiums of 15-20 percent separate emergency automotive qualification batches from standard 90-day contract volumes in the Kanto corridor. Pricing stratifies across medical-device-certified, automotive-validated, and general-industrial tiers, with PMDA biocompatibility documentation adding substantial procurement premiums. Cost compression in general-purpose polycarbonate intensifies as Chinese resin imports displace domestic spot volumes. Tier-1 automotive suppliers exhibit lowest price sensitivity due to platform-lock-in, while mid-tier electronics compounders face acute margin pressure from unbundled logistics contracts.
Supply Chain Analysis
Reverse-logistics flows for engineering plastics remain underdeveloped in Japan, with limited mechanical recycling infrastructure for high-heat nylon and polycarbonate streams constraining circular feedstock integration. Manufacturing concentrates in Japan, South Korea, and Taiwan, with Japanese producers maintaining captive caprolactam and bisphenol A capacity. Feedstock supply rests on benzene derivatives from Asian refinery complexes and polymer-grade bisphenol A from domestic aromatic units. Single-source vulnerability haunts specialized sulfone polymer formulations for medical applications. Distribution runs through compounder-owned warehousing networks clustered within 100 kilometers of Kanto and Kansai manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's engineering plastics market operates as a supply-constrained environment where polymer-grade bisphenol A concentration among three domestic producers props pricing power in polycarbonate channels.
For Market Incumbents: Lock in long-term offtake agreements with automotive OEMs before EU battery passport documentation requirements reshape procurement qualification timelines. Deepen backward integration into caprolactam intermediates to buffer benzene price volatility threatening nylon compounder margins. Prioritize JIS certification portfolio expansion for high-heat grades as METI thermal management benchmarks tighten. For New Entrants and Emerging Players: Capture white-space demand in the Osaka-Kobe medical device corridor where biocompatible sulfone polymer formulation capacity lags diagnostic equipment manufacturer requirements. Target PMDA-certified specialty grades for endoscopic and surgical instrument applications as Olympus and Terumo diversify supplier bases. Pursue toll-compounding partnerships with established resin distributors to bypass legacy asset stranding barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor carbon fiber-polymer hybrid technology developers in Aichi and Shizuoka prefectures as automotive platform launches accelerate continuous fiber-reinforced thermoplastic adoption. Mid-cap compounders with JIS-certified medical-grade portfolios offer acquisition exposure to healthcare procurement premiums. Monitor METI Top Runner standard revisions as inflection indicators for thermal performance threshold shifts that reshape formulation R&D allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Captive benzene-derived intermediate supply buffers Mitsubishi Chemical and UBE Corporation against Asian refinery output fluctuations. |
| JIS Certification Portfolio Expansion | Documented heat deflection temperature improvements under standardized protocols secure METI Top Runner Program compliance positioning. |
| Carbon Fiber-Polymer Hybridization Investment | Toray Industries anchors structural automotive applications through continuous fiber-reinforced thermoplastic composite expertise. |
| Medical-Grade Formulation Capacity Addition | Hyogo and Osaka prefecture biocompatible sulfone polymer production addresses PMDA-certified diagnostic equipment demand gaps. |
| EU Battery Passport Alignment | Early chain-of-custody system investments position Japanese suppliers for emerging European automotive export documentation requirements. |
Research Methodology
Independent corroboration across METI regulatory filings, JIS material certification databases, and PMDA medical device polymer registrations underwrites the qualitative findings in this study. Primary interviews with polymer plant managers, Tier-1 automotive procurement leads, medical device biomedical engineers, and distribution channel partners combined with secondary validation from customs trade data, SEC 10-K chemical segment disclosures, and ACC regional production reports. Bottom-up resin volume modeling and top-down automotive content-per-vehicle estimates triangulate market sizing.
Comparable-period anchoring to historical automotive production cycles and electronics substrate demand patterns shaped the projection framework across the analysis window. Segmentation dimensions modeled include product chemistry tier, end-use vertical, manufacturing technology, and regional industrial cluster. CAGRs derived from elasticity-adjusted demand curves incorporating METI efficiency standard compliance timelines and vehicle electrification penetration assumptions. Industry-specific inputs encompass caprolactam price elasticity coefficients and polycarbonate substitution rates in battery enclosure applications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Asian refinery output disruptions and EU regulatory alignment timelines. Forecasts reflect documented assumptions regarding automotive platform launch schedules and medical device certification backlog clearance. Practitioners should monitor METI Top Runner revision announcements and EU battery passport implementation triggers for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Carbide Inserts Market
Industrial Materials
Neoprene Foam Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
Industrial Seals Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
North America Activated Carbon Market
Industrial Materials
Air Classifiers Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Plastics in Electrical and Electronics Market
Industrial Materials
Bamboo Products Market
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Battery Separator Materials Market