
 Flumazenil Market | 2026-2036
Flumazenil Market Size, Share, and Industry Trends Forecast 2026-2036
Flumazenil Market Insights
Pharmaceutical-grade flumazenil is unwinding from legacy anesthesia-reversal positioning toward broader emergency toxicology use. Hoffmann La Roche anchors the originator segment with decades of clinical validation. Fresenius Kabi USA leverages hospital infusion channel dominance to sustain injectable volume leadership. Teva Pharmaceutical Industries Ltd. competes aggressively on generic pricing across North American acute-care procurement networks.
Flumazenil is a competitive benzodiazepine receptor antagonist synthesized as an imidazobenzodiazepine derivative, formulated primarily as an intravenous injection at 0.1 mg/mL concentration for rapid reversal of sedative-hypnotic effects. The compound functions by displacing benzodiazepines from GABA-A receptor sites without intrinsic agonist activity, restoring consciousness in overdose and post-procedural sedation scenarios. Injectable formulations occupy the dominant revenue position due to emergency medicine's demand for immediate bioavailability, while pre-filled syringe formats are gaining fastest among formulation variants by reducing preparation error and dosing latency in critical care. Emergency care applications lead absolute volume as opioid-benzodiazepine co-ingestion cases rise, though anesthesia reversal retains the most concentrated margin pool through perioperative protocol standardization.
FDA bioequivalence requirements for generic flumazenil injectables shape product development timelines and manufacturing scale decisions for market entrants. EMA's Good Manufacturing Practice inspections for active pharmaceutical ingredient suppliers determine European supply reliability and sourcing qualification burdens. Health Canada's PMRA oversight of benzodiazepine antagonist labeling influences prescriber training requirements and reimbursement coding alignment. Stakeholders must monitor evolving emergency medicine protocol updates and generic substitution policies across these jurisdictions to anticipate volume shifts and procurement contract renegotiation cycles.
Market Dynamics
Emergency medicine protocols are pivoting from anesthesia-centric flumazenil use toward toxicology-first deployment, driven by rising polydrug overdose caseloads and hospital formulary recalibrations. This structural reorientation compresses perioperative margins while expanding emergency department volume pools.
Growth Catalysts
- Poison Control Network Integration:US hospital emergency departments are embedding flumazenil into standardized benzodiazepine-opioid reversal protocols, expanding addressable patient volume through protocol harmonization.
- FDA ANDA Streamlining:Abbreviated New Drug Application pathways for injectable generics are compressing approval timelines, accelerating manufacturer entry and price competition.
- Pre-filled Syringe Adoption:Critical care units are substituting multi-dose vials with unit-dose formats, reducing medication errors and preparation latency in time-sensitive overdose scenarios.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production clusters in South Asian contract manufacturing organizations, creating single-source vulnerability for generic injectable supply.
- Naloxone Co-formulation Substitution:Combination opioid-benzodiazepine antagonist products under development threaten standalone flumazenil positioning in emergency kits.
- EMLA Reimbursement Compression:European Medicines Agency pricing benchmarks for emergency antidotes are narrowing hospital procurement budgets and generic margin floors.
Strategic Opportunities
- Ambulatory Surgery Center Penetration:Freestanding ASCs in Texas and Florida are adopting rapid-reversal protocols for outpatient sedation, opening volume beyond traditional hospital channels.
- Intranasal Formulation Development:Non-intravenous delivery mechanisms are converging with abuse-deterrent packaging technologies, enabling pre-hospital administration by paramedic services.
- Health Canada PMRA Label Expansion:Pediatric sedation reversal indications under regulatory review would unlock neonatal ICU and pediatric emergency segments currently off-label.
Industry Challenges
- Sterile Manufacturing Certification:FDA current Good Manufacturing Practice inspections for aseptic injectable facilities are extending qualification timelines for new market entrants.
- Cold Chain Integrity:Temperature excursion risks in flumazenil distribution are forcing capital investment into validated thermal packaging and real-time monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flumazenil Market |
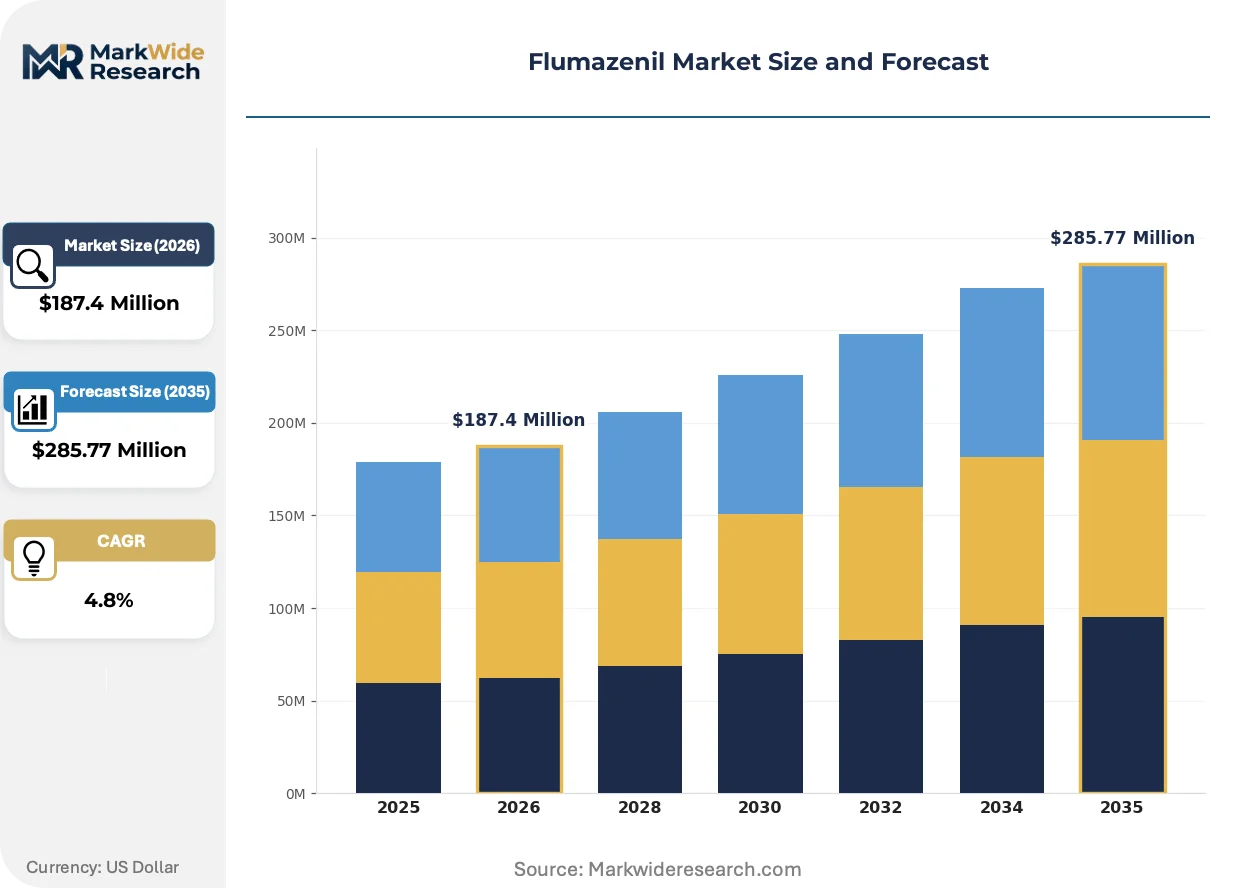
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral Tablet, Injection, Solution Application: Overdose Treatment, Anesthesia Reversal, Seizure Management, Emergency Care End User: Hospitals, Clinics, Emergency Rooms, Pharmacies Formulation: Syringe, Ampoule, Vial, Pre-filled Syringe |
| Companies Covered | Hoffmann La Roche, Fresenius Kabi USA, Sandoz Canada Incorporated, Mylan Pharmaceuticals, Genentech, West Ward Pharmaceutical, Pfizer Laboratories Div Pfizer Inc., Hikma Pharmaceuticals, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flumazenil Market Trends and Innovations
Formulation engineering and administration modality are diverging from legacy intravenous dependence, with device-drug convergence and regulatory science advancing in parallel. These shifts are compressing traditional competitive moats while opening new clinical utility vectors.
Pre-filled syringe systems with integrated needle safety mechanisms are decomposing the historical dominance of multi-dose vial formats in hospital emergency departments. Anesthesiology groups and emergency medicine physicians are adopting these units at accelerating rates, particularly in level-one trauma centers. This modality shift is enabling just-in-time inventory models and reducing pharmacy compounding burden.
EMA's Good Manufacturing Practice Annex 1 revisions for sterile medicinal products are tightening environmental monitoring requirements for flumazenil injectable manufacturers. European contract manufacturing organizations are retrofitting isolator technology and continuous particulate monitoring systems to maintain supply qualification. Small-volume generic sponsors face disproportionate compliance capital requirements relative to revenue base.
Hospital procurement consortia are consolidating antidote purchasing into system-wide formularies with mandatory generic substitution clauses. Group purchasing organizations are displacing individual hospital pharmacy negotiations, compressing supplier margins while securing supply continuity. This concentration is most visible in US integrated delivery networks spanning multiple states with standardized emergency medicine protocols.
Flumazenil Market Segmentation
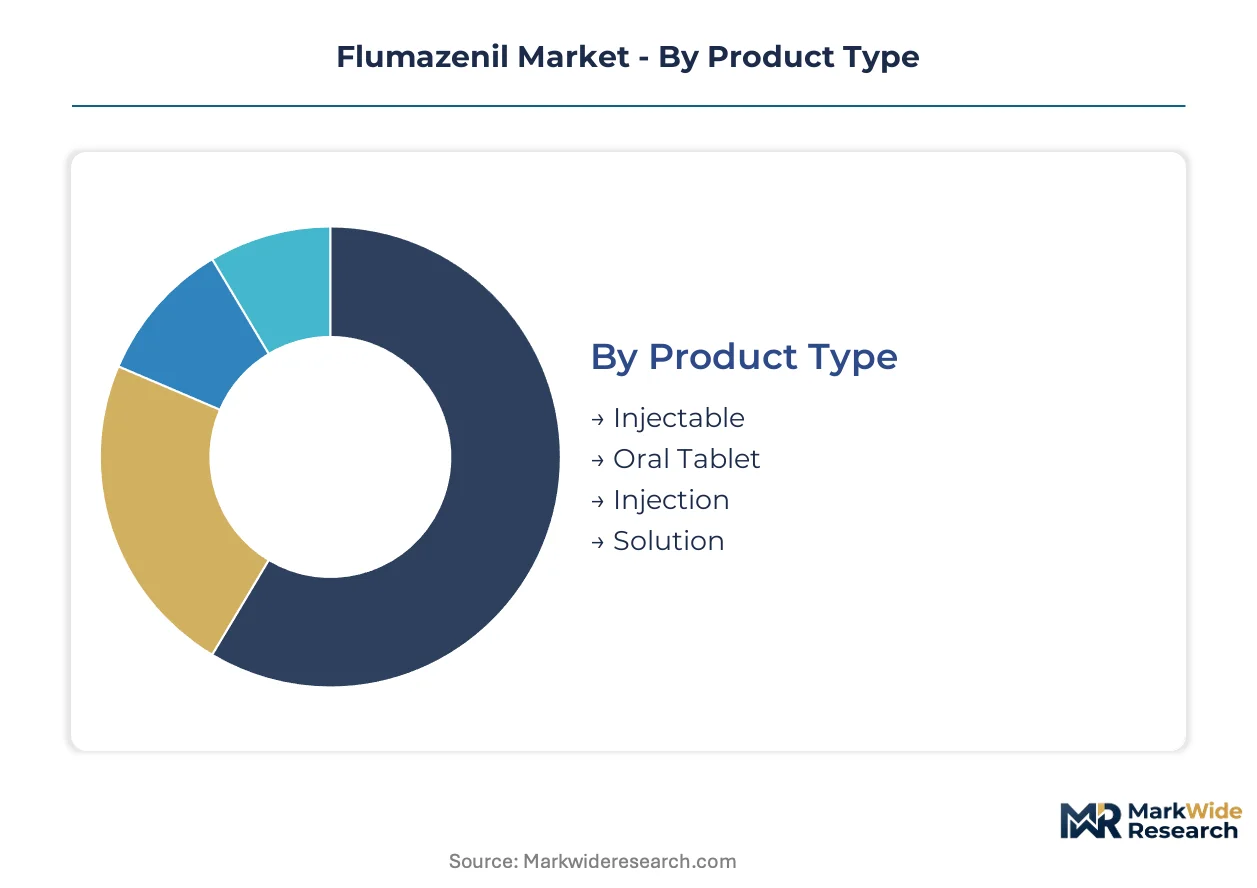
Flumazenil demand fragments across administration routes, clinical settings, and packaging formats that each impose distinct regulatory and supply chain requirements. Understanding these segment boundaries clarifies where pricing power concentrates versus where commoditization pressures dominate.
Product Type:
Injectable formulations anchor domestic hospital procurement in the United States, while oral tablet development targets export markets with limited intravenous infrastructure.
- Injectable:Intravenous solutions at 0.1 mg/mL concentration deliver immediate bioavailability for emergency benzodiazepine reversal. United States hospital emergency departments drive volume through standardized overdose protocols, with FDA bioequivalence requirements shaping generic manufacturer entry decisions.
- Oral Tablet:Sublingual and buccal absorption formats bypass first-pass metabolism for outpatient sedation management. European markets and select Asian jurisdictions with developed primary care networks concentrate demand for non-parenteral alternatives.
- Injection:Concentrated bolus formulations for rapid anesthesia reversal in perioperative settings. Ambulatory surgery centers in Texas and Florida adopt these units for outpatient procedural sedation.
- Solution:Dilute ready-to-use preparations reducing pharmacy compounding burden. Critical care units with limited pharmacy staffing hours favor these formats for just-in-time inventory models.
Injectable commands the established base. The steepest expansion runs through Pre-filled Syringe formats within this category.
Application:
Margin structure inverts across these use cases, with emergency toxicology applications expanding volume while anesthesia protocols retain pricing premiums.
- Overdose Treatment:Polydrug benzodiazepine-opioid co-ingestion cases are embedding flumazenil into standardized reversal algorithms. United States poison control network integration drives protocol harmonization across state emergency medicine systems.
- Anesthesia Reversal:Perioperative sedation termination commands concentrated margin pools through protocol standardization in academic medical centers. Hoffmann La Roche's decades of clinical validation sustain originator positioning in this segment.
- Seizure Management:Off-label utilization for refractory status epilepticus in pediatric intensive care units. Health Canada PMRA label expansion reviews could unlock formal indication status.
- Emergency Care:Pre-hospital administration by paramedic services for field reversal of sedative-hypnotic effects. Intranasal formulation development targets this application for non-intravenous deployment.
Anesthesia Reversal retains the premium pricing tier. Emergency Care applications are climbing the fastest as overdose caseloads reshape hospital formularies.
End User:
Procurement authority concentrates differently across these settings, with integrated delivery networks displacing individual pharmacy negotiations in the largest volume pools.
- Hospitals:Level-one trauma centers and academic medical centers anchor absolute volume through standardized antidote formularies. Group purchasing organization consolidation compresses supplier margins while securing multi-year supply contracts.
- Clinics:Outpatient procedural sedation in gastroenterology and dermatology practices generates concentrated demand for rapid-reversal protocols. Freestanding ambulatory surgery centers in high-growth Sun Belt states expand addressable volume.
- Emergency Rooms:Time-critical overdose scenarios prioritize preparation speed and dosing accuracy over unit cost. Pre-filled syringe adoption rates run highest in this setting.
- Pharmacies:Retail and specialty pharmacy channels for take-home reversal kits in high-risk benzodiazepine prescriptions. Abuse-deterrent packaging requirements shape product configuration.
Hospitals dominate absolute volume. Emergency Rooms are gaining share fastest as protocol standardization accelerates.
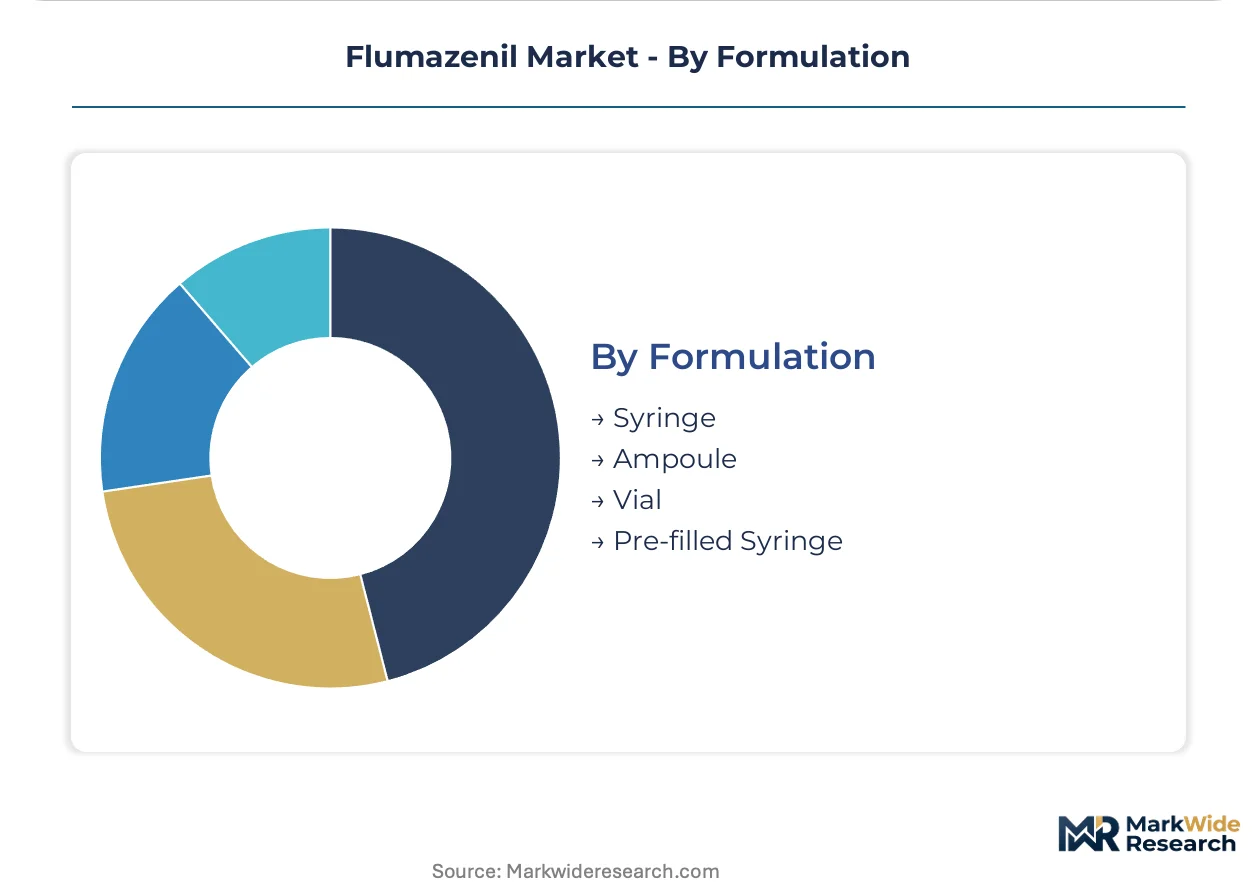
Formulation:
Packaging technology differentiation is displacing historical multi-dose vial dominance through medication error reduction and cold chain integrity improvements.
- Syringe:Conventional luer-lock syringes requiring pharmacy drawing from multi-dose vials. Legacy infrastructure in smaller community hospitals sustains residual demand.
- Ampoule:Glass break-seal units for single-dose emergency administration. European EMA Good Manufacturing Practice Annex 1 revisions tighten environmental monitoring for ampoule production.
- Vial:Multi-dose rubber-stopper containers for pharmacy compounding. Fresenius Kabi USA leverages hospital infusion channel relationships to sustain volume leadership.
- Pre-filled Syringe:Unit-dose formats with integrated needle safety mechanisms reducing preparation latency. Teva Pharmaceutical Industries competes aggressively on generic pricing for these units across North American acute-care procurement networks.
Vial formats command the established base. Pre-filled Syringe configurations are expanding most quickly as critical care units prioritize error reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing clusters in South Asian contract manufacturing organizations feed formulation facilities across North America and Europe. Hospital emergency department procurement patterns diverge sharply by reimbursement infrastructure and poison control network integration depth.
United States
Hospital emergency departments drive absolute volume through standardized benzodiazepine-opioid reversal protocols. FDA ANDA pathways for generic injectables compress approval timelines for domestic manufacturers. Texas and Florida ambulatory surgery centers expand addressable volume beyond traditional hospital channels through rapid-reversal protocol adoption.
Germany
Academic medical centers anchor perioperative anesthesia reversal demand with concentrated margin pools through protocol standardization. EMA Good Manufacturing Practice Annex 1 revisions tighten environmental monitoring for sterile injectable production. Bavarian and Baden-Württemberg hospital procurement consortia consolidate antidote purchasing into system-wide formularies with mandatory generic substitution clauses.
Canada
Health Canada PMRA oversight of benzodiazepine antagonist labeling shapes prescriber training requirements and reimbursement coding alignment. Pediatric sedation reversal indications under regulatory review would unlock neonatal ICU segments currently off-label. Ontario and Quebec integrated delivery networks standardize emergency medicine protocols across provincial health systems.
India
Contract manufacturing organizations concentrate active pharmaceutical ingredient production for generic injectable supply. CDSCO regulatory harmonization with ICH standards accelerates export qualification for formulation facilities. Hyderabad and Ahmedabad clusters supply intermediate chemical streams to European and North American finished dose manufacturers.
Switzerland
Originator compound clinical validation archives sustain premium positioning in anesthesia reversal segments. Swissmedic oversight of sterile medicinal product manufacturing maintains supply qualification standards for European hospital procurement. Basel-region pharmaceutical infrastructure anchors decades of benzodiazepine receptor antagonist development heritage.
Flumazenil Market Competitive Landscape
Concentration sits with hospital infusion channel specialists and generic injectable scale manufacturers. The vendor base splits between originator compound archives and high-volume commodity suppliers. Three archetypes dominate: originator heritage players with decades of clinical validation, hospital channel incumbents leveraging GPO relationships, and aggressive generic pricers competing on procurement network penetration. Competitive moves center on pre-filled syringe format launches and sterile manufacturing capacity expansion.
Within the originator heritage tier, Hoffmann La Roche anchors decades of clinical validation in perioperative sedation reversal. Among North American generic injectable specialists, Fresenius Kabi USA occupies hospital infusion channel dominance while Teva Pharmaceutical Industries Ltd. competes on aggressive pricing across acute-care procurement networks. These three entities exemplify the strategic archetypes reshaping competitive positioning.
| Leading Market Players |
|---|
| Hoffmann La Roche |
| Fresenius Kabi USA |
| Sandoz Canada Incorporated |
| Mylan Pharmaceuticals |
| Genentech |
| West Ward Pharmaceutical |
| Pfizer Laboratories Div Pfizer Inc. |
| Hikma Pharmaceuticals |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day API inventory buffers at North American formulation facilities compress margin flexibility for generic injectable manufacturers while amplifying pricing power for hospital channel incumbents with captive supply arrangements. This lead-time structure concentrates procurement leverage among integrated delivery networks capable of absorbing cold chain validation costs.
Pricing Analysis
FDA ANDA bioequivalence requirements dictate the pricing tier structure across originator, first-generic, and multi-source generic strata. Pricing stratifies across premium validated-originator, standard FDA-approved generic, and economy non-branded commodity tiers based on sterile manufacturing certification status and GPO contract penetration. Cost compression in the economy tier is intensifying because hospital procurement consortia mandate substitution clauses. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with protocol standardization requirements show lowest.
Supply Chain Analysis
Sixty-to-ninety-day API inventory cycles expose formulation facilities to temperature excursion risks during transoceanic transit. Active pharmaceutical ingredient production draws from India, China, and Italy, with imidazobenzodiazepine intermediate synthesis concentrated in Hyderabad and Ahmedabad clusters. Supply chain vulnerability centers on single-source dependence for sterile filtration membranes and rubber-stopper vial components. Distribution runs through hospital GPO contracts and specialty pharmaceutical wholesalers with cold chain monitoring infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flumazenil sits in early-cycle expansion as emergency medicine protocols embed benzodiazepine antagonism into standardized polydrug overdose algorithms, expanding addressable patient volume beyond legacy anesthesia applications.
For Market Incumbents: Consolidate sterile manufacturing capacity in FDA-registered facilities to preempt ANDA entrants facing extended qualification timelines. Deepen backward integration into API supply through captive relationships with South Asian contract manufacturing organizations. Lock in multi-year GPO contracts before intranasal formulation substitutes reach regulatory submission. For New Entrants and Emerging Players: Anchor in pre-filled syringe format development for emergency room procurement channels where preparation speed commands premium positioning. Texas and Florida ambulatory surgery centers represent the most penetrable white-space geography with rapid-reversal protocol adoption curves. Pursue Health Canada PMRA label expansion for pediatric indications as differentiation angle against entrenched hospital incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a defensive healthcare infrastructure play because benzodiazepine misuse trajectories and emergency medicine protocol standardization create durable volume baselines. Target acquisition profile: sterile injectable specialists with FDA aseptic facility certification and existing hospital GPO relationships. Watch intranasal formulation clinical trial readouts as inflection signal for administration modality displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-filled Syringe Manufacturing Scale-Up | Reduces medication errors in level-one trauma centers and accelerates emergency department adoption. |
| FDA ANDA Pathway Navigation | Compresses approval timelines for generic injectables and enables price competition in hospital procurement. |
| Intranasal Formulation Development | Opens paramedic pre-hospital administration channel beyond intravenous infrastructure constraints. |
| Health Canada PMRA Label Expansion | Unlocks neonatal ICU and pediatric emergency segments currently restricted to off-label utilization. |
| Hospital GPO Contract Consolidation | Secures multi-year supply commitments through integrated delivery network formulary standardization. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with emergency medicine physicians, hospital pharmacy directors, GPO contracts managers, and regulatory affairs specialists; and secondary validation through FDA ANDA filings, EMA GMP inspection records, Health Canada PMRA submission databases, and hospital procurement consortium contract disclosures. Bottom-up patient volume modeling and top-down pharmaceutical market sizing were triangulated against sterile injectable production capacity estimates.
Across the analysis window, the forecast framework applied treatment line segmentation by emergency versus perioperative application, formulation type by vial versus pre-filled syringe, and regional regulatory cluster by FDA, EMA, and Health Canada jurisdictions. CAGRs were derived from protocol adoption curve analysis and generic entry timing assumptions. Key inputs included poison control network integration rates and ambulatory surgery center procedural volume trajectories.
Decision-makers should treat outputs as directional under assumptions of stable benzodiazepine prescription prevalence and continued emergency medicine protocol harmonization; material deviation in polydrug overdose epidemiology or intranasal substitute approval timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Germany Pharmaceuticals Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Migraine Drugs Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Targeted Therapeutics Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market