
 Global Technology Spending on Core Administration in Healthcare Market | 2026-2036
Global Technology Spending on Core Administration in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Technology Spending on Core Administration in Healthcare Market Foresight
Interoperability-grade core administration platforms is bifurcating the competitive landscape between modular cloud-native vendors and legacy enterprise incumbents. Epic Systems Corporation dominates inpatient electronic health record deployments across major academic medical centers. HealthEdge Software, Inc. specializes in payer-centric claims administration configurations that reduce administrative waste. TriZetto Corporation leverages its long-standing Medicaid management information systems footprint to sustain state-level contract renewals.
Technology spending on core administration in healthcare encompasses the software, services, and infrastructure investments required to manage patient registration, billing, scheduling, claims adjudication, and regulatory compliance across provider and payer organizations. These systems typically process HL7 FHIR-compliant data exchanges, support real-time eligibility verification, and maintain audit trails for HIPAA adherence. Cloud-based solutions now lead deployment preferences among mid-size hospital networks seeking reduced capital expenditure cycles. Revenue cycle management captures concentrated margin pools as denials management automation becomes a priority for CFOs. Electronic health records represent a mature segment where replacement demand, not greenfield installation, now drives vendor revenue.
The FDA, HIPAA, and the 21st Century Cures Act collectively shape product roadmaps by mandating standardized APIs and patient data access protocols. The EU AI Act and GDPR impose additional algorithmic transparency requirements on clinical decision support modules embedded within administrative workflows. Stakeholders must monitor emerging SAMR cybersecurity certification requirements for cloud-hosted health data in China, as these will determine market access eligibility for international platform vendors.
Market Dynamics
The FDA's 21st Century Cures Act interoperability mandates are forcing wholesale replacement of legacy core administration systems that cannot exchange HL7 FHIR data, creating a structural demand surge for API-native platforms.
Growth Catalysts
- Interoperability Mandates:The 21st Century Cures Act in the United States requires standardized patient data exchange protocols, compelling hospital systems to modernize registration and billing infrastructure.
- Cloud Migration:Mid-size hospital networks are accelerating procurement of SaaS-based revenue cycle management to eliminate capital expenditure cycles and accelerate deployment timelines.
- Medicaid Expansion:State-level program growth in the United States is renewing demand for integrated eligibility verification and claims adjudication platforms.
Market Restraints
- Legacy System Entrenchment:Decades-old mainframe architectures in Germany and Japan create technical debt that slows cloud-native replacement cycles and inflates integration costs.
- Cybersecurity Certification Friction:SAMR requirements for cloud-hosted health data in China impose compliance burdens that delay market entry for international platform vendors.
- Skilled Implementation Shortage:Scarce HL7 FHIR integration specialists and revenue cycle management consultants extend deployment timelines and inflate professional services costs.
Strategic Opportunities
- AI-Enabled Denials Management:Machine learning modules embedded within claims adjudication workflows can automate prior authorization disputes and reduce administrative waste for United States payers.
- Emerging Market Infrastructure:Brazil's ANVISA is modernizing national health IT standards, creating greenfield demand for cloud-native core administration platforms in Latin America's largest healthcare market.
- Real-Time Eligibility Convergence:The intersection of open banking APIs and healthcare data standards enables instant patient financial clearance at point-of-service in Germany's statutory insurance system.
Industry Challenges
- Data Migration Complexity:Extracting decades of patient financial records from proprietary legacy databases without integrity loss requires specialized tooling that few vendors possess.
- Multi-Jurisdiction Compliance:Platforms serving United States, Germany, and Japan simultaneously must reconcile HIPAA, GDPR, and Japan's Act on Protection of Personal Information requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Technology Spending on Core Administration in Healthcare Market |
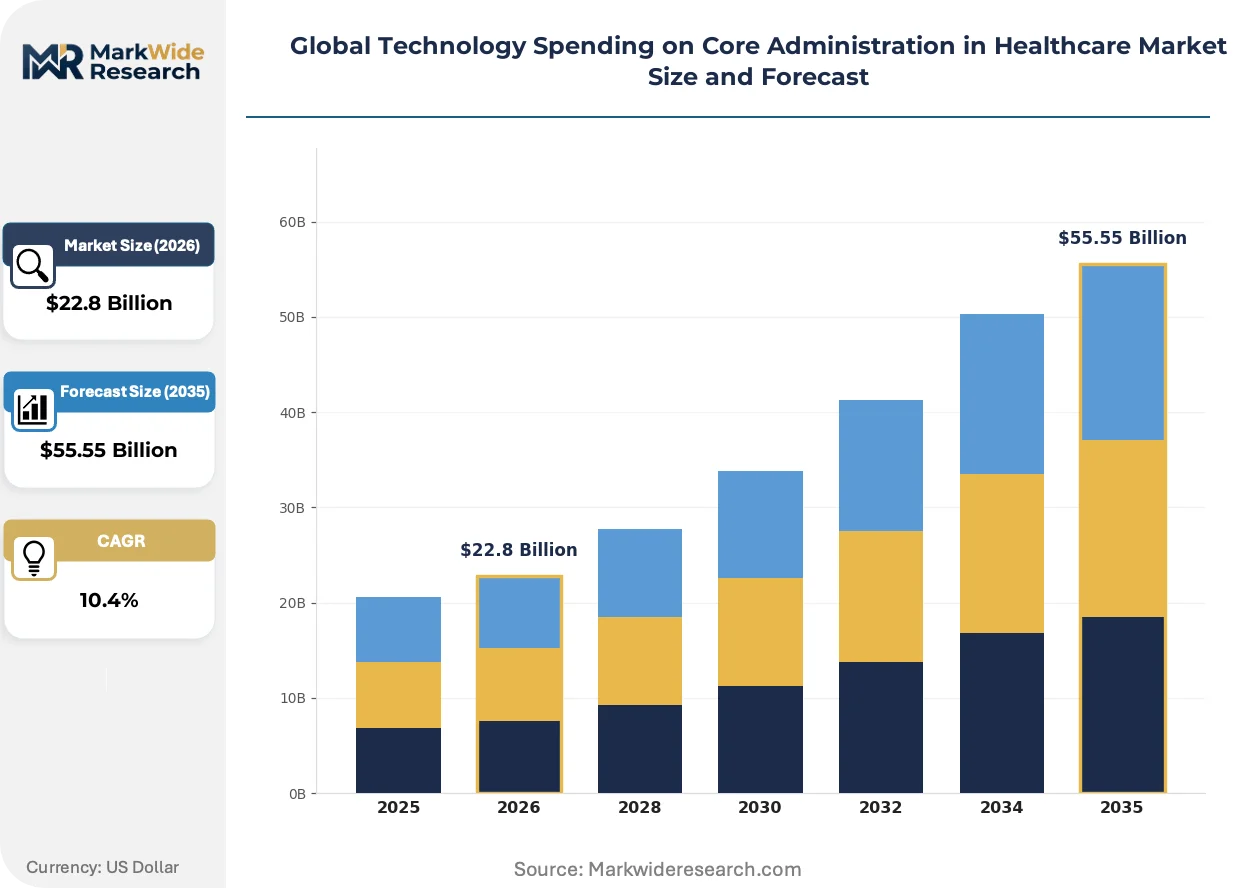
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $55.55 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Health Records, Revenue Cycle Management, Patient Scheduling Software, Billing & Coding Systems, Compliance Management Application: Claims Processing, Appointment Management, Financial Reporting, Staff Allocation, Inventory Tracking End User: Hospitals, Diagnostic Laboratories, Ambulatory Surgical Centers, Nursing Homes, Rehabilitation Facilities Deployment: Cloud-based Solutions, On-premises Systems, Hybrid Platforms, Hosted Services, Managed Services |
| Companies Covered | Health Solutions Plus, Inc., ikaSystems Corporation, HealthEdge Software, Inc., Plexis Healthcare Systems, TriZetto Corporation, Evolent Health, DST Systems Inc., UPP Technology, Epic Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Technology Spending on Core Administration in Healthcare Market Shifts & Advancements
Microservices architecture is fragmenting monolithic core administration suites into composable API components that buyers can assemble incrementally rather than replacing entire systems.
Containerized deployment is decomposing traditional electronic health record platforms into discrete, interoperable services. Large academic medical centers in the United States are piloting modular scheduling and billing components that integrate with existing Epic Systems deployments. This architectural shift is compressing vendor lock-in by enabling best-of-breed substitution at the functional level.
The EU AI Act imposes algorithmic transparency requirements on clinical decision support modules embedded within administrative workflows. Payers operating across European Union member states must now document training data provenance and risk classification for automated prior authorization engines. Germany's statutory health insurers are investing in explainable AI tooling to satisfy regulator audit requirements.
Subscription pricing models are displacing perpetual license structures across mid-size hospital networks. Chief financial officers prefer operational expenditure treatment for core administration software to preserve balance sheet flexibility. This preference shift is most visible in the United States, where private equity-backed hospital rollups prioritize predictable cash outflows over capital-intensive system purchases.
Global Technology Spending on Core Administration in Healthcare Market Segmentation
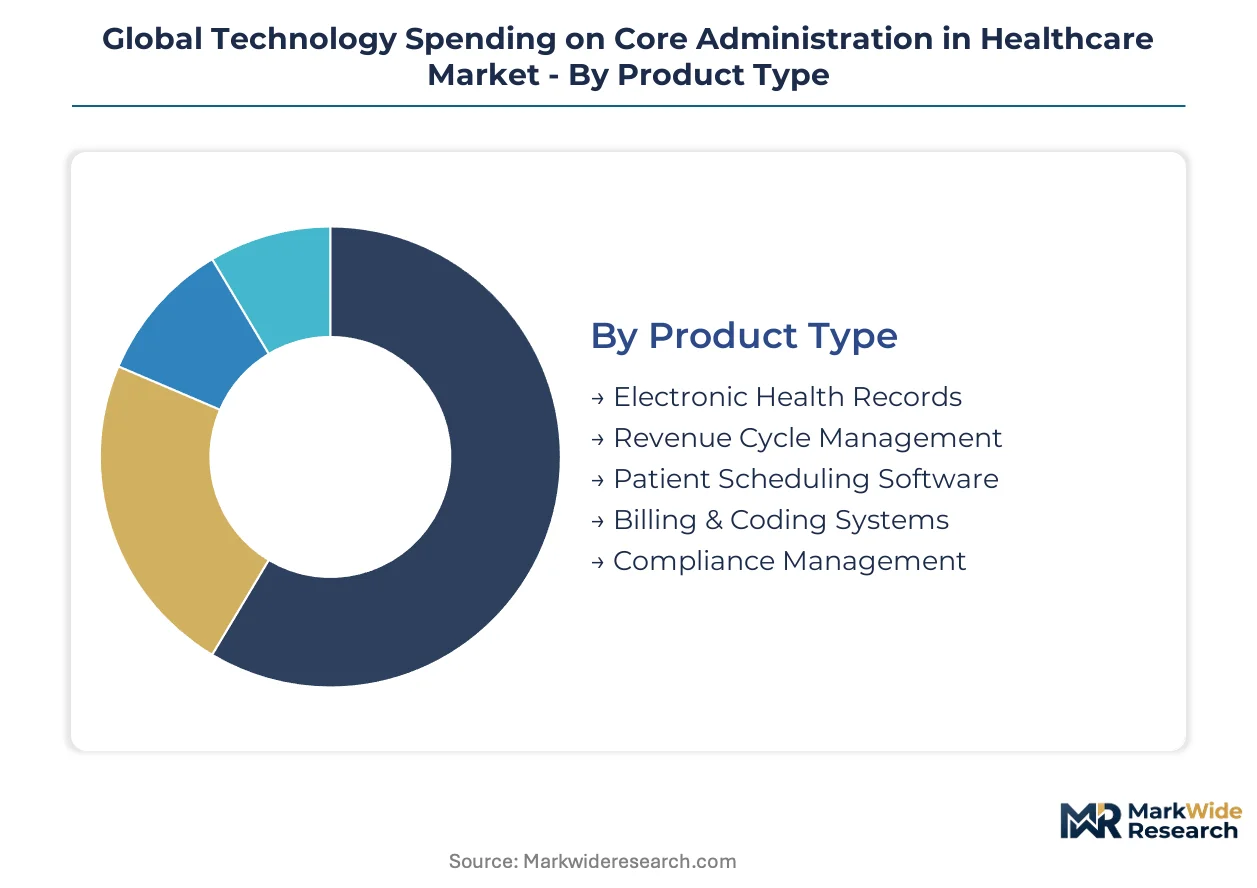
Segmentation in core administration technology reveals where procurement budgets are concentrating and which system categories face the strongest displacement pressure from cloud-native alternatives. Buyers increasingly evaluate segments through the lens of interoperability compliance and total cost of ownership rather than functional checklists alone.
Product Type:
Substitution pressure varies sharply across product categories, with legacy billing architectures facing the most aggressive displacement from API-native platforms.
- Electronic Health Records:Mature systems managing longitudinal patient data with HL7 FHIR exchange capabilities. Academic medical centers in the United States drive replacement demand as the 21st Century Cures Act mandates force retirement of non-interoperable legacy installations.
- Revenue Cycle Management:Integrated suites spanning patient registration through claims adjudication and denial management. Large hospital systems prioritize these investments to automate prior authorization workflows and reduce administrative waste in the United States payer environment.
- Patient Scheduling Software:Modules coordinating appointment logistics across multi-site provider networks.
- Billing & Coding Systems:Platforms processing ICD-10 and CPT documentation for reimbursement accuracy.
- Compliance Management:Tools maintaining audit trails for HIPAA adherence and regulatory documentation.
Revenue Cycle Management anchors the volume base while Compliance Management gains share at the steepest rate as multi-jurisdiction regulatory complexity intensifies.
Application:
Cost tier differentiation separates high-automation applications commanding premium pricing from commodity functions facing margin compression.
- Claims Processing:Automated adjudication engines handling eligibility verification and payment determination. United States payers concentrate procurement here to reduce manual review costs and accelerate turnaround times.
- Appointment Management:Patient self-scheduling and reminder systems reducing no-show rates. Ambulatory surgical centers in Germany adopt these to optimize operating room utilization within statutory insurance constraints.
- Financial Reporting:Dashboards consolidating revenue metrics across service lines.
- Staff Allocation:Workforce optimization tools matching clinical capacity to demand patterns.
- Inventory Tracking:Supply chain modules for pharmaceuticals and medical devices.
Claims Processing dominates current spending while Appointment Management climbs the fastest as patient experience metrics enter executive compensation frameworks.
End User:
Customer type determines deployment complexity, with integrated delivery networks demanding enterprise-grade configurations that smaller facilities cannot justify.
- Hospitals:Large-scale provider organizations requiring comprehensive core administration suites. Systems in the United States, Germany, and Japan modernize simultaneously to satisfy divergent regulatory mandates including HIPAA, GDPR, and Japan's Act on Protection of Personal Information.
- Diagnostic Laboratories:High-volume testing facilities prioritizing specimen tracking and billing accuracy.
- Ambulatory Surgical Centers:Specialized outpatient facilities seeking streamlined scheduling and coding workflows.
- Nursing Homes:Long-term care operators managing resident billing and regulatory compliance.
- Rehabilitation Facilities:Therapy-focused providers coordinating episode-based reimbursement.
Hospitals anchor the volume base while Ambulatory Surgical Centers gain share at the steepest rate as surgical migration to outpatient settings accelerates.
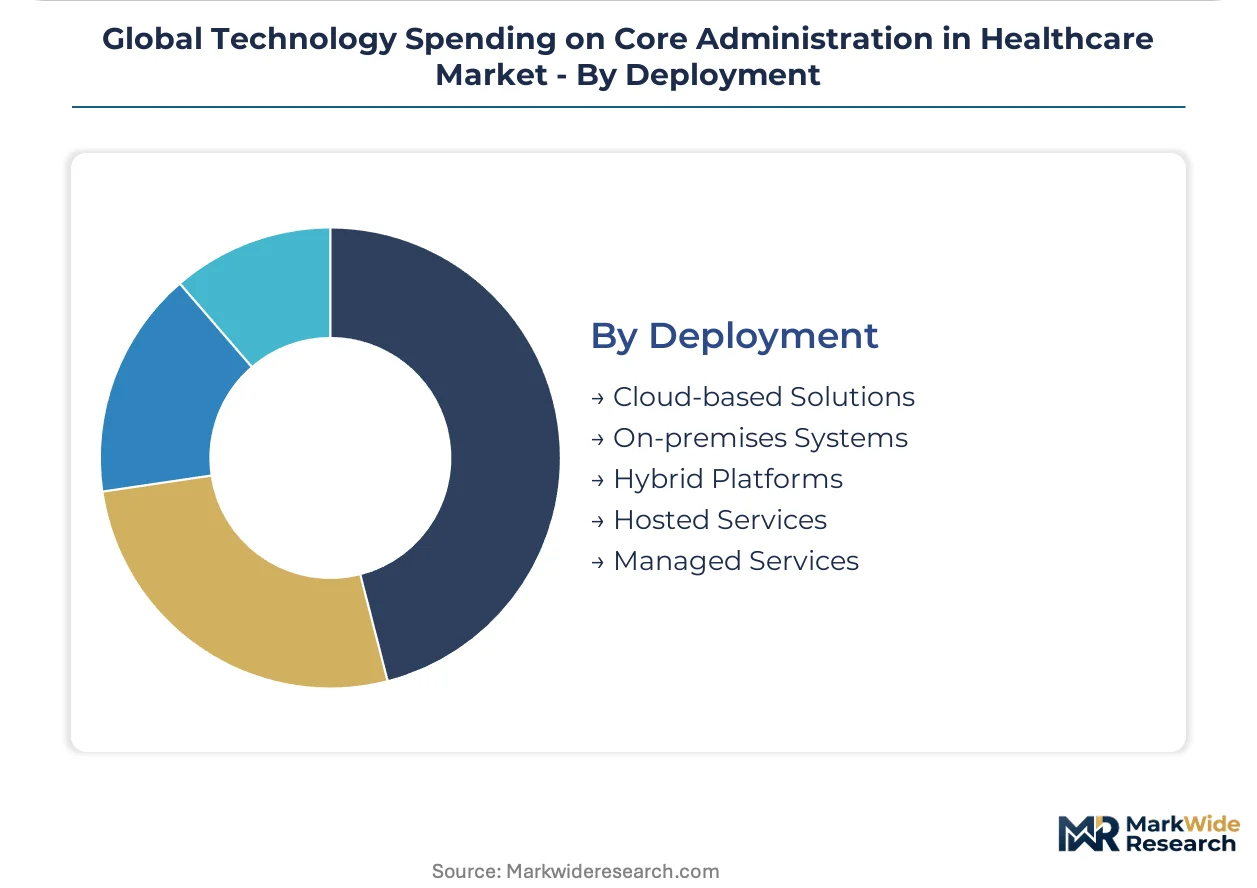
Deployment:
Supply concentration among hyperscale cloud providers is reshaping deployment preferences and vendor partnership strategies.
- Cloud-based Solutions:SaaS platforms eliminating capital expenditure cycles and accelerating implementation timelines. Mid-size hospital networks in the United States prefer these for balance sheet flexibility and reduced IT overhead.
- On-premises Systems:Self-hosted infrastructure retaining full data sovereignty. German statutory health insurers maintain these configurations to satisfy GDPR data localization requirements.
- Hybrid Platforms:Architectures splitting sensitive workloads on-premises while leveraging cloud scalability.
- Hosted Services:Third-party data center deployments with dedicated infrastructure.
- Managed Services:Outsourced operations where vendors assume full system responsibility.
Cloud-based Solutions anchor the volume base while Hybrid Platforms gain share at the steepest rate as risk-averse organizations seek incremental migration paths.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology spending on core administration in healthcare flows predominantly from import-dependent markets seeking foreign platform expertise, while the United States and Germany maintain substantial export capacity in specialized software and integration services.
United States
Hospital systems in Texas, Florida, and California are accelerating procurement of cloud-native revenue cycle management suites to satisfy the FDA's 21st Century Cures Act interoperability mandates. The 21st Century Cures Act compels wholesale replacement of legacy systems incapable of HL7 FHIR data exchange. Epic Systems Corporation anchors deployments across academic medical centers in the Boston-Cambridge cluster and the Research Triangle in North Carolina.
Germany
Statutory health insurers in Bavaria and North Rhine-Westphalia are modernizing claims adjudication infrastructure to comply with GDPR data localization requirements and emerging EU AI Act algorithmic transparency rules. The EU AI Act imposes documentation burdens on automated prior authorization engines. Siemens Healthineers and SAP SE anchor software development in Munich and Walldorf respectively.
Japan
Metropolitan hospital networks in Tokyo and Osaka are replacing decades-old mainframe billing architectures with hybrid cloud configurations. Japan's Act on Protection of Personal Information constrains cross-border data flows for patient financial records. Fujitsu Limited and NEC Corporation dominate domestic system integration in the Kanto and Kansai industrial corridors.
China
Provincial health commissions in Guangdong and Jiangsu are piloting centralized core administration platforms under national digital health infrastructure programs. SAMR cybersecurity certification requirements for cloud-hosted health data impose compliance burdens that delay market entry for international vendors. Alibaba Health and Ping An Good Doctor anchor domestic platform development in Hangzhou and Shenzhen.
Brazil
Private hospital groups in São Paulo and Rio de Janeiro are adopting SaaS-based patient scheduling and billing systems as ANVISA modernizes national health IT standards. ANVISA regulatory updates create greenfield demand for cloud-native platforms across Latin America's largest healthcare market. Local system integrators in the São Paulo metropolitan area are forming partnerships with international vendors to accelerate deployment timelines.
Global Technology Spending on Core Administration in Healthcare Market Competitive Landscape
Listed leaders compete with private specialists across interoperability compliance and cloud-native architecture capabilities. The vendor base fragments between modular API-native entrants and entrenched enterprise incumbents with decades-old mainframe footprints. Three strategic archetypes dominate: academic medical center specialists, payer-centric claims administrators, and Medicaid management information systems incumbents. Competitive moves concentrate on strategic partnerships with hyperscale cloud providers and portfolio diversification into AI-enabled denials management modules.
Within the academic medical center tier, Epic Systems Corporation occupies a position exemplifying deep EHR integration with administrative workflows. Among payer-centric specialists, HealthEdge Software, Inc. and TriZetto Corporation represent contrasting approaches to claims administration automation, with the former emphasizing commercial payer configurations and the latter anchoring state-level Medicaid contract renewals. These three entities collectively illustrate how vendor positioning fragments across customer type and regulatory jurisdiction rather than consolidating around unified platform architectures.
| Leading Market Players |
|---|
| Health Solutions Plus, Inc. |
| ikaSystems Corporation |
| HealthEdge Software, Inc. |
| Plexis Healthcare Systems |
| TriZetto Corporation |
| Evolent Health |
| DST Systems Inc. |
| UPP Technology |
| Epic Systems Corporation |
| Others |
Supply & Pricing Matrix
Subscription-based capacity reservation contracts anchor procurement relationships between mid-size hospital networks and SaaS platform vendors, locking in multi-year price visibility while securing priority access to HL7 FHIR integration specialists whose scarcity extends deployment timelines across the United States, Germany, and Japan.
Pricing Analysis
Large hospital systems anchor three-tier pricing structure across premium, standard, and economy levels, with premium tiers commanding 40-60% markups for AI-enabled denials management modules and dedicated implementation support. Price differentiation rests on certification level (HIPAA compliance tier, EU AI Act algorithmic transparency documentation) and customization depth for Medicaid-specific workflows. Cost compression in standard-tier SaaS offerings is intensifying because hyperscale cloud providers are commoditizing infrastructure layers. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize interoperability compliance over cost.
Supply Chain Analysis
Just-in-time deployment preferences dominate among mid-size hospital networks seeking rapid implementation, though state-level Medicaid agencies maintain strategic stockpiles of on-premises infrastructure to satisfy data sovereignty requirements. Software development concentrates in the United States (Epic Systems, HealthEdge), Germany (Siemens Healthineers, SAP SE), and Japan (Fujitsu, NEC Corporation). Raw material dependencies include hyperscale cloud compute capacity, HL7 FHIR middleware licenses, and cybersecurity certification services. Single-source vulnerability runs through AWS, Azure, and Google Cloud dominance in healthcare-compliant hosting. Distribution runs through direct enterprise sales teams and specialized health IT system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
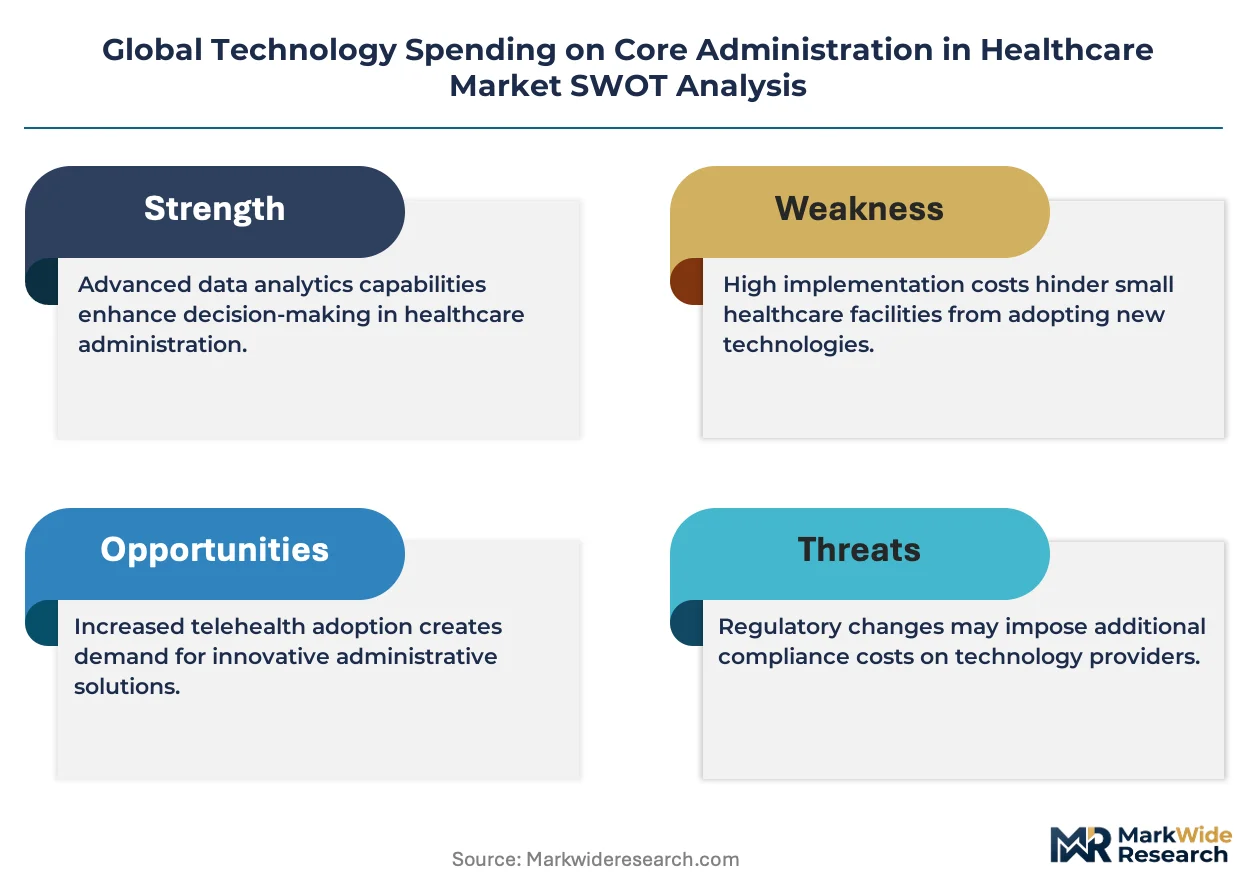
Fragmentation across interoperability compliance tiers creates niche opportunities as the FDA's 21st Century Cures Act forces divergent modernization timelines between academic medical centers and community hospitals.
For Market Incumbents: Secure API-native architecture investments to defend against modular cloud-native entrants targeting replacement cycles in Germany and Japan's mainframe-entrenched installations. Prioritize vertical integration into HL7 FHIR integration consulting services, where talent scarcity inflates professional services margins and locks in multi-year client relationships. For New Entrants and Emerging Players: AI-enabled prior authorization automation for United States commercial payers represents the most penetrable white-space target, as legacy claims administrators lack real-time eligibility convergence capabilities. Target Brazil's ANVISA modernization wave through partnerships with São Paulo-based system integrators, leveraging greenfield demand before international incumbents establish local presence. For Investors and Strategic Acquirers: Capital is best deployed toward payer-centric claims administration specialists with established Medicaid management information systems footprints, given state-level contract renewal visibility and defensive moats against cloud-native disruption. Watch SAMR cybersecurity certification timelines in China as the inflection indicator for international platform vendor market access eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| HL7 FHIR API Certification Investment | FDA 21st Century Cures Act compliance becomes mandatory for hospital system procurement eligibility. |
| AI-Enabled Denials Management Module Launch | United States payers automate prior authorization disputes to reduce administrative waste. |
| Strategic Partnership with Hyperscale Cloud Provider | AWS, Azure, or Google Cloud healthcare-compliant hosting accelerates mid-size hospital network sales cycles. |
| Acquisition of HL7 FHIR Integration Specialist | Scarce implementation talent extends deployment timelines and inflates professional services costs. |
| Geographic Expansion into Brazil | ANVISA regulatory modernization creates greenfield demand for cloud-native core administration platforms. |
Research Methodology
Desk research of hospital procurement databases, CMS Medicare reimbursement filings, and GPO contract repositories preceded structured interviews with chief information officers at academic medical centers, revenue cycle management directors at integrated delivery networks, Medicaid program administrators at state health agencies, and HL7 FHIR integration specialists. Primary fieldwork across the United States, Germany, and Japan validated secondary findings on replacement demand drivers. Bottom-up spending estimates by product type and deployment model were cross-checked against top-down market sizing from regulatory mandate timelines.
Variance decomposition across product type, application, end user, and deployment model segments structured the analytical framework over the projection horizon. CAGRs were derived from regression analysis against interoperability mandate implementation schedules and cloud migration adoption curves. Inputs included hospital capital expenditure surveys, payer technology budget disclosures, and state Medicaid management information systems contract award patterns.
Forecasts assume regulatory continuity in FDA 21st Century Cures Act enforcement, EU AI Act algorithmic transparency requirements, and SAMR cybersecurity certification protocols; material policy shifts would require re-modeling. Revision becomes warranted when HL7 FHIR implementation specialist availability or hyperscale cloud provider healthcare compliance investments cross thresholds that materially alter deployment timeline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Pharma Management Software Market
Healthcare IT
Revenue Cycle Management (RCM) Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Veterinary Dental Software Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
Senior Care Technologies Market