
 Healthcare Mobility Solutions Market | 2026-2036
Healthcare Mobility Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Mobility Solutions Market Intelligence
Subscription-based software access for clinical data management is pivoting the market away from one-time hardware sales toward recurring revenue models. Oracle Corporation leverages its enterprise software expertise to offer integrated cloud-based health platforms that manage electronic health records. Zebra Technologies Corporation specializes in ruggedized mobile workstations and scanners purpose-built for demanding hospital environments. Cisco Systems, Inc. provides the secure network infrastructure essential for reliable mobile connectivity across large medical campuses.
Healthcare mobility solutions are integrated systems of hardware, software, and communication technologies enabling remote access to clinical workflows and patient data. These platforms utilize secure network protocols like Wi-Fi and 5G to transmit encrypted patient information compliant with data privacy standards. Remote monitoring tools and wearable devices represent the fastest-growing product categories, driven by the expansion of telemedicine and preventative care. While hospitals remain the largest end-user segment by volume, home care providers offer significant margin opportunities due to lower overhead.
Data security and patient privacy regulations, including HIPAA in the United States and the GDPR in Europe, strictly govern solution design and data handling. Medical device approvals from bodies like the US FDA, the European Medicines Agency (EMA), and Japan's PMDA are required for diagnostic-grade remote monitoring tools. Stakeholders must now decide between developing proprietary platforms or partnering with established technology vendors to ensure compliance and future interoperability.
Market Dynamics
The central dynamic shaping the healthcare mobility market is the tension between the technological push for real-time, ubiquitous data access via 5G and IoT devices, and the regulatory pull for stringent data security and patient privacy compliance under frameworks like HIPAA and GDPR.
Growth Catalysts
- Telemedicine Expansion:The broader acceptance of remote consultations and diagnosis drives investment in mobile platforms that connect patients with providers, especially within chronic disease management programs in developed economies.
- 5G Network Deployment:The rollout of 5G infrastructure in urban centers across the United States, South Korea, and parts of Europe enables the low-latency, high-bandwidth connectivity required for real-time remote monitoring and data-intensive medical imaging applications.
- Government Digital Health Initiatives:Mandates and incentives promoting the adoption of electronic health records (EHRs) and interoperable data systems, such as those in the US and Germany, compel providers to invest in mobile solutions for clinical data access.
Market Restraints
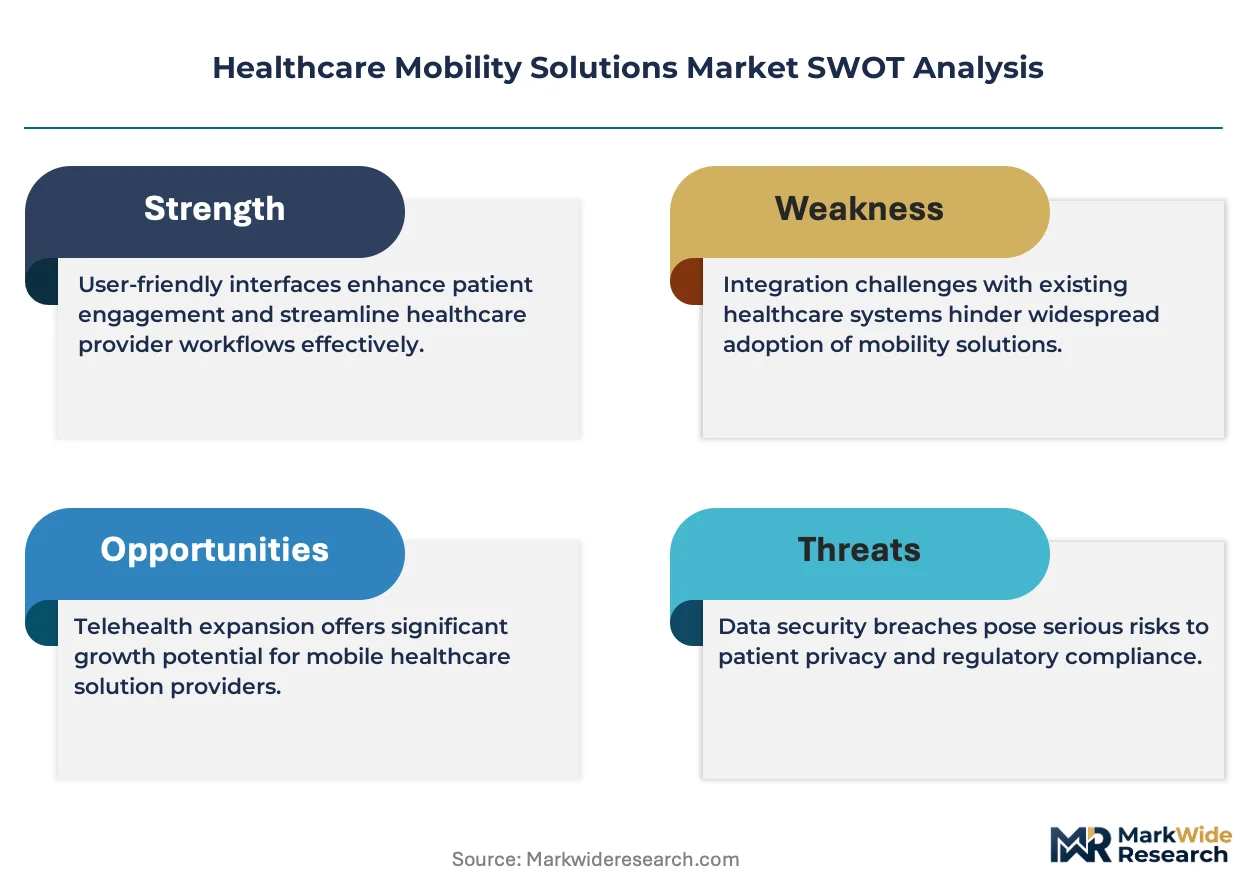
- High Implementation Costs:The significant upfront capital investment required for secure network infrastructure, ruggedized mobile devices, and enterprise-grade software platforms presents a substantial barrier for smaller clinics and hospitals with limited budgets.
- Stringent Regulatory Hurdles:Navigating the complex and time-consuming approval processes for medical-grade mobile applications and devices from regulatory bodies like the US FDA and the European Medicines Agency (EMA) can delay product launches and increase development costs.
- Data Interoperability Issues:A lack of universal standards for data exchange between disparate mobile health applications and legacy hospital IT systems creates data silos, limiting the effectiveness of integrated care delivery and analytics.
Strategic Opportunities
- Predictive Analytics Integration:Developing software that leverages AI and machine learning to analyze data from mobile and wearable devices offers the opportunity to provide predictive insights for early intervention and personalized patient care.
- Emerging Market Penetration:Targeting healthcare providers in regions like Southeast Asia and Latin America, where mobile-first infrastructure can leapfrog the need for extensive wired networks, presents a significant growth avenue.
- Specialized Home Care Solutions:Creating tailored mobility solutions for the growing home care segment, focusing on user-friendly interfaces for elderly patients and robust remote monitoring tools for chronic conditions, addresses a high-margin niche.
Industry Challenges
- Cybersecurity Vulnerabilities:Protecting sensitive patient health information from increasingly sophisticated cyberattacks requires continuous and costly investment in advanced encryption, threat detection, and secure network protocols, posing a major operational challenge. *Integration with Legacy Systems: The complexity of integrating new mobile platforms with existing, often outdated, hospital electronic health record (EHR) and administrative systems can lead to implementation delays, cost overruns, and workflow disruptions.
- Clinical Informatics Talent Gap:A shortage of skilled professionals who possess expertise in both clinical workflows and data analytics hinders the ability of healthcare organizations to fully leverage the data generated by mobility solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Mobility Solutions Market |
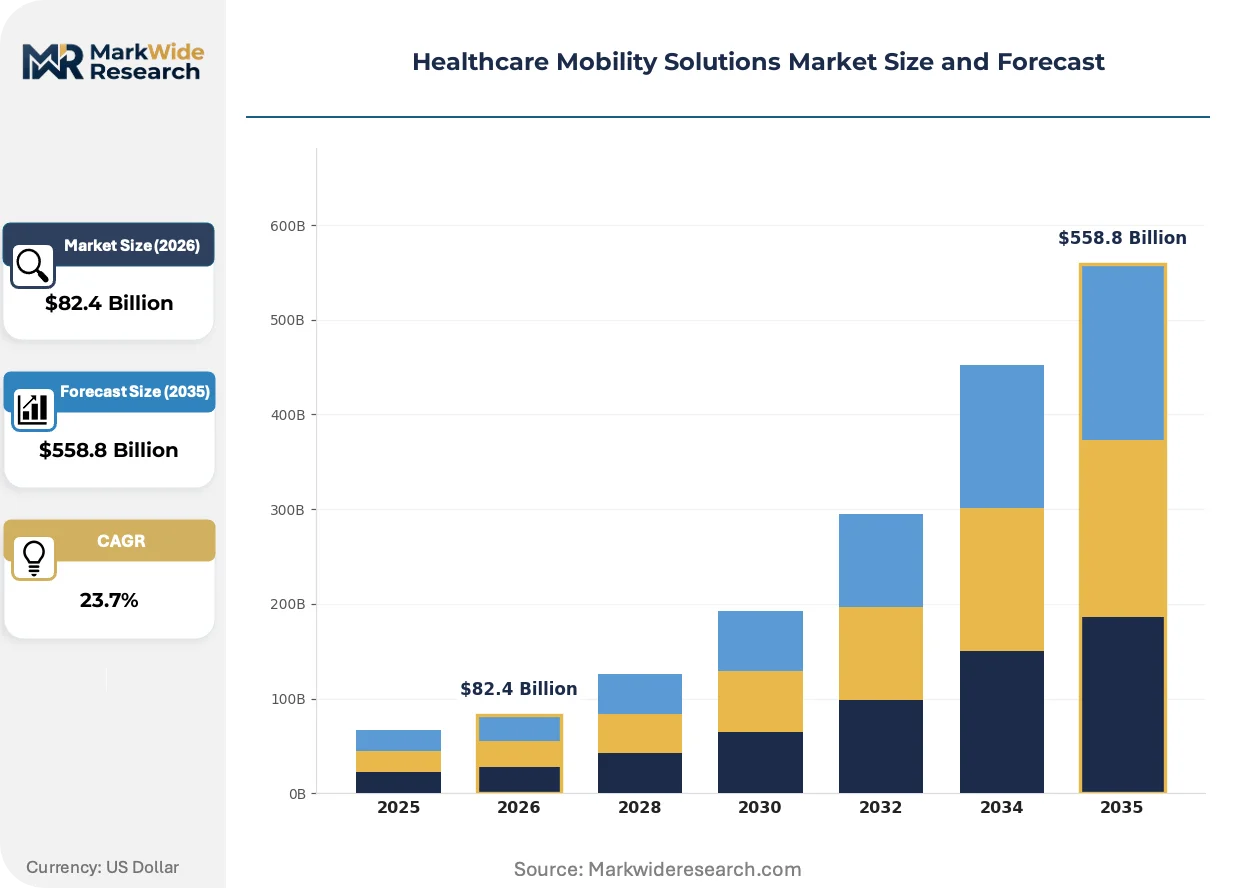
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $558.8 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Workstations, Wearable Devices, Remote Monitoring Tools, Communication Systems Technology: Bluetooth, Wi-Fi, NFC, 5G Networks, RFID Application: Patient Monitoring, Telemedicine, Emergency Response, Clinical Data Management End User: Hospitals, Outpatient Clinics, Home Care Providers, Diagnostic Centers |
| Companies Covered | McKesson Corporation, Oracle Corporation, Koninklijke Philips N.V., Cisco Systems, Inc., OMRON Healthcare, Inc., Cerner Corporation, Zebra Technologies Corporation, Apple Inc., SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Mobility Solutions Market Strategic Shifts & Innovations
Software and recurring revenue models are redefining competitive advantage, shifting focus from one-time hardware sales to integrated platforms that deliver continuous clinical value. This pivot emphasizes data management, security, and interoperability as core competencies for market leadership.
Edge computing is a pivotal technology for processing patient data. This approach allows for data analysis to occur on or near the mobile device itself, drastically reducing latency for time-sensitive applications. Hospital systems are adopting this for real-time patient monitoring and in-ambulance diagnostics. Edge computing is unifying data from disparate bedside monitors and wearable sensors into a coherent, actionable stream at the point of care.
The European Union's Medical Device Regulation (MDR) has elevated the compliance burden for software used in a clinical context. It mandates more rigorous clinical evidence and post-market surveillance for software as a medical device (SaMD). This directly affects developers of diagnostic and monitoring applications, who must now allocate greater resources to clinical validation and quality management to secure and maintain CE marking.
A transition from capital expenditure (CapEx) to operational expenditure (OpEx) models is reshaping procurement. Healthcare organizations are increasingly opting for subscription-based "device-as-a-service" bundles that include hardware, software, and support. This model is most visible in large hospital networks in the United States and Germany, which prefer predictable costs and outsourced technology lifecycle management.
Healthcare Mobility Solutions Market Segmentation
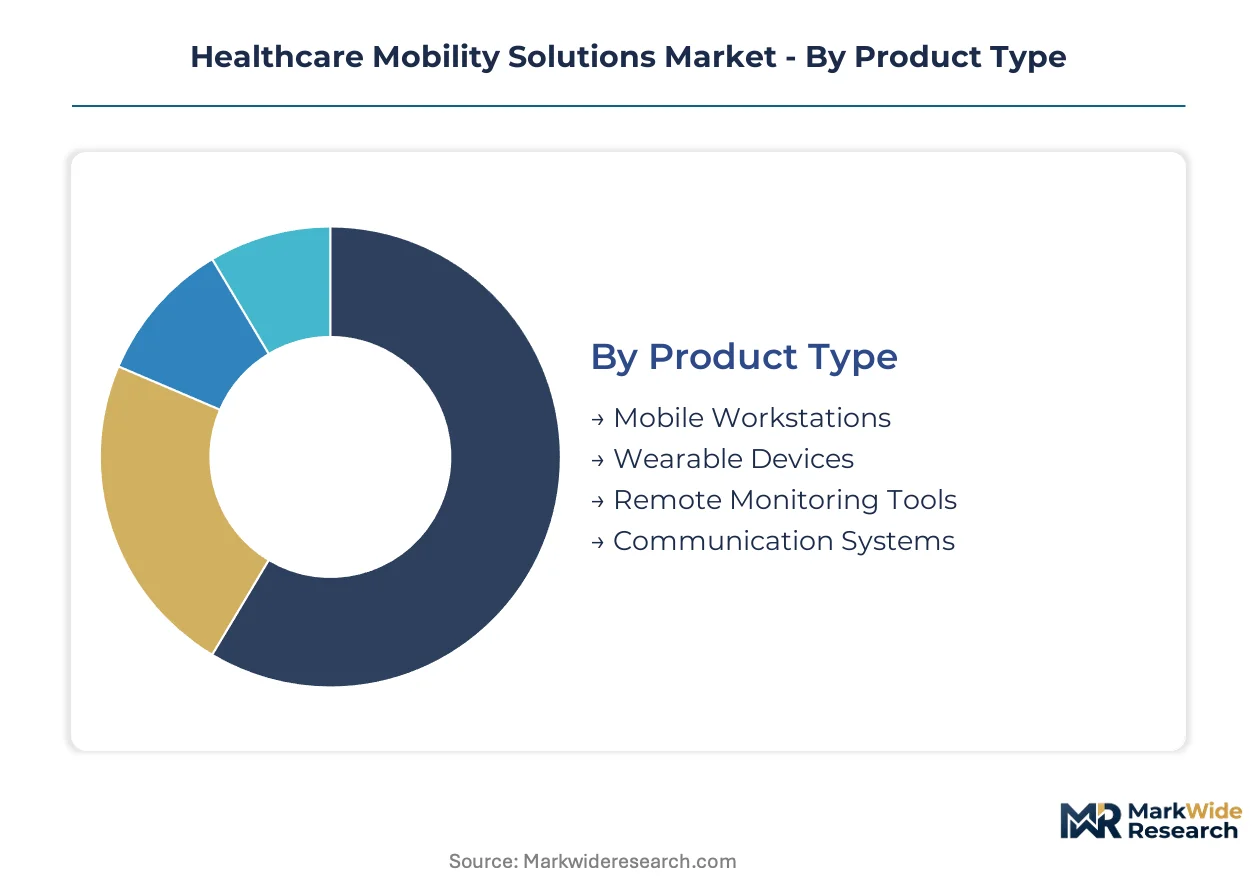
Segmentation provides a granular view of the diverse components and applications driving the healthcare mobility solutions market. Understanding these distinct segments helps stakeholders identify specific demand patterns, technological dependencies, and end-user requirements that shape strategic investments and product development.
Product Type:
The differentiation within product types often reflects a balance between high-volume utility and specialized, premium functionality.
- Mobile Workstations:These ruggedized carts integrate computers, scanners, and medical devices for point-of-care access to electronic health records within hospital environments.
- Wearable Devices:These are consumer-grade or medical-grade sensors worn on the body to track health metrics like heart rate, activity, and sleep patterns. Their adoption accelerates in home care settings, enabling preventative care and early detection of health issues.
- Remote Monitoring Tools:These devices collect physiological data from patients outside traditional clinical settings, often for chronic disease management and post-operative recovery. Demand concentrates in the United States and Germany, driven by an aging population and government digital health incentives.
- Communication Systems:These platforms facilitate secure voice, video, and text communication between healthcare professionals and patients, often via integrated mobile applications.
Today's leader: Remote Monitoring Tools. Tomorrow's challenger: Wearable Devices.
Technology:
Technology choices are increasingly driven by performance capabilities, with varying requirements for speed, range, and data throughput.
- Bluetooth:Short-range wireless technology connects wearable sensors and medical peripherals to mobile devices for localized data transfer and device pairing.
- Wi-Fi:This ubiquitous wireless local area network technology provides reliable, secure connectivity within medical campuses and residential settings, supporting EHR access and telemedicine consultations. Hospital networks in the United States rely heavily on robust Wi-Fi infrastructure.
- NFC:Near Field Communication enables contactless data exchange for patient identification, asset tracking, and secure payment within clinical workflows.
- 5G Networks:This next-generation wireless technology offers ultra-low latency and high bandwidth, essential for real-time medical imaging and remote-controlled surgical applications. Deployment in urban centers across South Korea and parts of Europe is enabling critical patient care.
- RFID:Radio-Frequency Identification tags track medical equipment, pharmaceuticals, and patient flow, improving inventory management and operational efficiency within healthcare facilities.
The pervasive nature of Wi-Fi and the transformative potential of 5G Networks underscore the evolving connectivity landscape.
Application:
Applications for healthcare mobility solutions significantly impact clinical workflows, ranging from direct patient interaction to backend data management.
- Patient Monitoring:This application involves continuous or intermittent tracking of a patient's physiological parameters, often remotely, to manage chronic conditions or post-operative recovery. Demand is increasing in developed economies due to the expansion of home-based care.
- Telemedicine:This application enables remote consultations, diagnosis, and treatment through secure video and audio communication, reducing the need for in-person visits. Broader acceptance in the United States and Europe drives investment in these mobile platforms.
- Emergency Response:Mobile solutions provide first responders with real-time access to patient records and facilitate communication with hospitals during critical incidents.
- Clinical Data Management:These applications allow healthcare professionals to securely access, input, and manage electronic health records and other clinical information on mobile devices.
The shift towards Telemedicine and advanced Patient Monitoring platforms requires robust underlying infrastructure.
End User:
End-user segments exhibit diverse investment capacities and operational needs, influencing the scale and complexity of deployed mobility solutions.
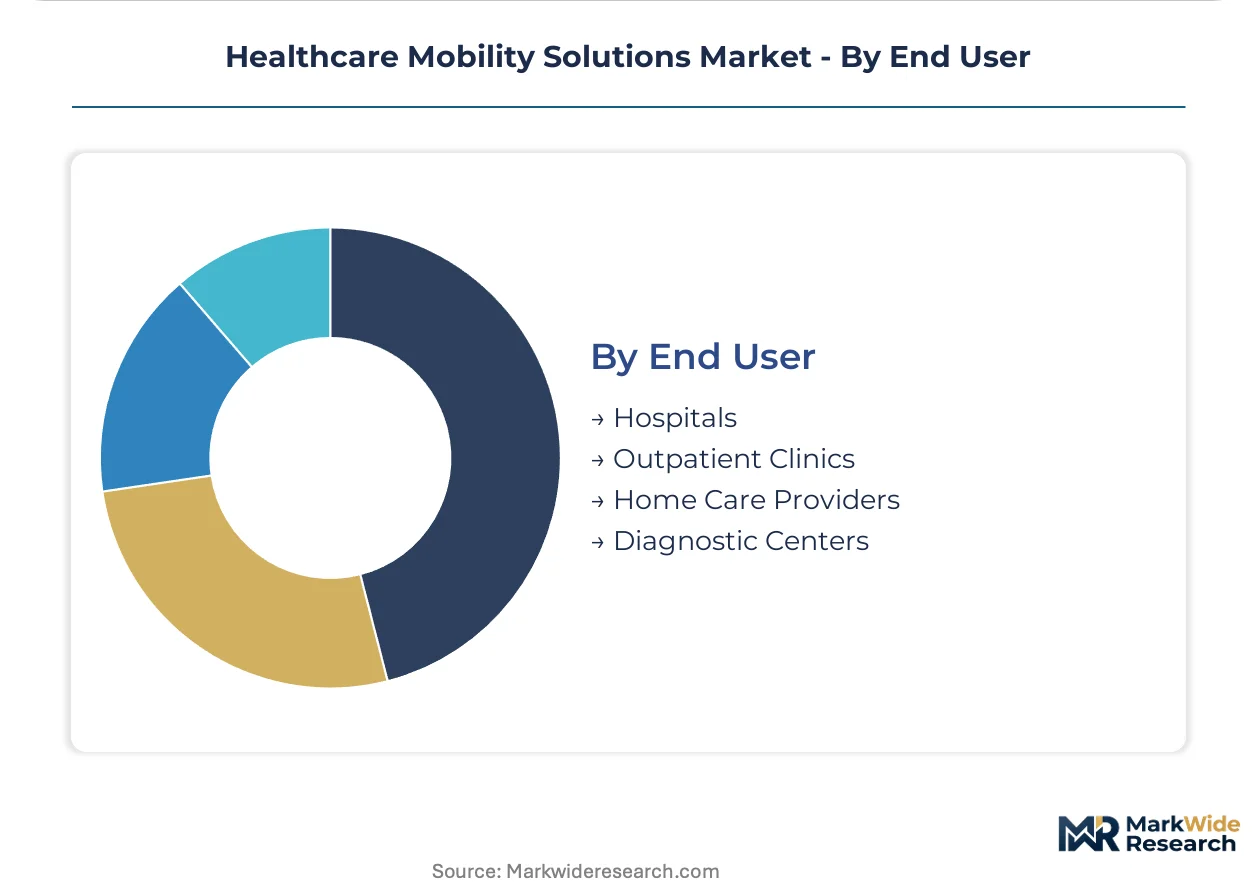
- Hospitals:These large institutions represent the primary end-user segment, investing in comprehensive mobile solutions for clinical workflows, patient engagement, and secure data access. Large hospital networks in Germany are particularly active in digital infrastructure investments.
- Outpatient Clinics:These facilities use mobile solutions to streamline patient check-ins, manage appointments, and provide clinicians with on-the-go access to patient information.
- Home Care Providers:This segment delivers medical services directly to patients' residences, leveraging mobile tools for remote monitoring, virtual visits, and medication management. This area offers significant margin opportunities due to lower overhead costs.
- Diagnostic Centers:Mobile applications assist in scheduling appointments, transmitting imaging results, and providing secure access to diagnostic reports for referring physicians.
Investment in Home Care Providers will increasingly drive the adoption of specialized remote monitoring tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany demonstrate strong demand for healthcare mobility solutions, driven by distinct but converging factors. Both nations prioritize digital health, yet their regulatory approaches and investment scales differ. This market expansion reflects a global shift towards integrated patient care.
United States
Demand in the United States is propelled by extensive hospital network investments and the widespread adoption of telemedicine for chronic disease management. HIPAA regulations strictly govern data privacy, influencing solution design and deployment. The Boston-Cambridge cluster continues to innovate in digital health platforms, integrating mobile solutions with advanced analytics.
Germany
Germany's market for healthcare mobility solutions benefits from significant hospital network investments and government digital health incentives. GDPR mandates stringent patient data protection, shaping all mobile application development. Munich and Berlin are emerging as key centers for health tech startups, focusing on secure, interoperable mobile platforms.
South Korea
South Korea is experiencing rapid growth due to advanced 5G network deployment, enabling high-bandwidth medical imaging and real-time remote monitoring. National digital health policies encourage the integration of mobile solutions into clinical workflows. Seoul's tech ecosystem is a hub for developing innovative mobile health applications and wearable devices.
Japan
Japanese healthcare providers increasingly adopt mobile solutions to address an aging population and expand preventative care services. The PMDA regulates diagnostic-grade remote monitoring tools, ensuring device safety and efficacy. Tokyo serves as a critical center for medical device innovation, driving the development of advanced wearable health technologies.
Brazil
Brazil offers a significant growth avenue for healthcare mobility, leveraging mobile-first infrastructure to leapfrog traditional wired networks. ANVISA oversees medical device approvals, ensuring compliance for new mobile health platforms entering the market. São Paulo is fostering a vibrant ecosystem of digital health startups, specializing in remote patient engagement tools.
Healthcare Mobility Solutions Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the healthcare mobility market. This landscape features a blend of established technology giants and agile solution providers. Strategic archetypes include integrated platform developers, specialized hardware manufacturers, and secure network infrastructure providers. Companies are actively pursuing strategic partnerships and portfolio diversification to enhance their market presence.
Within the enterprise software and medical device segments, Oracle Corporation and Zebra Technologies Corporation exemplify distinct market approaches. Oracle Corporation represents integrated cloud-based health platforms, leveraging its extensive software expertise to manage electronic health records and clinical data. Zebra Technologies Corporation anchors the specialized hardware segment, providing ruggedized mobile workstations and scanners purpose-built for demanding hospital environments. Cisco Systems, Inc. occupies a critical position as a provider of secure network infrastructure, essential for reliable mobile connectivity across large medical campuses and for real-time data transmission.
| Leading Market Players |
|---|
| McKesson Corporation |
| Oracle Corporation |
| Koninklijke Philips N.V. |
| Cisco Systems, Inc. |
| OMRON Healthcare, Inc. |
| Cerner Corporation |
| Zebra Technologies Corporation |
| Apple Inc. |
| SAP SE |
| Others |
Cost & Logistics Intelligence
Outsourced software development and hardware manufacturing anchors both the supply position and the pricing power in healthcare mobility solutions. This strategic choice allows technology vendors to leverage specialized expertise and optimize cost structures, influencing market entry barriers and competitive pricing strategies.
Pricing Analysis
Capacity additions in Southeast Asia for electronic components are reshaping price floors for mobile devices. Subscription-based software access and device-as-a-service bundles represent the dominant pricing models. Price differentiation stems from the certification level, such as US FDA or European Medicines Agency approvals, and the degree of customization for specific clinical workflows. Pricing pressure stems from the shift from capital expenditure to operational expenditure models, particularly among large hospital networks. Smaller outpatient clinics and individual home care providers exhibit the highest price sensitivity.
Supply Chain Analysis
Reverse-logistics flows for device refurbishment and secure data wiping are becoming increasingly critical for healthcare mobility. Geographic supply concentration for specialized medical sensors and semiconductors centers in countries like China, Taiwan, and South Korea. Raw material dependencies include rare earth elements for displays and advanced polymers for ruggedized enclosures. Regulatory restriction, particularly compliance with GDPR and HIPAA for data handling across borders, presents a structural supply chain risk. Distribution runs through direct sales channels to large hospital systems and specialized value-added resellers for smaller providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, where lower software development costs in emerging economies contrast with the stringent regulatory compliance demands in developed regions.
For Market Incumbents: Deepen integration capabilities with existing hospital electronic health record systems to enhance platform stickiness. Consolidate market share through strategic acquisitions of specialized software-as-a-medical-device (SaMD) providers to counter emerging entrant threats. Invest heavily in clinical validation and US FDA or European Medicines Agency certification for advanced remote monitoring tools. Control distribution channels by offering comprehensive device-as-a-service bundles directly to large hospital networks.
For New Entrants and Emerging Players: Capture underserved niche segments within home care, focusing on user-friendly interfaces for elderly patients. Target emerging markets like Southeast Asia and Latin America, leveraging mobile-first infrastructure to bypass traditional wired networks. Develop specialized applications for chronic disease management, offering a clear value proposition for preventative care. Penetrate the market through agile, cloud-native solutions that emphasize interoperability with diverse legacy systems.
For Investors and Strategic Acquirers: Roll-up economics work for specialized SaMD providers because market fragmentation allows for scale through consolidation. Long-term viability over the next 5-10 years favors platforms that offer integrated hardware, software, and secure communication. Acquisition targets should possess strong intellectual property in predictive analytics or robust regulatory compliance frameworks. Monitor increasing cross-border M&A activity in digital health platforms as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA/EMA Approval Pathway Acceleration | Secures market access for diagnostic-grade remote monitoring tools in key developed economies. |
| Hospital System Partnership Development | Expands market reach and validates clinical efficacy within established healthcare infrastructures. |
| AI/ML Integration for Predictive Analytics | Enhances diagnostic capabilities and personalizes patient care through advanced data interpretation. |
| Device-as-a-Service Model Launch | Aligns with shifting procurement preferences, offering predictable costs for healthcare providers. |
| Cybersecurity Enhancement Investment | Protects sensitive patient data, building trust and ensuring compliance with strict privacy regulations. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to inform market sizing and trend analysis. Primary research involved discussions with clinicians, hospital IT directors, medical device engineers, and regulatory specialists. This primary data was triangulated against secondary sources including US FDA filings, European Medicines Agency submissions, healthcare expenditure reports, and academic literature, ensuring robust validation.
A segment-weighting approach was applied to construct the forecast framework, modeling market behavior across product type, technology, application, and end-user. Compound annual growth rates were derived from historical trends and projected adoption rates across the analysis window. Industry-specific forecast inputs included 5G network rollout schedules in key regions and government digital health initiative funding allocations.
Regulatory changes, cybersecurity threats, and technological obsolescence are the dominant revision risks for market forecasts. Forecasts reflect current market assumptions regarding technology adoption and policy stability. Practitioners should monitor policy shifts and major security breaches for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Revenue Cycle Management (RCM) Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Global Pharma Knowledge Management Software Market
Healthcare IT
North American Dental Software Market
Healthcare IT
E-Prescribing Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market