
 Global Personal Cloud Market | 2026-2036
Global Personal Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Cloud Market Intelligence
The divergence between zero-cost, advertising-supported storage and paid, feature-rich subscription tiers is repositioning the value proposition in personal cloud services. Apple Inc. leverages its hardware ecosystem to integrate cloud services deeply within its user experience, creating a seamless environment for its customers. Microsoft Corporation competes by bundling its OneDrive storage with the broader Office 365 productivity suite for individuals and remote workers. Dropbox, Inc. differentiates through a focus on robust cross-platform synchronization and advanced collaboration tools.
Personal cloud refers to a digital storage model where data is stored on remote servers and made accessible to a user through a network, typically the internet. These services rely on client-side applications and web-based interfaces to manage file synchronization, backup, and access across authenticated devices. While basic File Storage constitutes the core offering, value is increasingly captured through advanced solutions like automated Backup & Recovery and integrated Collaboration Tools. Demand from Individual Consumers provides a large user base, while adoption by Remote Workers and Freelancers drives subscription upgrades.
Data governance frameworks, including Europe's GDPR and China's Personal Information Protection Law (PIPL), impose strict requirements on data handling and cross-border transfers. Compliance with these regulations, alongside various US state-level privacy laws, dictates data center location strategies and user data management policies for service providers. Navigating this fragmented regulatory landscape to deliver a seamless user experience remains a central strategic challenge for all market participants.
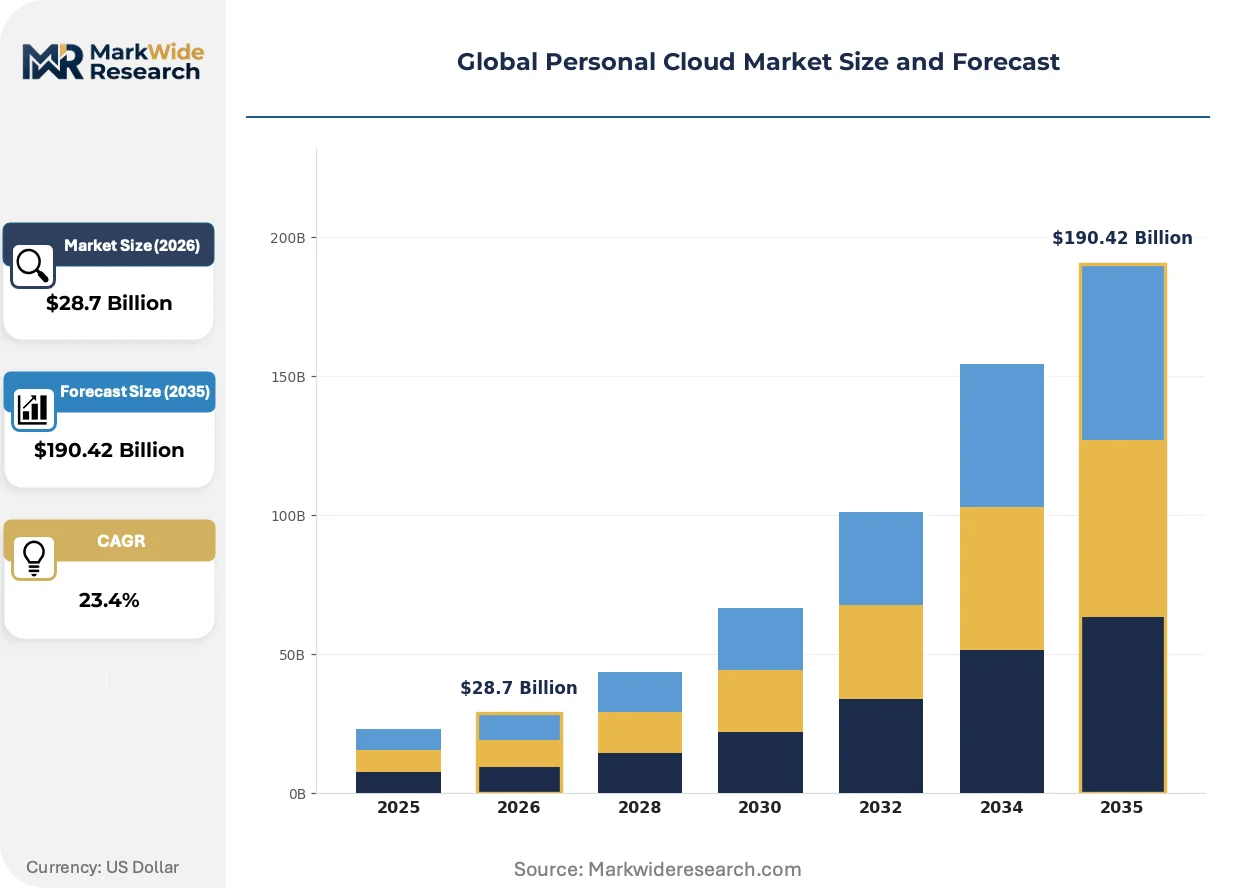
Market Dynamics
The central tension between data sovereignty regulations and user demand for seamless, cross-border data access is the primary structural force shaping the market. This conflict dictates service architecture, data center deployment strategies, and the very nature of competitive differentiation among providers.
Growth Catalysts
- Remote Work Expansion:The sustained shift to remote and hybrid work models necessitates constant, device-agnostic access to files and collaborative tools, driving individual and small business subscriptions for platforms that support this flexibility.
- Digital Content Creation:Proliferation of high-resolution photo and video content from smartphones exhausts local storage, pushing users toward scalable cloud-based solutions that can manage large file sizes and libraries effectively.
- Ecosystem Integration:Deep integration of cloud services within operating systems like iOS and Windows creates a frictionless user onboarding process, converting hardware buyers into recurring cloud service subscribers with high switching costs.
Market Restraints
- Data Sovereignty Laws:Regulations like Europe's GDPR and China's PIPL mandate local data residency, complicating global service delivery, fragmenting service features, and increasing infrastructure costs for providers operating internationally.
- Security Apprehension:Persistent user concern regarding data breaches and unauthorized government surveillance acts as a significant barrier, particularly for storing sensitive personal, financial, or health-related information in the cloud.
- Bandwidth Limitations:In regions with underdeveloped internet infrastructure, slow or unreliable connectivity severely degrades the user experience for uploading and synchronizing large files, limiting market penetration and user satisfaction.
Strategic Opportunities
- Privacy-Centric Services:A growing niche of users in markets like Germany and Switzerland shows willingness to pay a premium for end-to-end encrypted services that prioritize absolute user privacy and data control.
- AI-Powered Organization:Integrating artificial intelligence for automated photo tagging, document categorization, and intelligent search presents a key value-add opportunity to differentiate paid subscription tiers from basic free storage offerings.
- SMB and Freelancer Bundles:Developing specialized service bundles for small businesses and freelancers that combine storage with invoicing, project management, and client collaboration tools opens a lucrative and underserved B2B2C channel.
Industry Challenges
- Interoperability Standards:The lack of universal standards for data portability between competing cloud platforms creates vendor lock-in, frustrating users and complicating migration paths for those seeking alternative or specialized services.
- Energy Consumption:The high energy footprint of large-scale data centers is attracting regulatory scrutiny and public pressure, requiring significant capital investment in renewable energy and efficient cooling technologies to meet sustainability goals.
- Monetizing Free Tiers:Converting users from free, often advertising-supported, tiers to paid subscriptions remains a central operational challenge, requiring a careful balance of feature limitations and compelling value propositions in premium plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Cloud Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $190.42 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution/Offering: File Storage, Backup & Recovery, Data Synchronization, Media Streaming, Collaboration Tools Use Case: Data Backup, Remote Access, Content Sharing, Device Synchronization, Personal Archiving End User: Individual Consumers, Freelancers, Students, Remote Workers, Digital Nomads |
| Companies Covered | Google LLC, Microsoft Corporation, Apple Inc., Amazon Web Services, Inc., Dropbox, Inc., Box Inc., pCloud, BUFFALO Technology, ASUS Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Cloud Market Strategic Shifts & Innovations
The competitive landscape is being defined by the dual pursuit of seamless ecosystem integration and compliance with a fragmented global regulatory environment. This requires providers to innovate simultaneously in user experience design and backend data architecture to win and retain customers.
Edge computing places data processing and storage closer to the end-user, reducing latency for real-time synchronization. Mobile-first users and creators of large media files are the primary beneficiaries, experiencing faster uploads and access. This shift from centralized data centers to a distributed network is rewriting the performance expectations for cross-device file management and collaboration.
Data governance frameworks like the EU's GDPR and various US state privacy laws impose strict user consent and data access requirements. This forces providers to build granular user-facing controls for data management and to re-architect services for regional data residency. Compliance is most complex for providers operating across both the European Union and North American markets.
A discernible shift is occurring from basic file storage towards integrated application suites that bundle cloud storage with productivity tools. This disrupts the market for standalone storage providers, favoring companies that can offer a unified ecosystem for work and personal life. The trend is most pronounced among remote workers and small business segments seeking consolidated subscription models.
Global Personal Cloud Market Segmentation
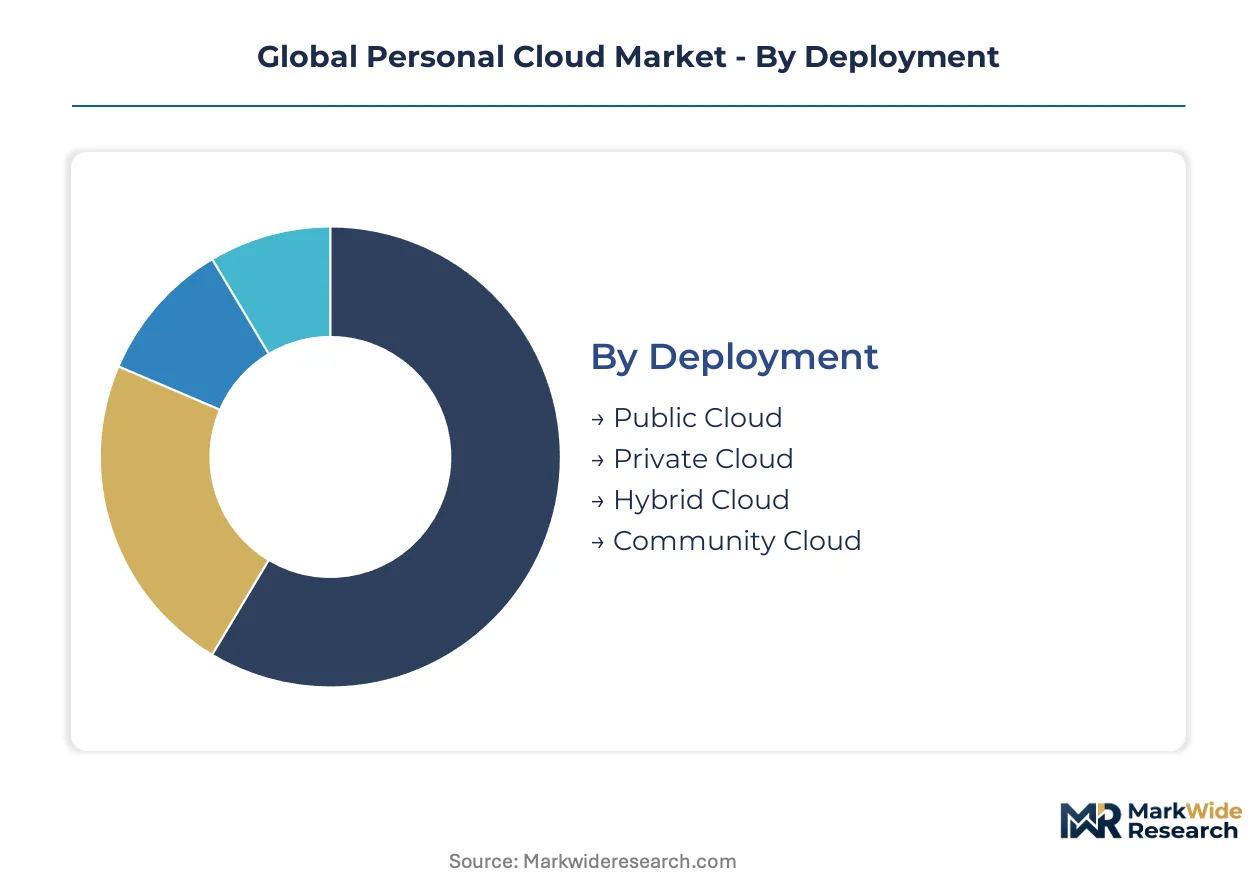
The personal cloud market segmentation clarifies how diverse user requirements and technological preferences influence service adoption and provider strategies. Understanding these distinct segments allows providers to tailor offerings that address specific needs for data storage, access, and collaboration. This granular view highlights areas of concentration and expansion across various deployment models and user types.
Deployment:
Buyers choose personal cloud deployment models based on their priorities for control, cost, and data residency.
- Public Cloud:Services delivered over the internet by a third-party provider, offering high scalability and cost-effectiveness due to shared infrastructure. Demand concentrates among individual consumers and small businesses seeking accessible solutions with minimal overhead.
- Private Cloud:Dedicated cloud infrastructure exclusively for a single organization or user, providing enhanced security, customization, and regulatory compliance. Organizations in Germany with strict data sovereignty laws often prefer this model for sensitive information.
- Hybrid Cloud:This model combines elements of both public and private clouds, allowing data and applications to move between environments.
- Community Cloud:Infrastructure shared by several organizations with common concerns, such as specific security or compliance requirements.
Volume sits with Public Cloud; growth tilts toward Hybrid Cloud.
Solution/Offering:
The range of solutions available in the personal cloud market addresses distinct application requirements for managing digital assets.
- File Storage:The foundational service providing digital space for users to save documents, photos, and videos remotely. This core offering sees sustained demand across all individual consumers, especially with the proliferation of high-resolution digital content.
- Backup & Recovery:Automated processes that create copies of digital data and enable restoration in case of data loss or system failure. Remote workers prioritize this solution for business continuity and disaster preparedness, particularly in regions with high digital literacy.
- Data Synchronization:This solution ensures consistent data across multiple devices, updating changes in real-time for seamless access.
- Media Streaming:Cloud-based services enabling access and playback of audio and video content without local downloads.
- Collaboration Tools:Integrated features facilitating shared document editing, project management, and communication among users.
File Storage commands the largest market share, while Collaboration Tools exhibit significant revenue potential.
Use Case:
Users adopt personal cloud services to fulfill specific needs related to data management and accessibility.
- Data Backup:The primary use case involving safeguarding digital information against loss, corruption, or hardware failure. Individual consumers widely adopt this for peace of mind regarding their personal photos and documents.
- Remote Access:Enabling users to retrieve and manage their files from any location using various authenticated devices. This use case is critical for remote workers who require constant, flexible data availability.
- Content Sharing:Facilitating the secure and convenient distribution of digital files and media with others.
- Device Synchronization:Maintaining consistent versions of files and settings across an individual's multiple electronic devices.
- Personal Archiving:Long-term storage of digital memories and historical data for future reference or sentimental value.
Data Backup remains a fundamental need, with Remote Access demonstrating the fastest expansion.
End User:
Different end-user segments exhibit distinct behaviors and priorities when selecting and utilizing personal cloud services.
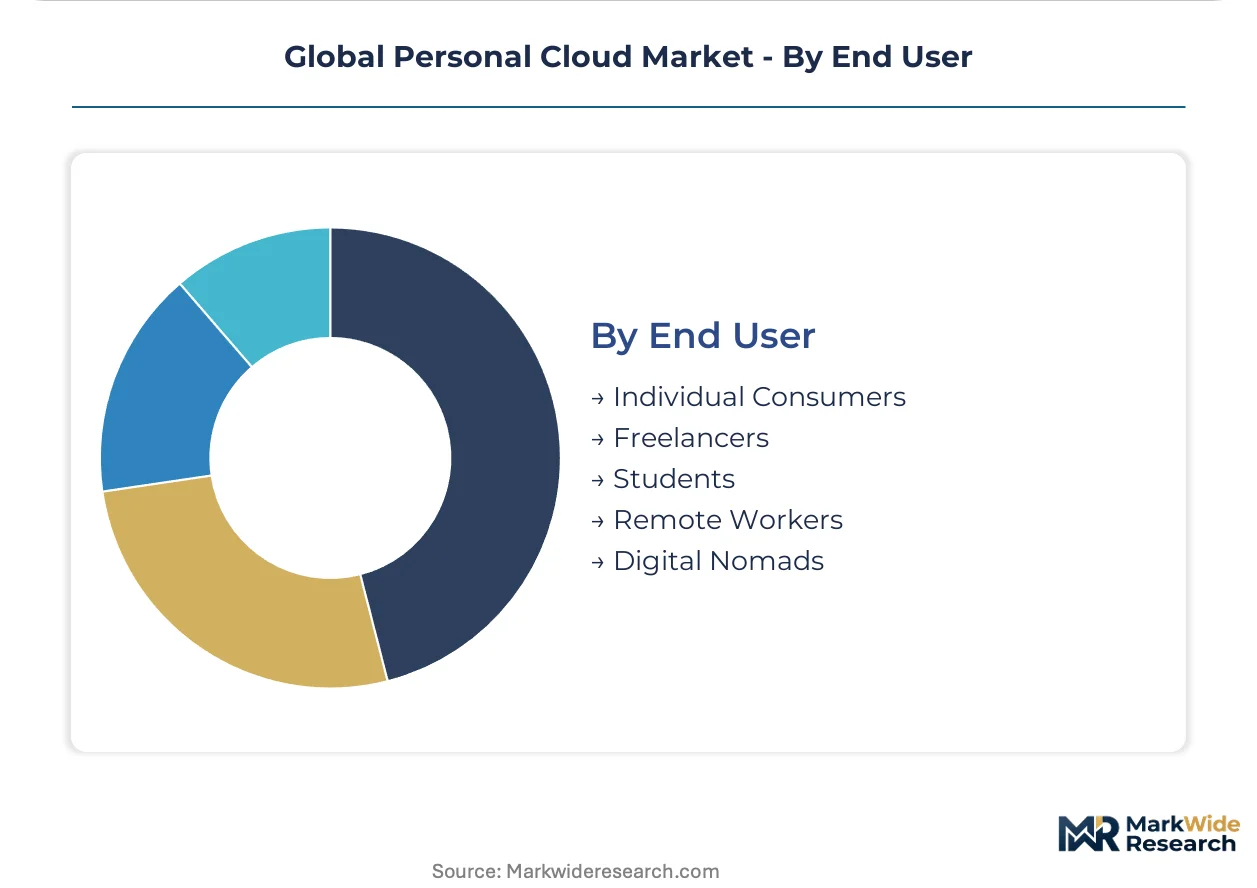
- Individual Consumers:The largest user base, primarily seeking storage for personal photos, videos, and documents, often driven by mobile device storage limitations. These users frequently leverage free tiers before considering paid upgrades for increased capacity.
- Remote Workers:Professionals requiring seamless access to work-related files and collaboration tools across multiple devices and locations. This segment drives demand for subscription upgrades and integrated productivity suites.
- Freelancers:Independent professionals who need reliable and secure cloud solutions for project files, client collaboration, and invoicing.
- Students:Users who utilize cloud storage for academic documents, research, and sharing assignments with peers and instructors.
- Digital Nomads:Individuals who work remotely while traveling, needing robust and globally accessible cloud services for their mobile lifestyle.
Individual Consumers represent a broad user base, while Remote Workers offer the highest revenue potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley in the United States remains a primary innovation hub for personal cloud services, influencing global development and market trends. Developed economies with high internet penetration and digital literacy, such as Germany, drive significant demand for advanced personal cloud solutions. Data sovereignty regulations, including Europe's GDPR and China's PIPL, significantly influence service architecture and deployment strategies across these diverse regions. This regulatory landscape necessitates localized data center strategies and tailored compliance frameworks from providers.
United States
Remote work expansion and the proliferation of digital content creation are primary demand drivers across the United States. US state-level privacy laws, such as California's CCPA, influence data handling practices and user consent mechanisms for service providers. Major tech hubs like Seattle and Silicon Valley lead in developing integrated personal cloud solutions, often bundled with broader productivity software.
Germany
High digital literacy and a strong emphasis on data privacy drive demand for premium, privacy-centric personal cloud services in Germany. The European Union's GDPR mandates strict data residency and user control, shaping service offerings for German consumers. Cities like Berlin and Munich are centers for cloud innovation, with a focus on secure, compliant data storage solutions.
China
A vast mobile-first user base and rapid digital content consumption fuel significant demand for personal cloud storage in China. The Personal Information Protection Law (PIPL) imposes stringent requirements on data localization and cross-border transfers for all service providers. The Yangtze River Delta region, including Shanghai, is a key area for localized cloud infrastructure development and service delivery.
Japan
Deep ecosystem integration within consumer electronics and a strong preference for seamless user experiences characterize Japan's personal cloud market. Guidelines from METI (Ministry of Economy, Trade and Industry) encourage secure data management and digital transformation initiatives. Tokyo and Osaka serve as major metropolitan centers where advanced cloud services are integrated into daily digital life.
India
A rapidly expanding internet user base and increasing smartphone penetration contribute to the growing demand for personal cloud services among individual consumers in India. The upcoming Digital Personal Data Protection Act will significantly influence how data is stored and processed within the country. Bengaluru, known as India's Silicon Valley, is a hub for cloud service development and adoption, particularly for mobile-centric solutions.
Global Personal Cloud Market Key Industry Players
Premium-margin players sit above commodity-margin players across the personal cloud services market, differentiating through feature sets and ecosystem integration. The market exhibits a tiered structure, with large technology companies leveraging existing user bases and smaller players focusing on niche offerings. Ecosystem integrators, cross-platform specialists, and privacy-centric providers represent distinct strategic archetypes. Dominant competitive moves include bundling services with hardware or software suites and differentiating through advanced collaboration and AI-powered organization tools.
Within the ecosystem-driven segment, Apple Inc. and Microsoft Corporation exemplify strategies that leverage extensive hardware and software platforms to integrate personal cloud services seamlessly. Apple Inc. deeply embeds its cloud services within its iOS ecosystem, creating high switching costs for users. Microsoft Corporation bundles OneDrive storage with its ubiquitous Office 365 productivity suite, targeting individual and remote workers. Dropbox, Inc. represents a cross-platform specialist archetype, focusing on robust synchronization and advanced collaboration tools to differentiate its offerings across various operating systems and devices.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| Apple Inc. |
| Amazon Web Services, Inc. |
| Dropbox, Inc. |
| Box Inc. |
| pCloud |
| BUFFALO Technology |
| ASUS Cloud |
| Others |
Cost & Logistics Intelligence
Venture-backed cloud innovators often dictate pricing discipline by focusing on rapid user acquisition and feature differentiation, influencing the competitive landscape and supply chain investments in global data center capacity. This approach shapes both service offerings and infrastructure deployment strategies.
Pricing Analysis
Pricing ties directly to storage capacity and feature sets, moving from basic free tiers to feature-rich subscription models. Price differentiation stems from advanced collaboration tools and deep ecosystem integration with hardware platforms like Apple's iOS. Pricing softness in basic storage reflects intense competition from large technology companies leveraging existing user bases. Individual consumers exhibit the highest price sensitivity, often opting for free tiers, while remote workers prioritize feature sets over minimal cost.
Supply Chain Analysis
Data sovereignty laws in Europe and China mandate localized infrastructure, reshaping sourcing for data center hardware and network components. Geographic supply concentration for cloud infrastructure relies heavily on the United States and China for server technology and network equipment. Raw material dependencies include specialized semiconductors and high-capacity storage arrays. Regulatory fragmentation presents a structural risk, increasing compliance costs and limiting cross-border data flow. Distribution runs through direct digital channels and bundled offerings with consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The personal cloud market is in a technology-transition phase, with integrated application suites displacing standalone file storage providers for remote work and digital content creation. This shift prioritizes unified platforms over fragmented services.
For Market Incumbents: Acquire specialized AI-powered organization platforms to enhance premium offerings and reduce reliance on basic storage. This move counters the threat of niche competitors focusing on intelligent data management and reinforces customer loyalty through advanced capabilities. Investment in secure data residency infrastructure, particularly in Germany, serves as a key lever against stringent data sovereignty regulations like GDPR.
For New Entrants and Emerging Players: Capture underserved SMB and freelancer segments by bundling project management and invoicing tools with secure cloud storage. This targets the most penetrable segment seeking integrated business solutions beyond simple file sharing. A go-to-market angle focusing on privacy-centric, end-to-end encrypted solutions can differentiate offerings in markets like Switzerland.
For Investors and Strategic Acquirers: Distressed-cycle entries favor privacy-focused providers in Europe, particularly Germany, for long-term value creation over the next five to ten years. These targets offer robust compliance frameworks and a loyal user base willing to pay a premium for data control. The signal to watch is the sustained enforcement of regional data residency mandates, which will consolidate demand for compliant providers.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Organization Integration | Enhances automated photo tagging and document categorization for Apple Inc. users. |
| Edge Computing Infrastructure Investment | Reduces latency for mobile-first users and creators of large media files. |
| Regional Data Center Expansion | Ensures compliance with Europe's GDPR and China's PIPL for Microsoft Corporation. |
| Productivity Suite Bundling | Attracts remote workers seeking consolidated subscription models from Google LLC. |
| End-to-End Encryption Development | Appeals to privacy-conscious users in Germany willing to pay a premium. |
Research Approach
Government privacy law publications, SEC 10-K filings, and industry whitepapers formed the secondary backbone, complemented by primary interviews with key stakeholders. These included CTOs and IT procurement officers from large enterprises, cloud architects, and privacy compliance leads across various regions. This approach allowed for robust bottom-up and top-down triangulation of market data.
A bottom-up analytical lens informed the market sizing, projecting demand across the analysis window based on segmentation dimensions. These included deployment model, solution/offering, end-user, and regional regulatory framework. Compound annual growth rates were derived from historical trends and anticipated market shifts. Key forecast inputs included global internet penetration rates and smartphone adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts impacting data residency and rapid technological disruption from new storage paradigms. The projections reflect current market dynamics and regulatory landscapes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Based Information Governance Market
Cloud Computing
Platform As a Service (Paas) Market
Cloud Computing
Public Cloud Market
Cloud Computing
Commerce Cloud Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Global Multi Cloud Management Market
Cloud Computing
Cloud ELN Service Market
Cloud Computing
Cloud Computing in Industrial IoT Market
Cloud Computing
Application Hosting Market
Cloud Computing
Public Finance Cloud Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
UAE Cloud Computing Market
Cloud Computing
Virtual Private Cloud (VPC) Market
Cloud Computing
Cognitive Cloud Market