
 Cloud Based Information Governance Market | 2026-2036
Cloud Based Information Governance Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Based Information Governance Market Analysis
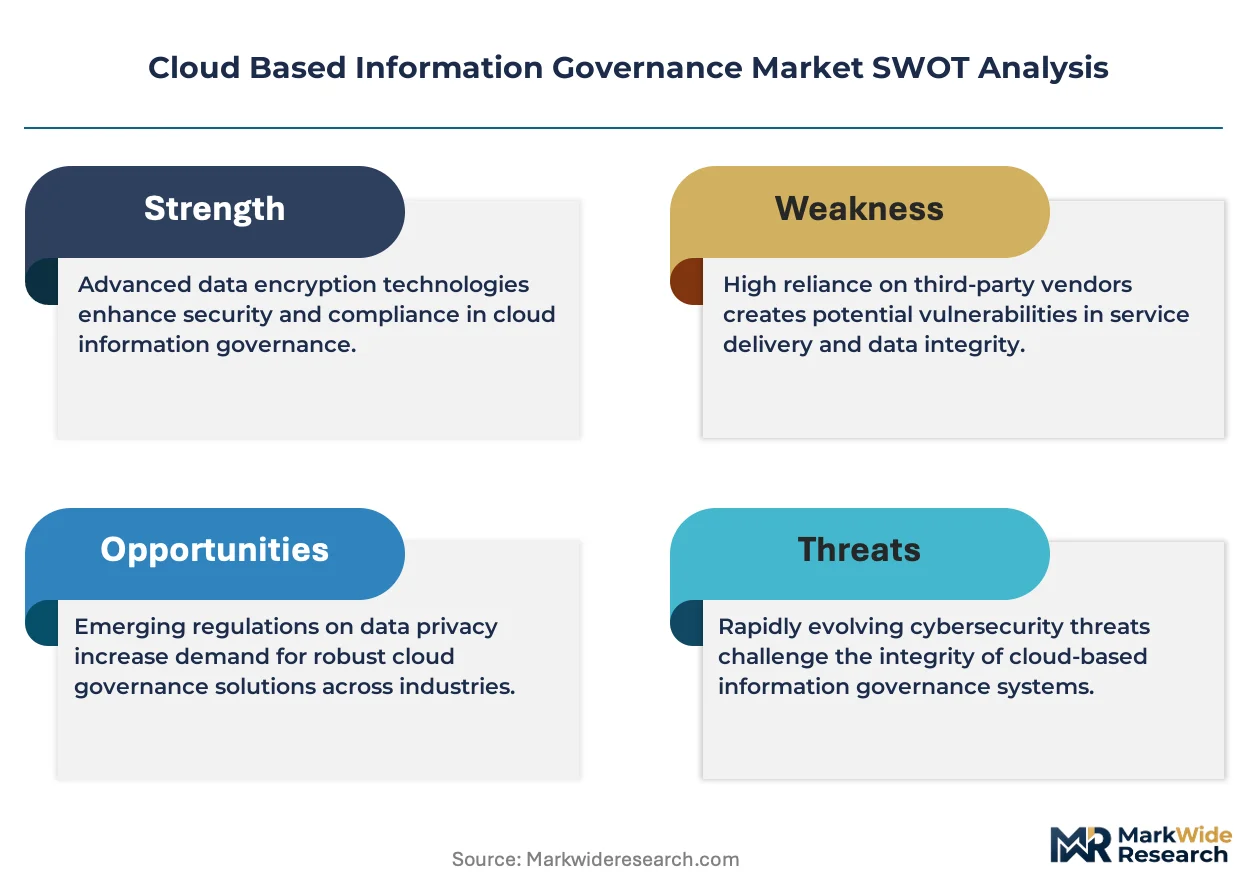
Healthcare is broadening its share of cloud-based information governance spending as hospitals and payers confront stricter patient data retention mandates. Microsoft Corporation leverages its Azure Purview platform to anchor enterprise compliance workflows across regulated industries. IBM Corporation sustains deep integration between its Cloud Pak for Data suite and legacy mainframe governance environments. Amazon Web Services competes through granular object-level policy controls in Amazon S3 and complementary Macie discovery services.
Cloud-based information governance encompasses policy-driven frameworks for data classification, retention scheduling, legal hold management, and audit trail preservation delivered through distributed cloud infrastructure. These systems enforce metadata schemas, automate lifecycle state transitions, and generate defensible destruction certificates for regulatory examinations. Compliance Management services command premium pricing due to jurisdictional complexity, while Hybrid Cloud deployments attract organizations with sovereignty-sensitive workloads split between on-premises vaults and hyperscaler regions. Artificial Intelligence technology leads segment momentum as natural language processing automates sensitive data discovery in unstructured repositories.
The EU AI Act, GDPR, and HIPAA shape product requirements by mandating explainable decision logs, data minimization proofs, and breach notification automation. The US Securities and Exchange Commission and the UK Information Commissioner's Office intensify enforcement against deficient record-keeping, directly expanding addressable demand for audit-ready governance platforms. Stakeholders must evaluate whether their current tooling satisfies emerging algorithmic accountability rules before regulators impose operational penalties.
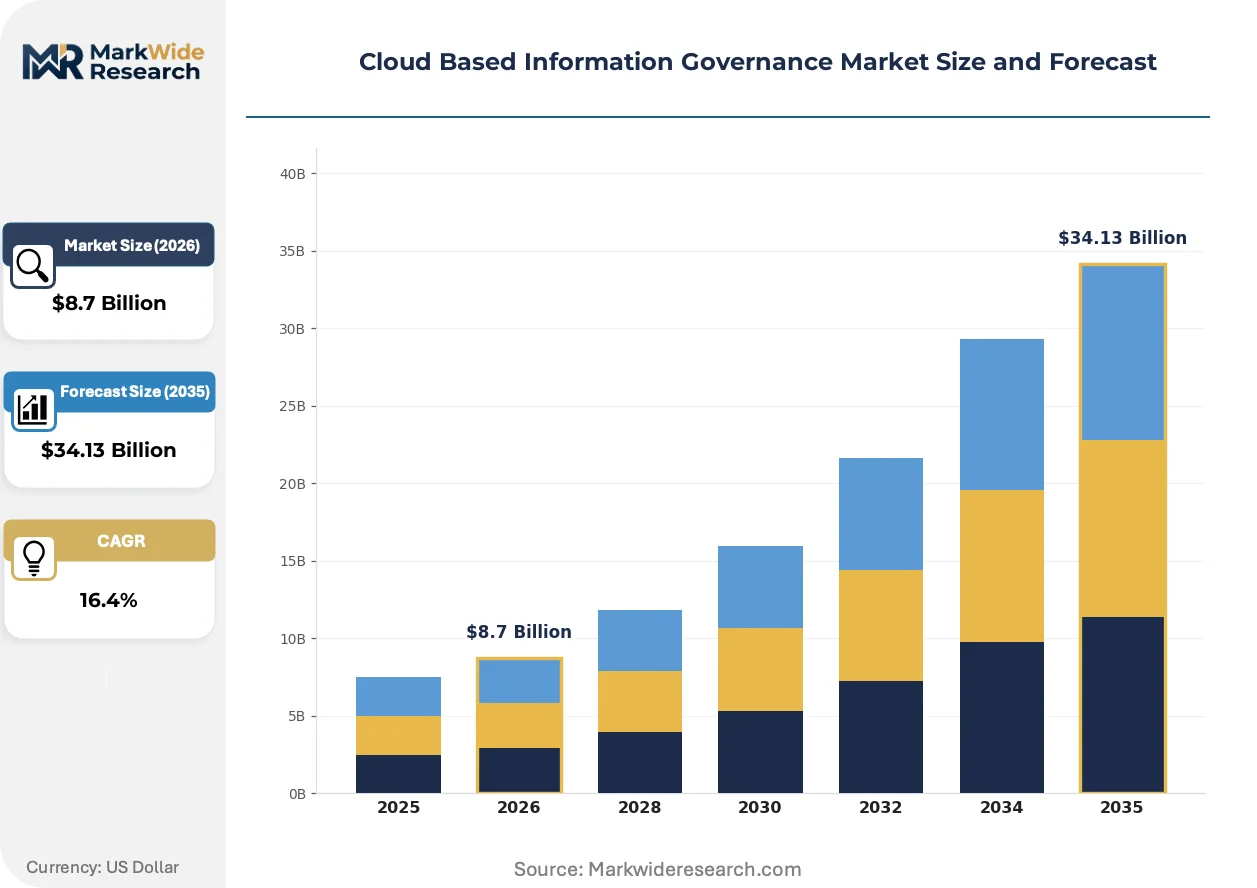
Market Dynamics
The EU AI Act is compelling organizations to deploy automated governance frameworks that generate immutable audit trails for algorithmic decision-making, fundamentally restructuring procurement priorities across regulated industries.
Growth Catalysts
- GDPR Article 17 Right to Erasure:Organizations in France and Germany must demonstrate defensible data destruction, driving demand for automated retention scheduling and certificate generation capabilities.
- Healthcare digitization:Hospitals in the United Kingdom are consolidating patient data lakes, requiring unified governance platforms that enforce HIPAA-equivalent standards across cloud and on-premises infrastructure.
- Natural language processing:Unstructured data repositories in legal and financial services now yield to automated sensitive data discovery, compressing manual classification timelines from months to days.
Market Restraints
- Cross-border data transfer friction:The EU AI Act's extraterritorial provisions create compliance complexity for US-based hyperscalers operating European workloads, elevating legal review costs.
- Technical debt in legacy mainframe environments:Financial institutions in Germany retain decades-old record-keeping systems that resist API-based governance integration without expensive middleware layers.
- Substitution by open-source tooling:Apache Atlas and commercial alternatives attract cost-conscious mid-market buyers, pressuring proprietary platform pricing in the United Kingdom.
Strategic Opportunities
- CSRD sustainability reporting mandates:The European Union's Corporate Sustainability Reporting Directive requires auditable ESG data lineage, opening governance platform extensions into carbon accounting workflows.
- Edge computing convergence:Manufacturing facilities in France are deploying lightweight governance agents at plant level, creating demand for federated policy orchestration between edge nodes and central cloud repositories.
- Small and medium enterprise underpenetration:Professional services firms in Germany lack dedicated compliance personnel, presenting managed governance service opportunities.
Industry Challenges
- Certified data steward scarcity:The United Kingdom reports acute shortages of professionals qualified under ISO 27001 and GDPR practitioner schemes, inflating implementation timelines.
- Multi-cloud policy synchronization:Organizations splitting workloads across AWS, Azure, and Google Cloud struggle to maintain consistent metadata taxonomies and retention rules without centralized control planes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Based Information Governance Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Archiving, Data Loss Prevention, Compliance Management, Risk Management Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Healthcare, Financial Services, Education, Government Technology: Artificial Intelligence, Blockchain, Machine Learning, Analytics |
| Companies Covered | IBM Corporation, Microsoft Corporation, Amazon Web Services, Google LLC, Oracle Corporation, OpenText Corporation, Veritas Technologies, Informatica, Collibra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Based Information Governance Market Emerging Trajectories
Automated policy enforcement is displacing manual governance workflows as natural language processing and machine learning classification achieve production reliability at enterprise scale.
Graph-based data lineage engines are expanding into financial services and pharmaceutical supply chains, mapping relationships across petabyte-scale repositories. Compliance teams at German insurers and French pharmaceutical distributors are adopting these tools to satisfy EMA pharmacovigilance and BaFin record-keeping requirements. The technology is expanding into real-time transaction monitoring, compressing breach detection windows from weeks to hours.
The EU AI Act's algorithmic accountability provisions now require explainable decision logs for high-risk AI systems, including credit scoring and medical diagnosis workflows. Organizations must implement technical documentation standards that trace training data provenance and model versioning. Healthcare providers in the United Kingdom and financial institutions in France are prioritizing governance platforms with built-in model cards and bias detection modules.
Subscription-based consumption models are displacing perpetual license arrangements as buyers demand elasticity aligned with data volume growth. Mid-market enterprises in Germany prefer usage-metered pricing that scales with repository expansion rather than upfront capital commitments. This shift concentrates vendor revenue in customer success functions and professional services attach rates rather than initial deployment fees.
Cloud Based Information Governance Market Segmentation
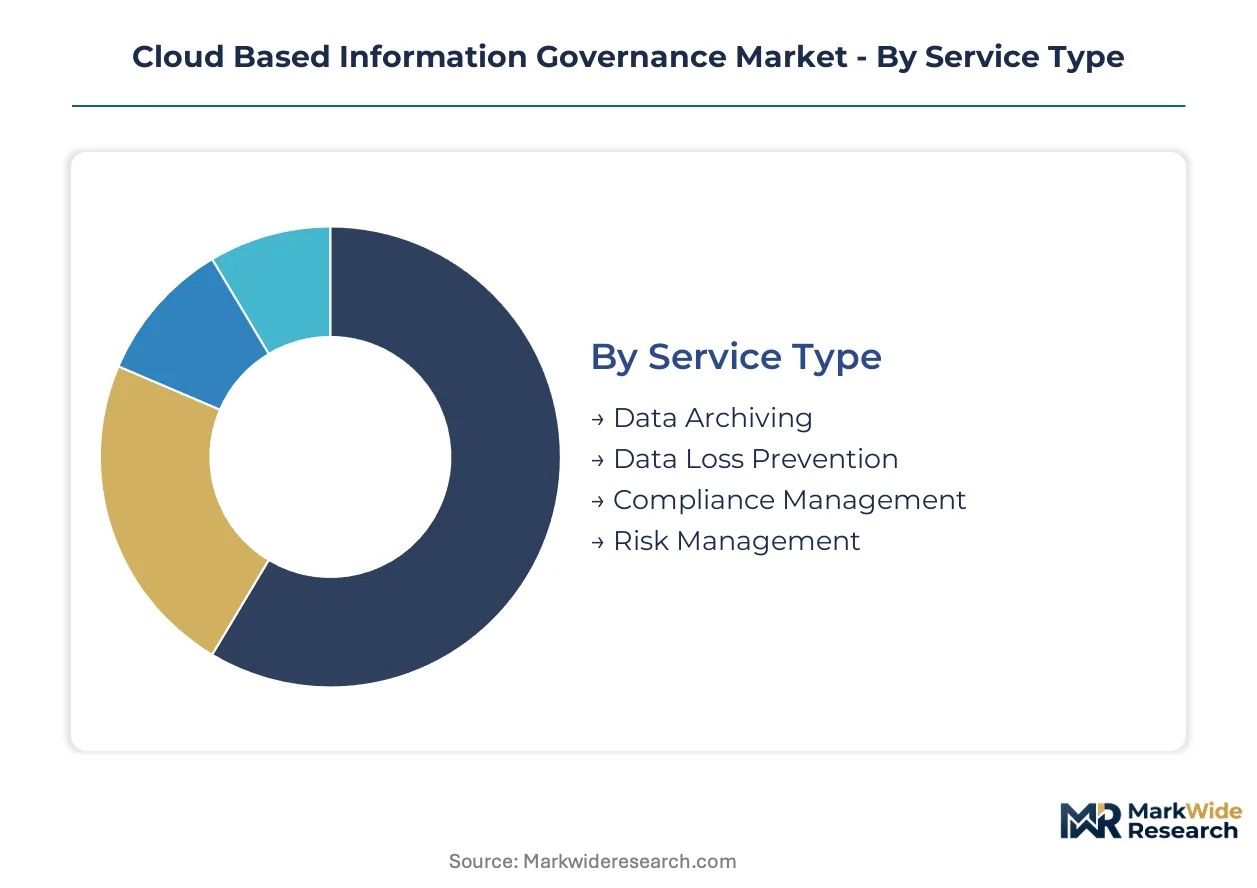
Cloud governance platforms fragment across four distinct segmentation axes that reflect divergent buyer priorities: compliance sophistication, infrastructure sovereignty, industry-specific regulatory exposure, and automation maturity. Procurement teams weight these dimensions differently based on data sensitivity, jurisdictional complexity, and legacy system constraints.
Service Type:
Buyers in this category separate by regulatory burden intensity — hospitals and banks demand defensible audit trails, while manufacturers prioritize operational risk reduction.
- Data Archiving:Long-term retention infrastructure with immutable storage tiers and legal hold capabilities. German automotive suppliers deploy these systems to satisfy commercial code record-keeping mandates for design documentation spanning decades.
- Data Loss Prevention:Real-time egress monitoring with content inspection and policy-based blocking. French healthcare networks concentrate spending here to prevent patient data exfiltration under CNIL enforcement protocols.
- Compliance Management:Automated mapping of data assets to regulatory control frameworks with evidence collection workflows.
- Risk Management:Quantitative assessment tools linking data exposure to business impact metrics for executive reporting.
Volume sits with Data Archiving; growth tilts toward Compliance Management.
Deployment Model:
Infrastructure choices track data sovereignty sensitivity — regulated industries reject pure public deployments while agile sectors embrace multi-cloud flexibility.
- Hybrid Cloud:Policy orchestration across on-premises vaults and hyperscaler regions with unified metadata control planes. United Kingdom financial institutions favor this architecture to retain trading records domestically while leveraging cloud analytics.
- Multi-Cloud:Federated governance spanning AWS, Azure, and Google Cloud with consistent classification taxonomies. German industrial conglomerates adopt this model to avoid vendor lock-in and satisfy procurement diversification rules.
- Public Cloud:Fully managed governance services with shared infrastructure and metered consumption pricing.
- Private Cloud:Dedicated tenant environments with isolated compute and storage for classified or state-secret workloads.
Adoption clusters in Hybrid Cloud; Multi-Cloud deployments are climbing the fastest as organizations diversify supplier relationships.
End User:
Industry verticals diverge by retention mandate complexity — healthcare and finance face prescriptive record-keeping rules that education and government interpret more variably.
- Healthcare:Patient data lifecycle management with HIPAA-equivalent controls and clinical trial documentation workflows. United Kingdom NHS trusts are consolidating fragmented governance tools into unified platforms to manage genomic data repositories.
- Financial Services:Transaction record preservation with MiFID II and SEC 17a-4 compliance automation. French asset managers concentrate investment here to satisfy AMF audit frequency requirements.
- Education:Student information protection with FERPA-aligned consent management and research data stewardship protocols.
- Government:Classified information handling with national security clearance integration and cross-border sharing restrictions.
Healthcare captures the largest committed spend; Financial Services shows the steepest expansion trajectory as algorithmic trading documentation demands intensify.
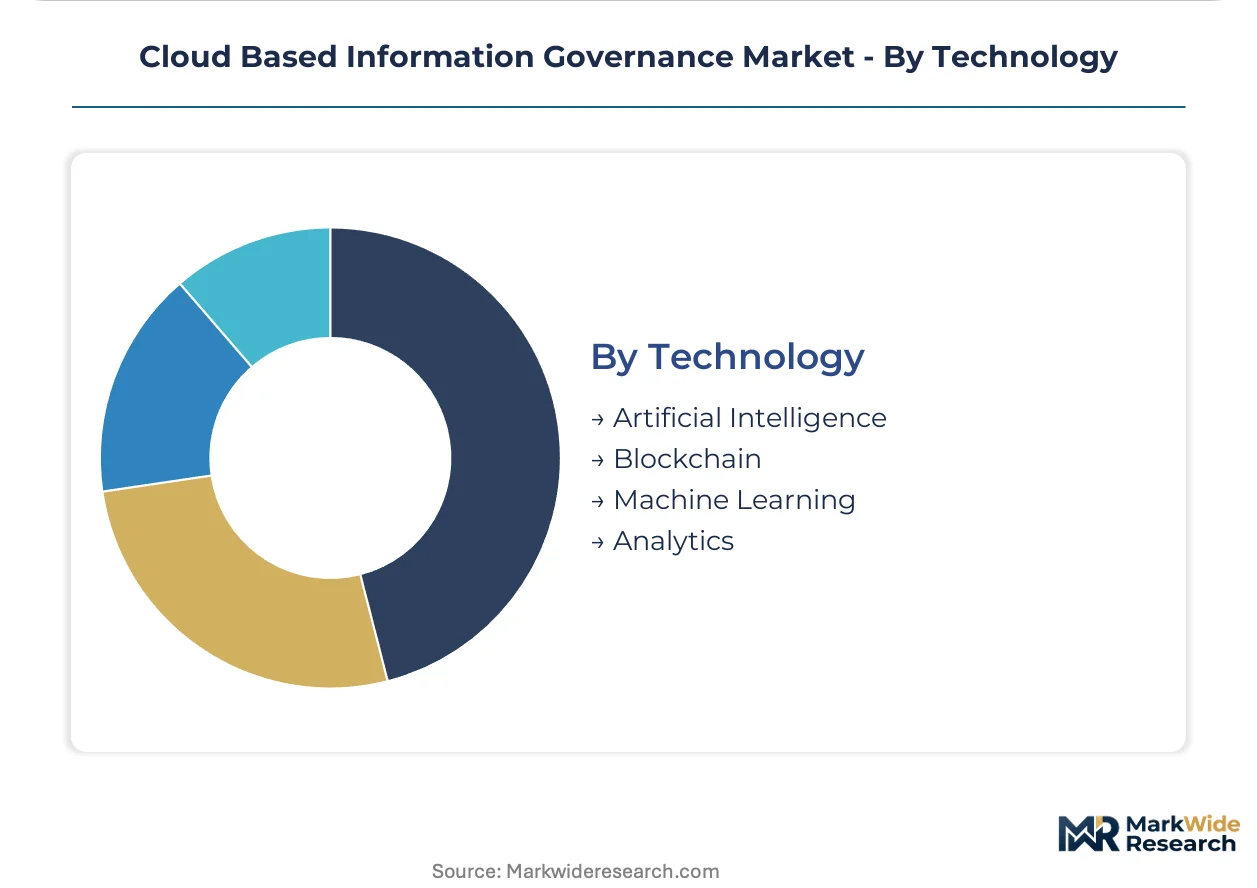
Technology:
Automation sophistication separates legacy buyers from digital-native adopters — mature organizations deploy AI for unstructured data discovery while laggards rely on rule-based classification.
- Artificial Intelligence:Natural language processing pipelines that identify sensitive entities in documents, images, and audio without predefined patterns. German legal services firms deploy these tools to compress contract review timelines from weeks to days.
- Machine Learning:Behavioral anomaly detection for insider threat identification and access pattern analysis.
- Blockchain:Distributed ledger notarization for immutable audit trails and provenance verification in supply chain documentation.
- Analytics:Dashboard-driven visibility into data lineage, retention compliance status, and policy violation trends.
Artificial Intelligence dominates current procurement cycles; Blockchain implementations remain exploratory pending interoperability standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt Rhine-Main metropolitan region concentrates European cloud governance investment through data center tax incentives and GDPR enforcement infrastructure. Healthcare digitization and financial compliance mandates drive procurement across four major economies.
Germany
BaFin record-keeping rules and the EU AI Act propel demand from Frankfurt asset managers and Munich automotive suppliers. The KBA enforces technical documentation standards for connected vehicle data. Bavarian pharmaceutical distributors deploy automated lineage tools to satisfy EMA pharmacovigilance requirements.
United Kingdom
NHS trusts consolidate fragmented governance systems to manage genomic data repositories under UK GDPR. The Information Commissioner's Office intensifies enforcement against deficient record-keeping. London financial institutions favor hybrid architectures to retain trading records domestically while leveraging cloud analytics.
France
CNIL enforcement protocols drive patient data protection spending at Paris healthcare networks. The EU AI Act mandates explainable decision logs for credit scoring workflows. Lyon pharmaceutical clusters adopt graph-based lineage engines for supply chain documentation compliance.
United States
HIPAA enforcement and SEC 17a-4 rules shape procurement from New York financial services and Boston healthcare systems. The FDA requires technical documentation standards for AI-enabled medical devices. Silicon Valley technology firms concentrate investment in multi-cloud policy orchestration tools.
Japan
METI guidelines on data free flow with trust accelerate adoption among Tokyo financial institutions and Osaka manufacturing conglomerates. The PMDA imposes pharmacovigilance data retention requirements. Yokohama pharmaceutical clusters integrate governance platforms with legacy mainframe environments.
Cloud Based Information Governance Market Vendor Landscape
Top-tier vendors anchor enterprise compliance workflows, while mid-market specialists compete on managed service delivery. The vendor base stratifies across three tiers: hyperscaler-native platforms, legacy enterprise integrators, and vertical-specific specialists. Dominant competitive moves include strategic partnerships with system integrators and geographic expansion through localized data center deployments.
Within the hyperscaler tier, Microsoft Corporation and Amazon Web Services exemplify platform-scale competition. IBM Corporation occupies a distinct position bridging legacy mainframe governance with cloud-native orchestration. These three entities represent divergent strategic archetypes: Azure Purview demonstrates compliance workflow anchoring, AWS Macie illustrates object-level policy granularity, and IBM Cloud Pak embodies hybrid integration capabilities.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Amazon Web Services |
| Google LLC |
| Oracle Corporation |
| OpenText Corporation |
| Veritas Technologies |
| Informatica |
| Collibra |
| Others |
Supply Flow & Price Mechanics
Hyperscaler compute pricing indices cascade through cloud governance platform tiers, compressing mid-market SaaS margins while amplifying premium capture for compliance-certified deployments in regulated European jurisdictions.
Pricing Analysis
Short lead-time provisioning commands 15-30% premiums over annual committed-use contracts across the analysis window. Subscription-based SaaS tiers dominate, with price differentiation anchored in certification depth (ISO 27001, SOC 2 Type II) and jurisdictional coverage breadth. Cost compression in standard-tier offerings is intensifying because open-source alternatives erode baseline functionality pricing. Mid-market professional services firms exhibit highest price sensitivity; financial institutions in Frankfurt and London demonstrate lowest elasticity due to regulatory penalty exposure.
Supply Chain Analysis
Specialized AI training infrastructure supply rests on NVIDIA-dominated GPU fabrication in Taiwan, South Korea, and the United States, with secondary dependencies on custom ASIC development from Google and Amazon. Raw material inputs span silicon wafers, high-bandwidth memory modules, and liquid cooling systems. Single-source vulnerability concentrates in advanced node semiconductor manufacturing. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with professional services attach rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act imposes algorithmic accountability documentation burdens that function as a compliance moat, elevating procurement thresholds for vendors lacking automated audit trail capabilities.
For Market Incumbents: Anticipate open-source governance tooling substitution by embedding managed compliance services that bundle ISO 27001 certification maintenance with platform subscriptions. Fortify hybrid cloud orchestration capabilities to capture financial services workloads split between on-premises vaults and hyperscaler regions. Vertical integration into edge computing governance agents addresses manufacturing sector expansion.
For New Entrants and Emerging Players: German mid-market professional services firms lack dedicated compliance personnel and present concentrated white-space opportunity. Target managed governance service bundles with usage-metered pricing that eliminates upfront capital barriers. Pursue channel partnerships with regional system integrators possessing existing BaFin and CNIL relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertical-specific specialists with pre-built regulatory content packs in France and Germany. Long-term viability hinges on sustained enforcement intensity from the Information Commissioner's Office and BaFin. Watch for EU AI Act delegated act clarifications as inflection indicators for compliance tooling standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified metadata control planes satisfy multi-cloud policy synchronization demands from German industrial conglomerates. |
| Geographic Expansion | Localized Frankfurt and London data center deployments address GDPR data residency requirements for financial services. |
| Strategic Partnership | System integrator alliances accelerate NHS trust consolidation of fragmented genomic data governance systems. |
| Acquisition of Specialist Firm | Graph-based lineage engine capabilities satisfy EMA pharmacovigilance documentation mandates for pharmaceutical distributors. |
| Product Launch | Edge-native governance agents capture federated policy orchestration demand from French manufacturing facilities. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with chief information security officers, compliance directors at NHS trusts and French healthcare networks, cloud procurement leads at German automotive suppliers, and data protection officers subject to CNIL enforcement protocols. SEC 10-K disclosures, EMA submission documents, hyperscaler capex reports, and ISO certification registries provided quantitative foundations. Bottom-up deployment counts and top-down market sizing underwent iterative reconciliation.
Data-stream reconciliation across deployment model, organization size, vertical regulatory exposure, integration complexity, and regional adoption pattern dimensions shaped analytical frameworks. CAGRs derived from segmented growth rate modeling with cross-validation against technology adoption curves. Industry-specific inputs encompassed EU AI Act implementation timelines, BaFin record-keeping rule amendments, and NHS digital transformation budget allocations.
Revisions become necessary when regulatory enforcement intensity shifts, hyperscaler pricing architectures transform, or open-source tooling functionality achieves parity with proprietary platforms. Forecasts reflect documented assumptions regarding sustained GDPR and EU AI Act compliance obligation expansion. Regulatory guidance clarifications, cross-border data transfer mechanism rulings, and certified data steward supply constraints warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
Global Cloud Office Services Market
Cloud Computing
Cloud Migration Services Market
Cloud Computing
Israel Cloud Computing Market
Cloud Computing
SME Cloud Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Cognitive Cloud Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Europe Cloud Computing Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
Automotive Cloud Based System Market
Cloud Computing
Spain Cloud Computing Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
Cloud Services Market
Cloud Computing
Asia Pacific Cloud Computing Market
Cloud Computing
India Cloud Computing Market