
 Cloud Computing in Industrial IoT Market | 2026-2036
Cloud Computing in Industrial IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Computing in Industrial IoT Market Analysis
ISO/IEC 27001 certification is unwinding competitive access for platform providers serving critical infrastructure operators. Microsoft Corporation leverages its Azure Industrial IoT stack to dominate manufacturing deployments across North American automotive hubs. Amazon Web Services anchors its position through backward integration into edge hardware partnerships with semiconductor vendors. Siemens specializes in hybrid cloud architectures that bridge on-premise SCADA systems with elastic compute resources.
Cloud computing in industrial IoT denotes the delivery of on-demand compute, storage, and analytics services to connected manufacturing assets via distributed data centers, typically operating with sub-50 millisecond latency thresholds for real-time process control. Its primary purpose is to transform operational technology data into actionable intelligence without capital-intensive local infrastructure. Hybrid cloud deployment captures the dominant margin pool as enterprises balance data sovereignty requirements against elastic scalability needs. Edge computing technology is accelerating fastest where AI-driven quality inspection demands millisecond response times. Predictive maintenance application segments concentrate demand from energy and transportation end users seeking to minimize unplanned downtime.
The EU AI Act and NIST Cybersecurity Framework are reshaping product standards for autonomous industrial systems, forcing platform providers to embed explainability and audit trails into machine learning pipelines. Germany's BSI IT-Grundschutz requirements add another compliance layer for cross-border data flows in European manufacturing networks. China's MIIT GB standards mandate localized data processing for critical industrial infrastructure, fragmenting architectural choices for multinational deployments. Stakeholders must decide whether to architect region-specific compliance stacks or pursue unified platforms with modular sovereignty controls.
Market Dynamics
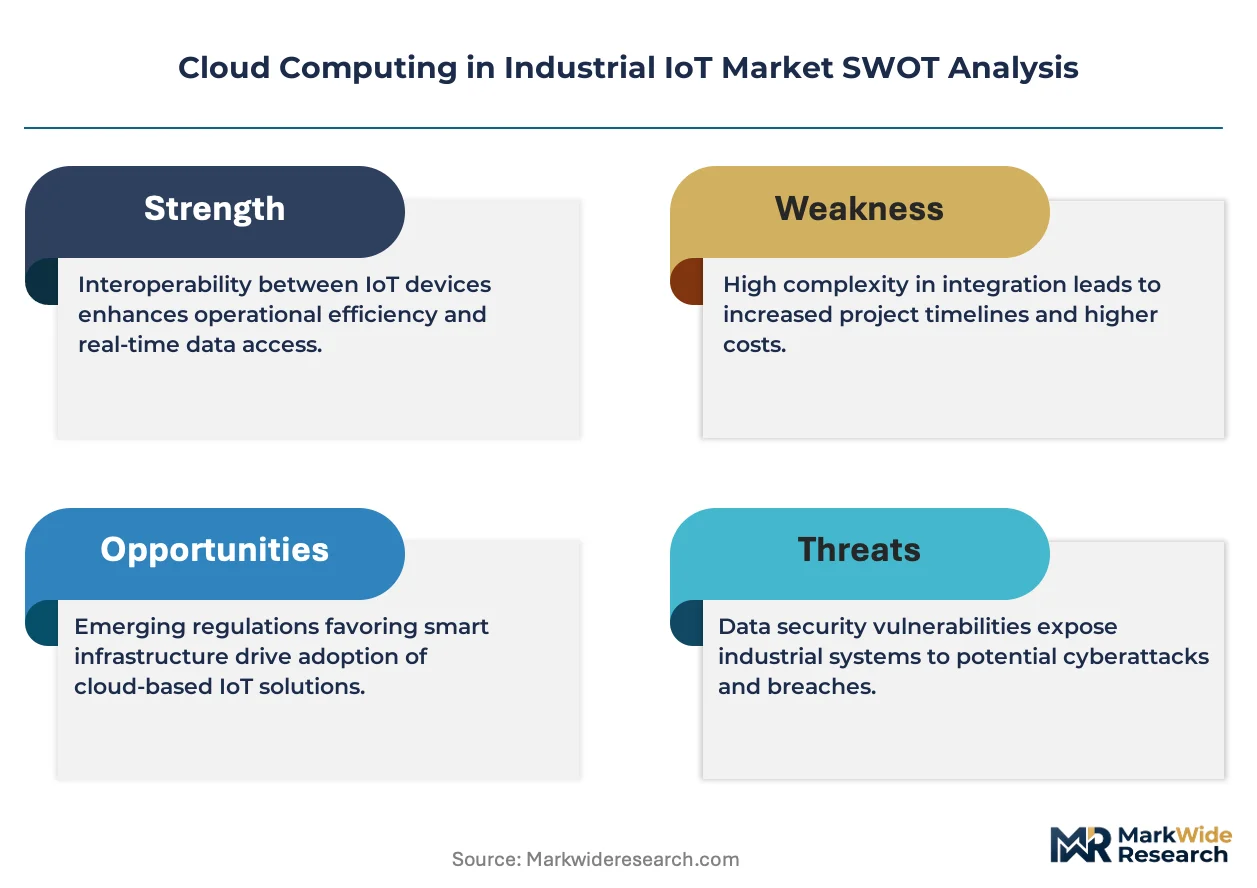
The EU AI Act is compressing architectural freedom for platform providers, forcing explainability modules into machine learning pipelines while NIST Cybersecurity Framework mandates reshape North American deployment standards.
Growth Catalysts
- EU AI Act compliance mandates:The regulation requires audit trails for automated industrial decisions, creating pull for platforms with embedded governance tooling.
- Predictive maintenance platforms:Manufacturing operators in Germany's Ruhr industrial cluster are expanding adoption to minimize unplanned downtime across energy assets.
- Edge-AI convergence:Semiconductor vendors are integrating neural processing units directly into industrial gateways, enabling sub-50 millisecond quality inspection response times.
Market Restraints
- Data sovereignty fragmentation:China's MIIT GB standards mandate localized processing for critical infrastructure, complicating multinational architectural choices.
- Certification timeline bottlenecks:ISO/IEC 27001 accreditation cycles for critical infrastructure operators extend 14-18 months, delaying platform access.
- Legacy SCADA integration costs:Hybrid cloud architectures require expensive protocol translation layers to bridge on-premise systems with elastic compute resources.
Strategic Opportunities
- Underpenetrated transportation verticals:Rail and maritime operators lag manufacturing in cloud-connected asset monitoring, representing white space for predictive maintenance vendors.
- Modular sovereignty controls:Platforms offering region-specific compliance stacks can capture multinational deployments without full architectural fragmentation.
- Energy sector AI inspection:Wind turbine blade and pipeline integrity monitoring using computer vision remains nascent, with millisecond latency requirements favoring edge-native architectures.
Industry Challenges
- OT-IT security expertise scarcity:Industrial control system cybersecurity skills remain concentrated among specialists familiar with both Purdue model layers and cloud-native tooling.
- Cross-border data flow complexity:Germany's BSI IT-Grundschutz requirements add compliance layers that conflict with elastic scalability benefits in European manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Computing in Industrial IoT Market |
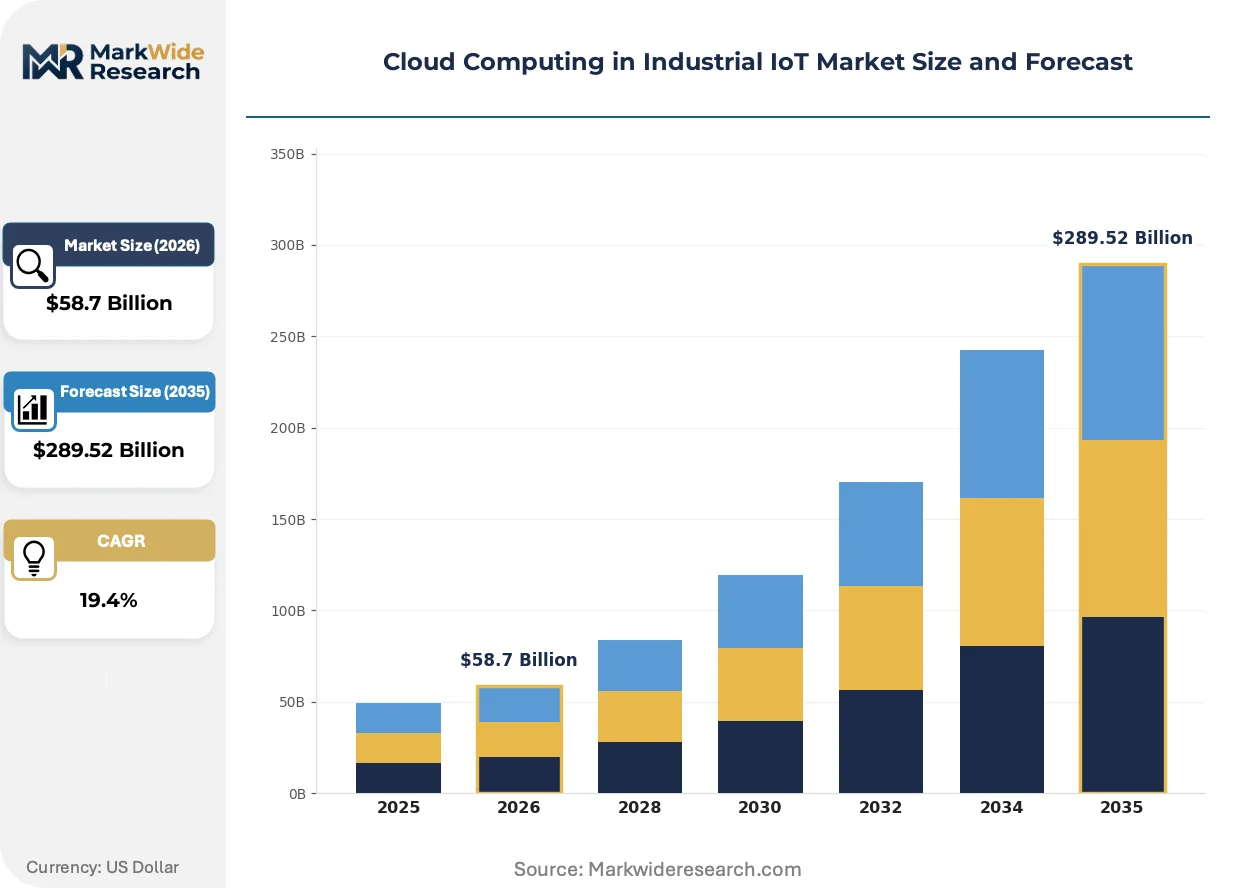
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $289.52 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Technology: Edge Computing, Big Data Analytics, Machine Learning, Artificial Intelligence End User: Manufacturing, Supply Chain, Energy, Transportation Application: Asset Monitoring, Predictive Maintenance, Inventory Management, Process Automation |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Cisco Systems, Huawei Technologies, General Electric, Siemens, IBM Corporation, Honeywell International, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Computing in Industrial IoT Market Emerging Trajectories
Architectural patterns in industrial IoT are fragmenting as sovereignty requirements clash with latency demands, forcing innovation in modular platform design and hybrid orchestration layers.
Containerized microservices architectures are decomposing monolithic SCADA systems into discrete, API-driven functions. Automotive manufacturers in Stuttgart and Detroit are piloting these modular stacks for production line reconfiguration. The shift is compressing vendor lock-in periods while enabling faster substitution of individual analytics components.
REACH chemical safety disclosures and EU AI Act algorithmic transparency mandates are converging to reshape supplier qualification processes. Industrial platform providers must now document training data provenance and model decision boundaries alongside traditional material safety documentation. German chemical processors and French aerospace suppliers face the steepest compliance ramps, driving demand for integrated governance dashboards.
Consumption patterns are rotating from perpetual licensing toward usage-metered platform subscriptions. Mid-sized discrete manufacturers in Bavaria and Michigan are abandoning multi-year enterprise agreements for elastic consumption models tied to connected asset counts. Channel partners are restructuring compensation around ongoing data throughput rather than upfront deployment fees, with systems integrators in industrial clusters capturing recurring revenue streams.
Cloud Computing in Industrial IoT Market Segmentation
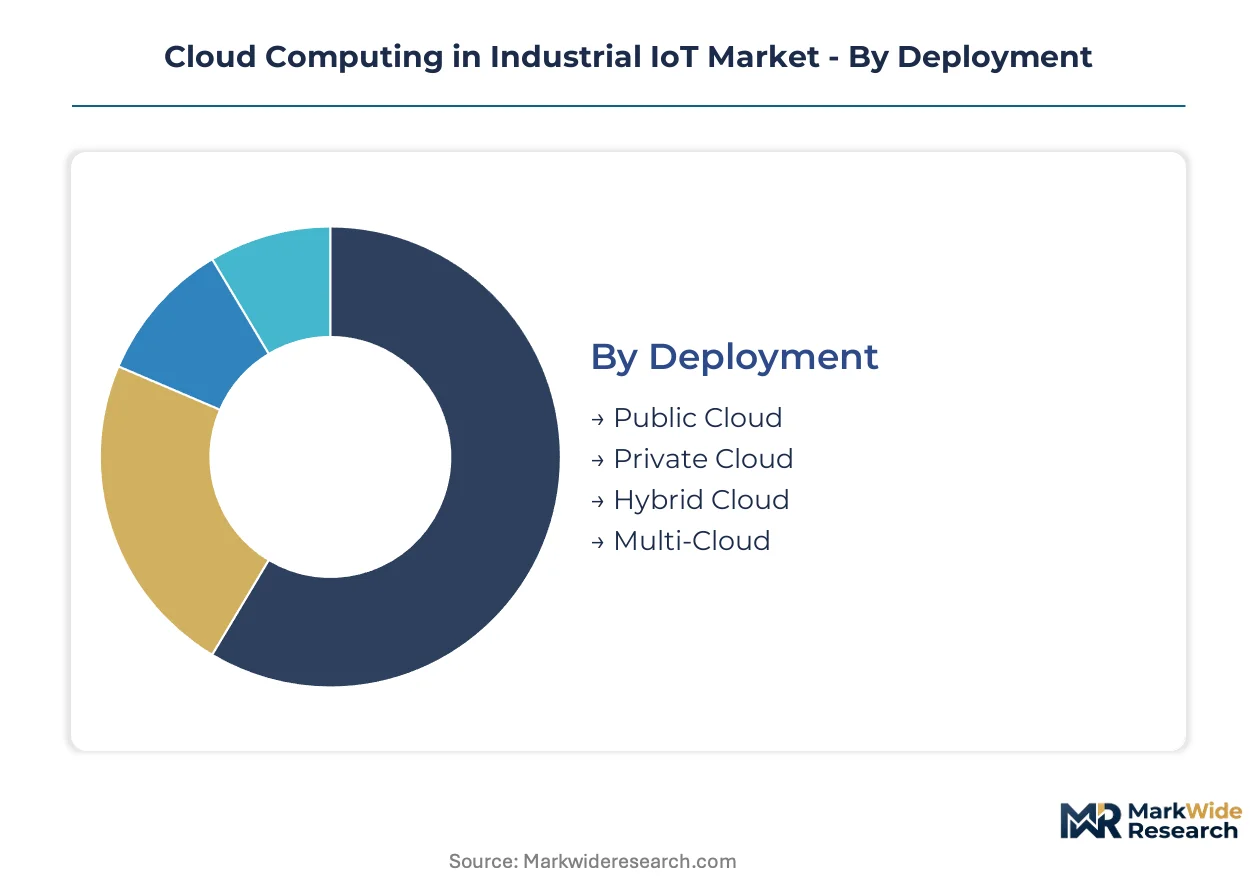
Architectural choices in industrial IoT cloud deployments fragment sharply across sovereignty requirements and latency thresholds. Each segmentation dimension carries distinct regulatory weight and margin implications for platform providers.
Deployment:
EU AI Act audit trail mandates and China's MIIT GB data localization rules split architectural preferences across jurisdictional boundaries.
- Hybrid Cloud:Bridges on-premise SCADA systems with elastic compute resources through orchestration layers that satisfy Germany's BSI IT-Grundschutz cross-border requirements. German automotive manufacturers in Stuttgart and Ruhr industrial cluster operators favor this architecture for balancing data sovereignty against scalability needs.
- Public Cloud:Delivers on-demand compute via distributed data centers operating under sub-50 millisecond latency thresholds for real-time process control. North American automotive hubs concentrate demand where NIST Cybersecurity Framework compliance suffices without localized infrastructure mandates.
- Private Cloud:Dedicated infrastructure deployments serving critical infrastructure operators requiring ISO/IEC 27001 certification cycles spanning 14-18 months.
- Multi-Cloud:Distributed workloads across competing hyperscaler platforms to mitigate vendor concentration risk in multinational manufacturing networks.
Hybrid Cloud handles the majority of throughput; Multi-Cloud is expanding most quickly on share.
Technology:
Millisecond response requirements for AI-driven quality inspection reshape technology adoption curves across manufacturing verticals.
- Edge Computing:Neural processing units integrated directly into industrial gateways enable sub-50 millisecond quality inspection response times. Semiconductor vendors anchor partnerships with cloud providers for backward integration into hardware layers serving wind turbine blade monitoring applications.
- Artificial Intelligence:Computer vision pipelines for pipeline integrity and predictive maintenance demand explainability modules under EU AI Act algorithmic transparency mandates. French aerospace suppliers and German chemical processors face steepest compliance ramps.
- Machine Learning:Embedded audit trails for automated industrial decisions satisfy regulatory governance tooling requirements.
- Big Data Analytics:Operational technology transformation into actionable intelligence without capital-intensive local infrastructure.
Edge Computing commands the dominant margin pool; Artificial Intelligence is climbing the fastest on deployment velocity.
End User:
Consumption patterns rotate from perpetual licensing toward usage-metered subscriptions tied to connected asset counts.
- Manufacturing:Mid-sized discrete manufacturers in Bavaria and Michigan abandon multi-year enterprise agreements for elastic consumption models. Containerized microservices architectures decompose monolithic SCADA systems into API-driven functions for production line reconfiguration.
- Energy:Wind turbine blade and pipeline integrity monitoring using computer vision remains nascent, with millisecond latency requirements favoring edge-native architectures. Predictive maintenance platforms minimize unplanned downtime across generation and transmission assets.
- Transportation:Rail and maritime operators lag manufacturing in cloud-connected asset monitoring, representing white space for predictive maintenance vendors.
- Supply Chain:Inventory visibility systems integrate with ERP layers through hybrid orchestration protocols.
Manufacturing absorbs the largest deployment volume; Transportation is gaining share fastest as underpenetrated verticals convert.
Application:
REACH chemical safety disclosures and EU AI Act transparency mandates converge to reshape supplier qualification processes.
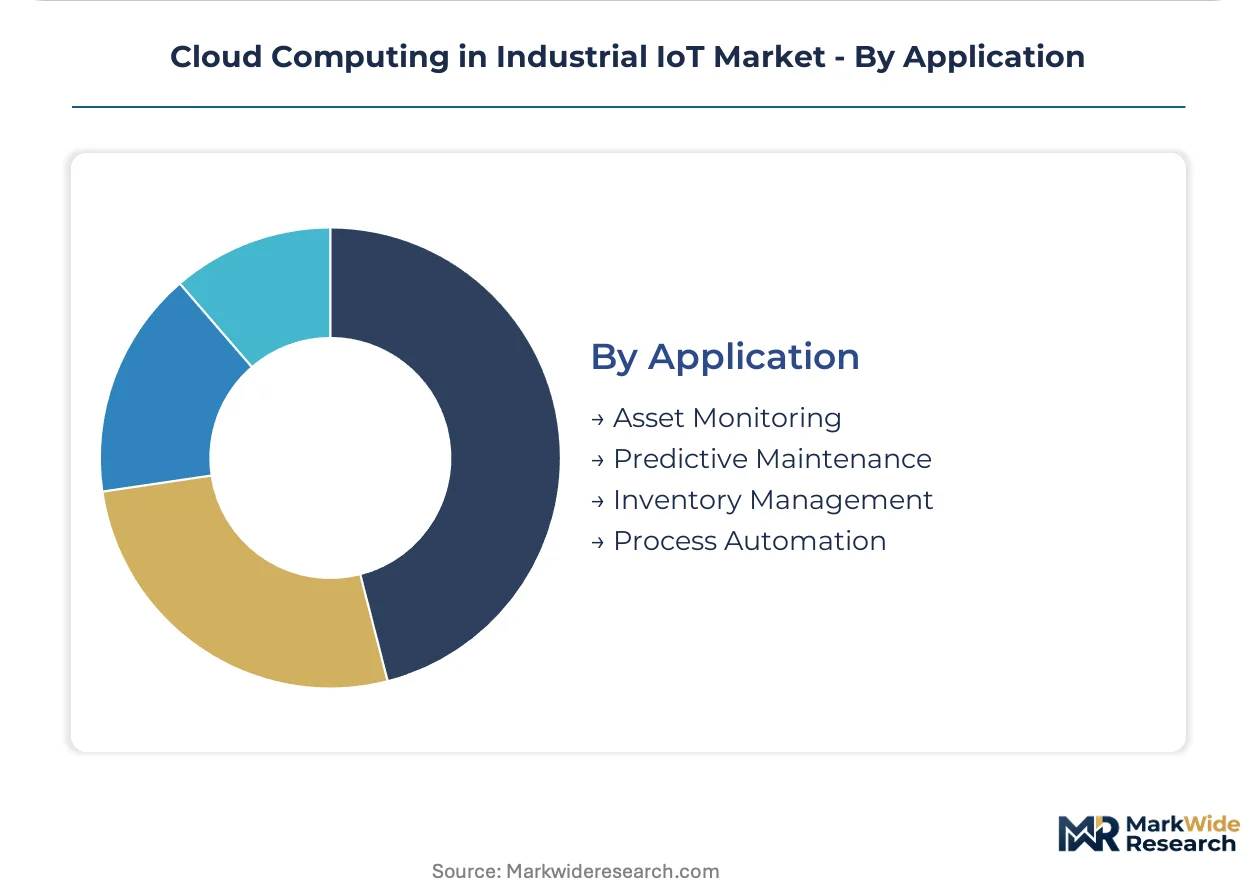
- Predictive Maintenance:Platforms concentrate demand from energy and transportation end users seeking to minimize unplanned downtime. Channel partners restructure compensation around ongoing data throughput rather than upfront deployment fees.
- Asset Monitoring:Connected device telemetry streams require governance dashboards documenting training data provenance alongside traditional material safety documentation.
- Process Automation:Real-time control loops demand sub-50 millisecond latency thresholds from distributed data center architectures.
- Inventory Management:Elastic scalability benefits conflict with Germany's BSI IT-Grundschutz cross-border data flow requirements in European manufacturing networks.
Predictive Maintenance captures the dominant revenue share; Asset Monitoring is expanding most rapidly on adoption velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform procurement concentrates among discrete manufacturers seeking elastic compute for predictive maintenance, with energy operators and transportation networks trailing in adoption velocity. Regulatory fragmentation across data sovereignty mandates splits architectural preferences by jurisdiction. Industrial clusters in Germany, the United States, China, Japan, and India anchor deployment concentration.
Germany
Automotive manufacturers in Stuttgart and Ruhr industrial cluster operators drive hybrid cloud adoption to balance scalability against BSI IT-Grundschutz cross-border requirements. The EU AI Act mandates audit trails for automated industrial decisions, forcing explainability modules into machine learning pipelines. Bavarian mid-sized discrete manufacturers abandon multi-year enterprise agreements for usage-metered subscriptions tied to connected asset counts.
United States
North American automotive hubs concentrate public cloud demand where NIST Cybersecurity Framework compliance suffices without localized infrastructure mandates. The FAA and FERC impose sector-specific operational technology cybersecurity standards on critical infrastructure operators. Detroit manufacturers pilot containerized microservices architectures that decompose monolithic SCADA systems into API-driven functions for production line reconfiguration.
China
MIIT GB standards mandate localized data processing for critical industrial infrastructure, fragmenting architectural choices for multinational deployments. The country's dual carbon goals accelerate edge-native architectures for wind turbine blade monitoring applications. Yangtze River Delta manufacturing networks favor private cloud deployments requiring ISO/IEC 27001 certification cycles spanning 14-18 months.
Japan
METI industrial digitization programs channel investment toward edge-AI convergence for semiconductor quality inspection demanding sub-50 millisecond response times. JIS standards govern interoperability between on-premise SCADA systems and elastic compute resources. Kansai region automotive suppliers and Chubu precision manufacturers anchor hybrid cloud throughput in the Asia-Pacific theater.
India
PLI scheme incentives for electronics manufacturing and industrial machinery attract cloud platform providers serving export-oriented production networks. BIS certification requirements add compliance layers for critical infrastructure cybersecurity. Tamil Nadu and Gujarat industrial corridors concentrate demand from automotive component suppliers adopting predictive maintenance platforms to minimize unplanned downtime.
Cloud Computing in Industrial IoT Market Vendor Landscape
Player mix skews toward hyperscaler-backed industrial platforms and legacy automation vendors with cloud-native extensions, creating a bifurcated structure where scale advantages concentrate among full-stack providers. The competitive terrain splits between consolidated hyperscaler dominance in North American automotive hubs and fragmented regional specialization across European and Asian industrial clusters. Strategic archetypes include backward-integrated cloud providers, hybrid orchestration specialists, and edge-hardware-anchored platform vendors. Dominant competitive moves encompass edge hardware partnerships with semiconductor vendors and modular sovereignty controls for multinational compliance stacks.
Within the hyperscaler tier, Microsoft Corporation and Amazon Web Services exemplify divergent integration strategies, with the former leveraging manufacturing deployment dominance and the latter anchoring position through semiconductor vendor alliances. Siemens occupies a position among hybrid orchestration specialists bridging on-premise SCADA systems with elastic compute resources. These three entities represent the primary competitive anchors shaping platform procurement decisions across German automotive clusters and North American industrial hubs.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| Cisco Systems |
| Huawei Technologies |
| General Electric |
| Siemens |
| IBM Corporation |
| Honeywell International |
| Intel Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity reservation agreements with hyperscaler cloud providers lock in compute access and price visibility for industrial IoT platform operators, binding German automotive manufacturers and Ruhr cluster energy operators to multi-year commitments that hedge against spot-market volatility in GPU and edge hardware procurement.
Pricing Analysis
Cost-plus contracts indexed to semiconductor foundry capacity utilization govern hyperscaler infrastructure pricing, with subscription tiers stratifying across premium sovereign-cloud, standard hybrid, and economy public-cloud service levels. Price differentiation hinges on ISO/IEC 27001 certification grade and data residency controls, with certified private cloud deployments commanding substantial premiums over uncertified alternatives. Pricing pressure stems from edge-AI hardware commoditization as neural processing units penetrate industrial gateway markets. Mid-sized discrete manufacturers in Bavaria and Michigan exhibit highest price sensitivity, while critical infrastructure operators absorbing ISO/IEC 27001 accreditation delays show lowest elasticity.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors constrain European edge hardware deployment timelines, with container availability fluctuations rippling through semiconductor vendor distribution networks. Supply concentrates in Taiwan for advanced neural processing units, South Korea for memory components, and China for industrial gateway assembly. Raw material dependencies span silicon wafers, rare earth elements for magnetics, and copper for connectivity infrastructure. Single-source vulnerability in TSMC's leading-edge fabrication exposes platform providers to allocation risk. Distribution runs through authorized systems integrators anchored in Stuttgart, Detroit, and Shenzhen industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in industrial IoT cloud computing hinge on API interoperability standards that decompose monolithic SCADA architectures, with containerized microservices adoption in Stuttgart and Detroit automotive plants signaling ecosystem inflection toward modular substitution.
For Market Incumbents: Secure hybrid orchestration intellectual property through targeted acquisition of edge-native software stacks, insulating against hyperscaler backward integration into semiconductor partnerships. Fortify channel control over systems integrators in Germany's Ruhr industrial cluster to lock out emerging platform competitors. Prioritize ISO/IEC 27001 certification investment cycles to maintain access barriers against uncertified challengers in critical infrastructure verticals. For New Entrants and Emerging Players: Anchor in underpenetrated rail and maritime transportation verticals where predictive maintenance platform adoption lags manufacturing by multiple deployment cycles. Target wind turbine blade inspection applications in China's Yangtze River Delta, where millisecond latency requirements favor edge-native architectures over incumbent hybrid solutions. Pursue OEM co-development partnerships with industrial gateway semiconductor vendors to bypass direct hyperscaler competition. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid orchestration specialists bridging legacy SCADA protocols with cloud-native microservices, positioned for consolidation as platform economics favor full-stack providers. Monitor EU AI Act enforcement velocity as inflection signal—accelerated audit trail mandates will compress architectural freedom and privilege incumbents with embedded governance tooling.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Hardware Partnership | Semiconductor vendor alliances with cloud providers enable sub-50 millisecond quality inspection response times. |
| Modular Sovereignty Controls | Region-specific compliance stacks capture multinational deployments without full architectural fragmentation. |
| ISO/IEC 27001 Certification Investment | Accreditation cycles spanning 14-18 months create sustained access barriers for critical infrastructure operators. |
| Containerized Microservices Migration | API-driven decomposition of monolithic SCADA systems enables faster production line reconfiguration in automotive hubs. |
| Predictive Maintenance Platform Expansion | Usage-metered subscriptions tied to connected asset counts capture recurring revenue from energy and transportation verticals. |
Methodological Framework
A spread of perspectives from plant engineers, IT procurement officers, systems integrators, and hyperscaler platform specialists converged on the working assumptions underlying deployment velocity and compliance cost estimates. Primary interviews with maintenance directors at German automotive manufacturers and channel partners in Michigan industrial corridors combined with secondary validation from SEC hyperscaler capex disclosures, BSI IT-Grundschutz documentation, and EU AI Act regulatory filings. Bottom-up connected asset counts and top-down infrastructure spend estimates triangulated on market sizing.
Segmentation dimensions modeled span deployment architecture, edge-AI technology layer, end-user vertical, and application type across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating EU AI Act compliance lag effects and MIIT GB localization mandates. Forecast inputs included semiconductor foundry capacity expansion schedules and ISO/IEC 27001 accreditation throughput constraints.
Underlying assumptions cover sustained hyperscaler infrastructure investment, regulatory enforcement continuity, and edge hardware cost curves, with deviation risk concentrated in trade policy fragmentation affecting semiconductor supply chains and accelerated EU AI Act implementation timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Web Service Cloud Market
Cloud Computing
Public Finance Cloud Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Commerce Cloud Market
Cloud Computing
Cloud VPN Market
Cloud Computing
Cloud Computing Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Global Cloud Based ITSM Market
Cloud Computing
Cloud Based Information Governance Market
Cloud Computing
GPU Virtualization Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
VM Service Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
Japan Cloud Computing Market