
 Cognitive Cloud Market | 2026-2036
Cognitive Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Cloud Market Analysis
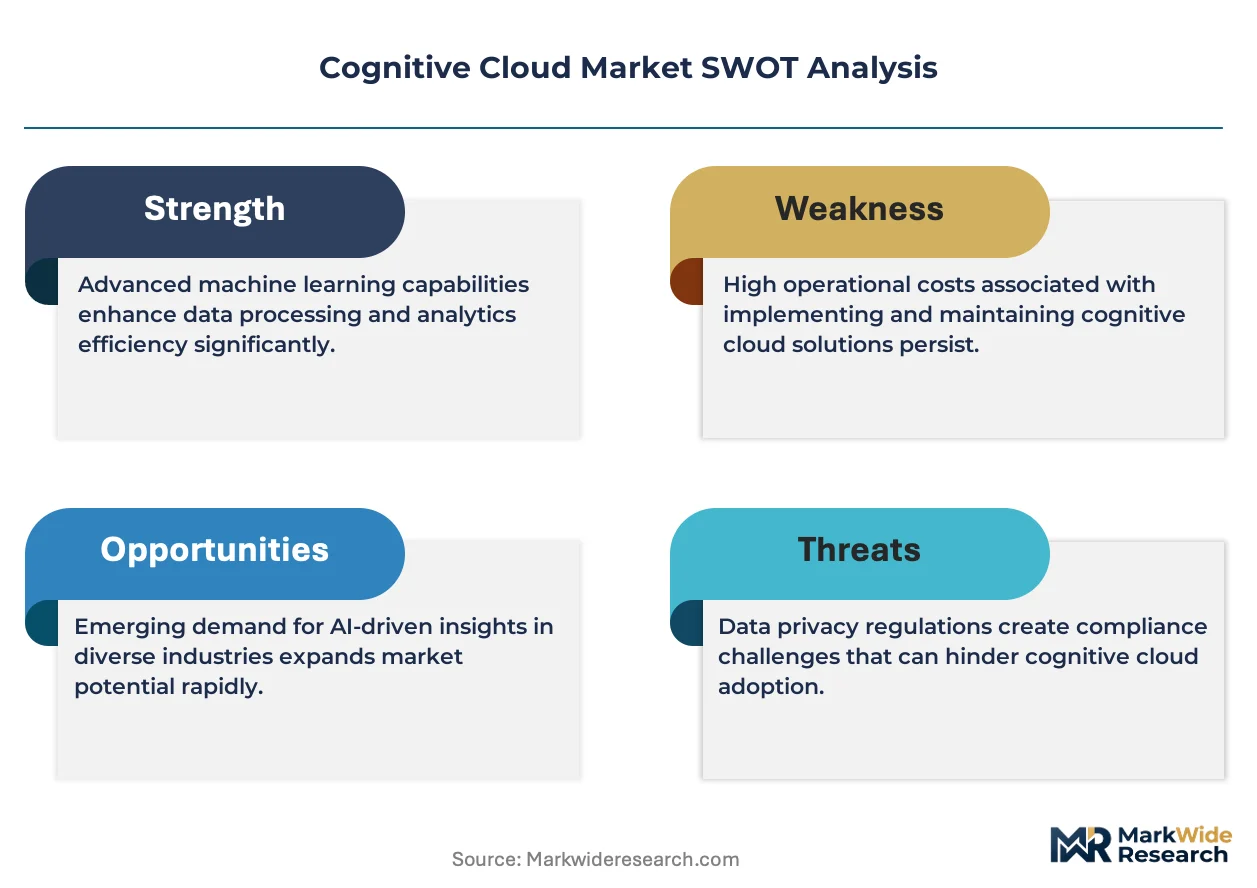
Cloud AI engineering talent scarcity is unwinding as universities and bootcamps expand machine learning curricula, yet the gap between supply and demand persists across enterprise implementations. IBM leverages its Watson platform heritage to sustain consulting-led deployment models for regulated industries. Google anchors its competitive stance through custom TPU availability and deep integration with open-source frameworks. Amazon Web Services dominates infrastructure provisioning with breadth across compute tiers and geographic availability zones.
Cognitive cloud denotes distributed computing architectures that embed artificial intelligence, natural language processing, and machine learning inference directly into cloud service layers, typically operating across API-accessible models with sub-100-millisecond latency thresholds for real-time decisioning. These systems process unstructured data streams to automate classification, prediction, and generative outputs for enterprise workflows. Hybrid cloud deployment is gaining structural prominence as organizations reconcile data sovereignty requirements with elastic compute needs, while Software as a Service solutions capture expanding margin pools through recurring revenue models. Healthcare and BFSI end users represent the most contested verticals, with compliance-sensitive workloads driving premium pricing for private cloud cognitive infrastructure.
FDA scrutiny of AI-enabled diagnostic tools intersects with HIPAA data handling mandates to shape product development roadmaps for healthcare-facing cognitive cloud vendors. The EU AI Act establishes conformity assessment obligations that condition market access on risk-tiered documentation and human oversight protocols. Stakeholders must weigh regulatory fragmentation against standardization momentum when selecting deployment architectures and geographic data residency strategies.
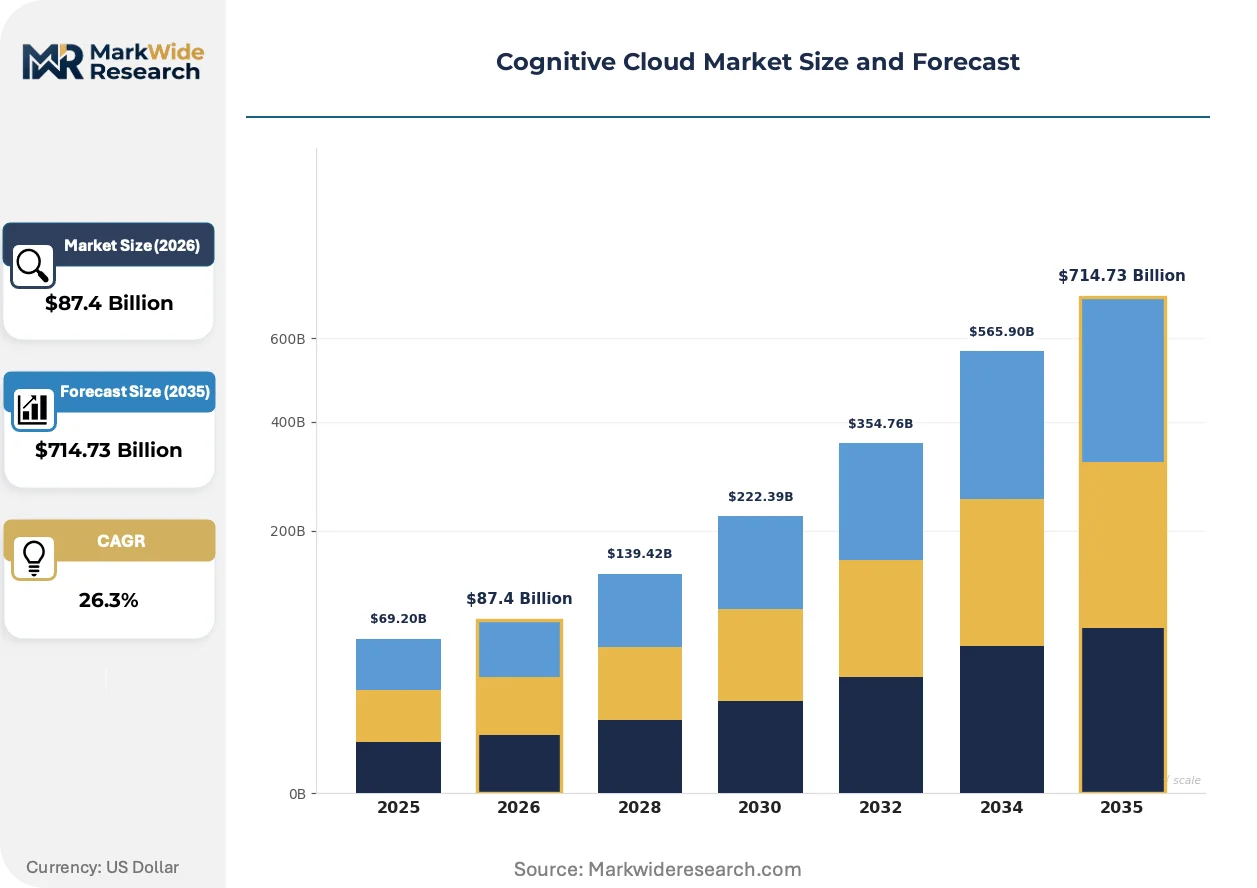
Market Dynamics
Hybrid cloud deployment architectures are displacing pure public cloud strategies as healthcare and financial services organizations reconcile HIPAA data sovereignty mandates with elastic compute requirements. The EU AI Act's risk-tiered conformity assessments are forcing vendors to restructure product roadmaps around human oversight protocols.
Growth Catalysts
- FDA Pre-Certification Pathway:The FDA's streamlined approval framework for AI-enabled diagnostic software accelerates deployment timelines for radiology and pathology applications.
- Edge Inference Hardware:Custom TPU and NPU availability at sub-$500 unit economics enables real-time clinical decision support outside centralized data centers.
- Germany Healthcare Digitization:The country's Hospital Future Act allocates dedicated capital for cognitive cloud infrastructure in university medical centers.
Market Restraints
- GPU Supply Concentration:Advanced accelerator fabrication depends on TSMC's N4 process node, creating single-source vulnerability for training infrastructure.
- EU AI Act Documentation Burden:High-risk system conformity assessments require 12-18 month preparation cycles before market entry.
- On-Premises Legacy Integration:Mainframe-dependent BFSI institutions face middleware complexity that inflates deployment costs by 40-60% versus greenfield implementations.
Strategic Opportunities
- Brazil Healthcare Infrastructure:The country's unified health system lacks diagnostic AI penetration, creating first-mover advantage for cloud-native platforms.
- Federated Learning Architectures:Cross-institutional model training without raw data movement addresses HIPAA and GDPR constraints simultaneously.
- India PLI Scheme for Cloud:Production-linked incentives for data center infrastructure reduce effective compute costs for domestic cognitive service providers.
Industry Challenges
- MLOps Talent Scarcity:Pipeline engineering and model observability functions command 35-50% salary premiums over conventional DevOps roles.
- Multi-Cloud Orchestration Complexity:Kubernetes-native cognitive workloads require specialized platform engineering that most enterprise IT organizations lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Cloud Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $714.73 Billion |
| CAGR (2026 – 2036) | 26.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multicloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service End User: IT Services, BFSI, Healthcare, Manufacturing Solution: Data Analytics, Machine Learning, AI Integration, Cognitive Computing |
| Companies Covered | IBM, Microsoft, Google, Amazon Web Services, Salesforce, Oracle, SAP, CognitiveScale, Nuance Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Cloud Market Emerging Trajectories
Foundation model architectures are compressing development cycles for domain-specific cognitive applications. Vendors are repositioning around inference optimization and retrieval-augmented generation rather than raw training scale.
Small language model deployment is fragmenting the cognitive cloud stack. Healthcare IT departments are adopting 3-7 billion parameter models for clinical documentation and coding automation. These compressed architectures reduce per-query costs by 80% versus frontier models while maintaining diagnostic accuracy thresholds.
The EU AI Act's high-risk system obligations are restructuring vendor-customer contracting. Platform providers must now maintain technical documentation, risk management systems, and human oversight protocols for healthcare and credit scoring deployments. German and French health authorities are requiring conformity assessment pre-approvals before procurement eligibility.
Consumption-based pricing is displacing committed-use contracts in enterprise cognitive cloud procurement. Healthcare systems facing reimbursement uncertainty prefer per-inference billing for diagnostic AI tools. This shift is most pronounced in United States hospital networks, where capital budget volatility makes fixed commitments untenable.
Cognitive Cloud Market Segmentation
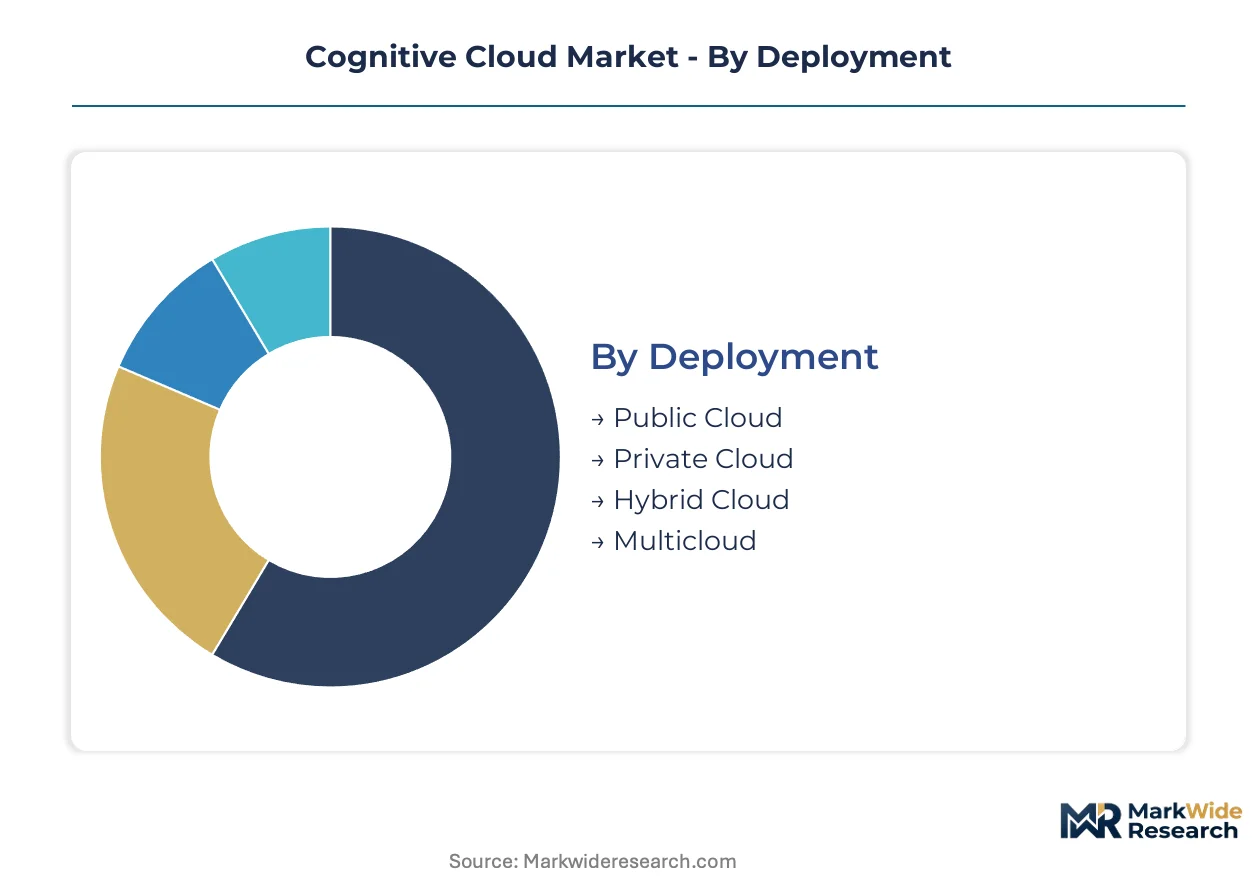
Cognitive cloud architectures fragment across deployment modes, service layers, and solution types that carry distinct compliance burdens and margin profiles. Understanding substitution pressures between public and private infrastructure, or between IaaS and SaaS consumption models, shapes vendor positioning and customer procurement strategies.
Deployment:
Hybrid architectures face the strongest substitution pressure as organizations reconcile HIPAA data sovereignty with elastic compute needs, while pure public cloud confronts regulatory displacement.
- Public Cloud:Shared infrastructure delivering API-accessible cognitive services with sub-100-millisecond latency for real-time decisioning. Healthcare systems in the United States favor consumption-based billing here for diagnostic AI tools facing reimbursement uncertainty.
- Private Cloud:Dedicated tenant environments hosting sensitive workloads with full data residency control. German university medical centers procure these under Hospital Future Act capital allocations to satisfy EU AI Act conformity pre-approvals.
- Hybrid Cloud:Orchestrated workload distribution across on-premises and off-premises resources. Financial services institutions deploy this architecture to maintain mainframe connectivity while accessing GPU training clusters.
- Multicloud:Cognitive services distributed across two or more hyperscaler environments. Enterprise IT organizations adopt this to mitigate TSMC N4 process node concentration risk for training accelerators.
Public cloud anchors the volume base while hybrid cloud gains share at the steepest rate.
Service Type:
Margin concentration follows the abstraction ladder upward, with infrastructure provisioning commoditizing fastest and application-layer services capturing expanding recurring revenue pools.
- Infrastructure as a Service:Bare-metal compute and storage provisioning for training and inference workloads. Amazon Web Services dominates this tier through geographic availability zone breadth across United States, Germany, and India.
- Platform as a Service:Managed Kubernetes and MLOps tooling for model lifecycle management. Talent scarcity in pipeline engineering commands 35-50% salary premiums that PaaS vendors capture through automation.
- Software as a Service:Pre-built cognitive applications with per-inference or seat-based pricing. United States hospital networks prefer this model given capital budget volatility and FDA pre-certification pathway acceleration.
- Function as a Service:Event-driven serverless execution for intermittent cognitive workloads. Edge inference deployments in Brazil's unified health system leverage this for cost-efficient diagnostic screening.
IaaS retains the largest revenue footprint while SaaS expands most quickly through consumption-based contracting displacement.
End User:
Compliance sensitivity varies sharply across verticals, with healthcare and financial services bearing the heaviest documentation burdens under EU AI Act and HIPAA mandates.
- Healthcare:Diagnostic imaging, clinical documentation automation, and patient data analytics. FDA scrutiny of AI-enabled tools intersects with HIPAA handling mandates to shape vendor product roadmaps.
- BFSI:Credit scoring, fraud detection, and algorithmic trading systems. Mainframe-dependent institutions face 40-60% deployment cost inflation versus greenfield implementations due to middleware complexity.
- IT Services:Internal cognitive infrastructure and client-facing AI consulting delivery. IBM Watson heritage sustains consulting-led deployment models for regulated industries in this segment.
- Manufacturing:Predictive maintenance, quality inspection, and supply chain optimization. Federated learning architectures address cross-facility model training without raw data movement.
Healthcare anchors the volume base while BFSI climbs the fastest as credit scoring AI faces expanding EU AI Act high-risk classification.
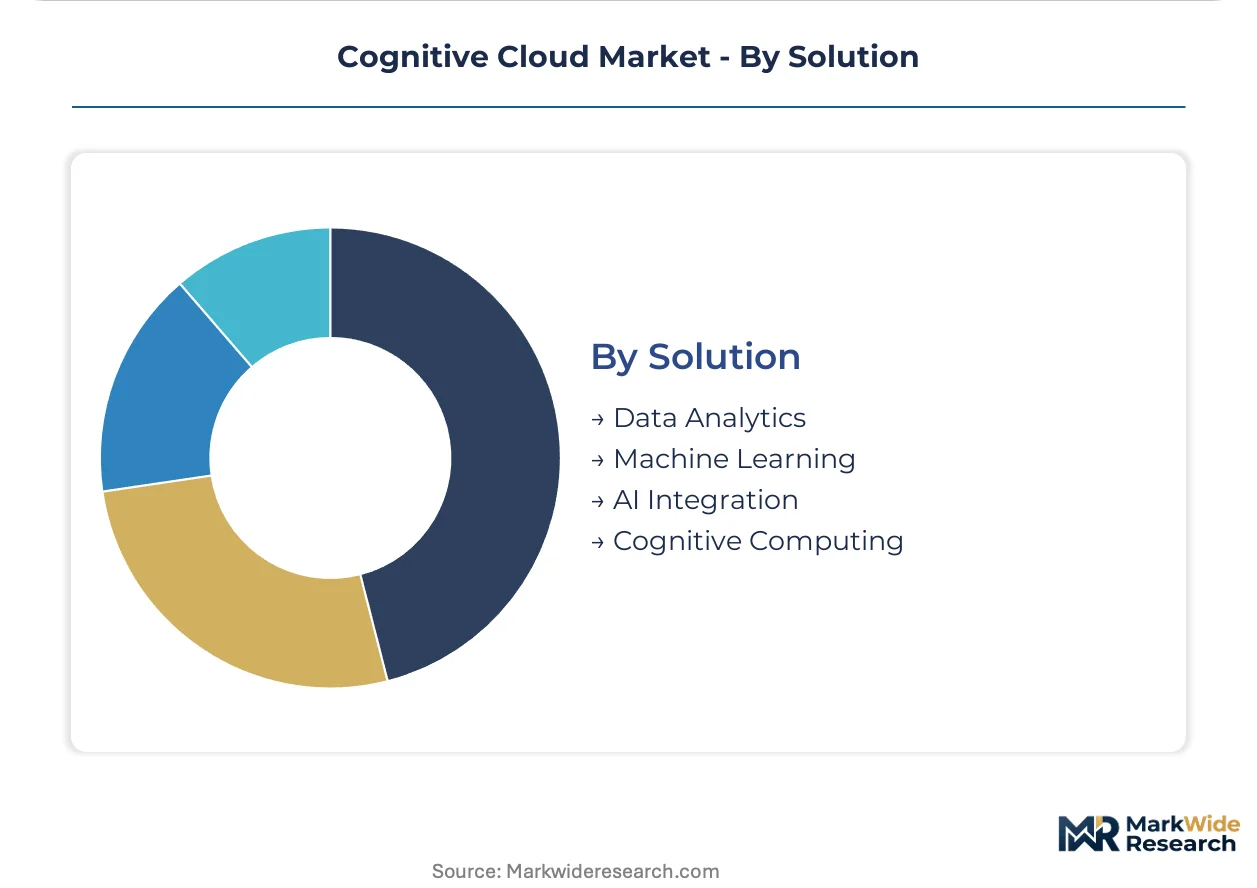
Solution:
Technology maturity separates established data analytics stacks from emerging generative and cognitive computing layers that command premium pricing.
- Machine Learning:Supervised and unsupervised model training for classification and prediction tasks. Google's custom TPU availability anchors competitive positioning for compute-intensive training.
- AI Integration:Embedded intelligence within existing enterprise workflows and applications. Small language model deployment at 3-7 billion parameters reduces per-query costs 80% versus frontier models.
- Data Analytics:Structured and unstructured data processing for business intelligence. This foundational layer faces the strongest price compression as open-source alternatives proliferate.
- Cognitive Computing:Natural language processing and generative outputs mimicking human reasoning. Retrieval-augmented generation architectures are displacing raw training scale as the primary vendor differentiator.
Data analytics anchors the volume base while cognitive computing gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States commands 30-40% premiums over comparable deployments in India, where the PLI scheme for data center infrastructure compresses effective compute costs for domestic providers.
United States
Federal cloud-first directives and enterprise IT modernization budgets sustain deployment momentum across hospital networks and financial institutions. FDA pre-certification pathways for AI-enabled diagnostic software accelerate radiology and pathology application timelines. Greater Boston and the San Francisco Bay Area anchor venture funding concentration for cognitive infrastructure startups.
Germany
The Hospital Future Act allocates dedicated capital for cognitive cloud infrastructure in university medical centers facing diagnostic imaging backlogs. EU AI Act conformity assessment pre-approvals are now mandatory before procurement eligibility from German and French health authorities. Baden-Württemberg's automotive supplier ecosystem is adopting federated learning architectures for cross-facility quality inspection without raw data movement.
India
Production-linked incentives for data center infrastructure reduce effective compute costs for domestic cognitive service providers competing with hyperscaler pricing. CDSCO oversight of AI-enabled medical devices intersects with state-level data localization mandates in Maharashtra and Karnataka. Hyderabad's Health City cluster is emerging as a testbed for clinical decision support systems targeting tier-2 hospital networks.
Brazil
The unified health system lacks diagnostic AI penetration, creating first-mover advantage for cloud-native platforms targeting cost-efficient screening workflows. ANVISA's evolving framework for software-as-medical-device classification shapes product registration timelines for foreign vendors. São Paulo's university hospital network is piloting edge inference deployments for rural telemedicine extension.
Japan
METI's AI governance guidelines and PMDA's software medical device review standards condition market entry for foreign cognitive cloud providers. Aging demographics and labor shortages in clinical documentation drive demand for automated coding and transcription services. Tokyo's diagnostic imaging equipment manufacturers are integrating API-accessible cognitive layers into hardware export bundles.
Cognitive Cloud Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with custom silicon vendors commanding premium positioning while infrastructure-scale operators compete on geographic availability zone breadth. The vendor base organizes around three strategic archetypes: hyperscaler platforms with full-stack integration, consulting-led system integrators with regulated industry expertise, and vertical specialists with domain-specific model training. Competitive moves concentrate on M&A for talent acquisition in MLOps pipeline engineering and strategic partnerships for edge inference hardware distribution.
Within the full-stack hyperscaler tier, Amazon Web Services, Microsoft, and Google exemplify divergent positioning strategies. Amazon Web Services occupies a position anchored in infrastructure provisioning breadth across compute tiers. Microsoft represents the enterprise productivity integration archetype with Azure cognitive services embedded in existing workflow suites. Google exemplifies the custom silicon differentiation vector through TPU availability and deep open-source framework integration.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Amazon Web Services |
| Salesforce |
| Oracle |
| SAP |
| CognitiveScale |
| Nuance Communications |
| Others |
Supply Flow & Price Mechanics
TSMC's 18-24 month wafer allocation lead times for N4 process nodes concentrate pricing power among hyperscaler incumbents while squeezing margin capture for second-tier infrastructure vendors. This supply rigidity feeds directly into compute cost structures that shape customer procurement thresholds.
Pricing Analysis
United States deployments command 30-40% premiums over comparable India-based cognitive cloud services, where PLI scheme subsidies compress domestic provider economics. Consumption-based per-inference billing dominates healthcare procurement, with hospital networks facing capital budget volatility preferring variable cost structures over committed-use contracts. Price differentiation hinges on EU AI Act conformity certification and HIPAA-compliant data residency controls. Pricing pressure intensifies as small language models at 3-7 billion parameters slash per-query costs 80% versus frontier architectures. Mid-market IT services buyers exhibit highest price sensitivity, while regulated BFSI institutions absorb premium private cloud tariffs for audit-ready infrastructure.
Supply Chain Analysis
TSMC's N4 process node monopoly in Taiwan constitutes the critical chokepoint for GPU and TPU fabrication, with Samsung's alternative 4nm yields trailing by 15-20 points. Advanced accelerator supply concentrates in Taiwan, South Korea, and the United States, drawing from silicon wafers, HBM memory stacks, and substrate interconnects. Single-source vulnerability at the leading-edge node creates systemic training infrastructure risk should geopolitical disruption constrain fab output. Distribution runs through hyperscaler direct procurement channels and specialized server OEM integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cognitive cloud market rewards scarce MLOps pipeline engineering talent and conformant infrastructure access, with capability gaps in model observability and EU AI Act documentation systems constraining vendor scalability.
For Market Incumbents: Fortify consulting-led deployment capabilities in regulated healthcare and BFSI verticals where IBM Watson heritage models demonstrate stickiness. Prioritize backward integration into custom TPU and NPU silicon to escape TSMC allocation constraints. Expand Germany-facing conformity assessment pre-approval services before Hospital Future Act procurement windows close. For New Entrants and Emerging Players: Federated learning architecture deployment gaps in cross-institutional healthcare training present white-space opportunity where HIPAA and GDPR constraints block incumbent centralized models. Brazil's unified health system diagnostic AI penetration remains under 5%, offering first-mover positioning for cloud-native screening platforms. Target edge inference hardware partnerships with São Paulo university hospital networks for rural telemedicine extension. For Investors and Strategic Acquirers: Long-term, this sits as a vertical infrastructure play because cognitive cloud workloads embed durably into enterprise workflow automation with high switching costs. Acquisition focus should center on MLOps tooling specialists with Kubernetes-native observability stacks and EU AI Act documentation automation. Monitor FDA pre-certification pathway expansion rates as inflection signal for healthcare deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Development | TPU and NPU in-house production reduces TSMC allocation dependency for training workloads. |
| EU Conformity Assessment Pre-Approval | Documentation automation accelerates German and French health authority procurement eligibility. |
| Federated Learning Platform Launch | Cross-institutional model training addresses HIPAA constraints without raw data movement. |
| Edge Inference Hardware Partnership | Sub-$500 unit economics enable Brazil rural telemedicine screening deployment. |
| MLOps Talent Acquisition | Pipeline engineering specialists command 35-50% premiums that automation can capture. |
Methodological Framework
Operator-level perspectives from cloud infrastructure architects, hospital CIOs, MLOps engineers, and regulatory compliance officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC hyperscaler filings, FDA 510(k) submission databases, EU AI Act implementation guidance, and German Hospital Future Act capital allocation records. Bottom-up service-type demand modeling triangulated against top-down IT modernization budget projections.
Sensitivity analysis tested pricing elasticity across consumption-based versus committed-use contract structures. Segmentation dimensions modeled include deployment architecture, service layer abstraction, vertical compliance sensitivity, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to infrastructure provisioning volumes and SaaS seat expansion trajectories. Forecast inputs incorporated GPU supply allocation forecasts and EU AI Act documentation burden timelines.
Forecasts assume regulatory continuity in FDA pre-certification pathways and EU AI Act risk-tier classifications; material policy shifts would require re-modeling. Model risk concentrates in TSMC supply disruption scenarios and healthcare reimbursement volatility. Practitioners should keep alternative scenarios live as accelerator fabrication capacity and conformity assessment throughput evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Europe AI Cloud Computing in Automotive Market
Cloud Computing
Dbaas and Cloud Database Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Data Virtualization Cloud Market
Cloud Computing
Cloud Continuum Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Cloud Management Market
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market
Cloud Computing
Multi-Cloud Optimization Tools Market
Cloud Computing
VM Service Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Global Multi Cloud Management Market
Cloud Computing
Global Cloud-Native Software Market
Cloud Computing
Cloud Microservice and Application Market