
 Cloud ELN Service Market | 2026-2036
Cloud ELN Service Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud ELN Service Market Analysis
Asset-light SaaS subscription models is rewriting competitive dynamics in the Cloud ELN Service Market, lowering capital barriers for mid-sized laboratories and CROs. Benchling leverages cloud-native architecture to compete in biotechnology workflows. Thermo Fisher Scientific anchors its position through integration with analytical instrument ecosystems. Dotmatics specializes in data management layers that extend across hybrid cloud deployments.
A Cloud ELN Service constitutes a web-hosted electronic laboratory notebook platform that captures experimental protocols, data entries, and metadata with timestamped audit trails, version control, and role-based access permissions. Its primary commercial purpose is to replace paper notebooks in regulated research environments while enabling real-time collaboration across distributed teams. The pharmaceutical end-user segment dominates current enterprise licensing volumes, reflecting stringent documentation requirements for IND and NDA submissions. Hybrid cloud deployment is expanding fastest among contract research organizations that must balance data sovereignty with client accessibility.
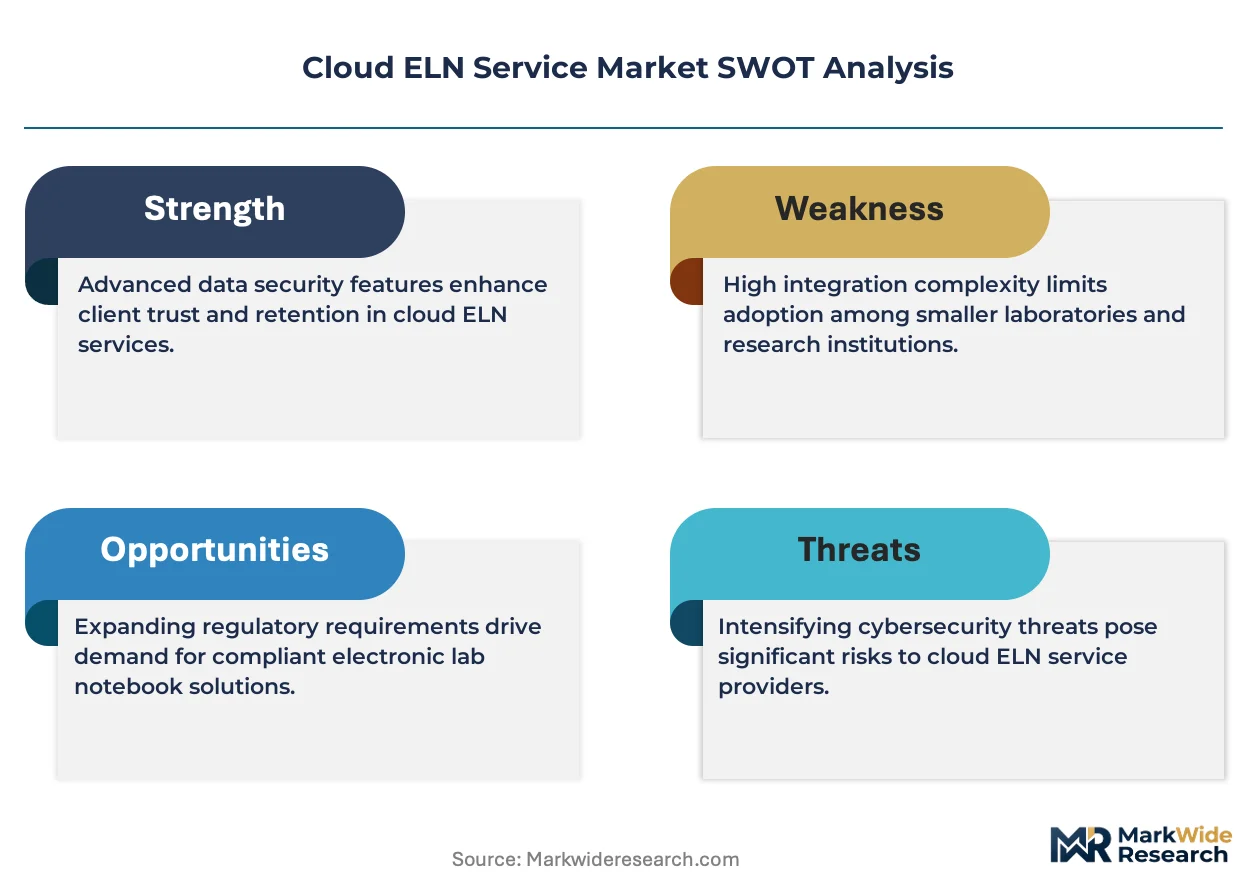
The FDA enforces 21 CFR Part 11 compliance for electronic records, directly shaping product validation roadmaps and vendor qualification processes. ISO 27001 certification has become a baseline requirement for market access, particularly in European pharmaceutical supply chains. Stakeholders must monitor evolving EMA guidance on cloud-based primary data storage, as regulator divergence between jurisdictions could fragment platform standardization efforts.
Market Dynamics
The Cloud ELN Service Market is being fundamentally restructured by the pharmaceutical industry's mandatory shift toward remote multi-site collaboration, driven by distributed R&D footprints and the FDA's 21 CFR Part 11 audit trail requirements that now extend to cloud-hosted primary data.
Growth Catalysts
- 21 CFR Part 11 Compliance Mandates:FDA enforcement of electronic record integrity requirements compels pharmaceutical sponsors to replace paper notebooks with validated cloud platforms for IND and NDA submissions.
- Contract Research Organization Expansion:CROs in the United States and Germany are deploying hybrid cloud ELN architectures to serve multiple pharmaceutical clients simultaneously while maintaining data segregation.
- AI-Ready Data Infrastructure:Machine learning pipelines for drug discovery require structured, queryable experimental datasets that cloud-native ELN platforms capture at the point of entry.
Market Restraints
- Data Sovereignty Fragmentation:Conflicting national data localization laws in China, Russia, and Saudi Arabia force vendors to maintain region-specific infrastructure, raising operational complexity.
- Validation Cost Burden:FDA-compliant IQ/OQ/PQ validation packages for cloud deployments add six-figure professional services costs that mid-sized biotechs struggle to absorb.
- Legacy LIMS Integration Friction:Proprietary data formats from established laboratory information management systems create migration barriers that extend implementation timelines by 12-18 months.
Strategic Opportunities
- Academic and Government Laboratory Penetration:National institutes of health in South Korea and Australia are piloting cloud ELN programs with simplified compliance tiers for non-GMP research.
- Cell and Gene Therapy Workflows:Complex manufacturing processes requiring chain-of-custody documentation for patient-specific therapies represent an emerging application with limited incumbent solutions.
- EU Green Deal Laboratory Digitization Incentives:European funding programs for sustainable research infrastructure subsidize cloud migration as a paper-reduction and energy-efficiency measure.
Industry Challenges
- Qualified Validation Engineer Shortage:The scarcity of professionals holding combined expertise in FDA 21 CFR Part 11, ISO 27001, and cloud architecture bottlenecks enterprise deployments.
- Multi-Tenant Security Architecture Complexity:Engineering truly isolated data environments for competing pharmaceutical clients on shared infrastructure demands specialized cybersecurity investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud ELN Service Market |
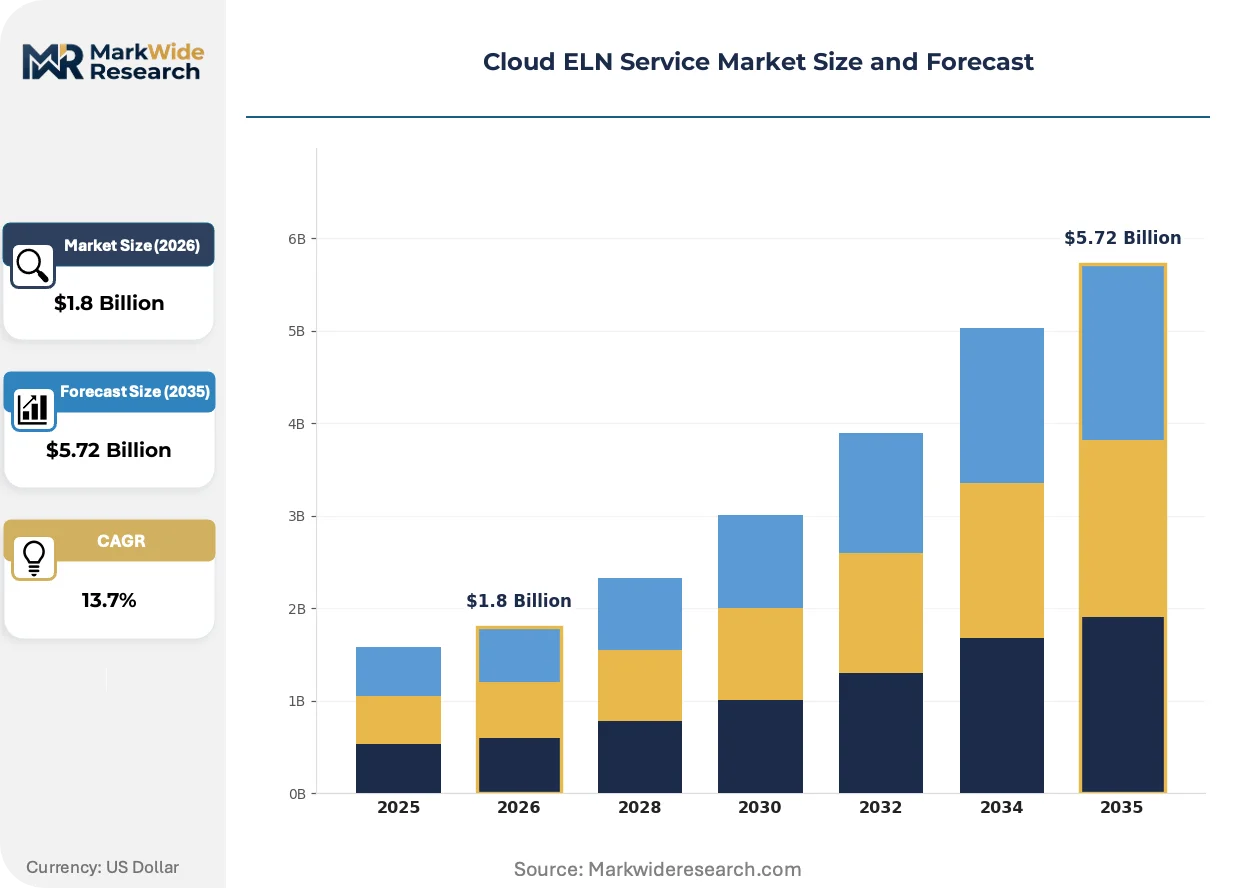
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-cloud End User: Pharmaceuticals, Biotechnology, Academia, Contract Research Organizations Solution: Data Management, Collaboration Tools, Compliance Solutions, Analytics Service Type: Subscription-Based, Pay-As-You-Go, Freemium, Enterprise Licensing |
| Companies Covered | LabArchives, LabVantage Solutions, Dotmatics, LabWare, Thermo Fisher Scientific, PerkinElmer, Benchling, Agilent Technologies, Abbott Informatics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud ELN Service Market Emerging Trajectories
Cloud ELN architectures are undergoing rapid functional expansion as vendors compete to capture workflow share beyond traditional notebook replacement, embedding analytical instruments, biological registries, and sample management into unified data fabrics.
Containerized microservices architecture is migrating from experimental deployments to standard product roadmaps across major platforms. Biotechnology firms with distributed manufacturing networks are adopting Kubernetes-orchestrated ELN instances to maintain consistent software versions across 15-20 global sites. This shift is compressing the competitive moat of legacy on-premise installations that require site-by-site upgrade cycles.
EMA guidance on cloud-based primary data storage for clinical trial materials is reshaping vendor qualification requirements across European pharmaceutical supply chains. The regulator's draft position on data integrity in outsourced environments is forcing platform providers to implement enhanced cryptographic audit trails and geographic redundancy disclosures. Sponsors in Germany and Switzerland are now demanding EMA-aligned contractual terms that supersede standard SaaS agreements.
Consolidated platform procurement is displacing point-solution purchasing as large pharmaceutical buyers seek to reduce vendor management overhead. Merck KGaA and Roche have both moved to enterprise-wide ELN-LIMS-CDMS bundles, pressuring standalone notebook vendors to demonstrate integration depth or exit consideration. This concentration is most visible in Boston and Basel, where procurement teams now evaluate platforms on API ecosystem breadth rather than core notebook functionality alone.
Cloud ELN Service Market Segmentation
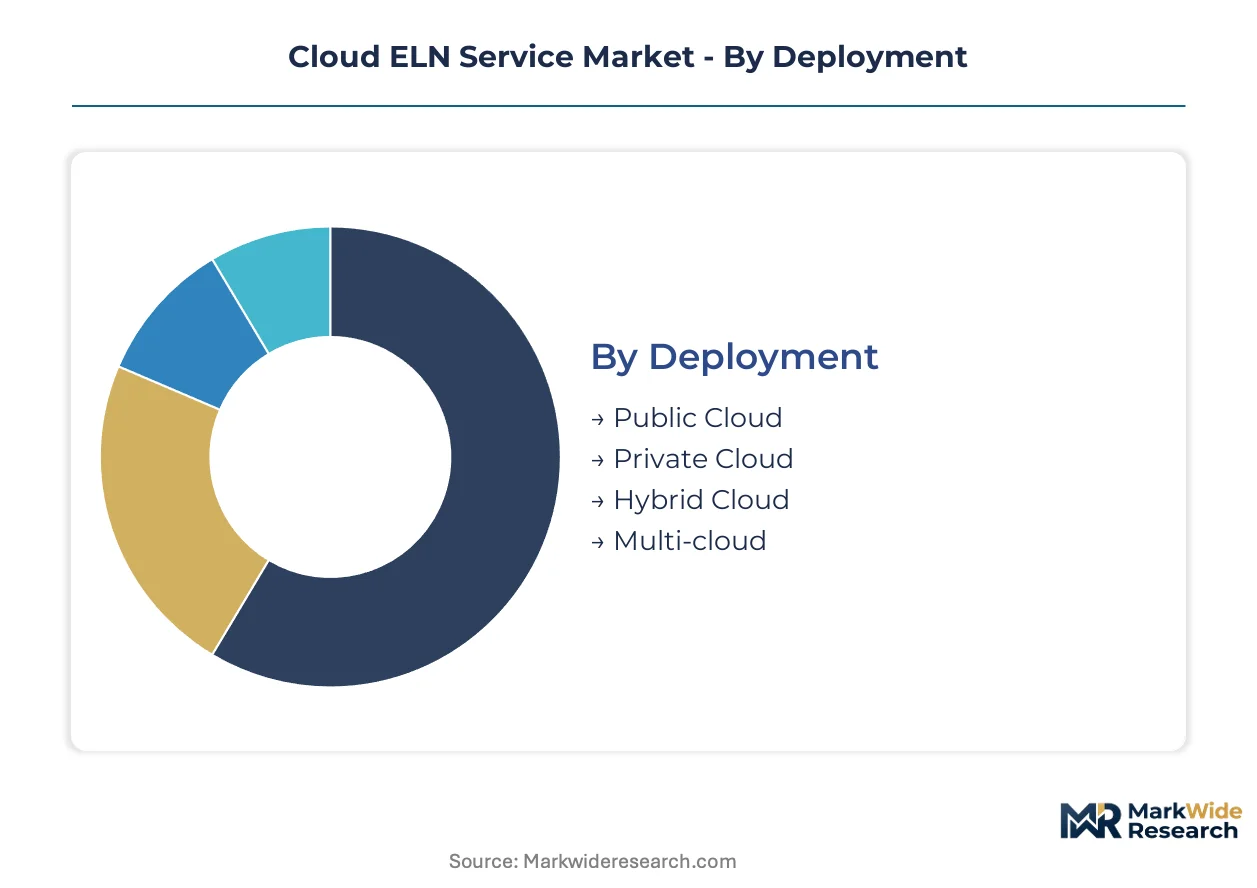
Cloud ELN purchasing cycles vary dramatically across deployment modes and end-user sophistication. Pharmaceutical sponsors run 3-5 year enterprise contracts with extensive validation phases, while academic laboratories cycle through freemium tiers within 12-18 months. Understanding these velocity differences shapes vendor resource allocation and product roadmap prioritization.
Deployment:
Hybrid cloud deployments compress implementation timelines compared to private cloud builds, while public cloud trials convert fastest from pilot to production.
- Public Cloud:Shared infrastructure with vendor-managed security patches and automatic feature releases. Pharmaceutical startups in Boston and San Francisco favor this model for rapid IND-enabling studies, though FDA 21 CFR Part 11 validation remains the buyer's responsibility.
- Private Cloud:Dedicated single-tenant environments with custom security configurations. German pharmaceutical manufacturers deploy these for EMA-aligned data sovereignty requirements, accepting 18-24 month implementation cycles for full control over audit trail architecture.
- Hybrid Cloud:Sensitive protocols reside on-premises while collaborative datasets sync to cloud instances. Contract research organizations in the United States adopt this architecture to segregate competing client data without sacrificing multi-site accessibility.
- Multi-cloud:Workload distribution across AWS, Azure, and Google Cloud to mitigate vendor lock-in. Large biotechnology firms with global manufacturing footprints use this for geographic redundancy compliance.
Private cloud dominates installed base among top-20 pharmaceutical sponsors. Hybrid cloud is where expansion concentrates as CROs seek flexible client segregation.
End User:
Pharmaceutical buyers command premium pricing tiers, while academic price sensitivity pushes vendors toward freemium conversion funnels.
- Pharmaceuticals:Enterprise licensees requiring validated 21 CFR Part 11 environments for regulatory submissions. Merck KGaA and Roche operate global ELN-LIMS bundles spanning 50+ manufacturing and R&D sites.
- Biotechnology:Mid-sized firms prioritizing cloud-native architecture for distributed team collaboration. Cell and gene therapy developers in Basel and Cambridge represent emerging demand for chain-of-custody documentation.
- Academia:National institutes of health in South Korea and Australia pilot simplified compliance tiers for non-GMP research, subsidized by government digitization grants.
- Contract Research Organizations:Multi-tenant platform requirements with strict data segregation between competing pharmaceutical clients. IQVIA and Charles River Laboratories drive hybrid cloud specifications.
Pharmaceuticals anchor vendor revenue concentration. Biotechnology is climbing the fastest as venture-funded drug developers bypass legacy on-premise installations.
Solution:
Compliance modules carry the highest gross margins, while collaboration tools face commoditization from horizontal SaaS competitors.
- Data Management:Structured experimental datasets with AI-ready ontologies for machine learning pipelines. Drug discovery teams in San Francisco require queryable molecular biology registries integrated with ELN entries.
- Collaboration Tools:Real-time protocol sharing, electronic signatures, and cross-site project dashboards. These features face encroachment from Microsoft Teams and Slack with laboratory-specific plugins.
- Compliance Solutions:Pre-validated 21 CFR Part 11 packages with IQ/OQ/PQ documentation. FDA enforcement actions against electronic record integrity drive pharmaceutical willingness to pay premium professional services fees.
- Analytics:Embedded statistical analysis and visualization tools replacing export to standalone software. Thermo Fisher Scientific integrates chromatography data directly into notebook entries.
Compliance solutions generate disproportionate profit pools. Analytics capabilities show steepest expansion trajectory as vendors compete on workflow breadth.
Service Type:
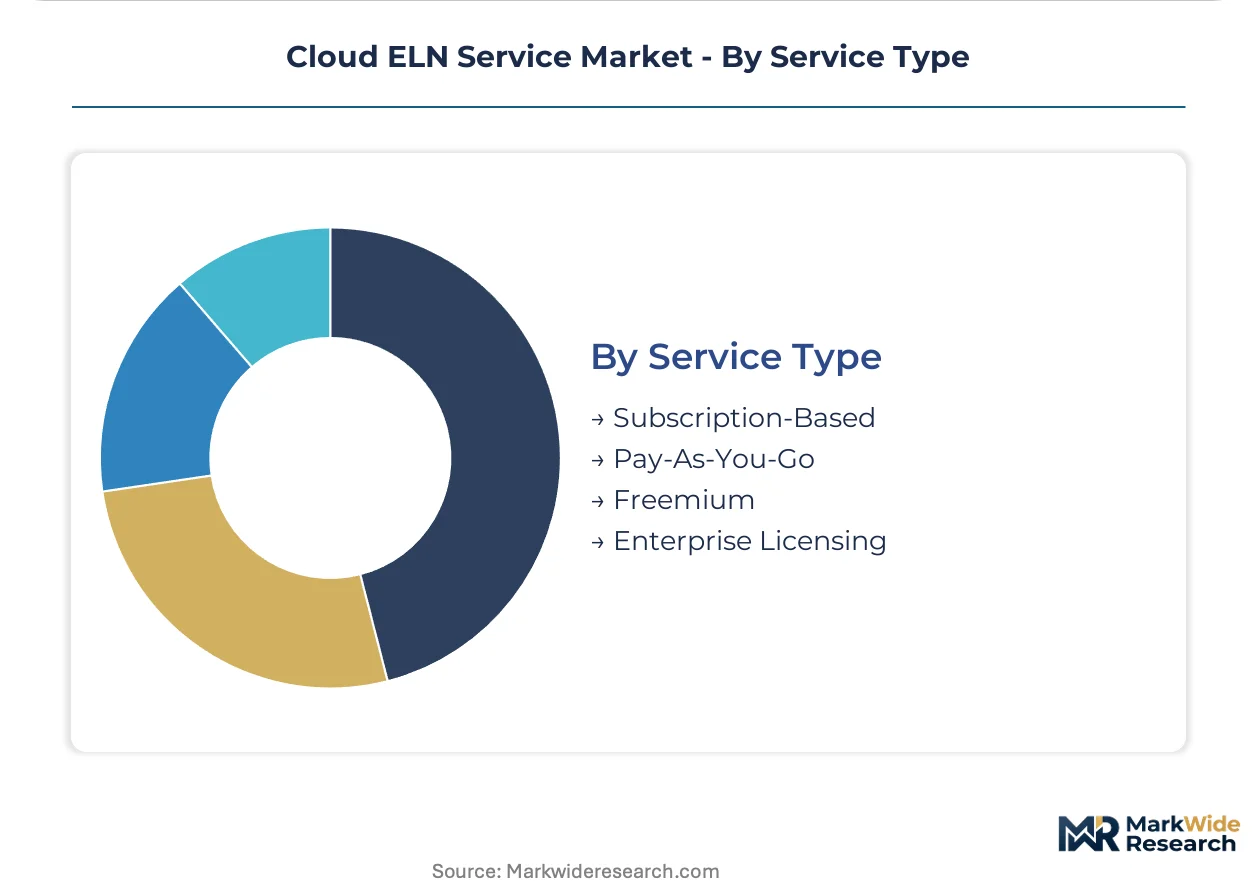
Enterprise licensing locks in multi-year commitments, while consumption-based models align costs with experimental volume fluctuations.
- Subscription-Based:Fixed annual fees per user seat with tiered feature access. Standard procurement vehicle for mid-sized biotechnology firms with predictable headcount.
- Pay-As-You-Go:Metered billing tied to data storage volume, API calls, or compute resources for analytical processing. Appeals to project-based contract research organizations with variable workload patterns.
- Freemium:Basic notebook functionality with paid upgrades for compliance modules and storage expansion. Academic laboratories in Australia and South Korea convert through this funnel.
- Enterprise Licensing:Negotiated multi-year agreements with custom SLAs, dedicated support, and bundled professional services. Pfizer and Novartis structure these around global site rollouts.
Enterprise licensing secures vendor revenue predictability. Pay-as-you-go is gaining share fastest among CROs seeking cost flexibility across client contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's 21 CFR Part 11 enforcement drives pharmaceutical cloud ELN adoption across multiple jurisdictions, while EMA guidance and national digitization programs create divergent compliance requirements that shape vendor qualification standards.
United States
Biotechnology clusters in Boston and San Francisco anchor enterprise licensing demand for validated cloud platforms. The FDA's 21 CFR Part 11 framework mandates electronic record integrity for IND and NDA submissions, compelling sponsors to replace paper documentation. Pfizer and Merck operate global ELN deployments spanning 50-plus R&D and manufacturing sites.
Germany
EMA-aligned data sovereignty requirements drive private cloud implementations among pharmaceutical manufacturers. The country's national pharmaceutical regulator enforces strict audit trail architectures that extend implementation timelines to 18-24 months. Basel-adjacent cell and gene therapy developers in Baden-Württemberg represent emerging demand for chain-of-custody documentation systems.
Switzerland
Swissmedic oversight of clinical trial materials shapes vendor qualification requirements for cloud-based primary data storage. Roche anchors enterprise-wide ELN-LIMS-CDMS bundles across global operations. Procurement teams in Basel evaluate platforms on API ecosystem breadth rather than core notebook functionality alone.
South Korea
Government digitization grants subsidize cloud ELN pilots at national institutes of health for non-GMP research. The country's national pharmaceutical regulator aligns with MFDS standards for electronic records in life sciences. Seoul-based contract research organizations deploy hybrid architectures to serve multiple pharmaceutical clients simultaneously.
Australia
TGA guidance on data integrity in outsourced environments forces platform providers to implement enhanced cryptographic audit trails. Academic laboratories convert through freemium tiers subsidized by federal research infrastructure programs. Melbourne and Sydney biotech clusters drive mid-sized firm adoption of cloud-native architectures for distributed team collaboration.
Cloud ELN Service Market Vendor Landscape
On the supply side, the industry is consolidating around platform breadth rather than point solutions, with large pharmaceutical buyers reducing vendor management overhead through bundled procurement. Three strategic archetypes dominate: analytical instrument integrators, cloud-native biotechnology specialists, and data management layer providers. M&A activity concentrates on API ecosystem expansion, while strategic partnerships target hybrid cloud deployment capabilities for contract research organizations.
Within the cloud-native tier, Benchling exemplifies architecture built for distributed biotechnology workflows. Thermo Fisher Scientific anchors the instrument-integrated segment through chromatography and analytical device connectivity. Dotmatics occupies a position emphasizing data management layers that extend across hybrid deployments, serving multi-site pharmaceutical sponsors requiring flexible infrastructure.
| Leading Market Players |
|---|
| LabArchives |
| LabVantage Solutions |
| Dotmatics |
| LabWare |
| Thermo Fisher Scientific |
| PerkinElmer |
| Benchling |
| Agilent Technologies |
| Abbott Informatics |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure concentration in the United States and Ireland concentrates margin capture among hyperscale providers, forcing ELN vendors to pass through compute costs while competing on compliance module differentiation. Pharmaceutical buyers absorb premium pricing for FDA-validated deployments, while mid-sized biotechs drive cost compression through SaaS tier competition.
Pricing Analysis
Certification level creates the primary spread between deployment tiers, with FDA 21 CFR Part 11-validated packages commanding substantial premiums over ISO 27001-baseline offerings. Three-tier pricing structure across premium, standard, and economy levels aligns with validation depth and professional services bundling. Pricing pressure stems from horizontal SaaS encroachment as Microsoft and Salesforce extend laboratory-specific plugins. Academic laboratories exhibit highest price sensitivity, converting through freemium funnels, while top-20 pharmaceutical sponsors lock in multi-year enterprise agreements with limited elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for hardware-dependent private cloud deployments. Cloud ELN software supply chains draw from development talent pools concentrated in the United States, Germany, and India, with customer success operations anchored in regional hubs. Single-source vulnerability rests on hyperscaler concentration for compute infrastructure, particularly AWS and Azure dominance in pharmaceutical workloads. Distribution runs through direct enterprise sales teams for validated deployments, supplemented by channel partners serving academic and government segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Horizontal collaboration platforms threaten to commoditize core notebook functionality, compelling incumbents to defend through workflow integration depth and regulatory certification moats.
For Market Incumbents: Harden multi-tenant security architectures to meet EMA-aligned contractual demands from Basel and Boston procurement teams. Deepen API ecosystem breadth to maintain platform bundling advantages against point-solution competitors. Vertical integration into analytical instrument connectivity preserves differentiation as Thermo Fisher Scientific has demonstrated with chromatography data integration. For New Entrants and Emerging Players: South Korean and Australian government digitization grants represent underpenetrated demand for simplified compliance tiers targeting non-GMP research environments. Cell and gene therapy workflows in Basel-adjacent regions offer white-space entry with limited incumbent solutions for chain-of-custody documentation. A compliance-light, collaboration-heavy go-to-market angle targets academic laboratories before upselling validated modules. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cloud-native specialists possessing strong API ecosystems but limited validation service depth. Long-term viability across a 5-10 year window favors platforms with demonstrated FDA enforcement survival and EMA guidance alignment. The signal to watch is procurement team consolidation around bundled ELN-LIMS-CDMS specifications versus standalone notebook tolerance.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies ELN-LIMS-CDMS bundles that Merck KGaA and Roche now demand across 50-plus sites. |
| Regulatory Certification Investment | Secures FDA 21 CFR Part 11 and EMA-aligned validation packages for pharmaceutical procurement qualification. |
| Geographic Expansion | Captures South Korean and Australian government-subsidized digitization programs for non-GMP research. |
| Strategic Partnership | Enables hybrid cloud deployment capabilities for CROs serving multiple competing pharmaceutical clients. |
| Acquisition of Specialist Firm | Extends API ecosystem breadth to meet Basel procurement team evaluation criteria. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR Part 11 guidance documents, EMA draft positions on cloud-based primary data storage, and hyperscaler capex disclosures. Interviews with regulatory affairs leads at pharmaceutical sponsors, cloud architects at contract research organizations, and procurement managers at biotechnology firms informed demand-side validation. SEC filings from publicly traded platform providers, ISO certification registries, and government digitization grant announcements supplied secondary triangulation. Bottom-up user seat estimates and top-down pharmaceutical R&D spending allocations were cross-referenced for convergence.
Forecast inputs include deployment mode adoption curves, end-user segment expansion rates, and regulatory guidance evolution timelines across the analysis window. Segmentation dimensions modeled encompass deployment architecture, end-user sophistication tier, solution module mix, and regional regulatory cluster. CAGRs were derived from fitted adoption curves against historical cloud software penetration patterns. Industry-specific forecast inputs incorporate FDA enforcement action frequency and EMA guidance finalization trajectories.
Macroeconomic conditions sit as an overlay; deviation in pharmaceutical R&D spending cycles or hyperscaler pricing power would shift the trajectory. Forecasts reflect assumptions about regulatory convergence between FDA and EMA positions, which fragmented guidance would revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
France Cloud Computing Market
Cloud Computing
Commerce Cloud Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Spain Cloud Computing Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Virtual Private Cloud (VPC) Market
Cloud Computing
AI Platform Cloud Service Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
UK Cloud Computing Market
Cloud Computing
Europe AI Cloud Computing in Automotive Market
Cloud Computing
Global Cloud Collaboration Market