
 Furan Dicarboxylic Methyl Ester (FDME) Market | 2026-2036
Furan Dicarboxylic Methyl Ester (FDME) Market Size, Share, and Industry Trends Forecast 2026-2036
Furan Dicarboxylic Methyl Ester (FDME) Market Analytics
Automotive lightweighting is repositioning FDME from niche polymer research toward structural composite applications. Avantium leverages its YXY technology platform to anchor European pilot production of furan-based building blocks. BASF SE competes through integrated R&D pathways spanning catalysis to polymer validation. Cargill Incorporated sustains agricultural feedstock security via its corn-processing infrastructure in the US Midwest.
Furan dicarboxylic methyl ester is a cyclic diester derived from 2,5-furandicarboxylic acid, typically produced through oxidative dehydration of C6 sugars followed by esterification with methanol, yielding a monomer suitable for polycondensation into polyethylene furanoate and other high-performance polyesters. The bio-based plastics segment dominates current volume allocation as packaging converters seek drop-in alternatives to petroleum-derived PET. Coatings applications represent the fastest-expanding category, driven by solvent-reduction mandates in industrial finishing operations. Resins for electronics encapsulation occupy a narrower but higher-margin niche serving semiconductor packaging laminates.
EPA biofuel pathway evaluations and REACH substance registration collectively shape feedstock qualification timelines and cross-border chemical commerce. FDA food-contact substance notifications additionally govern polyester migration limits for beverage packaging applications in the United States. Stakeholders must monitor catalytic efficiency breakthroughs and biorefinery co-product economics to determine optimal capacity commitment sequencing.
Market Dynamics
EU Green Deal compliance deadlines are compressing brand owner procurement timelines, forcing packaging converters to qualify bio-based polyester intermediates before 2030 circular economy mandates take full effect.
Growth Catalysts
- REACH substance registration:Tightening purity and traceability obligations across European value chains are filtering out unqualified suppliers and consolidating demand around certified FDME producers.
- Automotive lightweighting:Structural composite applications in electric vehicle platforms are pulling furan-based polymers from pilot research into production-scale material qualification.
- Corn-processing infrastructure:Agricultural feedstock security in the US Midwest is anchoring C6 sugar supply chains for oxidative dehydration routes to FDCA precursors.
Market Restraints
- Catalytic efficiency limitations:Heterogeneous catalyst degradation rates in continuous-flow FDCA production constrain single-pass yields and elevate methanol recovery costs.
- Supply concentration in Germany:Pilot-scale FDME conversion facilities cluster around automotive OEMs and chemical processors in Baden-Württemberg and Bavaria, creating geographic vulnerability.
- Petroleum-derived PET substitution economics:Virgin PET price volatility and established recycling infrastructure delay payback periods for bio-based polyester capital commitments.
Strategic Opportunities
- Coatings solvent-reduction mandates:Industrial finishing operations in France and Italy face tightening volatile organic compound limits, opening formulation trials for furan-based resin systems.
- Electronics encapsulation laminates:Semiconductor packaging applications in Japan and South Korea command premium pricing for high-purity FDME with sub-ppm metal specifications.
- Biorefinery co-product valorization:Levulinic acid and hydroxymethylfurfural side-stream integration is converging with carbon accounting frameworks to improve overall plant economics.
Industry Challenges
- Polymerization catalyst talent scarcity:Experienced technologists capable of scaling polycondensation from lab to tonnage demonstration are concentrated among legacy polyester producers.
- FDA food-contact notification timelines:Beverage packaging migration studies require 18-24 month review cycles that misalign with brand owner sustainability pledge deadlines.
- Legacy PET equipment retrofit complexity:Solid-state polymerization reactors and melt extrusion lines require substantial modification to handle furan ring thermal sensitivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furan Dicarboxylic Methyl Ester (FDME) Market |
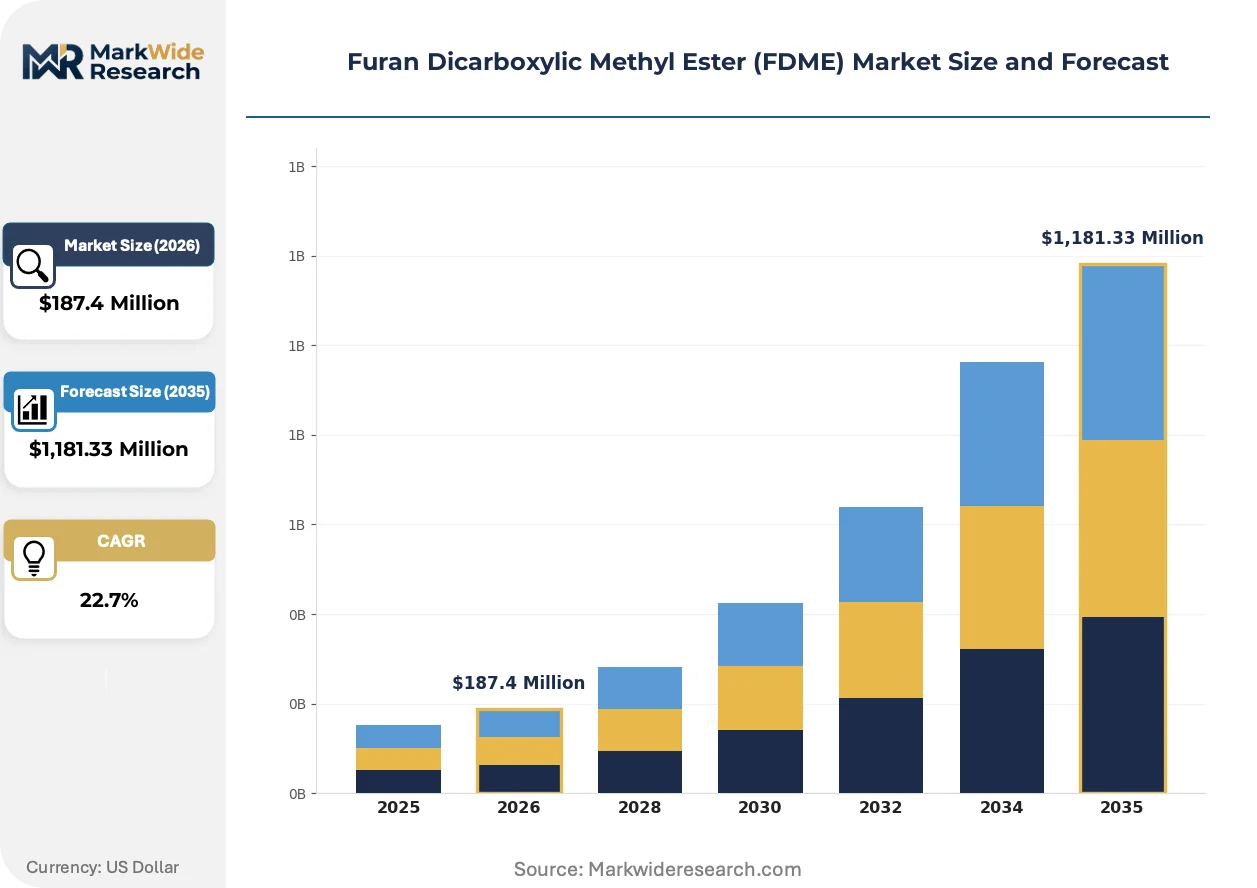
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FDME, Bio-based Plastics, Coatings, Resins End Use Industry: Packaging, Automotive, Textiles, Electronics Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Application: Solvents, Adhesives, Films, Fibers |
| Companies Covered | Clearsynth, V.V. Pharma Industries, Avantium, Cargill Incorporated, BASF SE, Synvina, TCL America, Archer Daniels Midland Company, AVA Biochem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furan Dicarboxylic Methyl Ester (FDME) Market Evolving Landscape
Bio-refinery process intensification is collapsing the capital intensity gap between furan chemistry and incumbent petrochemical routes, while regulatory chemistry is rewriting qualification protocols for novel monomers.
Catalytic oxidative dehydration is converging with continuous-flow reactor engineering to enable direct C6 sugar conversion without isolated HMF intermediates. Pilot plant operators in the Netherlands and Belgium are adopting these integrated designs to compress residence times and reduce solvent inventory. The technology is converging with automated process analytical control systems that enable real-time purity verification for REACH batch registration.
EPA biofuel pathway evaluations now classify certain FDCA production routes as eligible for renewable identification number credits, altering feedstock economics for US-based producers. This reclassification is redirecting agricultural residue flows toward furan platform chemical production. Corn stover and sugar beet pulp processors in Iowa and Minnesota are responding by commissioning pretreatment facilities compatible with oxidative catalysis.
Brand owner sustainability scorecards are elevating bio-based content thresholds from aspirational targets to contract minimums for primary packaging suppliers. Tier-one converters serving beverage and personal care multinationals now require third-party certification of biogenic carbon content. German and French packaging procurement teams are most advanced in enforcing these specifications through supplier audit programs.
Furan Dicarboxylic Methyl Ester (FDME) Market Segmentation
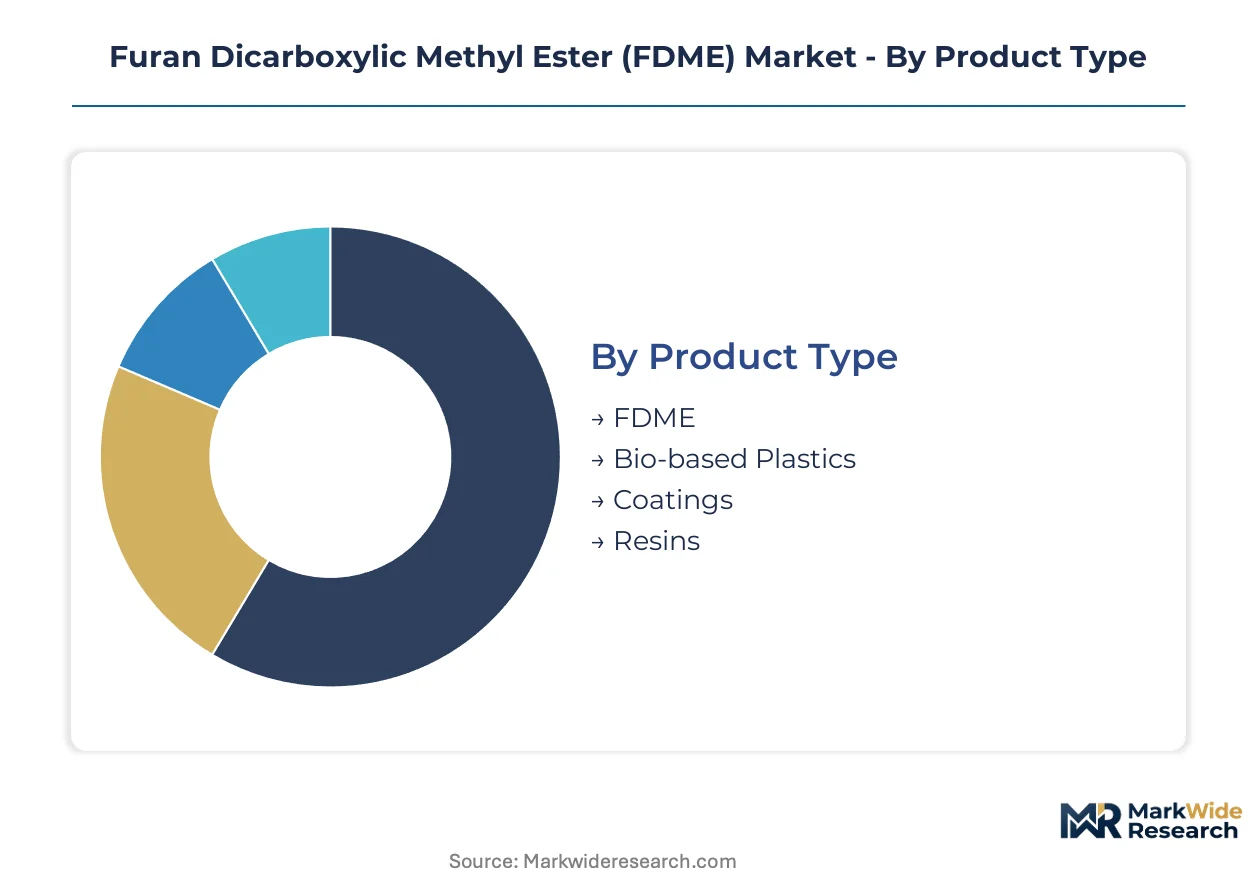
FDME procurement patterns diverge sharply across product grades and end-use specifications, with purity thresholds and thermal stability requirements dictating supplier qualification timelines. Segmentation clarity enables converters to align feedstock sourcing with polymerization process constraints and regulatory compliance obligations.
Product Type:
Supply concentration clusters around polymer-grade specifications, with specialty resin variants commanding premium positioning due to catalyst compatibility requirements.
- FDME:The foundational cyclic diester serves as the primary monomer input for polyethylene furanoate synthesis. German automotive OEMs and Dutch packaging converters anchor demand for high-purity grades meeting REACH batch registration standards.
- Bio-based Plastics:Polymer compounds incorporating furan-based building blocks target drop-in replacement of petroleum-derived PET in beverage packaging. EU Green Deal compliance deadlines in France and Germany are compressing qualification timelines for these materials.
- Coatings:Solvent-reduction formulations leverage furan ring structures for enhanced adhesion and weathering resistance.
- Resins:Electronics-grade encapsulation materials require sub-ppm metal specifications for semiconductor packaging laminates.
Bio-based Plastics absorbs the bulk of installed capacity; Coatings is expanding most quickly.
End Use Industry:
Application-driven cost tiers separate commodity packaging procurement from specialized automotive and electronics qualification pathways.
- Packaging:Beverage and personal care multinationals drive volume procurement through sustainability scorecards mandating third-party biogenic carbon certification. Brand owner contract minimums now enforce bio-based content thresholds previously treated as aspirational targets.
- Automotive:Electric vehicle platforms pull furan-based polymers from pilot research into structural composite production. Lightweighting mandates from the EU and US EPA fuel economy standards are accelerating material substitution in body panel and interior component applications.
- Textiles:Fiber-grade FDME competes with recycled PET in apparel and industrial yarn markets.
- Electronics:Semiconductor packaging applications in Japan and South Korea command premium pricing for ultra-high-purity specifications.
Packaging commands the dominant share of procurement volume; Automotive is climbing the fastest as OEMs advance from qualification to production scale.
Distribution Channel:
Customer type and order scale determine channel selection, with technical specification complexity favoring direct relationships for polymer-grade volumes.
- Direct Sales:Long-term offtake agreements dominate polymer-grade FDME procurement, with converters requiring technical service support for catalyst optimization and process integration. BASF SE and Avantium anchor European direct sales networks through pilot-scale production facilities.
- Distributors:Regional chemical distributors serve mid-tier coatings and adhesives formulators with standardized purity grades. Inventory positioning in Rotterdam and Antwerp hubs reduces lead times for Benelux and northern French processors.
- Online Sales:Sample quantities and research-grade materials move through specialized chemical marketplaces serving academic and pilot-scale operators.
- Retail:Limited to specialty resin formulations for artisan and small-batch coatings applications.
Direct Sales channels handle the majority of tonnage movement; Distributors are gaining share fastest among mid-market formulators seeking reduced inventory carrying costs.
Application:
Volume-maturity dynamics separate established film and fiber markets from emerging solvent and adhesive applications with steeper technical qualification curves.
- Solvents:Industrial finishing operations in France and Italy face tightening volatile organic compound limits under EU F-Gas Regulation and national air quality directives. Furan-based solvent systems enable formulation trials targeting 50% reduction in hazardous air pollutant emissions.
- Adhesives:Hot-melt and reactive adhesive formulations leverage FDME-derived polyesters for improved thermal stability and substrate adhesion. Automotive interior assembly and flexible packaging lamination represent the primary demand concentrations.
- Films:Biaxially oriented polyethylene furanoate films target high-barrier food packaging applications.
- Fibers:Textile-grade filaments compete with recycled polyester in apparel and technical textile markets.
Films retains the largest installed processing capacity; Solvents is gaining share fastest as regulatory pressure intensifies on incumbent petrochemical formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDME production concentrates in pilot-scale facilities clustered around automotive OEMs and chemical processors, while consumption spreads across packaging converters in multiple jurisdictions responding to divergent regulatory timelines. Germany anchors European supply through Baden-Württemberg and Bavaria conversion facilities. The United States, Japan, and South Korea represent distinct demand poles shaped by automotive lightweighting mandates, coatings solvent regulations, and electronics encapsulation requirements respectively.
Germany
Automotive OEMs in Stuttgart and Munich co-locate with chemical processors to advance structural composite qualification for electric vehicle platforms. REACH substance registration requirements filter supplier资格, consolidating procurement around certified FDME producers with batch-level traceability systems. Pilot-scale conversion facilities in Ludwigshafen and Leverkusen anchor European supply capacity.
United States
Corn-processing infrastructure in Iowa and Minnesota secures C6 sugar feedstocks for oxidative dehydration routes to FDCA precursors. EPA biofuel pathway evaluations classify certain production routes as eligible for renewable identification number credits, redirecting agricultural residue flows toward furan platform chemical production. Pretreatment facilities in the US Midwest respond by commissioning equipment compatible with oxidative catalysis.
Japan
Semiconductor packaging applications command premium pricing for ultra-high-purity FDME with sub-ppm metal specifications. METI industrial standards and national carbon neutrality targets accelerate material substitution in electronics encapsulation laminates. Production and R&D activity concentrates in the Osaka-Kobe industrial corridor serving display and memory chip manufacturers.
South Korea
Electronics-grade resin demand from Samsung and SK Hynix supply chains pulls high-purity FDME into semiconductor packaging qualification programs. MFDS chemical substance regulations and national green growth initiatives shape import and local production strategies. Busan-Ulsan chemical complexes host formulation trials for next-generation encapsulation materials.
Netherlands
Packaging converters in Rotterdam and Amsterdam pilot polyethylene furanoate films for high-barrier food applications under EU Green Deal compliance deadlines. ECHA regulatory guidance on novel polymer intermediates influences batch registration and purity verification protocols. Integrated biorefinery designs in Groningen and Zeeland compress residence times through continuous-flow reactor engineering.
Furan Dicarboxylic Methyl Ester (FDME) Market Competitive Landscape
Top-tier vendors anchor pilot-scale production and direct sales networks, while mid-tier agricultural processors and regional chemical distributors occupy feedstock security and formulation support roles. The vendor base stratifies across integrated chemical conglomerates, specialized biorefinery operators, and agricultural commodity processors with downstream chemical ambitions. Two dominant competitive moves are reshaping positioning: strategic partnerships between automotive OEMs and monomer suppliers for material qualification programs, and backward integration by agricultural processors into oxidative catalysis capabilities.
Among integrated chemical conglomerates, BASF SE occupies a position exemplifying catalysis-through-polymer validation pathways, while Avantium represents the dedicated biorefinery operator archetype with its YXY technology platform. Cargill Incorporated anchors the agricultural processor tier, leveraging corn-processing infrastructure for feedstock security. These three entities collectively illustrate the competitive tension between petrochemical legacy systems and bio-based platform chemical emergence.
| Leading Market Players |
|---|
| Clearsynth |
| V.V. Pharma Industries |
| Avantium |
| Cargill Incorporated |
| BASF SE |
| Synvina |
| TCL America |
| Archer Daniels Midland Company |
| AVA Biochem |
| Others |
Value Network & Pricing Analysis
Captive integration of C6 sugar feedstocks with oxidative catalysis capacity anchors supply positioning and pricing power for FDME producers serving REACH-registered polymer grades. German automotive OEMs and Dutch packaging converters negotiate from this structural foundation, where backward control over corn-processing infrastructure in Iowa and Minnesota creates cost advantages against spot-feedstock competitors.
Pricing Analysis
Lead-time premiums for electronics-grade FDME with sub-ppm metal specifications command substantial markups over standard polymer grades, while spot inventory discounts emerge for coatings-formulator volumes moving through Rotterdam distributors. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor encapsulation laminates from beverage packaging intermediates and industrial solvent formulations. Price differentiation hinges on REACH batch certification status and volume scale, with pricing pressure intensifying as virgin PET recycling infrastructure delays bio-based polyester payback periods. Mid-tier coatings formulators exhibit highest price sensitivity, while Japanese semiconductor packaging operations demonstrate lowest elasticity due to qualification timeline rigidity.
Supply Chain Analysis
Direct-to-OEM channels handle automotive and electronics hyperscale buyer demand, with long-term offtake agreements dominating polymer-grade FDME procurement. Supply concentrates in Germany, the United States, and the Netherlands, where pilot-scale conversion facilities cluster around automotive OEMs and chemical processors. Raw material dependencies center on corn-derived C6 sugars, methanol for esterification, and heterogeneous oxidation catalysts. Single-source vulnerability from geographic concentration in Baden-Württemberg and Bavaria creates structural exposure, compounded by tariff exposure on agricultural residue flows. Distribution runs through integrated direct sales for certified grades and regional chemical distributors for standardized formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDME procurement operates as a cost-of-compliance story where REACH substance registration creates barrier-to-entry moats for certified producers, filtering out unqualified suppliers and consolidating demand around batch-traceable operations.
For Market Incumbents: Cement market position by securing backward integration into corn-processing infrastructure in the US Midwest, insulating against feedstock price volatility that threatens margin stability. Expand catalysis-through-polymer validation capabilities to defend against emerging biorefinery operators with novel continuous-flow reactor designs. Prioritize certification investment for FDA food-contact substance notifications to capture beverage packaging procurement timelines compressed by brand owner sustainability pledges.
For New Entrants and Emerging Players: Regional chemical distributors in Benelux and northern France offer channel access to mid-tier coatings formulators seeking reduced inventory carrying costs and technical service support. Target solvent-reduction formulation trials in French and Italian industrial finishing operations, where EU F-Gas Regulation compliance deadlines create penetrable white space. Pursue go-to-market angles through biorefinery co-product valorization partnerships that improve plant economics via levulinic acid side-stream integration.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical conglomerates seeking catalysis capabilities and polymer validation pathways. Long-term viability favors producers with demonstrated continuous-flow reactor engineering and automated process analytical control systems for real-time purity verification. Monitor EPA biofuel pathway evaluation reclassifications as inflection indicators for feedstock economics shifts redirecting agricultural residue flows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Security | Corn-processing infrastructure in Iowa and Minnesota anchors C6 sugar supply chains against price volatility. |
| Capacity Expansion in Pilot-Scale Facilities | Baden-Württemberg and Bavaria conversion sites serve automotive OEM qualification programs. |
| Long-term Supply Agreement with OEMs | Electric vehicle platform lightweighting mandates pull furan-based polymers into production scale. |
| Joint Venture for Electronics-Grade Purification | Osaka-Kobe and Busan-Ulsan corridors demand sub-ppm metal specifications for semiconductor packaging. |
| Green Manufacturing Transition via Biorefinery Integration | Levulinic acid and hydroxymethylfurfural side-stream valorization improves carbon accounting frameworks. |
Research Methodology
Multi-period observation of pilot-scale facility commissioning, REACH registration timelines, and automotive material qualification programs anchored the trend analysis, supplemented by interviews with plant managers at oxidative catalysis operations, procurement leads at packaging converters, technical R&D directors in polymerization catalyst development, and distribution channel partners in Rotterdam and Antwerp hubs. Secondary validation drew from ECHA regulatory guidance documents, EPA biofuel pathway evaluations, customs and trade data for furan platform chemicals, and SEC filings from integrated chemical conglomerates. Bottom-up capacity estimates triangulated against top-down demand projections from beverage and personal care brand owner sustainability scorecards.
Segment-weighting approaches modeled product type tiers, end-use industry cost structures, and application-driven volume-maturity dynamics across the projection horizon. Analytical frameworks incorporated grade purity thresholds, thermal stability requirements, and regional regulatory cluster variations. CAGRs derived from installed capacity ramp schedules, polymerization catalyst scaling timelines, and brand owner contract minimum enforcement patterns. Industry-specific forecast inputs included heterogeneous catalyst degradation rates in continuous-flow FDCA production and solid-state polymerization reactor retrofit complexity for legacy PET equipment.
Caveats apply where catalytic efficiency breakthroughs, biorefinery co-product economics shifts, or FDA food-contact notification timeline accelerations could materially shift the outlook. Practitioners should monitor EU Green Deal compliance deadline enforcement, renewable identification number credit reclassifications, and semiconductor packaging laminate qualification completions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Citrate Market
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
Potassium Methylate Market
Functional Chemicals
Succinimide Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Ortho-Phthalaldehyde Market
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Citrulline Malate Market
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
Global Potassium Citrate Market
Functional Chemicals
Urea Formaldehyde Market