
 Global PEO Software Market | 2026-2036
Global PEO Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global PEO Software Market Outlook
Subscription-based compliance modules is repositioning how PEO software vendors monetize core HR platforms, shifting revenue from perpetual licenses to recurring access fees tied to regulatory updates. ADP TotalSource leverages its scale across tax jurisdictions to sustain dominant channel control in North America. TriNet anchors its competitive stance through vertical specialization in technology and healthcare sectors. Papaya Global differentiates by extending cloud-native architecture across emerging market payroll corridors.
Professional employer organization software integrates payroll processing, benefits administration, and regulatory compliance into unified workforce management platforms, typically delivered through multi-tenant cloud architectures with API connectivity to local tax authorities. The primary commercial purpose centers on enabling client companies to outsource employer-of-record responsibilities while retaining operational oversight of daily employee activities. Cloud-based deployment leads among product types due to lower implementation friction and automatic regulatory patch delivery, while compliance management commands the strongest margin pool within service categories as jurisdictional complexity intensifies. Small businesses represent the fastest-growing customer type as lean HR teams seek externalized expertise in employment law adherence.
FDA oversight of healthcare sector employee credentialing, EEOC guidelines on anti-discrimination recordkeeping, and GDPR data-processing requirements for EU-based workers collectively shape product development priorities and market access conditions for PEO software vendors. OSHA reporting integrations and state-level workers compensation regulations further fragment technical requirements across North American deployments. Stakeholders must monitor how emerging AI-driven hiring tools trigger fresh algorithmic accountability rules across multiple jurisdictions.
Market Dynamics
Cross-border employment compliance is fragmenting into jurisdiction-specific modules as the EU AI Act and evolving GDPR workforce-data rules force vendors to rebuild core architectures around automated regulatory patching rather than static rule engines.
Growth Catalysts
- GDPR workforce-data evolution:EU member states are tightening consent frameworks for employee biometric and performance data processing, compelling mid-market employers to outsource compliance infrastructure to specialized PEO platforms with embedded legal monitoring.
- API-first payroll corridors:Cloud-native architectures with direct tax authority connectivity in India and Brazil are reducing implementation timelines from quarters to weeks for multinational expansions.
- Small business HR externalization:Lean technology and healthcare sector employers with under fifty employees are abandoning in-house compliance functions entirely, driving subscription attach rates for regulatory update modules.
Market Restraints
- Input cost volatility:Specialized employment law expertise in German works councils and French labor tribunals commands premium pricing that compresses vendor margins on fixed-fee contracts.
- Supply concentration risk:North American tax calculation engines depend on three legacy providers for real-time jurisdictional rate updates, creating single-point-of-failure exposure during filing season peaks.
- Technical limitation:Real-time synchronization between benefits administration and local health insurance exchanges remains unreliable in fragmented Indian state-level implementations.
Strategic Opportunities
- Underpenetrated German mid-market:Mittelstand manufacturers with complex shift-based workforces lack localized PEO solutions combining payroll with co-determination compliance.
- Technology convergence:Embedded AI-driven contract classification tools merging with existing workforce platforms can automate worker status determinations across gig and traditional employment categories.
- Regulatory tailwind:India's Digital Personal Data Protection Act mandates auditable consent trails for employee information, creating mandatory upgrade cycles for legacy HR systems.
Industry Challenges
- Integration complexity with on-premise ERP:Large manufacturing clients in the United States maintain decades-old SAP and Oracle installations that resist API-based connectivity without expensive middleware development.
- Certification timeline compression:ISO 27001 and SOC 2 Type II audits for multi-tenant platforms now require continuous compliance monitoring rather than annual snapshots, stretching security engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PEO Software Market |
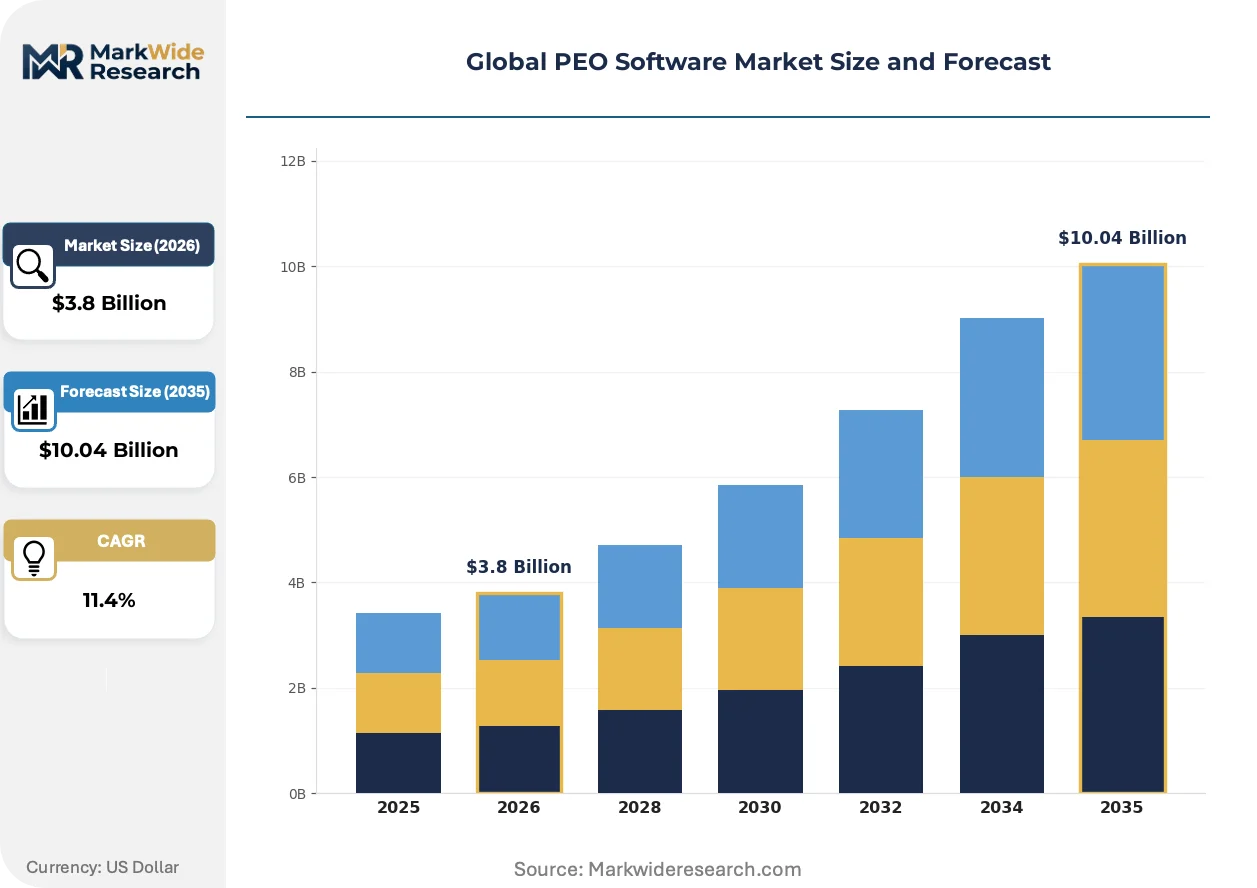
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile Service Type: Payroll Processing, Compliance Management, HR Administration, Employee Benefits Industry Vertical: Healthcare, Retail, Manufacturing, Technology Customer Type: Small Businesses, Medium Enterprises, Large Corporations, Startups |
| Companies Covered | ADP TotalSource, TriNet, Paychex PEO, Insperity, Justworks, Rippling, Papaya Global, Deel, Multiplier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PEO Software Market Strategic Shifts
Architectural decisions around data residency and algorithmic transparency are separating platform winners from legacy vendors unable to modularize compliance engines for divergent national requirements.
Native multi-tenant cloud payroll engines with automatic regulatory patch delivery are overtaking single-tenant hosted alternatives that require manual updates for each tax jurisdiction change. Small and medium enterprises with limited IT staffing are adopting these platforms fastest, compressing implementation windows from six-month cycles to under thirty days. This acceleration is forcing legacy providers to abandon perpetual license revenue models entirely.
The EU AI Act's risk classification system for employment-related algorithmic decision-making is mandating human-in-the-loop documentation and audit trails for automated hiring and performance tools. Vendors must now embed explainability interfaces directly into workforce analytics modules or face market access restrictions. German and French deployments are experiencing the most immediate compliance pressure as national regulators issue supplementary guidance ahead of full enforcement.
Buyer concentration among private equity-backed portfolio companies is consolidating vendor selection around platforms with standardized reporting across multiple holdings. Technology sector employers with distributed workforces are replacing point solutions for each country with unified global payroll contracts. This pattern is most visible in United States and India corridor expansions where rapid headcount scaling demands single-vendor accountability.
Global PEO Software Market Segmentation
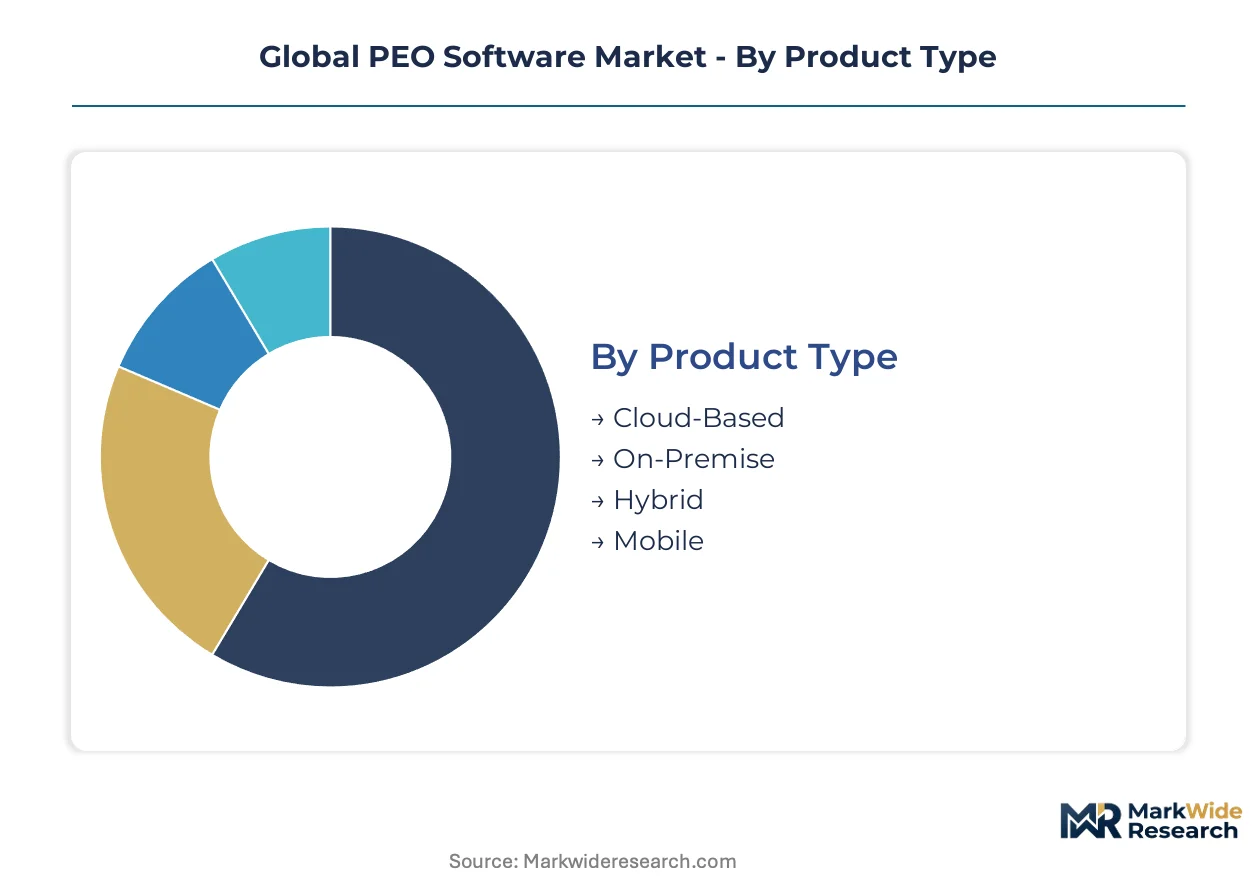
PEO software segmentation reveals how deployment architectures, service bundles, and buyer scale determine platform economics. Vendors must align engineering roadmaps with the compliance intensity and integration requirements of each segment cluster.
Product Type:
Cloud-native architectures with automatic regulatory patching are displacing legacy infrastructure across all buyer tiers.
- Cloud-Based:Multi-tenant SaaS platforms deliver real-time tax authority connectivity and embedded compliance updates. Demand concentrates among United States technology employers with distributed workforces requiring instant jurisdictional scaling.
- On-Premise:Single-tenant installations behind client firewalls persist in German manufacturing and United States defense contracting where data residency mandates override cloud economics. These deployments carry 18-24 month implementation cycles and dedicated infrastructure teams.
- Hybrid:Split architectures keep payroll engines local while pushing analytics to cloud tiers. Indian mid-market employers adopt this pattern to satisfy RBI data localization rules without sacrificing workforce visibility.
- Mobile:Native iOS and Android applications for manager self-service and employee onboarding. Startups with field-based workforces in Brazil and Mexico drive adoption for offline-capable expense submission.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Cloud-Based.
Service Type:
Margin pools diverge sharply between commodity payroll processing and high-retention compliance modules.
- Compliance Management:Automated regulatory monitoring across GDPR, EU AI Act, and OSHA reporting requirements. German Mittelstand manufacturers with works council obligations generate the steepest expansion trajectory for jurisdiction-specific rule engines.
- Payroll Processing:Core wage calculation, tax withholding, and direct deposit orchestration. United States small businesses with under fifty employees represent volume concentration, though pricing pressure from API-first competitors compresses margins.
- HR Administration:Time tracking, leave management, and employee record systems. Medium enterprises in India's technology corridors adopt these modules to replace fragmented spreadsheet workflows.
- Employee Benefits:Health insurance exchange integration, retirement plan administration, and voluntary benefit marketplaces. Large corporations with multi-state United States operations require carrier-agnostic platforms for competitive bidding.
Revenue concentration sits with Payroll Processing. Margin expansion is concentrated in Compliance Management.
Industry Vertical:
Regulatory complexity and workforce composition determine platform customization depth per vertical.
- Healthcare:FDA credentialing compliance, shift-based scheduling, and HIPAA-aligned data handling. United States hospital systems with traveling nurse programs demand multi-state license verification automation.
- Technology:Rapid headcount scaling, stock compensation administration, and distributed team management. India and United States corridor expansions dominate new contract volume.
- Retail:High-turnover hourly workforce scheduling and seasonal hiring spikes. Large German chains with union-negotiated works council structures require co-determination workflow integration.
- Manufacturing:OSHA incident reporting, skills-based pay grades, and apprenticeship tracking. Indian automotive suppliers with PLI scheme compliance obligations drive specialized module demand.
Platform maturity sits with Healthcare. New vertical penetration is concentrated in Technology.
Customer Type:
Buyer scale dictates service model economics from self-service onboarding to dedicated account management.
- Small Businesses:Employers with under fifty employees outsourcing entire HR functions. United States lean technology startups with no dedicated PeopleOps staff represent the fastest-climbing subscription attach rates for regulatory update modules.
- Medium Enterprises:Organizations with 50-500 employees seeking modular platform expansion. German family-owned manufacturers with complex shift rotations and works council representation drive localized feature development.
- Large Corporations:Multi-divisional employers requiring global payroll consolidation and advanced analytics. India-based IT services firms with 10,000+ employee United States expansions demand single-vendor accountability across corridors.
- Startups:Venture-backed companies prioritizing speed-to-hire and minimal compliance overhead. Brazil and Mexico fintech employers with remote-first policies adopt mobile-first platforms for rapid international contractor onboarding.
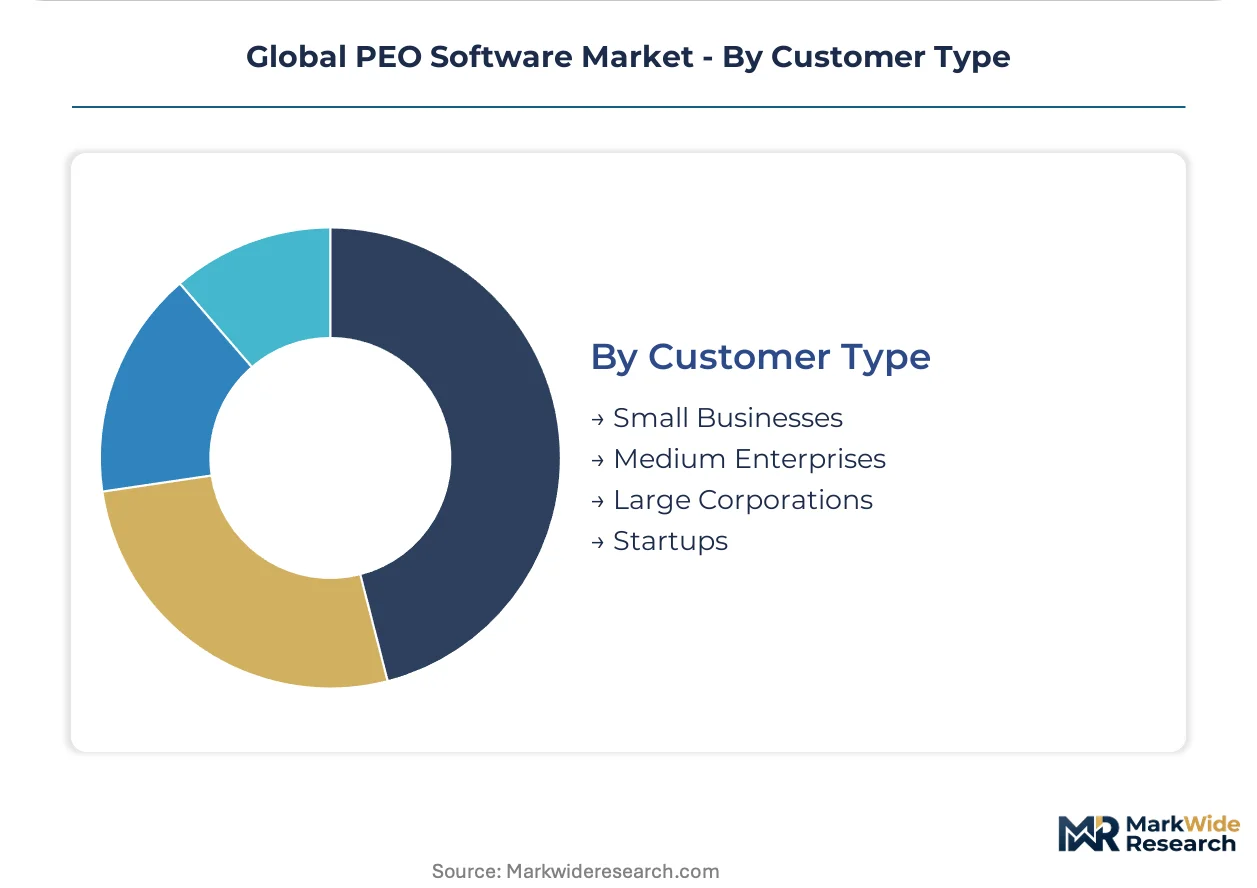
Contract value concentration sits with Large Corporations. Volume expansion is concentrated in Small Businesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PEO software production concentrates in cloud-native development hubs across the United States, Germany, and India, while consumption spreads through employer-of-record demand corridors linking these centers to distributed workforce endpoints in Brazil, Mexico, and Southeast Asia.
United States
Technology sector employers with distributed workforces and lean HR teams drive platform adoption, particularly among startups lacking dedicated PeopleOps staff. OSHA reporting integrations and multi-state workers compensation regulations fragment technical requirements across deployments. Silicon Valley and Austin clusters anchor vendor R&D investment, with corridor expansions into India generating single-vendor contract consolidation.
Germany
Mittelstand manufacturers with complex shift rotations and works council representation generate localized feature demand for co-determination compliance. The EU AI Act's risk classification system for employment-related algorithms mandates human-in-the-loop documentation, pressuring vendors to embed explainability interfaces. Industrial concentration in Baden-Württemberg and Bavaria drives specialized module development for automotive and machinery suppliers.
India
IT services firms with 10,000-plus employee United States expansions demand unified global payroll contracts and single-vendor accountability. The Digital Personal Data Protection Act mandates auditable consent trails for employee information, creating mandatory upgrade cycles for legacy HR systems. Bangalore and Hyderabad technology corridors dominate domestic platform development while serving as offshore delivery centers for multinational deployments.
Brazil
Fintech employers with remote-first policies adopt mobile-first platforms for rapid international contractor onboarding. API-first payroll architectures with direct tax authority connectivity reduce implementation timelines from quarters to weeks. São Paulo anchors financial services adoption, while regulatory fragmentation across state-level health insurance exchanges creates technical implementation challenges for benefits administration synchronization.
United Kingdom
Private equity-backed portfolio companies consolidate vendor selection around platforms with standardized reporting across multiple holdings. GDPR workforce-data evolution tightens consent frameworks for employee biometric processing. London's concentration of venture-backed technology employers drives demand for speed-to-hire solutions with minimal compliance overhead.
Global PEO Software Market Competitive Environment
Top-tier vendors anchor the multi-tenant SaaS segment, while legacy payroll processors and vertical specialists occupy distinct competitive tiers. Market structure reflects consolidation around scale-driven platforms with automatic regulatory patching capabilities, alongside fragmentation among region-specific compliance specialists. Three archetypes dominate: horizontal workforce management platforms, vertical specialists in technology and healthcare sectors, and emerging-market payroll corridor enablers. Competitive moves center on M&A for jurisdictional capability acquisition and API-first architecture development for tax authority connectivity.
Within the established platform tier, ADP TotalSource exemplifies scale-driven consolidation across North American tax jurisdictions, while TriNet occupies a position as a vertical specialist anchoring competitive stance through sector-specific customization. Papaya Global represents the cloud-native archetype extending architecture across emerging market payroll corridors. These three entities illustrate how vendor positioning diverges between geographic scale, industry depth, and architectural modernization vectors.
| Leading Market Players |
|---|
| ADP TotalSource |
| TriNet |
| Paychex PEO |
| Insperity |
| Justworks |
| Rippling |
| Papaya Global |
| Deel |
| Multiplier |
| Others |
Value Chain & Pricing Dynamics
EU AI Act algorithmic accountability mandates gate qualified supply for premium-tier PEO software vendors, forcing compliance-heavy engineering investments that separate ISO 27001-certified platforms from commodity payroll processors and reshape pricing power across customer tiers.
Pricing Analysis
Margin tightening in mid-market subscriptions reflects jurisdictional module fragmentation as EU AI Act and GDPR workforce-data rules multiply engineering costs per deployment. Three-tier pricing structure across enterprise, mid-market, and small business levels differentiates by compliance depth and API connectivity density. Pricing pressure stems from API-first entrants compressing implementation timelines in India and Brazil corridors. Small businesses with under fifty employees exhibit highest price sensitivity, while large corporations with multi-country expansions prioritize single-vendor accountability over unit economics.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certification gating concentrates qualified development talent in United States, Germany, and India cloud-native hubs. Core platform engineering draws from specialized employment law expertise pools in German works council advisory and French labor tribunal systems. Supply chain risk centers on North American tax calculation engine concentration among legacy rate-update providers. Distribution runs through direct enterprise sales teams for large corporations and self-service digital channels for small business adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PEO software market structure favors consolidation plays as regulatory patch automation investments force sub-scale vendors toward exit or acquisition, with EU AI Act compliance timelines accelerating shakeout dynamics.
For Market Incumbents: Cement dominance through M&A for jurisdictional capability acquisition in underpenetrated German Mittelstand manufacturing, while embedding explainability interfaces ahead of full EU AI Act enforcement. Channel control in North American tax jurisdictions anchors defensive positioning against API-first payroll corridor specialists. Vertical specialization in healthcare FDA credentialing and technology sector stock compensation administration deepens switching costs. For New Entrants and Emerging Players: Lean technology startups with no dedicated PeopleOps staff represent the most penetrable buyer archetype for mobile-first platforms with sub-thirty-day implementation windows. White-space concentration sits in Brazilian fintech remote-first employers and Mexican contractor onboarding corridors where legacy vendors lack offline-capable expense submission. Go-to-market execution should emphasize API-first tax authority connectivity as the primary differentiation lever. For Investors and Strategic Acquirers: Mandatory upgrade cycles triggered by India's Digital Personal Data Protection Act is the leading indicator that compliance-driven replacement demand will sustain vendor valuation premiums across the mid-market. Long-term viability frames around platforms with modularized compliance engines capable of divergent national requirements. Acquisition target archetype: cloud-native specialists with emerging market payroll corridor presence and embedded legal monitoring infrastructure. Signal to monitor: German works council co-determination workflow integration capabilities as Mittelstand penetration benchmark.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Jurisdictional capability acquisition in German Mittelstand manufacturing accelerates localized feature development timelines. |
| Platform Integration | Embedded AI-driven contract classification tools automate worker status determinations across gig and traditional employment categories. |
| Geographic Expansion | API-first payroll corridor penetration in Brazil and Mexico reduces multinational implementation windows from quarters to weeks. |
| Product Launch | Compliance management modules with automatic regulatory patching capture margin expansion as jurisdictional complexity intensifies. |
| Strategic Partnership | Direct tax authority connectivity partnerships in India and Brazil anchor cloud-native architecture differentiation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with PEO platform CTOs, HR procurement officers at technology and healthcare employers, employment law advisory specialists, and integration engineers with secondary validation from SEC filings, EU AI Act implementation guidance, and RBI data localization circulars. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates.
Granularity-level modeling operated at deployment architecture, organization size tier, vertical specialization, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic employment indicators and cross-border outsourcing penetration trends. Industry-specific forecast inputs included API connectivity density metrics and compliance module attach rate trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement timing, GDPR workforce-data rule evolution, and emerging market tax authority API standardization pace. Forecasts reflect assumptions around regulatory patch automation feasibility and mid-market outsourcing propensity without guaranteed outcomes. A model refresh is warranted upon material change in EU AI Act risk classification implementation schedules or India's Digital Personal Data Protection Act audit requirement finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Session Support Software Market
Software & Services
Cloud Communication Platform Software Market
Software & Services
Customer Revenue Optimization Software Market
Software & Services
Software-Defined Anything Market
Software & Services
Video Converter Software Market
Software & Services
Output Management Software Market
Software & Services
Legal Practice Management Software Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Data Center Backup and Recovery Software Market
Software & Services
K8s Market
Software & Services
Global Headless CMS Software Market
Software & Services
Structured Data Management Software Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Smartphone Applications Market
Software & Services
Global Auction Software Market