
 Legal Practice Management Software Market | 2026-2036
Legal Practice Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Legal Practice Management Software Market Outlook
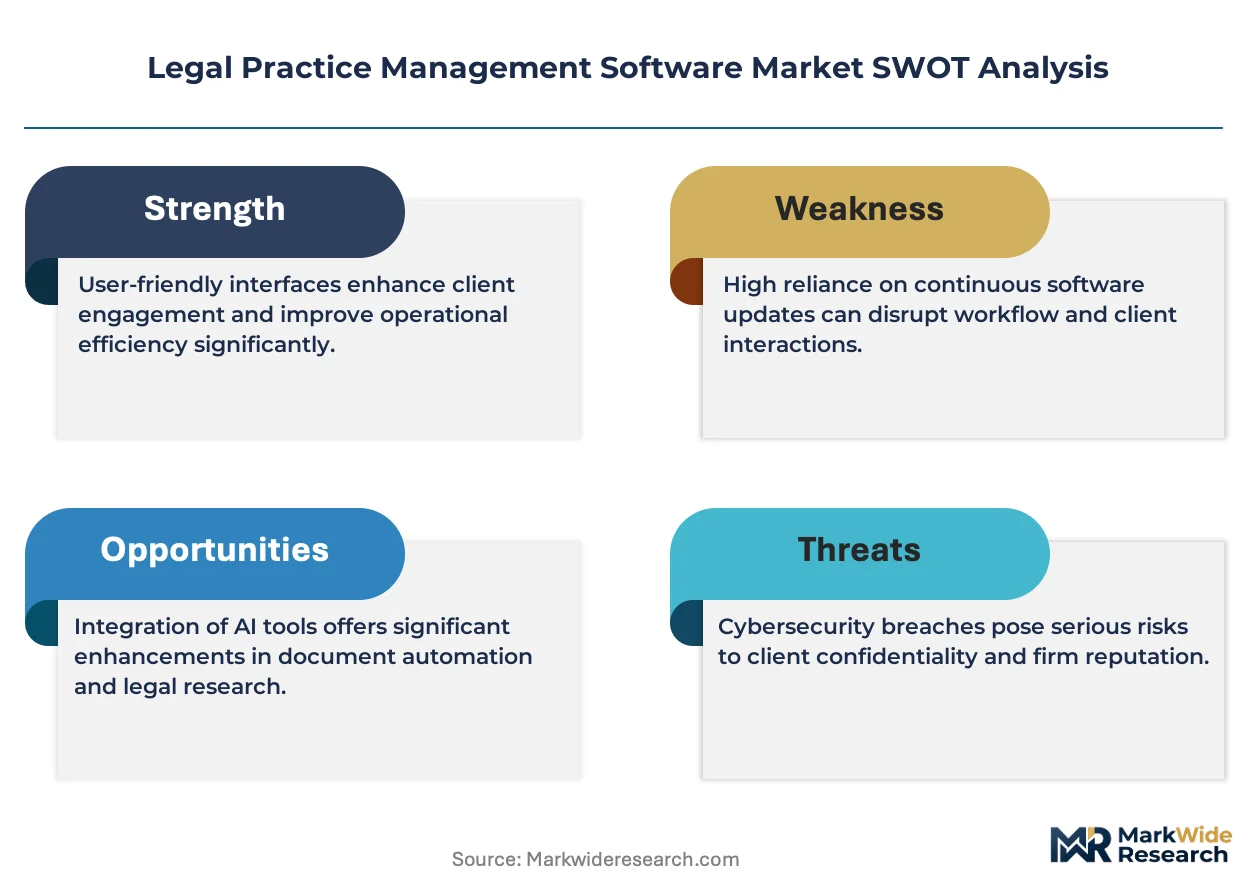
The EU AI Act is expanding the compliance burden for vendors selling automated decision-making tools into European legal markets, forcing platform redesigns around transparency and auditability. Clio leverages its first-mover cloud infrastructure to sustain dominance across North American small-to-mid-sized practices. Filevine differentiates through vertical specialization in mass tort and personal injury workflows. Smokeball anchors its position in the Australian and UK markets through tight calendar-court integration.
Legal practice management software denotes an integrated technology stack that orchestrates matter lifecycle workflows, trust accounting, time capture, and document assembly within a unified database architecture. The primary commercial purpose is to reduce administrative leakage while enforcing ethical walls and billing compliance across fee-earner populations. Cloud-based deployment leads the feature dimension because subscription economics lower capital barriers for solo practitioners and boutique firms. Case management functionality captures the deepest margin pools due to customization intensity and multi-year implementation cycles. On-premise installations occupy a shrinking but defensible niche among government agencies and white-shoe firms with stringent data sovereignty requirements.
The EU AI Act, GDPR, and state-level U.S. bar technology competence rules collectively reshape product roadmaps and geographic go-to-market sequencing. HIPAA and SEC record-keeping standards extend compliance obligations for legal software serving healthcare and securities practices. Stakeholders must monitor divergence between European algorithmic accountability mandates and American sectoral privacy frameworks when prioritizing development investment.
Market Dynamics
The EU AI Act mandates algorithmic transparency for automated legal decision tools, forcing vendors to rebuild workflow engines around audit trails and explainability requirements rather than black-box efficiency.
Growth Catalysts
- State Bar Technology Mandates:Multiple U.S. state jurisdictions now require technology competence for continuing legal education, creating compulsory upgrade cycles for practicing attorneys.
- Cloud Subscription Economics:Recurring revenue models eliminate capital expenditure barriers for solo practitioners and boutique firms, expanding addressable market penetration.
- GDPR and HIPAA Convergence:Cross-border data protection rules compel unified compliance architectures that legal software vendors can monetize as premium trust-accounting modules.
Market Restraints
- Data Sovereignty Requirements:Government agencies and white-shoe firms in Germany, France, and Switzerland demand on-premise installations, constraining cloud-native vendor expansion.
- Technical Debt Burden:Decades-old case management databases in established practices resist API integration, prolonging implementation timelines and inflating professional services costs.
- Substitution by Generic Platforms:Salesforce and Microsoft 365 ecosystems now offer configurable legal workflows at lower per-seat pricing, pressuring specialized vendor margins.
Strategic Opportunities
- India and Southeast Asia:Liberalization of foreign law firm ownership rules in Singapore and India creates first-mover advantage for cloud-based practice management entrants.
- AI-Document Convergence:Natural language processing engines integrated with contract lifecycle management open new revenue streams beyond traditional matter management.
- Outcome-Based Pricing Modules:Flat-fee and contingency billing workflows embedded within time-capture systems address alternative fee arrangement growth in personal injury and employment practices.
Industry Challenges
- Ethical Wall Engineering:Conflicts checking algorithms must reconcile against real-time corporate family tree data, requiring expensive third-party integrations and ongoing data licensing.
- Certification Timeline Compression:State bar ethics opinions lag behind product releases, creating liability exposure for vendors deploying AI-assisted billing before regulatory clarity emerges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legal Practice Management Software Market |
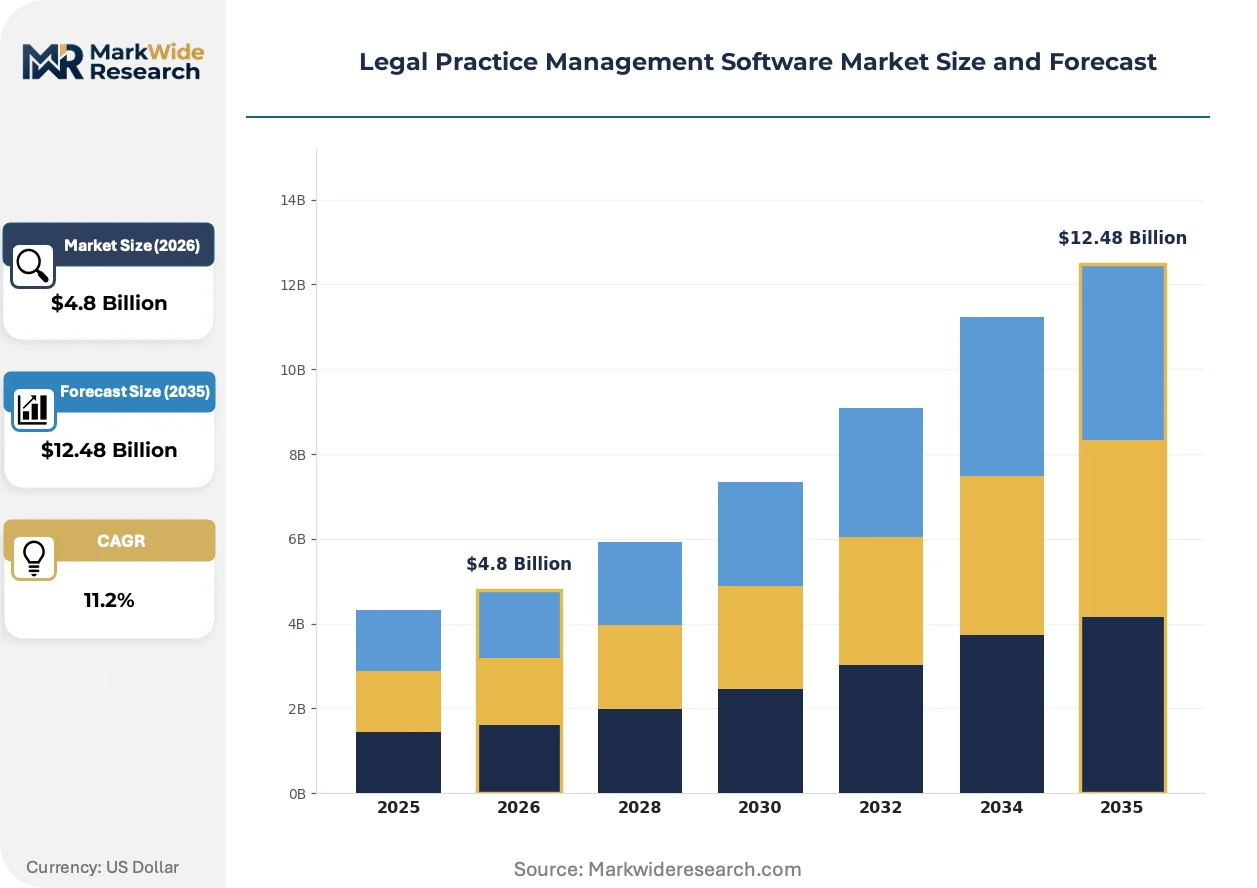
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Dedicated Server End User: Law Firms, Solo Practitioners, Corporate Legal Departments, Government Agencies Feature: Time Tracking, Billing Management, Document Automation, Case Management Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | CosmoLex, Filevine, Clio, Caret Legal, AbacusLaw, PracticePanther, MyCase, SurePoint Technologies, Smokeball, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legal Practice Management Software Market Strategic Shifts
Generative AI is compressing document assembly timelines from hours to minutes, forcing incumbents to reprice value away from hourly capture toward platform subscription stickiness.
Natural language generation embedded within matter management platforms is automating first-draft contract creation, deposition summaries, and client intake forms. Mid-sized litigation practices in Texas, Florida, and California are deploying these tools at scale, reducing associate leverage ratios. This compression is automating away traditional time-entry economics and forcing firms toward fixed-fee value pricing.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on high-risk legal automation tools, including those affecting judicial proceedings or asylum decisions. Vendors must now maintain technical documentation, human oversight protocols, and accuracy metrics for algorithmic outputs. European legal software deployments face 12-18 month compliance certification delays that U.S. and Australian competitors exploit for first-mover positioning.
Subscription bundling now dominates procurement decisions as law firms consolidate vendor relationships to reduce integration overhead and security audit burden. Channel partners and legal technology consultants in the United Kingdom and Australia are displacing direct sales motions for implementations above fifty seats. This concentration is most visible in London's Magic Circle firms and Sydney's top-tier practices, where procurement committees mandate single-platform standardization across all practice groups.
Legal Practice Management Software Market Segmentation
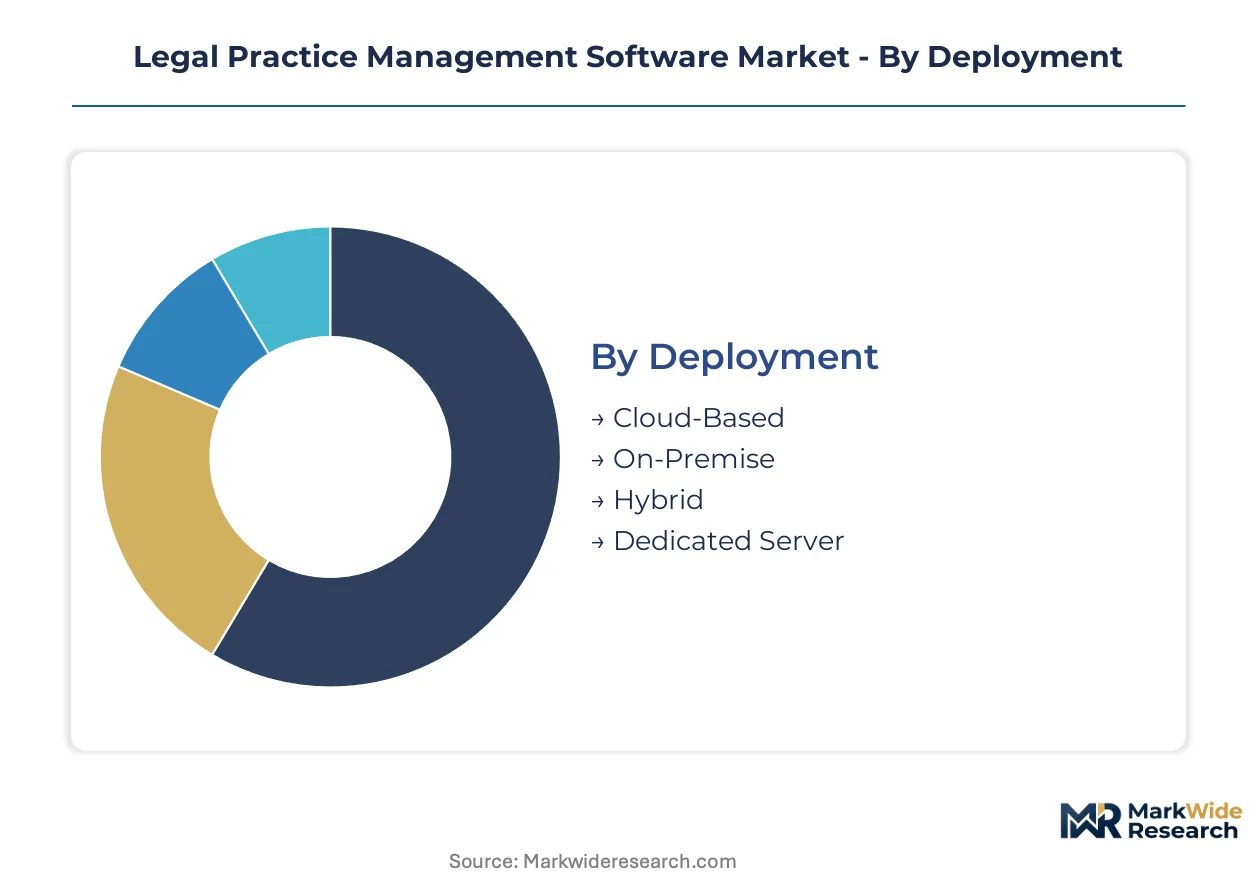
Segmentation reveals how vendor R&D investment and pricing architecture diverge across deployment modes, user scale, and functional depth. Procurement patterns in this market cluster around compliance requirements and capital constraints rather than feature breadth alone.
Deployment:
Supply concentration tilts heavily toward multi-tenant cloud architectures that amortize infrastructure costs across subscriber bases.
- Cloud-Based:Multi-tenant SaaS architectures with automatic updates and browser-based access dominate new vendor development pipelines. United States mid-sized firms in Texas and Florida drive subscription volume, compelled by state bar technology competence mandates that favor low-friction deployment.
- On-Premise:Self-hosted installations on client-controlled hardware persist where data sovereignty overrides operational agility. German government legal departments and Swiss white-shoe firms sustain this segment despite shrinking vendor support pools.
- Hybrid:Split architectures placing sensitive matters on-premise while routing routine workflows through cloud instances. Corporate legal departments in regulated industries favor this configuration for privilege protection.
- Dedicated Server:Single-tenant cloud deployments offering physical isolation without full on-premise burden. Australian top-tier practices and UK Magic Circle procurement committees specify this for security audit simplification.
Cloud-Based absorbs the bulk of installed capacity; Dedicated Server is expanding most quickly among security-conscious enterprise buyers.
End User:
Cost tier stratification separates price-sensitive solo operators from procurement committees managing hundred-seat rollouts.
- Law Firms:Partnership structures with 10-200 attorneys constitute the core revenue base, requiring trust accounting, conflicts checking, and matter-centric collaboration. California and New York litigation boutiques generate disproportionate demand for integrated billing-case management bundles.
- Solo Practitioners:Individual attorneys operating without support staff prioritize mobile time capture and simplified invoicing. Cloud subscription economics at sub-fifty-dollar price points unlock this long-tail segment.
- Corporate Legal Departments:In-house teams embedded within enterprises demand enterprise-grade security certifications and API connectivity to broader business systems. HIPAA and SEC record-keeping obligations shape their vendor selection criteria.
- Government Agencies:Public sector legal offices operate under procurement rules mandating on-premise or dedicated infrastructure. Federal and state-level offices in Germany, France, and Switzerland maintain legacy system dependencies.
Law Firms command the deepest vendor investment; Corporate Legal Departments are climbing the fastest as enterprises insource litigation.
Feature:
Application criticality varies by practice economics, with time-capture functionality commanding premium pricing in billable-hour cultures.
- Time Tracking:Automated capture of billable hours through desktop, mobile, and calendar integration underpins hourly billing compliance. Personal injury and mass tort practices in the United States depend on granular activity logs for contingency fee reconciliation.
- Billing Management:Invoice generation, trust accounting, and payment processing modules enforce ethical wall compliance and IOLTA regulations. State bar disciplinary exposure makes this non-negotiable for US-based practitioners.
- Document Automation:Template-driven assembly of contracts, pleadings, and correspondence compresses associate leverage ratios. Generative AI integration is repositioning this from efficiency tool to strategic differentiator.
- Case Management:Centralized matter files linking contacts, deadlines, documents, and financials across practice lifecycles. Customization intensity and multi-year implementation cycles sustain the highest margin pools.
Case Management captures the steepest expansion trajectory; Time Tracking remains the default entry point for new firm adoption.
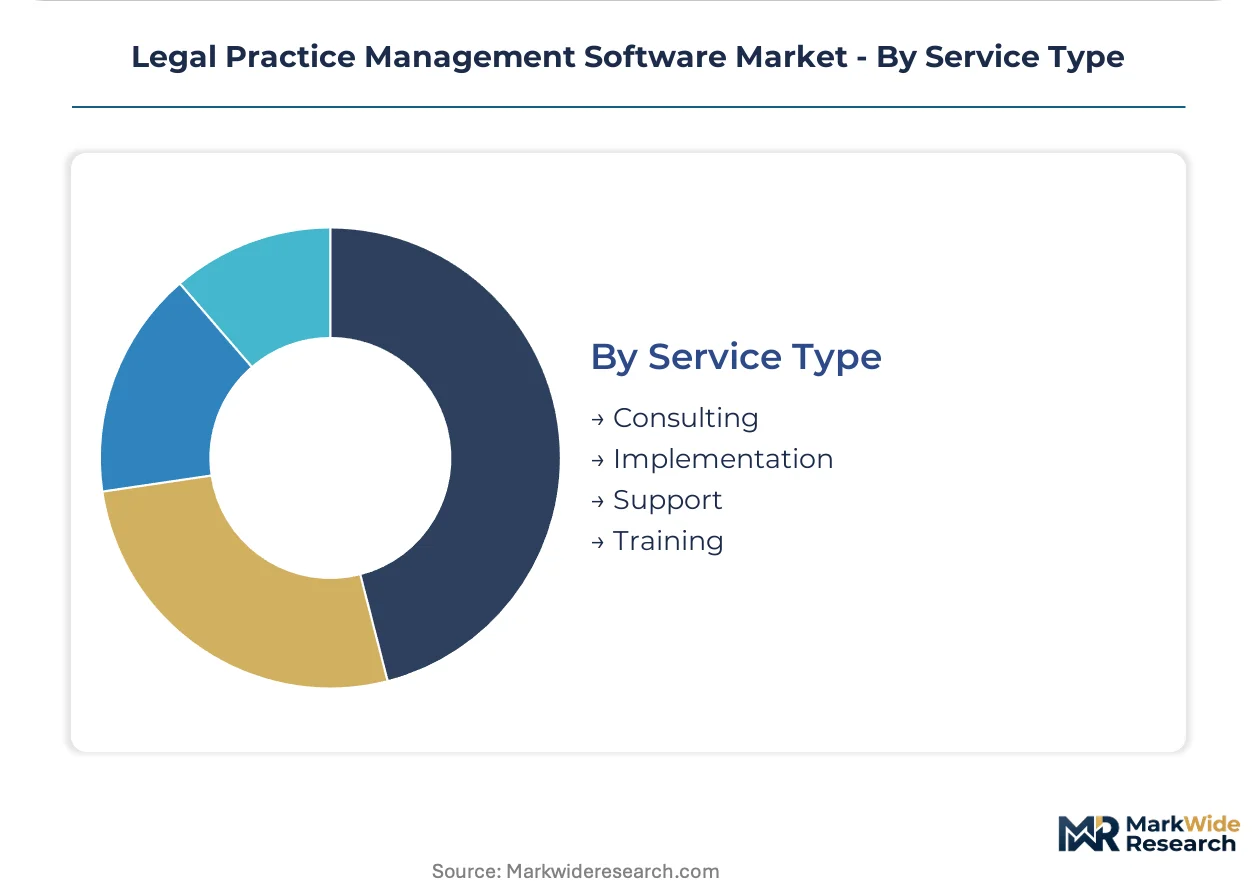
Service Type:
Customer maturity determines whether engagements emphasize initial configuration or ongoing optimization.
- Consulting:Workflow analysis and practice management redesign preceding platform selection. Large firm technology committees in London and Sydney commission these engagements for fifty-seat-plus implementations.
- Implementation:Data migration, system configuration, and integration with existing practice tools. Technical debt in decades-old case management databases prolongs these timelines.
- Support:Tiered helpdesk services distinguishing critical matter downtime from routine feature inquiries. Subscription bundling is compressing standalone support pricing.
- Training:Role-based certification programs for attorneys, paralegals, and administrative staff. State bar CLE accreditation requirements in multiple US jurisdictions sustain demand.
Implementation consumes the largest professional services allocation; Consulting is gaining share fastest as firms prioritize change management over technical deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors the deepest concentration of legal technology venture capital and cloud infrastructure development, with San Francisco and San Jose hosting the headquarters of dominant practice management platforms serving North American law firms.
United States
Texas and Florida litigation boutiques drive cloud subscription volume through state bar technology competence mandates that compel platform upgrades. The American Bar Association's Model Rules on technology competence create baseline obligations that cascade through state disciplinary systems. California's Silicon Valley corridor concentrates platform engineering talent and venture funding for AI-integrated workflow tools.
Germany
Federal and state government legal departments sustain on-premise installation demand through stringent data sovereignty requirements under national cybersecurity frameworks. The Federal Office for Information Security (BSI) certifies legal software for public sector procurement, creating compliance barriers for foreign cloud vendors. Frankfurt's financial legal sector maintains hybrid deployments balancing cloud efficiency with banking regulator data localization rules.
United Kingdom
London's Magic Circle procurement committees mandate single-platform standardization across all practice groups, compressing vendor relationships toward bundled subscriptions. The Solicitors Regulation Authority's technology and innovation guidance shapes compliance expectations for AI-assisted legal workflows. Sydney's top-tier practices mirror this procurement pattern through channel partner and consultant-led implementations.
Australia
New South Wales and Victoria state courts drive demand for calendar-court integration through electronic filing mandates and digital hearing management systems. The Australian Solicitors Conduct Rules technology competence requirements parallel American state bar developments. Melbourne's mid-sized litigation practices deploy document automation at scale for personal injury and commercial dispute workflows.
India
Liberalization of foreign law firm ownership rules in Singapore and India creates first-mover positioning for cloud-based entrants targeting emerging legal services demand. The Bar Council of India's technology guidelines for advocates establish nascent competence frameworks. Bangalore's legal process outsourcing clusters integrate practice management platforms with contract lifecycle management for multinational corporate clients.
Legal Practice Management Software Market Competitive Environment
The competitive structure tilts toward cloud-native specialists with established subscription economies of scale. Consolidation pressure concentrates around vendors offering integrated billing-case management bundles rather than point solutions. Three archetypes dominate: legacy on-premise incumbents defending government and white-shoe firm relationships; cloud-first platforms capturing mid-market volume through low-friction deployment; and vertical specialists embedding mass tort and personal injury workflows. Dominant competitive moves include geographic expansion into liberalizing Asian legal markets and AI-document convergence through natural language processing partnerships.
Within the cloud-native tier, Clio and Filevine occupy positions exemplifying divergent specialization strategies. Clio represents the horizontal scale archetype with infrastructure spanning small-to-mid-sized practices across North America. Filevine anchors the vertical depth position with workflow engineering concentrated in high-volume litigation segments. Smokeball exemplifies regional dominance through court system integration, securing defensive positioning in Australian and UK jurisdictions where calendar-court connectivity determines procurement decisions.
| Leading Market Players |
|---|
| CosmoLex |
| Filevine |
| Clio |
| Caret Legal |
| AbacusLaw |
| PracticePanther |
| MyCase |
| SurePoint Technologies |
| Smokeball |
| Others |
Value Chain & Pricing Dynamics
Mid-sized law firms in Texas and Florida anchor subscription volume, compelling vendors toward per-seat SaaS tiers with automatic compliance updates bundled into base pricing. Cloud-native platforms extract pricing power from state bar technology mandates that eliminate procurement delay tactics, while on-premise specialists defend premium positioning through data sovereignty certifications for German government legal departments.
Pricing Analysis
Per-matter value pricing tied to case outcome velocity anchors premium tiers for personal injury and mass tort practices. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade API connectivity from browser-only access and basic trust accounting. Cost compression in the solo practitioner tier intensifies because Microsoft 365 and Salesforce ecosystems undercut specialized vendors on per-seat economics. Corporate legal departments show least price sensitivity due to HIPAA and SEC record-keeping obligations that mandate certified compliance modules.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certifications gate vendor participation in UK Magic Circle and Australian top-tier procurement committees. Engineering talent concentrates in the United States, India, and Ireland, with Bangalore legal process outsourcing clusters feeding contract lifecycle management integrations. Cloud infrastructure draws from hyperscaler data centers in Frankfurt, Sydney, and Singapore, exposing vendors to EU AI Act conformity assessment delays. Distribution runs through channel partners and legal technology consultants for implementations above fifty seats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cloud-transition phase where generative AI document assembly displaces legacy time-entry economics. Vendors must reposition value capture from hourly capture toward platform subscription stickiness.
For Market Incumbents: Anticipate margin erosion from Microsoft 365 legal workflow configurations by deepening API integration partnerships with court systems and corporate ERP platforms. Defend position through exclusive data licensing for real-time corporate family tree conflicts checking, a capability generic platforms cannot replicate without expensive third-party contracts.
For New Entrants and Emerging Players: Capture first-mover positioning in India's liberalizing legal services market through cloud-native platforms designed for Bar Council of India technology guidelines. Target Singapore foreign law firm ownership liberalization with matter management tools pre-integrated with Southeast Asian contract lifecycle management workflows.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertical specialists with mass tort workflow depth in United States litigation corridors. Long-term viability hinges on AI-document convergence capabilities that reposition document automation from efficiency tool to strategic differentiator. Watch EU AI Act conformity assessment timeline compression as inflection signal for European competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates billing-case management bundles to reduce procurement committee vendor audit burden. |
| Geographic Expansion | Exploits 12-18 month EU AI Act certification delays to establish first-mover positioning in Asian liberalizing markets. |
| Acquisition of Specialist Firm | Absorbs vertical workflow depth in personal injury and mass tort segments with multi-year implementation cycles. |
| Strategic Partnership | Secures exclusive corporate family tree data licensing for conflicts checking algorithms against real-time ownership structures. |
| Product Launch | Deploys generative AI document assembly compressing contract creation timelines from hours to minutes. |
Study Parameters
SEC filings, state bar disciplinary databases, and EU AI Act conformity assessment records formed the secondary backbone. Primary interviews with legal technology consultants, court system integration specialists, and law firm technology committees validated deployment timelines and procurement patterns. Conversations with channel partners in London and Sydney captured subscription bundling trends across Magic Circle and top-tier practices. Bottom-up triangulation across firm-size segments and top-down validation against cloud infrastructure spend disclosures anchored volume estimates.
Bottom-up modeling of subscriber counts by deployment mode and organization size converged with top-down cloud software spend allocation across legal verticals. Segmentation dimensions spanned deployment architecture, end-user scale, functional depth, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical adoption inflections at state bar mandate implementation. Forecast inputs incorporated EU AI Act compliance timeline assumptions and generative AI feature penetration curves across document automation modules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement intensity and generic platform competitive encroachment. Forecasts reflect documented assumptions on state bar technology mandate expansion timelines and cloud infrastructure cost trajectories. A model refresh is warranted upon material change in EU AI Act high-risk system classification scope or Microsoft 365 legal workflow feature depth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Log Management Software Market
Software & Services
North America Equity Management Software Market
Software & Services
Global Plumbing Software Market
Software & Services
Email Applications Market
Software & Services
Petcare Software Market
Software & Services
Performance Management Software Market
Software & Services
Legal Software Market
Software & Services
Freight Management Software Market
Software & Services
Procurement Software Market
Software & Services
Employee Referral Software Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Global Translation Software Market
Software & Services
Mobile Application Development Platform (MADP) Market
Software & Services
UK Point of Sale Software Market
Software & Services
Global PEO Software Market
Software & Services
Global API Management Software Market