
 Session Support Software Market | 2026-2036
Session Support Software Market Size, Share, and Industry Trends Forecast 2026-2036
Session Support Software Market Insights
Premium behavioral analytics is decoupling from commodity session recording in pricing, architecture, and buyer expectations. FullStory, Inc. leverages deep digital experience intelligence to anchor enterprise contracts with advanced frustration signal detection. Hotjar Ltd. competes through accessible heatmapping and survey tools that dominate the mid-market self-service segment. Dynatrace LLC differentiates by extending session data into full-stack observability, controlling the premium integration layer.
Session support software encompasses tools that capture, replay, and analyze user interactions across web and mobile applications, typically processing DOM mutations, clickstreams, and network events at millisecond granularity to diagnose friction points and accelerate support resolution. The primary commercial purpose centers on reducing mean time to resolution for customer-facing technical issues while surfacing product improvement opportunities from aggregated behavioral telemetry. Cloud-based deployment leads volume expansion as IT services and retail buyers prioritize elastic infrastructure over capital-intensive on-premises installations. API integration capabilities command disproportionate margin attention because buyers demand seamless data flow into existing CRM and ticketing ecosystems rather than isolated point solutions.
ISO 27001 certification shapes vendor qualification criteria for enterprise procurement teams evaluating session data handling practices. In the United States, HIPAA constraints apply where healthcare end users process protected health information through support channels, while GDPR and the EU AI Act govern European deployments with strict purpose limitation and automated decision-making transparency requirements. Stakeholders must monitor evolving cross-border data localization mandates that could fragment cloud architecture strategies and force region-specific infrastructure commitments.
Market Dynamics
Enterprise IT services teams are decoupling behavioral analytics from commodity session recording, forcing vendors to rebuild architectures around privacy-preserving telemetry and API-first integration layers rather than standalone replay tools.
Growth Catalysts
- EU AI Act compliance mandates:GDPR and the EU AI Act are accelerating procurement of purpose-limited session data platforms across European financial services and healthcare providers.
- Cloud infrastructure elasticity:Retail and SaaS buyers in the United States are prioritizing elastic, consumption-based deployment models over capital-intensive on-premises installations.
- Fortune 500 digital experience budgets:Concentrated investment by US retailers in customer-facing technical issue resolution is pulling premium session intelligence spend.
Market Restraints
- Cross-border data localization mandates:Fragmenting cloud architecture strategies are forcing vendors into region-specific infrastructure commitments that compress margin structures.
- ISO 27001 certification barriers:Enterprise procurement teams are disqualifying vendors lacking certified session data handling practices, narrowing the qualified supplier pool.
- HIPAA constraint complexity:Healthcare end users processing protected health information through support channels face audit-intensive compliance requirements that extend sales cycles.
Strategic Opportunities
- API integration white space:Seamless data flow into existing CRM and ticketing ecosystems commands disproportionate margin attention versus isolated point solutions.
- Co-browsing convergence with observability:Session replay platforms that extend into full-stack telemetry capture premium integration contracts from IT services buyers.
- Mid-market self-service penetration:Accessible heatmapping and survey tools remain underdeployed among mid-market SaaS providers relative to enterprise saturation.
Industry Challenges
- Millisecond-granularity engineering talent scarcity:Capturing DOM mutations, clickstreams, and network events at required fidelity demands specialized frontend instrumentation expertise that outpaces supply.
- Legacy ticketing system integration friction:Buyers demand seamless workflow embedding, forcing vendors to maintain expensive connector development across fragmented CRM ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Session Support Software Market |
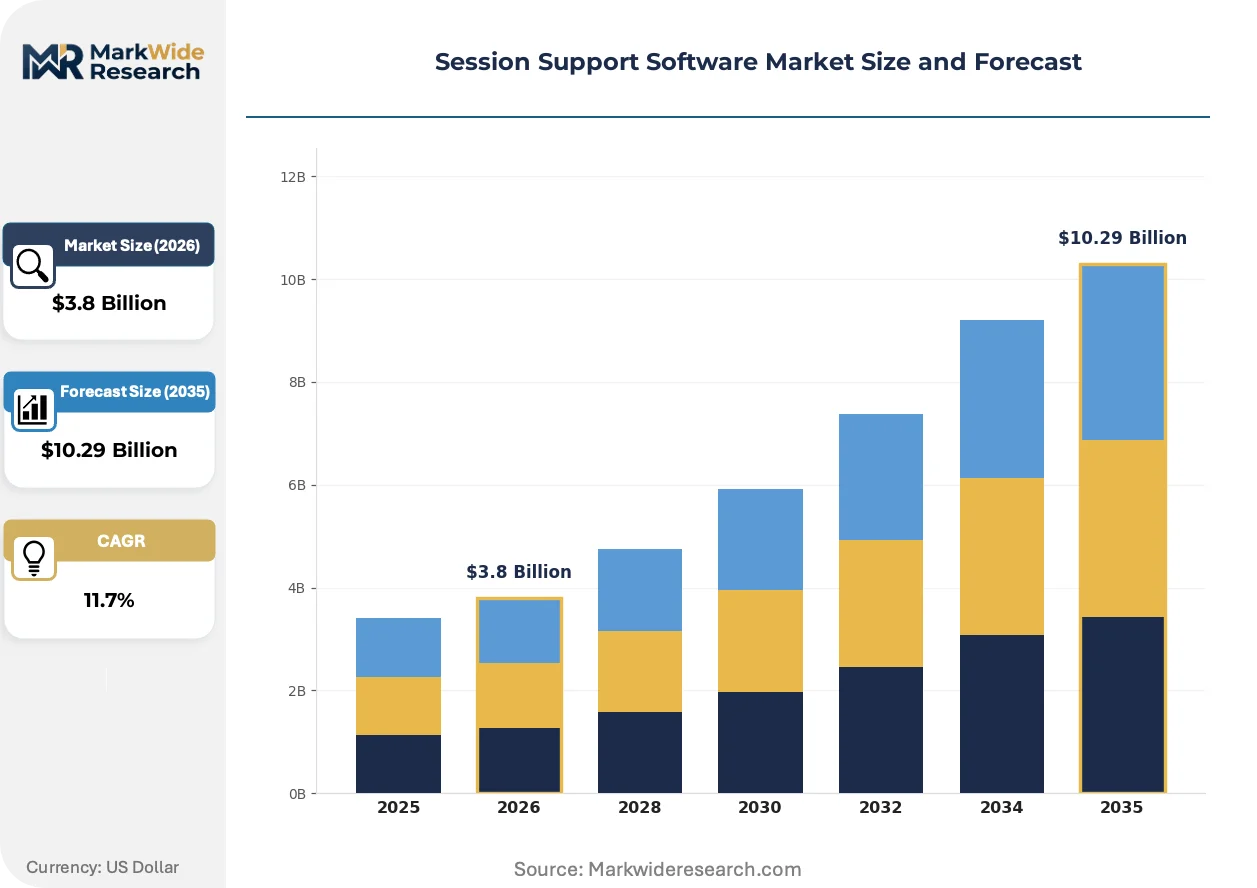
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Assistance, Live Chat, Screen Sharing, Ticketing System Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Retail, IT Services, Healthcare, Telecommunications Integration Level: API Integration, CRM Integration, ERP Integration, Third-Party Tools |
| Companies Covered | FullStory, Inc., Hotjar Ltd., Mouseflow, Smartlook, LogRocket, Inc., Dynatrace LLC, Datadog, Lucky Orange LLC, SessionStack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Session Support Software Market Trends and Innovations
Privacy-preserving telemetry architectures are actively displacing conventional session capture methods as regulatory pressure intensifies and buyer technical sophistication matures across enterprise procurement teams.
Differential privacy and on-device aggregation techniques are rewriting how session data flows from browser to warehouse. Financial services buyers in Germany and the United Kingdom are piloting these architectures ahead of full EU AI Act enforcement. The structural consequence is compressing the addressable market for raw session storage while expanding margin pools for privacy-engineered analytics layers.
The EU AI Act's automated decision-making transparency requirements are reshaping vendor qualification criteria. Session support platforms must now document purpose limitation and algorithmic explainability to serve European enterprise buyers. Healthcare and retail deployments in France and the Netherlands are experiencing the steepest compliance-driven procurement delays.
Subscription-to-consumption billing migration is altering vendor-customer relationships. Mid-market SaaS providers are unbundling seat-based contracts in favor of event-volume pricing that aligns spend with actual diagnostic usage. This pattern is most visible among Series B and C software companies in the United States seeking to rationalize pre-IPO operational expenditure.
Session Support Software Market Segmentation
Session support software segments diverge sharply in infrastructure requirements and compliance exposure. Buyers select configurations based on telemetry granularity needs, data residency constraints, and existing enterprise system architectures.
Product Type:
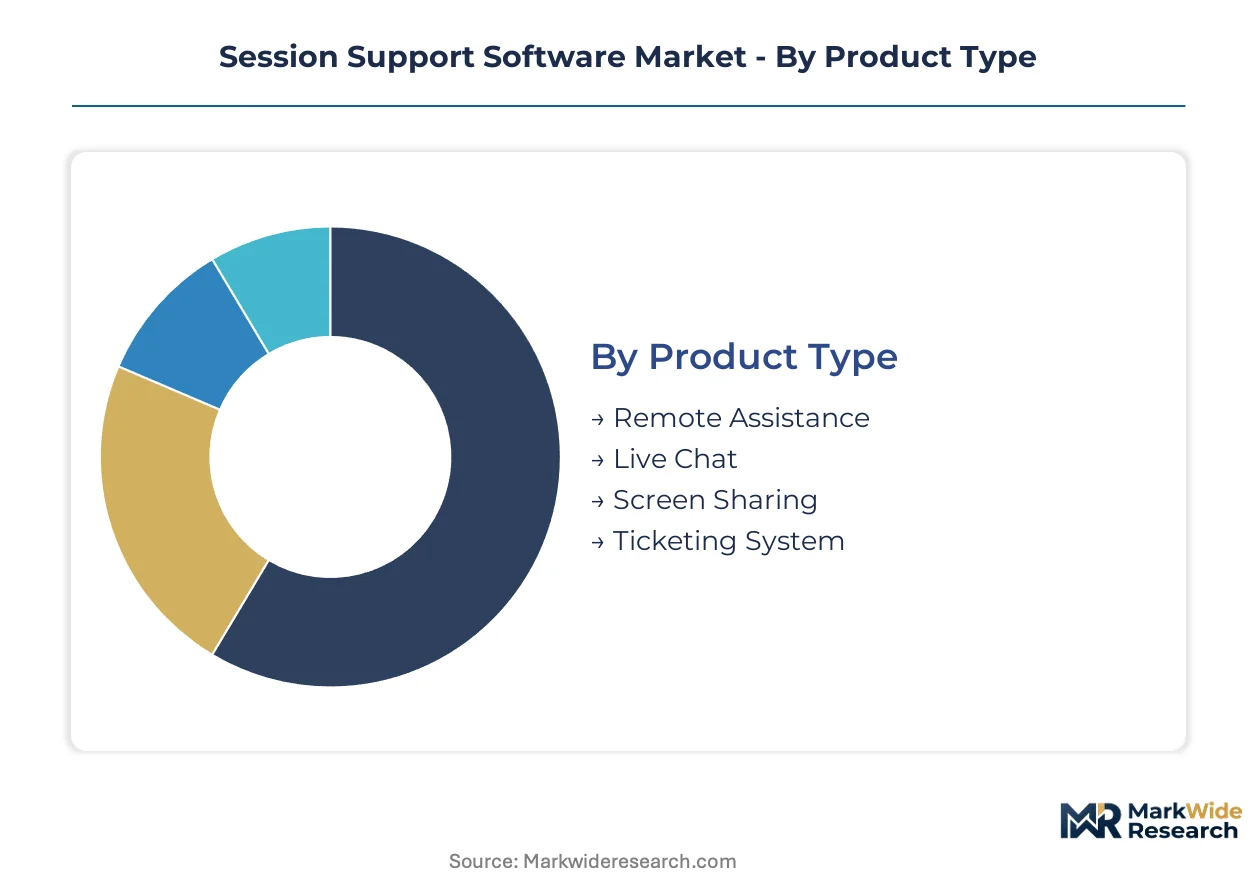
Remote Assistance and Live Chat demand the heaviest upfront engineering investment for millisecond-granularity capture engines and real-time streaming infrastructure.
- Remote Assistance:Combines co-browsing with full session replay for agent-guided troubleshooting. Financial services buyers in Germany and the United Kingdom prioritize this segment under EU AI Act transparency mandates.
- Live Chat:Synchronous messaging platforms with embedded behavioral context. Retailers in the United States deploy these at scale to compress mean time to resolution during peak transaction windows.
- Screen Sharing:Lightweight visual collaboration without DOM mutation logging. Healthcare providers favor this format to minimize PHI exposure in HIPAA-regulated environments.
- Ticketing System:Issue tracking with attached session metadata. IT services teams integrate these into existing ServiceNow or Zendesk workflows.
Remote Assistance absorbs the bulk of installed capacity; Live Chat is expanding most quickly.
Deployment:
Cloud-Based and SaaS configurations dominate procurement volume, while On-Premises retains footholds where data localization mandates apply.
- Cloud-Based:Elastic infrastructure with consumption-based pricing. SaaS providers in the United States favor this model to align diagnostic spend with actual event volume.
- SaaS:Fully managed multi-tenant platforms with rapid feature iteration. Mid-market buyers select this tier for zero-maintenance telemetry pipelines.
- On-Premises:Captive infrastructure for air-gapped or regulated environments. German automotive suppliers deploy these to satisfy BSI IT-Grundschutz requirements.
- Hybrid:Split architectures with edge aggregation and cloud analytics. French healthcare networks pilot these to balance GDPR data minimization with diagnostic depth.
Cloud-Based deployments command the largest revenue pool; Hybrid configurations are climbing the fastest as cross-border fragmentation intensifies.
End User:
Retail and IT Services generate disproportionate contract value through high-volume, mission-critical customer interaction pipelines.
- Retail:Fortune 500 e-commerce platforms processing millions of daily sessions. These buyers demand sub-second replay latency during checkout abandonment analysis.
- IT Services:Managed service providers embedding session intelligence into multi-client support operations. ISO 27001 certification is non-negotiable for enterprise procurement in this vertical.
- Healthcare:Hospitals and telehealth platforms navigating HIPAA audit trails. Extended sales cycles reflect compliance review intensity for PHI-adjacent tooling.
- Telecommunications:Subscriber support centers diagnosing network-impacted digital experiences. These deployments emphasize mobile session capture for app-based service channels.
Retail captures the greatest share of annual contract value; Healthcare is gaining share fastest as telehealth volumes stabilize post-pandemic.
Integration Level:
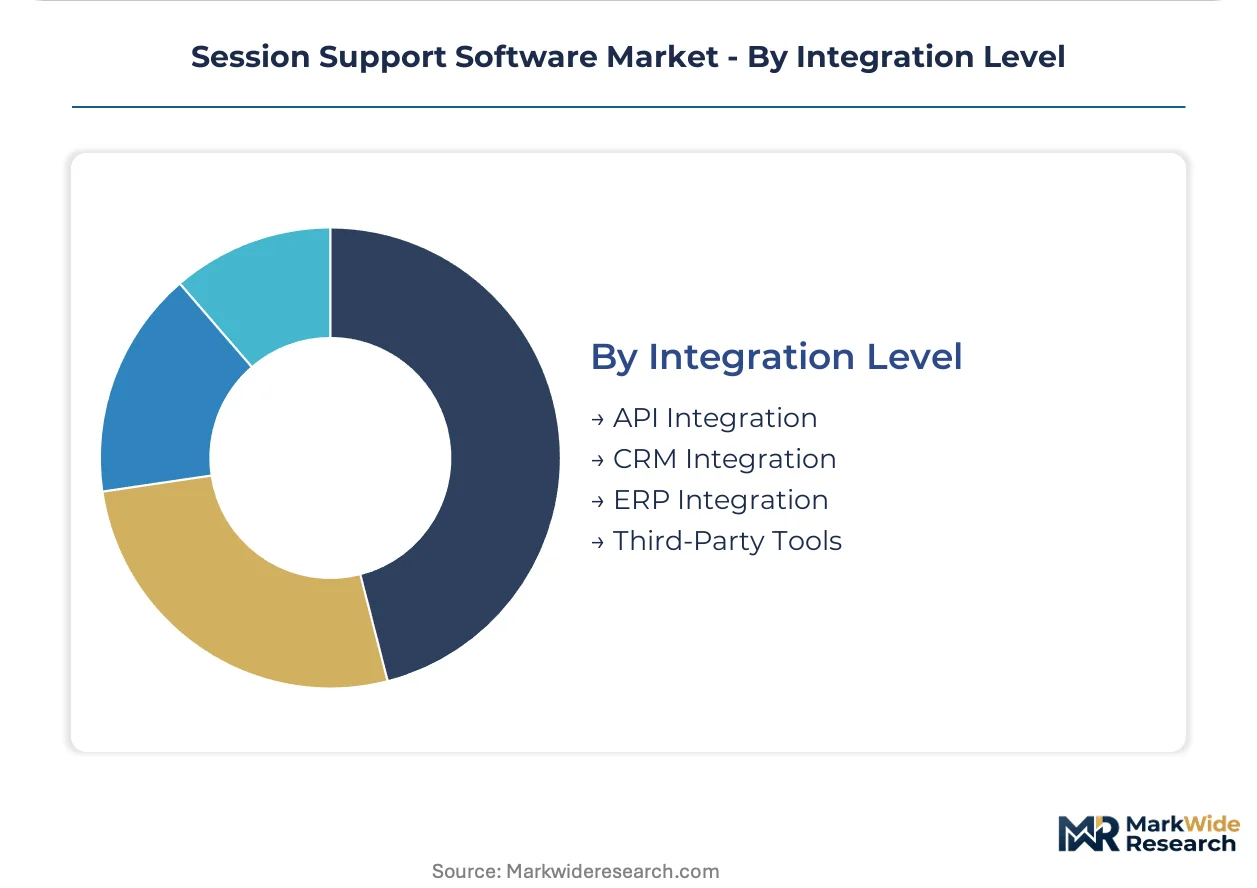
API Integration and CRM Integration attract premium pricing through workflow embedding and data unification capabilities.
- API Integration:Direct programmatic access to session events and metadata. Engineering teams at Series B and C SaaS companies in the United States prioritize this for custom analytics pipelines.
- CRM Integration:Native connectors to Salesforce, HubSpot, and Microsoft Dynamics. Sales operations teams demand this to correlate support friction with churn risk scoring.
- ERP Integration:Session data flowing into financial and supply chain systems. Discrete manufacturing buyers in Japan leverage these linkages for warranty claim validation.
- Third-Party Tools:Pre-built connectors to observability and marketing stacks. These reduce time-to-value for buyers with fragmented existing tooling.
API Integration anchors the highest-margin contracts; Third-Party Tools are expanding most quickly as connector marketplaces mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco Bay Area technology clusters anchor the highest concentration of session support software deployment, with enterprise SaaS providers and Fortune 500 retailers driving diagnostic infrastructure investment across three distinct continental markets.
United States
Fortune 500 retailers and Series B-C SaaS providers in Austin and New York Metro are expanding cloud-based session replay contracts to compress checkout abandonment resolution times. HIPAA constraints apply where healthcare end users process protected health information through support channels, extending sales cycles for PHI-adjacent tooling. Boston-based healthcare networks pilot hybrid deployment architectures to balance diagnostic depth with audit trail requirements.
Germany
Automotive suppliers in Stuttgart and Munich are deploying on-premises session capture to satisfy BSI IT-Grundschutz requirements for air-gapped manufacturing environments. The EU AI Act's automated decision-making transparency mandates are reshaping vendor qualification criteria for financial services buyers in Frankfurt. Berlin-based fintech pilots differential privacy architectures ahead of full regulatory enforcement.
United Kingdom
London financial services firms are procuring purpose-limited session data platforms under converging GDPR and EU AI Act compliance pressure. The Financial Conduct Authority's operational resilience expectations are accelerating investment in real-time co-browsing for trading platform support. Manchester-based IT services providers embed session intelligence into multi-client managed service operations.
France
Healthcare networks in Paris and Lyon are experiencing steep compliance-driven procurement delays as CNIL intensifies GDPR purpose limitation audits for telehealth platforms. Retail banking deployments in Île-de-France prioritize API integration layers that document algorithmic explainability. Toulouse-based aerospace suppliers evaluate hybrid architectures to satisfy defense contractor data residency requirements.
India
Bangalore and Hyderabad SaaS providers are unbundling seat-based contracts in favor of event-volume pricing models that align diagnostic spend with actual usage. The country's national data protection framework is pushing vendors toward edge aggregation architectures that minimize cross-border data flows. Mumbai-based IT services exporters demand ISO 27001 certification as non-negotiable procurement criteria.
Session Support Software Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light platform designers across a tiered vendor landscape. The market fragments across three strategic layers: enterprise-grade observability suites commanding premium integration contracts, mid-market self-service tools dominating volume expansion, and specialized co-browsing vendors capturing niche compliance-driven deployments. Dominant competitive moves include API-first architecture development and privacy-preserving telemetry engineering to satisfy diverging regional regulatory requirements.
Within the enterprise observability tier, Dynatrace LLC and Datadog exemplify full-stack integration strategies that extend session data into infrastructure monitoring contracts. FullStory, Inc. and Hotjar Ltd. occupy distinct positioning vectors—deep digital experience intelligence versus accessible heatmapping tools—illustrating how behavioral analytics has decoupled from commodity session recording in buyer expectations and pricing architecture.
| Leading Market Players |
|---|
| FullStory, Inc. |
| Hotjar Ltd. |
| Mouseflow |
| Smartlook |
| LogRocket, Inc. |
| Dynatrace LLC |
| Datadog |
| Lucky Orange LLC |
| SessionStack |
| Others |
Pricing and Supply Chain Analysis
Frontend instrumentation engineers concentrated in San Francisco Bay Area and Bangalore clusters command compensation premiums that widen pricing spreads between premium observability suites and economy-tier self-service tools. Labor-cost differentials between these specialized talent pools and mid-market development centers directly compress margin structures for vendors competing below the enterprise tier.
Pricing Analysis
Value-based pricing anchored to mean-time-to-resolution outcomes dominates enterprise contracts, with buyers paying premiums tied to diagnostic throughput guarantees. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified observability suites from mid-market SaaS tiers and self-service heatmapping tools. Pricing pressure stems from event-volume billing migration among Series B and C SaaS providers seeking pre-IPO operational expenditure rationalization. Mid-market SaaS buyers exhibit highest price sensitivity; Fortune 500 retailers with dedicated digital experience budgets show lowest.
Supply Chain Analysis
Reverse-logistics flows for on-premises hardware refreshes and hybrid deployment edge devices create secondary service revenue streams for systems integrators. Cloud infrastructure supply concentrates in the United States, Germany, and India, with hyperscaler regions anchoring elastic compute provisioning. Component dependencies span browser rendering engines, streaming protocols, and encryption modules. Single-source vulnerability in millisecond-granularity capture libraries threatens vendor differentiation. Distribution runs through direct enterprise sales, channel partners, and self-service digital marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU AI Act compliance mandates will force sub-scale vendors lacking privacy-preserving architectures to exit or sell. Regulatory qualification barriers favor capitalized incumbents with certified data handling practices.
For Market Incumbents: Anchor enterprise retention through differential privacy engineering investments that satisfy Frankfurt financial services procurement criteria. ISO 27001 certification maintenance and API-first architecture development defend against observability suite encroachment from full-stack competitors like Dynatrace and Datadog. For New Entrants and Emerging Players: The price-point gap between premium observability suites and economy self-service tools offers entry space for privacy-engineered mid-market platforms. Mid-market SaaS providers in Austin and New York Metro remain underpenetrated relative to enterprise saturation. Channel partnerships with IT services managed service providers accelerate time-to-revenue without direct enterprise sales overhead. For Investors and Strategic Acquirers: Re-rating potential sits with privacy-engineered analytics layer specialists given EU AI Act enforcement acceleration across European financial services and healthcare. Long-term viability favors vendors with hybrid deployment capabilities addressing cross-border data localization fragmentation. Monitor CNIL audit intensity in French healthcare networks as early signal for compliance-driven procurement delay severity.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Architecture Development | Differential privacy engineering captures Frankfurt financial services contracts under EU AI Act mandates. |
| API-First Platform Integration | Seamless CRM and ticketing ecosystem embedding commands premium margin over isolated point solutions. |
| Hybrid Deployment Capability Buildout | Edge aggregation with cloud analytics satisfies French healthcare GDPR data minimization requirements. |
| ISO 27001 Certification Investment | Certified session data handling qualifies vendors for Mumbai IT services exporter procurement. |
| Event-Volume Billing Model Migration | Consumption-based pricing aligns Series B and C SaaS provider diagnostic spend with actual usage. |
Research Methodology
Document review covered SEC filings, hyperscaler capex disclosures, and EU regulatory enforcement notices, complemented by interviews with CTOs at Series B and C SaaS providers, IT procurement officers at Fortune 500 retailers, and integration specialists at managed service providers. Primary fieldwork with platform engineers and channel partners informed deployment model preferences. Secondary validation drew from App Annie mobile telemetry data and ServiceNow ecosystem partnership directories. Bottom-up segment sizing and top-down market reconciliation triangulated volume estimates.
Model outputs project value expansion across deployment mode, organization size, vertical, integration complexity, and regional adoption pattern dimensions over the projection horizon. CAGRs were derived from elasticity-adjusted demand curves fitted to historical procurement velocity. Industry-specific inputs included ISO 27001 certification penetration rates and EU AI Act implementation timelines by member state.
Inputs from CTO interviews and regulatory filings were available through the study window; gaps in private company financial disclosures introduce uncertainty bands around mid-market vendor market share estimates. Forecasts reflect assumptions regarding enforcement consistency across CNIL, BSI, and national data protection authorities. Practitioners should monitor differential privacy pilot program outcomes in Berlin fintech and London financial services for early signals of architecture preference shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Contract Lifecycle Management Software Market
Software & Services
Europe Servicenow Store Apps Market
Software & Services
Global Offshore Software Development Market
Software & Services
Global Headless CMS Software Market
Software & Services
Professional Service Automation Market
Software & Services
Email Checker Tools Market
Software & Services
Saas Based HRM Market
Software & Services
Global Student Information System Market
Software & Services
Construction Suites Software Market
Software & Services
Global Managed Application Services Market
Software & Services
Performance Management Software Market
Software & Services
Global Electronic Dictionary Market
Software & Services
EDA Tools Market
Software & Services
Business Analytics Software Market
Software & Services
Equipment Management Software Market
Software & Services
Sales Platforms Software Market