
 Data Center Backup and Recovery Software Market | 2026-2036
Data Center Backup and Recovery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Backup and Recovery Software Market Intelligence
North American hyperscaler infrastructure buildouts are repositioning how enterprise buyers evaluate backup resilience. Commvault leverages its deep on-premises heritage to compete in hybrid environments where data gravity still favors local retention. Veeam anchors its growth in Microsoft-centric virtualization stacks, while Rubrik specializes in cloud-native immutable snapshots for ransomware recovery.
Data center backup and recovery software encompasses platforms that create, manage, and restore copies of enterprise data across physical, virtual, and cloud environments, typically supporting recovery point objectives measured in seconds to hours and recovery time objectives from minutes to days. These systems serve the fundamental commercial purpose of ensuring business continuity against hardware failures, cyber incidents, and operational errors. Cloud-based deployment is capturing the fastest expansion as organizations exit capital-intensive infrastructure, while deduplication technology holds the densest margin pool by reducing storage overhead per protected terabyte. DRaaS solutions within the solution segment are maturing rapidly as service-level guarantees replace in-house disaster recovery operations.
FDA guidelines on electronic records integrity, HIPAA security rule enforcement, and SEC cybersecurity disclosure rules are elevating backup auditability to a board-level priority in regulated US industries. The EU AI Act and GDPR cross-border data transfer restrictions are similarly forcing European operators to localize recovery infrastructure. Stakeholders must weigh immutable storage certification against latency requirements when selecting geographic recovery sites.
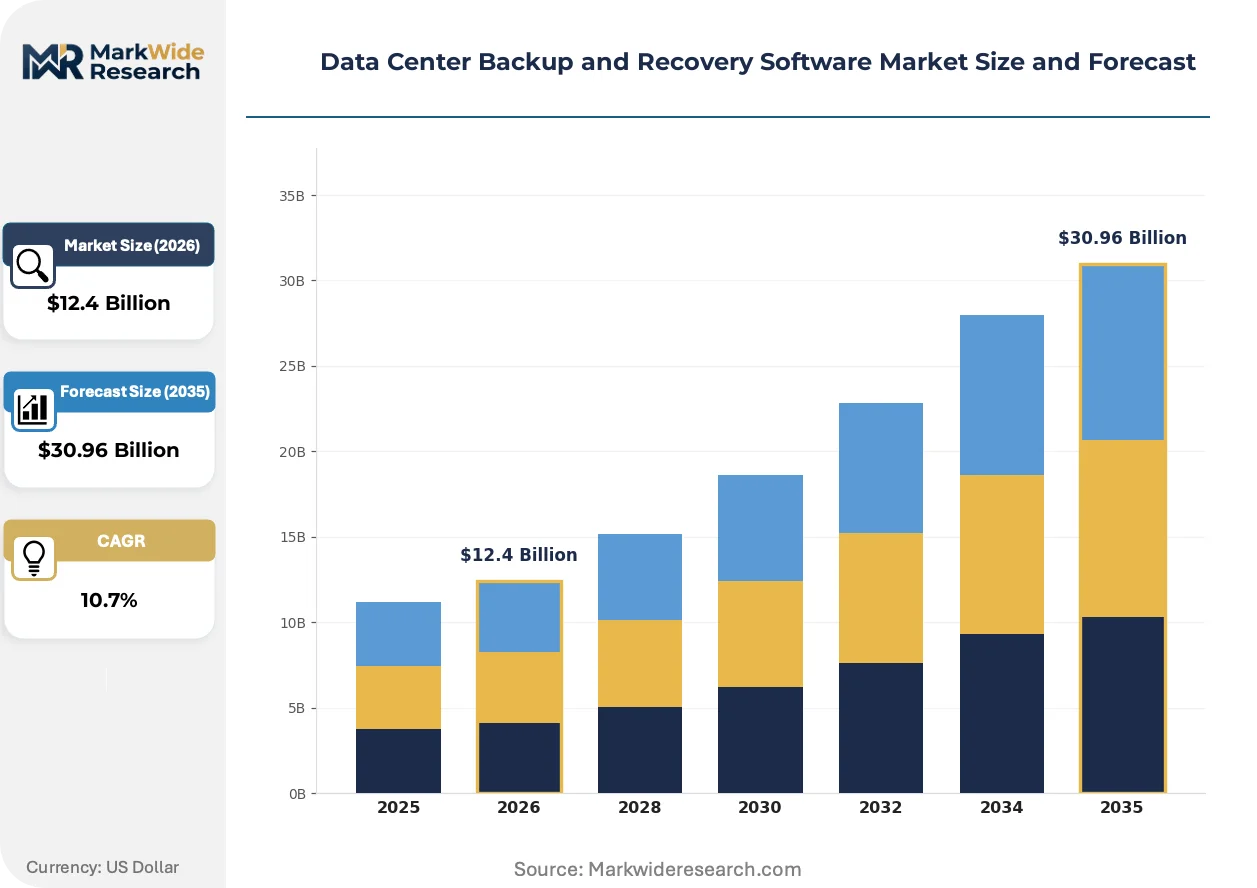
Market Dynamics
Immutable storage standards and data sovereignty mandates are compressing procurement cycles while forcing architectural splits between on-premises retention and cloud-native recovery tiers. Vendors must now certify against jurisdiction-specific audit frameworks before entering national procurement pipelines.
Growth Catalysts
- SEC Cybersecurity Disclosure Rules:Public companies must document backup recovery capabilities in financial filings, elevating immutable snapshot solutions to board-level procurement priorities.
- Ransomware Frequency:Financial services and healthcare operators are expanding air-gapped backup capacity to satisfy cyber insurance underwriters demanding demonstrated recovery point objectives under four hours.
- Edge Computing Expansion:Manufacturing and logistics facilities in Germany and India require localized backup nodes to process telemetry without cross-border data movement.
Market Restraints
- Specialized Engineering Talent Scarcity:Cloud-native backup architecture skills concentrate in Silicon Valley and Bangalore, inflating implementation costs for enterprises outside these clusters.
- Hyperscaler Storage Pricing Volatility:Egress fees from Amazon S3 and Azure Blob Storage introduce unpredictable cost spikes when recovering multi-petabyte datasets across regions.
- Legacy Tape Infrastructure Lock-in:Long-term retention contracts and physical media handling procedures delay migration to object-based immutable storage.
Strategic Opportunities
- EU AI Act Compliance Services:European operators need auditable backup chains for training data provenance, creating managed service attach rates for certified platforms.
- India Domestic Cloud Buildout:MeitY data localization directives are driving demand for indigenous backup infrastructure as global hyperscalers establish Mumbai and Hyderabad regions.
- Container-Native Protection Convergence:Kubernetes persistent volume backup integrated with DevOps pipelines opens new seats in software-driven enterprises.
Industry Challenges
- Multi-Cloud Orchestration Complexity:Enterprises operating across AWS, Azure, and Google Cloud struggle to maintain consistent recovery service levels without vendor-specific tooling proliferation.
- Immutable Certification Timeline Delays:Third-party validation against NIST and ISO 27001 standards extends sales cycles by six to nine months in regulated verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Backup and Recovery Software Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $30.96 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: DPM, Virtualization, Snapshot, Deduplication End User: Telecommunications, Finance, Healthcare, Government Solution: DRaaS, Backup Solutions, Archiving, File Recovery |
| Companies Covered | Commvault, Druva, Veeam, Dell Technologies, Veritas Technologies, Rubrik, Acronis, Arcserve, Cohesity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Backup and Recovery Software Market Strategic Shifts & Innovations
Continuous data protection architectures are displacing scheduled backup windows as ransomware recovery demands compress acceptable data loss intervals to near-zero. This shift favors platforms offering sub-second recovery point objectives without performance degradation to primary workloads.
AI-powered anomaly detection embedded in backup streams is electrifying threat identification capabilities. Financial services operators in Frankfurt and Singapore deploy these systems to flag encryption events before they propagate across secondary storage tiers. The technology is compressing mean-time-to-detection metrics from hours to minutes, forcing incumbent vendors to integrate machine learning inference engines or cede enterprise renewals.
GDPR Article 44 cross-border transfer restrictions and the EU AI Act training-data documentation requirements are mandating geographic segmentation of recovery infrastructure. European operators must now maintain physically separated backup regions with audit trails proving data residency. German automotive manufacturers and French pharmaceutical groups are leading this localization, establishing dedicated recovery sites in-country rather than relying on pan-European cloud zones.
Consumption-based licensing models are displacing perpetual capacity purchases as enterprises exit capital-intensive infrastructure ownership. Managed service providers in the United States and United Kingdom now bundle backup operations with cyber insurance policies, transferring operational risk to specialized operators. This bundling concentrates buyer power among three to four national MSSPs, compressing margins for standalone software vendors lacking service delivery capabilities.
Data Center Backup and Recovery Software Market Segmentation
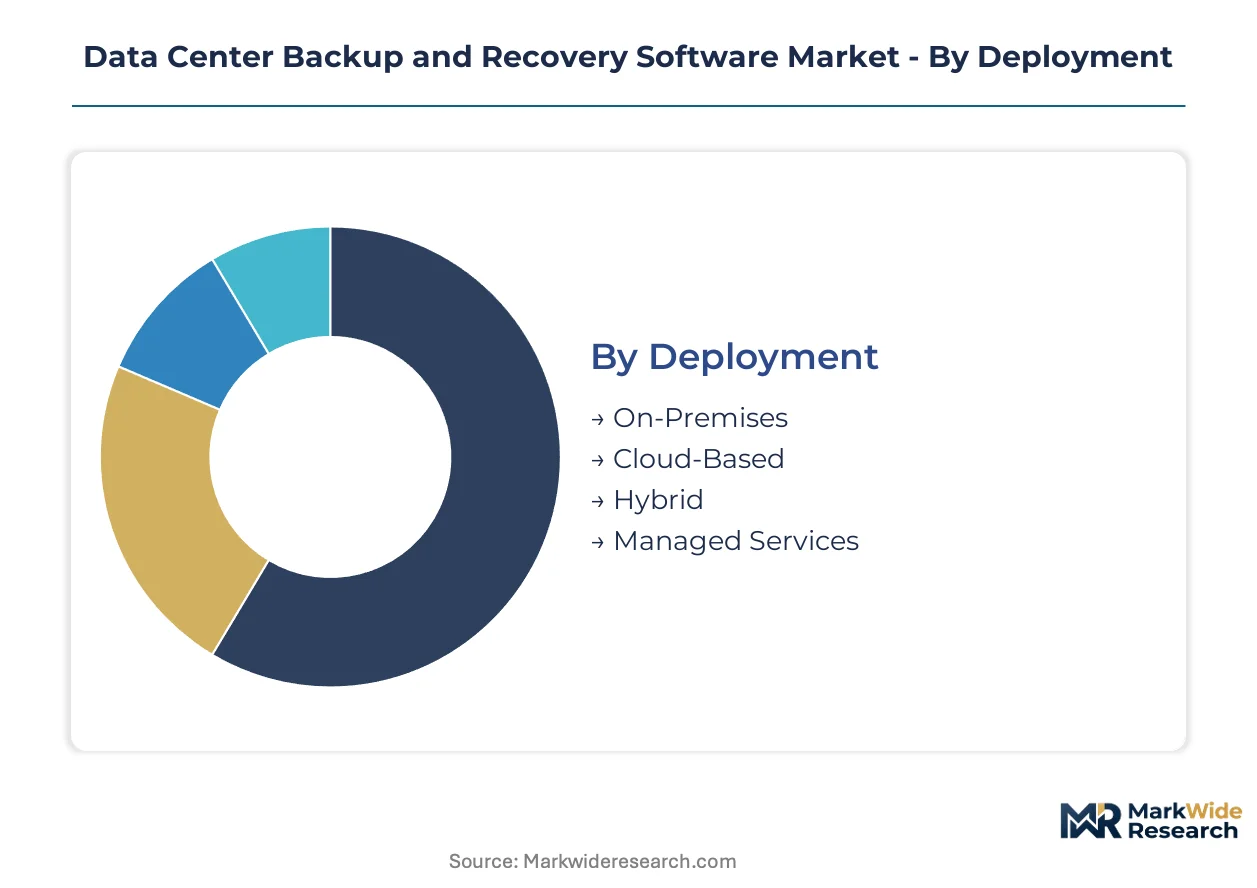
Backup infrastructure procurement splits across deployment models, underlying technologies, vertical compliance requirements, and solution architectures. Each segmentation dimension carries distinct margin profiles and vendor competitive dynamics that shape enterprise buying behavior.
Deployment:
Upgrade cycles in this category accelerate as organizations exit capital-intensive hardware ownership and adopt consumption-based operational models.
- On-Premises:Traditional appliance-based backup infrastructure retains dominance in regulated verticals requiring air-gapped retention. Financial services operators in Frankfurt and Singapore maintain substantial on-site capacity to satisfy cyber insurance underwriters demanding demonstrated recovery point objectives under four hours.
- Cloud-Based:Fully managed backup-as-a-service eliminates data center footprint while introducing egress cost volatility. Healthcare systems across the United States migrate here to offload HIPAA security rule compliance documentation to specialized operators.
- Hybrid:Tiered architecture placing active backups locally with long-term retention in object storage. German automotive manufacturers favor this model to balance GDPR Article 44 residency requirements against cloud elasticity.
- Managed Services:Third-party operators assume full operational responsibility including disaster recovery orchestration. National MSSPs in the United Kingdom bundle these offerings with cyber insurance policies, concentrating buyer power among a handful of specialized providers.
On-Premises sits at the top of the volume ranking, with Cloud-Based climbing the fastest.
Technology:
Technology selection correlates directly with recovery point objective requirements and storage efficiency targets across enterprise scale tiers.
- DPM:Continuous data protection architectures capture every data change in real-time, eliminating scheduled backup windows. Financial services operators deploy DPM to achieve near-zero recovery point objectives demanded by ransomware recovery playbooks.
- Virtualization:Agentless backup of VMware and Hyper-V environments dominates enterprise data center footprints. This technology captures the densest margin pool through integration with existing infrastructure management tools.
- Snapshot:Point-in-time copies leveraging storage array native capabilities for rapid recovery. Manufacturing facilities in India utilize snapshot-based protection for edge computing nodes processing telemetry without cross-border data movement.
- Deduplication:Pattern elimination algorithms reducing storage overhead per protected terabyte. Deduplication commands premium pricing in multi-petabyte environments where capacity efficiency determines total cost of ownership.
Virtualization holds the largest installed base, with DPM gaining share fastest among ransomware-conscious buyers.
End User:
Vertical-specific compliance mandates reshape procurement priorities and certification requirements across buyer categories.
- Telecommunications:Network operators require geographically distributed backup to ensure service continuity across infrastructure nodes. This vertical concentrates demand in India where MeitY data localization directives drive indigenous infrastructure buildout.
- Finance:Banks and insurers face the most stringent audit frameworks including SEC cybersecurity disclosure rules and GDPR training-data documentation. Immutable snapshot solutions have become board-level procurement priorities here.
- Healthcare:HIPAA security rule enforcement elevates backup auditability to operational imperatives. FDA guidelines on electronic records integrity further constrain acceptable recovery architectures.
- Government:Sovereign cloud mandates and classified data handling procedures favor domestic vendors with security clearances. Procurement cycles extend six to nine months for third-party validation against NIST standards.
Finance commands the highest average contract value, with Government expanding most quickly through national cloud infrastructure programs.
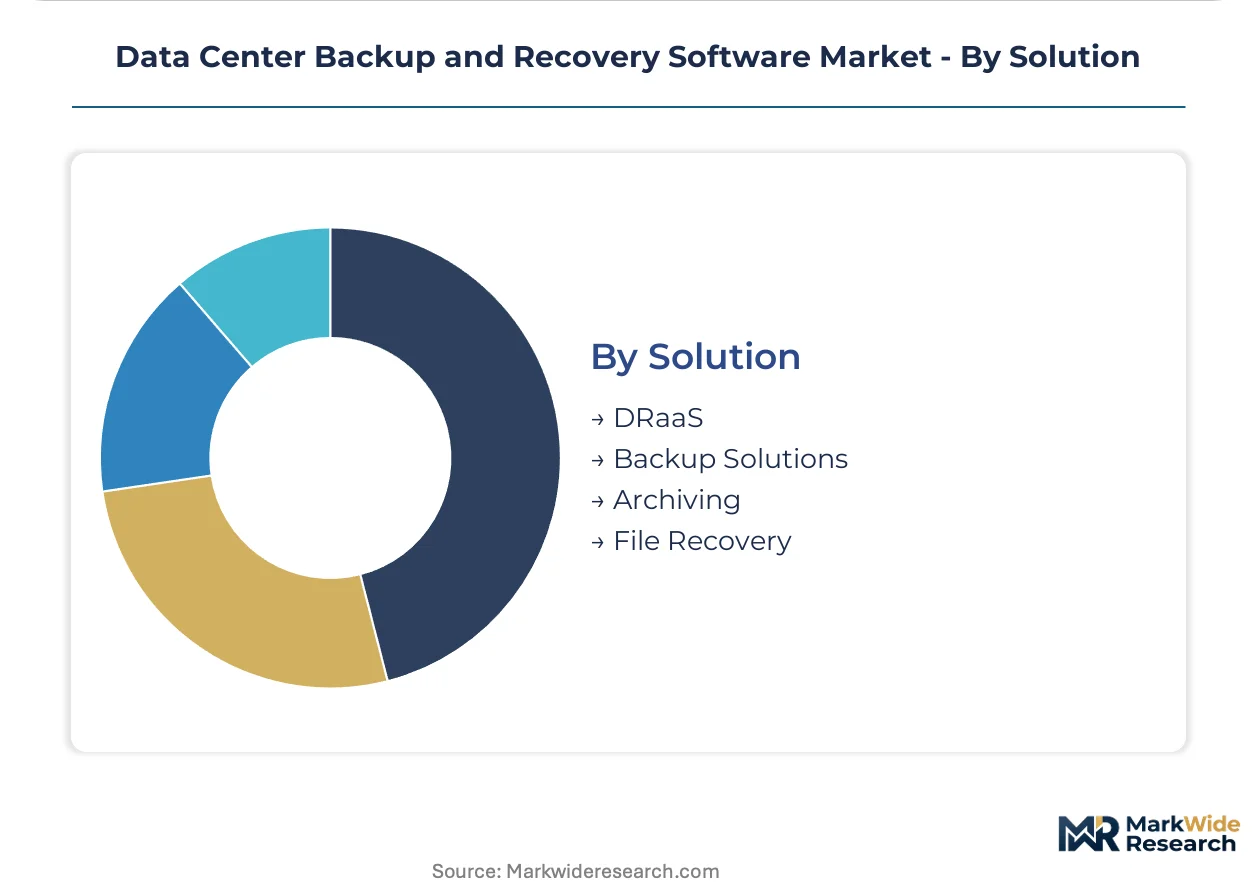
Solution:
Solution architecture determines whether enterprises retain operational risk or transfer it to specialized service providers.
- DRaaS:Service-level guarantees replace in-house disaster recovery operations with contracted recovery time objectives. This solution matures rapidly as managed service providers assume infrastructure ownership.
- Backup Solutions:Core data protection platforms encompassing policy management, scheduling, and restoration workflows. Backup Solutions constitute the foundational revenue layer across all vendor portfolios.
- Archiving:Long-term retention for regulatory compliance and legal discovery with immutable WORM storage. Archiving growth accelerates under EU AI Act training-data provenance requirements.
- File Recovery:Granular restore capabilities for individual documents and objects without full system recovery. File Recovery sees concentrated demand in legal and professional services verticals.
Backup Solutions anchors current revenue, with DRaaS showing the steepest expansion trajectory as operational risk transfers to service providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting backup infrastructure investment toward jurisdictions with clearer data sovereignty frameworks. Enterprises now site recovery operations where compliance costs are predictable rather than minimal.
United States
SEC cybersecurity disclosure rules and HIPAA enforcement are compressing procurement cycles for immutable storage solutions. Financial services operators in New York and healthcare systems in Boston are expanding air-gapped backup capacity to satisfy cyber insurance underwriters. The San Francisco Bay Area concentrates cloud-native architecture talent, inflating implementation costs for enterprises outside this cluster.
Germany
GDPR Article 44 cross-border transfer restrictions and the EU AI Act training-data documentation requirements are mandating geographic segmentation of recovery infrastructure. Automotive manufacturers in Stuttgart and pharmaceutical groups in Frankfurt are establishing dedicated in-country recovery sites rather than relying on pan-European cloud zones. The country's national data protection regulator enforces strict audit trail requirements for backup chains.
India
MeitY data localization directives are driving demand for indigenous backup infrastructure as global hyperscalers establish Mumbai and Hyderabad regions. Telecommunications operators and manufacturing facilities require localized backup nodes to process telemetry without cross-border data movement. Bangalore concentrates specialized engineering talent for cloud-native backup architectures.
United Kingdom
National MSSPs are bundling backup operations with cyber insurance policies, transferring operational risk to specialized operators. This concentration concentrates buyer power among three to four national providers. London-based financial services firms maintain substantial on-site capacity to satisfy recovery point objectives under four hours.
Singapore
Financial services operators deploy AI-powered anomaly detection embedded in backup streams to flag encryption events before propagation across secondary storage tiers. The city-state's position as a regional data hub attracts enterprises seeking jurisdictional clarity for Asia-Pacific recovery operations. Maritime and logistics facilities require edge computing backup nodes for localized telemetry processing.
Data Center Backup and Recovery Software Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cloud-native specialization and immutable storage certification. The vendor base stratifies across three maturity tiers: legacy platform holders with deep on-premises heritage, cloud-native challengers with ransomware recovery focus, and managed service providers bundling operational risk transfer. Strategic moves center on hybrid deployment certification and jurisdiction-specific audit framework compliance to enter national procurement pipelines.
Within the cloud-native tier, Rubrik and Druva exemplify the shift toward immutable snapshots for ransomware recovery, while Commvault anchors the hybrid-deployment segment where data gravity still favors local retention. These three occupy positions spanning the competitive spectrum from pure-cloud to on-premises heritage, representing how vendor archetypes map to enterprise architectural preferences. Each sits within a distinct competitive space: Rubrik and Druva exemplify the emerging cloud-native standard, while Commvault represents the established hybrid-transition play.
| Leading Market Players |
|---|
| Commvault |
| Druva |
| Veeam |
| Dell Technologies |
| Veritas Technologies |
| Rubrik |
| Acronis |
| Arcserve |
| Cohesity |
| Others |
Cost & Logistics Intelligence
National MSSPs in the United Kingdom and United States bundle backup operations with cyber insurance policies, concentrating buyer power among three to four specialized providers and compressing margins for standalone software vendors lacking service delivery capabilities. This procurement concentration forces pricing discipline across deployment tiers while rewarding vendors with certified compliance frameworks.
Pricing Analysis
Managed service provider margins absorb the steepest compression as hyperscaler storage pricing volatility introduces unpredictable cost spikes when recovering multi-petabyte datasets across regions. Three-tier pricing structure across premium, standard, and economy levels separates immutable-certified platforms from basic backup solutions from legacy tape migration offerings. Price differentiation hinges on ISO 27001 certification tier and after-sales service bundling. Cost compression in the economy tier intensifies because legacy tape infrastructure lock-in delays migration to object-based storage. Healthcare systems exhibit highest price sensitivity due to HIPAA compliance documentation burdens, while financial services operators show lowest sensitivity given SEC cybersecurity disclosure rule enforcement.
Supply Chain Analysis
Cross-border data transfer costs from hyperscaler regions in Mumbai, Hyderabad, Frankfurt, and Singapore inflate total cost of ownership for enterprises operating distributed recovery architectures. Engineering talent concentrates in Silicon Valley and Bangalore, drawing from specialized cloud-native backup architecture skills that inflate implementation costs for enterprises outside these clusters. Raw material dependencies center on semiconductor components for backup appliances, lithium-ion cells for edge computing nodes, and optical media for long-term archival retention. Single-source vulnerability runs through hyperscaler storage API dependencies that lock enterprises into vendor-specific tooling proliferation. Distribution runs through direct enterprise sales for large accounts, value-added resellers for mid-market penetration, and national MSSPs for operational risk transfer bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center backup and recovery software functions as a stable compounder anchored by immutable storage mandates that elevate backup auditability to board-level procurement priorities across regulated verticals. Regulatory enforcement creates durable demand floors regardless of macroeconomic cycles.
For Market Incumbents: Extend hybrid deployment certification coverage to capture data gravity preferences in Frankfurt, Singapore, and Mumbai where local retention requirements persist. Deepen vertical integration into immutable storage hardware partnerships to defend margin position against cloud-native challengers. Invest in NIST and ISO 27001 validation pipelines to compress six-to-nine-month sales cycles in government and finance verticals.
For New Entrants and Emerging Players: National MSSPs represent the most accessible channel for operational risk transfer bundling without competing against established vendor direct sales forces. Target India's domestic cloud buildout under MeitY localization directives where indigenous infrastructure demand outpaces certified supplier availability. Pursue Kubernetes persistent volume backup integration with DevOps pipelines as the primary go-to-market angle for software-driven enterprises.
For Investors and Strategic Acquirers: Hyperscalers expanding sovereign cloud regions are the most active acquirer in this space, seeking compliance-certified platforms to anchor national infrastructure bids. Five-to-ten-year viability favors vendors with jurisdiction-specific audit framework pre-certification rather than pure technology plays. Monitor SEC cybersecurity disclosure rule expansion to additional registrant categories as the inflection signal for accelerated procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Immutable Storage Certification | ISO 27001 validation compresses sales cycles in SEC-regulated financial services procurement pipelines. |
| Hybrid Deployment Architecture | Tiered local-cloud retention balances GDPR Article 44 residency requirements against cloud elasticity for German automotive manufacturers. |
| AI-Powered Anomaly Detection | Machine learning inference engines embedded in backup streams compress mean-time-to-detection from hours to minutes for Singapore financial operators. |
| MSSP Partnership Expansion | Cyber insurance policy bundling concentrates buyer power among three to four national UK providers. |
| Container-Native Protection | Kubernetes persistent volume backup integration opens new seats in software-driven enterprises deploying DevOps pipelines. |
Research Approach
Bottom-up enterprise IT procurement modeling reconciled against top-down hyperscaler infrastructure tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners combine with secondary validation against SEC cybersecurity disclosure filings, HIPAA enforcement actions, EU AI Act documentation requirements, and hyperscaler capex disclosures. Data triangulation across deployment model adoption rates, vertical compliance spending patterns, and regional infrastructure buildout timelines ensures segmentation integrity.
Input-output matrices map software licensing revenue to underlying infrastructure investment across on-premises, cloud-based, hybrid, and managed services deployment categories. Segmentation dimensions modeled include deployment architecture, recovery point objective tier, vertical compliance requirement, and regional data sovereignty framework. CAGRs derive from regression analysis of historical procurement cycles against regulatory enforcement intensity. Forecast inputs incorporate edge computing node expansion telemetry and ransomware recovery playbook adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hyperscaler storage pricing volatility and immutable certification timeline delays. Forecasts reflect documented assumptions about regulatory enforcement continuity and talent cluster concentration persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Ecommerce Software and Platform Market
Software & Services
Technology CAD Software Market
Software & Services
Inventory Management Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Attendance Tracking Software Market
Software & Services
Cloud Communication Platform Software Market
Software & Services
Global Archiving Software Market
Software & Services
Global Localization Software Market
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Session Support Software Market
Software & Services
Global Online Expense Management Software Market
Software & Services
Global Process Mining Software Market
Software & Services
Content Distribution Software Market
Software & Services
App Development Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Global Data Warehouse Software Market