
 Global Headless CMS Software Market | 2026-2036
Global Headless CMS Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Headless CMS Software Market Foresight
Subscription-based API access tiers is pivoting how vendors monetize headless CMS platforms. Contentful leverages multi-region infrastructure to anchor enterprise accounts across North America and Europe. Sanity sustains developer-community loyalty through real-time collaboration tools and customizable content schemas. Strapi competes on open-source extensibility, allowing self-hosted deployments that reduce long-term licensing exposure for mid-market buyers.
Headless CMS software decouples content repositories from presentation layers through RESTful or GraphQL APIs, enabling content reuse across websites, mobile applications, IoT displays, and emerging touchpoints without template lock-in. Cloud deployment dominates solution type demand as organizations prioritize elastic scaling and reduced infrastructure overhead over on-premises control. Omnichannel publishing leads use case adoption, while e-commerce integration commands premium pricing due to real-time inventory synchronization requirements and conversion-optimized content delivery demands.
The EU GDPR and AI Act shape data residency requirements and automated content governance, compelling vendors to offer regional instance isolation and audit trails. The US FCC and state-level privacy frameworks in California and Virginia impose parallel compliance obligations for cross-border content delivery networks. Enterprise procurement teams must evaluate API rate-limit architectures and vendor certification against ISO 27001 and SOC 2 Type II before committing to multi-year platform contracts.
Market Dynamics
API-first content architectures are forcing enterprise procurement teams to reevaluate vendor lock-in risks against composable stack flexibility. The tension between sovereign data mandates and cloud-native delivery models is restructuring how platforms negotiate regional hosting commitments.
Growth Catalysts
- EU AI Act compliance mandates:Automated content governance requirements are accelerating procurement of headless CMS platforms with built-in audit trails and regional instance isolation capabilities.
- Automotive digital experience modernization:German industrial manufacturers are deploying decoupled content repositories to synchronize technical documentation across dealer networks and connected vehicle interfaces.
- Real-time inventory APIs:E-commerce operators are adopting headless architectures to enable sub-second product availability updates across mobile applications, in-store displays, and third-party marketplaces.
Market Restraints
- GraphQL expertise scarcity:The shallow talent pool for API schema design is extending implementation timelines and inflating professional services costs for mid-market buyers.
- Multi-cloud egress fees:Cross-border content delivery networks face unpredictable bandwidth pricing from hyperscale providers, complicating total cost of ownership forecasts.
- Legacy CMS sunk costs:Enterprises with extensive template libraries and editorial workflows resist migration despite technical debt accumulation.
Strategic Opportunities
- Edge computing convergence:Pairing headless CMS with serverless functions at CDN nodes enables sub-50-millisecond personalization without origin round-trips.
- India PLI scheme alignment:Domestic software vendors can capture incentives by building sovereign-hosted alternatives for financial services and public sector clients.
- IoT display proliferation:Smart signage, wearable interfaces, and automotive head units represent content surfaces lacking established CMS coverage.
Industry Challenges
- ISO 27001 certification timelines:Vendor security audits stretch 8-14 months, delaying enterprise contract closures and consuming scarce compliance resources.
- Editor-experience parity gaps:Marketing teams accustomed to WYSIWYG page builders resist adoption when real-time previews require developer intervention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Headless CMS Software Market |
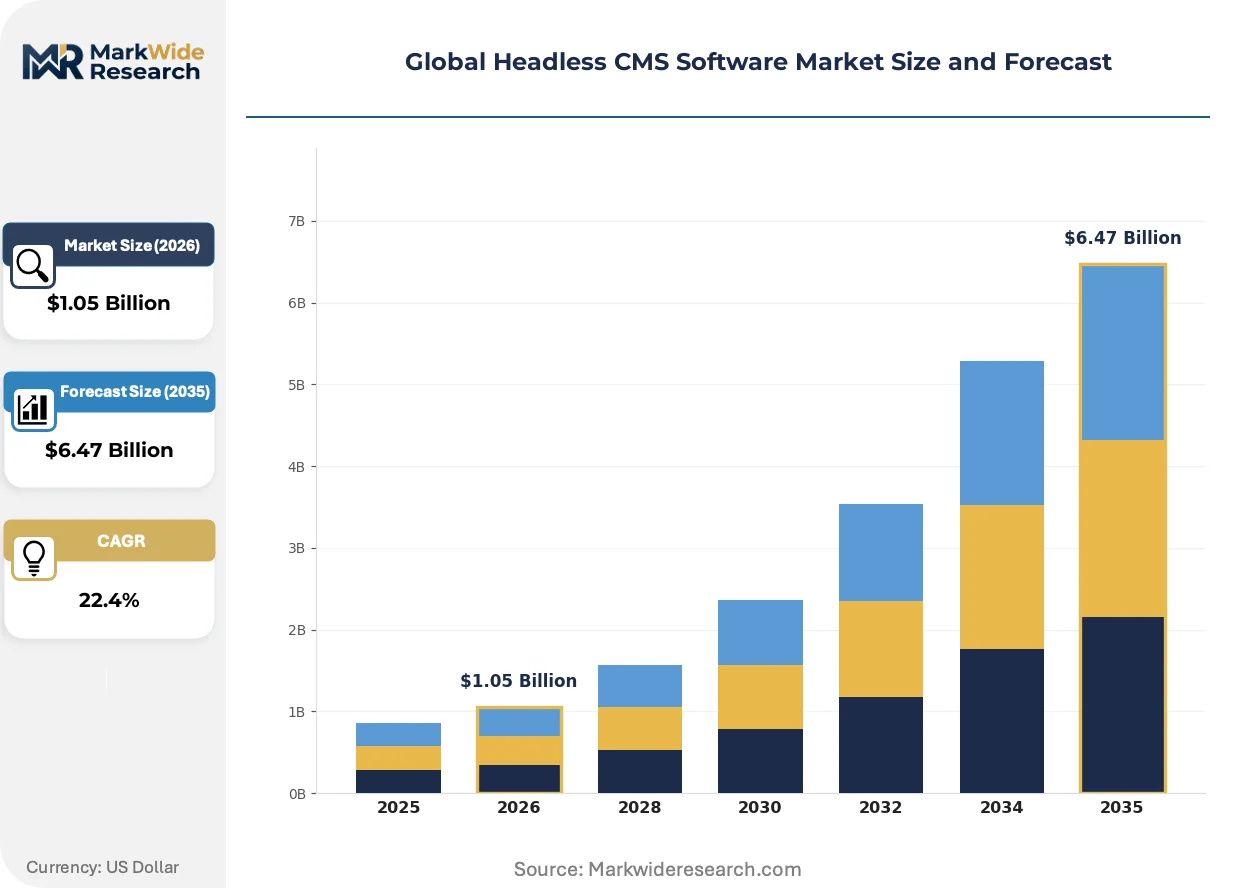
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $6.47 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premises, Hybrid, Private Cloud, Public Cloud Solution Type: Content Delivery, Content Management, Digital Experience, API Management, Workflow Automation Use Case: Omnichannel Publishing, E-commerce Integration, Mobile Applications, Personalized Marketing, Enterprise Portals End User Industry: Media & Entertainment, Education, Government, Financial Services, Telecommunications |
| Companies Covered | Storyblok, CrafterCMS, Contentful, Adobe Experience Manager, Optimizely, Sanity, Kontent.ai, Contentstack, Strapi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Headless CMS Software Market Shifts & Advancements
Composable architecture principles are dissolving monolithic platform boundaries. Vendors now compete on interoperability depth rather than feature breadth.
GraphQL federation is consolidating multiple content sources into unified query layers. Retail conglomerates with acquired brand portfolios are adopting this approach to merge product catalogs without forced migration. The technology is consolidating vendor positioning around schema stewardship rather than storage ownership.
GDPR Article 44 transfer mechanism restrictions are compelling platforms to deploy EU-isolated infrastructure stacks. SaaS providers are responding with Germany-specific data residency pods and contractual guarantees against US jurisdiction exposure. Financial services clients in Frankfurt and Amsterdam are demanding these provisions as non-negotiable procurement criteria.
Enterprise buyers are compressing vendor evaluation cycles through standardized API benchmarking suites. Procurement teams now require proof of 99.99% availability SLAs and sub-100-millisecond p95 response times before pilot authorization. This pattern is most pronounced among UK and US media publishers managing traffic spikes during live events.
Global Headless CMS Software Market Segmentation
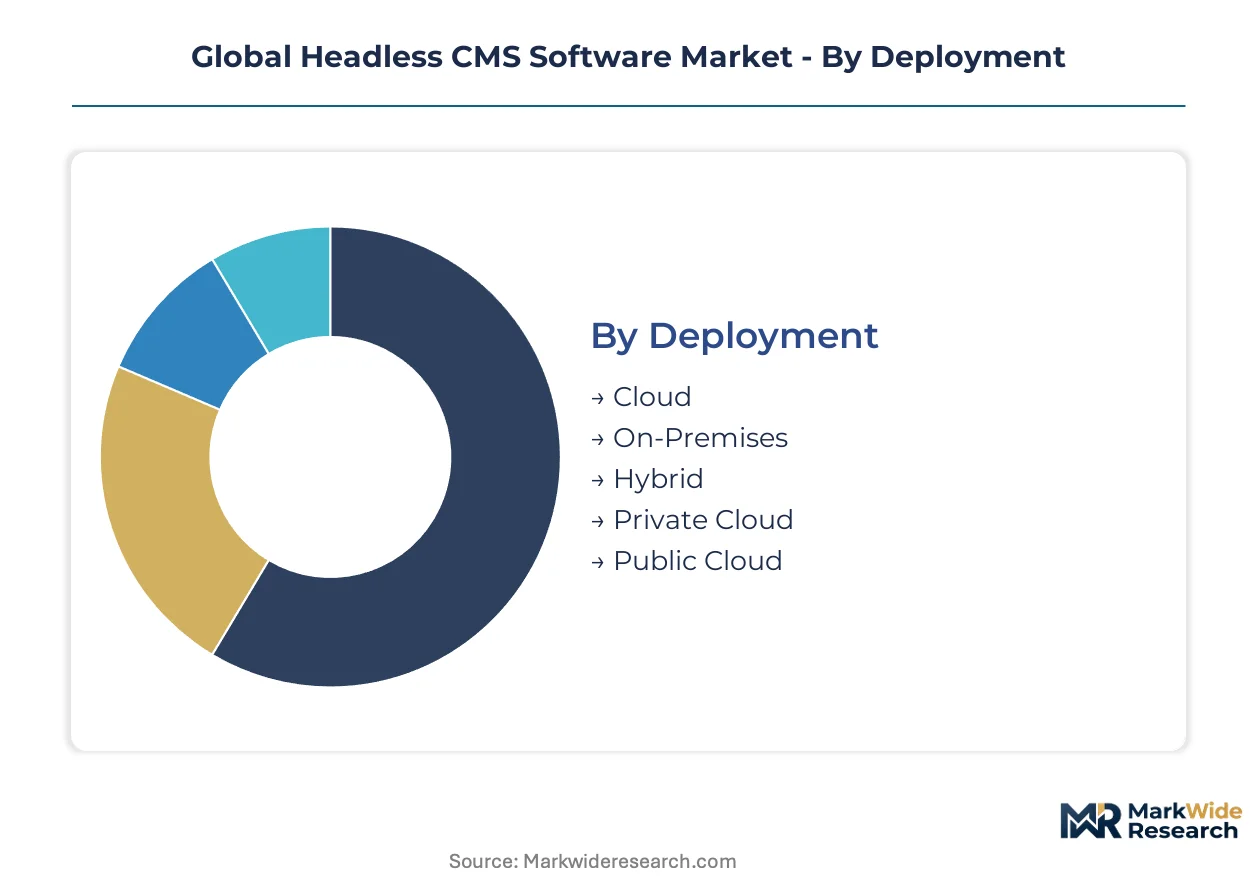
Headless CMS procurement decisions hinge on deployment sovereignty, API architecture depth, and content velocity requirements across digital touchpoints. Segmentation reveals how vendor capabilities align with organizational risk tolerance and technical maturity.
Deployment:
Cloud-native infrastructure configurations determine data residency compliance and operational agility trade-offs.
- Cloud:Elastic compute scaling eliminates capacity planning overhead for traffic-spike scenarios. Media publishers in the United Kingdom demand 99.99% availability SLAs with sub-100-millisecond response times for live event coverage.
- On-Premises:Complete hardware control satisfies air-gapped security mandates and legacy integration requirements. German automotive manufacturers favor this model to synchronize technical documentation across dealer networks without external data exposure.
- Hybrid:Workload portability between private infrastructure and public cloud balances compliance flexibility with burst capacity.
- Private Cloud:Dedicated tenant isolation addresses financial services requirements in Frankfurt and Amsterdam under GDPR Article 44 restrictions.
- Public Cloud:Shared infrastructure economics appeal to mid-market buyers prioritizing speed-to-deployment over customization depth.
Cloud leads on scale; hybrid architectures gain share fastest as sovereignty mandates intensify.
Solution Type:
Functional module selection reflects organizational maturity in API-first content operations.
- Content Delivery:CDN-optimized distribution layers enable sub-50-millisecond personalization at edge nodes. Retail conglomerates deploy this for real-time inventory synchronization across mobile applications and in-store displays.
- Content Management:Repository governance tools with customizable schemas sustain developer-community adoption. Marketing teams require WYSIWYG parity to overcome editorial workflow resistance.
- Digital Experience:Composable orchestration platforms merge content, commerce, and customer data layers.
- API Management:Rate-limit architectures and GraphQL federation capabilities consolidate multi-source content streams.
- Workflow Automation:Audit-trail generation supports EU AI Act compliance for automated content governance.
Content Delivery dominates revenue contribution; Digital Experience shows steepest expansion trajectory as enterprises consolidate point solutions.
Use Case:
Application patterns reveal where decoupled architectures deliver measurable conversion or efficiency gains.
- Omnichannel Publishing:Single-source content reuse across websites, IoT displays, and emerging touchpoints eliminates template lock-in. Media organizations in the United States prioritize this for brand consistency at volume.
- E-commerce Integration:Real-time product availability APIs command premium pricing due to conversion-optimized delivery requirements. Operators demand sub-second synchronization across third-party marketplaces.
- Mobile Applications:Native SDK support with offline content caching improves engagement metrics in bandwidth-constrained environments.
- Personalized Marketing:Behavioral data integration with serverless edge functions enables contextual content assembly.
- Enterprise Portals:Role-based access control and multi-tenant isolation serve internal knowledge management at scale.
Omnichannel Publishing anchors installed base; E-commerce Integration captures highest per-seat pricing.
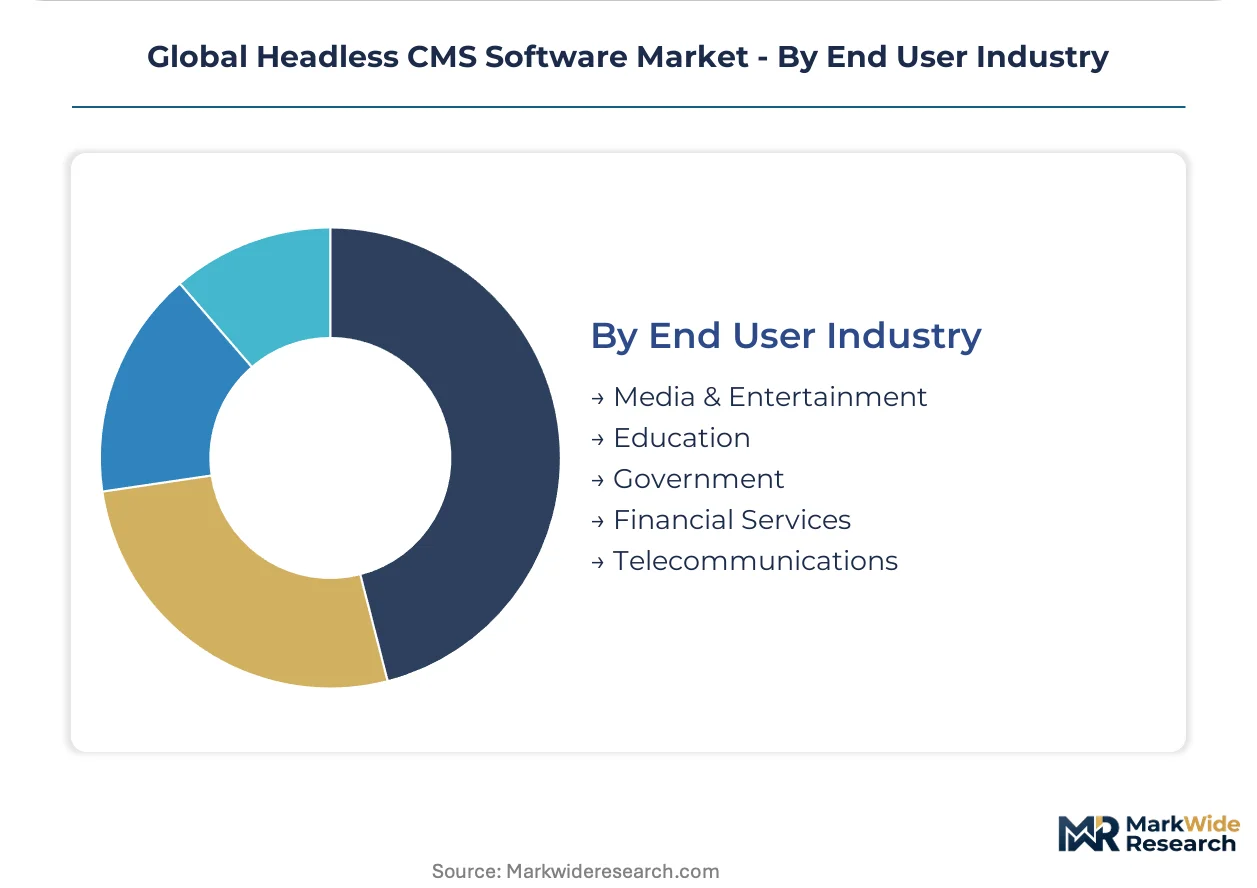
End User Industry:
Sector-specific compliance regimes and content velocity requirements shape procurement criteria.
- Media & Entertainment:Traffic spike tolerance and editorial workflow velocity determine platform selection. Live event publishers benchmark API response consistency under load.
- Education:Multi-campus content governance and accessibility compliance drive LMS integration priorities.
- Government:Sovereign hosting mandates and Section 508 accessibility requirements constrain vendor shortlists.
- Financial Services:ISO 27001 certification and audit trail depth are non-negotiable for Frankfurt and Amsterdam procurement teams.
- Telecommunications:Self-service portal scalability and real-time tariff publishing support subscriber retention metrics.
Media & Entertainment generates highest transaction volume; Financial Services imposes strictest certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive manufacturers deploy decoupled content architectures faster than their Japanese counterparts, while US media publishers demand stricter API performance benchmarks than British operators. Sovereign data mandates and sector-specific compliance regimes are reshaping procurement patterns across national boundaries.
United States
Media conglomerates and e-commerce operators drive API-first adoption, with live-event publishers requiring sub-100-millisecond response times under traffic spikes. The FCC and state-level privacy frameworks in California and Virginia impose cross-border content delivery obligations. New York and Los Angeles media clusters anchor enterprise procurement decisions for omnichannel publishing stacks.
Germany
Automotive and industrial manufacturers modernize digital experience infrastructure to synchronize technical documentation across dealer networks. The EU AI Act and GDPR Article 44 transfer restrictions mandate regional instance isolation and audit trail capabilities. Frankfurt financial services clients demand Germany-specific data residency pods as non-negotiable procurement criteria.
United Kingdom
Media publishers benchmark API availability SLAs at 99.99% for live event coverage, compressing vendor evaluation cycles through standardized testing suites. UK GDPR alignment with EU data protection standards maintains parallel compliance obligations for cross-border delivery networks. London anchors demand for elastic scaling capabilities among broadcast and streaming operators.
India
Domestic software vendors capture PLI scheme incentives by building sovereign-hosted alternatives for financial services and public sector clients. The RBI and SEBI impose data localization requirements on banking and securities content management. Bangalore and Hyderabad technology clusters incubate API-first development talent for regional platform deployment.
Japan
Enterprise manufacturers adopt headless architectures for IoT display integration across connected vehicle and industrial equipment interfaces. METI industrial digitization programs accelerate modernization of legacy content management systems. Tokyo and Osaka metropolitan areas concentrate demand for real-time collaboration tools and customizable content schemas.
Global Headless CMS Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with open-source extensibility competing against proprietary cloud-native delivery models. The vendor base organizes around three strategic archetypes: API-first SaaS platforms with multi-region infrastructure, developer-centric tools emphasizing real-time collaboration, and self-hosted solutions reducing long-term licensing exposure. Consolidation pressure intensifies through M&A activity targeting schema federation capabilities and geographic expansion into sovereign hosting markets.
Within the cloud-native tier, Contentful and Contentstack exemplify multi-region infrastructure deployment for enterprise accounts across North America and Europe. Sanity occupies a position emphasizing developer-community engagement through customizable schemas, while Strapi represents the open-source archetype enabling self-hosted deployments. These three anchors illustrate how competitive positioning diverges between proprietary SaaS economics and extensible community-driven models.
| Leading Market Players |
|---|
| Storyblok |
| CrafterCMS |
| Contentful |
| Adobe Experience Manager |
| Optimizely |
| Sanity |
| Kontent.ai |
| Contentstack |
| Strapi |
| Others |
Supply & Pricing Matrix
API performance tier divergence between sub-100-millisecond enterprise SLAs and commodity self-hosted deployments manifests in both subscription pricing and infrastructure sourcing strategies. Premium vendors anchor multi-region cloud instances in Frankfurt and Amsterdam to satisfy GDPR Article 44 mandates, while open-source alternatives reduce licensing exposure through on-premises control.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for sovereign-hosted instances as vendors deploy EU-isolated infrastructure stacks. Pricing stratifies across enterprise API tiers with guaranteed availability, mid-market SaaS bundles, and self-hosted open-source distributions with support subscriptions. Price differentiation hinges on ISO 27001 certification status and multi-region redundancy depth. Pricing pressure stems from hyperscale egress fee unpredictability complicating total cost of ownership forecasts. Mid-market buyers in India exhibit highest price sensitivity, while Frankfurt financial services clients accept premium tiers for data residency guarantees.
Supply Chain Analysis
GraphQL engineering talent scarcity in Bangalore and Hyderabad constrains implementation velocity for regional platform deployments. Supply concentration centers on cloud infrastructure provisioning from Germany, the United States, and India, with edge computing nodes expanding into Japan and the United Kingdom. Raw material dependencies include hyperscale compute capacity, CDN bandwidth reservations, and API gateway software licenses. Supply chain risk manifests in single-source vulnerability for specialized schema federation tooling. Distribution runs through direct enterprise sales teams, channel partners, and open-source community ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in API management tier upgrades and sovereign hosting premiumization, with cost compression in open-source support models enabling volume penetration.
For Market Incumbents: Cement multi-region infrastructure moats through Germany-specific data residency pods and ISO 27001 certification acceleration. Threat substitution from composable DXP platforms demands deeper GraphQL federation capabilities. Vertical integration into edge computing partnerships secures sub-50-millisecond personalization performance. For New Entrants and Emerging Players: Begin with IoT display content management white space in Japanese automotive and industrial equipment interfaces. India's PLI scheme alignment for sovereign-hosted financial services alternatives offers the most penetrable entry vector. Developer-community cultivation through real-time collaboration tooling provides differentiated go-to-market positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where schema federation capabilities concentrate among mid-tier vendors lacking geographic expansion resources. Long-term viability favors platforms with demonstrated EU AI Act compliance architecture and audit trail depth. Acquisition target archetypes include specialist API management layers and Germany-focused hosting providers. Watch for inflection where enterprise procurement teams mandate 99.99% availability SLAs as table stakes rather than premium differentiators.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | GraphQL federation merges acquired brand catalogs without forced migration disruption. |
| Geographic Expansion | Germany-specific data residency pods satisfy Frankfurt financial services procurement mandates. |
| Strategic Partnership | Edge computing alliances with CDN providers enable sub-50-millisecond personalization delivery. |
| Acquisition of Specialist Firm | Schema stewardship capabilities consolidate vendor positioning beyond storage ownership. |
| Product Launch | Real-time collaboration tools sustain developer-community loyalty against proprietary alternatives. |
Research Methodology
Bottom-up deployment modeling reconciled against top-down vendor infrastructure tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across Germany, the United States, the United Kingdom, India, and Japan inform demand-side validation. Secondary sources include SEC filings, hyperscaler capex disclosures, EU regulatory filings under GDPR and the AI Act, and API benchmarking suite results. Triangulation across these inputs ensures segmentation alignment between reported vendor capabilities and enterprise procurement criteria.
Historical trendline analysis of API-first adoption velocity across media, automotive, financial services, and e-commerce verticals establishes baseline growth patterns. Segmentation dimensions modeled span deployment sovereignty, solution type, use case intensity, and end-user industry compliance requirements. CAGRs derive from elasticity-adjusted projections of API call volume expansion and seat-based subscription conversion. Industry-specific forecast inputs include EU AI Act implementation timelines and German automotive digital experience modernization capex cycles.
Several conditions sit outside the modeled scope, including unforeseen regulatory reinterpretations of GDPR Article 44 transfer mechanisms and abrupt hyperscale pricing restructuring. Forecasts reflect assumptions regarding sustained enterprise preference for cloud-native elasticity over on-premises control. Material deviation in sovereign data mandate enforcement intensity or GraphQL talent pool expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Collaboration Software Market
Software & Services
Service Scheduling Software Market
Software & Services
AI Powered Software Testing Tool Market
Software & Services
RFP Software Market
Software & Services
Cricket Analysis Software Market
Software & Services
Patent Management Software Market
Software & Services
Poland IT Software and Service Market
Software & Services
Expense Management Software Market
Software & Services
Global Pension Administration Software Market
Software & Services
Jobsite Management Software Market
Software & Services
Global Desktop As a Service Market
Software & Services
Predictive Dialer Software Market
Software & Services
Retail Space Planning Software Market
Software & Services
Software Licensing Market
Software & Services
United Kingdom IT Services Market
Software & Services
Virtual Fitting Software Market