
 Global Auction Software Market | 2026-2036
Global Auction Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Auction Software Market Foresight
Online auction marketplaces is reconfiguring how sellers reach dispersed buyer pools across time zones and device types. RainWorx Software leverages its platform architecture to anchor multi-currency transaction support for international consignments. Handbid specializes in mobile-first bidding interfaces that sustain engagement during live charity galas. Bidlogix competes through white-label deployment flexibility that extends brand control to enterprise auctioneers.
Auction software encompasses cloud-native and on-premise applications that manage lot cataloging, real-time bid processing, payment settlement, and post-auction analytics through encrypted socket connections and automated reserve-price triggers. Its primary commercial purpose is to replace physical bidding floors with scalable digital venues that reduce per-transaction overhead. Cloud-based deployment leads solution distribution because subscription models lower capital barriers for small auction houses entering online channels. Reverse auction functionality represents the fastest-growing solution type as procurement teams at government entities adopt competitive sourcing protocols. Commission-based pricing still occupies the largest margin pool among revenue models, though freemium tiers are gaining traction with non-profit organizations testing digital fundraising.
FDA guidelines on financial data handling intersect with auction software when pharmaceutical surplus equipment enters secondary markets, while GDPR in Europe mandates consent frameworks for bidder data retention across cross-border platforms. The EU AI Act introduces algorithmic transparency requirements for automated reserve pricing and bid-ranking systems that European auction houses must integrate. Stakeholders should monitor how divergent data-localization standards between jurisdictions reshape platform architecture decisions and compliance costs.
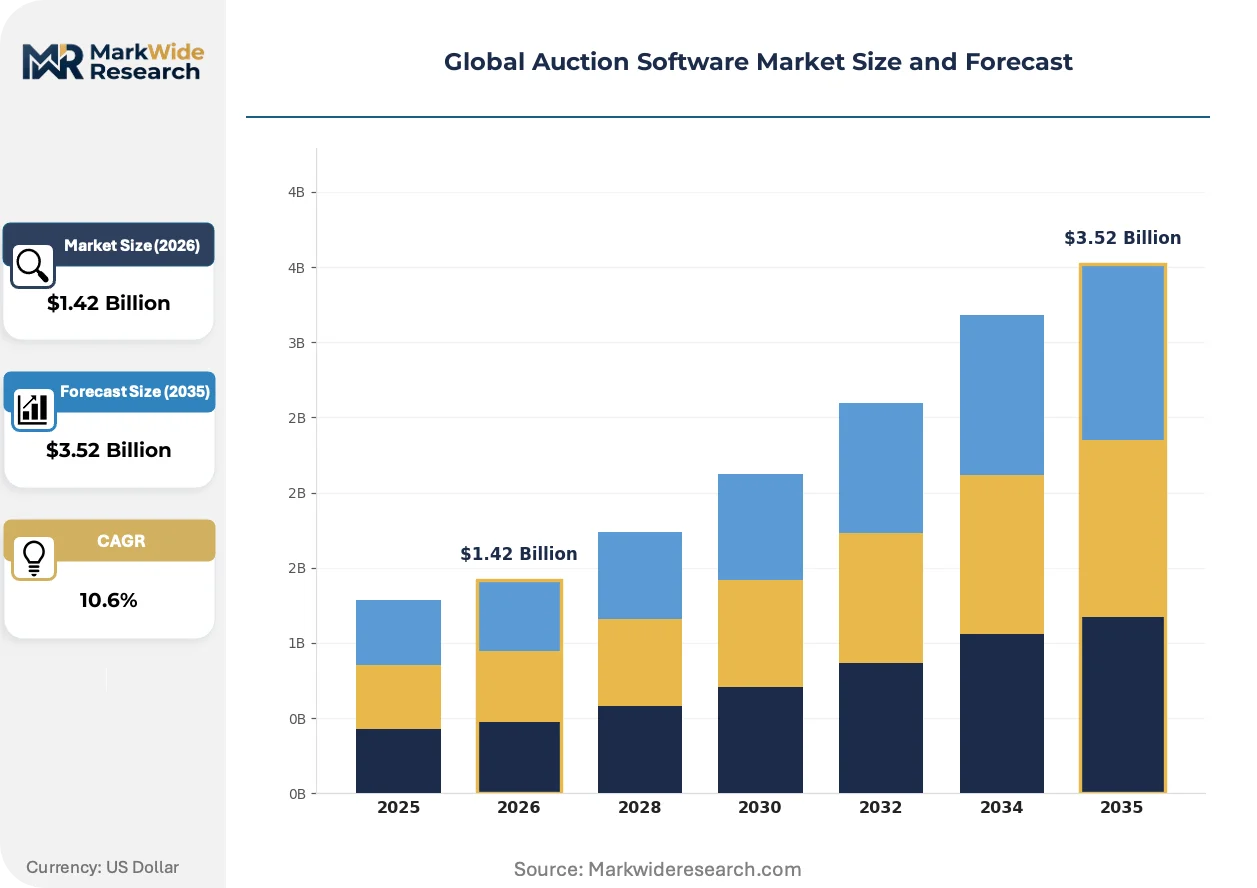
Market Dynamics
Cloud migration is compressing deployment timelines for auction software vendors while API-first architectures unlock modular integration with legacy ERP systems at regional auction houses.
Growth Catalysts
- Government procurement mandates:Competitive bidding protocols at US federal agencies and EU public-sector bodies are institutionalizing reverse auction workflows for capital equipment sourcing.
- Mobile penetration:Smartphone-first bidding interfaces are capturing consignor attention in charity gala segments where real-time engagement drives donation velocity.
- GDPR-compliant data frameworks:Standardized consent architectures are reducing cross-border platform launch friction for auctioneers operating across Germany, France, and Netherlands markets.
Market Restraints
- Payment processor concentration:Reliance on Stripe, Adyen, and regional acquirers creates single-point vulnerability for multi-currency settlement at international consignment platforms.
- EU AI Act compliance overhead:Algorithmic transparency mandates for automated reserve pricing are forcing architecture redesigns that extend deployment cycles by 8-14 months.
- Cyber insurance cost escalation:Premium spikes for financial data breach coverage are eroding margins at mid-tier SaaS auction providers serving non-profit segments.
Strategic Opportunities
- India's digitizing agricultural mandis:Government-mandated eNAM platform expansion is creating openings for auction software adapted to commodity spot-trading workflows in wheat and cotton belts.
- Carbon credit spot markets:Voluntary emissions trading registries in Switzerland and Singapore require auction infrastructure for standardized lot clearing.
- Embedded finance convergence:Integration of lending APIs and buyer financing tools is unlocking new revenue streams at industrial equipment resale platforms.
Industry Challenges
- Blockchain engineer scarcity:Provenance verification features for fine art and luxury goods segments require specialized cryptographic talent that commands premium compensation in London and New York hiring markets.
- ISO 27001 certification timelines:Information security management audits are extending vendor onboarding cycles at enterprise auction houses with multi-jurisdiction data residency requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Auction Software Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.52 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based, Mobile Solution Type: Real-Time Bidding, Silent Auction, Reverse Auction, Timed Auction, Dutch Auction End User: Government Entities, Financial Institutions, Non-Profit Organizations, Automotive Dealerships, Art Dealers Pricing Model: Subscription-Based, Commission-Based, One-Time License, Freemium, Pay-Per-Use |
| Companies Covered | bidlogix, AuctionWorx, RainWorx Software, GiveSmart, ClickBid, Handbid, 32auctions, Auction Flex, BiddingOwl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Auction Software Market Shifts & Advancements
Real-time streaming infrastructure and generative cataloging tools are compressing lot-preparation timelines while expanding bidder reach beyond traditional geographic strongholds.
Computer vision for automated condition grading is hybridizing physical inspection workflows with remote consignment acceptance. Industrial equipment auctioneers in Germany and Japan are deploying smartphone-captured imagery to pre-qualify machinery lots without on-site specialist travel. This compression of verification overhead is expanding addressable consignor pools to secondary cities and rural equipment holders.
The EU AI Act's algorithmic transparency requirements are mandating explainability layers for dynamic reserve pricing engines. Auction platforms serving European fine art and wine markets must now document bid-ranking logic for regulatory audit trails. Vendors are responding by partitioning AI-driven pricing modules from core transaction engines to isolate compliance scope.
Subscription pricing for auction SaaS is displacing perpetual license models among mid-market auction houses in the United States and United Kingdom. Monthly fee structures align vendor incentives with client transaction volume success, reducing upfront capital barriers for digitizing family-owned auctioneers. This shift is most visible in estate jewelry and collectibles segments where seasonal volume fluctuation makes fixed-cost licensing uneconomical.
Global Auction Software Market Segmentation
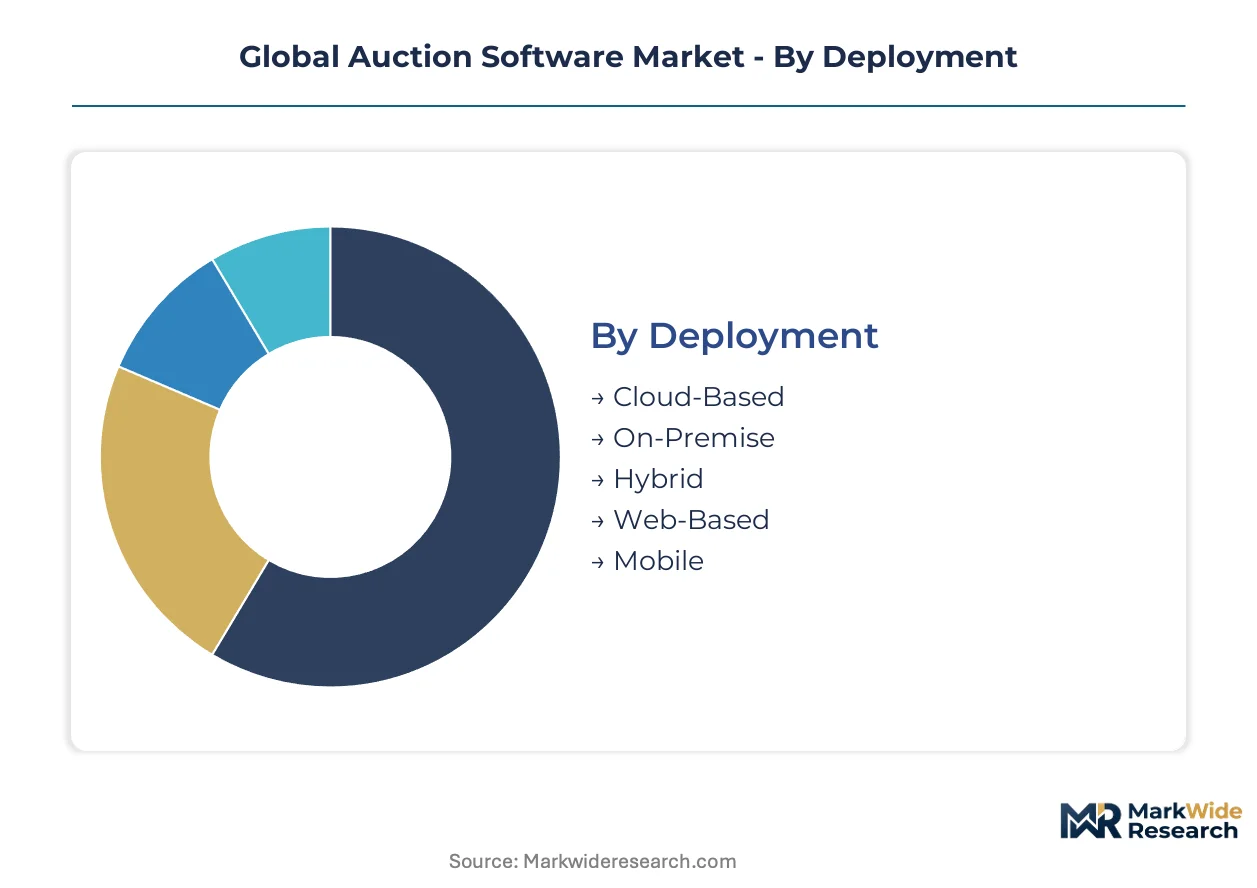
Auction software segmentation reveals how deployment architecture, bidding mechanics, and revenue models align with distinct operational requirements across consignment types. Procurement teams and auctioneers select configurations based on transaction velocity, compliance burdens, and consignor geographic dispersion.
Deployment:
After-sales service intensity varies sharply across deployment modes, with cloud-native platforms demanding continuous uptime guarantees and on-premise installations requiring specialized field engineering capacity.
- Cloud-Based:Multi-tenant SaaS architectures deliver automatic feature updates and elastic scaling for seasonal auction volume spikes. Demand concentrates among mid-tier auction houses in the United States and Germany seeking to avoid data center capital expenditure while meeting GDPR data residency requirements through EU-region hosting.
- On-Premise:Dedicated server installations within client facilities provide air-gapped transaction processing for defense surplus and pharmaceutical equipment auctions subject to ITAR and FDA data handling protocols. Japanese industrial machinery auctioneers favor this mode for legacy ERP integration with METI-standardized procurement systems.
- Hybrid:Split architectures keep sensitive bidder data on local servers while pushing catalog streaming to cloud CDNs, balancing latency performance with compliance control.
- Web-Based:Browser-accessible platforms without native app dependencies reduce friction for occasional bidders in charity fundraising segments.
- Mobile:Native iOS and Android applications with push notification engines capture real-time engagement during live gala events where smartphone penetration exceeds 90% among attendees.
By volume, Cloud-Based deployments lead. By growth pace, Mobile is ahead.
Solution Type:
Cost tier differentiation separates commodity procurement tools from premium consignment platforms serving discretionary asset categories.
- Real-Time Bidding:WebSocket-based auction floors replicate live saleroom dynamics with sub-second bid propagation across global bidder pools. Art dealers in London and New York deploy these engines for evening sales where competitive tension drives hammer prices above estimate ranges.
- Reverse Auction:Competitive sourcing protocols invert price discovery, with suppliers driving bids downward for government contracts. US federal agencies and EU public-sector bodies institutionalized these workflows under competitive bidding mandates, accelerating procurement cycle compression.
- Silent Auction:Sealed-bid mechanisms with fixed closing times suit charity galas where social dynamics discourage overt competition among donors.
- Timed Auction:Extended bidding windows with auto-extension triggers accommodate consignors across time zones without live auctioneer staffing.
- Dutch Auction:Descending-price mechanisms clear perishable inventory in agricultural commodity markets, particularly within India's expanding eNAM platform infrastructure.
By transaction count, Real-Time Bidding dominates. By expansion velocity, Reverse Auction is climbing the fastest.
End User:
Application-specific requirements shape feature prioritization, with regulatory complexity and stakeholder transparency demands varying substantially across verticals.
- Government Entities:Public procurement platforms mandate audit trails, competitive bid documentation, and integration with national e-procurement registries. EU member states layer CSRD sustainability reporting onto supplier evaluation workflows.
- Non-Profit Organizations:Donor management integration and tax-receipt automation drive selection criteria, with mobile-first interfaces capturing gala fundraising momentum.
- Financial Institutions:Collateral liquidation and distressed asset disposal require settlement integration with custodial banking networks and regulatory reporting to SEC and national banking supervisors.
- Automotive Dealerships:Fleet remarketing and trade-in liquidation platforms integrate with DMS systems and vehicle history databases.
- Art Dealers:Provenance documentation, condition reporting tools, and buyer anonymity features align with market customs and cultural property export control compliance.
By installed base, Government Entities lead. By activation rates, Non-Profit Organizations are gaining share fastest.
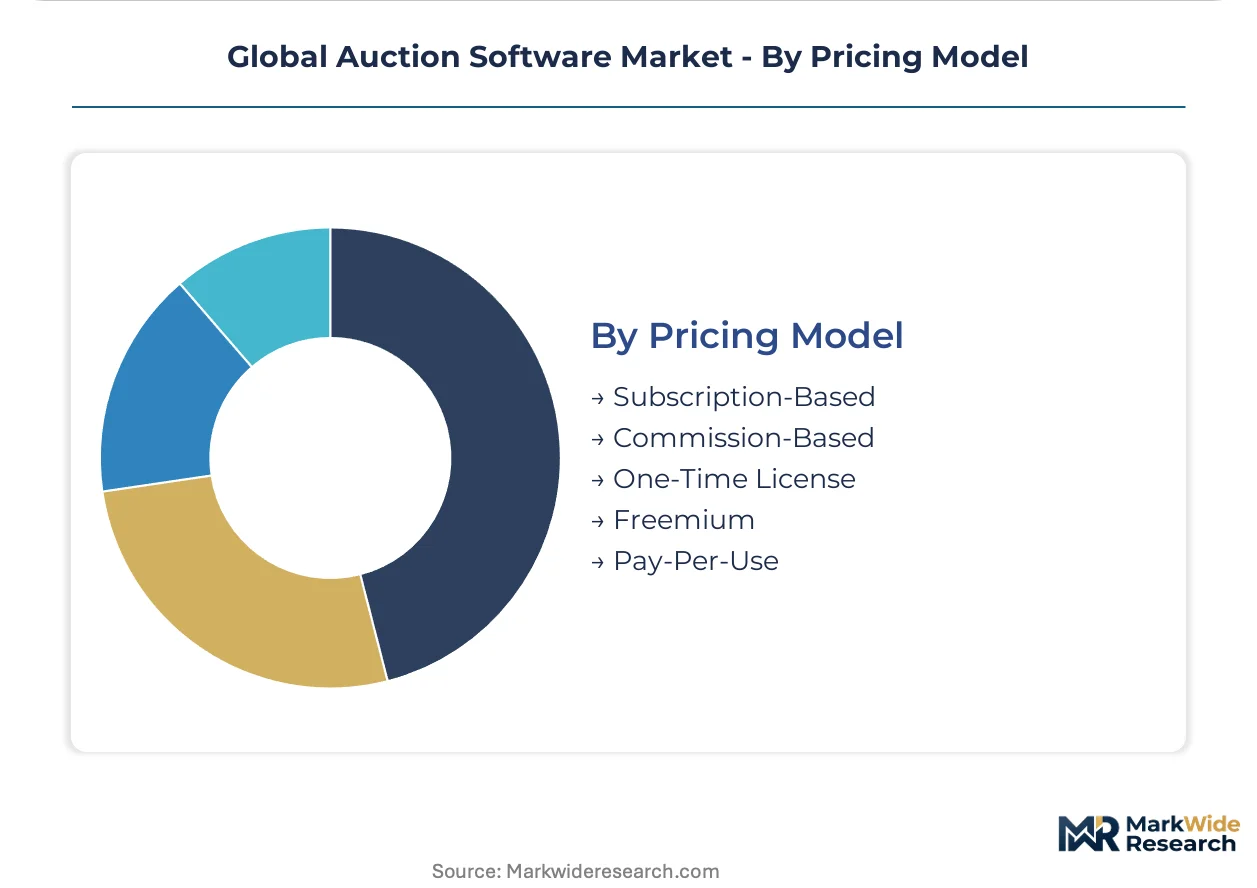
Pricing Model:
Customer type and transaction predictability determine pricing structure viability, with enterprise auctioneers resisting variable cost exposure.
- Commission-Based:Percentage-of-hammer pricing aligns vendor incentives with consignor success, dominating fine art and industrial equipment segments where lot values justify proportional fees.
- Subscription-Based:Fixed monthly fees reduce capital barriers for seasonal auctioneers in estate jewelry and collectibles, with RainWorx and Handbid deploying tiered plans scaled to lot volume bands.
- One-Time License:Perpetual software acquisition with annual maintenance contracts persists among established auction houses with dedicated IT departments and stable transaction forecasts.
- Freemium:Zero-entry tiers with transaction-volume caps attract non-profit organizations testing digital fundraising before platform commitment.
- Pay-Per-Use:Per-transaction or per-lot fees suit occasional auctioneers and pilot programs without predictable volume commitments.
By revenue contribution, Commission-Based structures lead. By new customer acquisition velocity, Freemium entry points are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidelines on financial data handling intersect with auction software when pharmaceutical surplus equipment enters secondary markets in the United States, while GDPR mandates reshape platform architecture across European jurisdictions.
United States
Federal procurement mandates institutionalize reverse auction workflows at US agencies, with competitive bidding protocols compressing capital equipment sourcing cycles. SEC reporting requirements govern collateral liquidation platforms serving financial institutions. New York and Los Angeles anchor fine art digitization efforts, with established auction houses deploying real-time bidding engines for evening sales.
Germany
Industrial machinery auctioneers favor on-premise deployments integrating with METI-standardized procurement systems for legacy ERP compatibility. The EU AI Act forces explainability layers into dynamic reserve pricing engines, extending deployment timelines. Munich and Stuttgart clusters concentrate equipment verification workflows using smartphone-captured imagery to pre-qualify machinery lots.
Japan
Smartphone-first bidding interfaces capture consignor attention in charity segments where real-time engagement drives donation velocity. METI standards govern procurement system integration for industrial auctioneers. Tokyo and Osaka metropolitan areas lead estate jewelry digitization among family-owned auctioneers adopting subscription pricing models.
India
Government-mandated eNAM platform expansion creates openings for auction software adapted to commodity spot-trading workflows in wheat and cotton belts. The central bank's digital payment infrastructure supports multi-currency settlement for agricultural mandis. Punjab and Haryana agricultural clusters pilot descending-price mechanisms for perishable inventory clearing.
United Kingdom
GDPR-compliant data frameworks reduce cross-border platform launch friction for auctioneers operating across Germany, France, and Netherlands markets from London headquarters. CSRD sustainability reporting layers onto supplier evaluation workflows for public procurement. The City of London anchors distressed asset disposal platforms integrating with custodial banking networks.
Global Auction Software Market Competitive Landscape
Cloud-native specialists and mobile-first engagement platforms split the market between enterprise scalability and real-time event participation. The vendor base organizes around three strategic archetypes: white-label deployment providers, charity fundraising specialists, and industrial procurement platforms. Consolidation pressure concentrates among mid-tier SaaS providers facing cyber insurance cost escalation. Competitive moves center on API-first architecture investments and embedded finance partnerships.
Within the white-label deployment tier, Bidlogix and AuctionWorx occupy positions emphasizing brand control for enterprise auctioneers. RainWorx Software anchors the multi-currency transaction support archetype for international consignments. Handbid exemplifies mobile-first bidding interfaces sustaining engagement during live charity galas. These three companies represent distinct strategic vectors: deployment flexibility, cross-border settlement infrastructure, and real-time mobile participation.
| Leading Market Players |
|---|
| bidlogix |
| AuctionWorx |
| RainWorx Software |
| GiveSmart |
| ClickBid |
| Handbid |
| 32auctions |
| Auction Flex |
| BiddingOwl |
| Others |
Supply & Pricing Matrix
Payment processor concentration at Stripe, Adyen, and regional acquirers determines both SaaS pricing tier spreads and supply chain resilience architecture for auction software vendors. This single-source dependency forces commission-based platforms to absorb settlement cost volatility while compressing margins at mid-tier providers serving non-profit segments.
Pricing Analysis
The customization-premium spread separates white-label deployment fees from standard SaaS subscription tiers. Commission-based pricing dominates fine art and industrial equipment segments where lot values justify percentage-of-hammer fees, while subscription models reduce capital barriers for seasonal auctioneers in estate jewelry. Price differentiation hinges on GDPR compliance bundling and multi-currency settlement capability. Pricing pressure stems from cyber insurance premium spikes eroding margins at charity-focused SaaS providers. Non-profit organizations exhibit highest price sensitivity, whereas enterprise auctioneers in London and New York resist variable cost exposure.
Supply Chain Analysis
Export-control regimes under ITAR and FDA data handling protocols restrict cloud infrastructure flows for defense surplus and pharmaceutical equipment auction platforms. Engineering talent concentrates in the United States, Germany, and India for API-first architecture development. Raw material inputs draw from cryptographic libraries, WebSocket streaming frameworks, and payment gateway SDKs. Single-source vulnerability runs through concentrated payment processor relationships. Distribution feeds from direct SaaS sales teams and channel partners serving regional auction house networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates constitute a regulatory inflection that will reshape competitive positioning across European fine art and wine auction platforms. Cloud migration and embedded finance convergence accelerate disruption velocity.
For Market Incumbents: Entrench API-first architecture investments to lock in enterprise auctioneer switching costs against white-label deployment specialists. Deepen backward integration into payment settlement infrastructure to reduce processor concentration risk. Prioritize ISO 27001 certification maintenance to defend enterprise client relationships against cyber insurance cost pass-through. For New Entrants and Emerging Players: India's digitizing agricultural mandis represent the most penetrable entry point for commodity spot-trading workflow adaptation. Carbon credit spot markets in Switzerland and Singapore offer secondary white-space for standardized lot clearing infrastructure. Lead with mobile-first bidding interfaces to capture charity gala fundraising momentum against established desktop platforms. For Investors and Strategic Acquirers: The EU AI Act's deployment timeline reshapes the acquisition landscape toward vendors with partitioned AI-driven pricing modules already compliant with explainability mandates. Long-term viability centers on embedded finance convergence capabilities and cross-border settlement infrastructure. Target acquisition archetypes feature cloud-native specialists with modular ERP integration capacity. Monitor blockchain engineer hiring velocity in London and New York as signal for provenance verification feature arms races.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Investment | Unlocks modular ERP integration with METI-standardized procurement systems at Japanese industrial auctioneers. |
| Embedded Finance Partnership | Integrates lending APIs and buyer financing tools at industrial equipment resale platforms for new revenue streams. |
| GDPR-Compliant Data Framework | Reduces cross-border platform launch friction for auctioneers operating across Germany, France, and Netherlands markets. |
| Mobile-First Platform Development | Captures real-time engagement during live charity galas where smartphone penetration exceeds 90% among attendees. |
| Computer Vision Integration | Automates condition grading for industrial equipment verification using smartphone-captured imagery without on-site specialist travel. |
Research Methodology
A standing panel of auction platform CTOs, charity fundraising directors, government procurement officers, and industrial equipment auctioneers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SEC filings, EU e-procurement registry data, and METI standardization documents. Bottom-up transaction volume modeling and top-down market sizing triangulated segment-level estimates.
Scenario-bracketing framed analytical outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, bidding mechanics, end-user vertical, and regional regulatory cluster. CAGRs derived from historical growth rate analysis and forward-looking adoption curve modeling. Industry-specific forecast inputs incorporated eNAM platform expansion timelines and EU AI Act compliance deployment cycles.
Practitioners should monitor payment processor consolidation, cyber insurance premium trajectories, and blockchain engineer wage inflation for early signals of structural cost shifts. Forecasts reflect assumptions about cloud migration velocity and mobile penetration rates. Material shifts in EU AI Act enforcement intensity or India's agricultural mandi digitization pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
User Feedback Software Market
Software & Services
Terminal Emulator Software Market
Software & Services
Global Legal Case Management Software Market
Software & Services
Auto Software Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Enterprise-Grade Saas Market
Software & Services
Global Florist Software Market
Software & Services
Global Organizational Change Management Software Market
Software & Services
Global Reference Check Software Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
Global Business Card Software Market
Software & Services
Live Chat Software Market
Software & Services
Web Scraping Software Market
Software & Services
Ground Handling Software Market
Software & Services
Global Fixed Asset Management Software Market