
 Smartphone Applications Market | 2026-2036
Smartphone Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone Applications Market Outlook
On-device AI inference silicon is recalibrating how applications process data without cloud round-trips. Google LLC leverages its tensor processing units to anchor generative features inside Android's core services. Apple Inc differentiates through vertical silicon-to-software control, sustaining premium latency benchmarks for photography and voice workloads. ByteDance Ltd competes by optimizing recommendation engines for heterogeneous chipsets across mid-tier devices in emerging markets.
Smartphone applications are software programs designed to execute on mobile operating systems, typically distributed through platform-specific storefronts with sandboxed permissions, API-level hardware abstraction, and over-the-air update mechanisms; they mediate commercial transactions, content consumption, and sensor-driven interactions for billions of users daily. Gaming and social media command the largest share of consumer attention minutes and in-app purchase volume, though productivity and health & fitness segments are expanding fastest as enterprise BYOD policies and wearable integration deepen engagement. Monetization through subscription and freemium models now captures disproportionate margin pools compared to advertising-dependent applications, reflecting user willingness to pay for uninterrupted utility.
The EU Digital Markets Act and GDPR framework constrain how Apple Inc and Google LLC operate storefronts and handle user data, directly shaping developer access rules and consent architectures. In the US, the FTC and state attorneys general scrutinize app store fee structures and data harvesting practices, creating compliance costs that favor larger publishers with legal infrastructure. Stakeholders must monitor whether interoperability mandates fragment platform control or consolidate alternative distribution channels.
Market Dynamics
On-device AI inference silicon is compressing cloud dependency for real-time processing, while interoperability mandates from Brussels to Delhi force platform operators to open payment rails and API access, fragmenting storefront control.
Growth Catalysts
- Enterprise Mobility Suites:Field service digitization across logistics and utilities absorbs substantial developer resources, creating sustained demand for offline-capable workforce applications.
- EU Digital Markets Act:The interoperability mandate forces Apple and Google to permit alternative app stores and payment systems, lowering distribution barriers for mid-sized publishers.
- Localized Content Ecosystems:Affordable data tariffs in India sustain tier-two and tier-three city adoption, with vernacular-language interfaces driving first-time smartphone utility.
Market Restraints
- Input Cost Volatility:Advanced packaging for AI-capable mobile system-on-chips concentrates in Taiwan Semiconductor Manufacturing facilities, exposing supply to geopolitical friction.
- Regulatory Fragmentation:India's TRAI data localization requirements, the EU's GDPR consent architectures, and US state-level privacy laws force parallel compliance engineering.
- Technical Limitation:Thermal constraints in sub-7nm silicon prevent sustained on-device large language model inference without throttling, limiting generative AI utility.
Strategic Opportunities
- Underpenetrated Geographies:Indonesia's archipelago logistics and Nigeria's agent banking networks remain underserved by localized enterprise applications.
- Regulatory Tailwind:India's PLI scheme for semiconductor assembly and testing incentivizes domestic AI chip packaging, enabling lower-latency on-device inference.
- Technology Convergence:Wearable health sensors and smartphone applications are merging into continuous glucose monitoring and arrhythmia detection workflows.
Industry Challenges
- Talent Scarcity:Embedded AI optimization for heterogeneous chipsets requires rare skill combinations in TensorFlow Lite and vendor-specific neural processing unit SDKs.
- Certification Complexity:Health applications seeking FDA 510(k) clearance or EU MDR Class IIa designation face 18-24 month validation timelines for algorithm-based diagnostic outputs.
- Integration Friction:Legacy enterprise resource planning systems in manufacturing and logistics resist API-first mobile frontends, requiring costly middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone Applications Market |
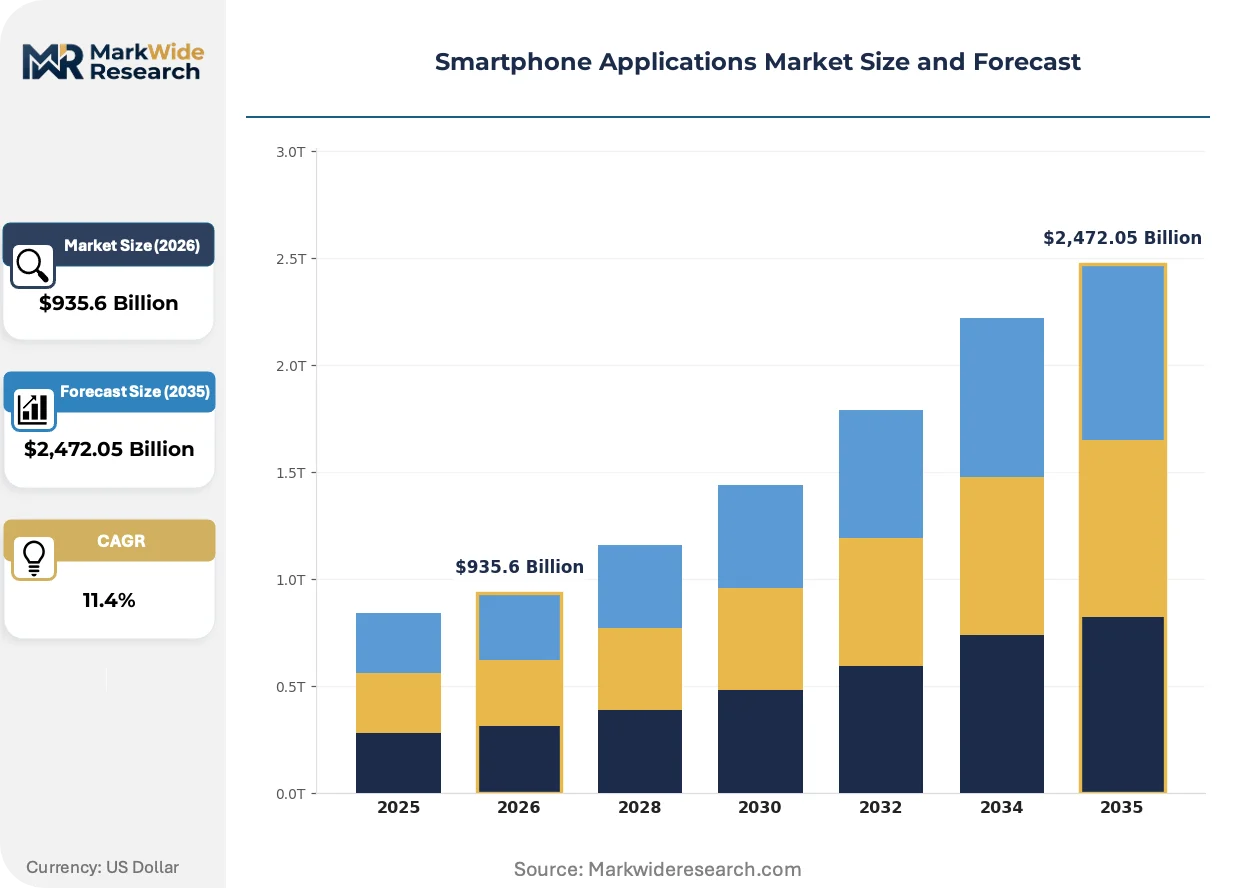
| Market Size in 2026 | $935.6 Billion |
| Market Size in 2035 | $2,472.05 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Social Media, Gaming, Productivity, Health & Fitness Deployment Model: Native, Hybrid, Web-Based, Cross-Platform End User: Individuals, Enterprises, Educational Institutions, Government Monetization Strategy: In-App Purchases, Subscription, Advertising, Freemium |
| Companies Covered | Apple Inc, Google LLC, Meta Platforms, Tencent Holdings Ltd, Microsoft Corporation, ByteDance Ltd, Alibaba Group Holding Ltd, Samsung Electronics Co Ltd, Spotify Technology SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone Applications Market Strategic Shifts
Generative AI capabilities are migrating from cloud data centers to smartphone neural processing units, while regulatory pressure on platform gatekeepers accelerates alternative distribution channel formation.
On-device large language model inference is expanding into photography, messaging, and code generation workflows. Mid-tier Android device manufacturers in Vietnam and Mexico are adopting Qualcomm's INT4-quantized models to enable offline summarization. This compression of cloud round-trip latency is expanding into markets with intermittent connectivity.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on health, finance, and biometric applications. Developers must maintain technical documentation and human oversight protocols for high-risk systems. Medical imaging applications targeting the European market are restructuring product architectures to satisfy notified body review requirements.
Subscription fatigue among consumers is compressing willingness to tolerate advertising-supported models. Productivity and creative tool categories in South Korea and Brazil are pivoting toward lifetime license options and usage-based tiers. This unbundling of perpetual access from recurring payments is most visible among freelance professionals and small agency buyers.
Smartphone Applications Market Segmentation
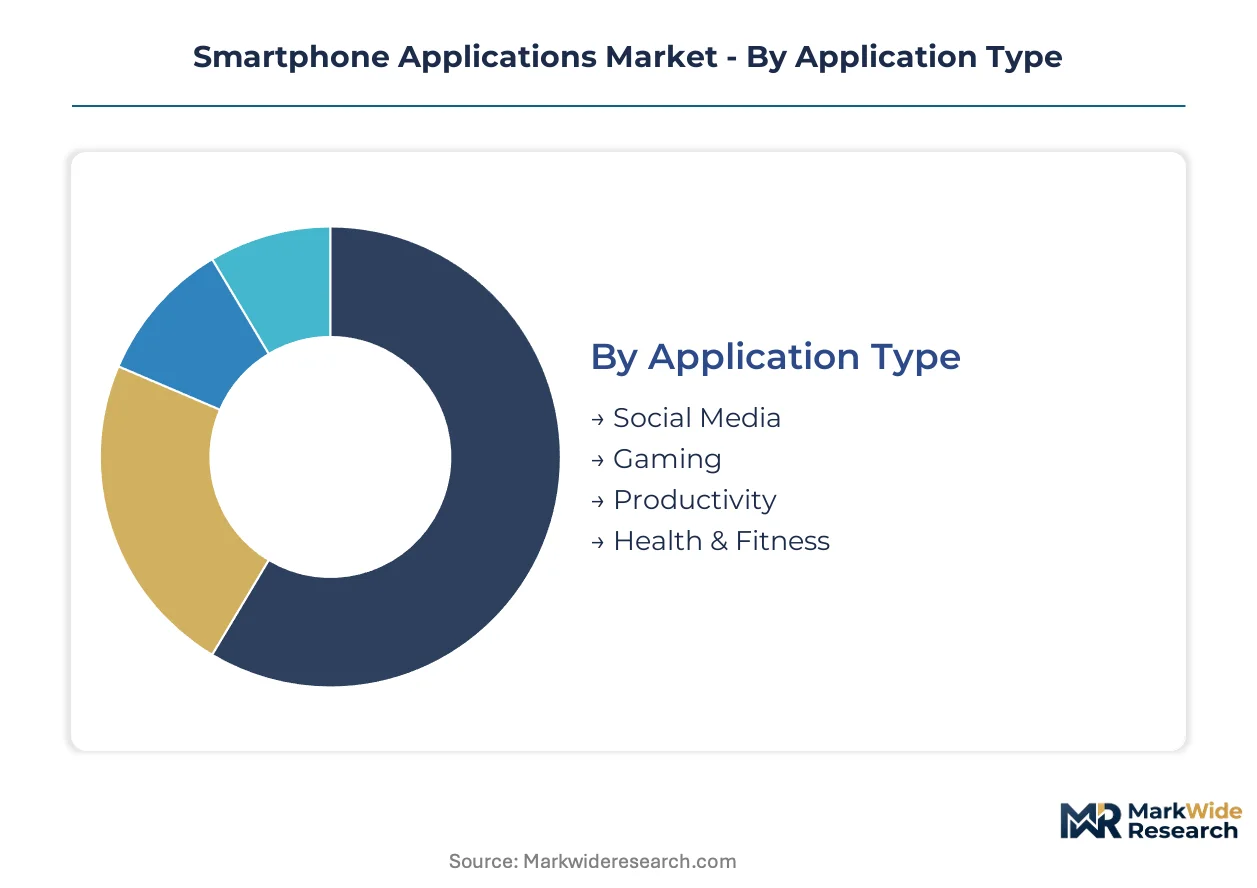
Application architectures and revenue models fragment across user expectations and hardware capabilities. Developers must align technical choices with monetization physics and regulatory exposure.
Application Type:
Volume concentrates in attention-economy categories, while premium monetization clusters around utility and wellness.
- Gaming:Real-time rendering engines and cloud-save synchronization dominate technical requirements. Battle royale and hyper-casual formats absorb development resources in Vietnam and Indonesia, where affordable mid-tier chipsets drive optimization priorities for heterogeneous neural processing units.
- Social Media:Recommendation algorithms and short-form video pipelines consume disproportionate bandwidth and silicon. ByteDance and Meta Platforms compete on inference latency for content ranking across India's tier-two cities, where intermittent connectivity rewards aggressive prefetching architectures.
- Productivity:Offline-first document editing and enterprise SSO integration characterize this segment. Microsoft's Office mobile suite and Notion compete on cross-device state synchronization.
- Health & Fitness:FDA 510(k) and EU MDR compliance pathways separate regulated diagnostic features from wellness tracking. Continuous glucose monitoring integrations drive sensor fusion complexity.
Mature deployment sits with Gaming. Newer deployment is concentrated in Health & Fitness.
Deployment Model:
Performance requirements and distribution economics split across abstraction layers.
- Native:Direct compilation to ARM or RISC-V instruction sets yields optimal thermal and latency profiles. Camera-centric applications in South Korea and Japan demand native SDK access for computational photography pipelines.
- Cross-Platform:React Native and Flutter frameworks compress development velocity for mid-sized publishers. Fintech applications in Brazil and Nigeria leverage shared codebases to accelerate regulatory compliance across operating systems.
- Hybrid:WebView containers with native plugin bridges balance reach and capability. Enterprise field service tools in Germany and France adopt hybrid architectures for rapid form-factor adaptation.
- Web-Based:Progressive Web Apps bypass storefront fees and approval delays. Progressive Web Apps gain traction where EU Digital Markets Act interoperability mandates reduce platform gatekeeper leverage.
Mature deployment sits with Native. Newer deployment is concentrated in Cross-Platform.
End User:
Budget authority and procurement cycles differentiate technical requirements.
- Enterprises:Mobile device management integration and FIPS 140-2 encryption compliance dominate security specifications. Logistics operators in the United States and Germany deploy offline-capable workforce applications with geofenced data residency.
- Individuals:Consumer-grade permissions models and frictionless onboarding drive retention optimization. First-time smartphone users in India's tier-three cities prioritize vernacular-language interfaces and low-bandwidth onboarding flows.
- Educational Institutions:COPPA and GDPR-K compliance frameworks constrain data handling. K-12 deployments in California and Texas require parental consent architectures and audit logging.
- Government:FedRAMP and ISO 27001 certification gates restrict vendor eligibility. Public safety applications in the United Kingdom and Australia mandate encrypted evidence chains and audit trails.
Mature deployment sits with Individuals. Newer deployment is concentrated in Enterprises.
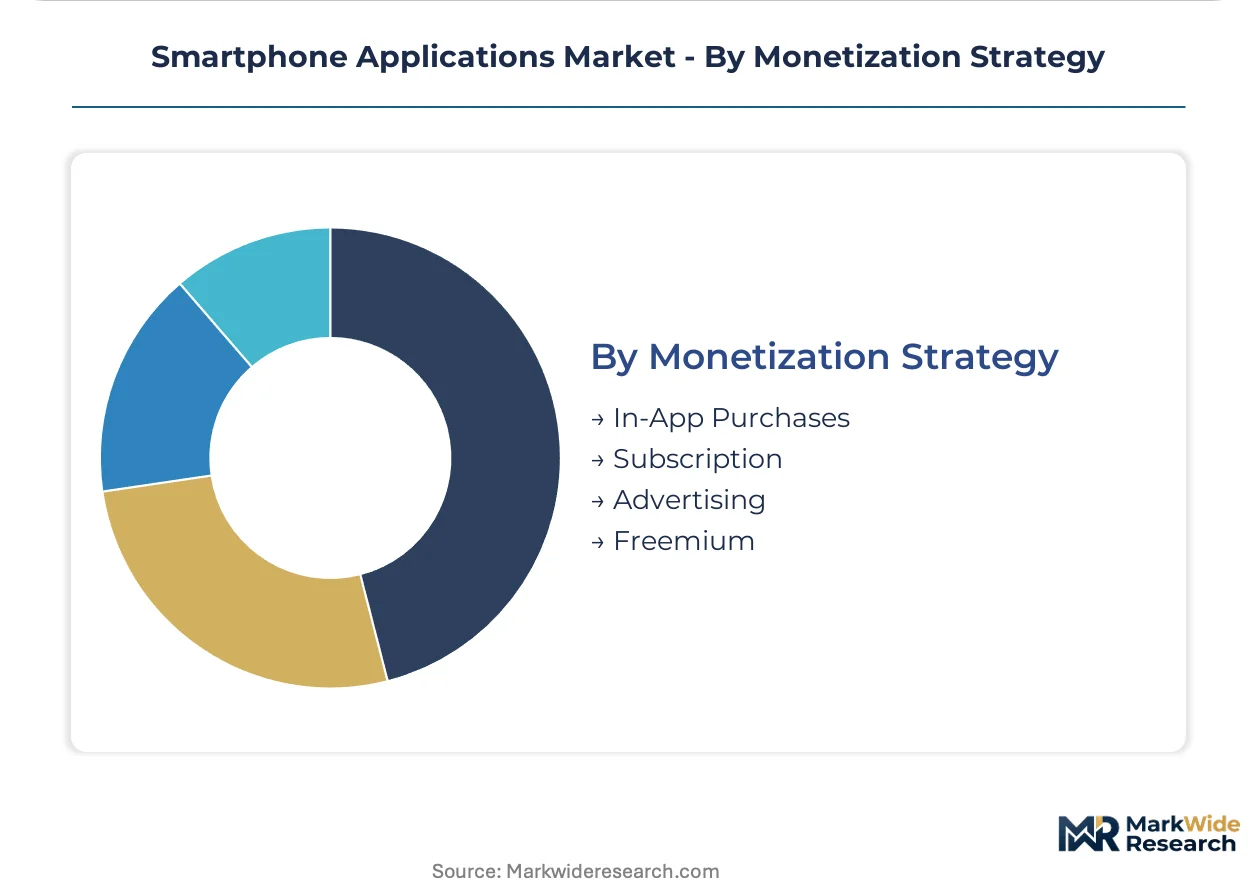
Monetization Strategy:
Revenue predictability and user acquisition costs shape publisher strategy.
- Subscription:Recurring revenue models demand continuous feature velocity and retention engineering. Creative tool publishers in South Korea pivot toward lifetime license options as consumer fatigue compresses willingness to tolerate recurring payments.
- In-App Purchases:Virtual goods and gacha mechanics dominate gaming economics. Gacha monetization in Japan and China drives ARPU concentration in whale segments, with regulatory scrutiny from consumer protection agencies intensifying.
- Freemium:Tiered capability gates balance acquisition and conversion. Productivity applications in Brazil and Mexico optimize paywall placement through behavioral segmentation.
- Advertising:ATT framework constraints and GDPR consent architectures compress targeting precision. ATT opt-in rates in the European Union lag North American benchmarks, forcing reliance on contextual rather than behavioral signals.
Mature deployment sits with Advertising. Newer deployment is concentrated in Subscription.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand through tier-two and tier-three city adoption, where affordable data tariffs and vernacular-language interfaces drive first-time smartphone utility. Developer resources flow toward localized content ecosystems serving these emerging user bases.
United States
Enterprise mobility suites absorb substantial developer resources as logistics and utilities operators digitize field operations. The FTC scrutinizes app store fee structures and data harvesting practices, creating compliance costs that favor larger publishers with legal infrastructure. Seattle and San Francisco Bay Area clusters anchor native application development for camera-centric and productivity segments.
India
Affordable data tariffs sustain adoption across tier-two and tier-three cities, with vernacular-language interfaces driving first-time smartphone utility. TRAI data localization requirements force parallel compliance engineering alongside GDPR architectures. Bengaluru and Hyderabad clusters concentrate cross-platform development for fintech applications targeting regulatory compliance across operating systems.
Germany
Enterprise field service tools adopt hybrid architectures for rapid form-factor adaptation across manufacturing and logistics verticals. The EU Digital Markets Act interoperability mandate forces platform operators to open payment rails and API access, lowering distribution barriers. Munich and Berlin clusters anchor health application development seeking EU MDR Class IIa designation for algorithm-based diagnostic outputs.
South Korea
Creative tool publishers pivot toward lifetime license options as consumer fatigue compresses willingness to tolerate recurring payments. MFDS regulates wearable health sensor integrations with smartphone applications for continuous glucose monitoring workflows. Seoul anchors native SDK development for computational photography pipelines demanding optimal thermal and latency profiles.
Brazil
Fintech applications leverage shared codebases to accelerate regulatory compliance across operating systems, with productivity applications optimizing paywall placement through behavioral segmentation. ANVISA oversees health application classifications as developers navigate certification complexity for diagnostic features. São Paulo clusters concentrate cross-platform development targeting freelance professionals and small agency buyers.
Smartphone Applications Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with platform operators and independent publishers occupying distinct competitive tiers. The vendor base concentrates around three strategic archetypes: vertically integrated hardware-software operators controlling silicon-to-software stacks, cross-platform publishers optimizing for heterogeneous device ecosystems, and specialized developers targeting regulated verticals with compliance-first architectures. Dominant competitive moves include strategic API opening in response to interoperability mandates and on-device AI inference optimization to reduce cloud dependency.
Within the vertically integrated tier, Apple Inc and Google LLC exemplify contrasting approaches to silicon-to-software control, while ByteDance Ltd occupies a position emphasizing recommendation engine optimization for mid-tier devices across emerging markets. These three entities anchor distinct competitive vectors: premium latency benchmarks, open ecosystem scale, and algorithmic content distribution respectively.
| Leading Market Players |
|---|
| Apple Inc |
| Google LLC |
| Meta Platforms |
| Tencent Holdings Ltd |
| Microsoft Corporation |
| ByteDance Ltd |
| Alibaba Group Holding Ltd |
| Samsung Electronics Co Ltd |
| Spotify Technology SA |
| Others |
Value Chain & Pricing Dynamics
Advanced packaging costs for AI-capable mobile system-on-chips flow from Taiwan Semiconductor Manufacturing facilities through three-tier pricing structures across premium, standard, and economy levels, with downstream publishers absorbing differential silicon access fees based on volume commitments and thermal performance tiers.
Pricing Analysis
Volume concentrates in advertising-supported and freemium tiers where ATT framework constraints and GDPR consent architectures compress targeting precision, while margin pools shift toward subscription models demanding continuous feature velocity. Price differentiation separates regulated health applications seeking FDA 510(k) clearance from wellness tracking utilities, with certification complexity adding eighteen-to-twenty-four-month validation premiums. Pricing pressure stems from subscription fatigue among consumers in South Korea and Brazil, where lifetime license options displace recurring payments. Individual consumers in India's tier-three cities exhibit highest price sensitivity, while enterprise mobility suites with FIPS 140-2 encryption requirements demonstrate lowest sensitivity due to budget authority and compliance mandates.
Supply Chain Analysis
Neural processing unit silicon supply rests on Taiwan, South Korea, and USA fabrication and advanced packaging facilities, with EUV lithography equipment and photoresist chemicals drawing from Dutch and Japanese specialty producers. Sub-7nm wafer starts and heterogeneous chipsets for mid-tier Android devices feed from concentrated foundry capacity, while thermal management components source from Chinese and Vietnamese assembly operations. Single-source vulnerability in EUV equipment creates chokepoint exposure for on-device AI inference scaling. Distribution runs through platform-specific storefronts with sandboxed permissions, though EU Digital Markets Act interoperability mandates accelerate alternative channel formation via Progressive Web Apps and sideloading architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smartphone applications market functions as a vertical-integration race where control over on-device AI inference silicon determines latency benchmarks and premium pricing power, with upstream foundry access and downstream storefront leverage as the contested levers.
For Market Incumbents: Deepen silicon-to-software control through proprietary neural processing unit optimization, securing exclusive tensor processing unit access for generative features inside core services. Consolidate developer ecosystem lock-in by expanding API-level hardware abstraction for computational photography pipelines, countering ByteDance's mid-tier device optimization and interoperability mandate fragmentation of storefront control. For New Entrants and Emerging Players: On-device large language model inference for intermittent connectivity markets presents the most penetrable technology-first wedge, targeting Indonesia's archipelago logistics and Nigeria's agent banking networks with offline-capable workforce applications. Pursue regulatory arbitrage through EU Digital Markets Act alternative distribution channels, leveraging Progressive Web App architectures to bypass platform gatekeeper fees and accelerate fintech compliance across operating systems. For Investors and Strategic Acquirers: First FDA 510(k) clearance or EU MDR Class IIa designation for algorithm-based diagnostic outputs is the leading indicator that health application publishers have crossed the compliance moat into recurring revenue viability. Target cross-platform development specialists with TensorFlow Lite and vendor-specific neural processing unit SDK capabilities, as talent scarcity in embedded AI optimization constrains scaling for mid-tier publishers across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| On-Device AI Inference Optimization | Qualcomm's INT4-quantized models enable offline summarization for Vietnam and Mexico mid-tier devices. |
| Alternative Distribution Channel Formation | EU Digital Markets Act interoperability mandates reduce Apple and Google storefront gatekeeper leverage. |
| Regulatory Compliance Certification | FDA 510(k) and EU MDR Class IIa designation separates regulated diagnostic features from wellness tracking. |
| Enterprise Mobility Suite Expansion | Offline-capable workforce applications with geofenced data residency capture logistics and utilities digitization budgets. |
| Vernacular Localization Investment | Affordable data tariffs in India's tier-two and tier-three cities drive first-time smartphone utility through language interfaces. |
Study Parameters
Document review covered SEC filings from platform operators, App Annie and Sensor Tower mobile analytics, hyperscaler capex disclosures, and EU regulatory filings, complemented by interviews with CTOs at cross-platform publishers, IT procurement officers at logistics operators, platform engineers at storefront operators, and integration specialists at enterprise mobility suite vendors. Secondary validation drew from TRAI data localization guidance, FDA 510(k) clearance databases, and EU MDR notified body records. Bottom-up triangulation across application type, deployment model, and monetization strategy segments intersected with top-down macroeconomic and regulatory scenario analysis.
Segmentation outputs across application type, deployment model, end user archetype, and monetization strategy were modeled over the projection horizon, with CAGRs derived from installation base growth, average revenue per user trajectories, and platform fee structure evolution. On-device AI inference silicon penetration, interoperability mandate implementation timelines, and enterprise BYOD policy expansion served as primary forecast inputs alongside vernacular localization velocity in emerging market tier-two and tier-three cities.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan Semiconductor Manufacturing capacity, unilateral platform operator fee structure changes, and breakthrough thermal management solutions enabling sustained large language model inference. Forecasts reflect documented assumptions about regulatory implementation timelines and silicon yield improvements. A small set of named triggers warrants ongoing watch: EU AI Act risk classification enforcement, India's PLI scheme semiconductor assembly incentives, and ATT opt-in rate divergence between European Union and North American benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Asia-Pacific IT Services Market
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Global Job Evaluation Software Market
Software & Services
Productivity Management Software Market
Software & Services
France Digital Marketing Software Market
Software & Services
Global Wedding Invitations Software Market
Software & Services
Global Online Survey Software Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Scanning and Migration Software Market
Software & Services
Payroll - HR Solutions and Services Market
Software & Services
Nonconformance Management Software Market
Software & Services
Winery Management Software Market
Software & Services
Global Employee Recognition Software Market
Software & Services
Content Moderation Software Market