
 Software-Defined Anything Market | 2026-2036
Software-Defined Anything Market Size, Share, and Industry Trends Forecast 2026-2036
Software-Defined Anything Market Intelligence
The capital-intensity divergence between bare-metal hardware vendors and cloud-native software stacks is unwinding competitive dynamics across the infrastructure layer. Cisco Systems leverages its installed base of routing hardware to extend software subscription revenue. VMware anchors enterprise virtualization demand through multi-cloud management platforms. Dell Technologies competes by integrating software-defined storage with direct server sales.
Software-Defined Anything encompasses the abstraction of networking, storage, and compute resources from proprietary hardware through programmable control planes, API-driven orchestration, and policy-based automation. Its primary commercial purpose is enabling elastic resource allocation across distributed infrastructure while reducing vendor lock-in and operational overhead. Network virtualization solutions lead current revenue pools as telecom providers modernize core networks, while security services represent the fastest-expanding margin segment amid zero-trust architecture mandates. Storage virtualization remains comparatively mature, with consolidation pressure favoring integrated platform vendors over point-product specialists.
The FCC, NIST cybersecurity frameworks, and EU NIS2 Directive collectively shape product certification timelines and cross-border data governance requirements for software-defined infrastructure deployments. HIPAA and SEC disclosure rules further constrain how healthcare and financial enterprises architect virtualized environments, creating compliance-driven demand for audited automation platforms. Stakeholders must monitor how sovereignty requirements fragment cloud interoperability standards and whether open-source control-plane projects erode proprietary vendor pricing power.
Market Dynamics
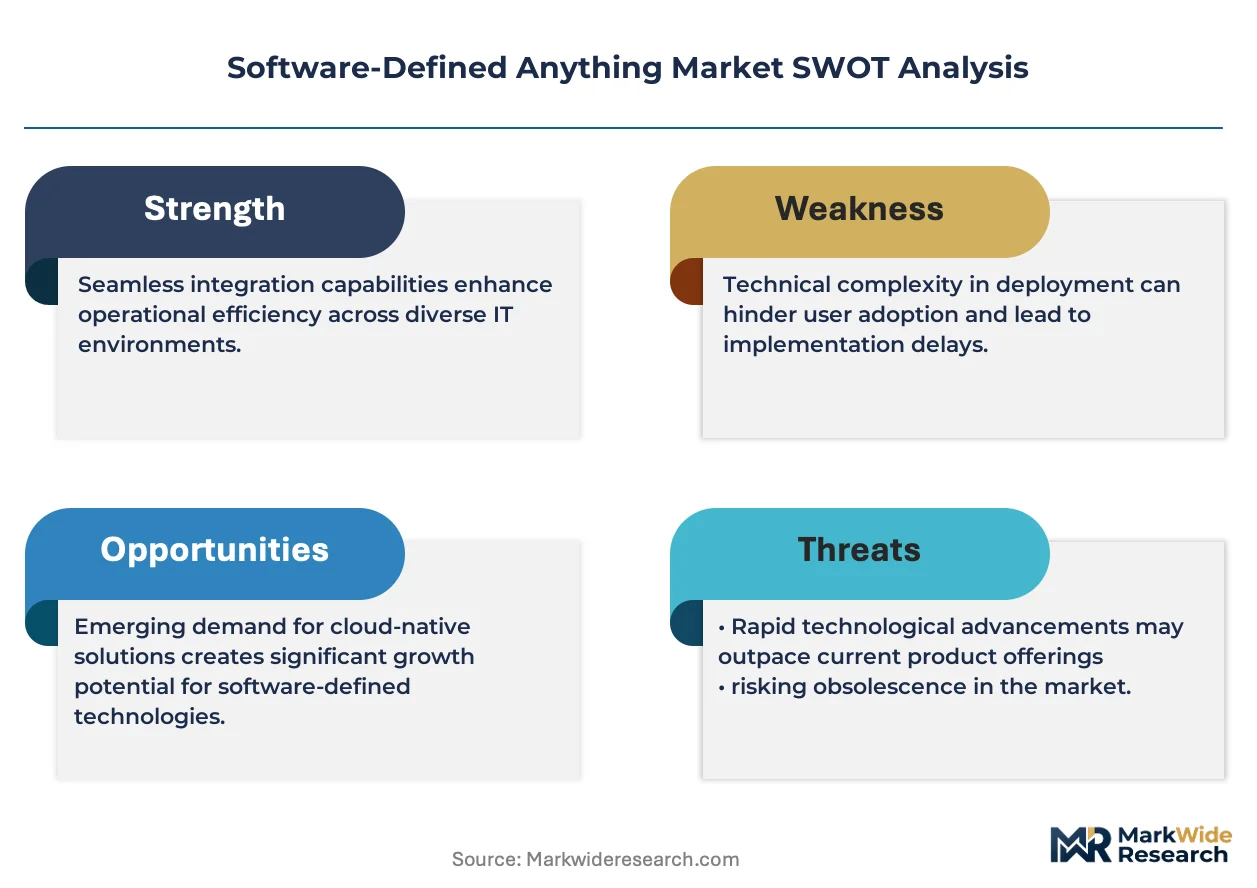
The Federal zero-trust architecture mandate is forcing enterprise infrastructure teams to rearchitect network segmentation through programmable control planes rather than perimeter appliances. This policy pressure is compressing procurement cycles for hardware-dependent security vendors while expanding subscription revenue pools for API-native orchestration platforms.
Growth Catalysts
- EU NIS2 Directive:The directive mandates continuous monitoring and automated threat response for critical infrastructure operators across member states, accelerating software-defined security deployments in energy and transport sectors.
- Hyperscaler data center buildouts:Amazon Web Services, Microsoft Azure, and Google Cloud are expanding bare-metal-as-a-service offerings that require programmable networking fabrics to maintain multi-tenant isolation at scale.
- Container orchestration:Kubernetes-native service mesh architectures are standardizing east-west traffic management, creating pull-through demand for software-defined networking layers that integrate with cloud-native workload schedulers.
Market Restraints
- Specialized engineering talent scarcity:Deep expertise in programmable data plane languages like P4 and eBPF concentrates among a limited pool of developers, inflating implementation costs for enterprise self-managed deployments.
- Silicon supply concentration:Merchant silicon for programmable switching ASICs depends heavily on Taiwan Semiconductor Manufacturing and Broadcom, exposing infrastructure roadmaps to geopolitical disruption risks.
- Legacy protocol inertia:Enterprise brownfield environments maintain substantial investments in Spanning Tree Protocol and VLAN-based segmentation, slowing forklift upgrades to intent-based networking models.
Strategic Opportunities
- Edge computing convergence:5G network slicing and industrial IoT deployments in Germany and France require distributed software-defined WAN nodes that collapse networking, security, and compute into unified platforms.
- Healthcare zero-trust mandates:HIPAA security rule enforcement is driving hospital systems toward microsegmentation architectures that isolate medical devices through policy-driven network virtualization rather than physical air gaps.
- Open-source control plane adoption:The Linux Foundation's Open Networking Foundation projects are gaining traction among telecommunications providers seeking to reduce dependency on proprietary orchestration licenses.
Industry Challenges
- Multi-vendor integration complexity:Enterprises struggle to maintain consistent policy enforcement across heterogeneous environments mixing VMware NSX, Cisco ACI, and cloud-native CNI plugins without creating security gaps.
- Certification timeline compression:Federal Risk and Authorization Management Program (FedRAMP) and StateRAMP audit cycles for software-defined infrastructure products lag behind product release velocity, delaying public sector revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software-Defined Anything Market |
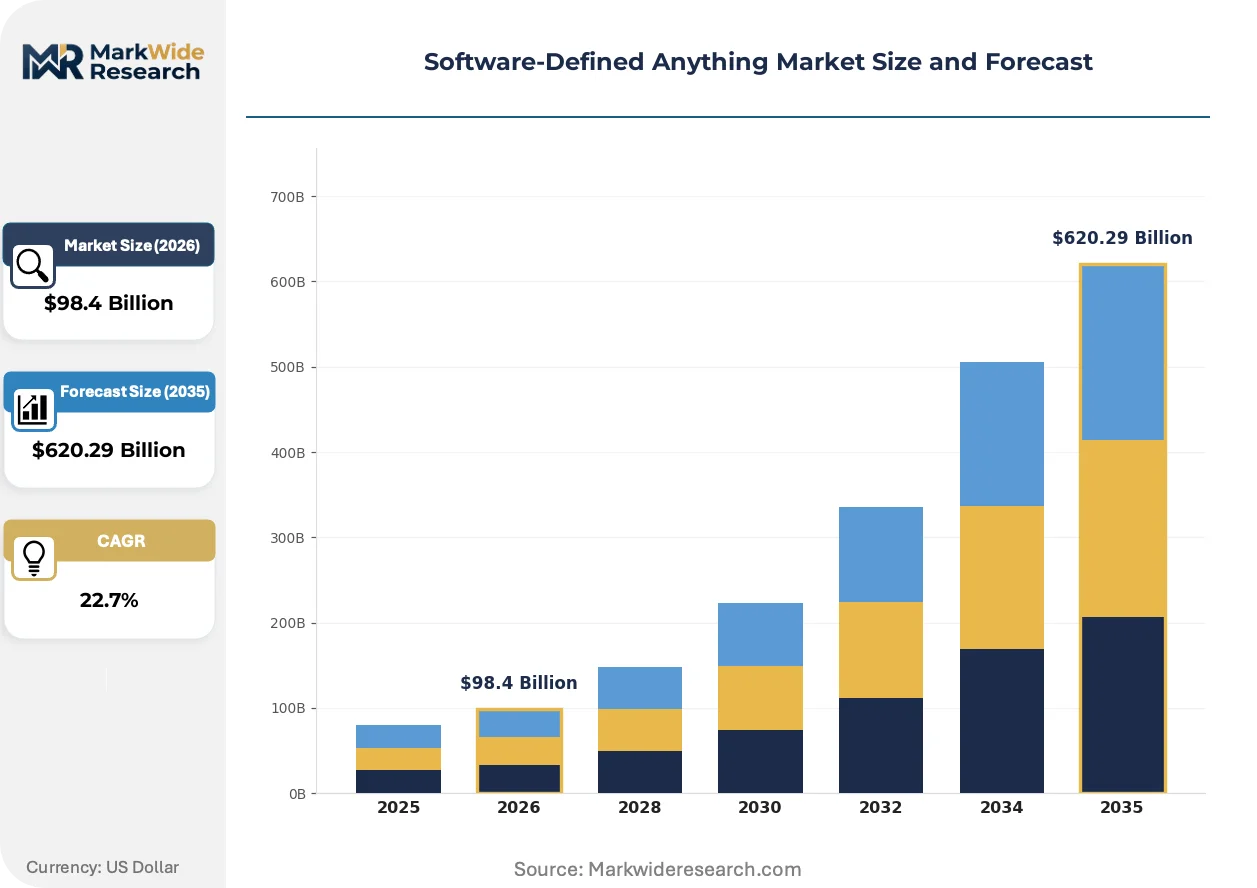
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $620.29 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution: Network Virtualization, Storage Virtualization, Compute Virtualization, Security Services End User: IT Enterprises, Telecom Providers, Cloud Service Providers, Government Agencies Technology: Network Functions Virtualization, Software-Defined Networking, Cloud Computing, Automation Tools |
| Companies Covered | Cisco Systems, IBM, Hewlett Packard Enterprise, Juniper Networks, Broadcom, VMware, Dell Technologies, Arista Networks, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software-Defined Anything Market Strategic Shifts & Innovations
Intent-based networking systems are displacing CLI-driven configuration workflows across enterprise campus and data center environments. This shift is compressing operational headcount requirements while elevating the strategic importance of network automation engineering functions.
eBPF-based observability and security tooling is displacing kernel-bypass and agent-heavy monitoring architectures. Cloud-native platform teams at financial services and SaaS providers are adopting these technologies to achieve sub-millisecond telemetry without sidecar resource overhead. The displacement of traditional network performance monitoring vendors is accelerating as eBPF becomes a standard Linux kernel capability.
The EU AI Act's risk-based classification system is mandating documented traceability for automated decision-making in critical infrastructure. Software-defined networking vendors serving European utilities and healthcare providers must now embed audit logging and policy versioning into their orchestration platforms. German network operators are responding by prioritizing vendors with pre-certified compliance documentation over feature velocity.
Consumption-based licensing for networking software is displacing perpetual entitlement models in enterprise procurement. Infrastructure teams at US healthcare systems and universities are negotiating subscription terms that scale with actual port utilization rather than peak provisioned capacity. This behavioral shift is most visible among mid-market enterprises that previously deferred refresh cycles due to upfront capital constraints.
Software-Defined Anything Market Segmentation
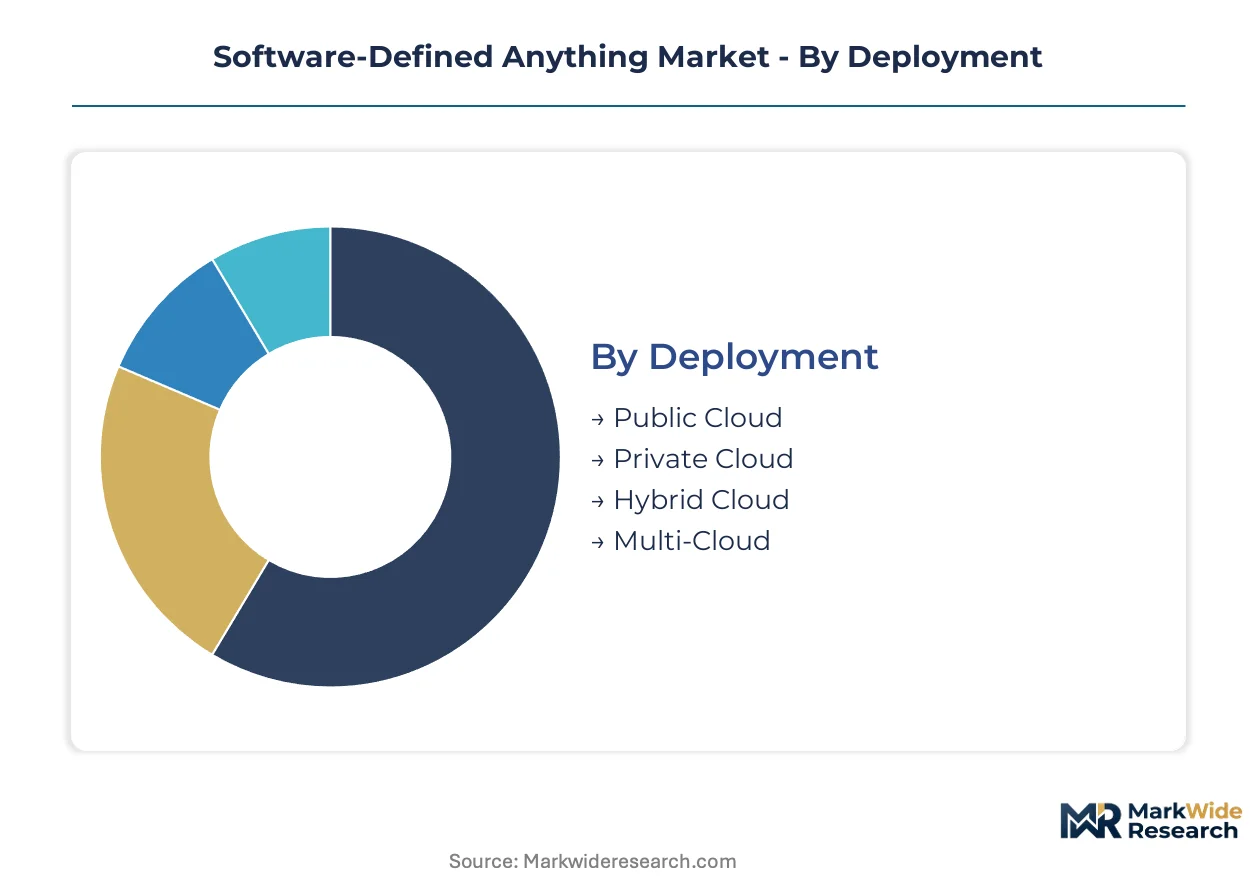
Segmentation in software-defined infrastructure reveals how abstraction layers map to procurement authority and operational maturity. Deployment models determine capital structure, while solution types expose where vendor consolidation pressure concentrates most intensely.
Deployment:
Public cloud deployments concentrate demand in the United States among hyperscaler data center buildouts, whereas private and hybrid models dominate European enterprise procurement under NIS2 Directive sovereignty requirements.
- Public Cloud:Fully managed infrastructure delivered by hyperscale providers with programmable APIs for tenant isolation. United States healthcare systems and financial services firms are migrating campus networks to cloud-native fabrics to satisfy federal zero-trust mandates without self-managing control planes.
- Private Cloud:Dedicated virtualized infrastructure maintained on-premises or in colocation facilities with full administrative control. German automotive manufacturers and French energy utilities are prioritizing private deployments to maintain operational data residency under EU AI Act documentation requirements.
- Hybrid Cloud:Unified orchestration across on-premises and public cloud resources with policy-driven workload placement. United States federal agencies are standardizing on hybrid architectures to bridge legacy classified environments with commercial cloud services.
- Multi-Cloud:Distributed control planes spanning two or more hyperscale providers without vendor-specific lock-in. Japanese financial institutions are deploying multi-cloud networking to satisfy METI operational resilience guidelines while avoiding single-provider concentration risk.
Public cloud commands the established base. The steepest expansion runs through multi-cloud orchestration platforms.
Solution:
Network virtualization solutions absorb the largest share of enterprise infrastructure budgets, while security services extract the highest margins from compliance-driven procurement cycles.
- Network Virtualization:Abstraction of switching, routing, and load-balancing functions from proprietary hardware into software control planes. Telecom providers in South Korea and Germany are modernizing 5G core networks through NFV-based packet cores to reduce reliance on single-vendor routing stacks.
- Security Services:Microsegmentation, zero-trust enforcement, and threat detection delivered through programmable policy engines. United States hospital systems facing HIPAA security rule enforcement are isolating medical device traffic through software-defined microsegmentation rather than physical network segmentation.
- Storage Virtualization:Pooling of heterogeneous storage arrays into unified namespaces with automated tiering and replication. Mature adoption curves in enterprise data centers are compressing pricing power for point-product vendors.
- Compute Virtualization:Abstraction of server resources through hypervisors and container runtimes with dynamic resource scheduling. Cloud service providers are extending bare-metal-as-a-service offerings that require compute virtualization layers for tenant isolation at scale.
Network virtualization commands the established base. The steepest expansion runs through security services.
End User:
IT enterprises and telecom providers exhibit divergent procurement patterns, with the former prioritizing operational simplicity and the latter demanding carrier-grade reliability certifications.
- IT Enterprises:Corporate technology departments managing internal infrastructure across campus, data center, and cloud environments. United States mid-market enterprises are negotiating consumption-based licensing terms that scale with actual port utilization rather than peak provisioned capacity.
- Cloud Service Providers:Hyperscale and regional cloud operators delivering multi-tenant infrastructure services. Amazon Web Services, Microsoft Azure, and Google Cloud are expanding bare-metal-as-a-service offerings that require programmable networking fabrics for tenant isolation.
- Telecom Providers:Mobile network operators and fixed-line carriers modernizing core and access networks. European operators are prioritizing vendors with pre-certified EU AI Act compliance documentation over feature velocity.
- Government Agencies:Federal, state, and municipal entities with classified or citizen-facing service mandates. FedRAMP and StateRAMP audit cycles for software-defined infrastructure products lag behind commercial release velocity, delaying public sector revenue recognition.
IT enterprises command the established base. The steepest expansion runs through cloud service providers.
Technology:
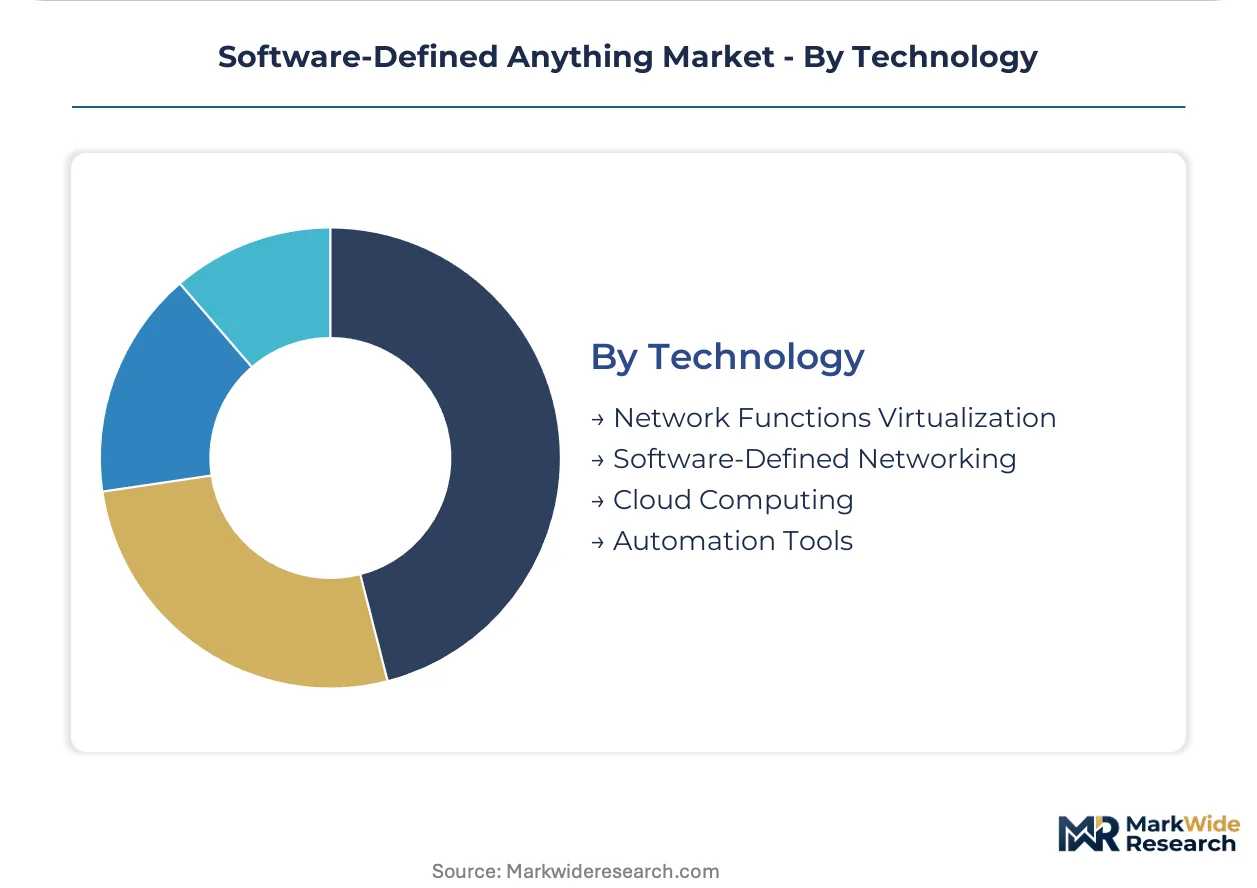
Software-defined networking and network functions virtualization dominate current deployment volumes, while automation tooling is gaining share fastest among cloud-native platform teams.
- Software-Defined Networking:Centralized control planes that decouple network intelligence from forwarding hardware through open protocols. United States federal zero-trust architecture mandates are compressing procurement cycles for hardware-dependent security vendors while expanding subscription revenue pools for API-native orchestration platforms.
- Automation Tools:Infrastructure-as-code frameworks, intent-based networking systems, and closed-loop remediation engines. Financial services and SaaS providers are adopting eBPF-based observability tooling to achieve sub-millisecond telemetry without sidecar resource overhead.
- Network Functions Virtualization:Virtualization of network appliance functions into software instances running on commodity hardware. Telecom providers are deploying NFV-based packet cores to reduce capital intensity and accelerate service velocity.
- Cloud Computing:Elastic resource provisioning through virtualized compute, storage, and networking services delivered over network connections. Kubernetes-native service mesh architectures are standardizing east-west traffic management and creating pull-through demand for integrated networking layers.
Software-defined networking commands the established base. The steepest expansion runs through automation tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States exhibit the lowest price elasticity as federal zero-trust mandates compress procurement cycles, while European enterprises under NIS2 Directive sovereignty requirements accept premium pricing for compliant private deployments. Asian markets demonstrate intermediate sensitivity, with hyperscaler scale driving volume discounts.
United States
Federal agencies and healthcare systems drive infrastructure modernization through FedRAMP-authorized orchestration platforms. The FCC and NIST cybersecurity frameworks shape certification timelines for software-defined networking vendors. Hyperscaler data center clusters in Northern Virginia and Dallas-Fort Worth anchor programmable fabric demand.
Germany
Automotive manufacturers and energy utilities prioritize operational data residency under EU AI Act documentation requirements. The NIS2 Directive mandates continuous monitoring for critical infrastructure operators across member states. Industrial IoT deployments in Bavaria and Baden-Württemberg require distributed software-defined WAN nodes.
China
Domestic cloud operators and telecom providers scale programmable infrastructure to support 5G network slicing and industrial digitization. MIIT standards and dual carbon goals influence control plane energy efficiency requirements. Technology clusters in the Yangtze River Delta and Pearl River Delta concentrate merchant silicon demand.
Japan
Financial institutions deploy multi-cloud networking to satisfy METI operational resilience guidelines while avoiding single-provider concentration. The country's central bank and financial regulator enforce strict system redundancy mandates. Tokyo and Osaka metropolitan areas host dense concentrations of Kubernetes-native service mesh implementations.
United Kingdom
Enterprise technology departments negotiate consumption-based licensing terms that scale with actual port utilization rather than peak provisioned capacity. The UK national cybersecurity center publishes guidance on zero-trust architecture adoption. London financial services firms and Manchester digital infrastructure clusters drive intent-based networking procurement.
Software-Defined Anything Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the infrastructure layer. The market structures around three tiers: legacy hardware vendors extending software subscriptions, cloud-native specialists capturing API-driven orchestration demand, and integrated platform providers bundling storage virtualization with server sales. Dominant competitive moves include strategic partnerships between silicon vendors and control plane developers, plus geographic expansion through certified compliance documentation for European sovereignty requirements.
Within the legacy hardware extension tier, Cisco Systems and Dell Technologies occupy positions that leverage installed base relationships to convert capital equipment purchases into recurring software revenue. VMware exemplifies the multi-cloud management archetype, anchoring enterprise virtualization demand through policy-driven orchestration platforms. Juniper Networks sits within the cloud-native specialist category, representing programmable fabric approaches that displace traditional appliance-dependent security vendors.
| Leading Market Players |
|---|
| Cisco Systems |
| IBM |
| Hewlett Packard Enterprise |
| Juniper Networks |
| Broadcom |
| VMware |
| Dell Technologies |
| Arista Networks |
| Microsoft |
| Others |
Cost & Logistics Intelligence
Hyperscaler data center buildouts in Northern Virginia and Dallas-Fort Worth create procurement scale that compresses unit economics for programmable switching ASICs while elevating subscription revenue floors for API-native orchestration platforms. This concentration of demand among cloud service providers and United States federal agencies shapes both supply allocation priorities and pricing power distribution across the infrastructure layer.
Pricing Analysis
Software subscription and support contracts generate the majority of lifetime value for infrastructure vendors, displacing perpetual licensing models as United States healthcare systems and universities negotiate consumption-based terms tied to actual port utilization. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by FedRAMP authorization status and multi-cloud orchestration depth. Cost compression in the standard tier is intensifying because open-source control plane projects erode proprietary vendor pricing power. Cloud service providers exhibit the lowest price sensitivity due to hyperscaler scale, while mid-market enterprises remain most elastic given capital constraint histories.
Supply Chain Analysis
Extended lead times for merchant silicon stretch infrastructure roadmaps as programmable switching ASIC production concentrates in Taiwan and South Korea with final assembly in China and Mexico. Taiwan Semiconductor Manufacturing and Broadcom supply the critical merchant silicon, while memory components and specialized optics draw from South Korean and Japanese suppliers. Single-source vulnerability around Taiwan Semiconductor Manufacturing exposes infrastructure vendors to geopolitical disruption risks. Distribution runs through direct enterprise sales teams for federal and healthcare accounts, with hyperscaler procurement managed through dedicated supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep expertise in programmable data plane languages like P4 and eBPF concentrates among a limited talent pool, creating structural bottlenecks that inflate implementation costs and delay enterprise self-managed deployments. This capability scarcity rewards vendors who embed automation into managed service offerings.
For Market Incumbents: Compound subscription revenue from installed base relationships by converting capital equipment purchases into recurring software entitlements, while accelerating FedRAMP and StateRAMP certification pipelines to capture federal zero-trust procurement cycles before open-source alternatives mature. For New Entrants and Emerging Players: FedRAMP authorization fast-tracks enable public sector market entry where incumbent certification lags create temporary white space, with European NIS2 Directive compliance documentation offering parallel entry into German energy and French transport sectors through sovereignty-aligned private cloud deployments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API-native orchestration platforms over hardware-dependent security vendors, with long-term viability hinging on Kubernetes-native integration depth and eBPF-based observability capabilities. Monitor open-source control plane adoption rates among telecommunications providers as the inflection signal for proprietary license erosion.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Accelerates public sector revenue recognition through pre-certified compliance documentation. |
| Multi-Cloud Orchestration Platform Integration | Captures enterprise demand for unified policy enforcement across heterogeneous environments. |
| eBPF-Based Observability Capability Development | Displaces agent-heavy monitoring architectures among financial services and SaaS providers. |
| Strategic Partnership with Merchant Silicon Vendors | Secures supply allocation priority for programmable ASICs amid Taiwan concentration risk. |
| EU NIS2 Directive Compliance Certification | Unlocks critical infrastructure procurement in Germany and France under sovereignty requirements. |
Research Approach
Desk research of hyperscaler capex disclosures, SEC infrastructure vendor filings, and EU regulatory documentation preceded structured interviews with platform engineers at cloud service providers, network architects at telecommunications operators, federal procurement officers, and enterprise IT directors responsible for zero-trust migration. Primary fieldwork combined with secondary validation against NIST cybersecurity framework publications and FedRAMP authorization databases enabled bottom-up and top-down triangulation of deployment volumes and pricing trajectories.
Variance decomposition across deployment models, solution types, end-user categories, and regional adoption patterns structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate analysis incorporating infrastructure refresh cycle timing, regulatory mandate implementation schedules, and open-source project maturity curves. Kubernetes-native service mesh penetration and eBPF kernel capability standardization served as technology-specific forecast inputs.
Underlying assumptions cover sustained hyperscaler data center expansion, stable Taiwan semiconductor supply, and phased EU AI Act enforcement, with deviation risk concentrated in geopolitical disruption to merchant silicon supply and accelerated open-source control plane adoption among telecommunications providers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Continuous Integration Tools Market
Software & Services
Collaboration Software Market
Software & Services
Global Invoice Automation Software Market
Software & Services
Global PPC Software Market
Software & Services
Global Intelligent Apps Market
Software & Services
United States Donation Management Software Market
Software & Services
Visitor Identification Software Market
Software & Services
Global Cloud Enterprise Resource Planning Market
Software & Services
Global Budgeting Software Market
Software & Services
Customer Revenue Optimization Software Market
Software & Services
Global IVR Software Market
Software & Services
Cloud-Based Dental Practice Management Software Market
Software & Services
Proxy Services and Software Market
Software & Services
Global Intranet Software Market
Software & Services
Global App Builder Software Market
Software & Services
Web Framework Software Market