
 K8s Market | 2026-2036
K8s Market Size, Share, and Industry Trends Forecast 2026-2036
K8s Market Insights
EU corporate sustainability reporting mandates under CSRD is broadening procurement criteria for container infrastructure across European enterprises. Google leverages its GKE platform to sustain engineering mindshare through open-source stewardship of the Kubernetes project itself. Amazon anchors commercial Kubernetes adoption through EKS integration with its broader cloud services ecosystem. Microsoft competes by extending Azure Kubernetes Service into hybrid edge scenarios with Arc connectivity.
Kubernetes is an open-source container orchestration platform that automates deployment, scaling, and management of containerized applications across clusters of hosts, typically operating with etcd for distributed state storage and supporting container runtimes conforming to the Open Container Initiative specification. Its primary industrial purpose is enabling portable, resilient application infrastructure that decouples software from underlying hardware across development, testing, and production environments. Public cloud deployment dominates volume as hyperscalers absorb operational complexity, while security solutions command premium pricing due to compliance-driven procurement requirements. Enterprise end users represent the deepest margin pool given their multi-cluster governance needs and professional services attach rates.
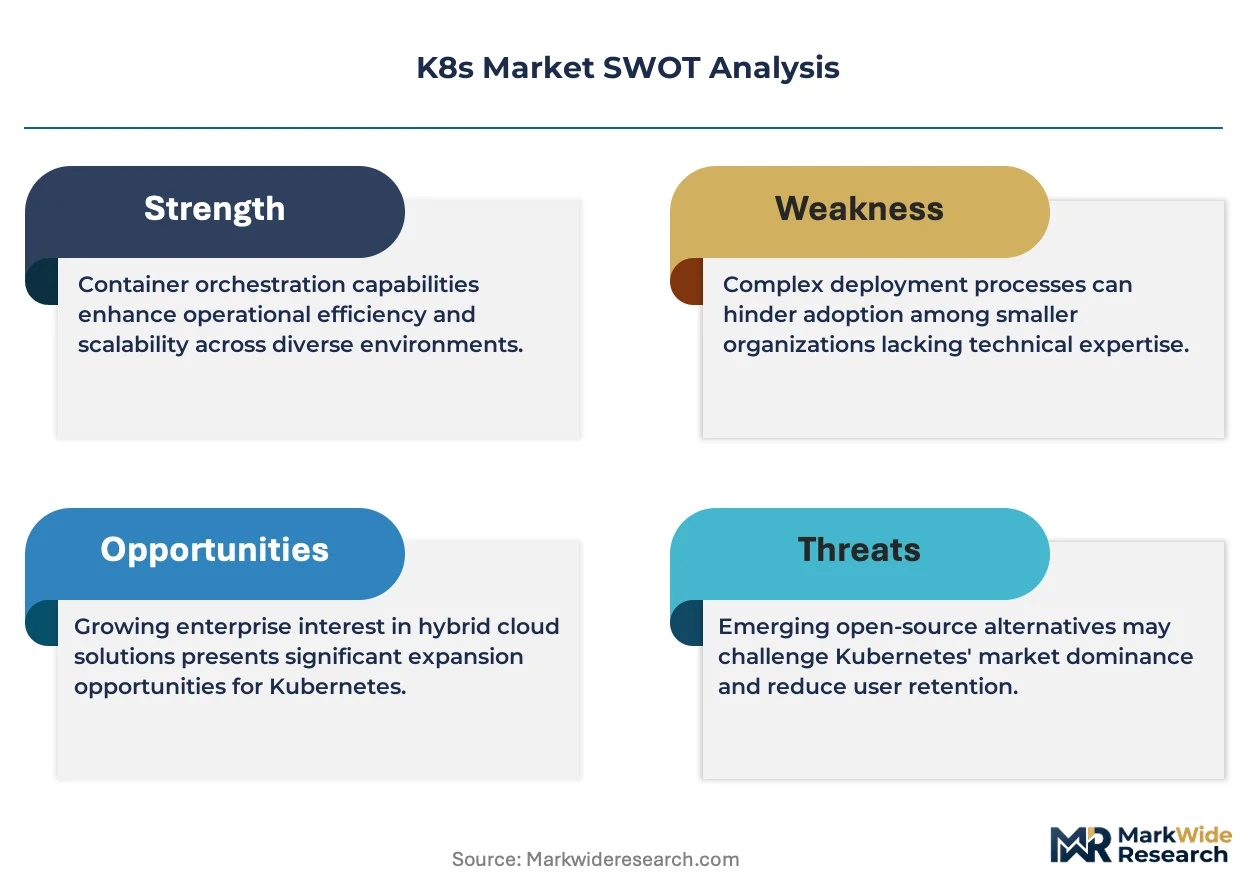
FDA 21 CFR Part 11 guidelines shape validation requirements for Kubernetes deployments in pharmaceutical manufacturing environments, while NIST SP 800-204 standards govern microservices security architecture in US federal cloud environments. ISO 27001 certification has become a baseline market access requirement for European Kubernetes service providers under GDPR-aligned vendor due diligence. Stakeholders must monitor whether emerging sovereign cloud regulations fragment Kubernetes control plane architectures across jurisdictional boundaries.
Market Dynamics
Financial services firms are accelerating Kubernetes adoption for trading infrastructure modernization, creating a structural pull for low-latency orchestration capabilities that decouple software from hardware dependencies.
Growth Catalysts
- EU AI Act compliance mandates:Container orchestration platforms face new algorithmic transparency requirements that Kubernetes-native tooling addresses through audit-ready deployment pipelines.
- Multi-cloud portability imperatives:Enterprise IT organizations demand workload mobility across hyperscaler environments that Kubernetes abstraction layers uniquely enable.
- Edge computing expansion:Manufacturing and telecommunications sectors deploy containerized workloads at distributed sites requiring lightweight control plane architectures.
Market Restraints
- etcd state management complexity:Distributed consensus mechanisms for cluster state storage impose operational overhead that constrains adoption in resource-constrained environments.
- Certified Kubernetes administrator scarcity:Labor market tightness for platform engineering skills inflates implementation timelines and professional services costs.
- Container runtime fragmentation:Divergence between CRI-O, containerd, and legacy Docker implementations complicates standardization efforts across vendor ecosystems.
Strategic Opportunities
- CSRD-aligned sustainability reporting:European enterprises must document IT infrastructure carbon footprints, creating procurement preference for energy-efficient orchestration platforms.
- GitOps operational models:Declarative infrastructure management converges with Kubernetes APIs to enable fully automated deployment pipelines for regulated industries.
- Confidential computing integration:Hardware-based trusted execution environments combine with container isolation to unlock multi-tenant deployments in sensitive data verticals.
Industry Challenges
- FDA 21 CFR Part 11 validation complexity:Pharmaceutical manufacturers face extended qualification timelines for Kubernetes deployments in GxP environments.
- Multi-cluster governance tooling gaps:Fleet management and policy enforcement across hundreds of clusters strain existing platform engineering capabilities.
- Legacy monolith decomposition friction:Brownfield application modernization projects encounter persistent state management and networking migration obstacles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | K8s Market |
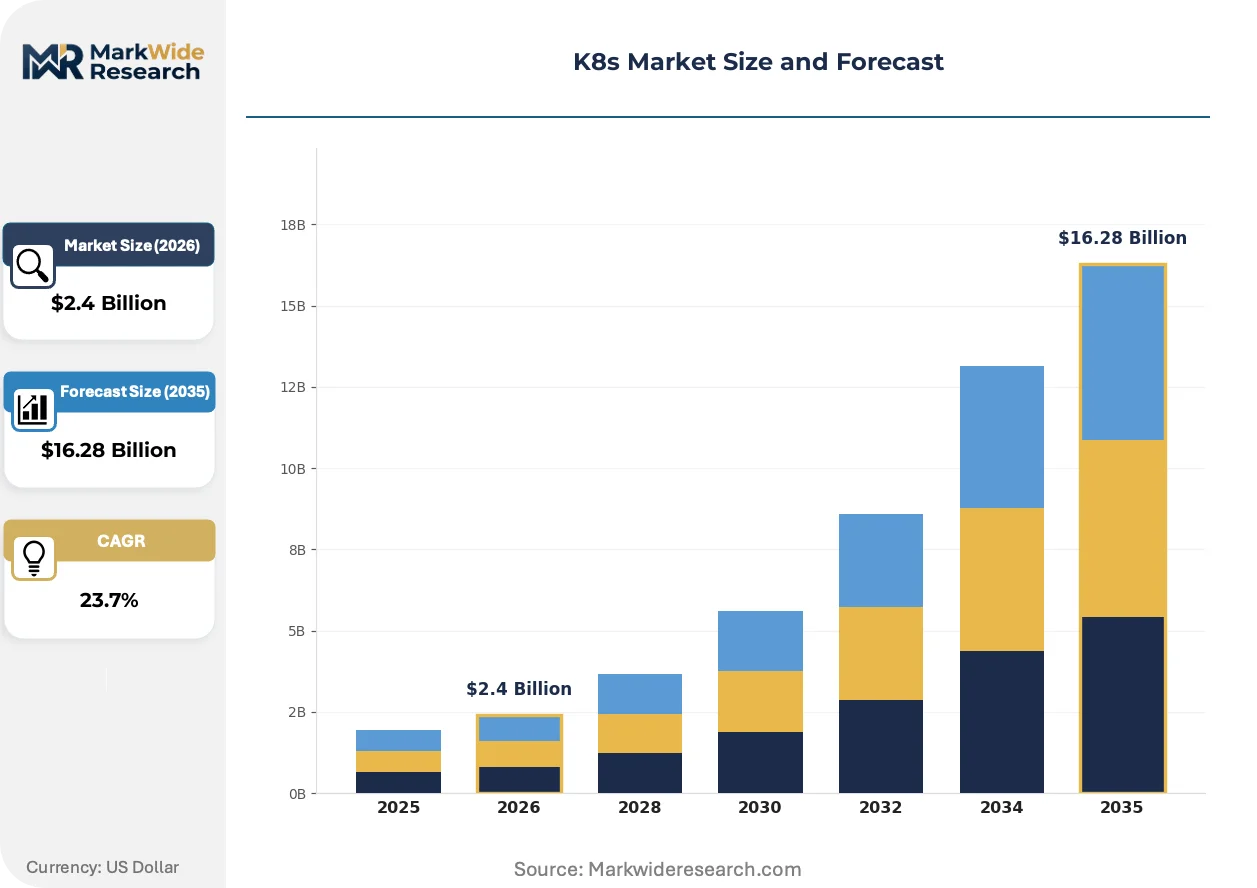
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $16.28 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud Solution Type: Container Management, Monitoring Tools, Security Solutions, CI/CD Tools End User: SMBs, Enterprises, Government, Educational Institutions Service Model: Managed Services, Professional Services, Consulting Services, Training & Support |
| Companies Covered | Google, Amazon, Microsoft, IBM, Oracle, Red Hat, VMware, Sysdig, Rancher Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
K8s Market Trends and Innovations
Container orchestration architectures are converging with sovereign cloud requirements and AI/ML operational pipelines, reshaping how enterprises evaluate platform capabilities against compliance and performance benchmarks.
eBPF kernel instrumentation is unifying observability, security enforcement, and networking control within Kubernetes clusters. Platform engineering teams at financial services and telecommunications firms adopt eBPF-based tooling to replace fragmented sidecar architectures. This consolidation is unifying telemetry pipelines and reducing per-node resource overhead that previously constrained cluster density.
NIS2 Directive network security mandates are compelling European enterprises to implement zero-trust segmentation for containerized workloads. The regulation's incident reporting requirements accelerate procurement of Kubernetes-native security platforms with automated threat detection. Financial services and critical infrastructure operators in Germany, France, and the Netherlands represent the earliest compliance-driven adopters.
Platform engineering teams are consolidating vendor relationships around integrated Kubernetes distributions that bundle ingress, storage, and observability components. This bundling displaces best-of-breed component assembly that dominated early enterprise adoption cycles. The shift is most pronounced among US-based healthcare and federal contractors navigating FedRAMP authorization complexity.
K8s Market Segmentation
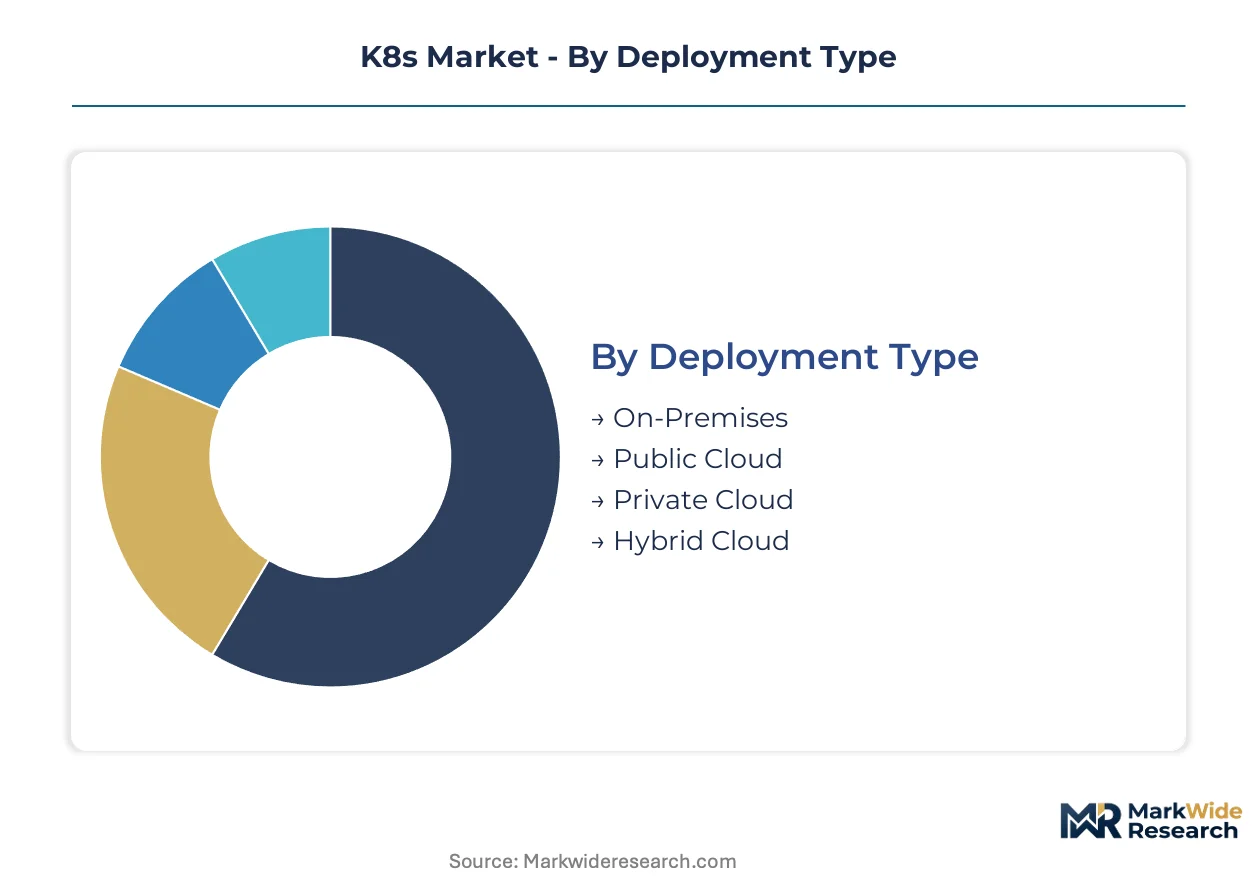
Segmentation in the K8s Market reveals how deployment complexity, security requirements, and operational maturity fragment procurement patterns across buyer types. Understanding these divides illuminates where platform engineering investments concentrate versus where managed service abstraction dominates purchasing decisions.
Deployment Type:
Public cloud deployments absorb the highest transaction volumes through hyperscaler operational simplification, while on-premises and hybrid configurations command premium pricing due to compliance-driven customization requirements.
- Public Cloud:Hyperscaler-managed control planes eliminate etcd operational overhead and cluster lifecycle management. Financial services firms in the United States deploy trading infrastructure on these platforms to decouple software from hardware dependencies while meeting low-latency requirements.
- On-Premises:Bare-metal or virtualized infrastructure with customer-managed control planes enables sovereign data residency and custom networking configurations. Pharmaceutical manufacturers pursuing FDA 21 CFR Part 11 validation favor this model for GxP environment audit trails and air-gapped security boundaries.
- Private Cloud:Dedicated cloud infrastructure operated by third-party providers or internal platform teams delivers isolated multi-tenancy without hyperscaler shared responsibility models. European enterprises under NIS2 Directive mandates select this path for network segmentation control.
- Hybrid Cloud:Workload portability across on-premises and cloud environments with unified control plane federation addresses burst capacity and disaster recovery scenarios. Telecommunications operators leverage hybrid architectures to extend container orchestration from core data centers to distributed edge locations.
Mature deployment sits with On-Premises configurations in regulated manufacturing and government sectors. Newer deployment is concentrated in Public Cloud among digital-native enterprises and mid-market firms prioritizing speed over customization.
Solution Type:
Security solutions capture the steepest margin expansion as EU AI Act and NIS2 compliance mandates reshape procurement criteria, while monitoring tools face commoditization pressure from open-source observability stacks.
- Security Solutions:Admission controllers, runtime threat detection, and secrets management platforms enforce zero-trust segmentation for containerized workloads. German and French critical infrastructure operators under NIS2 incident reporting requirements drive fastest adoption of automated Kubernetes-native security platforms.
- Container Management:Core orchestration platforms including cluster provisioning, workload scheduling, and resource optimization form the foundational technology layer. Platform engineering teams at US federal contractors select FedRAMP-authorized distributions that bundle ingress, storage, and observability components.
- Monitoring Tools:Metrics aggregation, log management, and distributed tracing systems provide visibility into cluster health and application performance. eBPF-based instrumentation is displacing fragmented sidecar architectures at financial services and telecommunications firms.
- CI/CD Tools:GitOps-enabled deployment pipelines automate infrastructure-as-code workflows and progressive delivery strategies. Regulated industries adopt these solutions to satisfy EU AI Act algorithmic transparency requirements through audit-ready deployment histories.
Platform engineering teams consolidate vendor relationships around integrated Container Management distributions. Security Solutions represent the fastest-growing procurement category as compliance deadlines approach.
End User:
Enterprise buyers generate the deepest professional services attach rates given multi-cluster governance complexity, while government procurement emphasizes sovereign cloud and FedRAMP authorization pathways.
- Enterprises:Large organizations operating hundreds of clusters across business units require fleet management, policy enforcement, and cost optimization platforms. Multi-cloud portability imperatives drive these buyers toward Kubernetes abstraction layers that enable workload mobility across hyperscaler environments.
- SMBs:Small and medium businesses with limited platform engineering headcount favor managed Kubernetes services that absorb operational complexity. These organizations prioritize rapid application deployment over customization, selecting hyperscaler solutions with minimal configuration overhead.
- Government:Federal, state, and local agencies mandate specific security certifications and data residency controls for container infrastructure. US federal deployments follow NIST SP 800-204 microservices security architecture standards, while European public sector buyers align with GDPR-aligned vendor due diligence requirements.
- Educational Institutions:Universities and research organizations deploy Kubernetes for computational research, student training environments, and administrative application modernization. These buyers balance cost sensitivity with requirements for on-premises hardware utilization and specialized AI/ML workload support.
Certified Kubernetes administrator scarcity constrains expansion among SMBs. Government and Enterprise segments are climbing the fastest as compliance mandates and brownfield modernization projects accelerate platform investments.
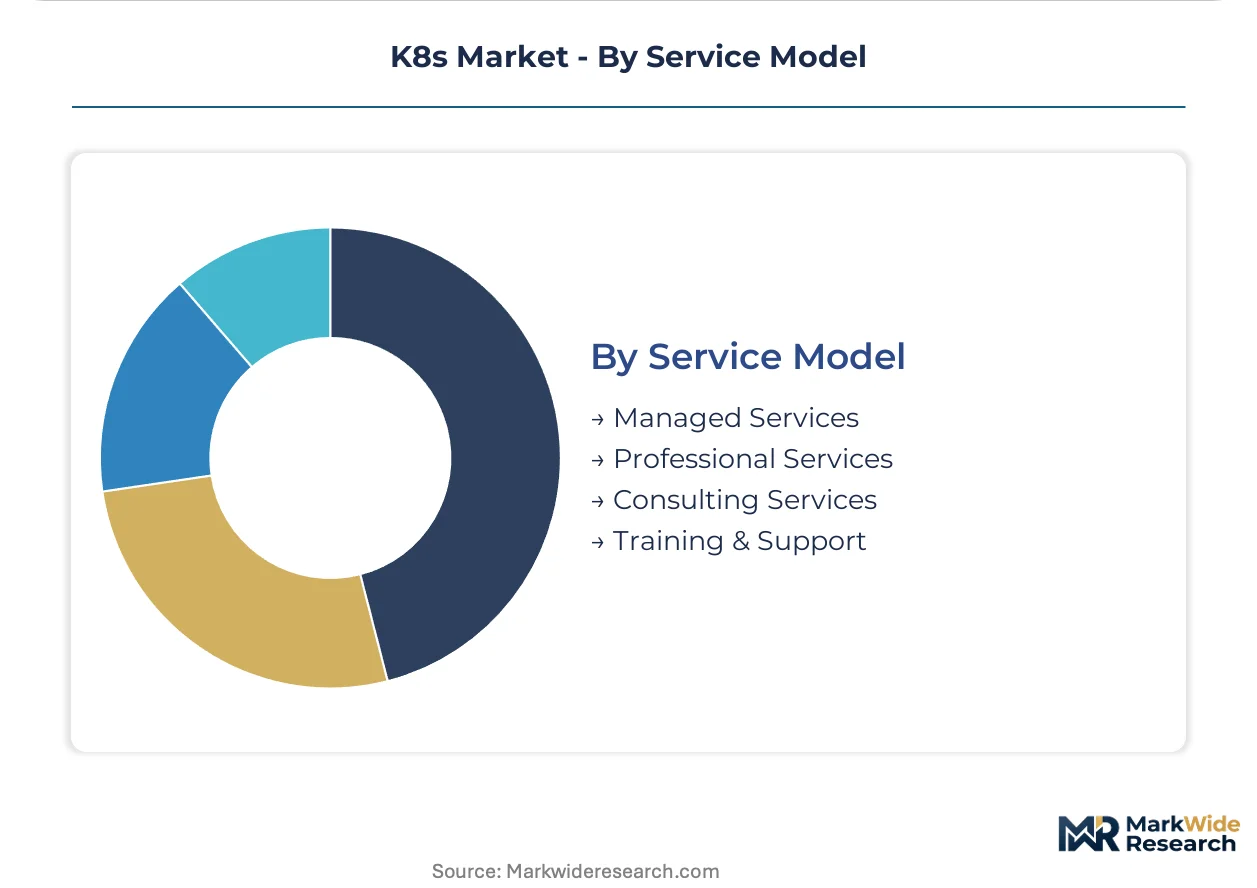
Service Model:
Managed services capture recurring revenue through operational abstraction, while professional services face margin pressure from labor market tightness in platform engineering skills.
- Managed Services:Third-party operation of cluster infrastructure including patching, scaling, and incident response eliminates customer operational burden. Healthcare organizations navigating FDA validation complexity outsource GxP environment qualification to specialized managed service providers.
- Professional Services:Implementation, migration, and customization engagements address legacy monolith decomposition and multi-cluster governance tooling gaps. Extended timelines for pharmaceutical Kubernetes deployments inflate project costs and create backlog constraints for specialized consultancies.
- Consulting Services:Strategic advisory on platform architecture, security posture, and cloud-native transformation roadmaps guides enterprise Kubernetes investments. CSRD-aligned sustainability reporting requirements create new procurement criteria for European enterprises evaluating infrastructure carbon footprints.
- Training & Support:Certification programs, hands-on workshops, and technical support subscriptions address the certified administrator scarcity constraining market expansion. Platform vendors leverage training ecosystems to sustain engineering mindshare and reduce customer churn.
Revenue concentration favors Managed Services in cloud-native enterprises. Professional Services are gaining share fastest among regulated industries requiring specialized compliance expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco Bay Area technology corridors concentrate the highest density of Kubernetes engineering talent and hyperscaler cloud regions, anchoring North American deployment scale. Financial services firms in Manhattan and Chicago drive low-latency trading infrastructure modernization. European compliance mandates reshape procurement patterns across Frankfurt, Paris, and Amsterdam financial centers.
United States
Financial services firms in Manhattan and Chicago accelerate trading infrastructure modernization using low-latency orchestration capabilities. NIST SP 800-204 standards govern microservices security architecture in federal cloud environments. San Francisco Bay Area hyperscaler regions and enterprise data centers absorb the highest public cloud deployment volumes.
Germany
Critical infrastructure operators under NIS2 Directive mandates drive fastest adoption of automated Kubernetes-native security platforms. The country's national cybersecurity regulator enforces network security and incident reporting requirements for containerized workloads. Frankfurt financial center concentrates compliance-driven procurement among banking and insurance platform engineering teams.
France
ANSM pharmaceutical oversight shapes validation requirements for GxP environment deployments in manufacturing sectors. EU AI Act algorithmic transparency requirements accelerate GitOps-enabled deployment pipeline adoption. Paris financial services and Île-de-France technology clusters represent earliest compliance-driven adopters of zero-trust segmentation.
United Kingdom
London financial services firms demand workload mobility across hyperscaler environments that Kubernetes abstraction layers enable. GDPR-aligned vendor due diligence requirements establish ISO 27001 certification as baseline market access criteria. UK-based healthcare and federal contractors navigate complex authorization pathways for integrated Kubernetes distributions.
Netherlands
Amsterdam data center and cloud hub concentration supports European enterprise multi-cloud portability imperatives. CSRD-aligned sustainability reporting mandates broaden procurement criteria for energy-efficient orchestration platforms. Dutch critical infrastructure operators align with NIS2 network security mandates for container workload segmentation.
K8s Market Competitive Landscape
The competitive structure tilts toward hyperscaler cloud providers with operational scale advantages. Three distinct archetypes populate the vendor landscape: cloud-native platform operators, open-source distribution specialists, and security-focused tooling vendors. Consolidation pressure intensifies as platform engineering teams reduce vendor relationships. Strategic partnerships and technology licensing dominate competitive moves as firms bundle ingress, storage, and observability components.
Within the hyperscaler tier, Google, Amazon, and Microsoft anchor commercial adoption through managed service integration. Google leverages open-source project stewardship to sustain engineering mindshare. Amazon anchors adoption through cloud services ecosystem integration. Microsoft competes through hybrid edge connectivity extensions. Red Hat and VMware occupy positions within the enterprise distribution archetype, serving regulated industries requiring customized control plane configurations.
| Leading Market Players |
|---|
| Amazon |
| Microsoft |
| IBM |
| Oracle |
| Red Hat |
| VMware |
| Sysdig |
| Rancher Labs |
| Others |
Pricing and Supply Chain Analysis
Certified Kubernetes administrator labor costs cascade through managed service premiums, with scarcity in platform engineering skills inflating implementation timelines and professional services attach rates across deployment tiers.
Pricing Analysis
Uptime guarantees and compliance certification tiers anchor value-based pricing for Kubernetes platforms, with FedRAMP-authorized distributions commanding substantial premiums over standard hyperscaler offerings. Price differentiation rests on security certification depth and multi-cluster governance capabilities, with pharmaceutical manufacturers under FDA 21 CFR Part 11 requirements showing lowest price sensitivity. Pricing pressure stems from open-source observability stack commoditization in monitoring tools. SMBs with limited platform engineering headcount exhibit highest price sensitivity, favoring managed services with minimal configuration overhead.
Supply Chain Analysis
Cross-border data transfer compliance costs elevate logistics complexity for European deployments under GDPR and NIS2 mandates. Control plane software development concentrates in the United States, Germany, and India, with hyperscaler cloud regions anchoring distribution scale. Raw material inputs encompass bare-metal server infrastructure, specialized networking hardware, and energy for data center operations. Single-source vulnerability sits with etcd distributed state storage dependencies. Distribution runs through hyperscaler direct sales, systems integrator channels, and open-source community ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified Kubernetes administrator scarcity constrains market expansion, propping pricing power for specialized training and managed service providers across regulated verticals.
For Market Incumbents: To counter hyperscaler operational scale advantages, Red Hat and VMware should deepen upstream control over critical etcd state management components while expanding FedRAMP-authorized distribution footprints. Certification investment in EU AI Act compliance tooling represents a priority lever for European market defense. For New Entrants and Emerging Players: NIS2 Directive in Germany and France opens a window for zero-trust security platform specialists targeting critical infrastructure operators with automated threat detection capabilities. The most penetrable segment sits with mid-market European enterprises lacking in-house platform engineering teams. A channel partnership strategy with systems integrators accelerates compliance-driven procurement capture. For Investors and Strategic Acquirers: Consolidation of vendor relationships around integrated Kubernetes distributions is the leading indicator that platform engineering tooling gaps are widening acquisition opportunities. Long-term viability favors specialists with confidential computing integration capabilities and sovereign cloud deployment expertise. Target firms with GitOps-native operational models and established healthcare or federal contractor customer bases.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundling ingress, storage, and observability displaces best-of-breed assembly at US federal contractors. |
| Strategic Partnership | Systems integrator alliances accelerate NIS2 compliance solution deployment among Dutch critical infrastructure operators. |
| Acquisition of Specialist Firm | eBPF instrumentation capabilities consolidate observability, security, and networking control for financial services firms. |
| Geographic Expansion | Frankfurt and Paris cloud regions capture EU AI Act algorithmic transparency procurement preferences. |
| Product Launch | Confidential computing-enabled multi-tenant platforms unlock sensitive data verticals including pharmaceutical manufacturing. |
Research Methodology
Document review covered hyperscaler capex disclosures, SEC filings, and regulatory mandate texts, complemented by interviews with platform engineering directors, Kubernetes administrators, cloud procurement officers, and systems integrator technical leads. Secondary validation drew from NIST SP 800-204 standards documentation, EU AI Act compliance guidelines, and FDA 21 CFR Part 11 guidance materials. Bottom-up cluster deployment estimates and top-down cloud infrastructure spend analysis enabled triangulation across data sources.
Market sizing outputs reflect segmentation across deployment type, solution category, end-user organization scale, and service model engagement patterns over the projection horizon. CAGRs were derived from trend extrapolation of hyperscaler managed Kubernetes revenue disclosures and enterprise platform engineering budget allocations. Modeled inputs incorporated certified administrator labor market tightness, compliance deadline schedules, and edge computing workload growth trajectories.
The model assumes a particular technology adoption path; alternative pathways for eBPF kernel instrumentation or confidential computing hardware would alter the outlook for security solution pricing and platform consolidation timing. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and hyperscaler competitive positioning. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Acoustic Simulation Software Market
Software & Services
Towing Software Market
Software & Services
Global Digital Rights Management Software Market
Software & Services
Global Contract Management Software Market
Software & Services
Product Optimization Software Market
Software & Services
SMS Marketing Software Market
Software & Services
Automotive Dealership Software Market
Software & Services
Engineering Software Market
Software & Services
Global HVAC Software Market
Software & Services
Global Process Mining Software Market
Software & Services
Office Productivity Software Market
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Geomechanics Software and Service Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Payroll and HR Software Market
Software & Services
Testing As a Service (Taas) Market