
 Application Performance Management (APM) Software Market | 2026-2036
Application Performance Management (APM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Application Performance Management (APM) Software Market Outlook
Platform licensing revenue is reconfiguring how vendors capture value across the APM stack, shifting margin pools from perpetual deployment fees toward consumption-based telemetry contracts. Datadog leverages its cloud-native architecture to anchor recurring revenue in high-volume observability workloads. Dynatrace competes through AI-driven root-cause automation that sustains premium positioning in enterprise accounts. New Relic navigates pricing compression by extending usage-based models downmarket to developer-led adoption.
Application Performance Management software encompasses tools that instrument code, infrastructure, and user sessions to measure response times, error rates, and throughput across distributed systems, with primary commercial purpose being the prevention of revenue loss from degraded digital experiences. Cloud-Based deployment leads segment expansion as organizations retire on-premises collectors in favor of elastic, API-first ingestion architectures. Real User Monitoring represents the fastest-growing solution category as product teams prioritize session replay and journey analytics over synthetic transaction scripts. Error Management functionality commands outsized margin contribution because automated anomaly detection reduces mean-time-to-resolution and supports outcome-based service level agreements.
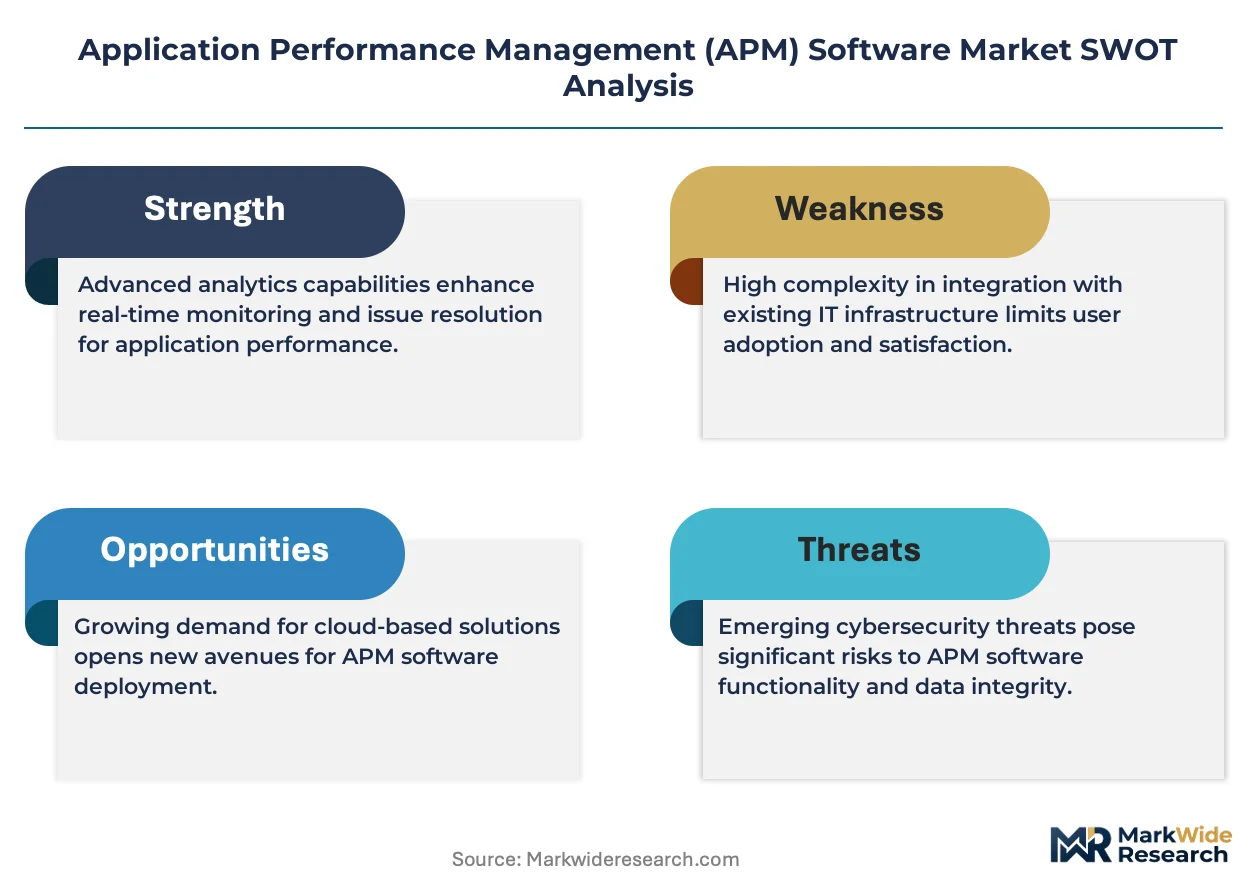
ISO 27001 certification and SOC 2 Type II attestation now function as de facto market access requirements for APM vendors serving regulated industries, with procurement teams rejecting unqualified suppliers during security reviews. The EU AI Act and GDPR cross-border data transfer rules are forcing European enterprises to evaluate whether SaaS monitoring platforms can maintain telemetry residency within regional boundaries. Stakeholders must decide whether to consolidate observability spend with full-stack vendors or maintain specialized point solutions as telemetry volumes and compliance scope expand in parallel.
Market Dynamics
Telemetry volume inflation from microservices architectures is compressing per-gigabyte pricing while expanding total addressable spend, forcing vendors to rearchitect ingestion pipelines for cost efficiency at scale.
Growth Catalysts
- ISO 27001 and SOC 2 mandates:Financial services procurement teams now require attested security frameworks as table stakes, disqualifying unqualified vendors and consolidating spend toward compliant platforms.
- Real User Monitoring adoption:Product teams prioritize session replay and journey analytics over synthetic scripts, expanding solution category penetration in e-commerce and digital banking.
- Cloud migration in financial services:Elastic API-first ingestion architectures replace on-premises collectors, enlarging the buyer base for SaaS-native observability platforms.
Market Restraints
- Data residency requirements:GDPR cross-border transfer rules and EU AI Act provisions force European enterprises to evaluate telemetry sovereignty, complicating SaaS platform deployment.
- Specialized engineering talent scarcity:Shortages in distributed systems observability expertise inflate implementation costs and extend deployment timelines for complex environments.
- Open-source telemetry standards:OpenTelemetry adoption enables buyer substitution away from proprietary agents, pressuring vendor lock-in strategies.
Strategic Opportunities
- Edge computing observability:IoT and 5G distributed workloads create greenfield demand for lightweight agents capable of processing telemetry at network periphery.
- Outcome-based pricing models:Mean-time-to-resolution guarantees and SLA-attached contracts allow vendors to capture value from operational outcomes rather than raw consumption.
- AI-driven root-cause automation:Convergence of causal AI with observability pipelines enables premium positioning in enterprise accounts seeking autonomous remediation.
Industry Challenges
- Legacy system integration complexity:Mainframe and monolithic application instrumentation requires custom agent development, fragmenting engineering resources.
- Certification timeline compression:Accelerated security review cycles demand parallel SOC 2 Type II and ISO 27001 audits, straining vendor compliance operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Performance Management (APM) Software Market |
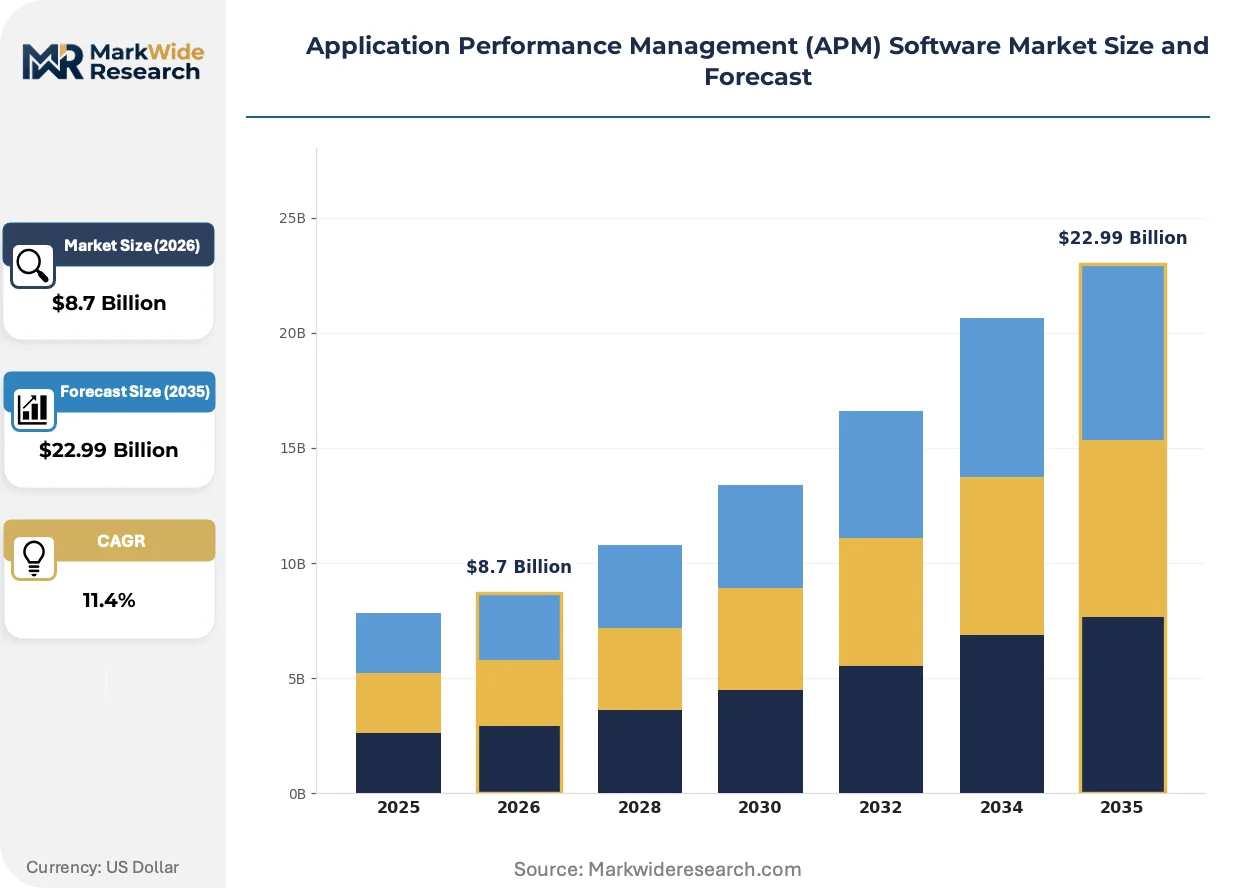
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: IT Departments, DevOps Teams, Managed Service Providers, Enterprises Solution: Real User Monitoring, Synthetic Monitoring, Application Mapping, Log Management Functionality: Error Management, Performance Tracking, Incident Management, Reporting |
| Companies Covered | Splunk AppDynamics, AppDynamics, Datadog, IBM Maximo, GE Vernova, Dynatrace, IBM Instana, AVEVA, New Relic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Performance Management (APM) Software Market Strategic Shifts
Observability pipelines are fragmenting into specialized layers as buyers reject monolithic platforms in favor of composable telemetry stacks that optimize for specific workload economics.
OpenTelemetry is hybridizing telemetry collection across cloud-native and legacy infrastructure. Platform engineering teams at Fortune 500 enterprises are adopting the standard to normalize data ingestion across hybrid environments. This convergence is hybridizing vendor competitive positioning, forcing proprietary agent vendors toward collector compatibility or marginalization.
The EU AI Act's risk classification framework is reshaping algorithmic transparency requirements for automated anomaly detection systems. Vendors must now document training data provenance and decision logic for high-risk AI deployments. European financial institutions are responding by demanding audit trails and explainability modules as standard platform features.
Developer-led adoption is displacing centralized IT procurement as the primary buying motion for observability tools. Engineering teams now self-serve trial deployments and usage-based contracts through product-led growth channels, bypassing traditional enterprise sales cycles. This pattern is most pronounced in United States technology startups and mid-market SaaS companies.
Application Performance Management (APM) Software Market Segmentation
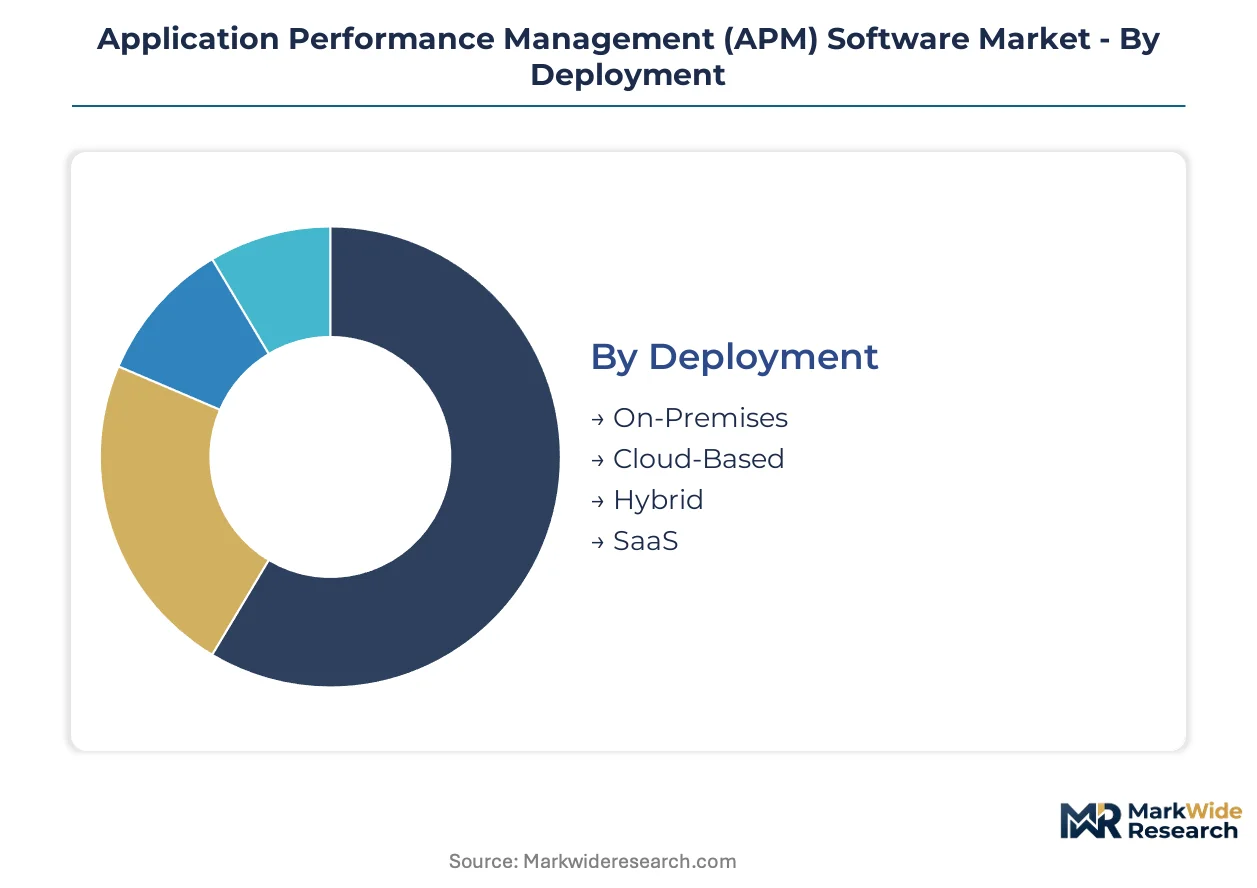
APM software segmentation reflects divergent infrastructure strategies across regulated enterprises and cloud-native startups. Procurement patterns split between compliance-driven centralized purchasing and developer-led self-service adoption.
Deployment:
Deployment choice maps directly to data sovereignty requirements and capital allocation preferences across buyer types.
- Cloud-Based:Elastic API-first ingestion architectures dominate new procurement in financial services and digital commerce. German automotive manufacturers and Japanese electronics firms are retiring on-premises collectors in favor of consumption-scaled telemetry contracts.
- SaaS:Multi-tenant platforms with ISO 27001 attestation capture mid-market expansion through product-led growth channels. United States technology startups and SaaS companies bypass traditional enterprise sales cycles via self-serve trials.
- On-Premises:Air-gapped collectors persist in defense contractors and classified government facilities with strict data residency mandates.
- Hybrid:Split architectures accommodate phased cloud migration in legacy-heavy enterprises maintaining mainframe telemetry alongside cloud-native workloads.
The dominant share belongs to Cloud-Based, while SaaS is closing the gap fastest.
End User:
Buying authority is fragmenting as engineering teams gain autonomous procurement power.
- DevOps Teams:Platform engineering groups at Fortune 500 enterprises self-serve observability tooling through usage-based contracts. United States technology startups prioritize developer experience and API ergonomics over centralized IT approval.
- Enterprises:Centralized procurement functions in regulated industries demand SOC 2 Type II attestation and GDPR-compliant data residency. European financial institutions conduct parallel security reviews across multiple jurisdictions.
- IT Departments:Traditional infrastructure teams maintain legacy APM deployments while evaluating cloud migration paths.
- Managed Service Providers:Outsourced monitoring operations consolidate multi-tenant observability platforms for mid-market clients lacking internal expertise.
Enterprises retain the largest contract values, though DevOps Teams are expanding fastest through bottom-up adoption.
Solution:
Solution preference tracks the shift from synthetic validation toward experiential measurement.
- Real User Monitoring:Session replay and journey analytics capture actual customer interactions across web and mobile applications. E-commerce platforms and digital banking operations prioritize this category for revenue protection.
- Synthetic Monitoring:Scripted transaction testing maintains relevance for SLA verification and baseline performance benchmarking.
- Application Mapping:Dependency visualization tools map service topology across microservices architectures for root-cause analysis.
- Log Management:Centralized log aggregation supports compliance auditing and security incident investigation in regulated sectors.
Real User Monitoring holds the dominant position, while Application Mapping is gaining share fastest through cloud-native adoption.
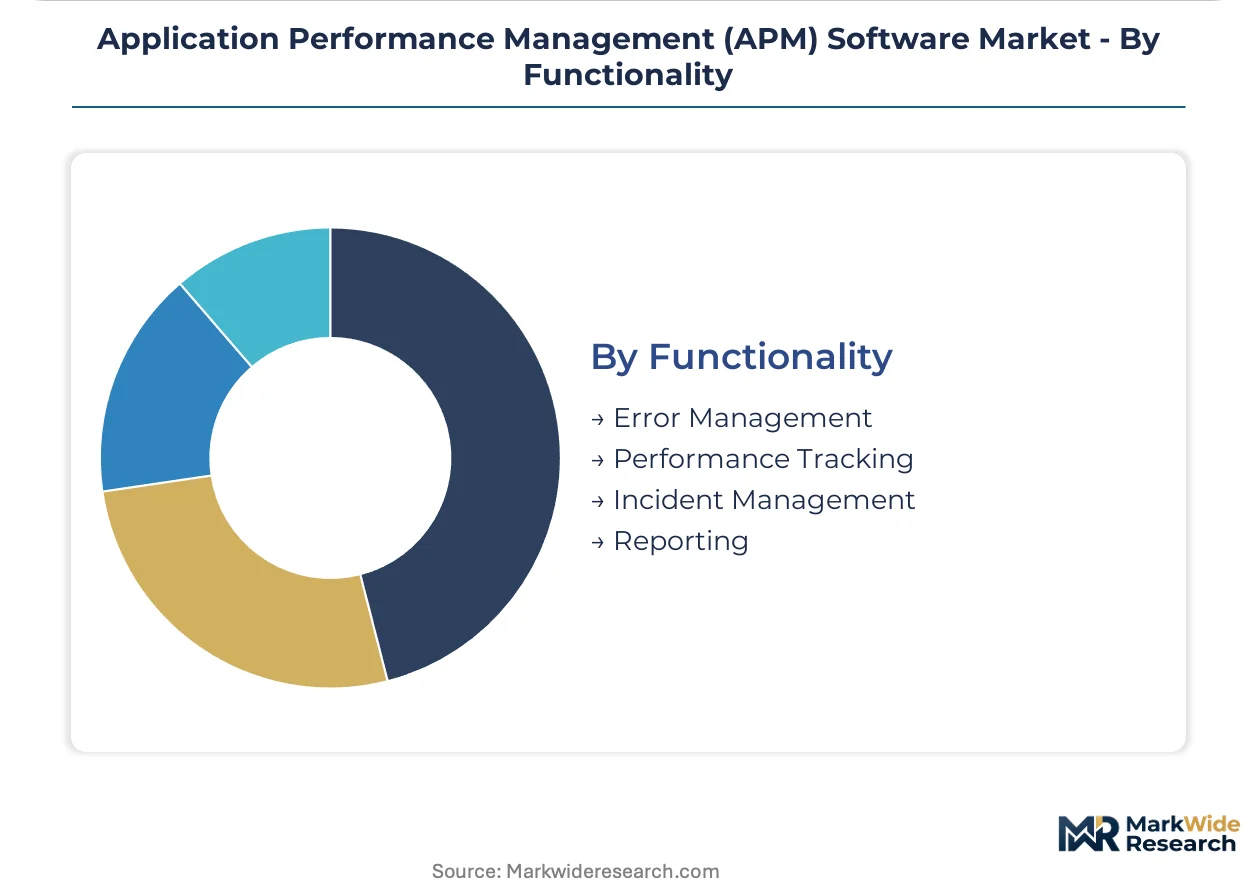
Functionality:
Margin concentration aligns with automation depth and outcome-based contracting potential.
- Error Management:Automated anomaly detection reduces mean-time-to-resolution and supports SLA-attached pricing models. Vendors capture premium positioning through autonomous remediation capabilities.
- Performance Tracking:Response time and throughput measurement forms the baseline layer of observability stacks with compressed per-metric pricing.
- Incident Management:Alert routing and escalation workflows integrate with ITSM platforms for operational workflow automation.
- Reporting:Compliance dashboards and executive summaries serve audit requirements and stakeholder communication needs.
Error Management commands the highest margins, while Incident Management is climbing fastest through ITSM platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price sensitivity as cloud-native enterprises prioritize telemetry volume elasticity over per-gigabyte costs. German and Japanese procurement teams exhibit moderate elasticity, balancing compliance mandates against consumption-scaled contracts. Indian and Brazilian markets show highest sensitivity, with mid-market buyers favoring usage-based entry points and self-serve deployment models.
United States
Financial services cloud migration and developer-led procurement expansion drive SaaS-native platform adoption. SEC cybersecurity disclosure rules and state-level data privacy statutes reshape vendor qualification requirements. Silicon Valley technology clusters and New York financial services corridors anchor enterprise contract concentration for full-stack observability deployments.
Germany
Automotive manufacturers and industrial conglomerates prioritize real user monitoring for digital commerce and connected vehicle platforms. GDPR cross-border transfer restrictions and EU AI Act algorithmic transparency mandates force telemetry residency evaluations. Bavarian automotive engineering hubs and Baden-Württemberg manufacturing clusters drive hybrid cloud migration for legacy-mainframe observability integration.
Japan
Electronics firms and digital banking operations demand session replay capabilities for customer experience protection. METI data governance guidelines and sector-specific financial regulations influence platform selection criteria. Tokyo metropolitan technology corridors and Osaka-Kobe manufacturing belts concentrate procurement for elastic API-first ingestion architectures.
United Kingdom
Fintech startups and enterprise SaaS companies accelerate product-led growth adoption for observability tooling. FCA operational resilience requirements and post-Brexit data adequacy arrangements complicate vendor compliance positioning. London financial services clusters and Manchester technology hubs represent primary demand centers for consumption-based telemetry contracts.
India
IT services exporters and domestic digital payment platforms expand mid-market observability spend through self-serve channels. RBI data localization directives and CERT-In cybersecurity incident reporting obligations constrain SaaS platform deployment options. Bengaluru technology corridors and Hyderabad IT clusters anchor developer-led procurement for cloud-native monitoring solutions.
Application Performance Management (APM) Software Market Competitive Environment
Capability concentration sits with specialized AI-automation vendors; scale advantage sits with full-stack cloud-native platforms. The vendor base organizes around three strategic tiers: incumbent enterprise suites with deep ITSM integration, cloud-native challengers with consumption-scaled pricing, and open-source-backed specialists with telemetry standardization. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into adjacent security and IT service management domains.
Within the cloud-native challenger tier, Datadog and Dynatrace exemplify divergent scale-versus-automation positioning strategies. Datadog occupies a position anchored in high-volume telemetry ingestion and developer-centric product-led growth. Dynatrace represents premium-tier positioning through causal AI and autonomous root-cause remediation capabilities. New Relic sits within the usage-based downmarket expansion archetype, targeting developer-led adoption with simplified entry pricing. Splunk AppDynamics and IBM Instana exemplify incumbent enterprise suite positioning, leveraging existing customer relationships and IT operations management integration.
| Leading Market Players |
|---|
| Splunk AppDynamics |
| AppDynamics |
| Datadog |
| IBM Maximo |
| GE Vernova |
| Dynatrace |
| IBM Instana |
| AVEVA |
| New Relic |
| Others |
Value Chain & Pricing Dynamics
United States hyperscaler infrastructure concentration anchors downstream margin capture for APM vendors, as elastic compute and storage costs from Amazon Web Services, Microsoft Azure, and Google Cloud Platform directly shape consumption-based pricing floors. Telemetry ingestion economics hinge on negotiated egress rates and reserved instance commitments, transferring cloud provider pricing power into vendor cost structures.
Pricing Analysis
Consumption-scaled telemetry contracts drive lifetime value, with platform vendors anchoring recurring revenue in high-volume observability workloads rather than perpetual licensing. Three-tier pricing structure across premium, standard, and economy levels differentiates by AI automation depth and compliance certification tier. Pricing pressure stems from OpenTelemetry standardization enabling buyer substitution away from proprietary agents. DevOps-led technology startups show lowest price sensitivity, while Indian mid-market IT services exporters exhibit highest elasticity.
Supply Chain Analysis
Export-control regimes around AI training infrastructure and advanced semiconductors constrain telemetry processing hardware flows to certain jurisdictions. Engineering talent supply concentrates in the United States, Germany, and India, with platform development anchored in Silicon Valley, Berlin, and Bengaluru technology corridors. Proprietary machine learning frameworks and causal AI algorithms constitute critical intellectual property dependencies. Single-source vulnerability sits with hyperscaler cloud infrastructure concentration. Distribution runs through direct enterprise sales teams, product-led growth channels, and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through procurement team consolidation at Fortune 500 enterprises, where centralized observability spend decisions displace fragmented tool adoption. This shift favors full-stack vendors with compliance attestation over point-solution specialists.
For Market Incumbents: Entrench SOC 2 Type II and ISO 27001 certification as non-negotiable table stakes, accelerating parallel audit timelines to outpace compliance-lagging competitors. Deepen ITSM platform integration to raise switching costs against cloud-native challengers. Prioritize causal AI R&D investment to defend premium positioning against Datadog's volume-scale threat.
For New Entrants and Emerging Players: Establish a beachhead in edge computing observability for IoT and 5G distributed workloads, where lightweight agent demand outstrips incumbent platform adaptation. Target European financial institutions confronting EU AI Act algorithmic transparency mandates with explainability-first positioning. Pursue developer-led growth through OpenTelemetry-native architectures and self-serve trial deployment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cloud-native challengers possessing high telemetry volume growth but compressed path to profitability. Five-to-ten-year viability hinges on outcome-based pricing model adoption and autonomous remediation capability maturation. Monitor OpenTelemetry standardization penetration rates as inflection indicator for proprietary agent vendor margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Root-Cause Automation | Causal AI convergence enables premium positioning in enterprise accounts seeking autonomous remediation capabilities. |
| Outcome-Based Pricing Transition | Mean-time-to-resolution guarantees allow vendors to capture value from operational results rather than raw consumption. |
| Hyperscaler Marketplace Expansion | AWS Marketplace and Azure Marketplace listings accelerate procurement cycles for cloud-native buyer segments. |
| OpenTelemetry Collector Compatibility | Standardized telemetry ingestion hybridizes vendor positioning against proprietary agent marginalization risk. |
| Edge Computing Observability Development | Lightweight agent architectures address IoT and 5G greenfield demand outside core cloud workload coverage. |
Study Parameters
Desk research of SEC filings, hyperscaler capex disclosures, and compliance attestation databases preceded structured interviews with platform engineering directors, IT procurement officers, observability vendor sales leaders, and channel integration specialists. Primary fieldwork captured deployment decision criteria, pricing negotiation dynamics, and vendor selection processes across financial services, technology, and industrial end-use segments. Secondary validation drew from ISO certification registries, SOC 2 audit reports, and EU regulatory guidance documents. Bottom-up telemetry volume estimates and top-down enterprise spend allocations were triangulated to anchor market sizing.
Assumptions around cloud migration velocity, OpenTelemetry adoption curves, and compliance timeline compression were held fixed against stress-tested scenarios for regulatory acceleration and economic slowdown. Segmentation modeling spanned deployment architecture, organization size tier, vertical industry, integration complexity, and regional adoption pattern. CAGRs were derived from fitted growth curves against historical spend trajectories and projected infrastructure expansion. Forecast inputs incorporated microservices architecture penetration rates and real user monitoring solution category expansion.
Stress conditions across GDPR enforcement intensity, EU AI Act implementation pace, and hyperscaler pricing volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about telemetry volume inflation and buyer consolidation trajectories. Material shifts in OpenTelemetry standardization velocity or cross-border data transfer regulatory posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Fiber Simulation Software Market
Software & Services
Metal Fabrication Software Market
Software & Services
Meditation Software Market
Software & Services
Enterprise Search Software Market
Software & Services
Computer Engineering Market
Software & Services
Global IVR Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Global Managed File Transfer Software Market
Software & Services
ELD Compliance Software Market
Software & Services
Global Performance Appraisal Software Market
Software & Services
User Retention Software Market
Software & Services
Period-Tracking Software Market
Software & Services
Global Childcare Management Software Market
Software & Services
Channel Management Software Market
Software & Services
Africa Sports Management Software Market
Software & Services
Parametric Design Software Market