
 Customer Revenue Optimization Software Market | 2026-2036
Customer Revenue Optimization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Customer Revenue Optimization Software Market Outlook
Fragmentation across mid-market SaaS buyers is recalibrating vendor go-to-market economics, forcing platform providers to serve narrower use cases with lower contract values. Gainsight leverages deep workflow integration to sustain retention analytics leadership among enterprise accounts. Clari anchors its position through revenue intelligence specialization in forecasting pipelines. ChurnZero competes aggressively on implementation speed for sub-thousand-employee deployments.
Customer revenue optimization software encompasses predictive analytics engines, subscription billing modules, and churn prevention algorithms designed to maximize lifetime value across recurring revenue relationships. These systems process behavioral signals, usage telemetry, and contract metadata through machine learning models to flag expansion risks and upsell timing. Enterprise Solutions dominate current margin pools due to complex multi-entity billing requirements and custom API demands. Cloud-Based deployment captures the fastest growth trajectory as banking and e-commerce verticals prioritize elastic infrastructure over capital-intensive on-premises installations.
FCC guidelines on data privacy in telecommunications customer records shape how telecom-oriented vendors architect consent management layers. GDPR and EU AI Act compliance obligations in Europe force platform developers to localize inference models and document algorithmic decision pathways. ISO 27001 certification operates as a baseline market-access requirement for procurement teams at regulated financial institutions. Stakeholders must monitor evolving state-level privacy legislation in the United States as fragmented compliance obligations threaten to fragment product architectures and inflate implementation costs.
Market Dynamics
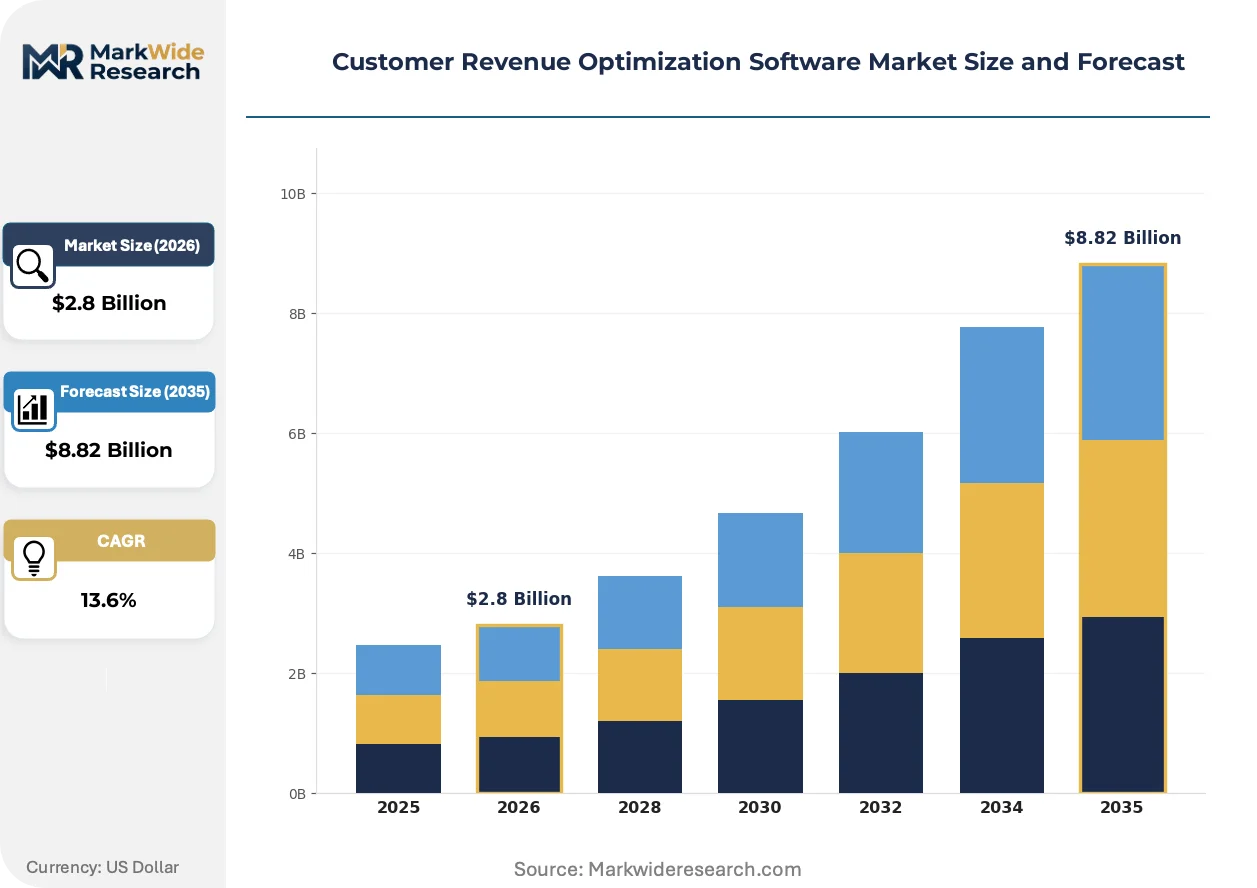
AI-driven predictive analytics is compressing sales cycles and forcing vendors to rearchitect platforms around real-time inference rather than batch-processed reporting. Cloud-native architectures now dominate procurement evaluations as enterprise buyers prioritize elastic scaling over fixed-capacity licensing.
Growth Catalysts
- Subscription billing intelligence:Banking and e-commerce verticals in the United States deploy automated dunning and usage-based pricing modules to reduce involuntary churn. These tools process payment failure signals through machine learning models that trigger recovery sequences before contract termination.
- EU AI Act compliance infrastructure:European vendors localize inference models and document algorithmic decision pathways to meet documentation mandates. This creates procurement pull for platforms with built-in explainability layers and audit trails.
- Net revenue retention targets:Enterprise SaaS procurement teams mandate platform acquisitions that flag expansion risks and upsell timing through behavioral signal processing. Finance executives now own software buying decisions previously controlled by IT departments.
Market Restraints
- Data residency requirements:GDPR localization obligations force multi-region infrastructure deployments that inflate operational costs for vendors serving European enterprises. Inference model hosting must replicate across Frankfurt, Dublin, and Stockholm zones.
- ISO 27001 certification timelines:Regulated financial institutions require baseline security attestations that extend sales cycles by four to six months. Procurement teams reject uncertified vendors regardless of feature parity.
- Legacy CRM integration complexity:Custom API development for Salesforce and Microsoft Dynamics deployments consumes professional services capacity. Mid-market buyers lack engineering resources to self-configure connections.
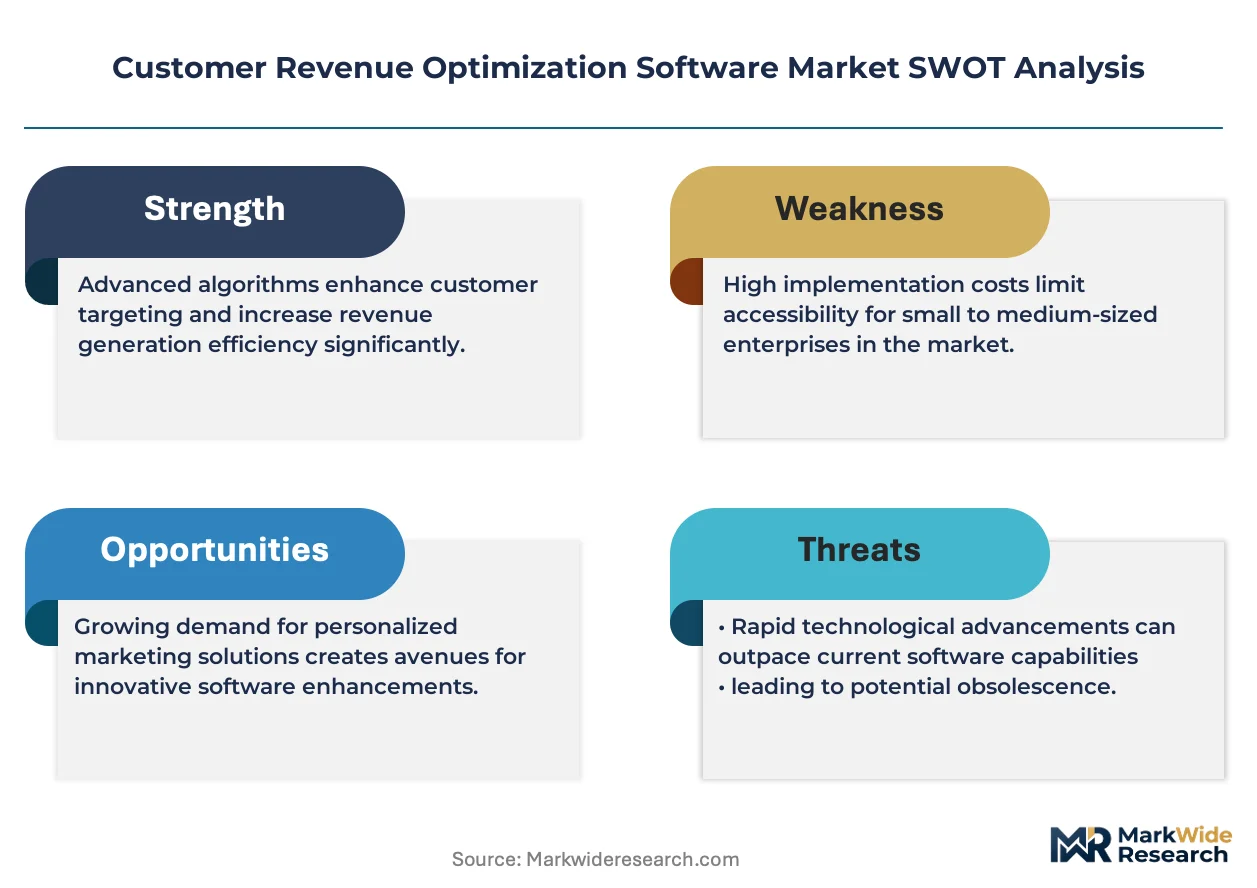
Strategic Opportunities
- India PLI scheme alignment:Software vendors serving manufacturing exporters can bundle revenue optimization with production incentive compliance tracking. Localized billing modules help SMEs document value-addition thresholds for tax credits.
- Real-time usage metering convergence:Integration of streaming telemetry from IoT devices with subscription billing engines enables outcome-based pricing for industrial equipment. This opens machinery-as-a-service models previously blocked by measurement gaps.
- State-level privacy legislation fragmentation:California, Virginia, and Colorado diverging compliance obligations create demand for configurable consent management layers. Vendors with modular privacy architectures capture multi-state enterprise deployments.
Industry Challenges
- Machine learning operations talent scarcity:Vendors compete for engineers capable of deploying production inference pipelines with sub-100-millisecond latency. Compensation inflation in San Francisco and New York strains R&D budgets.
- Multi-entity billing configuration:Enterprise buyers with complex corporate structures require custom chart-of-account mappings that strain standardized product roadmaps. Professional services margins compress as implementations extend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customer Revenue Optimization Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Subscription-Based, One-Time License, Freemium, Enterprise Solutions Industry Vertical: Retail, Telecom, Banking, E-Commerce End User: Small Businesses, Medium Enterprises, Large Corporations, Startups Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services |
| Companies Covered | Guideflow, Planhat, Gainsight, Catalyst, Vitally, ChurnZero, Clari, Salesforce Revenue Cloud, Totango, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customer Revenue Optimization Software Market Strategic Shifts
Real-time inference architectures are displacing batch-processed analytics as the default expectation among enterprise buyers. Vendors now compete on prediction latency rather than dashboard visualization depth.
Transformer-based natural language models are overtaking rule-based churn scoring in enterprise deployments. These systems process support ticket sentiment, email thread tone, and call transcript emotion to flag cancellation risk before explicit signals appear. Banking procurement teams in the United States now mandate sub-second inference response times for high-value account alerts. The technology is compressing vendor differentiation from feature breadth to model accuracy benchmarks.
The EU AI Act documentation requirements are forcing platform developers to retrofit explainability layers onto black-box algorithms. Vendors must now generate human-readable rationale for every churn risk score and upsell recommendation. European deployments face extended implementation timelines as engineering teams build audit trail infrastructure. Financial services buyers in Germany and France delay procurement decisions until vendors demonstrate compliance with algorithmic accountability standards.
Finance-led procurement is consolidating vendor selection authority away from IT departments. CFOs now evaluate revenue optimization platforms through net revenue retention impact models rather than technical architecture reviews. This shift favors vendors with pre-built connectors to ERP systems like SAP and Oracle over those with superior machine learning performance. The pattern is most visible among United States-based SaaS companies with recurring revenue exceeding fifty million dollars annually.
Customer Revenue Optimization Software Market Segmentation
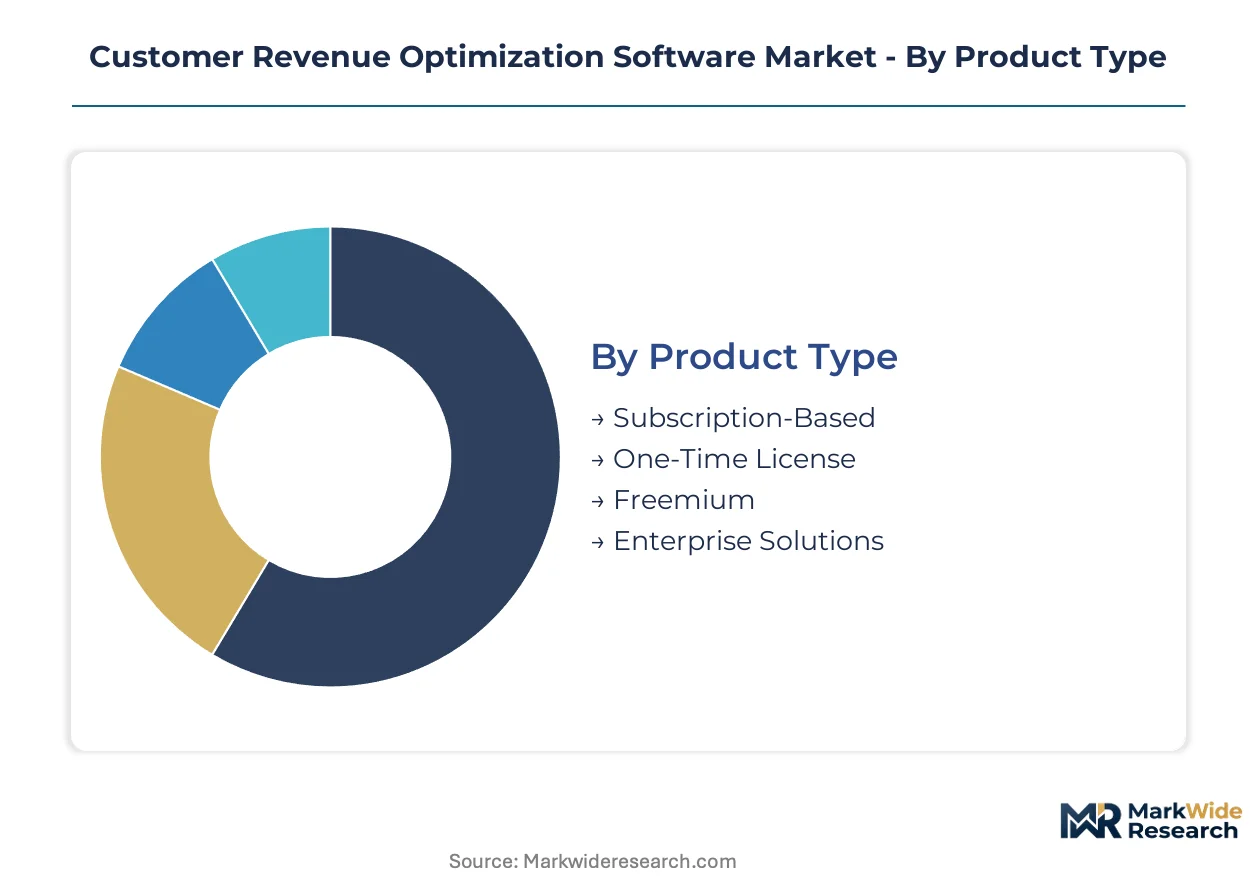
Segmentation in customer revenue optimization software reveals how procurement priorities diverge across buyer sophistication levels and infrastructure constraints. Deployment choices and licensing models directly determine implementation complexity and total cost of ownership for recurring revenue platforms.
Product Type:
Enterprise Solutions demand the heaviest upfront investment in professional services and custom API development, while Freemium models minimize capital barriers to entry.
- Enterprise Solutions:Multi-tenant architectures with custom chart-of-account mappings and complex billing rule engines serve corporate structures with multi-entity consolidation needs. Banking procurement teams in the United States prioritize these configurations for regulatory reporting integration, though extended implementation timelines compress vendor margins.
- Subscription-Based:Recurring licensing with tiered feature access dominates SaaS vendor procurement due to predictable cash flow alignment. E-commerce platforms deploy automated dunning modules within these structures to reduce involuntary churn from payment failures.
- One-Time License:Perpetual purchase models appeal to regulated financial institutions with capital expenditure preference over operating expense recognition.
- Freemium:Limited-feature entry tiers accelerate user acquisition among startups and sub-hundred-employee deployments with constrained procurement budgets.
Most installed capacity flows through Subscription-Based contracts. Expansion is steepest in Enterprise Solutions.
Industry Vertical:
Banking verticals concentrate procurement spend on compliance-integrated platforms, while E-Commerce drives volume through rapid-deployment cloud configurations.
- Banking:Institutions mandate ISO 27001-certified platforms with sub-second inference latency for high-value account risk alerts. FCC guidelines on telecommunications customer records shape consent architecture for banking vendors with cross-sector clients.
- E-Commerce:Automated dunning and usage-based pricing modules process payment failure signals through machine learning recovery sequences. United States platforms prioritize elastic scaling over fixed-capacity licensing to match transaction volatility.
- Telecom:Subscription billing intelligence tools integrate with legacy OSS/BSS systems requiring extensive professional services engagement.
- Retail:Seasonal revenue patterns demand flexible contract structures with expansion risk flagging tied to inventory cycles.
Procurement volume concentrates in Banking. E-Commerce is gaining share fastest among new deployments.
End User:
Large Corporations absorb the highest implementation costs, while Startups prioritize speed-to-value over feature depth.
- Large Corporations:Complex procurement committees with finance-led decision authority evaluate platforms through net revenue retention impact models. These buyers mandate pre-built ERP connectors to SAP and Oracle over superior machine learning performance.
- Medium Enterprises:Sub-thousand-employee deployments compete aggressively on implementation speed, favoring vendors with standardized onboarding playbooks and limited customization.
- Small Businesses:Constrained engineering resources drive demand for self-configuring CRM integrations without custom API development.
- Startups:Rapid scaling requirements prioritize platforms with immediate churn prevention algorithms over predictive analytics depth.
Revenue concentration sits with Large Corporations. Medium Enterprises show the steepest expansion trajectory.
Deployment:
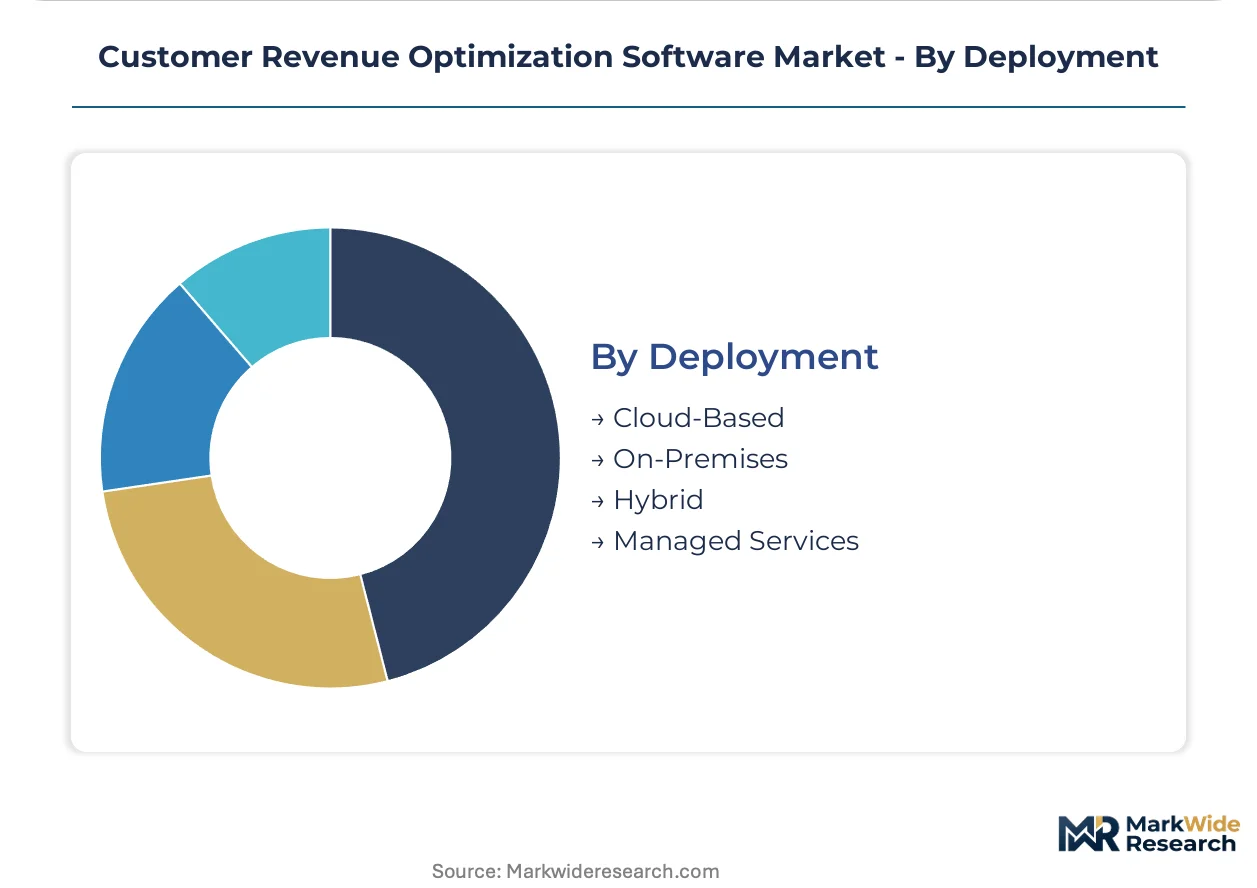
Cloud-Based architectures eliminate capital-intensive infrastructure commitments, while On-Premises retains preference among data residency-constrained buyers.
- Cloud-Based:Elastic scaling infrastructure dominates procurement evaluations as enterprise buyers prioritize real-time inference over batch-processed reporting. GDPR localization obligations force multi-region hosting across Frankfurt, Dublin, and Stockholm zones for European deployments.
- Hybrid:Split configurations satisfy data residency requirements for regulated financial institutions while leveraging cloud analytics for non-sensitive workloads.
- On-Premises:Fixed-capacity licensing persists among buyers with strict data sovereignty mandates or legacy compliance architectures.
- Managed Services:Outsourced infrastructure operations appeal to mid-market buyers lacking internal DevOps capacity for ML operations pipeline maintenance.
New procurement flows predominantly through Cloud-Based deployments. Hybrid configurations are climbing the fastest among regulated verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates procurement spend for revenue optimization platforms while Germany enforces the strictest algorithmic accountability standards in Europe. This divergence shapes vendor product roadmaps and compliance investments across major markets.
United States
Banking and e-commerce verticals drive adoption of subscription billing intelligence tools with automated dunning capabilities. FCC guidelines on telecommunications customer records shape consent management architecture for cross-sector vendors. Silicon Valley clusters anchor development of real-time inference engines with sub-second latency specifications.
Germany
Financial services buyers mandate ISO 27001-certified platforms with documented algorithmic decision pathways for churn risk scoring. EU AI Act compliance obligations force localization of inference models and audit trail infrastructure. Frankfurt hosts multi-region hosting deployments serving GDPR-constrained European enterprises.
United Kingdom
Enterprise SaaS procurement teams prioritize net revenue retention impact models over technical architecture reviews. Finance executives now control software buying decisions previously managed by IT departments. London's fintech corridor demands pre-built connectors to SAP and Oracle ERP systems.
India
Manufacturing exporters seek bundled revenue optimization with PLI scheme compliance tracking for production incentive documentation. RBI oversight of fintech data localization influences cloud deployment preferences among domestic SaaS vendors. Bangalore and Hyderabad clusters specialize in ML operations talent for inference pipeline development.
Japan
Industrial equipment manufacturers explore outcome-based pricing models through IoT telemetry integration with subscription billing engines. METI standards for data governance shape vendor selection criteria among machinery-as-a-service pioneers. Tokyo-Osaka corridor concentrates demand for hybrid cloud configurations balancing latency with data sovereignty.
Customer Revenue Optimization Software Market Competitive Environment
United States vendors anchor the enterprise tier; European specialists hold compliance-integrated positions. The market structures around three tiers: workflow-integrated incumbents, forecasting-specialized platforms, and rapid-deployment challengers. Consolidation pressures intensify as finance-led procurement favors pre-built ERP connectors over superior machine learning performance. Dominant competitive moves include strategic partnerships with cloud infrastructure providers and portfolio diversification into adjacent revenue intelligence modules.
Within the workflow-integrated tier, Gainsight and Planhat occupy positions serving complex multi-entity billing requirements. ChurnZero exemplifies the rapid-deployment archetype targeting sub-thousand-employee deployments with standardized onboarding playbooks. Clari anchors the forecasting-specialized segment through revenue intelligence capabilities in pipeline management.
| Leading Market Players |
|---|
| Guideflow |
| Planhat |
| Gainsight |
| Catalyst |
| Vitally |
| ChurnZero |
| Clari |
| Salesforce Revenue Cloud |
| Totango |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure costs cascade through SaaS pricing tiers as hyperscale compute consumption in the United States reshapes vendor margin structures. Professional services capacity for custom API development absorbs disproportionate cost allocation in enterprise deployments.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for subscription-based revenue optimization platforms. Three-tier pricing structure across premium, standard, and economy levels separates enterprise multi-tenant configurations from mid-market standardized deployments and startup freemium entry points. Price differentiation rests on ISO 27001 certification status and ERP integration depth. Pricing pressure stems from mid-market buyers demanding implementation speed without professional services premiums. Startups exhibit highest price sensitivity; banking procurement teams in the United States show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for revenue optimization platforms with pre-built ERP connectors. Engineering talent concentrates in the United States, India, and Germany for ML operations pipeline development. Raw material dependencies include cloud compute credits, proprietary training datasets, and open-source framework licensing. Single-source vulnerability sits with hyperscaler infrastructure concentration. Distribution runs through cloud marketplace listings and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in customer revenue optimization software hinges on automation compressing professional services intensity in enterprise implementations. Cloud-native delivery architectures enable premium-tier pricing for real-time inference capabilities.
For Market Incumbents: Anchor defensive positioning through pre-built ERP connector libraries that finance-led procurement committees mandate. Deepen workflow integration moats against forecasting-specialized challengers. ISO 27001 certification maintenance protects banking vertical access. Capacity additions in India for ML operations talent offset San Francisco compensation inflation. For New Entrants and Emerging Players: Real-time usage metering convergence with IoT telemetry offers technology-first wedge into industrial equipment-as-a-service pricing gaps. Target manufacturing exporters in India seeking PLI scheme compliance bundling. White-space exists in state-level privacy legislation fragmentation across California, Virginia, and Colorado. Freemium land-and-expand motion accelerates user acquisition before incumbent workflow lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where finance-led procurement favors pre-built ERP connectors over superior machine learning performance. Long-term viability favors platforms with modular privacy architectures spanning multi-state compliance obligations. Acquisition target archetype: rapid-deployment vendors with standardized onboarding playbooks for sub-thousand-employee segments. Signal to watch: CFO ownership of software buying decisions displacing IT department control.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built SAP and Oracle connectors capture finance-led procurement committees. |
| Strategic Partnership | Hyperscaler alliances accelerate multi-region GDPR-compliant hosting deployments. |
| Acquisition of Specialist Firm | IoT telemetry providers enable outcome-based pricing for machinery-as-a-service. |
| Geographic Expansion | India PLI scheme alignment opens manufacturing exporter revenue pools. |
| Product Launch | Explainability layers satisfy EU AI Act algorithmic accountability mandates. |
Study Parameters
Multiple input streams — primary interviews with CTOs, IT procurement officers, and platform engineers; secondary validation through SEC filings, hyperscaler capex disclosures, and cloud marketplace data; bottom-up and top-down triangulation — were reconciled to construct segment-level estimates. Primary fieldwork captured deployment preferences across banking, e-commerce, and telecom verticals. Secondary sources included vendor product roadmap documentation and regulatory filing analysis for GDPR and EU AI Act compliance patterns.
Historical growth trajectories were cross-referenced against panel input from finance executives and integration specialists to anchor projection assumptions. Segmentation dimensions modeled encompass deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGR derivation incorporated subscription billing intelligence adoption curves and net revenue retention target penetration across enterprise SaaS buyers. Industry-specific inputs included ML operations pipeline latency benchmarks and ISO 27001 certification timeline data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement intensity and state-level privacy legislation fragmentation. Forecasts reflect assumptions about finance-led procurement consolidation and cloud-native architecture preference stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Digital Illustration App Market
Software & Services
Global Virtual Desktop Market
Software & Services
Global Intranet Software Market
Software & Services
Global Website Builder Software Market
Software & Services
Metal Fabrication Software Market
Software & Services
HR Saas Market
Software & Services
Global Retail Execution Software Market
Software & Services
Camera Tracking Software Market
Software & Services
Problem Management Software Market
Software & Services
Global Legal Case Management Software Market
Software & Services
Manufacturing Quoting and Estimating Software Market
Software & Services
Content Marketing Software Market
Software & Services
Enterprise Search Software Market
Software & Services
Avionics Software Market
Software & Services
Agile Application Life-Cycle Management Market
Software & Services
Binary Drivers Market